
 US Transportation and Logistics Market | 2026-2036
US Transportation and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
US Transportation and Logistics Market Insights
Modular service bundling is shifting buyer choice across the US Transportation and Logistics Market, as shippers unbundle single-carrier contracts into multi-provider stacks that separate line-haul, warehousing, and final-mile execution. J.B. Hunt Transport Services anchors intermodal dominance through rail-highway integration across North American corridors. C.H. Robinson competes through digital freight-matching platforms that connect fragmented truck capacity with shipper demand. FedEx sustains premium express positioning through time-definite network density and customs brokerage integration.
US transportation and logistics encompasses the physical movement, storage, and coordination of goods across road, rail, air, and maritime modes, employing trailer tracking systems, warehouse management software, and cross-dock facilities to achieve delivery velocity and inventory precision. Freight Shipping leads service-type revenue generation due to contracted volume commitments from manufacturing and retail shippers, while Last-Mile Delivery captures accelerating growth as e-commerce order frequency reshapes residential delivery economics. Road transport dominates modal tonnage given drayage flexibility and the national highway system's reach, though Rail competes on bulk commodity and long-haul intermodal movements where fuel efficiency and lane density offset slower transit times.
The Federal Motor Carrier Safety Administration enforces hours-of-service rules and electronic logging device compliance that constrain driver availability and elevate fleet technology investment requirements, while the Department of Transportation's infrastructure funding allocations shape corridor capacity and port access modernization. The Environmental Protection Agency's Phase 3 greenhouse gas standards for heavy-duty vehicles are forcing engine and aerodynamic redesigns that alter total cost of ownership calculations for fleet operators. Stakeholders must monitor how autonomous trucking pilot programs and state-level permitting frameworks recalibrate labor-capital tradeoffs in long-haul operations.
Market Dynamics
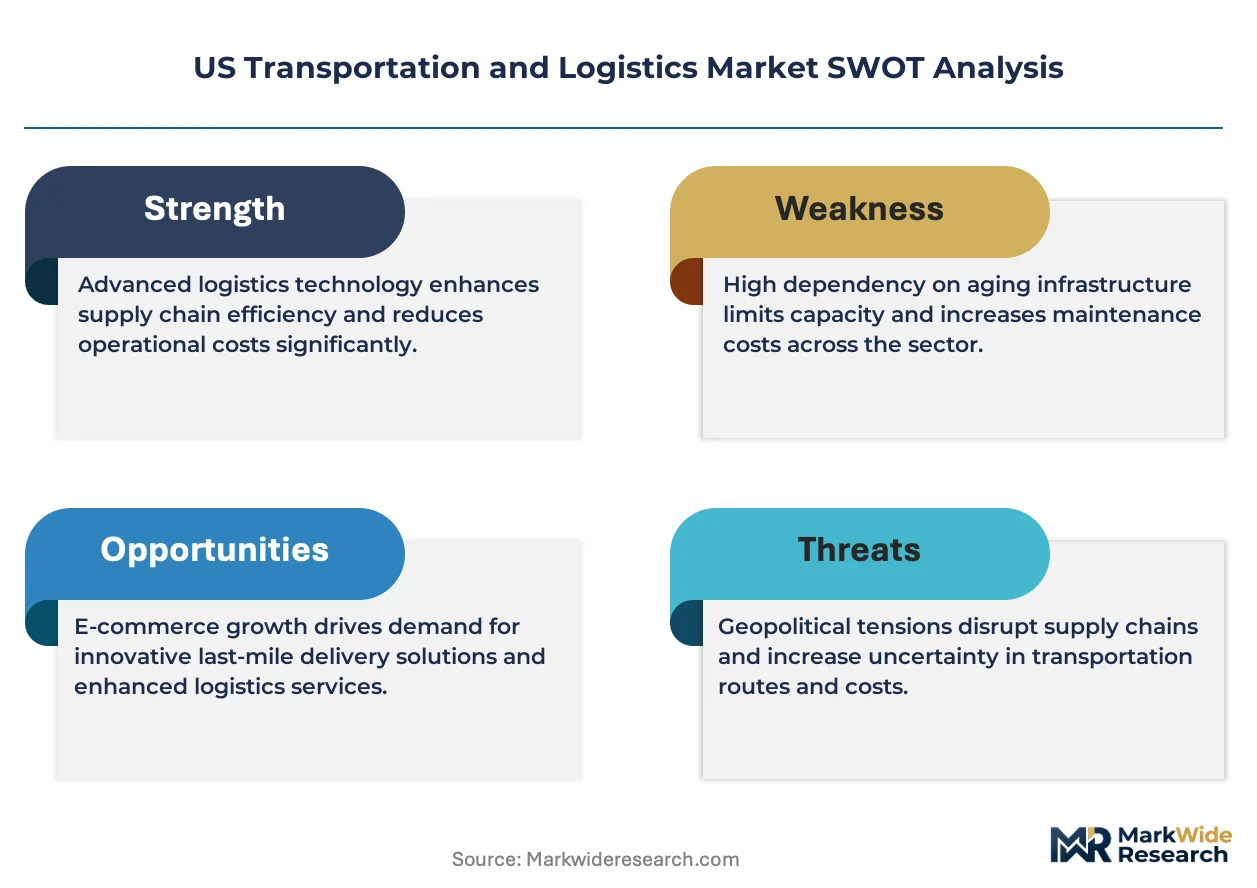
The Federal Motor Carrier Safety Administration's electronic logging device mandate continues compressing driver hour flexibility while parcel volume density from e-commerce fulfillment networks forces warehouse automation investment across the Texas-California freight corridor.
Growth Catalysts
- Intermodal rail-highway integration:Shippers are consolidating freight onto integrated networks that reduce fuel exposure and improve transit predictability along I-10 and I-35 corridors.
- EPA Phase 3 greenhouse gas standards:Fleet operators are accelerating engine redesign and aerodynamic retrofits to comply with heavy-duty vehicle emissions mandates ahead of enforcement timelines.
- E-commerce fulfillment density:Residential parcel volume surges are pulling capital into automated sortation hubs and micro-fulfillment nodes within 50 miles of major metropolitan zones.
Market Restraints
- Driver availability constraints:Hours-of-service rules and electronic logging device compliance are structurally limiting fleet capacity expansion regardless of freight demand signals.
- Diesel price volatility:Fuel represents 25-30% of operating costs for road transport operators, creating margin compression that cannot be fully passed through contract rate structures.
- Chassis and container equipment shortages:Port drayage and intermodal terminals face persistent equipment availability gaps during peak seasonal windows.
Strategic Opportunities
- Autonomous trucking pilot corridors:State-level permitting frameworks in Texas and Arizona are enabling supervised autonomous lane operations that recalibrate labor-capital tradeoffs.
- Final-mile electrification:Urban delivery zones are mandating zero-emission vehicle access, creating first-mover advantage for fleets deploying electric step-vans and cargo bikes.
- Cold-chain pharmaceutical expansion:Temperature-controlled logistics infrastructure is capturing volume from biologics distribution as healthcare supply chains diversify sourcing.
Industry Challenges
- Warehouse management system integration:Legacy enterprise resource planning architectures resist real-time data exchange with robotic material handling equipment.
- Cross-dock labor availability:Sortation and consolidation facilities struggle to staff overnight shifts at wage levels that preserve unit economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Transportation and Logistics Market |
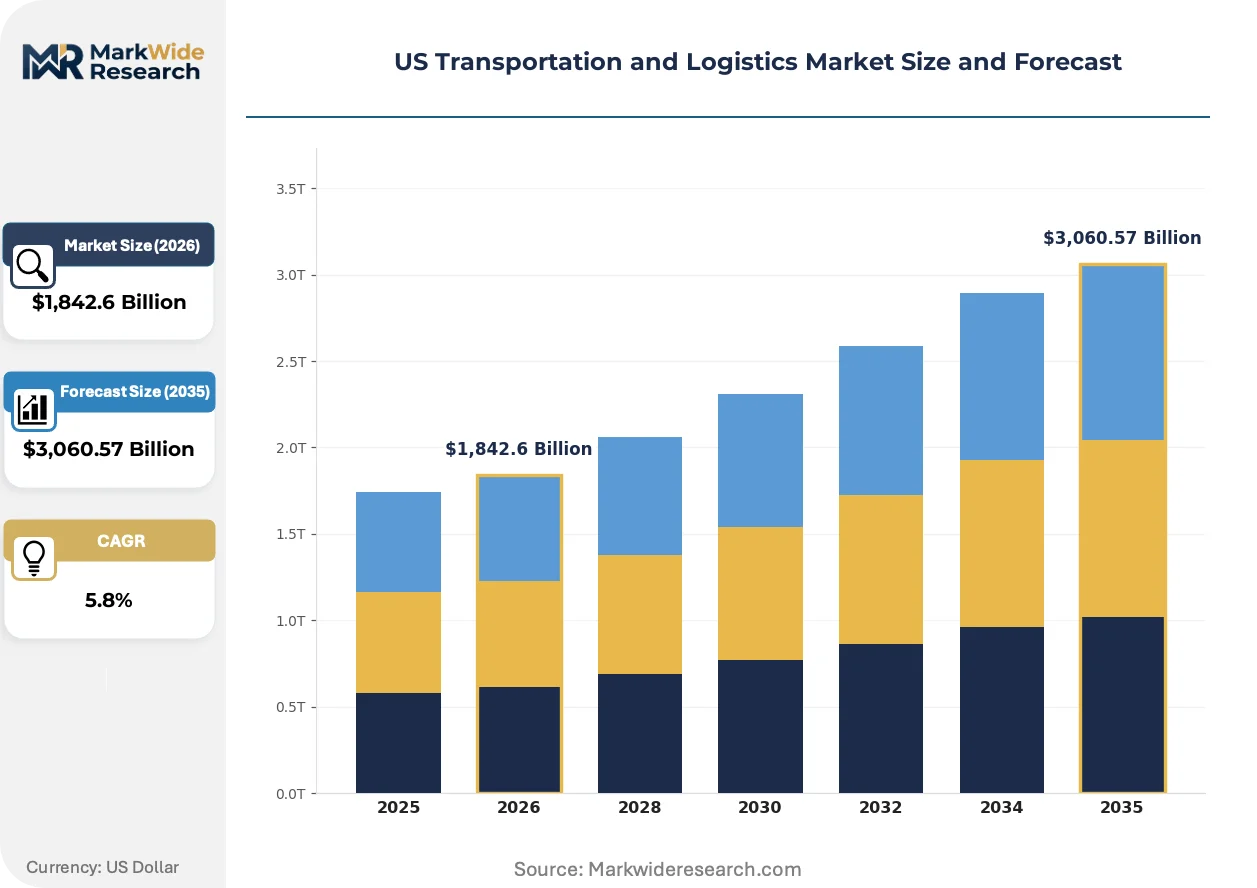
| Market Size in 2026 | $1,842.6 Billion |
| Market Size in 2035 | $3,060.57 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Freight Shipping, Warehousing, Last-Mile Delivery, Supply Chain Management Transportation Mode: Road, Rail, Air, Maritime End User: E-commerce, Retail, Manufacturing, Healthcare Technology: Telematics, IoT, Automated Systems, Blockchain |
| Companies Covered | Knight-Swift Transportation, C.H. Robinson, UPS, Old Dominion Freight Line, XPO Logistics, FedEx, Schneider National, Ryder System, J.B. Hunt Transport Services, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Transportation and Logistics Market Trends and Innovations
Digital freight-matching platforms are compressing broker margins while trailer telematics and warehouse robotics reshape asset utilization economics across modes.
Autonomous yard tractors are absorbing dock scheduling inefficiencies at distribution centers. Retailers and third-party logistics providers are deploying these systems to compress trailer dwell times and reduce chassis detention fees. The technology is absorbing labor variability in high-turnover environments while enabling 24-hour gate operations.
The EPA's Phase 3 greenhouse gas standards are forcing powertrain diversification across heavy-duty fleets. Engine manufacturers are accelerating natural gas and battery-electric platform development to meet fleet-average emissions targets. Long-haul operators are responding with pilot deployments in California corridors where state incentives offset capital premiums.
Shippers are unbundling single-carrier contracts into multi-provider stacks that separate line-haul, warehousing, and final-mile execution. This procurement fragmentation is displacing traditional annual rate negotiations with modular service purchasing. Food and beverage manufacturers are most visibly adopting this model to match volatile seasonal demand patterns.
US Transportation and Logistics Market Segmentation
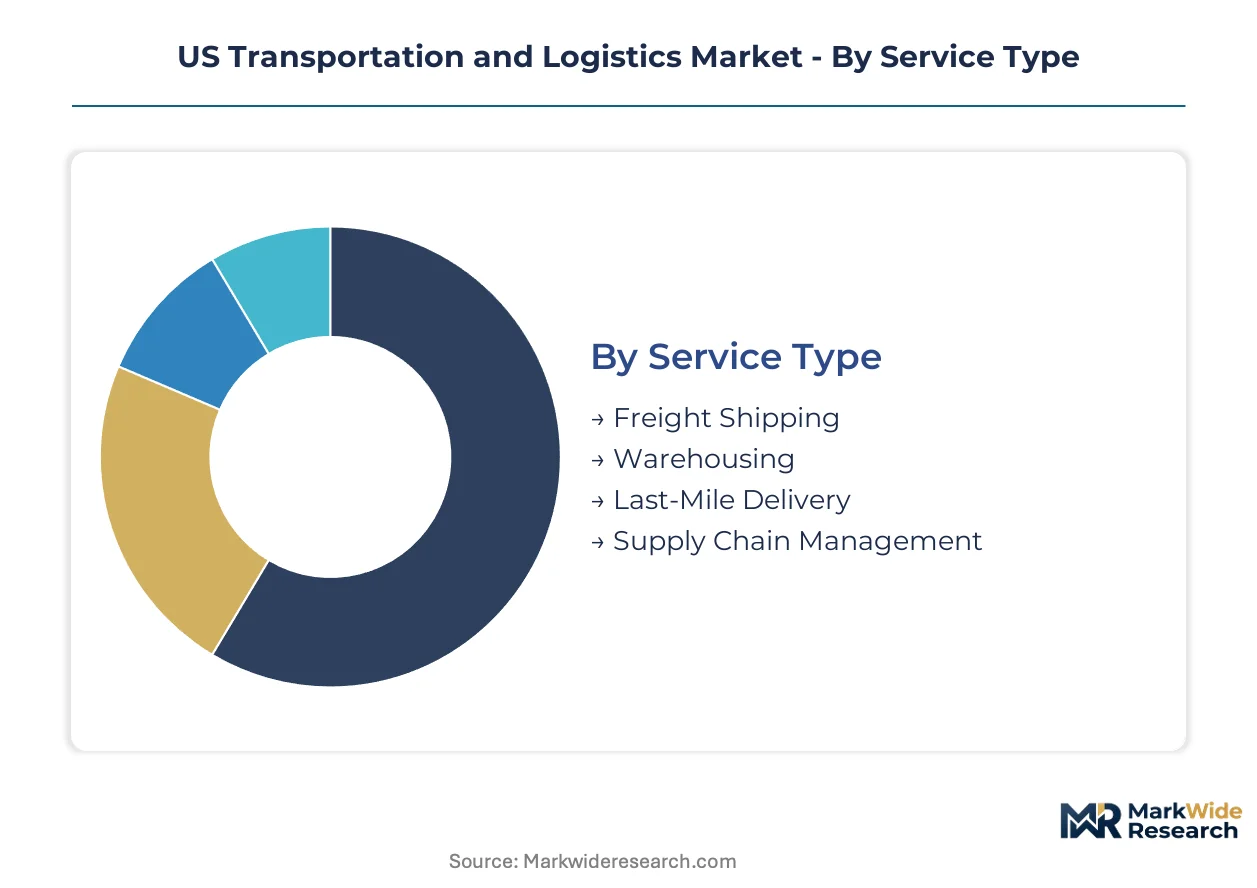
Segmentation in the US Transportation and Logistics Market reveals how capital allocation and operational priorities diverge across service layers, modal infrastructure, and technology adoption curves. Shippers and carriers make fundamentally different investment decisions depending on which segment combination they target.
Service Type:
Standalone service providers compete against integrated operators offering bundled execution across multiple segments.
- Freight Shipping:Contracted line-haul movements using asset-based or brokered truck capacity, rail intermodal, and domestic air freight. Manufacturing shippers in the Midwest and Southeast anchor contracted volume commitments that stabilize fleet utilization through seasonal demand swings.
- Warehousing:Climate-controlled and ambient storage facilities with value-added services including kitting, labeling, and returns processing. Distribution centers cluster within 50 miles of Dallas, Chicago, and Atlanta metropolitan zones to minimize final-mile transit times.
- Last-Mile Delivery:Residential parcel execution through dedicated fleets, gig-economy drivers, and locker networks. E-commerce order frequency above 100 packages per capita annually in dense coastal metros is compressing delivery windows toward same-day and next-day service levels.
- Supply Chain Management:Third-party orchestration of procurement, inventory positioning, and multi-modal routing decisions. Retailers with seasonal demand volatility outsource planning complexity to preserve working capital flexibility.
Freight Shipping leads volumes today; Last-Mile Delivery is gaining share fastest.
Transportation Mode:
Cost structures and transit reliability vary dramatically across modal choices, with fuel exposure and lane density determining competitive position.
- Road:Drayage, long-haul trucking, and dedicated fleet operations using the national highway system. The Texas-California corridor generates the highest tonnage density, though driver hour constraints under FMCSA rules limit capacity expansion regardless of freight demand signals.
- Rail:Bulk commodity movements and intermodal container service on Class I networks. BNSF and Union Pacific compete for intermodal volume along I-10 and I-35 corridors where fuel efficiency offsets slower transit times against trucking alternatives.
- Air:Time-definite express cargo and integrated belly freight on domestic passenger networks. Pharmaceutical and electronics shippers absorb premium rates for delivery velocity that road and rail cannot match.
- Maritime:Coastal barge movements and short-sea shipping connecting Gulf and Atlantic ports. Petrochemical and agricultural bulk flows dominate this modal choice where waterway access reduces per-ton-mile costs below surface alternatives.
Road transport anchors modal tonnage; intermodal Rail is climbing the fastest as shippers seek fuel cost insulation.
End User:
Demand patterns and service requirements diverge sharply across customer industries, with inventory velocity and delivery precision driving procurement priorities.
- E-commerce:Pure-play online retailers and marketplace platforms requiring parcel sortation hubs and urban micro-fulfillment nodes. Residential delivery density in California, New York, and Florida metros is forcing automation investment to preserve unit economics.
- Retail:Omnichannel operators balancing store replenishment with direct-to-consumer fulfillment. Seasonal demand peaks around holiday windows create capacity procurement challenges that favor flexible multi-provider arrangements.
- Manufacturing:Automotive, aerospace, and industrial goods producers with just-in-time inventory requirements. Supplier park proximity to assembly plants in Michigan, Alabama, and South Carolina determines modal and warehousing choices.
- Healthcare:Pharmaceutical distributors and medical device manufacturers with temperature-controlled and regulatory-compliant handling needs. Cold-chain infrastructure investments concentrate near FDA-registered distribution hubs.
E-commerce commands the steepest logistics spend growth; Healthcare is expanding most quickly on a smaller base.
Technology:
Technology deployment separates asset-heavy operators from digital intermediaries, with integration depth determining data utility and automation returns.
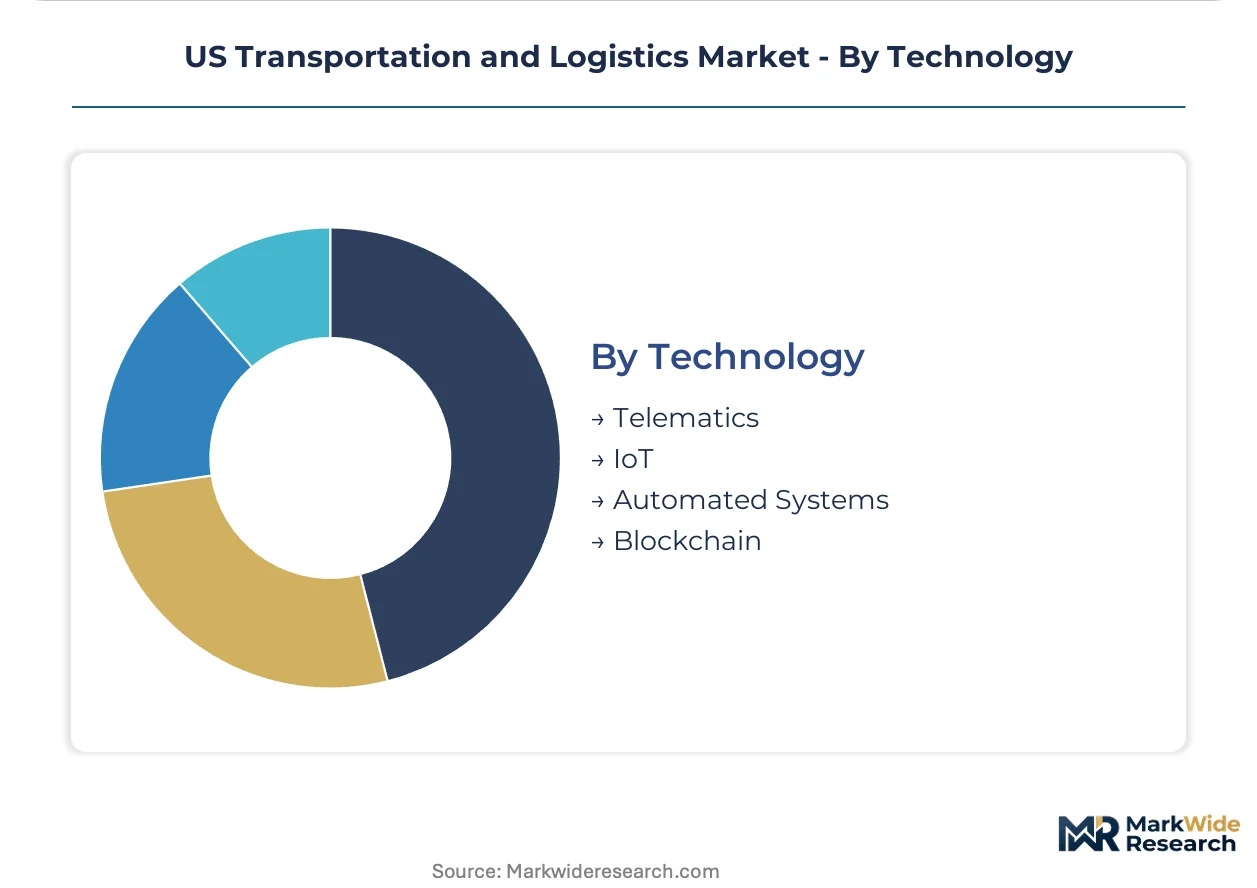
- Telematics:GPS-enabled trailer and tractor tracking systems providing location, fuel consumption, and driver behavior data. Fleet operators deploy these systems to optimize routing and reduce insurance premiums through risk scoring.
- IoT:Sensor networks monitoring cargo condition, chassis location, and warehouse environmental parameters. Pharmaceutical and food shippers mandate temperature logging that creates audit trails for FDA and USDA compliance.
- Automated Systems:Robotic sortation, autonomous yard tractors, and warehouse management software integration. Distribution centers in the Inland Empire and Dallas-Fort Worth deploy these technologies to offset cross-dock labor availability constraints.
- Blockchain:Distributed ledger applications for documentation authenticity and supply chain provenance tracking. International freight forwarders pilot these systems for customs brokerage efficiency, though domestic adoption remains limited.
Telematics saturates fleet deployments; Automated Systems is gaining investment share fastest as warehouse labor costs rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US transportation and logistics industry traces its modern scale to the post-World War II interstate highway system expansion, which enabled national freight networks to replace fragmented regional haulage. Federal infrastructure investment through the 1950s-60s established the physical backbone that today's intermodal operators still exploit.
Texas
Petrochemical exports through Gulf Coast ports and cross-border manufacturing supply chains generate the highest freight tonnage density nationally. The Texas Department of Transportation's I-35 corridor expansion program addresses congestion at Dallas-Fort Worth intermodal terminals. The Dallas-Fort Worth-Arlington metroplex anchors distribution center construction within 50 miles of 80% of the US population reachable in two days.
California
Port of Los Angeles-Long Beach container throughput and agricultural export volumes from the Central Valley sustain heavy truck and rail demand. The California Air Resources Board's Advanced Clean Trucks regulation mandates zero-emission vehicle sales quotas that reshape fleet procurement timelines. The Inland Empire warehouse cluster east of Los Angeles concentrates automated sortation hub investment to serve e-commerce fulfillment networks.
Illinois
Chicago's position as the primary rail interchange hub for transcontinental freight creates intermodal terminal density unmatched elsewhere. The Illinois Commerce Commission's freight rail safety oversight shapes corridor capacity allocation between passenger and cargo movements. The I-55 corridor linking Chicago to St. Louis hosts automotive supplier parks that demand just-in-time trucking precision.
Georgia
Savannah Port expansion and Atlanta's air cargo hub status position the state as a Southeast logistics gateway. The Georgia Department of Transportation's FAST Lane infrastructure program accelerates port connector highway improvements. The I-75 corridor through Atlanta concentrates cold-chain distribution centers serving pharmaceutical and food manufacturing clusters.
Washington
Pacific Northwest agricultural exports and aerospace manufacturing supply chains generate specialized heavy-haul and time-definite freight demand. The Washington State Department of Ecology's clean fuel standard incentivizes fleet electrification in Seattle-Tacoma metropolitan delivery zones. The I-5 corridor linking Seattle to Portland hosts refrigerated warehousing clusters serving Asian export markets.
US Transportation and Logistics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across service integration depth, with asset-heavy operators commanding rate premiums over brokered capacity providers. The market exhibits tiered consolidation where integrated parcel networks and specialized truckload carriers coexist alongside fragmented final-mile contractors. Three archetypes dominate: rail-highway intermodal specialists, digital freight-matching platforms, and integrated express parcel networks. Capacity expansion through autonomous trucking pilot programs and warehouse automation partnerships represent the primary competitive vectors reshaping cost structures.
Within the integrated intermodal tier, J.B. Hunt Transport Services and C.H. Robinson occupy positions that exemplify divergent capital intensity strategies, while FedEx represents premium express network density. These three anchors illustrate how service bundling separates asset-light brokerage from asset-heavy execution in shipper procurement decisions.
| Leading Market Players |
|---|
| Knight-Swift Transportation |
| C.H. Robinson |
| UPS |
| Old Dominion Freight Line |
| XPO Logistics |
| FedEx |
| Schneider National |
| Ryder System |
| J.B. Hunt Transport Services |
| Others |
Pricing and Supply Chain Analysis
Diesel fuel expenditure flows from upstream petroleum refining through fleet operating cost structures into contract rate negotiations between shippers and asset-based carriers. The EPA's Phase 3 greenhouse gas standards are forcing powertrain diversification that splits procurement into compliance tiers, with natural gas and battery-electric platforms commanding capital premiums that reshape total cost of ownership calculations across premium, standard, and economy service levels.
Pricing Analysis
Contract-based long-term offtake agreements with annual rate negotiations dominate shipper-carrier relationships, though modular service bundling is displacing single-carrier contracts. Price differentiation hinges on fuel surcharge transparency and electronic logging device compliance certification tier. Cost compression in standard line-haul services is intensifying because brokered capacity platforms compress margins through real-time freight matching. E-commerce retailers exhibit highest price sensitivity due to parcel volume density pressures, while pharmaceutical shippers absorb premium rates for temperature-controlled integrity.
Supply Chain Analysis
Single-source vulnerability sits with chassis and container equipment manufacturers concentrated in China and South Korea, where foundry capacity constraints ripple through intermodal terminal operations. The US transportation and logistics supply chain draws from steel rolling mills in Indiana and Ohio, semiconductor fabrication for telematics hardware in Taiwan, and tire production facilities across Southeast Asia. Tariff exposure on imported chassis components creates procurement risk during peak seasonal windows. Distribution runs through hub-and-spoke networks anchored by Dallas-Fort Worth, Chicago, and Atlanta metropolitan zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Transportation and Logistics Market functions as a regulatory compounder where FMCSA hours-of-service enforcement and EPA emissions mandates continuously reshape fleet economics and technology investment requirements.
For Market Incumbents: Lock in intermodal terminal capacity along the I-10 and I-35 corridors through long-term rail partnership agreements that secure lane density against digital freight-matching platform encroachment. Deepen backward integration into autonomous trucking pilot programs in Texas and Arizona to recalibrate labor-capital tradeoffs before regulatory frameworks solidify.
For New Entrants and Emerging Players: Warehouse management system integration gaps present a technology-first wedge for specialized software vendors targeting mid-market third-party logistics providers with legacy enterprise resource planning architectures. Final-mile electrification in California urban delivery zones offers the most penetrable segment, with electric step-van deployment supported by state incentive programs and zero-emission vehicle access mandates.
For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented final-mile contractor networks face margin compression from e-commerce parcel volume surges and urban labor availability constraints. Acquisition targets with autonomous yard tractor deployments and automated sortation hub technology offer viable positioning across the projection horizon. Watch for FMCSA regulatory relaxation on autonomous trucking permitting as the inflection indicator for labor substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Rail-Highway Intermodal Integration | J.B. Hunt's corridor dominance demonstrates fuel cost insulation through BNSF and Union Pacific partnerships. |
| Digital Freight-Matching Platform Expansion | C.H. Robinson's broker margin compression illustrates technology displacement of traditional capacity procurement. |
| Autonomous Trucking Pilot Deployment | Supervised lane operations in Texas recalibrate driver hour constraints under FMCSA regulatory frameworks. |
| Warehouse Automation Partnership | Robotic sortation hubs in the Inland Empire offset cross-dock labor availability constraints overnight. |
| Final-Mile Electrification Program | California Air Resources Board mandates create first-mover advantage for zero-emission step-van fleets. |
Research Methodology
Multiple input streams — FMCSA regulatory filing analysis, Class I railroad waybill data, and EPA emissions compliance disclosures — were reconciled with primary interviews involving fleet operations directors, third-party logistics procurement managers, intermodal terminal supervisors, and warehouse automation engineers. Secondary validation incorporated DOT infrastructure funding allocations, ATA driver shortage reports, and SEC 10-K filings from publicly traded carriers. Bottom-up volume modeling across service types and transportation modes was triangulated against top-down macroeconomic freight demand indicators.
Data-stream reconciliation anchored the analytical framework across the projection horizon, with segmentation dimensions spanning service type, transportation mode, end-use industry, and technology adoption tier. CAGRs were derived from trend extrapolation of historical volume movements adjusted for regulatory intervention effects and infrastructure capacity constraints. Forecast inputs incorporated diesel price volatility scenarios and autonomous trucking pilot program expansion timelines without specific year anchoring.
The model holds under stable FMCSA enforcement intensity and continued EPA Phase 3 implementation; deviation in federal infrastructure funding levels or state-level autonomous vehicle permitting acceleration would shift capacity expansion trajectories. Forecasts reflect documented assumptions regarding driver availability demographics and e-commerce parcel volume growth sustainability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
US Tolling Market
Transportation & Logistics
Africa Cross Border Road Freight Transport Market
Transportation & Logistics
Germany Road Freight Transport Market
Transportation & Logistics
Italy Road Freight Transport Market
Transportation & Logistics
United States less than-Truck-Load (LTL) Market
Transportation & Logistics
North America Road Freight Transportation Market
Transportation & Logistics
Cross-Border Road Transport Market
Transportation & Logistics
Road Haulage Market
Transportation & Logistics
Germany Cold Chain Logistics Market
Transportation & Logistics
Slovakia Road Freight Transport Market
Transportation & Logistics
United States Road Freight Transport Market
Transportation & Logistics
Customs Brokerage Market
Transportation & Logistics
Europe Road Freight Transport Market
Transportation & Logistics
Automatic Vehicle Location System (AVL) Market
Transportation & Logistics
GCC International Express Service Market
Transportation & Logistics
Hazardous Chemicals Transportation Solution Market