
 India Road Freight Transport Market | 2026-2036
India Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
India Road Freight Transport Market Outlook
Last-mile delivery margins is narrowing as fleet operators shift toward hub-and-spoke consolidation and temperature-controlled services. Delhivery leverages its technology platform to optimize route density across e-commerce fulfillment. VRL Logistics anchors its position through dedicated less-than-truckload networks spanning southern and western India. Safexpress specializes in time-definite express distribution for automotive and pharmaceutical shippers.
India road freight transport encompasses the movement of goods via motorized commercial vehicles across national and state highways, secondary roads, and urban corridors, utilizing diesel, CNG, and increasingly electric powertrains with gross vehicle weights ranging from sub-one-tonne mini trucks to forty-tonne multi-axle trailers. Its primary commercial purpose is connecting manufacturing clusters, agricultural mandis, port terminals, and consumption centers through flexible, door-to-door cargo movement. Full truck load services dominate volume throughput on long-haul corridors linking Delhi-Mumbai and Chennai-Bengaluru industrial belts, while temperature-controlled segments capture premium pricing from pharmaceutical and perishable food chains. Less-than-truckload networks are expanding fastest in tier-two cities as fragmented shippers seek consolidated pickup and delivery options without minimum load commitments.
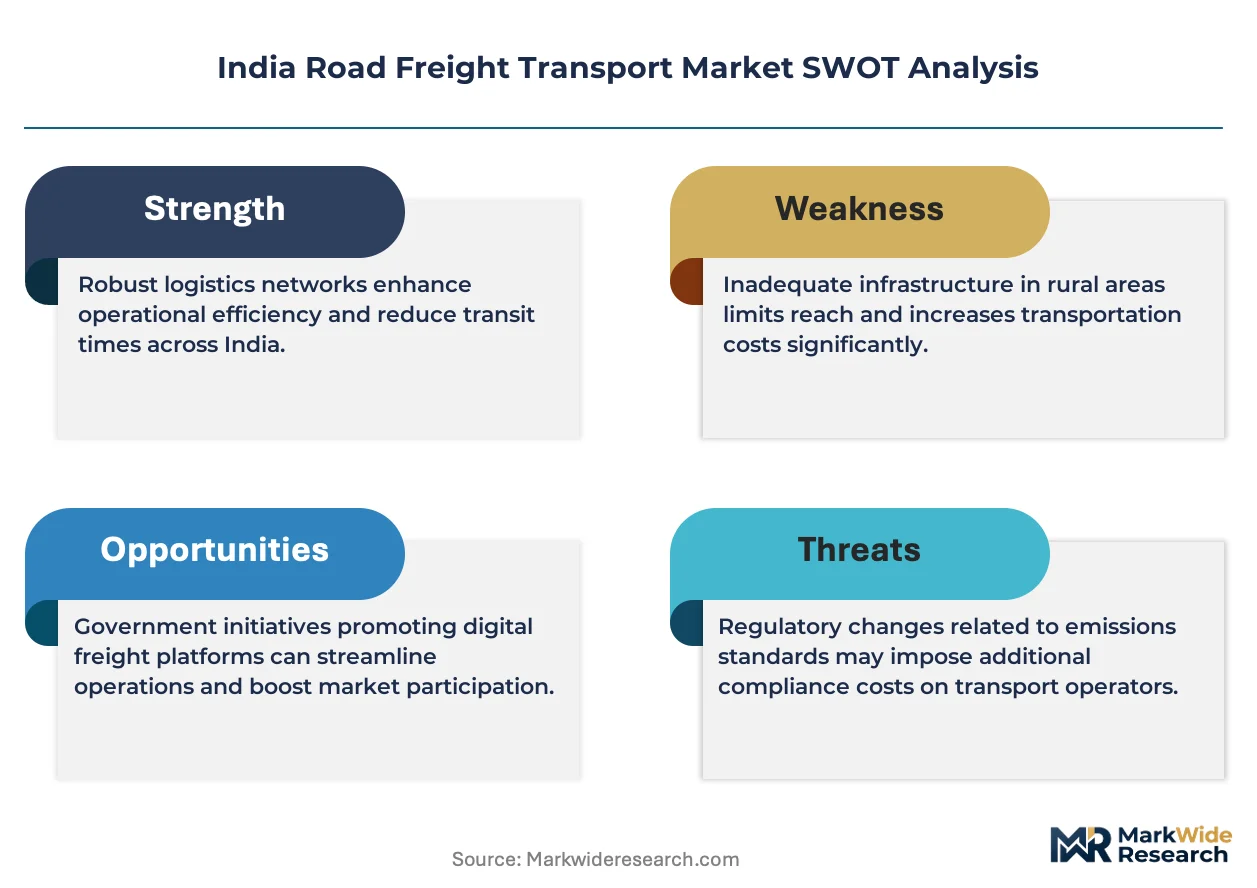
The Ministry of Road Transport and Highways enforces axle load norms and vehicle fitness standards that directly determine fleet replacement cycles and capital deployment timing. BIS certification for automotive components and CEA electrical safety mandates for charging infrastructure shape technology adoption pathways for electric commercial vehicles. State-level RTO permit regimes and the national FASTag tolling framework create compliance complexity that favors organized operators with dedicated regulatory teams. Stakeholders must monitor how the proposed national logistics policy and green hydrogen corridor announcements alter fleet composition strategies and terminal infrastructure investment priorities.
Market Dynamics
Fleet electrification timelines are compressing as BIS certification for EV components and CEA charging infrastructure mandates force asset replacement decisions ahead of natural depreciation cycles. The PLI scheme for automotive manufacturing is accelerating capital deployment toward alternative powertrains while FASTag tolling integration reshapes route economics for organized operators.
Growth Catalysts
- E-commerce fulfillment networks:Tier-two and tier-three city penetration is creating demand for consolidated pickup and delivery infrastructure without minimum load commitments.
- PLI scheme for automotive manufacturing:Production-linked incentives are lowering acquisition costs for electric commercial vehicles and modernized trailers.
- Temperature-controlled segments:Pharmaceutical cold chains and perishable food networks are commanding premium pricing for specialized fleet assets.
Market Restraints
- Diesel price volatility:Fuel constitutes the largest variable cost component for long-haul operators, compressing margins on Delhi-Mumbai and Chennai-Bengaluru corridors.
- Driver availability constraints:The fragmented owner-operator segment faces acute shortages of qualified commercial license holders.
- State-level RTO permit complexity:Interstate compliance requirements favor large fleet operators with dedicated regulatory teams, raising barriers for smaller competitors.
Strategic Opportunities
- Hub-and-spoke consolidation:Last-mile operators can capture margin expansion through centralized sorting facilities and route density optimization.
- Green hydrogen corridor announcements:Pilot freight routes under development will create first-mover advantages for fleet operators investing in compatible powertrain trials.
- Less-than-truckload networks:Southern and western India present underpenetrated markets for dedicated LTL services targeting fragmented shippers.
Industry Challenges
- Charging infrastructure deployment:CEA electrical safety mandates require specialized installation expertise that outpaces current technician supply.
- Fleet management system integration:Legacy dispatch operations face complexity migrating to telematics platforms without disrupting daily freight movements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Road Freight Transport Market |
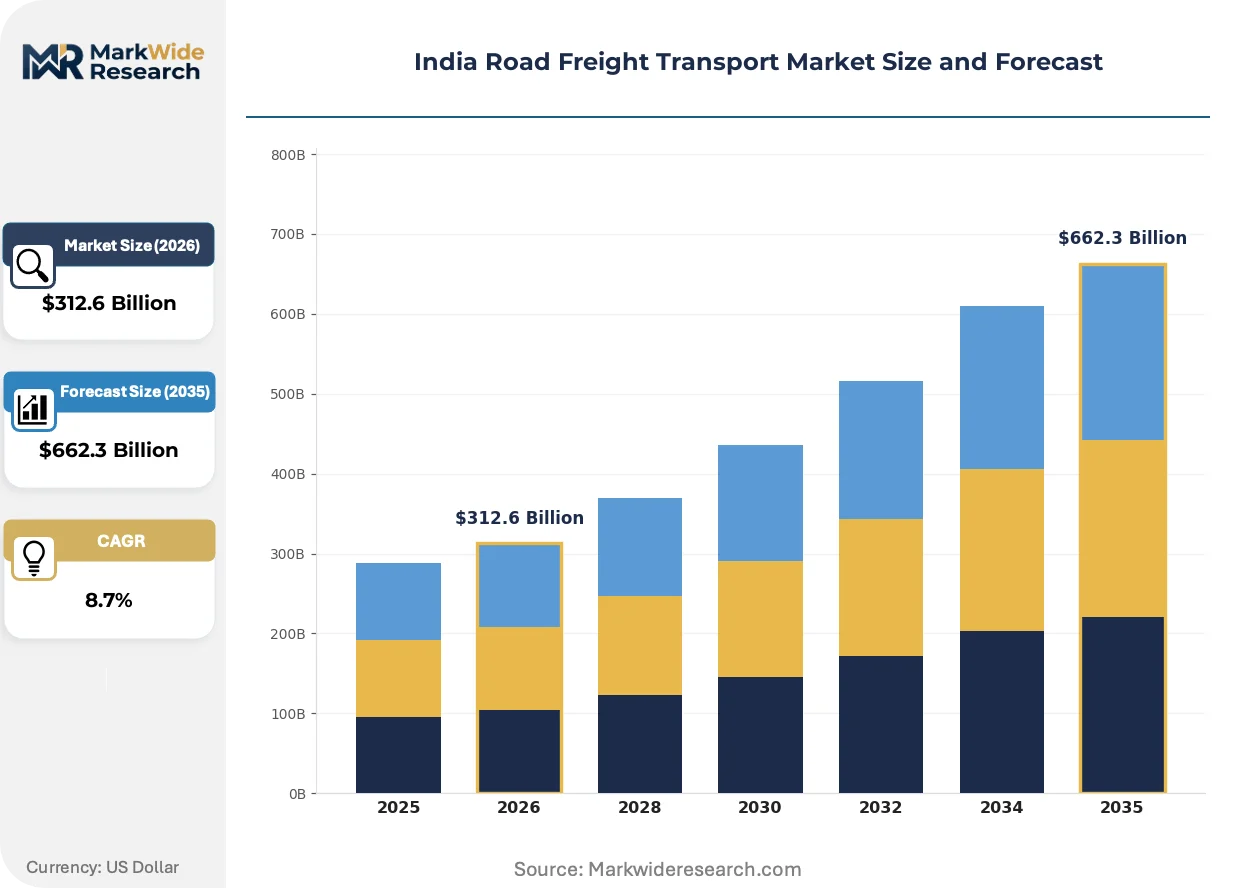
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Trucks, Vans, Trailers, Buses Service Type: Full Truck Load, Less Than Truck Load, Temperature Controlled, Hazardous Materials End User: Manufacturing, Retail, Construction, Agriculture Delivery Model: Direct Delivery, Hub and Spoke, Intermodal, Freight Forwarding |
| Companies Covered | Gati Ltd, Mahindra Logistics, Transport Corporation of India, TCI Express, Allcargo Logistics, VRL Logistics, Delhivery, V-Trans, Safexpress, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Road Freight Transport Market Strategic Shifts
Digital freight matching platforms are restructuring how cargo owners connect with available truck capacity, replacing phone-based broker networks with algorithmic load allocation. This shift is compressing information asymmetries that previously sustained intermediary margins.
Telematics-enabled predictive maintenance is collapsing unplanned downtime for multi-axle trailer fleets. Large logistics operators are deploying sensor networks across refrigerated and dry van assets to anticipate component failures before roadside breakdowns occur. The technology is collapsing maintenance cost spreads between organized fleet operators and fragmented owner-operators.
BIS certification requirements for EV powertrain components are tightening quality thresholds for battery management systems and electric axle assemblies. The Ministry of Road Transport and Highways is aligning vehicle fitness standards with electrification roadmaps, forcing component suppliers to accelerate testing cycles. Tier-one automotive suppliers are responding by consolidating validation partnerships with certified testing laboratories.
Shippers are unbundling long-term contracts in favor of spot-market procurement for non-core freight lanes. E-commerce fulfillment networks are driving this behavioral shift, prioritizing flexibility over rate predictability for seasonal volume spikes. The pattern is most visible in Maharashtra and Karnataka, where industrial corridor density supports rapid carrier switching.
India Road Freight Transport Market Segmentation
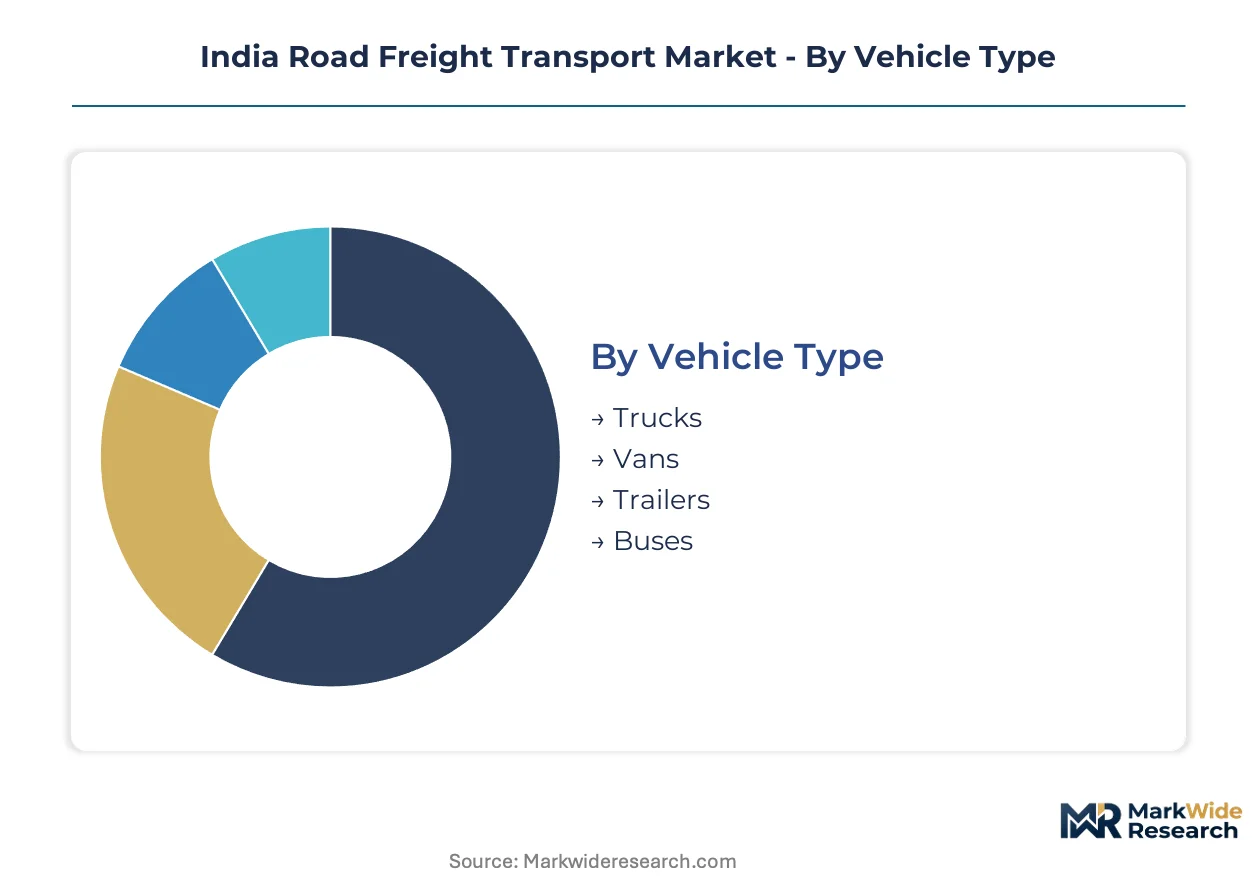
Road freight segmentation in India reflects the tension between long-haul corridor economics and last-mile density requirements. Vehicle classification, service configuration, and delivery architecture each determine capital deployment and margin structure for fleet operators across Maharashtra, Gujarat, and Karnataka industrial belts.
Vehicle Type:
Vehicle classification spans payload ranges from sub-one-tonne urban distribution to forty-tonne multi-axle interstate haulage, with powertrain choices increasingly shaped by BIS certification timelines and CEA charging mandates.
- Trucks:Multi-axle diesel and CNG vehicles dominate Delhi-Mumbai and Chennai-Bengaluru corridors, with gross vehicle weights from 16 to 40 tonnes. Fleet operators in Gujarat and Maharashtra are accelerating replacement cycles ahead of BIS-mandated fitness standard revisions.
- Vans:Compact commercial vehicles below 3.5 tonnes handle tier-two and tier-three city penetration for e-commerce fulfillment networks. Demand concentrates in Karnataka and Tamil Nadu where hub-and-spoke consolidation requires flexible last-mile capacity without minimum load commitments.
- Trailers:Containerized and flatbed configurations serve port connectivity from JNPT, Mundra, and Chennai terminals. Organized operators deploy sensor-enabled refrigerated and dry van assets for predictive maintenance advantages.
- Buses:Cargo-converted and dedicated freight bus services operate on fixed-route schedules between state capitals and industrial clusters. Karnataka and Tamil Nadu RTO permit regimes favor scheduled operators with dedicated regulatory compliance teams.
Established volume favors trucks; emerging adoption favors vans.
Service Type:
Service configuration determines pricing architecture and asset utilization, with temperature-controlled and consolidated offerings commanding premium positioning over commodity full-truck movements.
- Full Truck Load:Dedicated vehicle allocation for single-shipper cargo dominates volume throughput on long-haul corridors. FTL services anchor revenue for operators across Delhi-Mumbai industrial belts where manufacturing clusters generate predictable lane density.
- Less Than Truck Load:Consolidated pickup and delivery without minimum load commitments is expanding fastest in tier-two cities. Southern and western India present underpenetrated markets for dedicated LTL networks targeting fragmented shippers.
- Temperature Controlled:Refrigerated units serving pharmaceutical cold chains and perishable food networks capture premium pricing. CDSCO pharmaceutical distribution mandates and FSSAI food safety requirements drive specialized fleet investment.
- Hazardous Materials:DGFT-licensed carriage of chemicals, fuels, and industrial gases requires specialized driver certification and vehicle placarding. Maharashtra and Gujarat petrochemical corridors concentrate demand for compliant Hazmat capacity.
Full Truck Load retains margin stability; temperature-controlled services are gaining share fastest.
End User:
End-use segmentation tracks industrial output geography, with manufacturing and retail concentration in western and southern states driving corridor-specific fleet deployment.
- Manufacturing:Automotive, electronics, and engineering goods shippers in Pune, Chennai, and Gurgaon generate scheduled lane requirements. PLI scheme incentives for automotive manufacturing are reshaping fleet modernization timelines.
- Retail:E-commerce fulfillment networks and FMCG distribution drive demand for flexible, non-committed capacity. Tier-two city penetration is creating infrastructure requirements for consolidated pickup and delivery.
- Construction:Cement, steel, and project cargo movements follow infrastructure investment cycles across state highway and industrial corridor projects. Karnataka and Tamil Nadu road building programs concentrate demand.
- Agriculture:Mandi-to-warehouse and cold chain movements from Punjab, Haryana, and western Uttar Pradesh require seasonal surge capacity. Perishable horticulture exports through Mumbai and Chennai ports drive refrigerated investment.
Manufacturing anchors contracted revenue; retail drives spot-market expansion.
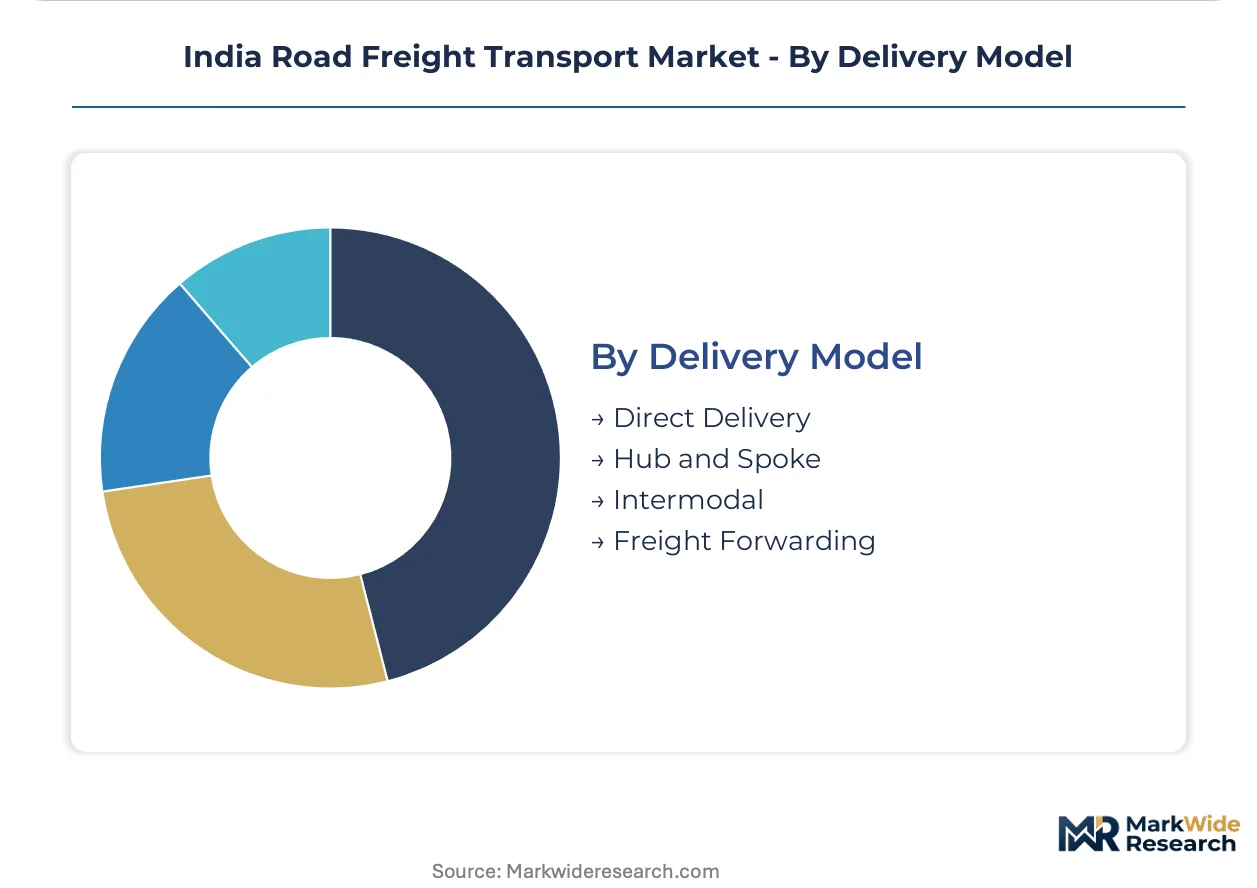
Delivery Model:
Delivery architecture determines terminal infrastructure requirements and route economics, with hub-and-spoke consolidation offering margin recovery against direct point-to-point operations.
- Direct Delivery:Point-to-point movements without intermediate handling serve time-critical manufacturing and pharmaceutical shippers. Safexpress and similar operators deploy direct lanes for automotive and pharmaceutical time-definite requirements.
- Hub and Spoke:Centralized sorting facilities enable route density optimization and last-mile margin recovery. Delhivery leverages technology platforms to optimize consolidation across e-commerce fulfillment networks.
- Intermodal:Rail-road and coastal-road combinations reduce diesel exposure on long-haul corridors. Dedicated freight corridors and coastal shipping integration reshape economics for Delhi-Mumbai and Chennai-Bengaluru lanes.
- Freight Forwarding:Third-party coordination of multi-leg movements serves export-import shippers through JNPT, Mundra, and Chennai terminals. Organized forwarders with FASTag integration capture margin from fragmented broker networks.
Direct delivery retains premium positioning; hub-and-spoke models are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra, Gujarat, and Karnataka consume road freight services differently from tier-two hinterlands, with western industrial belts demanding scheduled manufacturing lanes while southern corridors prioritize e-commerce flexibility and temperature-controlled pharmaceutical distribution.
Maharashtra
Pune automotive clusters and Mumbai port traffic generate dense full-truck-load demand on Delhi-Mumbai industrial belts. The state RTO permit regime under the Ministry of Road Transport and Highways enforces interstate compliance complexity that favors organized operators with dedicated regulatory teams. JNPT terminal connectivity and the Mumbai-Pune Expressway concentrate containerized trailer deployment for export-import shippers.
Gujarat
Mundra port operations and petrochemical corridors in Hazira drive hazardous materials carriage requirements under DGFT licensing mandates. The state offers favorable RTO permit structures for scheduled freight bus services linking Ahmedabad with industrial clusters. Sanand automotive manufacturing zones generate scheduled lane density for automotive component suppliers.
Karnataka
Bengaluru electronics manufacturing and e-commerce fulfillment networks create divergent demand patterns—scheduled lanes for PLI scheme automotive suppliers, flexible capacity for retail distribution. BIS certification timelines for EV components are compressing fleet replacement cycles in the state. Hosur and Peenya industrial belts anchor less-than-truckload network expansion.
Tamil Nadu
Chennai automotive manufacturing and Sriperumbudur electronics clusters generate time-definite express requirements. The state RTO permit regime favors dedicated regulatory compliance teams for interstate operations. Ennore and Chennai port terminals concentrate refrigerated trailer investment for perishable horticulture exports.
Telangana
Hyderabad pharmaceutical distribution and emerging data center construction drive temperature-controlled and project cargo demand. FASTag tolling integration reshapes route economics for organized operators on Hyderabad-Mumbai and Hyderabad-Chennai corridors. The Genome Valley pharmaceutical cluster commands specialized cold chain fleet assets under CDSCO distribution mandates.
India Road Freight Transport Market Competitive Environment
Capability concentration sits with technology-integrated operators; scale advantage sits with legacy fleet owners. The vendor base spans three tiers: national express networks with dedicated less-than-truckload infrastructure, regional full-truck-load specialists anchoring corridor density, and fragmented owner-operators serving spot markets. Dominant competitive moves include hub-and-spoke terminal consolidation and telematics platform deployment for route optimization.
Among technology-integrated platforms, Delhivery and VRL Logistics represent the capability-driven archetype, while Safexpress anchors the time-definite express tier. Transport Corporation of India sits within the diversified logistics conglomerate segment with multi-modal service breadth. These operators exemplify how FASTag integration and BIS-certified EV procurement are separating organized fleet operators from fragmented competitors.
| Leading Market Players |
|---|
| Gati Ltd |
| Mahindra Logistics |
| Transport Corporation of India |
| TCI Express |
| Allcargo Logistics |
| VRL Logistics |
| Delhivery |
| V-Trans |
| Safexpress |
| Others |
Value Chain & Pricing Dynamics
Maharashtra's Pune automotive clusters and Mumbai port terminals concentrate fleet capacity deployment, translating upstream asset density into downstream rate-setting power for organized operators across Delhi-Mumbai industrial belts. Diesel price volatility feeds directly into spot-market rate adjustments, while long-term manufacturing contracts insulate scheduled lane operators from margin compression.
Pricing Analysis
Long-term offtake agreements anchor revenue stability for full-truck-load operators serving Pune automotive clusters and Chennai manufacturing belts, while spot-market procurement dominates e-commerce fulfillment networks prioritizing flexibility over rate predictability. Price differentiation rests on temperature-control certification tier and route density optimization, with CDSCO-compliant pharmaceutical cold chains commanding premium positioning over commodity dry freight. Cost compression in last-mile segments is intensifying because hub-and-spoke consolidation investments lag demand growth in tier-two cities. Fragmented owner-operators exhibit highest price sensitivity due to diesel exposure and FASTag compliance burdens, while organized fleet operators with dedicated regulatory teams absorb margin pressure through scale.
Supply Chain Analysis
Ashok Leyland, Tata Motors, and Mahindra & Mahindra concentrate domestic commercial vehicle manufacturing capacity across Tamil Nadu, Maharashtra, and Gujarat production hubs. Battery cell supply draws from China and South Korea, while axle assemblies and telematics hardware source from Germany and Japan. Single-source vulnerability in lithium-ion cell supply creates fleet electrification risk as BIS certification timelines compress replacement cycles. Distribution runs through manufacturer-authorized dealerships and direct fleet sales channels, with aftermarket parts flowing via regional distribution centers anchored to industrial corridor density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India road freight transport sits at a high-growth inflection as PLI scheme incentives and BIS-mandated EV fitness standards force asset replacement decisions ahead of natural depreciation cycles.
For Market Incumbents: Pre-empt margin erosion by accelerating backward integration into charging infrastructure deployment and captive maintenance networks before CEA electrical safety mandates widen compliance gaps. Consolidate hub-and-spoke terminal density across Karnataka and Tamil Nadu industrial belts to capture route optimization advantages that fragmented competitors cannot replicate. Threat substitution from digital freight matching platforms demands telematics platform deployment as a defensive necessity. For New Entrants and Emerging Players: Build out dedicated less-than-truckload networks in southern and western India where underpenetrated tier-two cities offer white-space expansion without incumbent density advantages. Target temperature-controlled pharmaceutical distribution in Telangana's Genome Valley cluster, where CDSCO compliance requirements create specialized barrier-to-entry moats. Go-to-market positioning should emphasize FASTag-integrated fleet management systems as a service differentiation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors organized operators with BIS-certified EV procurement pipelines and dedicated regulatory compliance teams over fragmented asset-light models. Long-term viability across the analysis window hinges on electrification roadmap execution and charging infrastructure access rights. Acquisition focus should center on fleet operators with established terminal infrastructure in Maharashtra and Gujarat corridors. Signal to monitor: state-level RTO permit simplification announcements that would lower barriers for scaled competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Hub-and-Spoke Terminal Consolidation | Delhivery's platform optimization demonstrates route density recovery in e-commerce fulfillment networks. |
| Electric Fleet Procurement Pipeline | BIS certification timelines force organized operators into accelerated asset replacement cycles ahead of competitors. |
| Temperature-Controlled Capacity Expansion | CDSCO pharmaceutical mandates and FSSAI food safety requirements drive specialized refrigerated investment. |
| Telematics Platform Deployment | Predictive maintenance capabilities collapse downtime spreads between organized fleets and fragmented owner-operators. |
| Regulatory Compliance Team Investment | State-level RTO permit complexity favors dedicated teams as a competitive moat against smaller competitors. |
Study Parameters
Operator-level perspectives from fleet managers, dispatch operators, RTO compliance officers, and automotive procurement leads anchored the qualitative base for this study. Primary fieldwork combined structured interviews across Maharashtra, Gujarat, Karnataka, and Tamil Nadu logistics corridors with secondary validation from Ministry of Road Transport and Highways circulars, BIS certification registries, and FASTag transaction disclosures. Bottom-up fleet size estimates triangulated against top-down industrial output projections from manufacturing clusters.
Scenario-bracketing around PLI scheme incentive trajectories and diesel price volatility bands shaped the analytical framework across the modeling period. Segmentation dimensions included vehicle payload class, service configuration, end-use industry concentration, and delivery architecture typology. CAGRs derived from corridor-specific freight volume elasticities tied to industrial production indices and e-commerce penetration curves. Forecast inputs incorporated BIS-mandated EV fitness standard revision timelines and state-level RTO permit regime evolution.
The forecast holds incumbent behavior within observed patterns; aggressive fleet electrification moves by national express networks or unexpected PLI scheme modifications would shift outcomes materially. Quarterly review of BIS certification completion rates, FASTag penetration in tier-two cities, and state RTO permit processing times is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Europe Road Freight Transport Market
Transportation & Logistics
Mexico Customs Brokerage Market
Transportation & Logistics
US Transportation and Logistics Market
Transportation & Logistics
Freight Transport Market
Transportation & Logistics
Traction Equipment Market
Transportation & Logistics
Hazardous Chemicals Transportation Solution Market
Transportation & Logistics
Romania Road Freight Transport Market
Transportation & Logistics
Fuel Management Systems (FMS) Market
Transportation & Logistics
Europe Road Feeder Services Market
Transportation & Logistics
Thailand Road Freight Transport Market
Transportation & Logistics
Germany Road Freight Transport Market
Transportation & Logistics
Japan Cold Chain Logistics Market
Transportation & Logistics
Refrigerated Road Transportation Market
Transportation & Logistics
ASEAN Inland Waterway Freight Transport Market
Transportation & Logistics
Europe Long Haul Transport Market
Transportation & Logistics
Automatic Vehicle Location System (AVL) Market