
 United Kingdom Video Surveillance Market | 2026-2036
United Kingdom Video Surveillance Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Video Surveillance Market Insights
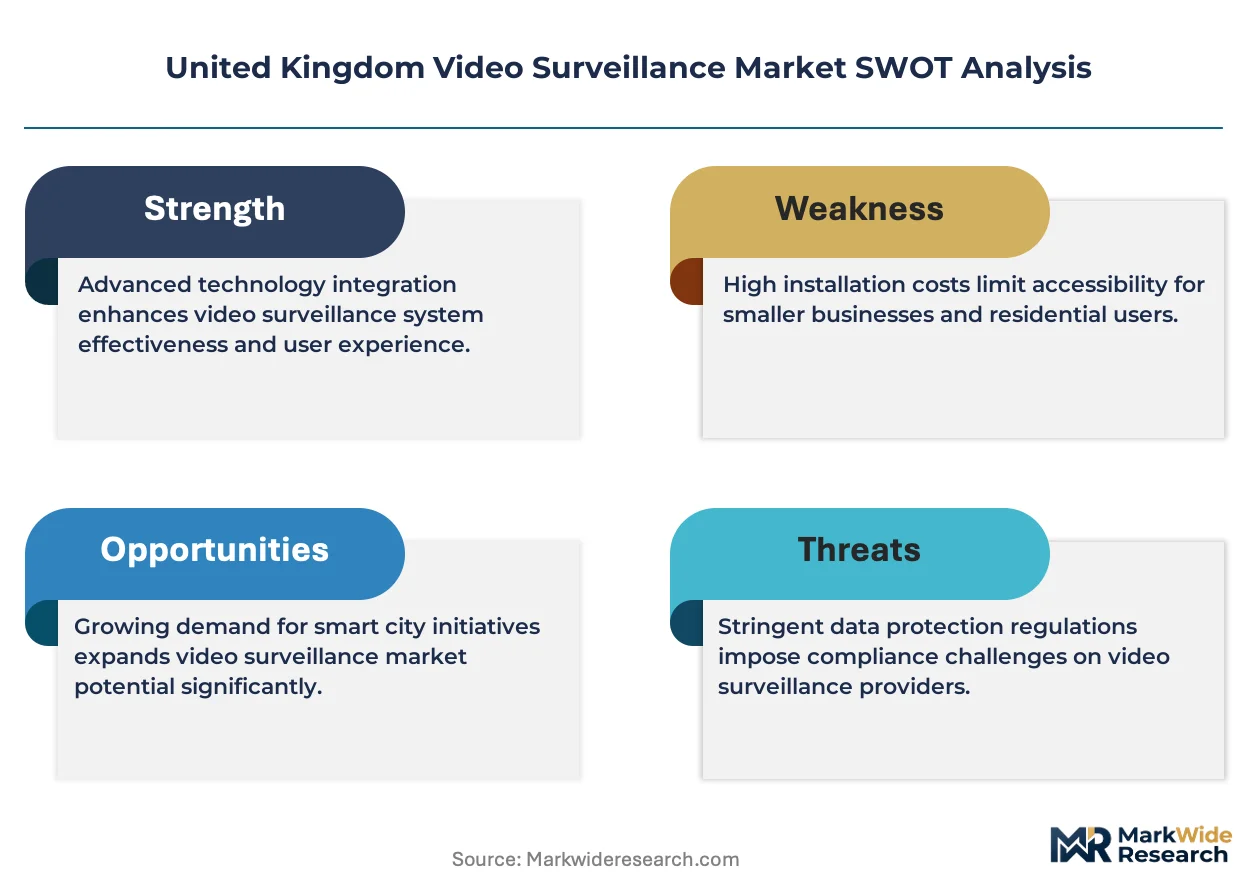
The Investigatory Powers Act is decoupling legacy analog infrastructure from public-sector eligibility, forcing councils to budget for encrypted IP-native systems. Hikvision Digital Technology Co., Ltd. leverages its manufacturing scale to dominate bulk municipal tenders. Axis Communications AB differentiates through edge-computing firmware that processes analytics locally. Bosch Security Systems anchors high-assurance contracts with police forces through its UK-certified supply chain.
Video surveillance encompasses networked camera systems, video management platforms, and storage architectures that capture, transmit, and analyze visual data for security and operational intelligence. IP cameras now dominate new installations, transmitting H.264/H.265 compressed streams over Power-over-Ethernet at resolutions up to 4K. AI-enabled technology leads structural growth, with machine-learning analytics commanding premium pricing for behavioral detection. Cloud-based deployment is displacing on-premises NVR estates in mid-tier retail and hospitality, where capital constraints favor operational expenditure models.
The Surveillance Camera Commissioner and Information Commissioner's Office jointly enforce the National Surveillance Camera Strategy and GDPR-derived data protection impact assessments. These frameworks mandate encryption, retention limits, and public signage that shape product specifications and disqualify non-compliant vendors. Stakeholders must monitor proposed amendments to the Data Protection and Digital Information Bill that could relax certain processing grounds while tightening biometric governance.
Market Dynamics
The UK's video surveillance sector is pivoting around the Investigatory Powers Act's encryption mandates, which are systematically decommissioning legacy analog estates and redirecting public procurement toward IP-native, cloud-integrated architectures.
Growth Catalysts
- Smart city infrastructure mandates:Greater Manchester's integrated command centers are deploying AI-enabled cameras with real-time behavioral analytics across transport nodes.
- GDPR-derived data protection impact assessments:Mandatory encryption and retention limit protocols are disqualifying non-compliant vendors and consolidating demand around certified suppliers.
- Financial sector security requirements:London's banking district mandates facial recognition integration with access control systems, creating premium demand for biometric-capable systems.
Market Restraints
- Semiconductor supply concentration:Image sensor fabrication depends on East Asian foundry capacity, exposing UK integrators to lead-time volatility.
- Skills gap in edge-computing deployment:Local authorities lack certified technicians for firmware-level analytics configuration, slowing rollout velocity.
- Cloud storage cost structures:Encrypted transmission and tiered retention requirements under the Investigatory Powers Act inflate operational expenditure beyond municipal budgets.
Strategic Opportunities
- Edge-computing convergence with 5G:Low-latency cellular backhaul enables real-time processing at camera nodes without fiber infrastructure.
- Retail and hospitality cloud migration:Mid-tier operators are abandoning on-premises NVR estates for subscription-based video management platforms.
- Transport authority modernization:British rail and bus operators face compliance deadlines for encrypted archiving, opening upgrade cycles.
Industry Challenges
- Legacy system integration complexity:Analog-to-IP migration requires hybrid video management platforms that strain IT departments.
- Biometric governance uncertainty:Proposed amendments to the Data Protection and Digital Information Bill threaten to tighten facial recognition deployment grounds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Video Surveillance Market |
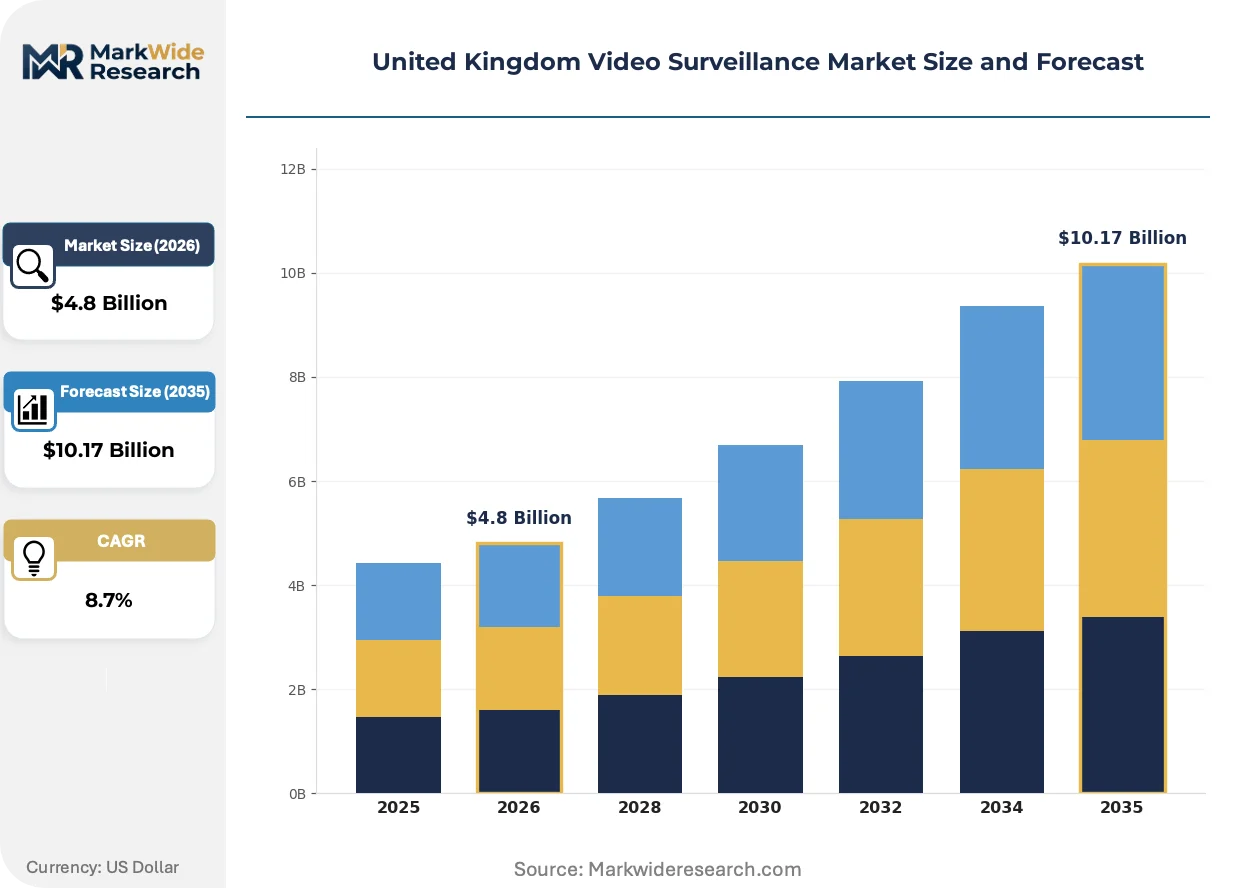
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CCTV Cameras, IP Cameras, Video Encoders, Video Management Software Installation Type: Indoor, Outdoor, Wired, Wireless End User: Retail, Transportation, Government, Hospitality Technology: Analog, Digital, Cloud-based, AI-enabled |
| Companies Covered | Bosch Security Systems, Hikvision Digital Technology Co., Ltd., Milestone Systems A/S, Honeywell International Inc, Zhejiang Dahua Technology Co., Ltd., Vivotek Inc., Synectics Plc, Hanwha Vision Co., Ltd., Axis Communications AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Video Surveillance Market Trends and Innovations
Edge-computing firmware and encrypted cloud architectures are reconfiguring how visual data is captured, processed, and stored across UK public and private estates.
Machine-learning analytics embedded at the camera node is consolidating market structure around vendors with proprietary silicon and firmware stacks. Police forces and critical infrastructure operators are prioritizing local processing to minimize bandwidth costs and latency. This technical shift is compressing margins for pure-hardware manufacturers while elevating software-defined players.
The Surveillance Camera Commissioner and Information Commissioner's Office are jointly enforcing the National Surveillance Camera Strategy alongside GDPR retention protocols. These frameworks mandate public signage, encryption standards, and data protection impact assessments that shape product specifications. Transport authorities and municipal councils are responding by embedding compliance checkpoints into procurement scoring matrices.
Subscription-based video management platforms are displacing capital-intensive on-premises NVR installations across retail and hospitality verticals. Mid-tier operators favor operational expenditure models that bundle hardware, software, and maintenance into per-camera monthly fees. This procurement evolution is most visible in London's commercial property sector, where landlords prioritize scalable, multi-tenant security infrastructure.
United Kingdom Video Surveillance Market Segmentation
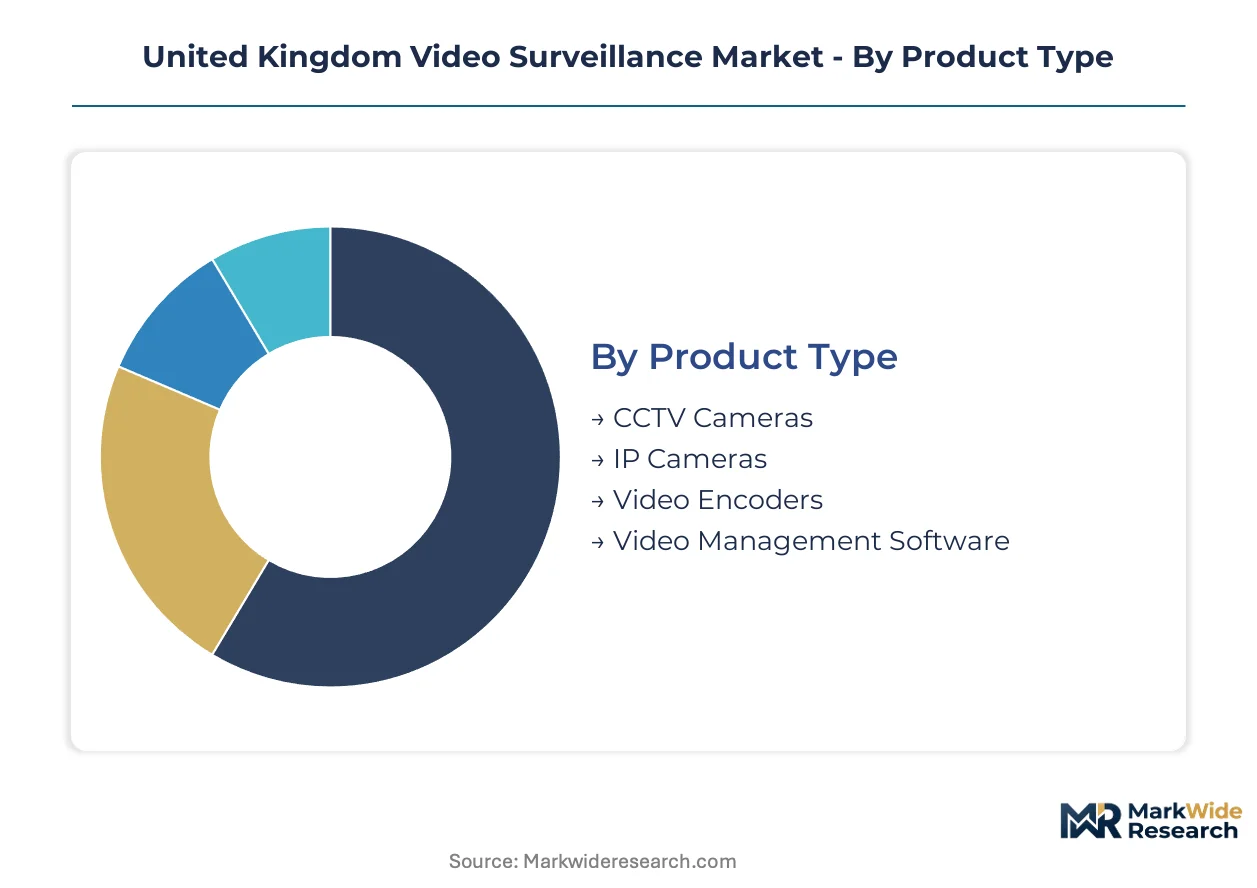
Segmentation in the United Kingdom video surveillance market reveals how procurement patterns split across technical architectures, deployment environments, and compliance requirements. Each dimension carries distinct margin profiles and vendor qualification barriers that shape competitive positioning.
Product Type:
Supply concentration in image sensor fabrication tilts procurement power toward manufacturers with captive silicon access or long-term foundry partnerships.
- IP Cameras:These units transmit H.264/H.265 compressed streams over Power-over-Ethernet at resolutions up to 4K, embedding edge-computing chipsets for local analytics. Demand clusters in London's financial district, where banks mandate facial recognition integration with access control systems and disqualify analog alternatives.
- CCTV Cameras:Legacy coaxial-based systems still service budget-constrained municipal estates, though the Investigatory Powers Act's encryption mandates are systematically decommissioning these analog installations. Greater Manchester's smart city command centers have already excluded CCTV from new transport node procurements.
- Video Encoders:Hybrid devices enabling analog-to-digital signal conversion bridge migration timelines for councils with stranded infrastructure investments.
- Video Management Software:Platform licenses governing multi-camera orchestration and encrypted cloud archiving are gaining share fastest in mid-tier retail and hospitality verticals favoring subscription models.
Today's leader: IP Cameras. Tomorrow's challenger: Video Management Software.
Installation Type:
Cost tier differentiation separates premium fiber-backhaul deployments from budget wireless configurations, with compliance complexity widening the gap.
- Outdoor:Weather-sealed housings with IP66/IP67 ratings and thermal management withstand British rail and bus operator environments. British Transport Police specifications mandate encrypted transmission and tiered retention protocols that inflate hardware costs beyond indoor equivalents.
- Wireless:Cellular backhaul via 5G enables rapid deployment at remote infrastructure nodes lacking fiber connectivity. Edge-computing convergence with low-latency networks is accelerating procurement across Greater Manchester's integrated command centers.
- Indoor:Controlled-environment specifications dominate commercial property and banking sector installations where aesthetic integration matters.
- Wired:Power-over-Ethernet remains the default for high-assurance contracts with police forces requiring guaranteed bandwidth and physical security.
Outdoor installations command premium pricing. Wireless configurations are expanding most quickly.
End User:
Customer type maturity varies sharply, with government and financial sector buyers imposing certification barriers that exclude uncertified vendors.
- Government:Central and local authority procurement operates under Surveillance Camera Commissioner and Information Commissioner's Office joint enforcement, mandating encryption, retention limits, and public signage. The National Surveillance Camera Strategy disqualifies non-compliant vendors and consolidates demand around certified suppliers.
- Transportation:British rail and bus operators face compliance deadlines for encrypted archiving under the Investigatory Powers Act, opening upgrade cycles for IP-native systems. Real-time behavioral analytics at transport nodes represent the steepest expansion trajectory within this vertical.
- Retail:Mid-tier operators are abandoning on-premises NVR estates for subscription-based video management platforms that bundle hardware, software, and maintenance into per-camera monthly fees.
- Hospitality:London's commercial property sector landlords prioritize scalable, multi-tenant security infrastructure with cloud-native management.
Government procurement sets compliance benchmarks. Transportation verticals are climbing the fastest.
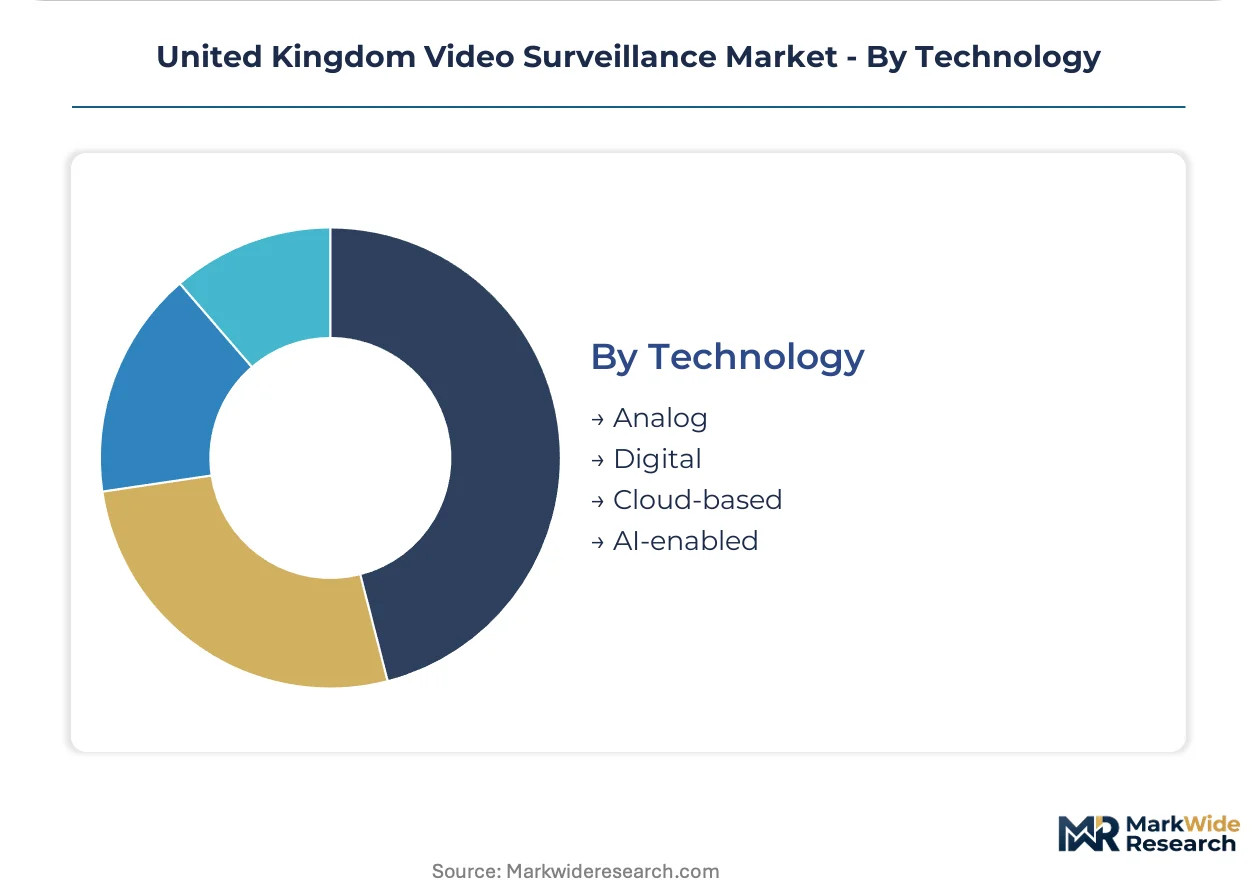
Technology:
Margin structure concentrates in AI-enabled and cloud-based architectures, where software-defined capabilities command recurring revenue streams.
- AI-enabled:Machine-learning analytics embedded at camera nodes process behavioral detection locally, minimizing bandwidth costs and latency. Police forces and critical infrastructure operators prioritize this technical shift, compressing margins for pure-hardware manufacturers while elevating vendors with proprietary silicon and firmware stacks.
- Cloud-based:Encrypted cloud storage architectures satisfy Investigatory Powers Act compliance requirements while displacing capital-intensive on-premises NVR installations. Transport authorities respond by embedding compliance checkpoints into procurement scoring matrices.
- Digital:IP-native transmission without edge analytics serves cost-sensitive applications where local processing remains unnecessary.
- Analog:Legacy signal formats are decoupling from public-sector eligibility as encryption mandates render coaxial infrastructure non-compliant.
AI-enabled systems anchor premium positioning. Cloud-based deployment is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United Kingdom's video surveillance industry traces its modern scaling to London's banking district security mandates in the 1990s, which established encrypted digital infrastructure as a procurement baseline before continental European adoption.
London and the Southeast
Financial institutions in the City of London mandate facial recognition integration with access control systems, creating concentrated demand for biometric-capable IP cameras. The Investigatory Powers Act enforces encrypted cloud storage for all transport authority deployments. Canary Wharf estate managers prioritize scalable multi-tenant security infrastructure with subscription-based management platforms.
Greater Manchester
Integrated command centers across transport nodes deploy AI-enabled cameras with real-time behavioral analytics for smart city infrastructure. The Surveillance Camera Commissioner mandates encryption and retention limit protocols that disqualify non-compliant vendors. Manchester's municipal procurement excludes analog CCTV from new tenders, accelerating IP-native system adoption.
Midlands
Manufacturing and logistics hubs generate demand for edge-computing cameras that process analytics locally to minimize bandwidth costs. The Information Commissioner's Office enforces GDPR-derived data protection impact assessments for all surveillance deployments. Birmingham's commercial property sector favors cloud-native video management platforms over capital-intensive NVR estates.
Scotland
Police Scotland specifications anchor high-assurance contracts requiring UK-certified supply chains and guaranteed bandwidth for critical infrastructure. The National Surveillance Camera Strategy mandates public signage and encryption standards that shape product specifications. Edinburgh's hospitality sector adopts subscription-based per-camera monthly fee structures for operational expenditure flexibility.
Wales
Budget-constrained municipal councils face compliance deadlines for encrypted archiving under transport authority modernization programs. The Data Protection and Digital Information Bill proposals threaten to tighten facial recognition deployment grounds, creating procurement uncertainty. Cardiff's retail operators abandon on-premises systems for bundled hardware-software-maintenance packages.
United Kingdom Video Surveillance Market Competitive Landscape
The competitive structure tilts toward manufacturing-scale specialists with captive silicon access and firmware-integrated software players. Market concentration splits between bulk municipal tender winners and premium-tier vendors serving financial sector mandates. Two strategic archetypes dominate: scale-driven hardware fabricators with East Asian manufacturing bases, and edge-computing specialists with proprietary firmware stacks. Dominant competitive moves include strategic partnerships for cloud-integrated architectures and portfolio diversification into AI-enabled analytics.
Among manufacturing-scale players, Hikvision Digital Technology Co., Ltd. and Zhejiang Dahua Technology Co., Ltd. represent the volume-driven archetype with China-based fabrication advantages. Axis Communications AB exemplifies the edge-computing specialist model with locally-processed analytics. Bosch Security Systems occupies a position anchoring high-assurance police contracts through certified supply chain positioning.
| Leading Market Players |
|---|
| Bosch Security Systems |
| Hikvision Digital Technology Co., Ltd. |
| Milestone Systems A/S |
| Honeywell International Inc |
| Zhejiang Dahua Technology Co., Ltd. |
| Vivotek Inc. |
| Synectics Plc |
| Hanwha Vision Co., Ltd. |
| Axis Communications AB |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between police-anchored high-assurance contracts and municipal commodity tenders manifests in both component sourcing and service bundling. Premium-tier vendors command captive silicon access and UK-certified supply chains, while budget-constrained councils absorb compressed margins through East Asian fabrication dependencies and stripped-down firmware configurations.
Pricing Analysis
Bundled subscription services versus unbundled hardware procurement split the market into divergent commercial models. Three-tier pricing structure across premium, standard, and economy levels aligns with Investigatory Powers Act compliance grades, where encryption-native architectures justify recurring SaaS fees against analog-to-IP migration projects priced per camera node. Cost compression in municipal tenders is intensifying because transport authorities face encrypted archiving mandates without matching budget allocations. Retail and hospitality operators exhibit highest price sensitivity, favoring per-camera monthly fees over capital-intensive NVR estates, while financial sector buyers in London's banking district absorb premium pricing for biometric-integrated access control systems.
Supply Chain Analysis
Regional distribution centers in the Netherlands and Germany anchor hub-and-spoke patterns serving UK integrators with consolidated component shipments. Image sensor fabrication draws from Taiwan, South Korea, and China, with Power-over-Ethernet chipsets and edge-computing processors similarly concentrated in East Asian foundries. Single-source vulnerability in semiconductor supply exposes UK procurement teams to lead-time volatility when transport node deployment deadlines converge. Distribution runs through certified security distributors holding Surveillance Camera Commissioner pre-qualification status, filtering non-compliant hardware before council tender evaluation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK video surveillance market functions as a regulatory compounder, where Investigatory Powers Act encryption mandates systematically decommission legacy analog estates and redirect procurement toward compliant IP-native architectures.
For Market Incumbents: Lock in firmware-level differentiation through proprietary edge-computing stacks that process analytics locally, insulating against pure-hardware margin compression from manufacturing-scale competitors. Deepen UK-certified supply chain positioning to capture high-assurance police contracts, while embedding compliance checkpoints into procurement scoring matrices before Data Protection and Digital Information Bill amendments tighten biometric governance. For New Entrants and Emerging Players: Mid-tier retail operators abandoning on-premises NVR estates represent the most penetrable buyer archetype, with subscription-based video management platforms offering operational expenditure flexibility absent from incumbent hardware-centric portfolios. Target hospitality landlords in London's commercial property sector seeking scalable multi-tenant security infrastructure, deploying cloud-native management platforms with bundled hardware-software-maintenance packages priced per camera monthly. For Investors and Strategic Acquirers: Consolidation pressure builds where edge-computing firmware capabilities concentrate among specialists with proprietary silicon partnerships, while pure-hardware manufacturers face margin compression from manufacturing-scale competitors with captive foundry access. Long-term viability favors vendors with recurring revenue streams from encrypted cloud architectures and AI-enabled analytics subscriptions. Monitor proposed Data Protection and Digital Information Bill amendments as the critical inflection signal determining facial recognition deployment permissibility.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Firmware Development | Local analytics processing at camera nodes minimizes bandwidth costs for British Transport Police specifications. |
| Cloud-Native Platform Integration | Subscription-based video management displaces capital-intensive NVR estates across retail and hospitality verticals. |
| UK Supply Chain Certification | Surveillance Camera Commissioner pre-qualification filters non-compliant vendors from municipal tender pools. |
| AI-Enabled Analytics Acquisition | Machine-learning behavioral detection capabilities command premium pricing in Greater Manchester smart city deployments. |
| 5G Cellular Backhaul Partnership | Low-latency convergence enables rapid deployment at remote infrastructure nodes lacking fiber connectivity. |
Research Methodology
Coverage spans England, Scotland, Wales, and Northern Ireland, with primary inputs from each jurisdiction's transport authorities and municipal procurement teams. The analysis combines structured interviews with surveillance system integrators, security infrastructure procurement officers, and Surveillance Camera Commissioner compliance auditors alongside secondary validation from Investigatory Powers Act regulatory filings, National Surveillance Camera Strategy documentation, and GDPR-derived Information Commissioner's Office enforcement records. Bottom-up camera deployment tallies triangulate against top-down market sizing from certified vendor shipment data.
Rate-of-change decomposition separates volume expansion from value migration across the projection horizon. Segmentation dimensions modeled include product architecture, installation environment, end-user vertical, and technology tier, with compliance-grade certification status serving as an additional industry-specific filter. CAGRs derive from polynomial trend fitting against historical procurement cycles, incorporating transport authority modernization deadlines and financial sector security mandate adoption curves as anchor points.
Underlying measurement precision varies by segment; government and transportation verticals carry tighter precision than fragmented retail and hospitality estates due to centralized procurement transparency. Forecasts reflect documented assumptions regarding regulatory amendment timelines, semiconductor supply normalization, and 5G network deployment velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
India Surveillance Analog Camera Market
Video Surveillance Systems
Hosted Video Surveillance Market
Video Surveillance Systems
Canada Surveillance Analog Camera Market
Video Surveillance Systems
Global GCC Video Surveillance Storage Market
Video Surveillance Systems
Employee Monitoring Solutions (Automated) Market
Video Surveillance Systems
Europe Video Surveillance Systems Market
Video Surveillance Systems
Smart Home Security Camera Market
Video Surveillance Systems
Global CCTV Market
Video Surveillance Systems
United States Surveillance Storage Market
Video Surveillance Systems
Canada Surveillance IP Camera Market
Video Surveillance Systems
Smart Outdoor Cameras Market
Video Surveillance Systems
United States Surveillance Analog Camera Market
Video Surveillance Systems
Asia Pacific Surveillance IP Camera Market
Video Surveillance Systems
Night Vision Outdoor Camera Market
Video Surveillance Systems
Wireless Video Surveillance Market
Video Surveillance Systems
Asia-Pacific Surveillance Analog Camera Market