
 Smart Home Security Camera Market | 2026-2036
Smart Home Security Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Home Security Camera Market Intelligence
A divergence in R&D investment between on-device AI processing and cloud-dependent analytics is bifurcating the competitive landscape. Amazon (Ring) leverages its extensive cloud ecosystem to deliver integrated services. Arlo Technologies specializes in premium hardware and subscription-based features for a dedicated user base. In contrast, Xiaomi dominates high-volume segments by offering feature-rich cameras at accessible price points in Asia.
Smart home security cameras are IP-based digital video devices that transmit footage over a network for remote viewing. They typically feature resolutions from HD to 4K, incorporate motion detection sensors, and are managed via smartphone applications. Wireless cameras command the largest share of new installations due to their installation flexibility over wired counterparts. Within technology segments, 4K cameras are displacing older HD models in the premium residential user category.
Product design and market access are shaped by a complex web of regulations. These include the EU's GDPR, which governs user data privacy, FCC standards for wireless spectrum use in the United States, and China's GB standards for electronic safety. Successfully navigating these fragmented international data sovereignty and cybersecurity requirements is critical for vendors aiming for sustained market leadership.
Market Dynamics
The central dynamic shaping the market is the bifurcation between on-device AI processing, driven by data privacy concerns, and integrated cloud services. This creates a strategic divergence in vendor R&D, product design, and business models.
Growth Catalysts
- Residential Security Demand:Homeowners' need for remote property monitoring directly supports hardware adoption, especially cameras managed via smartphone apps.
- Smart City Initiatives:Projects in geographies like China create a large consumer base accustomed to surveillance technology, easing residential adoption.
- Privacy-Enhancing Regulation:Data protection laws like GDPR push vendors to develop on-device analytics, opening a market for privacy-focused users.
Market Restraints
- Data Sovereignty Complexity:Fragmented international regulations, including the EU's GDPR, create significant compliance hurdles for vendors offering global cloud storage solutions.
- Cybersecurity Perceptions:High-profile security breaches of consumer IoT devices foster public distrust, which can slow adoption or lead users to prefer non-connected alternatives.
- Wireless Network Limitations:Performance of wireless cameras can be degraded by network congestion in smart homes with numerous connected devices, impacting reliability and user satisfaction.
Strategic Opportunities
- Specialized AI Applications:Developing on-device AI for niche tasks like pet monitoring, elderly care alerts, or specific vehicle detection offers differentiation beyond standard security.
- Service-Based Revenue Models:Expanding subscription tiers to include advanced AI analytics, professional monitoring partnerships, and interoperability with other smart home ecosystems creates recurring revenue.
- Underpenetrated Geographic Markets:Introducing affordable, easy-to-install camera systems in developing residential markets across Southeast Asia and Latin America presents a significant volume opportunity.
Industry Challenges
- Interoperability and Standardization:The absence of a universal communication standard for smart home devices complicates integration for consumers and increases development costs for manufacturers.
- Navigating Fragmented Compliance:Successfully managing a product portfolio across disparate regulatory frameworks like FCC wireless rules, EU CE marking, and Chinese GB standards is a major operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Home Security Camera Market |
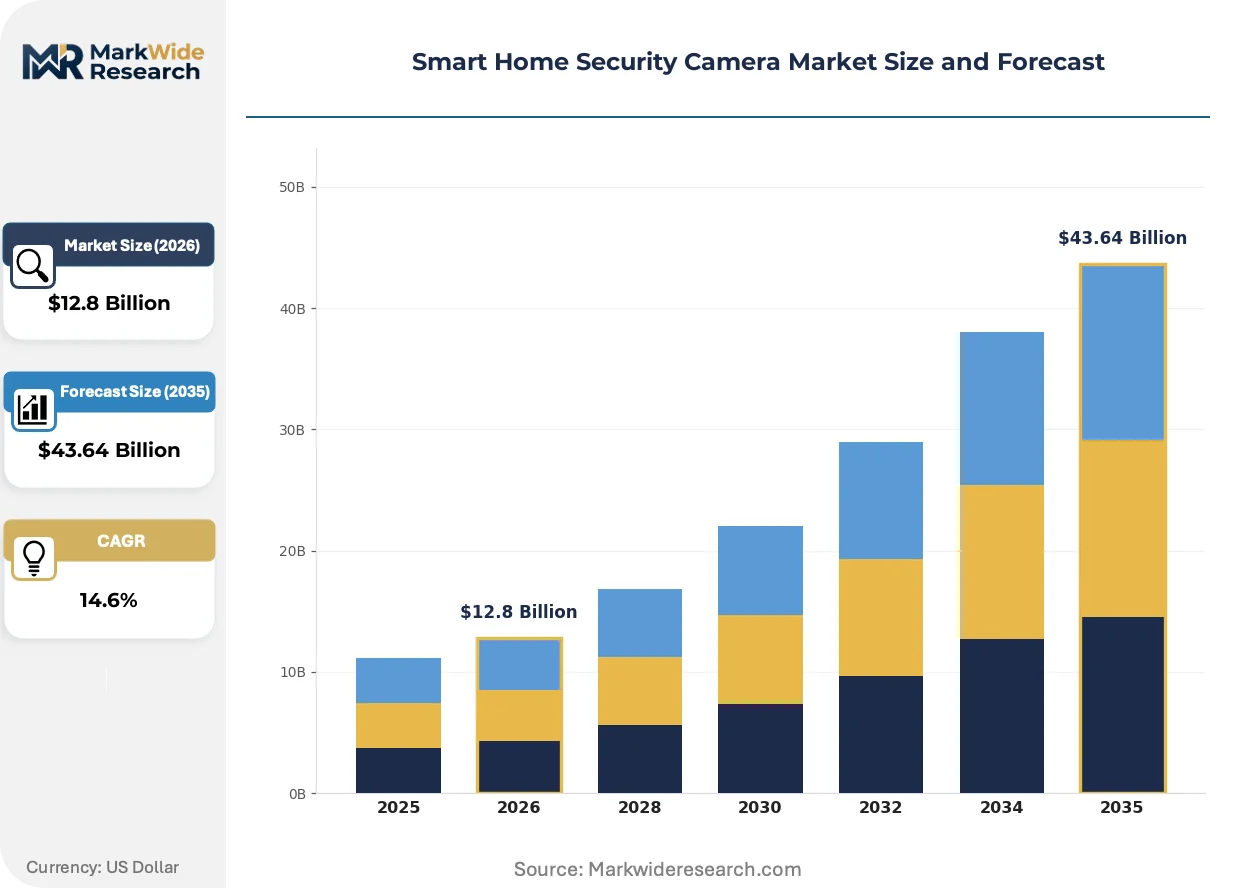
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $43.64 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired Cameras, Wireless Cameras, Indoor Cameras, Outdoor Cameras Technology: IP Cameras, Analog Cameras, HD Cameras, 4K Cameras End User: Residential Users, Small Businesses, Large Enterprises, Government Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distributors |
| Companies Covered | Samsung Electronics, Arlo Technologies, Amazon (Ring), Vivint Smart Home, ADT, SimpliSafe, Xiaomi, Eufy (Anker Innovations), Nest Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Home Security Camera Market Strategic Shifts & Innovations
Technological maturation and evolving user expectations are redefining the market's trajectory. The focus is shifting from passive video capture toward proactive, intelligent surveillance systems that prioritize user control and data security.
On-device Artificial Intelligence processes video data on the camera, reducing latency and cloud reliance. Premium residential users concerned with privacy and response speed are driving its adoption. This local processing is supplanting cloud-dependent analytics for critical, real-time functions like person detection, which enhances system responsiveness.
European Union data privacy rules, particularly the General Data Protection Regulation (GDPR), are a powerful force in product development. The regulation mandates strict controls on the collection and use of personal data, which includes video footage from security cameras. This directly impacts vendors serving the EU, compelling them to integrate privacy-by-design features and offer transparent data management tools to users.
Subscription-based services are altering the business model for security cameras. This disrupts the traditional one-time hardware sale with recurring revenue from cloud storage, advanced AI, and professional monitoring. The shift is most prominent in North American and European markets where consumers value enhanced functionality and continuous service updates.
Smart Home Security Camera Market Segmentation
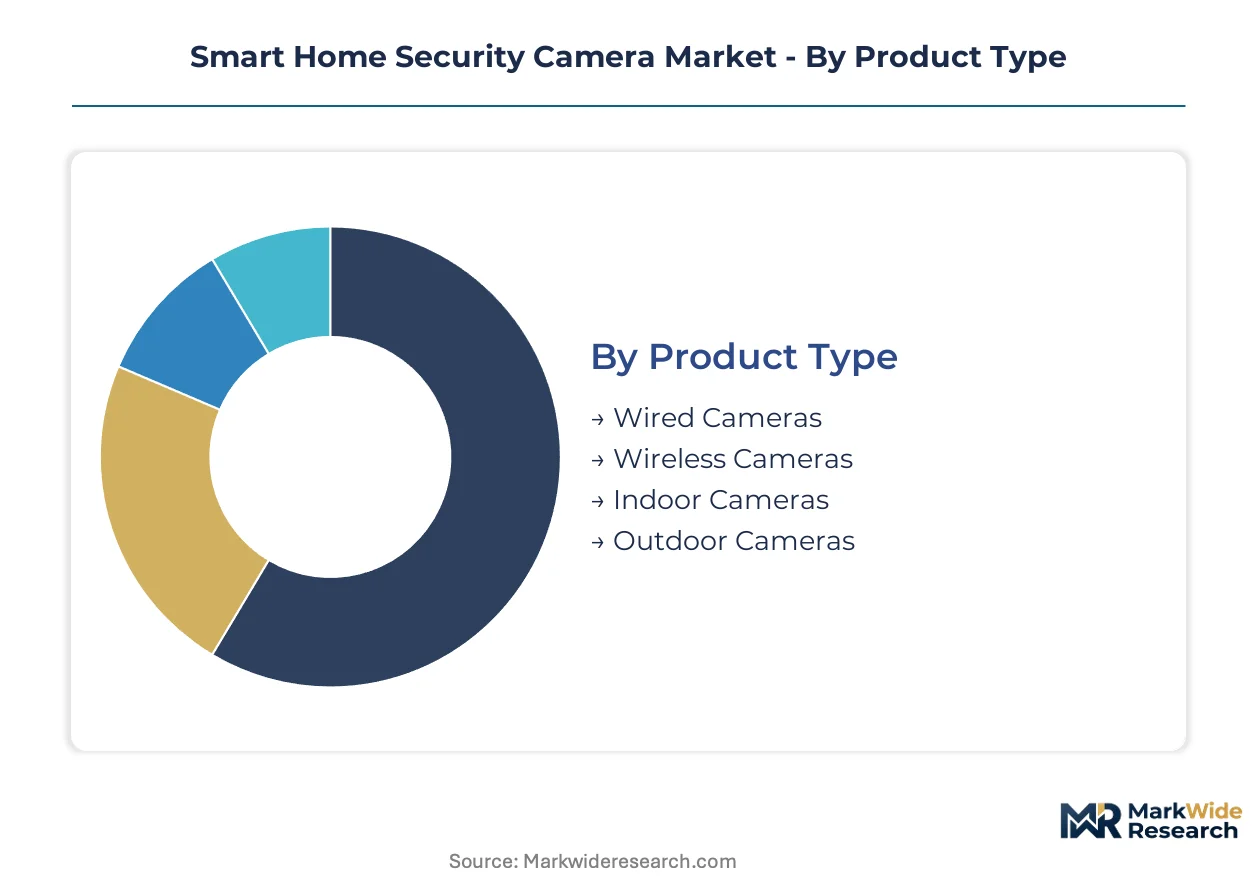
Understanding the Smart Home Security Camera Market through segmentation highlights critical areas for product innovation, market penetration strategies, and regulatory compliance. This detailed breakdown helps vendors target specific user needs and adapt offerings to diverse operational environments.
Product Type:
Regulatory frameworks for wireless spectrum use and data transmission significantly influence product type development.
- Wireless Cameras:These devices transmit video data over Wi-Fi or other wireless protocols, offering flexible placement without extensive cabling. Demand concentrates among residential users in North America and Europe, driven by ease of installation and smartphone integration.
- Outdoor Cameras:Designed for harsh environmental conditions, these units feature weatherproofing and robust construction for perimeter monitoring. Residential demand is strong in suburban areas across the US and Germany, where property protection against intruders is a primary concern.
- Wired Cameras:These cameras rely on physical cabling for power and data transmission, ensuring stable connections and enhanced security.
- Indoor Cameras:Optimized for interior spaces, these devices focus on discreet monitoring and often include features like two-way audio.
Wireless Cameras handle the majority of throughput; Outdoor Cameras are the fastest mover on share.
Technology:
Different technology tiers reflect varying cost structures and performance capabilities for video capture.
- 4K Cameras:These advanced devices capture ultra-high-definition video, providing superior image clarity and detail for forensic analysis. Premium residential users in urban centers like London and Tokyo drive demand, prioritizing image fidelity and advanced zoom features.
- IP Cameras:Leveraging internet protocols, these cameras transmit digital video streams over networks, enabling remote access and integration with smart home ecosystems. Residential and small business users in China and the US prefer IP solutions for their scalability and advanced features.
- HD Cameras:Offering high-definition resolution, these cameras provide a balance of image quality and affordability for mainstream applications.
- Analog Cameras:Older technology transmitting video over coaxial cables, these systems offer basic surveillance capabilities at lower costs.
4K Cameras are expanding most quickly, while IP Cameras maintain significant market volume.
End User:
Diverse end-user applications dictate specific feature sets and deployment scales for security cameras.
- Residential Users:Homeowners deploy these cameras for property monitoring, pet surveillance, and family safety, often managed via smartphone applications. Demand is particularly high in suburban areas of North America and Western Europe, driven by convenience and personal security needs.
- Small Businesses:These entities utilize cameras for storefront security, inventory monitoring, and employee oversight, requiring scalable and cost-effective solutions. Demand from small retail and office spaces in Germany and Australia prioritizes ease of installation and remote access.
- Government:Public sector entities deploy cameras for city surveillance, infrastructure protection, and law enforcement, often requiring robust, networked systems.
- Large Enterprises:Corporations use extensive camera networks for facility security, asset protection, and operational oversight across multiple sites.
Residential Users represent the largest segment, with Small Businesses climbing the fastest in adoption.
Distribution Channel:
Distribution channels vary significantly based on sales volume and customer engagement models.
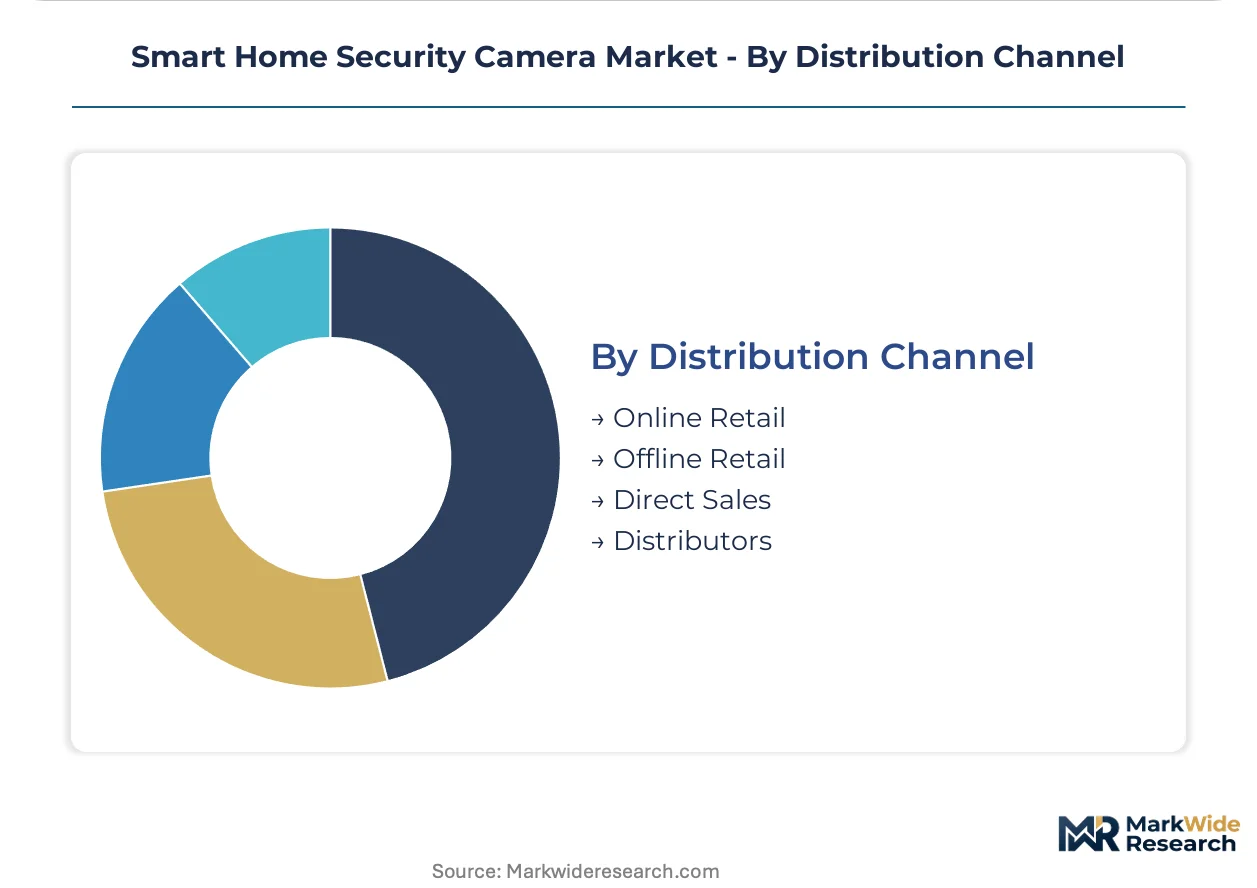
- Online Retail:E-commerce platforms facilitate broad product availability and competitive pricing, appealing to tech-savvy consumers for self-installation. This channel drives significant volume in the US and India, benefiting from extensive logistics networks and digital marketing.
- Offline Retail:Brick-and-mortar stores offer product demonstrations, immediate purchase, and installation support, catering to customers preferring physical interaction. Consumers in Germany and Japan frequently use this channel for complex systems or professional advice.
- Direct Sales:Manufacturers sell directly to end-users, often for specialized or enterprise-level solutions, enabling customized configurations.
- Distributors:Intermediaries supply cameras to installers, system integrators, and retailers, serving as a crucial link in the supply chain.
Online Retail accounts for substantial sales volume, with Distributors gaining share fastest in the professional installation market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global smart home security camera market exhibits a varied landscape, with certain countries acting as significant net importers of technology while others drive localized innovation and production. Data privacy concerns and smart city initiatives shape demand patterns across diverse geographies. Regulatory environments further influence product design and market access for vendors.
China
China presents substantial demand for smart home security cameras, driven by its large consumer base and widespread smart city projects. The country's GB standards for electronic safety heavily influence product design and market entry. Major urban centers like Shenzhen and Hangzhou are hubs for both manufacturing and adoption of advanced surveillance technology, integrating cameras into broader smart home ecosystems.
United States
Residential security demand remains a primary driver for smart camera adoption across the United States, particularly for wireless models. FCC standards for wireless spectrum use dictate device specifications for market access. Silicon Valley and other tech clusters across California foster innovation in on-device AI analytics and advanced sensor technologies, enhancing system responsiveness.
Germany
Germany shows strong demand from residential users seeking property protection and small businesses requiring scalable security solutions. The EU's GDPR significantly impacts data handling requirements for cameras sold within the country. Major cities such as Berlin and Munich see high adoption rates for premium hardware and subscription-based features, reflecting a preference for robust and compliant systems.
Japan
Premium residential users in Japan prioritize 4K cameras for superior image clarity and advanced zoom capabilities. METI regulations influence product safety and energy efficiency standards for electronic devices. Tokyo and Osaka are key markets for high-end security cameras, often purchased through offline retail channels where consumers value product demonstrations and professional advice.
Brazil
Brazil represents a significant underpenetrated geographic market, offering substantial volume opportunities for affordable, easy-to-install camera systems. ANVISA regulations might influence certain electronic product imports and certifications. São Paulo and Rio de Janeiro are emerging urban centers where basic home monitoring solutions are gaining traction among residential users seeking enhanced personal safety.
Smart Home Security Camera Market Key Industry Players
Concentration sits with established technology conglomerates and specialized hardware providers, yet the market also accommodates agile, price-competitive players. The smart home security camera sector is characterized by a tiered structure, with premium, mid-range, and economy segments. Strategic archetypes include cloud-ecosystem integrators, hardware-centric innovators, and volume-driven accessible solution providers. Dominant competitive moves involve portfolio diversification into adjacent smart home devices and the expansion of subscription-based service models.
Among cloud-ecosystem integrators, Amazon (Ring) exemplifies leveraging an extensive cloud infrastructure to deliver integrated services and user convenience. Arlo Technologies represents premium hardware innovation, specializing in advanced features and subscription-based offerings for a dedicated user base. Xiaomi, a Chinese technology company, occupies a position at the scale-driven end, offering feature-rich cameras at accessible price points, particularly in Asian markets.
| Leading Market Players |
|---|
| Samsung Electronics |
| Arlo Technologies |
| Amazon (Ring) |
| Vivint Smart Home |
| ADT |
| SimpliSafe |
| Xiaomi |
| Eufy (Anker Innovations) |
| Nest Labs |
| Others |
Cost & Logistics Intelligence
The increasing prevalence of on-device AI processing for smart home cameras, replacing cloud-dependent analytics, simultaneously reshapes manufacturing geography and alters pricing economics. This shift reduces reliance on extensive cloud infrastructure, driving demand for specialized local processing components and influencing regional supply chain decisions.
Pricing Analysis
Residential users anchor the pricing structure, which operates on a hybrid model combining one-time hardware sales with recurring subscription-based services. Pricing stratifies across premium, standard, and economy tiers, differentiated by 4K resolution, advanced on-device AI features, and brand premium. Pricing softness stems from high-volume players like Xiaomi, which offer feature-rich cameras at accessible price points. Basic residential users exhibit the highest price sensitivity, while premium residential users prioritize advanced functionality and data privacy features.
Supply Chain Analysis
Port congestion and container availability, particularly on key trade lanes from Asia, significantly impact the inbound logistics costs for smart home security cameras. Geographic supply concentration sits primarily in China, a major hub for electronic manufacturing, alongside other East Asian countries. Key raw material dependencies include image sensors, AI processing chips, wireless communication modules, and robust plastic casings. Single-source vulnerability for advanced AI chips represents a structural supply chain risk. Distribution runs through online retail platforms, traditional offline stores, and a growing network of specialized distributors for professional installation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Smart Home Security Camera Market presents a defensive-moat story, primarily due to the high switching costs associated with integrated smart home ecosystems and established subscription models.
For Market Incumbents:Shield existing market share by deepening integration within proprietary smart home ecosystems, leveraging advanced on-device AI to address data privacy concerns. Invest significantly in R&D for specialized AI applications beyond basic motion detection, creating differentiation against low-cost entrants. Expand subscription model offerings to include professional monitoring and advanced analytics, countering margin pressure from commoditized hardware sales. Strengthen channel control through partnerships with installation service providers.
For New Entrants and Emerging Players:Anchor in underpenetrated geographic markets like Brazil and Southeast Asia, offering affordable, easy-to-install camera systems tailored to local needs. Target niche applications such as pet monitoring or elderly care alerts, leveraging privacy-by-design principles to differentiate from established players. A go-to-market angle focused on easy setup, local data storage options, and transparent data policies can attract privacy-conscious residential users. Focus on cost-effective hardware with scalable subscription add-ons.
For Investors and Strategic Acquirers:The market sits at a maturing phase that favors companies with strong recurring revenue streams and proprietary technology. Long-term viability rests on the ability to consolidate market share through ecosystem lock-in and advanced AI capabilities. Identify acquisition targets among niche AI solution providers or regional players with robust compliance frameworks. The signal to watch is the sustained growth in subscription penetration rates, indicating successful monetization of advanced features and customer retention.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Subscription Tiers | Creates recurring revenue and enhances customer lifetime value for smart home ecosystems. |
| Invest in On-Device AI | Addresses data privacy concerns and reduces cloud reliance for real-time analytics. |
| Target Developing Markets | Captures significant volume opportunities with affordable, easy-to-install camera systems. |
| Enhance Cybersecurity Protocols | Builds consumer trust and mitigates risks from high-profile IoT security breaches. |
| Develop Interoperability Standards | Simplifies smart home integration and reduces development costs for manufacturers. |
Research Approach
Initial hypotheses were tested against primary input from smart home device engineers, product managers, retail buyers, cybersecurity experts, and privacy officers, then refined through iterative analysis. This involved combining insights from in-depth interviews with industry stakeholders and validating findings against secondary data sources. Secondary research included regulatory filings from bodies like the FCC, GDPR implementation reports, smart home industry consortium publications, and consumer electronics sales data. Both bottom-up and top-down triangulation methods were employed to ensure data accuracy.
The analytical framework modeled market dynamics across the analysis window, segmenting the market by product type (wireless, wired), technology (4K, HD), end-user (residential, small business), geographic region, and AI processing type (on-device, cloud). Compound annual growth rates were derived from historical data analysis, market growth drivers identified, and expert projections integrated into the model. Industry-specific forecast inputs included smartphone application adoption rates, smart city project investment trends, and wireless network infrastructure buildout.
Material uncertainties — unforeseen major regulatory shifts or rapid technological obsolescence — sit outside the modeled envelope, as do significant global supply chain disruptions. Forecasts reflect assumptions documented and validated during the research process. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Germany Surveillance Analog Camera Market
Video Surveillance Systems
Europe Surveillance Camera Market
Video Surveillance Systems
Asia-Pacific Surveillance Analog Camera Market
Video Surveillance Systems
AI Surveillance Camera Market
Video Surveillance Systems
Global Night Vision System and Driver Monitoring System Market
Video Surveillance Systems
Hosted Video Surveillance Market
Video Surveillance Systems
Latin America Surveillance IP Cameras Market
Video Surveillance Systems
Aircraft Video Surveillance Systems Market
Video Surveillance Systems
Video Surveillance As a Service Market
Video Surveillance Systems
Connected Enterprise Video Surveillance Solutions Market
Video Surveillance Systems
United Kingdom Surveillance IP Camera Market
Video Surveillance Systems
Latin America Surveillance Camera Market
Video Surveillance Systems
Germany Surveillance IP Camera Market
Video Surveillance Systems
AI CCTV Market
Video Surveillance Systems
Middle East and Africa Surveillance Analog Camera Market
Video Surveillance Systems
Rugged Thermal Cameras Market