
 Asia Pacific Surveillance IP Camera Market | 2026-2036
Asia Pacific Surveillance IP Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Surveillance IP Camera Market Insights
Buyer concentration across Asia Pacific's surveillance IP camera landscape is recalibrating as government-led smart city tenders consolidate procurement authority while mid-sized commercial buyers fragment across retail chains, logistics parks, and educational campuses. Hangzhou Hikvision Digital Technology Co., Ltd. leverages its integrated manufacturing base to dominate domestic Chinese supply and extend into Southeast Asian infrastructure bids. Panasonic Corporation anchors premium positioning in Japan's corporate and transit security verticals through specialized imaging sensor development. Samsung Electronics Co., Ltd. competes aggressively in South Korea's domestic market while navigating channel control challenges across emerging Southeast Asian economies.
Asia Pacific surveillance IP cameras are network-connected digital video capture devices transmitting compressed image data over TCP/IP protocols, typically supporting H.265 encoding, Power over Ethernet connectivity, and ONVIF interoperability for centralized management platforms. Their primary commercial purpose spans real-time security monitoring, forensic evidence collection, and operational analytics across physical infrastructure. Dome cameras lead indoor commercial installations where discreet positioning matters, while bullet and PTZ variants capture the fastest-growing share in perimeter defense and critical infrastructure applications where motorized zoom and pan-tilt functionality justify premium positioning. Government end-user procurement sustains the largest volume pool, though residential wireless connectivity segments are expanding rapidly as broadband penetration and cloud storage economics improve across second-tier Chinese cities and Indian metropolitan regions.
China's MIIT enforces GB standards compliance and cybersecurity review for networked surveillance equipment, while India's BIS certification mandates and TRAI data localization guidelines shape product specification requirements for vendors entering these markets. Japan's METI promotes JIS-aligned interoperability standards that influence procurement criteria across East Asian public sector tenders. Stakeholders must monitor evolving cross-border data flow restrictions and local content requirements as these regulations increasingly determine market access eligibility and competitive positioning across the region.
Market Dynamics
Smart city infrastructure tenders across Southeast Asian metros are consolidating procurement authority into centralized government agencies, fragmenting commercial buyer segments and compressing vendor margins through volume aggregation.
Growth Catalysts
- China's GB standards compliance mandates:Cybersecurity review requirements for networked surveillance equipment under MIIT are accelerating replacement cycles as municipalities upgrade legacy installations.
- India's retail and logistics facility upgrades:Analog-to-IP migration across warehousing clusters and shopping complexes is generating sustained hardware demand.
- H.265 encoding adoption:Bandwidth efficiency gains from advanced compression protocols are enabling 4K streaming deployment across bandwidth-constrained municipal networks.
Market Restraints
- Image sensor supply concentration:Dependence on specialized CMOS fabrication facilities in Taiwan and South Korea creates input vulnerability during capacity constraints.
- India's BIS certification timelines:Extended product approval processes delay market entry for new vendors and compress launch windows.
- Cloud storage substitution pressure:Edge-to-cloud architectures are reducing on-premise NVR hardware attach rates in price-sensitive residential segments.
Strategic Opportunities
- Indonesia's underpenetrated secondary cities:Surabaya and Bandung smart city initiatives remain early-stage with limited incumbent vendor lock-in.
- AI-powered video analytics convergence:Integration of edge inference chips with camera hardware is creating premium pricing tiers for behavioral recognition applications.
- Vietnam's data localization incentives:TRAI-aligned domestic server requirements are favoring regional manufacturing investments over pure import models.
Industry Challenges
- Cybersecurity firmware expertise scarcity:Vendors struggle to recruit embedded systems engineers capable of implementing GB-compliant encryption stacks.
- Legacy analog integration complexity:Hybrid deployments requiring coaxial-to-IP bridge hardware extend installation timelines and elevate service costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Surveillance IP Camera Market |
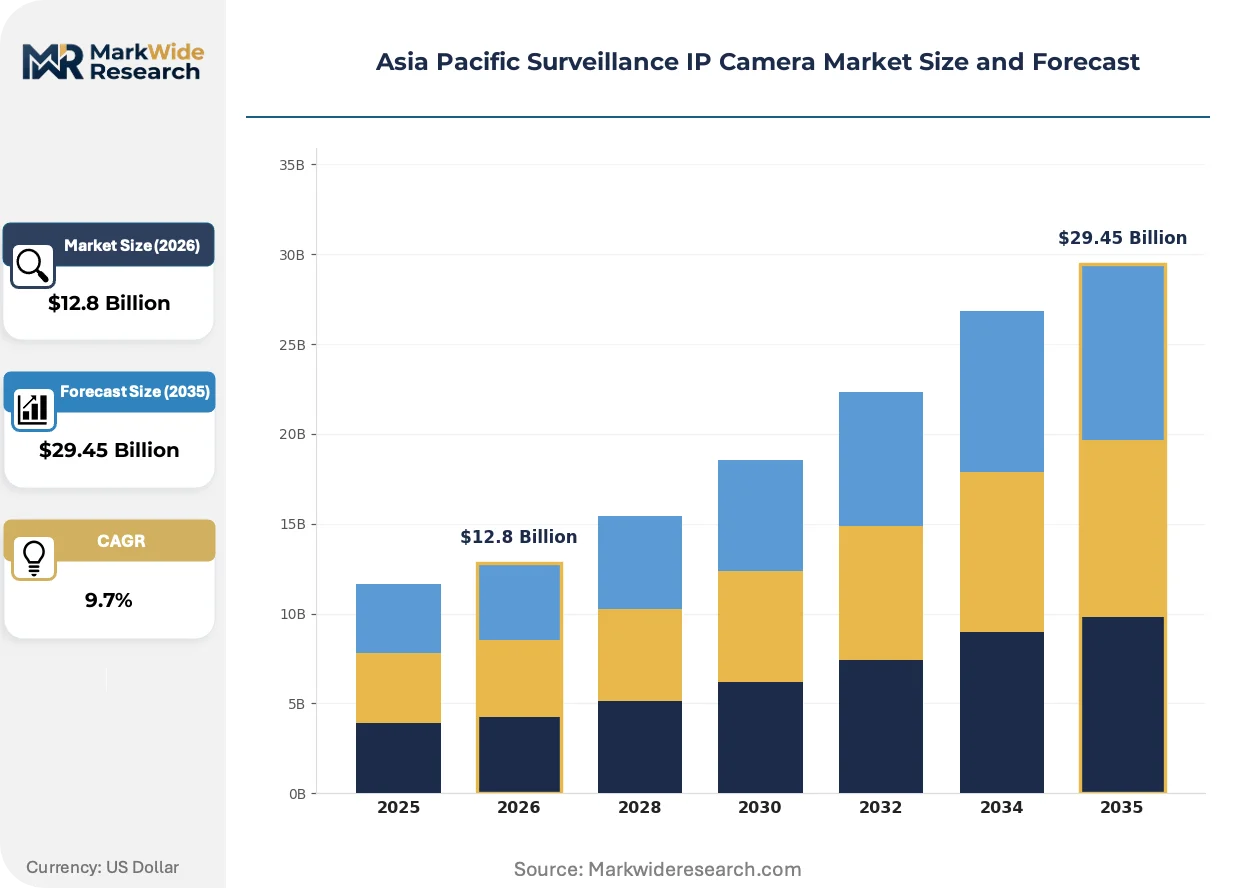
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $29.45 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Camera Type: Dome, Bullet, PTZ, C-mount Connectivity: Wired, Wireless, Power over Ethernet, Fiber Optic End User: Commercial, Residential, Government, Industrial Installation Type: Indoor, Outdoor, Ceiling-mounted, Wall-mounted |
| Companies Covered | Bosch Security Systems GmbH, Panasonic Corporation, Hangzhou Hikvision Digital Technology Co., Ltd., Samsung Electronics Co., Ltd, Honeywell International, Inc., Zhejiang Dahua Technology Co Ltd, Axis Communications, D-Link Corporation, Hanwha Vision, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Surveillance IP Camera Market Trends and Innovations
Edge computing architectures are displacing centralized processing models across Asia Pacific surveillance networks, compressing latency requirements and redistributing analytics workloads toward camera hardware.
Multi-sensor fusion technology is converging with thermal imaging modules to deliver continuous perimeter monitoring regardless of lighting conditions. Critical infrastructure operators in Australia's mining and energy sectors are deploying these units for 24-hour intrusion detection. The convergence is compressing standalone thermal camera demand while elevating average unit values in defense and border security applications.
Japan's METI has issued updated JIS interoperability guidelines mandating ONVIF Profile T compliance for all public sector surveillance tenders. The regulation forces legacy proprietary protocol vendors to retrofit firmware or exit municipal procurement channels. South Korean transit authorities are adopting similar specifications, creating harmonized technical barriers across Northeast Asian government buyers.
Cloud-managed service contracts are displacing traditional capital expenditure procurement models among India's mid-sized retail chains. Managed video surveillance providers bundle hardware, connectivity, and storage into monthly subscriptions, reducing upfront barriers for franchise operators. This shift is most visible in Bangalore and Mumbai's organized retail corridors where property developers specify service-inclusive security packages.
Asia Pacific Surveillance IP Camera Market Segmentation
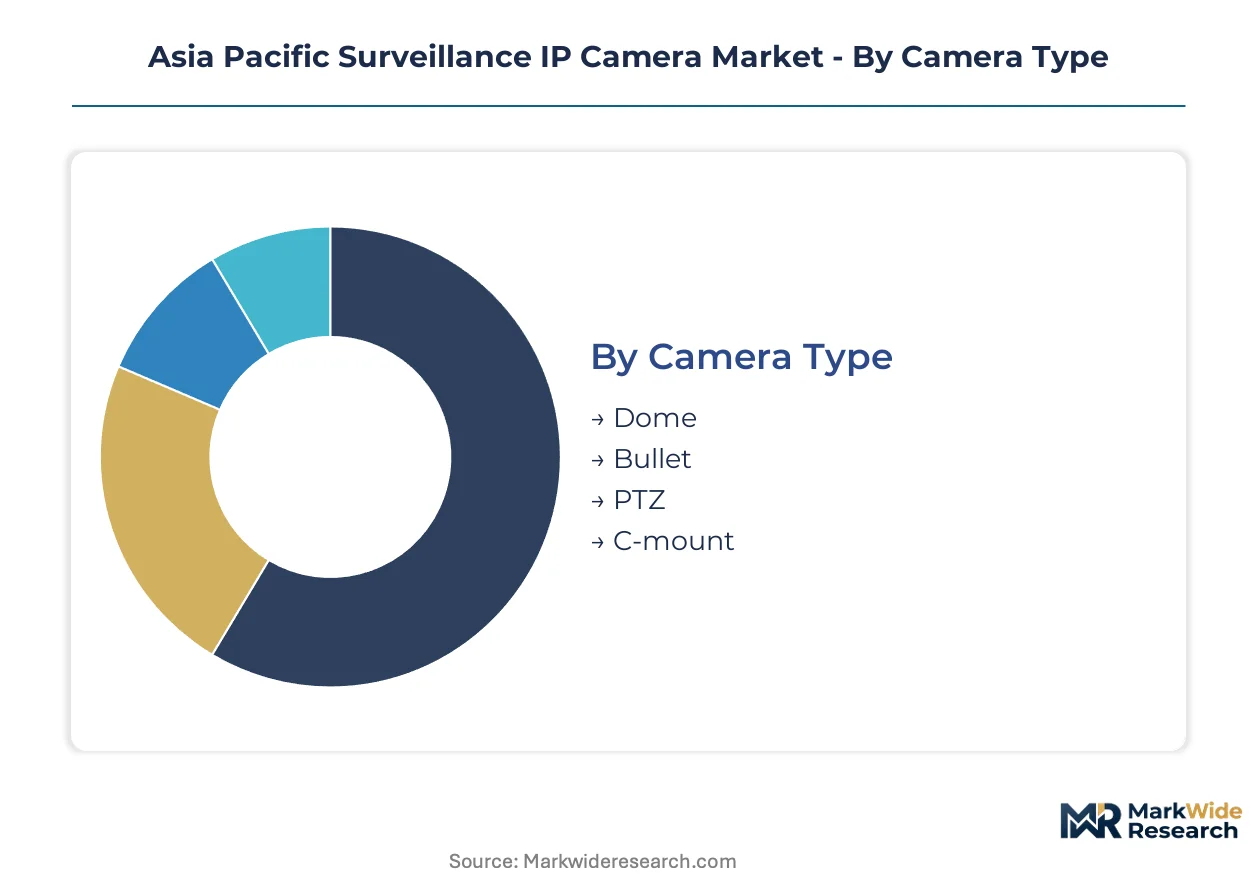
Segmentation in Asia Pacific surveillance IP cameras reveals how technical specifications align with procurement authority concentration and infrastructure investment patterns across government, commercial, and residential buyers.
Camera Type:
Supply concentration among integrated manufacturers favors dome and bullet variants with established component ecosystems, while specialized PTZ assemblies depend on discrete motor and optical supply chains.
- Dome:Hemispherical enclosures with vandal-resistant polycarbonate housings and varifocal lenses enable discreet positioning in retail banking and hotel lobbies. India's shopping mall operators specify these units for ceiling-integrated deployments where aesthetic constraints override perimeter range requirements.
- Bullet:Cylindrical weather-sealed housings with integrated IR illuminators deliver fixed focal length monitoring across logistics yard perimeters. Southeast Asian smart city tenders allocate the largest procurement volumes to bullet configurations for roadway and bridge surveillance where mounting flexibility simplifies installation.
- PTZ:Motorized pan-tilt-zoom mechanisms with optical zoom ranges exceeding 30x serve critical infrastructure operators requiring active operator control.
- C-mount:Interchangeable lens systems accommodate specialized optical requirements in scientific and industrial quality control applications.
Today's leader: Dome. Tomorrow's challenger: Bullet.
Connectivity:
Installation cost structures vary dramatically across connectivity modes, with Power over Ethernet dominating commercial retrofits while fiber optic commands premium positioning in greenfield critical infrastructure.
- Wired:Traditional Ethernet cabling with dedicated power infrastructure persists in legacy building upgrades where conduit access permits structured cable deployment. China's municipal surveillance networks rely on wired backbones for bandwidth-intensive 4K streaming across urban command centers.
- Wireless:Wi-Fi and cellular modules enable rapid deployment in temporary construction sites and remote agricultural monitoring where trenching costs prove prohibitive.
- Power over Ethernet:Single-cable power and data transmission via IEEE 802.3af/at standards reduces installation labor in India's mid-sized retail chains upgrading from analog systems.
- Fiber Optic:Single-mode and multimode fiber connections support long-haul transmission beyond 10 kilometers for mining and energy sector perimeter networks across Australia and Indonesia.
PoE commands current procurement volumes. Wireless connectivity gains share fastest in residential and temporary deployment segments.
End User:
Procurement authority concentration shapes vendor engagement strategies, with centralized government tenders demanding compliance certification while fragmented commercial buyers prioritize total cost of ownership.
- Government:Centralized agency procurement for smart city infrastructure, border security, and public safety networks across China, India, and Southeast Asian metros. MIIT cybersecurity review and BIS certification requirements filter vendor participation.
- Commercial:Fragmented demand across retail chains, logistics parks, and educational campuses where analog-to-IP migration drives replacement cycles.
- Residential:Wireless cloud-connected cameras with mobile app management expand across second-tier Chinese cities and Indian metropolitan regions as broadband penetration improves.
- Industrial:Hardened enclosures with explosion-proof ratings serve oil and gas, mining, and chemical processing facilities in Australia's resource sectors and Indonesia's extraction industries.
Government tenders anchor volume. Commercial segment climbs the fastest as analog replacement accelerates.
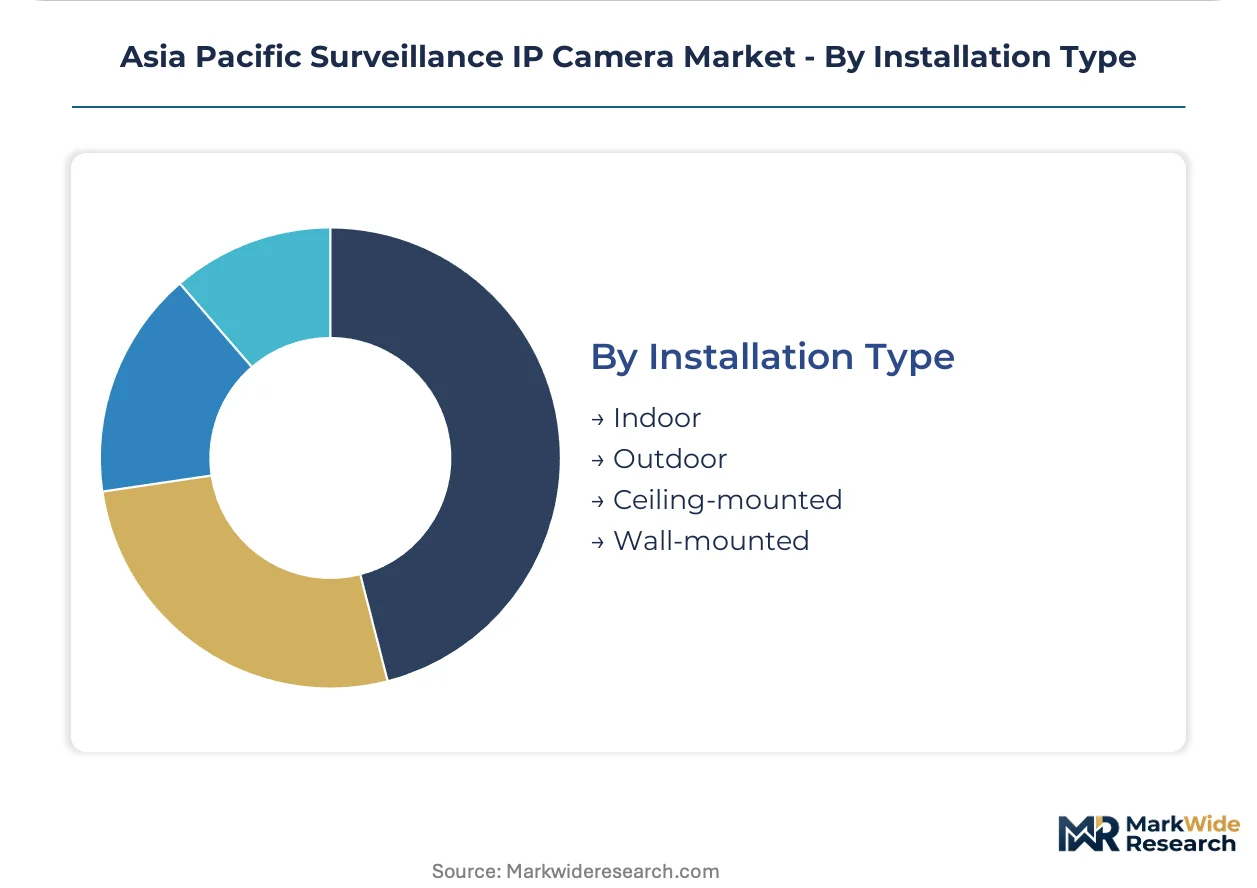
Installation Type:
Environmental sealing specifications and mounting hardware differentiation create distinct cost tiers, with outdoor-rated enclosures commanding material premiums over indoor variants.
- Indoor:Standard IP54-rated enclosures without active heating or cooling elements serve climate-controlled office and retail environments where condensation risks remain minimal.
- Outdoor:IP66/IP67-rated housings with integrated heaters and fans maintain operational temperatures across Japan's northern prefectures and India's monsoon-exposed coastal installations.
- Ceiling-mounted:Recessed and surface-mount brackets optimize sightlines in corridor and lobby applications where wall space constraints limit positioning options.
- Wall-mounted:Articulated arm assemblies with cable concealment channels dominate perimeter and facade installations across commercial and industrial facilities.
Outdoor configurations lead value contribution. Ceiling-mounted designs expand most quickly in premium commercial interiors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's smart city procurement volumes dwarf India's commercial replacement cycles, yet both markets tighten certification requirements that filter vendor participation differently.
China
Municipal surveillance networks in Beijing and Shanghai drive 4K streaming hardware demand across urban command centers. MIIT enforces GB standards compliance and cybersecurity review for all networked equipment. The Yangtze River Delta manufacturing corridor supplies integrated camera assemblies to domestic infrastructure tenders.
India
Retail chains and logistics parks in Mumbai and Bangalore accelerate analog-to-IP migration across warehousing clusters. BIS certification timelines and TRAI data localization guidelines shape product specifications for entering vendors. The Delhi-NCR corridor concentrates system integrators serving commercial security upgrades.
Japan
Corporate and transit security verticals in Tokyo and Osaka sustain premium positioning for specialized imaging applications. METI promotes JIS-aligned interoperability standards that influence procurement criteria across public sector tenders. The Kansai industrial belt hosts precision optical component fabricators.
South Korea
Domestic market competition intensifies around Seoul Capital Area smart city deployments and commercial facility upgrades. Transit authorities adopt ONVIF Profile T specifications, harmonizing technical barriers with Japanese procurement channels. The Busan-Ulsan corridor anchors electronics manufacturing for regional export.
Vietnam
Data localization incentives in Ho Chi Minh City and Hanoi favor regional manufacturing investments over pure import models. TRAI-aligned domestic server requirements reshape vendor establishment strategies. The Red River Delta corridor attracts assembly operations serving Southeast Asian distribution.
Asia Pacific Surveillance IP Camera Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around manufacturing scale, software integration depth, and geographic certification coverage. Three archetypes dominate: integrated hardware-software platforms, specialized imaging sensor developers, and regional system integrators with local compliance expertise. Capacity expansion and strategic partnerships constitute the dominant competitive moves as vendors navigate fragmented procurement authority.
Among diversified technology conglomerates, Panasonic Corporation and Samsung Electronics Co., Ltd occupy positions spanning multiple security verticals. Hangzhou Hikvision Digital Technology Co., Ltd exemplifies the integrated platform archetype with captive manufacturing and domestic certification advantages. Bosch Security Systems GmbH represents the European multinational tier competing on compliance breadth across heterogeneous regulatory environments.
| Leading Market Players |
|---|
| Bosch Security Systems GmbH |
| Panasonic Corporation |
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Samsung Electronics Co., Ltd |
| Honeywell International, Inc. |
| Zhejiang Dahua Technology Co Ltd |
| Axis Communications |
| D-Link Corporation |
| Hanwha Vision |
| Others |
Pricing and Supply Chain Analysis
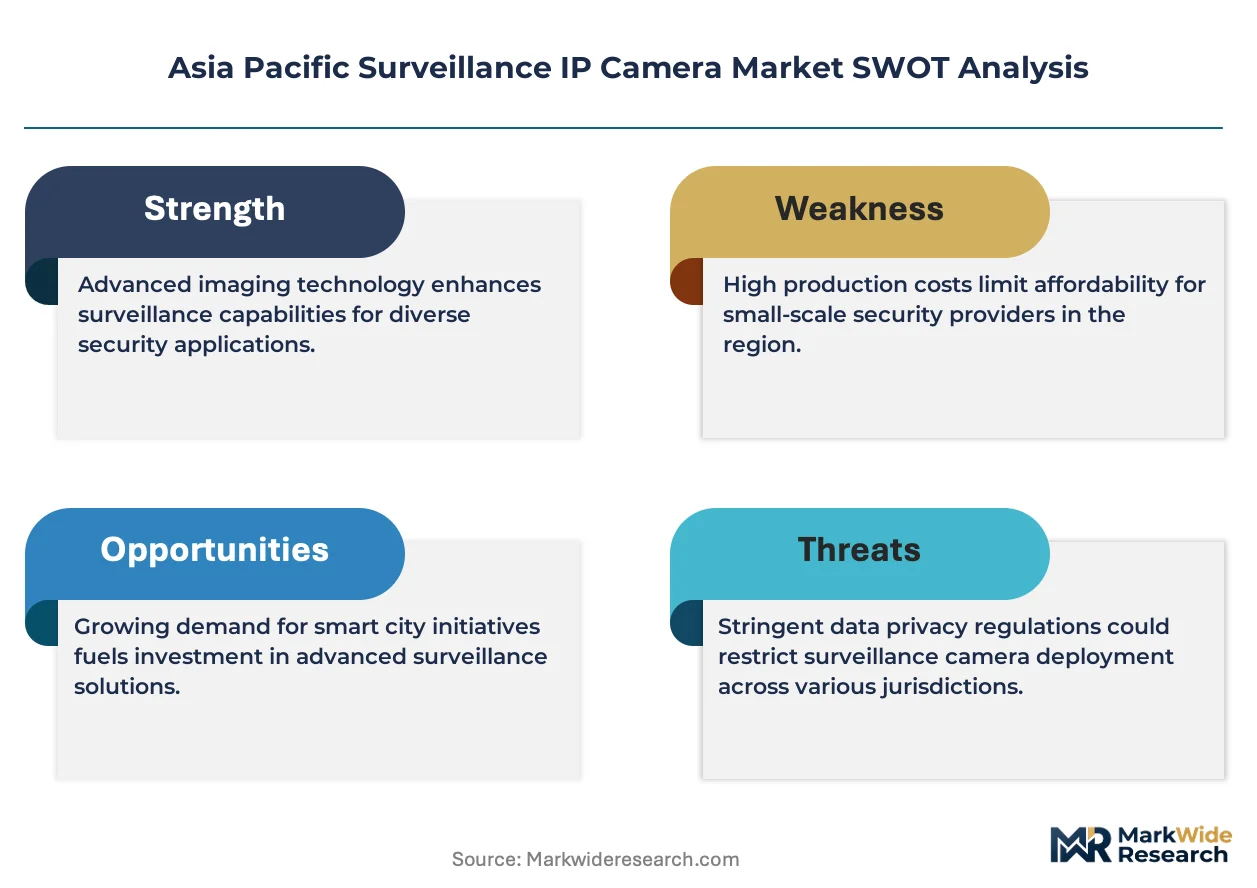
China's GB standards compliance mandates for networked surveillance equipment gate qualified supply access and premium-tier pricing power, filtering vendors through MIIT cybersecurity reviews while concentrating procurement authority among certified domestic manufacturers.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing corridor are reshaping price floors across mid-tier camera assemblies. Three-tier pricing structure across premium, standard, and economy levels segments on certification grade and after-sales service bundling. Cost compression in standard-tier bullet cameras intensifies because Hangzhou Hikvision and Zhejiang Dahua leverage captive component supply. India's mid-sized retail chains exhibit highest price sensitivity, while Japan's corporate security buyers accept premium positioning for JIS-aligned interoperability.
Supply Chain Analysis
Image sensor supply rests on specialized CMOS fabrication facilities in Taiwan and South Korea, with Sony and Samsung semiconductor divisions anchoring high-performance optical component output. Taiwan, South Korea, and Japan concentrate critical inputs including precision motors for PTZ assemblies, polycarbonate housing materials, and edge inference chipsets. Single-source vulnerability in Taiwanese foundry capacity exposes vendors to allocation constraints during demand surges. Distribution runs through regional system integrators in Delhi-NCR and authorized distributors across Southeast Asian metros.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific surveillance IP cameras offer geographic-arbitrage value as Vietnam's data localization incentives reduce landed cost differentials versus pure import models serving Indian BIS certification requirements.
For Market Incumbents: Anticipate margin compression from cloud-managed service substitution in India's residential segment by deepening firmware encryption expertise for GB-compliant tenders. Prioritize backward integration into edge inference chip supply through partnerships with Taiwanese semiconductor foundries. Channel control investments across Indonesia's secondary cities defend positioning against emerging regional assemblers. For New Entrants and Emerging Players: Enter via Surabaya and Bandung smart city tenders where incumbent vendor lock-in remains limited and procurement authority fragments across municipal agencies. Indonesia's underpenetrated secondary cities present the most penetrable geography. Bundle hardware with localized data center partnerships to satisfy TRAI-aligned domestic server requirements. For Investors and Strategic Acquirers: Roll-up economics work for regional system integrators with BIS certification expertise because India's analog-to-IP migration fragments procurement across mid-sized commercial buyers. Five-to-ten year viability hinges on AI-powered video analytics convergence creating premium pricing tiers. Watch GB standards tightening frequency as inflection indicator for vendor consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Inference Chip Integration | Enables behavioral recognition premiums in Australian mining and energy perimeter networks. |
| GB Standards Certification Investment | Unlocks Beijing and Shanghai municipal tender participation under MIIT cybersecurity review. |
| Regional Manufacturing Establishment | Satisfies Vietnam's TRAI-aligned data localization requirements versus pure import models. |
| ONVIF Profile T Firmware Retrofit | Maintains access to Japanese METI-mandated public sector procurement channels. |
| Cloud-Managed Service Launch | Captures Bangalore and Mumbai retail chain demand shifting from capital expenditure models. |
Research Methodology
Coverage spans China, India, Japan, South Korea, and Southeast Asian metros, with primary inputs from each combining interviews with smart city procurement officers, commercial security system integrators, surveillance hardware distributors, and MIIT certification consultants. Secondary validation draws from MIIT GB standards filings, BIS certification databases, TRAI localization guidelines, METI JIS interoperability publications, and customs trade data. Bottom-up vendor shipment analysis triangulates against top-down infrastructure investment tracking.
Granularity-level modeling captures camera type, connectivity mode, end-user segment, and installation environment across the projection horizon. Camera type splits across dome, bullet, PTZ, and C-mount variants. Connectivity segments wired, wireless, Power over Ethernet, and fiber optic deployments. End-user modeling distinguishes government, commercial, residential, and industrial procurement patterns. CAGRs derive from shipment-volume trajectories adjusted for average selling price erosion and mix-shift toward AI-enabled configurations.
Inputs from MIIT certification registries and BIS approval timelines were available through the study window; gaps in real-time Southeast Asian tender award data introduce uncertainty bands around Indonesia and Vietnam volume assumptions. Forecasts reflect documented assumptions on smart city budget allocation continuity and analog replacement cycle timing. Regulatory tightening on cross-border data flows and local content thresholds warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Mexico Surveillance Camera Market
Video Surveillance Systems
Europe Video Surveillance Storage Market
Video Surveillance Systems
Wireless Video Surveillance Market
Video Surveillance Systems
Asia-Pacific Surveillance Camera Market
Video Surveillance Systems
France Surveillance Analog Camera Market
Video Surveillance Systems
Privacy Filters Market
Video Surveillance Systems
Security Cameras (IR Illuminator) Market
Video Surveillance Systems
Gunshot Detection System Market
Video Surveillance Systems
United States Surveillance Analog Camera Market
Video Surveillance Systems
United States Surveillance Camera Market
Video Surveillance Systems
Mexico Surveillance Analog Camera Market
Video Surveillance Systems
Video Surveillance Software Market
Video Surveillance Systems
India Surveillance IP Cameras Market
Video Surveillance Systems
Video Surveillance and Vsaas Market
Video Surveillance Systems
China Video Surveillance Market
Video Surveillance Systems
China Surveillance IP Camera Market