
 United States Facial Recognition Market | 2026-2036
United States Facial Recognition Market Size, Share, and Industry Trends Forecast 2026-2036
United States Facial Recognition Market Analytics
Domestic cloud infrastructure providers is broadening the addressable base for facial recognition APIs across government and commercial verticals. Amazon Web Services leverages its FedRAMP-authorized cloud regions to anchor public-sector deployments requiring sovereign data residency. Microsoft competes through Azure AI services that embed ethical-review workflows for law-enforcement clients. NEC Corporation dominates large-scale biometric installations at US ports of entry with its long-standing Department of Homeland Security relationships.
Facial recognition technology maps distinctive facial geometry—interocular distance, jawline contour, and nodal point coordinates—into encrypted templates for automated identity matching against enrolled databases. The primary commercial purpose spans physical access control, digital identity proofing, and real-time surveillance alerting. Software solutions lead revenue contribution due to recurring licensing models, while deep learning architectures represent the fastest-expanding technology tier as convolutional neural networks displace legacy 2D eigenface algorithms. Hardware modules for edge deployment, including infrared cameras and neural processing units, capture concentrated margin pools in defense and critical-infrastructure segments.
The National Institute of Standards and Technology (NIST) Face Recognition Vendor Test shapes procurement criteria by publishing accuracy benchmarks that federal buyers mandate in solicitations. State-level biometric privacy statutes, notably Illinois Biometric Information Privacy Act and Texas Capture or Use of Biometric Identifier Act, impose consent and retention obligations that constrain deployment practices in consumer-facing retail and banking contexts. Stakeholders must monitor pending federal legislation that could preempt fragmented state regimes and establish uniform compliance thresholds for algorithmic auditing and data deletion.
Market Dynamics
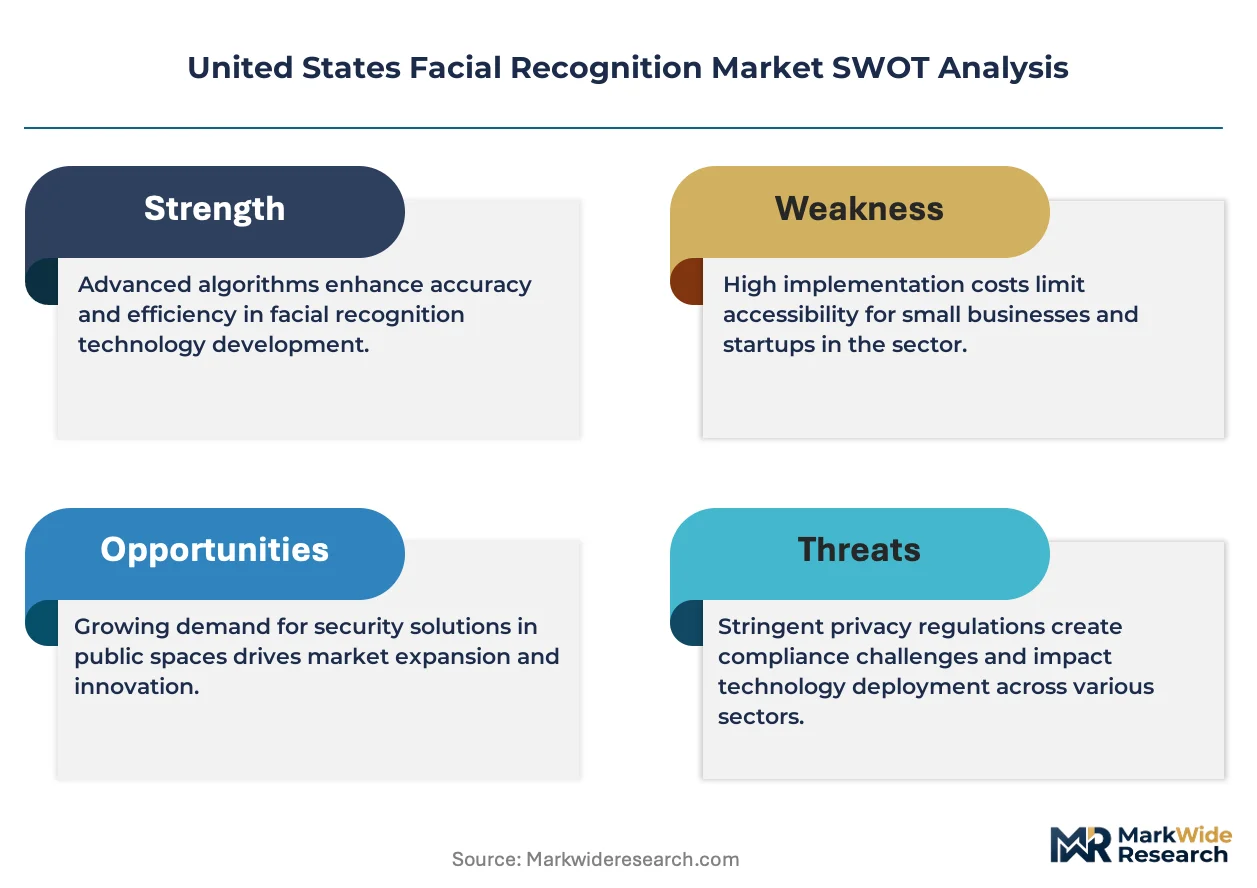
Deep learning architectures are displacing legacy 2D eigenface algorithms across federal and commercial deployments, compressing vendor margins while elevating accuracy thresholds mandated by NIST testing protocols.
Growth Catalysts
- FedRAMP-authorized cloud regions:Federal agencies require sovereign data residency for biometric workloads, expanding the addressable base for API-first vendors serving public-sector verticals.
- Smart city infrastructure clusters:California and Texas municipalities are deploying edge-based facial recognition for traffic management and public safety, creating concentrated demand pockets.
- Department of Homeland Security port modernization:Biometric screening programs at land, sea, and air ports of entry are driving large-scale installation cycles with multi-year procurement horizons.
Market Restraints
- Illinois BIPA compliance costs:The Biometric Information Privacy Act mandates written consent and retention limits, forcing consumer-facing retailers to implement costly opt-in workflows or abandon deployments.
- Neural processing unit supply concentration:Edge hardware modules depend on specialized semiconductor fabrication concentrated in East Asian foundries, exposing defense contractors to geopolitical supply disruption.
- Algorithmic bias litigation exposure:False-positive disparities across demographic groups create class-action liability risks that constrain law-enforcement adoption in politically sensitive jurisdictions.
Strategic Opportunities
- Healthcare identity proofing:HIPAA-covered entities are piloting facial recognition for patient matching at admission, reducing medical record duplication errors and insurance fraud.
- Texas Capture or Use of Biometric Identifier Act harmonization:Pending federal preemption legislation could establish uniform compliance thresholds, reducing multi-state operational complexity for national retail chains.
- Infrared-thermal sensor fusion:Convergence of liveness detection with temperature screening creates dual-use value propositions for critical infrastructure operators managing both security and health protocols.
Industry Challenges
- Convolutional neural network talent scarcity:Federal contractors and commercial vendors compete for machine-learning engineers with biometric specialization, inflating compensation and extending development timelines.
- NIST FRVT certification latency:Vendor testing queues stretch twelve to eighteen months, delaying product launches and freezing procurement decisions pending benchmark publication.
- Legacy access control integration:Physical security systems using proprietary Wiegand protocols require costly middleware development to interoperate with modern API-based facial recognition platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Facial Recognition Market |
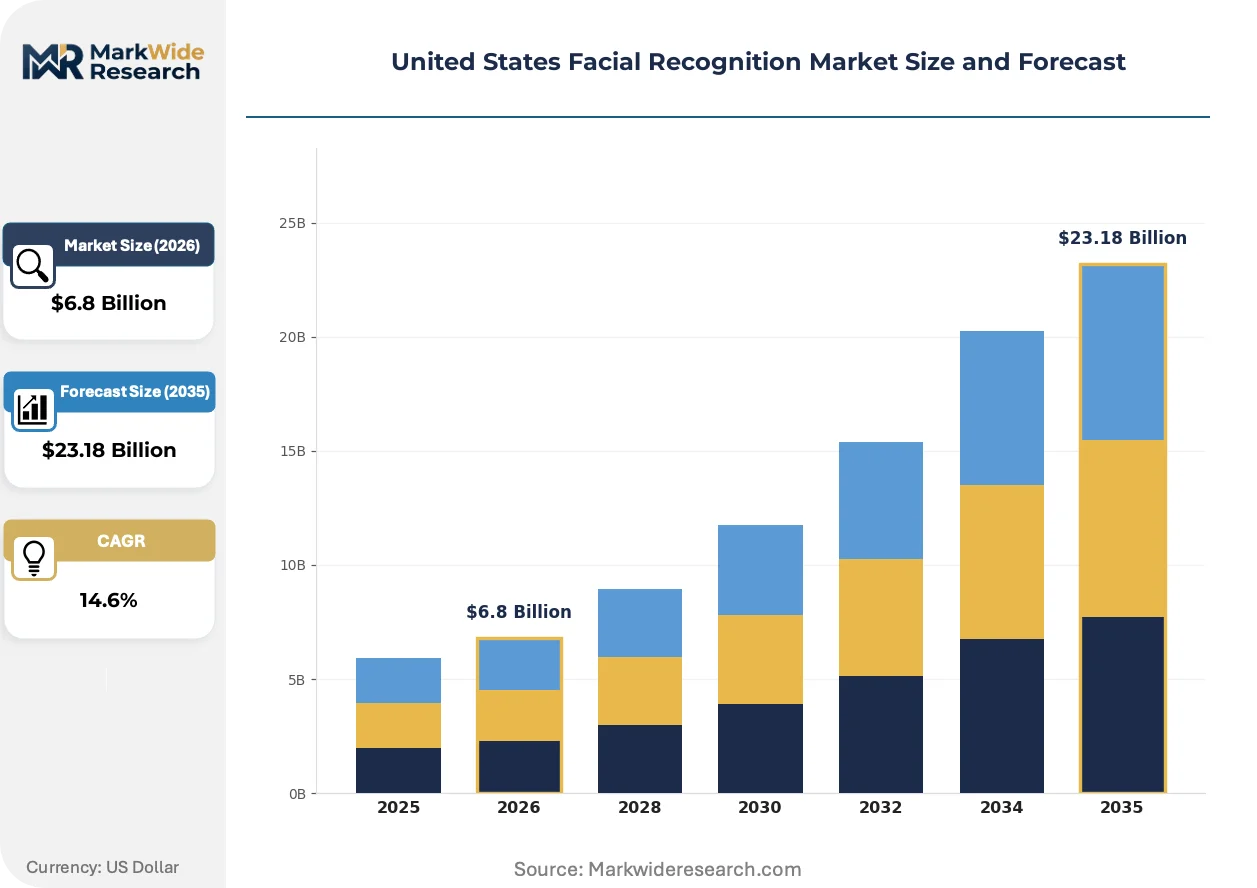
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $23.18 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Integrated Systems, Cloud Solutions End User: Law Enforcement, Retail, Banking, Healthcare Technology: 2D Recognition, 3D Recognition, Thermal Imaging, Deep Learning Application: Surveillance, Access Control, Identity Verification, Emotion Recognition |
| Companies Covered | Amazon Web Services, Microsoft, NEC Corporation, Thales Group, Aware Inc., Clearview AI Inc., FaceFirst Inc., Cognitec Systems, Panasonic Connect North America, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Facial Recognition Market Evolving Landscape
Edge computing architectures are redistributing processing loads from centralized cloud to local inference nodes, altering hardware procurement patterns and vendor competitive positioning across federal and commercial segments.
3D structured light sensing is converging with neural network-based depth estimation to enable spoof-resistant authentication without dedicated infrared hardware. Financial services institutions are adopting these hybrid systems for mobile onboarding at scale, reducing per-unit sensor costs while maintaining liveness assurance. The technology is converging with existing smartphone camera modules, compressing the addressable market for specialized biometric hardware manufacturers.
The National Institute of Standards and Technology Face Recognition Vendor Test is evolving from voluntary benchmarking to de facto procurement gatekeeping. Federal solicitations now mandate NIST-published accuracy thresholds for demographic parity and false-match rates, disqualifying vendors without recent test participation. State-level corrections departments and large municipal police forces are adopting these same criteria, extending federal influence into local procurement decisions.
Subscription-based licensing is displacing perpetual software sales across mid-market commercial buyers. Security integrators and value-added resellers are bundling facial recognition APIs with managed services, capturing recurring revenue streams previously retained by end-users. This shift is most visible in the banking vertical, where regional credit unions prefer operational expenditure models over capital-intensive on-premise deployments.
United States Facial Recognition Market Segmentation
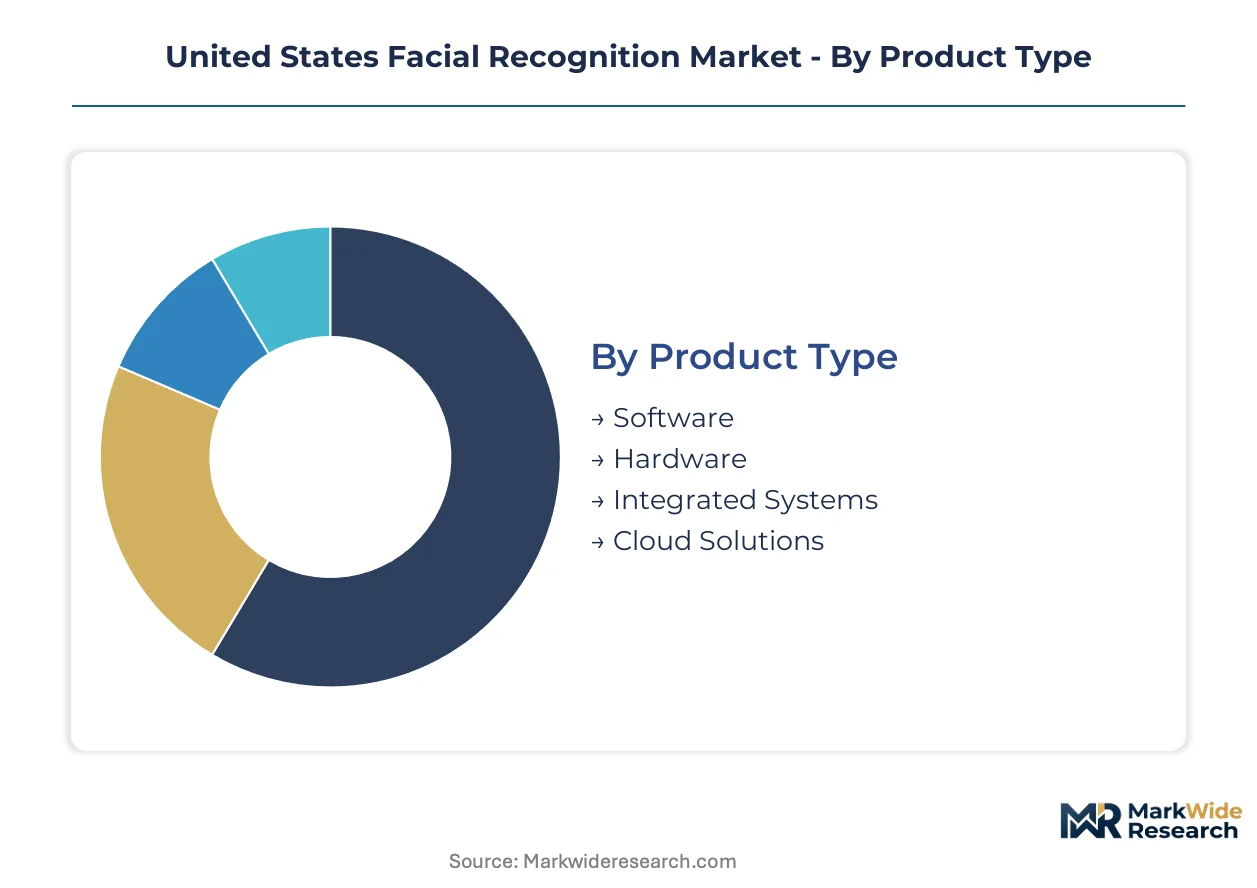
Facial recognition procurement patterns diverge sharply between high-volume software licensing and premium hardware-integrated deployments. Understanding these splits reveals where margin pools concentrate and which technology tiers command strategic investment priority across federal and commercial verticals.
Product Type:
Software solutions dominate transaction volume while integrated systems capture concentrated margin at the premium tier.
- Software:Recurring licensing models for API-based facial recognition generate predictable revenue streams. Banking and retail verticals in California and Texas drive subscription uptake as regional credit unions abandon capital-intensive on-premise deployments.
- Hardware:Infrared cameras and neural processing units for edge deployment command premium pricing in defense and critical-infrastructure segments. Supply concentration in East Asian foundries exposes procurement timelines to geopolitical disruption.
- Integrated Systems:Bundled hardware-software configurations for large-scale biometric installations at Department of Homeland Security ports of entry.
- Cloud Solutions:FedRAMP-authorized API services enabling sovereign data residency for federal biometric workloads.
Today's leader: Software. Tomorrow's challenger: Cloud Solutions.
End User:
Public-sector procurement cycles stretch longer but lock in multi-year revenue, while commercial verticals demand faster implementation with stricter compliance guardrails.
- Law Enforcement:Federal agencies and municipal police forces mandate NIST FRVT-certified accuracy thresholds. Algorithmic bias litigation exposure constrains deployment in politically sensitive jurisdictions.
- Retail:Illinois BIPA compliance costs force consumer-facing chains into costly opt-in workflows or abandonment. Texas Capture or Use of Biometric Identifier Act creates parallel operational complexity.
- Banking:Regional credit unions prefer operational expenditure models, accelerating subscription-based licensing adoption for identity verification at account opening.
- Healthcare:HIPAA-covered entities pilot patient matching at admission to reduce medical record duplication errors and insurance fraud.
Law Enforcement anchors current procurement volume. Healthcare shows steepest expansion trajectory as identity proofing protocols mature.
Technology:
Legacy 2D eigenface algorithms yield to neural architectures, compressing vendor margins while elevating performance benchmarks.
- 2D Recognition:Legacy eigenface algorithms face displacement as federal solicitations mandate NIST-published demographic parity standards.
- 3D Recognition:Structured light sensing converges with neural network-based depth estimation for spoof-resistant authentication. Financial services institutions adopt hybrid systems for mobile onboarding at scale.
- Thermal Imaging:Infrared-thermal sensor fusion creates dual-use value propositions for critical infrastructure operators managing security and health protocols simultaneously.
- Deep Learning:Convolutional neural networks displace legacy approaches across federal and commercial deployments. Talent scarcity for machine-learning engineers with biometric specialization inflates compensation and extends development timelines.
Deep Learning commands strategic investment priority. Thermal Imaging gains share fastest through pandemic-era infrastructure retrofit demand.
Application:
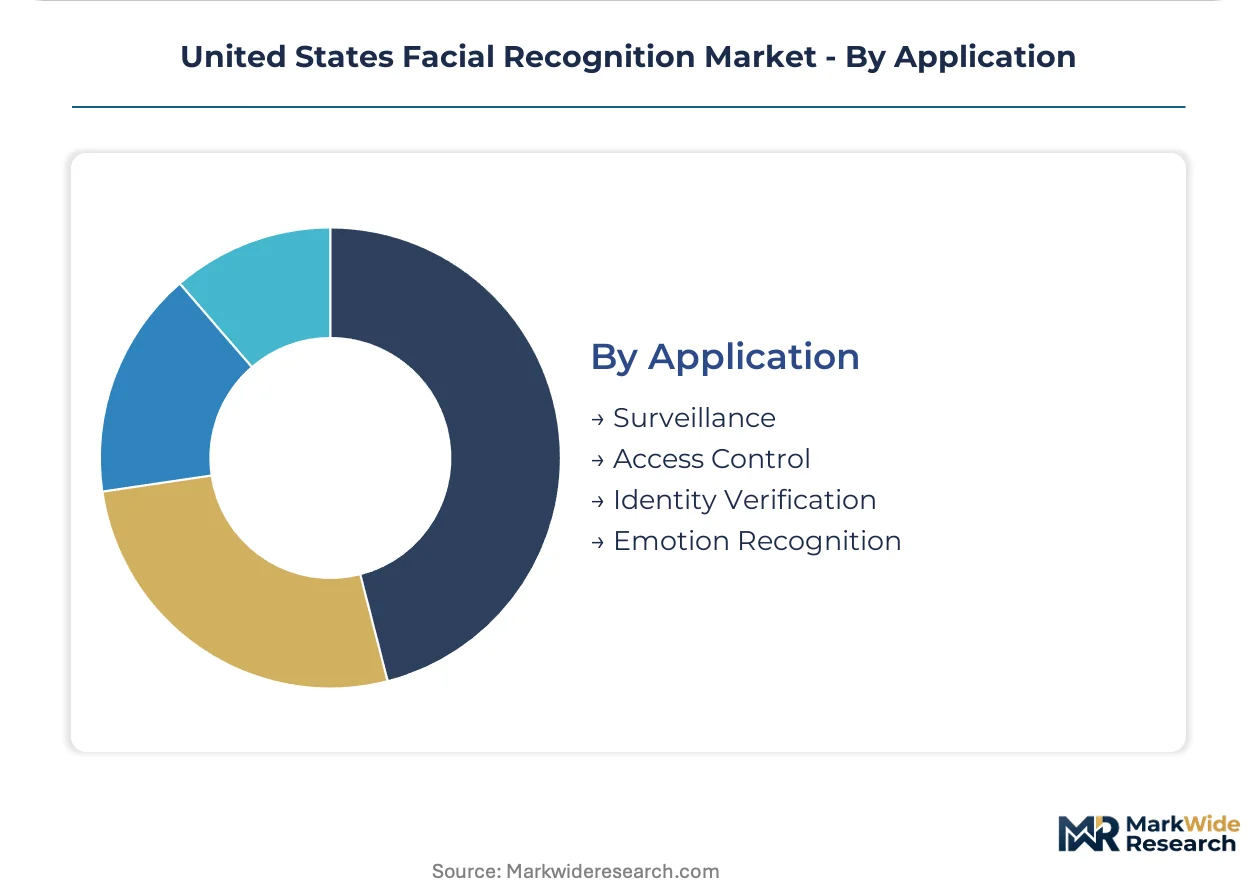
Physical security and digital identity proofing split the market between surveillance-heavy government deployments and consent-based commercial workflows.
- Surveillance:Real-time alerting systems for public safety and border security dominate federal and smart city infrastructure clusters in California and Texas municipalities.
- Access Control:Physical security integration requires costly middleware development to bridge proprietary Wiegand protocols with modern API-based platforms.
- Identity Verification:Digital onboarding and patient matching applications face regulatory fragmentation across state biometric privacy statutes.
- Emotion Recognition:Controversial deployment category facing heightened scrutiny from civil liberties advocates and pending federal algorithmic auditing legislation.
Identity Verification leads commercial adoption. Emotion Recognition faces regulatory headwinds that may constrain expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic cloud infrastructure providers leverage regulatory-arbitrage opportunities as state-level biometric privacy statutes fragment compliance costs across US jurisdictions, driving vendor concentration in permissive regulatory environments.
California
Smart city infrastructure clusters in Los Angeles and San Francisco deploy edge-based facial recognition for traffic management and public safety. The California Consumer Privacy Act imposes data deletion obligations that constrain retention practices for municipal surveillance systems. Silicon Valley technology corridors anchor commercial R&D investment in deep learning architectures for biometric authentication.
Texas
Border security deployments along the Rio Grande Valley drive concentrated demand for large-scale biometric installations at ports of entry. The Texas Capture or Use of Biometric Identifier Act mandates retention limits that parallel Illinois BIPA but with narrower private-right-of-action provisions. Dallas-Fort Worth metroplex clusters defense contractors specializing in infrared-thermal sensor fusion for critical infrastructure protection.
Illinois
Consumer-facing retail deployments face elevated compliance costs under the Biometric Information Privacy Act's written consent requirements. Chicago metropolitan area banking verticals pilot patient-matching protocols for healthcare identity proofing despite regulatory headwinds. The state's circuit court interpretations of BIPA damages exposure have forced national retail chains to abandon biometric checkout systems or implement costly opt-in workflows.
Virginia
Federal procurement concentration in Northern Virginia's defense corridor sustains demand for NIST FRVT-certified accuracy thresholds. The Commonwealth's proximity to Washington D.C. anchors Department of Homeland Security vendor relationships for port modernization programs. Arlington and Fairfax County technology clusters specialize in convolutional neural network development for law-enforcement applications.
Florida
Seaport biometric screening programs at Miami and Port Everglades drive installation cycles with multi-year procurement horizons. State-level preemption legislation pending in Tallahassee could establish uniform compliance thresholds reducing operational complexity for national security integrators. Tampa Bay medical centers pilot facial recognition for patient admission workflows under HIPAA-covered entity protocols.
United States Facial Recognition Market Competitive Landscape
West Coast cloud providers anchor one tier; East Coast federal contractors hold specialized positions in security-cleared installations. The vendor base separates between API-first platform vendors and hardware-integrated system specialists serving defense-critical infrastructure. Three archetypes dominate: hyperscale cloud providers with FedRAMP authorization, legacy biometric specialists with DHS relationships, and emerging AI-native challengers with ethical-review workflows. Competitive moves concentrate on strategic partnerships with security integrators and portfolio diversification into healthcare identity verticals.
Among hyperscale cloud providers, Amazon Web Services and Microsoft exemplify the platform-archetype competition for federal biometric workloads requiring sovereign data residency. NEC Corporation occupies a distinct position as a legacy specialist with long-standing Department of Homeland Security port-of-entry relationships. These three anchors represent divergent strategic postures: API-first scalability, ethical-review embedding, and large-scale hardware-software integration respectively.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft |
| NEC Corporation |
| Thales Group |
| Aware Inc. |
| Clearview AI Inc. |
| FaceFirst Inc. |
| Cognitec Systems |
| Panasonic Connect North America |
| Others |
Value Network & Pricing Analysis
Neural processing unit fabrication costs cascade through three distinct pricing tiers for facial recognition hardware, with Taiwan Semiconductor Manufacturing Company wafer pricing directly determining margin structures at the infrared camera module level.
Pricing Analysis
Distributor margins for security integrators compress pricing at the mid-market tier while direct-to-federal contracts preserve premium realization. Three-tier pricing structure across FedRAMP-authorized cloud APIs, on-premise perpetual licenses, and edge hardware bundles stratifies buyer segments. Pricing pressure stems from convolutional neural network commoditization as open-source architectures erode proprietary algorithm premiums. Regional credit unions exhibit highest price sensitivity, demanding operational expenditure models; defense contractors show lowest sensitivity, prioritizing NIST FRVT certification over unit cost.
Supply Chain Analysis
Regional distribution centers in Northern Virginia and Dallas-Fort Worth anchor hub-and-spoke patterns for federal and critical infrastructure deployments. Semiconductor fabrication concentrates in Taiwan, South Korea, and mainland China, with neural processing units and infrared sensors drawing from East Asian foundries. Rare earth elements for thermal imaging arrays rest on concentrated mining operations. Single-source vulnerability in advanced node chip production exposes procurement timelines to geopolitical disruption. Distribution runs through security integrators and value-added resellers with FedRAMP authorization credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Illinois BIPA compliance costs versus Texas regulatory permissiveness create a geographic-arbitrage opportunity for vendors able to modularize deployment architectures across state lines.
For Market Incumbents: Extend NIST FRVT certification pipelines to lock out emerging challengers facing eighteen-month testing queues. Deepen vertical integration into infrared sensor manufacturing to offset East Asian foundry concentration risk. Capture channel control through exclusive security integrator partnerships before open-source algorithms commoditize software margins. For New Entrants and Emerging Players: The Texas Capture or Use of Biometric Identifier Act opens a window for healthcare identity proofing pilots with narrower private-right-of-action exposure than Illinois. Target HIPAA-covered entities in Florida and Texas municipalities for patient-matching workflows. Pursue API-first go-to-market positioning through FedRAMP-authorized cloud marketplaces to bypass incumbent hardware-software bundling. For Investors and Strategic Acquirers: Consolidation pressure builds where convolutional neural network talent scarcity intersects with extended NIST certification timelines. Mid-stage vendors with existing FRVT participation and healthcare vertical penetration represent priority acquisition archetypes. Watch for federal preemption legislation as the inflection signal that would harmonize compliance costs and accelerate national retail chain adoption.| Strategic Initiative | Industry Significance |
|---|---|
| NIST FRVT Certification Investment | Federal solicitations now mandate published accuracy thresholds, disqualifying non-participants. |
| Healthcare Identity Proofing Expansion | HIPAA-covered entities pilot patient matching to reduce medical record duplication errors. |
| FedRAMP Cloud Authorization | Sovereign data residency requirements expand addressable base for API-first vendors. |
| Infrared-Thermal Sensor Fusion Development | Dual-use security and health screening creates value propositions for critical infrastructure operators. |
| Security Integrator Partnership | Channel bundling captures recurring revenue streams from regional credit unions preferring operational expenditure models. |
Research Methodology
Direct dialogue with biometric procurement officers at federal agencies, platform engineers at cloud service providers, security integrators, and healthcare IT directors grounded qualitative findings. Secondary validation drew from NIST FRVT benchmark publications, FedRAMP authorization databases, SEC 10-K filings of publicly traded vendors, and state legislative tracking systems for biometric privacy statutes. Bottom-up segment sizing triangulated against top-down federal procurement budget analysis.
Segment-level outputs across the analysis window reflect modeled deployment patterns by technology tier, end-user vertical, and state regulatory cluster. Convolutional neural network adoption curves and NIST certification queue durations informed hardware-software split projections. CAGRs derived from historical procurement cycles and pipeline visibility into Department of Homeland Security port modernization programs.
Revisions become necessary when federal preemption legislation materializes, East Asian semiconductor export controls expand, or class-action algorithmic bias litigation alters law-enforcement procurement risk calculus. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Biometric Smart Cards Market
Biometrics & Identity Management
E-Government Identity Management Market
Biometrics & Identity Management
Identity Verification Market
Biometrics & Identity Management
Global Behavioral Biometrics Market
Biometrics & Identity Management
IRIS Biometrics Market
Biometrics & Identity Management
Vein Recognition Biometrics Market
Biometrics & Identity Management
Europe Biometrics Market
Biometrics & Identity Management
Gait Biometrics Market
Biometrics & Identity Management
AI-Enabled Biometrics Market
Biometrics & Identity Management
Latin America Government & Security Biometrics Market
Biometrics & Identity Management
Multi-Factor Authentication (MFA) Market
Biometrics & Identity Management
Global Biometric Card Market
Biometrics & Identity Management
Mobile Biometrics Market
Biometrics & Identity Management
Passive Authentication Market
Biometrics & Identity Management
Global Biometric Technology Market
Biometrics & Identity Management
Asia-Pacific Government and Security Biometrics Market