
 Employee Monitoring Solutions (Automated) Market | 2026-2036
Employee Monitoring Solutions (Automated) Market Size, Share, and Industry Trends Forecast 2026-2036
Employee Monitoring Solutions (Automated) Market Foresight
Direct enterprise sales channels are reshaping how automated employee monitoring solutions reach buyers, with vendors bypassing traditional IT resellers to build subscription relationships. Teramind leverages behavioral analytics specialization to command premium positioning in regulated industries. Insightful competes on transparent pricing for mid-market SaaS buyers. ActivTrak anchors North American presence through native integrations with productivity suites.
Employee monitoring solutions (automated) encompass software systems that capture keystroke patterns, application usage timestamps, screen activity recordings, and communication metadata to generate workforce productivity analytics. These systems deploy lightweight endpoint agents or browser extensions that transmit encrypted telemetry to centralized dashboards for managerial review. Cloud-based deployment leads volume adoption due to minimal infrastructure requirements and rapid provisioning for distributed teams. Activity monitoring generates the deepest margin pools where behavioral baselining and insider threat detection command premium pricing. API integration capabilities separate platform-grade vendors from point solutions as enterprises demand native connectivity with HRIS and security information tools.
The EU AI Act classifies certain automated monitoring as high-risk, forcing algorithmic impact assessments and human oversight protocols. The US lacks federal comprehensive surveillance legislation, leaving the FTC and state-level biometric privacy laws such as Illinois BIPA to fragment compliance requirements. OSHA guidelines on electronic monitoring in hazardous workplaces add another compliance layer for industrial deployments. Stakeholders must track evolving algorithmic accountability standards and worker consent frameworks to anticipate which product architectures will retain market access.
Market Dynamics
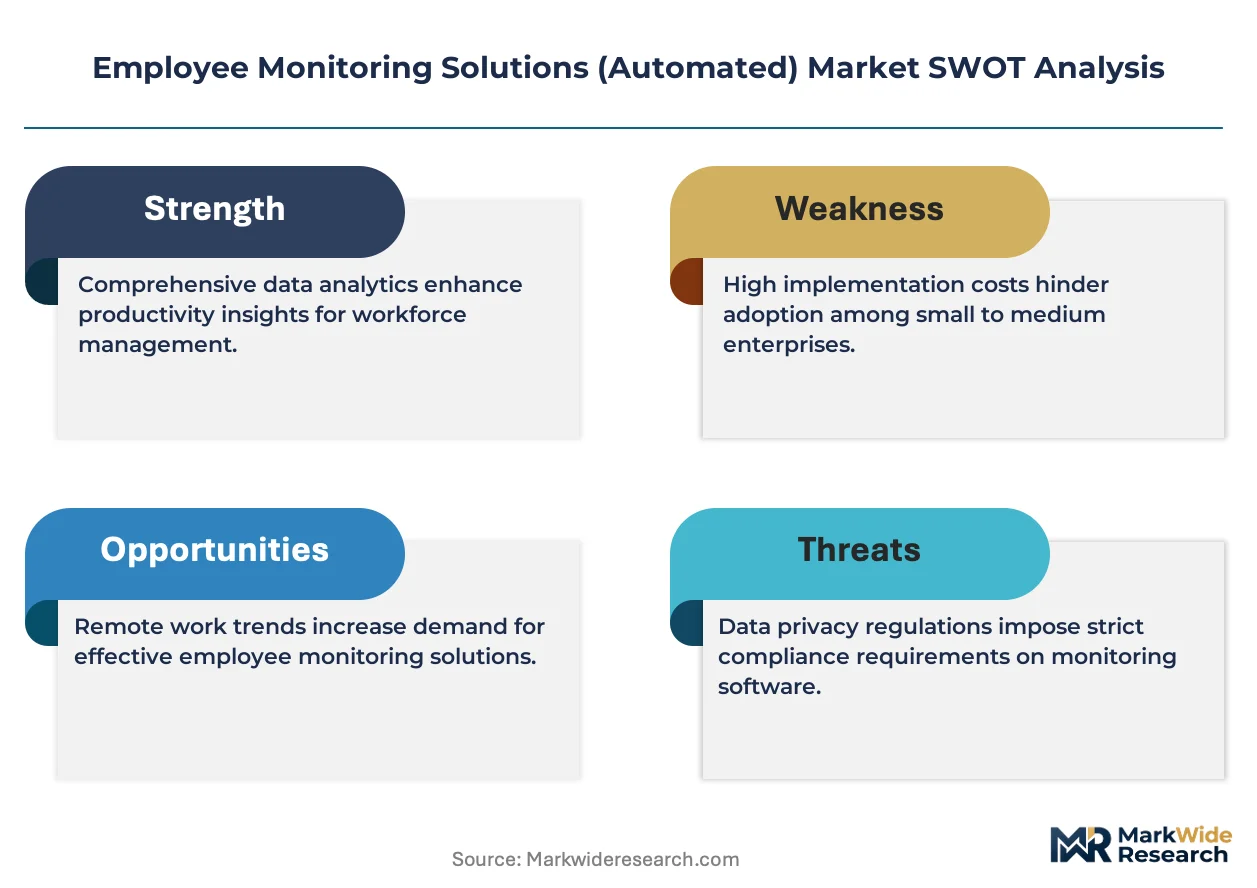
The EU AI Act's high-risk classification of algorithmic employee surveillance is forcing vendors to rearchitect products around human-in-the-loop oversight and impact assessment protocols.
Growth Catalysts
- GDPR Article 88:National implementations across Germany, France, and Italy legitimize monitoring where proportionality assessments are documented, creating compliant deployment pathways for regulated employers.
- Financial services compliance:Basel III operational risk frameworks and SEC cybersecurity disclosure rules drive automated oversight adoption for trading floor conduct and insider threat detection.
- Endpoint agent miniaturization:Containerized deployment models reduce IT friction, accelerating time-to-value for distributed enterprise rollouts without infrastructure overhaul.
Market Restraints
- Works council veto power:German Betriebsrat consent requirements under Works Constitution Act Section 87 create procedural delays and limit algorithmic scope in collective bargaining environments.
- Biometric data liability:Illinois BIPA's private right of action for biometric collection without informed consent exposes vendors and employers to statutory damages per violation.
- Cloud concentration risk:Reliance on AWS, Azure, and GCP for telemetry storage creates single-point-of-failure exposure and cross-border data sovereignty complications under Schrems II.
Strategic Opportunities
- India's Digital Personal Data Protection Act:Emerging clarity on employee consent frameworks opens deployment pathways for IT/ITES sector employers managing hybrid workforces.
- API-first architectures:Native connectivity with ServiceNow, Okta, and CrowdStrike enables platform positioning above point-solution competitors in enterprise security stacks.
- Unionized manufacturing:Predictive safety analytics for OSHA-recordable incident prevention creates differentiated value in automotive and chemical processing plants.
Industry Challenges
- Behavioral data science talent scarcity:Shortage of professionals combining occupational psychology credentials with machine learning engineering blocks advanced anomaly detection development.
- Algorithmic audit complexity:Proving non-discrimination in promotion and termination recommendations requires documentation infrastructure most vendors lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Employee Monitoring Solutions (Automated) Market |
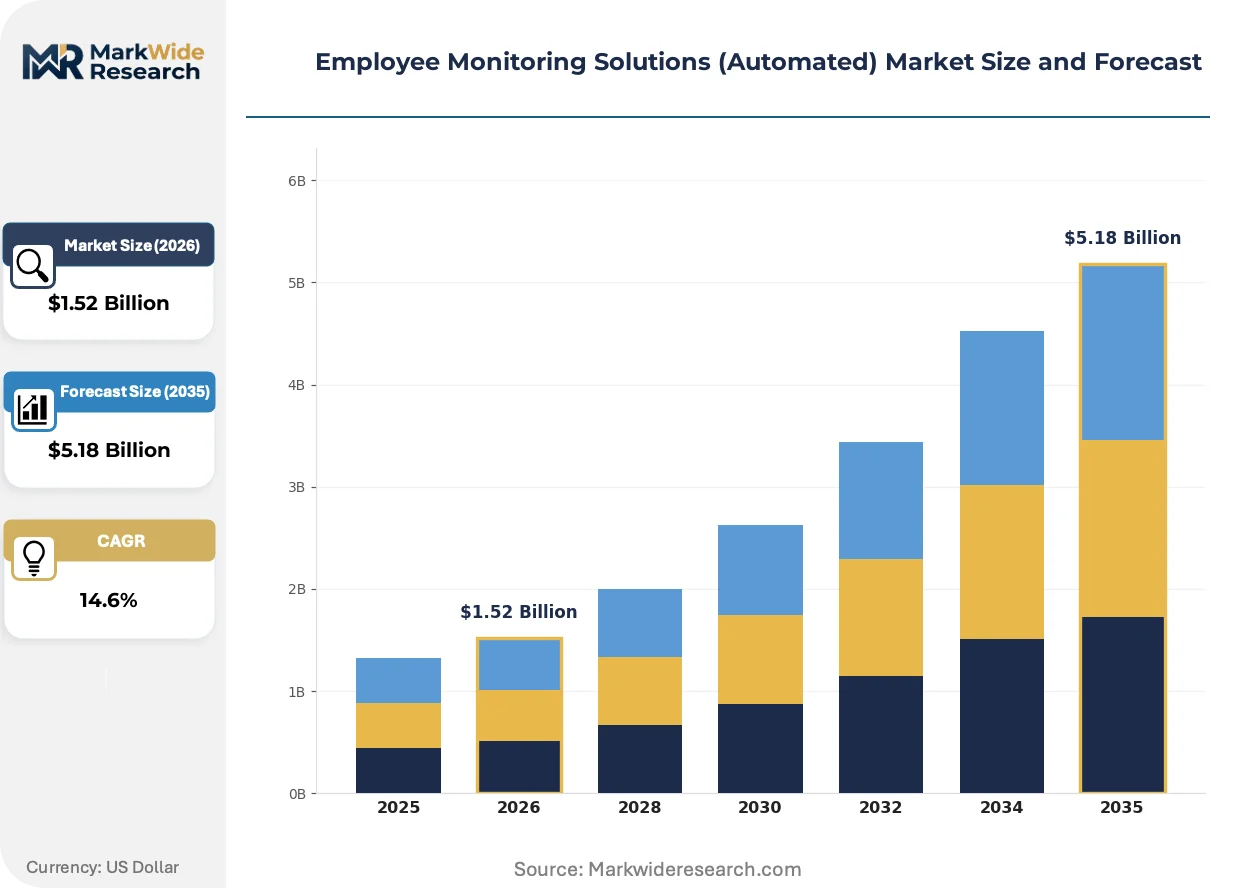
| Market Size in 2026 | $1.52 Billion |
| Market Size in 2035 | $5.18 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Time Tracking, Activity Monitoring, Communication Insights, Project Management Deployment: Cloud-based, On-premises, Hybrid, Mobile End User: SMEs, Large Enterprises, Remote Teams, Technical Support Integration Level: API Integration, Third-party Tools, SDK Support, Custom Solutions |
| Companies Covered | Teramind, Insightful, ActivTrak, CurrentWare, Hubstaff, Monitask, Prodscore, Veriato, Connecteam, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Employee Monitoring Solutions (Automated) Market Shifts & Advancements
Automated workforce oversight is pivoting from retrospective productivity scoring toward predictive risk intelligence, compressing vendor differentiation around behavioral science depth and integration breadth.
Keystroke dynamics and application logging is migrating from rule-based threshold alerts toward continuous behavioral baselining that flags deviation patterns indicative of insider threat or burnout. Defense contractors and cleared facilities are adopting these systems fastest, with deployment timelines compressing from 18 months to 90 days. This migration from reactive to predictive architectures is compressing margins for vendors lacking proprietary behavioral models.
The EU AI Act's high-risk system classification mandates algorithmic impact assessments and human oversight protocols for automated monitoring tools processing biometric or emotion data. Industrial consequence includes mandatory conformity assessments before market placement and ongoing post-market monitoring obligations. Financial services and public sector employers across Germany, France, and the Netherlands are most affected, with procurement teams now requiring vendor documentation of compliance-by-design architectures.
Enterprise buyers are consolidating vendor relationships around platforms offering native HRIS and security tool integration rather than standalone monitoring products. Mid-market SaaS purchasers specifically are displacing point solutions with bundled workforce analytics from existing ITSM or identity providers. This consolidation pattern is most visible in North American technology and professional services sectors, where procurement teams prioritize reduced integration overhead over specialized feature depth.
Employee Monitoring Solutions (Automated) Market Segmentation
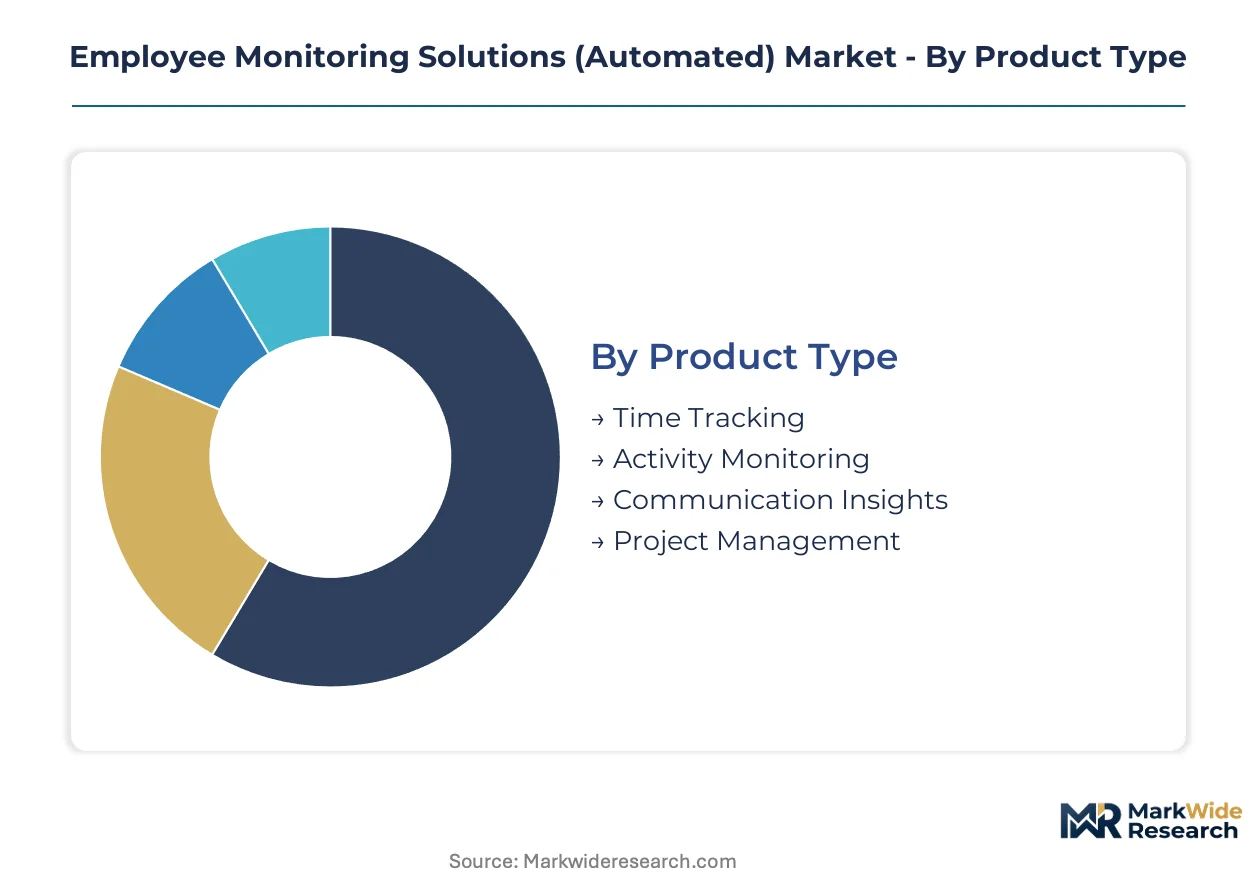
Automated employee monitoring solutions fragment across deployment architectures, functional depth, and organizational scale. Buyers prioritize segments matching their compliance exposure, IT maturity, and workforce distribution patterns.
Product Type:
Use-case spectrum spans from basic attendance verification to predictive behavioral intelligence, with feature depth determining pricing tier and buyer profile.
- Activity Monitoring:Captures keystroke dynamics, application usage timestamps, and screen recordings through lightweight endpoint agents. Financial services firms in Germany and France deploy these systems for Basel III operational risk compliance and insider threat detection, with works councils negotiating strict proportionality boundaries under GDPR Article 88 implementations.
- Communication Insights:Aggregates metadata from email, chat, and video conferencing platforms to flag sentiment shifts and policy violations. Demand concentrates among remote-first technology employers managing distributed engineering teams across multiple jurisdictions, driven by SEC cybersecurity disclosure requirements for material incident reporting.
- Time Tracking:Logs attendance patterns and project hour allocation through automated clock-in mechanisms. Professional services firms and legal practices favor this functionality for client billing accuracy.
- Project Management:Correlates individual activity data with task completion milestones and resource allocation dashboards. Mid-market SaaS buyers prioritize this integration to reduce standalone tool proliferation.
The dominant share belongs to Activity Monitoring, while Communication Insights is closing the gap fastest.
Deployment:
Cost tier stratification separates enterprise buyers with infrastructure investment capacity from mid-market purchasers seeking operational simplicity.
- Cloud-based:Delivers encrypted telemetry storage and centralized dashboards through multi-tenant SaaS architectures with minimal IT overhead. North American technology and professional services sectors drive volume adoption, prioritizing rapid provisioning for distributed teams without data center capital expenditure.
- Hybrid:Retains sensitive behavioral data on-premises while pushing analytics workloads to cloud infrastructure. German automotive manufacturers and chemical processors favor this architecture to satisfy Betriebsrat consent requirements and Schrems II data sovereignty constraints.
- On-premises:Deploys fully captive infrastructure for air-gapped environments and cleared facilities. Defense contractors and government agencies mandate this model for classified workforce oversight.
- Mobile:Extends monitoring capabilities to smartphone and tablet endpoints through containerized applications. Field service organizations and logistics operators deploy these agents for location-verified time tracking.
Cloud-based deployment holds the installed base majority, though Hybrid architectures are gaining share fastest among regulated European employers.
End User:
Customer type determines feature complexity tolerance, procurement cycle length, and integration requirements across the buyer journey.
- Large Enterprises:Demand platform-grade solutions with native HRIS and security information tool connectivity. These buyers command custom implementation roadmaps and dedicated customer success resources.
- SMEs:Prioritize transparent per-seat pricing and rapid self-service deployment without professional services engagement.
- Remote Teams:Require asynchronous activity verification and timezone-aware reporting for distributed workforce coordination.
- Technical Support:Leverages screen recording and application usage analytics for quality assurance and training optimization in customer service operations.
Large Enterprises contribute the deepest revenue per account, while Remote Teams are expanding most quickly as hybrid work permanence solidifies.
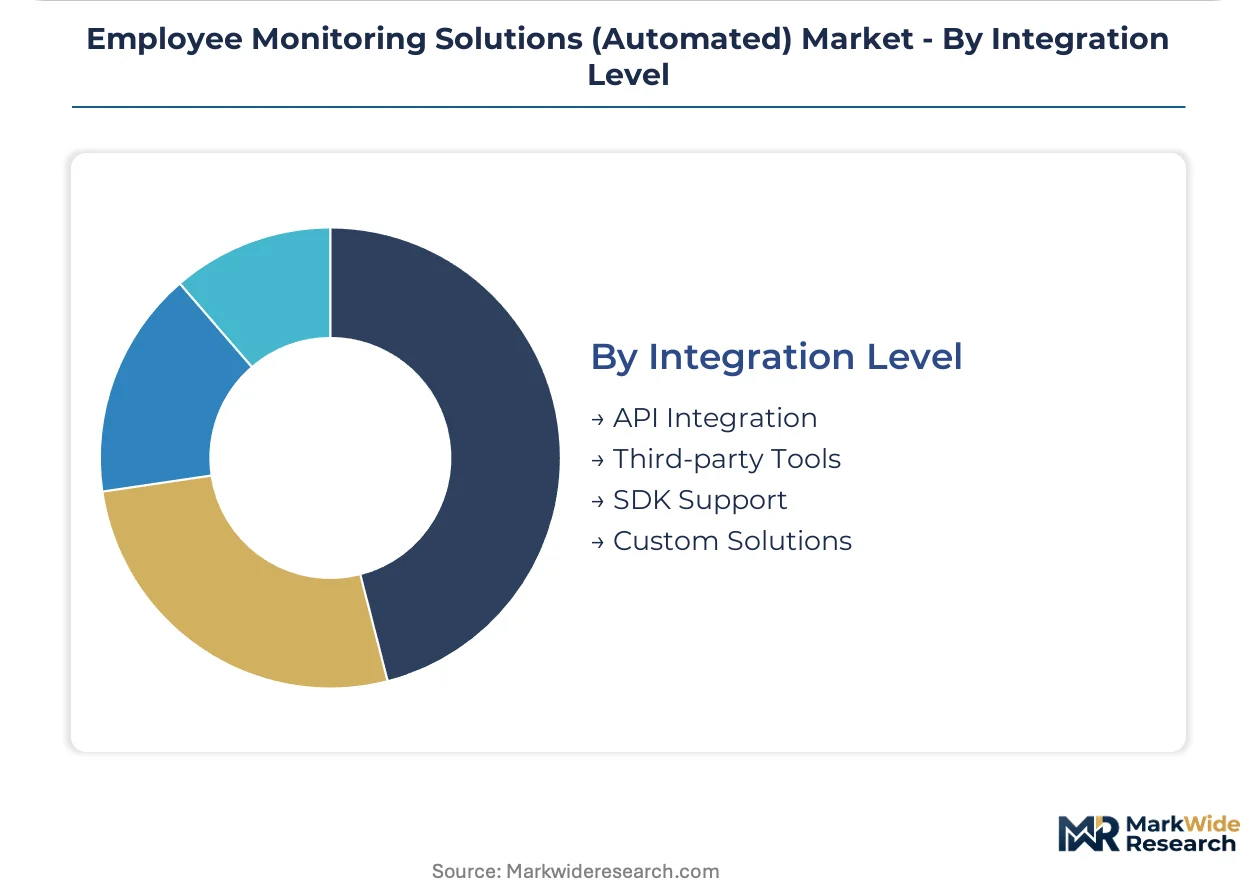
Integration Level:
Supply concentration among platform vendors versus point-solution specialists hinges on connectivity depth with existing enterprise software stacks.
- API Integration:Enables native data exchange with ServiceNow, Okta, CrowdStrike, and Splunk through RESTful endpoints and webhook architectures. Enterprise security teams prioritize this capability to consolidate vendor relationships and reduce integration maintenance overhead.
- Third-party Tools:Pre-built connectors for productivity suites, collaboration platforms, and identity providers accelerate time-to-value for mid-market buyers lacking development resources.
- SDK Support:Embeds monitoring functionality directly into custom applications through software development kits. Technology companies with proprietary internal tools favor this approach.
- Custom Solutions:Delivers bespoke agent development and dashboard configuration for specialized compliance environments or unique workflow requirements.
API Integration commands the premium positioning, with Third-party Tools climbing fastest as bundled workforce analytics displace standalone monitoring purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German works council negotiations, where procedural consent requirements inflate deployment costs, while US employers capture faster rollouts under fragmented state-level privacy regimes.
Germany
Financial services and automotive manufacturers drive demand for Basel III compliance and insider threat detection. Betriebsrat consent under the Works Constitution Act Section 87 mandates proportionality assessments before algorithmic deployment. Stuttgart's automotive cluster and Frankfurt's banking sector host the densest vendor-client negotiations, with hybrid cloud architectures preferred to satisfy data sovereignty constraints.
United States
Technology employers and defense contractors prioritize rapid provisioning for distributed engineering teams. FTC enforcement and Illinois BIPA's private right of action for biometric collection create liability exposure without federal uniformity. Silicon Valley and Northern Virginia's cleared facilities corridor anchor North American adoption, with cloud-native deployments dominating procurement patterns.
France
Public sector employers and regulated industries expand automated oversight under CNIL guidance on GDPR Article 88 proportionality. The EU AI Act's high-risk classification forces algorithmic impact assessments for emotion recognition systems. Paris-Île-de-France concentrates financial services deployment, while Lyon and Toulouse house aerospace and defense monitoring requirements.
India
IT/ITES sector employers managing hybrid workforces seek clarity under the Digital Personal Data Protection Act's emerging consent frameworks. The RBI's operational risk guidelines for financial institutions accelerate adoption among banking technology service providers. Bengaluru's technology corridor and Hyderabad's IT cluster represent the fastest-expanding addressable markets for endpoint agent deployment.
United Kingdom
Professional services firms and legal practices demand client billing accuracy through automated time tracking. The Information Commissioner's Office guidance on employee monitoring legitimacy shapes procurement documentation requirements. London's financial and legal services density drives premium-tier platform adoption, with Manchester and Edinburgh emerging as mid-market expansion targets.
Employee Monitoring Solutions (Automated) Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream capturing margin on behavioral analytics modules. The vendor base stratifies across three tiers: enterprise-grade platforms with native security stack connectivity, mid-market SaaS providers competing on transparent per-seat pricing, and point-solution specialists in keystroke dynamics or insider threat detection. Strategic archetypes include API-first architects, behavioral science boutiques, and bundled workforce analytics divisions of larger ITSM vendors. Competitive moves concentrate on M&A for behavioral data science talent and strategic partnerships with identity providers.
Within the behavioral analytics specialist tier, Teramind occupies a position exemplifying premium positioning in regulated industries. Insightful and ActivTrak represent alternative archetypes: the former sits within transparent mid-market SaaS positioning, while the latter anchors North American presence through productivity suite integration strategies. These three companies collectively illustrate how vendor differentiation compresses around either integration breadth or behavioral science depth.
| Leading Market Players |
|---|
| Teramind |
| Insightful |
| ActivTrak |
| CurrentWare |
| Hubstaff |
| Monitask |
| Prodscore |
| Veriato |
| Connecteam |
| Others |
Supply & Pricing Matrix
Undercapacity in German behavioral data science talent pools tightens vendor pricing power while compressing margins for algorithmic audit documentation. This utilization squeeze forces tiered SaaS pricing stratification across cloud-native, hybrid, and on-premises deployment architectures.
Pricing Analysis
Customization-premium spreads separate configured-to-order implementations for German automotive manufacturers from standard cloud-native subscriptions for North American technology employers. Three-tier pricing structure across premium, standard, and economy levels anchors on integration depth with ServiceNow and CrowdStrike, with API-first architectures commanding brand premiums. Cost compression in the mid-market tier intensifies because bundled workforce analytics from ITSM vendors displace standalone purchases. SMEs exhibit highest price sensitivity, while defense contractors with air-gapped requirements show least elasticity.
Supply Chain Analysis
Export-control regimes limiting endpoint agent cryptography flows constrain telemetry processing capabilities in cleared facilities. Supply concentrates in the United States, Ireland, and India for cloud infrastructure and behavioral analytics engineering. Component dependencies include containerized deployment frameworks, encrypted streaming protocols, and GPU clusters for anomaly detection training. Single-source vulnerability runs through AWS, Azure, and GCP concentration for telemetry storage. Distribution runs through direct enterprise sales teams bypassing traditional IT resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense against bundled workforce analytics from ITSM and identity platform vendors eroding standalone monitoring value. Native HRIS integration depth determines retention against this displacement threat.
For Market Incumbents: Entrench platform positioning through backward integration into proprietary behavioral science models and captive compliance documentation infrastructure. Prioritize Betriebsrat negotiation playbooks for German market retention against works council veto risks. Certification investment in EU AI Act conformity assessment capabilities separates defensible vendors from displacement casualties.
For New Entrants and Emerging Players: Indian IT/ITES sector underpenetration offers white-space expansion under emerging Digital Personal Data Protection Act clarity. Target mid-market SaaS purchasers in Bengaluru and Hyderabad with transparent per-seat pricing and rapid self-service deployment. Go-to-market leverage rests on pre-built connectors for existing productivity suite footprints rather than standalone agent proliferation.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among API-first architects with native security stack connectivity and established enterprise customer success functions. Long-term viability across the analysis window favors behavioral science boutiques with occupational psychology credentials combined with machine learning engineering depth. Acquisition target archetype: specialized keystroke dynamics firms with defense sector certifications. Signal to watch: procurement team consolidation patterns around platform-grade solutions versus point-solution displacement rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native connectivity with Okta and ServiceNow consolidates vendor relationships in enterprise security stacks. |
| Acquisition of Specialist Firm | Behavioral data science boutiques fill talent scarcity gaps for advanced anomaly detection development. |
| Geographic Expansion | Indian IT/ITES sector penetration captures hybrid workforce management demand under DPDPA frameworks. |
| Product Launch | Predictive safety analytics modules differentiate offerings for OSHA-regulated manufacturing environments. |
| Strategic Partnership | Identity provider alliances embed monitoring functionality within existing authentication workflows. |
Research Methodology
Initial hypotheses were tested against primary input from CTOs, IT procurement officers, platform engineers, and integration specialists and refined through secondary validation. Bottom-up sizing triangulated endpoint agent deployment estimates with top-down market consolidation analysis. Secondary sources included SEC filings of publicly traded workforce analytics vendors, hyperscaler capex disclosures for cloud infrastructure capacity, and CNIL guidance documentation on GDPR Article 88 proportionality assessments.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across deployment architecture, functional depth, organization size, integration complexity, and regional regulatory cluster dimensions. CAGRs derived from installed base growth rates weighted by pricing tier mix and cloud-native adoption curves. Industry-specific forecast inputs incorporated works council negotiation timelines for German deployments and SEC cybersecurity disclosure compliance deadlines for financial services adoption.
Practitioners should monitor EU AI Act implementing acts and state-level biometric privacy legislation expansions for early signals of algorithmic accountability standard shifts. Forecasts reflect assumptions on hybrid work permanence and regulatory enforcement intensity that may require revision. Cross-checking against vendor earnings call commentary on enterprise sales cycle length is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Privacy Filters Market
Video Surveillance Systems
United Arab Emirates Surveillance Camera Market
Video Surveillance Systems
Brazil Surveillance IP Cameras Market
Video Surveillance Systems
Mini Security Camera Market
Video Surveillance Systems
Wireless Video Surveillance Market
Video Surveillance Systems
Surveillance Camera Systems Market
Video Surveillance Systems
India Video Surveillance Market
Video Surveillance Systems
Smart Camera System Market
Video Surveillance Systems
Middle East and Africa Surveillance Analog Camera Market
Video Surveillance Systems
India Surveillance Camera Market
Video Surveillance Systems
Asia-Pacific Video Surveillance Systems Market
Video Surveillance Systems
Smart Outdoor Cameras Market
Video Surveillance Systems
Security Camera Software Market
Video Surveillance Systems
Coastal Surveillance Systems Market
Video Surveillance Systems
North America Video Surveillance Systems Market
Video Surveillance Systems
Rugged Thermal Cameras Market