
 United Kingdom Access Control Market | 2026-2036
United Kingdom Access Control Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Access Control Market Insights
Enterprise-grade access credentialing is bifurcating the United Kingdom market into premium integrated suites and cost-optimized standalone units. Assa Abloy leverages its door hardware heritage to anchor high-specification installations across London's commercial core. Johnson Controls competes through building management convergence, embedding access logic within wider energy and security platforms. Paxton Access specializes in mid-market networked systems, sustaining growth through installer channel density and simplified commissioning protocols.
United Kingdom access control encompasses electromechanical and electronic systems that govern physical entry through credential verification, lock release mechanisms, and audit trail generation, typically operating at 12-24V DC with IP65-rated outdoor readers. These systems secure commercial assets, protect personnel, and enforce time-bound permissions across multi-zone facilities. Biometric systems command premium positioning due to liveness detection requirements and GDPR-aligned data governance, while RFID solutions retain volume leadership through backward compatibility with legacy infrastructure. Cloud-based solutions represent the fastest-expanding technology dimension as estate managers prioritize remote administration and API-driven integration with visitor management platforms.
The UK Information Commissioner's Office enforces GDPR-mandated biometric data processing protocols, compelling vendors to deploy on-premise template storage or EU-sovereign cloud instances. The Building Safety Regulator, established under the Building Safety Act, imposes traceable access logging for high-rise residential structures, directly stimulating demand for audit-capable systems. Stakeholders must evaluate whether their credential architectures can absorb anticipated amendments to the Digital Identity and Attributes Trust Framework without wholesale infrastructure replacement.
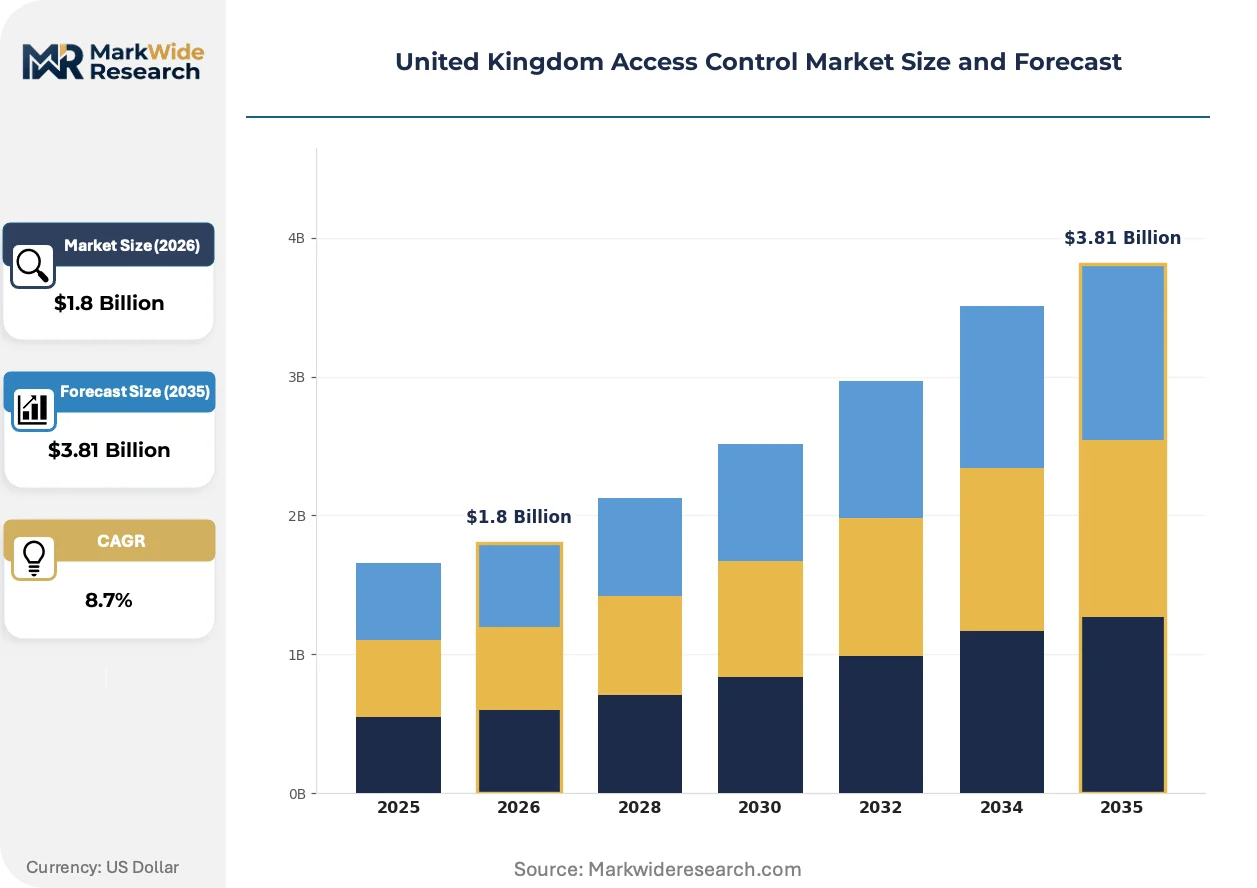
Market Dynamics
The Building Safety Act 2022 mandates audit-trail logging for high-rise residential structures, forcing estate managers toward cloud-native credential platforms and compressing replacement cycles for legacy card-based infrastructure across England and Wales.
Growth Catalysts
- GDPR-mandated biometric governance:The UK Information Commissioner's Office enforces strict template storage protocols, compelling upgrades to on-premise or EU-sovereign cloud architectures that vendors must certify.
- London financial district:Enterprise-grade deployments in the Square Mile accelerate hardware refresh rates as banks consolidate physical security with cyber-identity frameworks.
- Multi-occupancy housing stock:The Building Safety Regulator's traceable access requirements stimulate demand for networked electromechanical systems in residential towers exceeding 18 meters.
Market Restraints
- Semiconductor supply concentration:Reader controller chipsets depend on East Asian fabrication capacity, exposing UK integrators to lead-time volatility for IP65-rated outdoor units.
- Copper and rare-earth magnet costs:Electromechanical lock assemblies face input price pressure from commodity markets, compressing margin on mid-market standalone installations.
- Legacy RS-485 infrastructure:Thousands of commercial buildings retain proprietary wiring topologies that resist IP-native retrofit without full cable replacement.
Strategic Opportunities
- API-driven visitor management convergence:Integration between access platforms and workspace booking systems creates new revenue streams for software-enabled hardware vendors.
- Scotland's urban regeneration zones:Glasgow and Edinburgh commercial developments present underpenetrated demand for cloud-credentialing in Class A office stock.
- Digital Identity and Attributes Trust Framework:Anticipated amendments to this UK government scheme will favor credential architectures with portable identity verification, rewarding early standard adopters.
Industry Challenges
- Cyber-physical security skills gap:Installer networks lack sufficient technicians certified in both network engineering and physical lock hardware, delaying commissioning timelines.
- Multi-vendor integration complexity:Estate managers struggle to unify disparate door hardware, video management, and identity platforms into coherent administration workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Access Control Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biometric Systems, RFID Solutions, Keyless Entry, Access Cards End User: Commercial Buildings, Government Facilities, Healthcare Organizations, Educational Institutions Technology: Cloud-Based Solutions, Wireless Systems, Mobile Access, Wired Systems Application: Perimeter Security, Internal Access Control, Parking Management, Time and Attendance |
| Companies Covered | Assa Abloy, Johnson Controls, Honeywell International Inc, Paxton Access, Suprema Inc, Bosch Security Systems, Allegion PLC, dormakaba Group, Thales Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Access Control Market Trends and Innovations
Mobile credentialing via smartphone wallets is redrawing competitive boundaries between traditional lock manufacturers and consumer electronics platforms, while regulatory pressure on data residency accelerates architectural decisions.
Biometric liveness detection is supplanting static fingerprint templates in high-assurance deployments. London financial institutions now mandate presentation-attack-resistant readers for trading floor access. This technology compression is collapsing the price premium between enterprise and mid-market biometric hardware tiers.
The Building Safety Act's golden thread documentation requirements impose digital record-keeping obligations on dutyholders. High-rise residential developers must demonstrate traceable access event logs from construction through occupancy. Northern England's build-to-rent pipeline shows the steepest compliance-driven procurement acceleration.
Estate managers now specify subscription-based credential lifecycle management rather than perpetual license purchases. Channel partners pivot toward recurring revenue models, displacing upfront hardware margins with multi-year service agreements. This preference shift concentrates in Manchester and Birmingham commercial developments where flexible tenancy structures dominate.
United Kingdom Access Control Market Segmentation
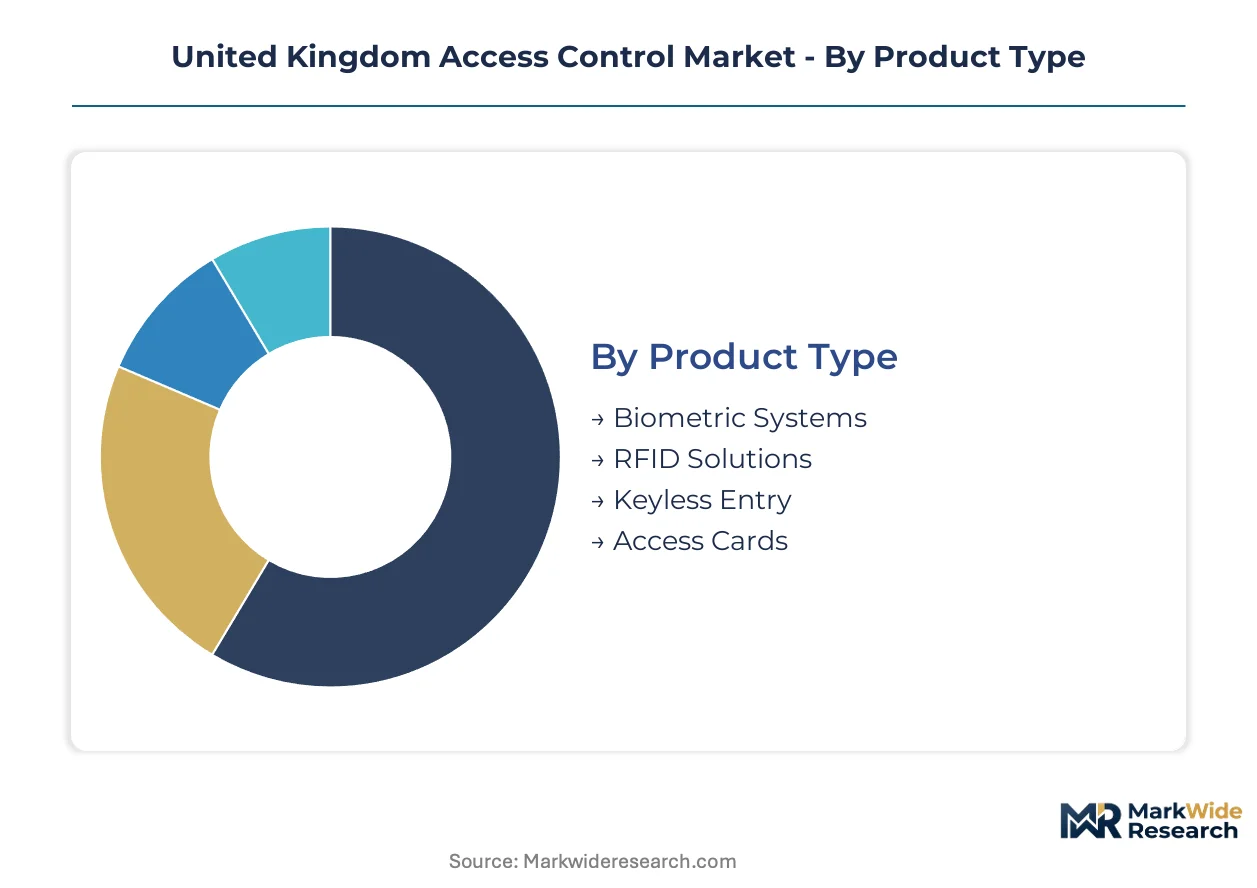
Access control procurement in the United Kingdom follows distinct technical and regulatory pathways. Buyers segment investments by compliance burden, integration complexity, and estate scale rather than hardware specifications alone.
Product Type:
The UK Information Commissioner's Office enforces divergent data governance protocols across credential technologies, forcing architectural trade-offs between biometric template storage and legacy card compatibility.
- Biometric Systems:Liveness detection readers with presentation-attack resistance now dominate high-assurance deployments in London's financial district. Trading floors mandate these systems under consolidated cyber-physical security frameworks, though GDPR compliance requires on-premise or EU-sovereign cloud template architectures that inflate deployment costs.
- RFID Solutions:Backward compatibility with installed card populations sustains volume leadership across commercial estates. Manchester and Birmingham office developments favor multi-technology readers that bridge 125kHz legacy credentials with 13.56MHz encrypted formats, easing transition without full infrastructure replacement.
- Keyless Entry:Smartphone wallet integration is displacing dedicated fobs in build-to-rent residential towers. Glasgow and Edinburgh regeneration zones show concentrated specification of BLE-enabled locks that synchronize with tenant onboarding platforms.
- Access Cards:Physical credential production concentrates in mid-market standalone installations where perpetual licensing persists. Northern England residential compliance procurement favors these systems for their audit-trail simplicity under Building Safety Regulator mandates.
RFID Solutions handles the majority of throughput; Biometric Systems is gaining share fastest on regulatory tailwinds.
End User:
Cost tier differentiation separates enterprise-grade integrated suites from cost-optimized standalone procurement across UK verticals.
- Commercial Buildings:Cloud-native credential platforms dominate Class A office stock in London, Manchester, and Birmingham. Estate managers prioritize API-driven visitor management convergence and subscription-based lifecycle economics over perpetual hardware purchases.
- Government Facilities:CESG-compliant architectures and sovereign data residency requirements constrain vendor selection. Central government estates mandate on-premise identity platforms with air-gapped biometric template storage, compressing addressable supply base.
- Healthcare Organizations:NHS estates balance infection control with access audit requirements. Electromechanical locks with antimicrobial coatings see concentrated specification in acute care settings, though legacy RS-485 infrastructure resists IP-native retrofit in aging hospital stock.
- Educational Institutions:University campuses favor mobile credentialing for student populations. Edinburgh and Glasgow higher education estates are accelerating smartphone wallet deployments that integrate with library and catering systems.
Commercial Buildings absorbs the dominant share of capital deployment; Healthcare Organizations is expanding most quickly on post-pandemic security prioritization.
Technology:
Volume concentration favors established connectivity architectures, though customer preference is shifting toward administration flexibility.
- Cloud-Based Solutions:Remote credential provisioning and API-driven integration with workspace booking platforms now dominate new-build commercial specifications. The Building Safety Act's golden thread documentation requirements accelerate adoption in high-rise residential developments where traceable access logs must persist from construction through occupancy.
- Wireless Systems:Battery-powered locks with mesh networking reduce cabling costs in heritage building retrofits. London's listed commercial stock shows concentrated deployment where structural restrictions prohibit new cable runs.
- Mobile Access:Smartphone wallet credentialing is redrawing competitive boundaries between traditional lock manufacturers and consumer electronics platforms. Channel partners pivot toward recurring revenue models as estate managers specify subscription-based lifecycle management.
- Wired Systems:Hardwired controllers retain preference in high-assurance government and financial deployments where electromagnetic interference resilience outweighs installation flexibility.
Cloud-Based Solutions commands the steepest expansion trajectory; Wired Systems retains foundation share in security-critical estates.
Application:
Margin structure varies by integration depth, with perimeter systems commanding premium positioning against commoditized time-tracking functions.
- Perimeter Security:IP65-rated outdoor readers with multi-factor authentication anchor high-specification installations. London financial district deployments mandate these systems for trading floor separation, with liveness detection readers specified at primary entry points.
- Internal Access Control:Networked electromechanical systems with zone-based permissioning dominate multi-occupancy commercial estates. The Building Safety Regulator's traceable access requirements stimulate demand in residential towers exceeding 18 meters.
- Parking Management:ANPR-integrated barrier systems with credential verification see specification in mixed-use developments. Birmingham and Manchester commercial pipelines favor these integrations for tenant experience differentiation.
- Time and Attendance:Basic card readers with shift-logging functionality face commoditization pressure. Mid-market standalone units concentrate in light industrial estates where GDPR compliance burden remains minimal.
Internal Access Control carries the volume base; Perimeter Security captures premium positioning on assurance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across UK sub-regions. London buyers absorb premium pricing for integrated suites, while Northern England and Midlands procurement favors cost-optimized standalone units with compressed replacement cycles.
London and Southeast
The Square Mile's financial institutions mandate liveness detection biometric readers for trading floor access under consolidated cyber-physical security frameworks. The UK Information Commissioner's Office enforces GDPR-compliant template storage protocols, compelling on-premise or EU-sovereign cloud architectures. Canary Wharf and City of London commercial developments anchor enterprise-grade deployment concentration.
Midlands
Birmingham's Class A office pipeline favors cloud-native credential platforms with API-driven visitor management integration. The Building Safety Act's golden thread documentation requirements accelerate networked electromechanical procurement in high-rise residential towers. Build-to-rent developments across the West Midlands specify subscription-based lifecycle management over perpetual licensing.
North England
Manchester commercial estates drive RFID solution volume through multi-technology readers bridging legacy 125kHz credentials with encrypted 13.56MHz formats. The Building Safety Regulator's traceable access mandates stimulate audit-capable system demand in residential structures exceeding 18 meters. Northern build-to-rent pipelines show steepest compliance-driven procurement acceleration.
Scotland
Glasgow and Edinburgh regeneration zones present underpenetrated demand for smartphone wallet credentialing in new commercial stock. Scottish urban development programs prioritize BLE-enabled locks synchronized with tenant onboarding platforms. Higher education estates in Edinburgh accelerate mobile credential deployments integrating library and catering systems.
Wales
Cardiff commercial developments concentrate mid-market standalone installations where perpetual licensing persists. Welsh housing associations navigate Building Safety Act compliance through simplified audit-trail systems. Semiconductor supply volatility for IP65-rated outdoor readers disproportionately impacts Welsh integrator networks with limited inventory buffers.
United Kingdom Access Control Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the UK access control market. Premium integrated suites command position through door hardware heritage and building management convergence, while cost-optimized standalone units compete on installer channel density and simplified commissioning protocols. Three archetypes dominate: heritage lock manufacturers with electromechanical expertise, building automation conglomerates with platform integration capabilities, and mid-market specialists with dense installer networks. Competitive moves concentrate on strategic partnerships for API-driven integration and portfolio diversification into cloud-credentialing services.
Within the heritage manufacturer tier, Assa Abloy and dormakaba Group anchor high-specification installation positioning through door hardware lineage. Johnson Controls and Honeywell International Inc exemplify building automation convergence archetypes, embedding access logic within wider energy and security platforms. Paxton Access occupies the mid-market specialist position, sustaining growth through installer channel density. Bosch Security Systems and Allegion PLC sit within the diversified security conglomerate category, while Suprema Inc and Thales Group represent technology-forward credentialing specialists.
| Leading Market Players |
|---|
| Assa Abloy |
| Johnson Controls |
| Honeywell International Inc |
| Paxton Access |
| Suprema Inc |
| Bosch Security Systems |
| Allegion PLC |
| dormakaba Group |
| Thales Group |
| Others |
Pricing and Supply Chain Analysis
Cloud-native credential platforms displacing perpetual license models simultaneously redistribute margin capture toward recurring revenue streams and concentrate procurement leverage among software-enabled hardware vendors with EU-sovereign cloud architectures. This substitution dynamic reshapes both supply geography—favoring vendors with certified GDPR-compliant template storage—and pricing economics, compressing upfront hardware margins while expanding lifetime value through subscription attach rates.
Pricing Analysis
After-sales service tiers and multi-year credential lifecycle contracts now drive lifetime value capture, displacing transactional hardware sales as the dominant revenue architecture. Three-tier pricing structure across premium integrated suites, standard networked systems, and economy standalone units separates Assa Abloy's door hardware heritage deployments from Paxton's mid-market density play. Cost compression in economy standalone tiers intensifies because copper and rare-earth magnet input volatility squeezes electromechanical lock assembly margins. Mid-market installer networks show greatest price sensitivity; London financial district buyers absorb premium liveness detection biometric premiums with minimal negotiation.
Supply Chain Analysis
Taiwan and South Korea anchor controller chipset fabrication for IP65-rated outdoor readers, while China dominates electromechanical lock component stamping and rare-earth magnet processing. UK integrators draw from East Asian semiconductor capacity for reader controller chipsets, European door hardware heritage for high-specification electromechanical assemblies, and domestic channel partners for installation commissioning. Single-source vulnerability in East Asian fabrication capacity exposes UK integrators to lead-time volatility for outdoor-rated units. Distribution runs through certified installer networks with direct vendor relationships, bypassing traditional distribution intermediaries for enterprise-grade deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom access control market constitutes a high-growth disruption as mobile credentialing via smartphone wallets collapses competitive boundaries between heritage lock manufacturers and consumer electronics platforms, accelerated by Building Safety Act mandates for traceable access logging.
For Market Incumbents: Secure API-driven integration capabilities with visitor management and workspace booking platforms to defend against software-native entrants. Deepen backward integration into EU-sovereign cloud credential architectures to satisfy GDPR-mandated biometric template storage requirements. Channel control through certified installer network expansion remains essential as mid-market procurement shifts toward simplified commissioning protocols. For New Entrants and Emerging Players: Lead with smartphone wallet credentialing in Scotland's underpenetrated Glasgow and Edinburgh regeneration zones, where BLE-enabled lock specifications lag London deployment maturity. Target build-to-rent residential towers exceeding 18 meters across Northern England, where Building Safety Regulator compliance creates urgent replacement demand for legacy card systems. Go-to-market through property technology platform partnerships rather than traditional security integrator channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed mid-market access control specialists possessing dense UK installer networks but limited cloud-credentialing capabilities. Five-to-ten year viability hinges on successful SaaS transition and API ecosystem integration. Acquisition candidates showing accelerated recurring revenue mix and EU-sovereign cloud certification merit priority evaluation. The signal to watch is amendment timing to the Digital Identity and Attributes Trust Framework, which will favor portable identity architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Credentialing Platform Migration | Enables subscription revenue capture and satisfies Building Safety Act golden thread documentation mandates. |
| API-Driven Visitor Management Integration | Creates differentiated tenant experience in Manchester and Birmingham Class A office developments. |
| EU-Sovereign Cloud Certification | Unlocks GDPR-compliant biometric deployments across London financial district trading floors. |
| Installer Channel Density Expansion | Accelerates commissioning timelines and captures mid-market standalone replacement cycles. |
| Liveness Detection Biometric Certification | Meets presentation-attack resistance requirements for high-assurance government and financial estates. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with security integrators, estate managers, and biometric technology vendors; and secondary validation through SEC filings of building automation conglomerates, UK government regulatory publications, and trade association procurement surveys. Physical security directors at London financial institutions, NHS estates managers, and certified installer network heads provided deployment timeline and technology preference intelligence. Bottom-up triangulation against top-down market sizing from customs trade data and hardware shipment records ensured cross-validation.
Across the projection horizon, the analytical framework modeled technology adoption curves, regulatory compliance deadlines, and replacement cycle dynamics. Segmentation dimensions included credential technology type, deployment architecture, end-use vertical, and geographic sub-region. CAGRs were derived from installed base evolution, new-build specification rates, and compliance-driven replacement acceleration. Forecast inputs incorporated semiconductor lead-time volatility, copper price trajectory assumptions, and cloud infrastructure penetration rates.
Forecasts assume regulatory continuity in UK GDPR enforcement and Building Safety Act implementation; material policy shifts in biometric data governance or high-rise residential safety mandates would require re-modeling. Recalibration cycles align with material shifts in Digital Identity and Attributes Trust Framework amendments, East Asian semiconductor supply availability, and London commercial development pipeline announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Europe Access Control Hardware Market
Access Control Systems
US Access Control Market
Access Control Systems
Door Controller Systems Market
Access Control Systems
Digital Security Control Market
Access Control Systems
North America Access Control Market
Access Control Systems
Global Barrier Systems Market
Access Control Systems
Japan Smart Lock Market
Access Control Systems
Keyless Entry System Market
Access Control Systems
Pedestrian Access Control System Market
Access Control Systems
Global Industrial Security Systems Market
Access Control Systems
Europe Cylinder Lock Market
Access Control Systems
Latin America Pin-Based Access Control Market
Access Control Systems
Middle-East and Africa Airport Passenger Screening Systems Market
Access Control Systems
Card-Based Electronic Access Control Systems Market
Access Control Systems
Global Industrial Safety Gates Market
Access Control Systems
Facial Recognition Access Control Solution Market