
 Canada Surveillance Analog Camera Market | 2026-2036
Canada Surveillance Analog Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Surveillance Analog Camera Market Insights
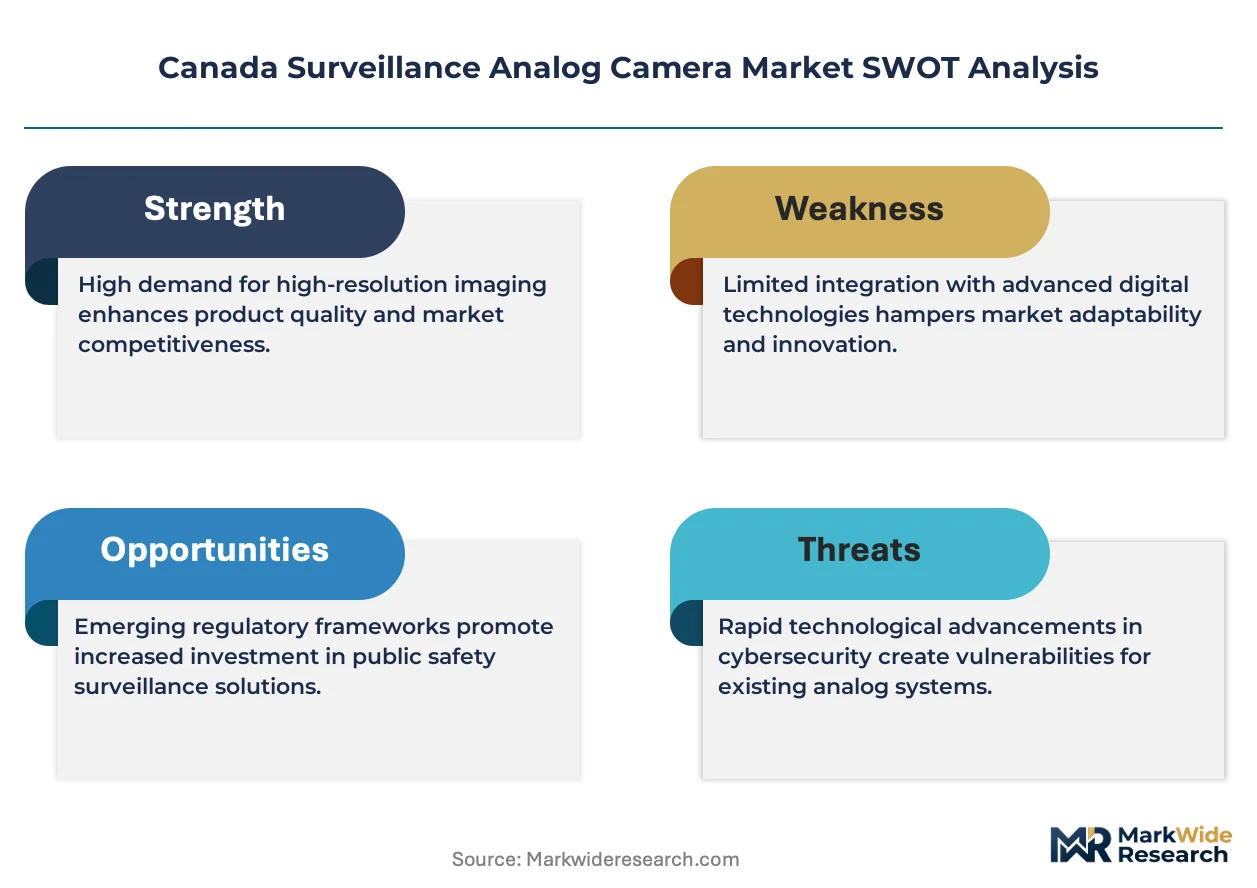
Multi-source procurement for image sensors and DSP chipsets is pivoting toward consolidated vendor relationships among Canadian security integrators. Hangzhou Hikvision Digital Technology leverages its broad distribution network to sustain volume availability across provincial tenders. Hanwha Vision anchors its position through localized technical support and firmware customization for Canadian climate conditions. Bosch Sicherheitssysteme differentiates via ruggedized housing designs rated for subarctic temperature extremes.
Canada surveillance analog cameras employ coaxial-cable signal transmission with composite video output, typically operating at 720p or 960H resolution through NTSC encoding standards. These devices serve critical infrastructure where real-time monitoring without network latency takes precedence over analytics capability. Dome cameras occupy the largest installed base within retail and government corridors where vandal resistance matters. Bullet cameras lead outdoor installations across transportation yards and perimeter fencing. PTZ units capture the fastest replacement cycle among education-sector buyers seeking mechanical pan-tilt reliability without IP-network dependency.
Health Canada and the Office of the Privacy Commissioner of Canada jointly shape surveillance deployment through health-sector privacy guidelines and public-space recording restrictions. CSA Group certification requirements for electrical safety and environmental sealing filter non-compliant imports from the supply chain. The Canadian Security Intelligence Service advises on critical infrastructure camera hardening standards. Stakeholders must weigh analog lifecycle extension against hybrid-upgrade pathways as provincial privacy rulings tighten retention and access protocols.
Market Dynamics
Hybrid migration pathways are fragmenting procurement timelines across Canadian security integrators as provincial privacy rulings tighten retention protocols and force parallel analog-digital system planning.
Growth Catalysts
- Correctional infrastructure mandates:Ontario and British Columbia sustain analog procurement for legacy system compatibility within penitentiary networks where IP-network dependency creates operational risk.
- Canada's Privacy Act constraints:Federal and provincial data-protection statutes limit cloud-connected camera deployment, preserving demand for closed-circuit analog architectures in sensitive facilities.
- Prairie-region network gaps:Agricultural and remote industrial sites across Saskatchewan and Manitoba lack fiber infrastructure, making coaxial-based analog systems the only viable surveillance option.
Market Restraints
- Image sensor supply concentration:Canadian integrators face single-source dependency on Asian semiconductor foundries for CCD and CMOS sensors used in analog camera assembly.
- Resolution ceiling:NTSC encoding standards cap analog output at 960H, creating technical disqualification from procurement tenders requiring facial recognition-grade image clarity.
- IP-camera substitution pressure:Power-over-Ethernet devices with embedded analytics threaten analog market share in urban commercial applications where network infrastructure exists.
Strategic Opportunities
- Northern territorial expansion:Yukon, Northwest Territories, and Nunavut present underpenetrated demand for cold-climate-rated analog units where satellite backhaul costs prohibit IP-system deployment.
- CSA Group certification pathways:Electrical safety and environmental sealing standards create regulatory moats for compliant domestic integrators against uncertified import competition.
- Hybrid encoder convergence:Analog-to-IP bridge devices enable staged infrastructure upgrades, extending equipment lifecycle value for budget-constrained municipal buyers.
Industry Challenges
- Coaxial technician scarcity:Aging workforce proficiency in BNC termination and 75-ohm impedance matching limits installation capacity as vocational programs pivot to network certification.
- Privacy compliance timeline compression:Provincial information and privacy commissioners are accelerating audit frequencies, forcing integrators to document analog footage chain-of-custody protocols under tighter deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Surveillance Analog Camera Market |
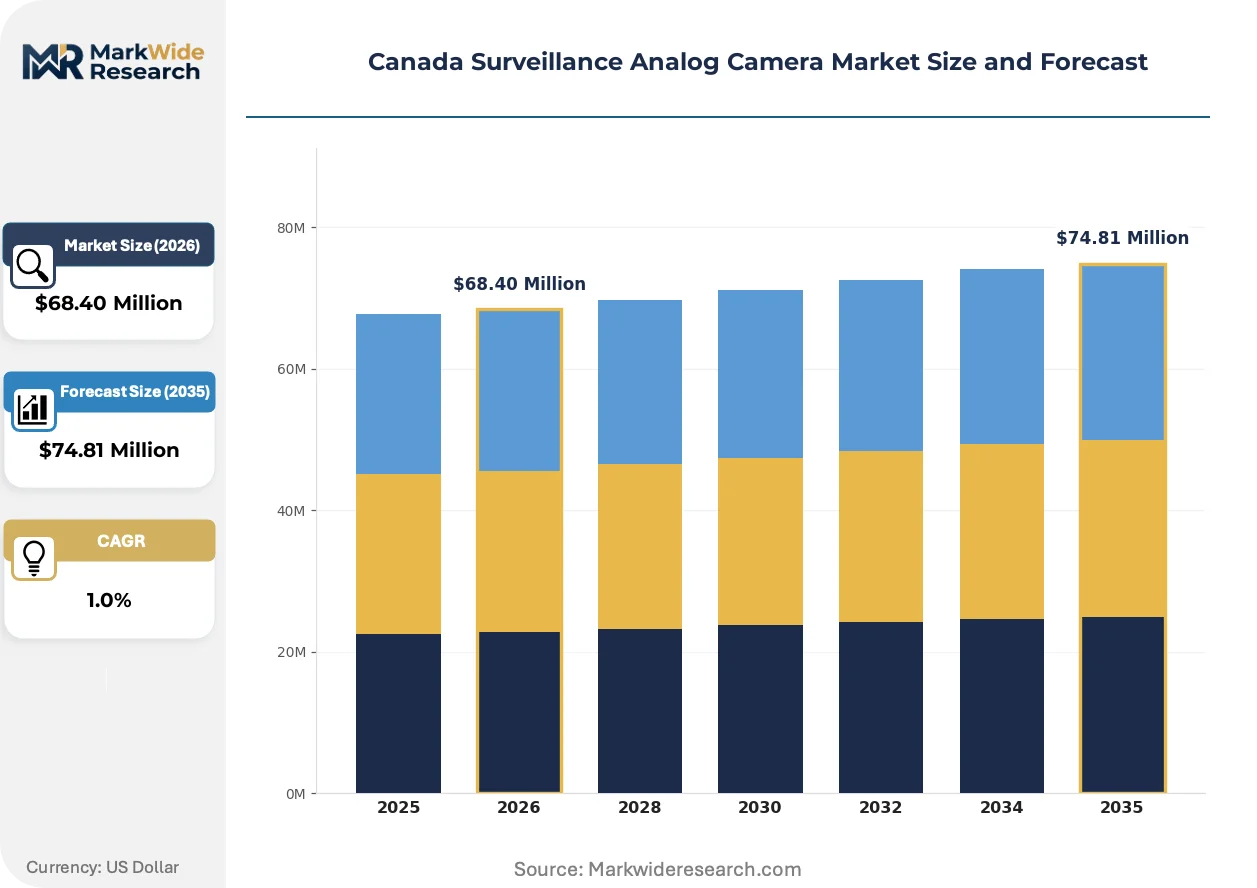
| Market Size in 2026 | $68.40 Million |
| Market Size in 2035 | $74.81 Million |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dome Cameras, Bullet Cameras, PTZ Cameras, Box Cameras End User: Retail, Government, Transportation, Education Technology: Analog, Hybrid, IP-Ready, Network-Compatible Installation Type: Indoor, Outdoor, Wall-Mounted, Ceiling-Mounted |
| Companies Covered | Teledyne FLIR, Hangzhou Hikvision Digital Technology, Hanwha Vision, Bosch Sicherheitssysteme, ACTi Corporation, Zhejiang Uniview Technologies, Honeywell International, Pelco, Zosi Technology, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Surveillance Analog Camera Market Trends and Innovations
Signal processing architectures are bifurcating as Canadian buyers weigh real-time reliability against analytics capability, with climate-hardened housing designs gaining specification priority in subarctic deployment zones.
Digital Signal Processor chipsets with integrated noise reduction are automating low-light performance optimization in analog dome and bullet configurations. Correctional facilities and remote mining operations are adopting these units fastest, replacing 2015-era sensor modules. The technology is automating technician workload reduction in perimeter zones where manual gain adjustment was previously required seasonally.
Health Canada and the Office of the Privacy Commissioner have issued joint surveillance deployment guidelines tightening health-sector recording restrictions. These rules now require explicit signage and retention limits for cameras near patient areas. Long-term care operators in Quebec and Alberta are retrofitting analog systems with localized DVR storage to satisfy data-sovereignty requirements.
Integrator consolidation is compressing distributor margins as national security firms acquire regional specialists across the Prairie provinces. Independent dealers in Manitoba and Saskatchewan are losing specification influence to direct manufacturer relationships. This channel restructuring is most visible in agricultural co-operative procurement, where volume buyers now negotiate provincial supply agreements bypassing traditional wholesaler networks.
Canada Surveillance Analog Camera Market Segmentation
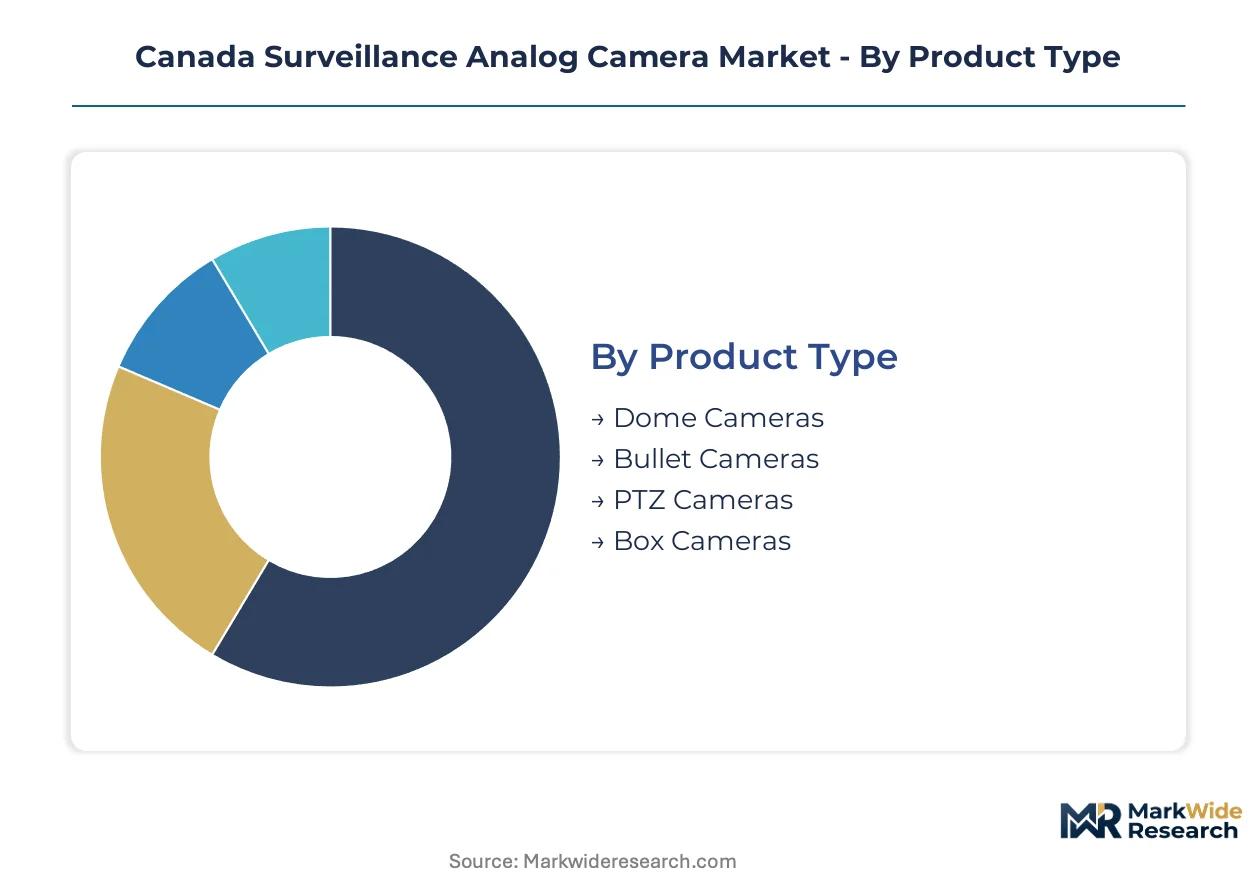
Segmentation in the Canadian surveillance analog camera market reveals how procurement specifications diverge across regulatory environments and infrastructure constraints. Understanding these divides helps vendors align certification investments with buyer priorities.
Product Type:
CSA Group certification requirements for electrical safety and environmental sealing vary significantly across housing configurations, with cold-climate ratings mandatory for outdoor-deployed units.
- Dome Cameras:Vandal-resistant hemispherical housings with polycarbonate domes dominate retail corridors and government facilities. Ontario penitentiaries specify these units for cell-block monitoring where physical tampering resistance outweighs optical range requirements.
- Bullet Cameras:Cylindrical weather-sealed housings with integrated sunshields lead transportation yard installations across British Columbia. Prairie-region agricultural buyers favor these units for perimeter fencing where directional surveillance and cost minimization converge.
- PTZ Cameras:Motorized pan-tilt-zoom mechanisms with mechanical position feedback serve education-sector auditoriums and gymnasiums. These units carry the shortest replacement cycles as mechanical wear drives scheduled refresh programs.
- Box Cameras:Modular lens-interchangeable housings for specialized focal-length requirements persist in legacy industrial sites. Saskatchewan mining operations maintain these configurations for customizable field-of-view adaptation.
Dome cameras sit at the top of the volume ranking, with bullet cameras climbing the fastest as transportation infrastructure spending accelerates.
End User:
Privacy Act compliance burdens concentrate heaviest in health-adjacent and public-space deployments, creating divergent procurement approval timelines.
- Retail:Loss-prevention departments in Quebec and Alberta shopping centers prioritize discrete dome installations with localized DVR storage. Provincial privacy commissioners mandate explicit signage protocols that delay deployment schedules.
- Government:Federal facilities and provincial correctional institutions sustain analog procurement through legacy system compatibility mandates. British Columbia penitentiaries reject IP-network dependency for operational security reasons.
- Transportation:Rail yards and port terminals across Vancouver and Montreal require cold-rated bullet cameras with subarctic temperature specifications. These buyers prioritize real-time reliability over analytics integration.
- Education:K-12 districts and post-secondary campuses in Manitoba favor PTZ units for auditorium coverage. Mechanical pan-tilt reliability without network latency drives specification choices.
Government end users command the largest installed base, though transportation procurement is expanding most quickly as infrastructure security budgets rise.
Technology:
Signal processing architectures determine hybrid-upgrade pathways and residual equipment valuation for municipal buyers.
- Analog:Pure composite-video output through coaxial transmission persists where network infrastructure is absent. Northern territorial deployments across Yukon and Nunavut depend exclusively on this architecture due to satellite backhaul cost prohibitions.
- Hybrid:Dual-output units with simultaneous analog and digital encoding enable staged infrastructure migration. Budget-constrained municipal buyers in Saskatchewan favor these configurations for lifecycle extension.
- IP-Ready:Analog cameras with embedded encoders for future network attachment. These units carry price premiums that limit adoption to integrators with confirmed upgrade roadmaps.
- Network-Compatible:Firmware-configurable units supporting both closed-circuit and packet-switched operation. Alberta long-term care operators specify these for flexibility under evolving Health Canada privacy guidelines.
Pure analog technology retains volume leadership, while hybrid configurations are gaining share fastest as provincial privacy rulings force parallel system planning.
Installation Type:
Mounting specifications determine labor cost structures and technician certification requirements across installation geographies.
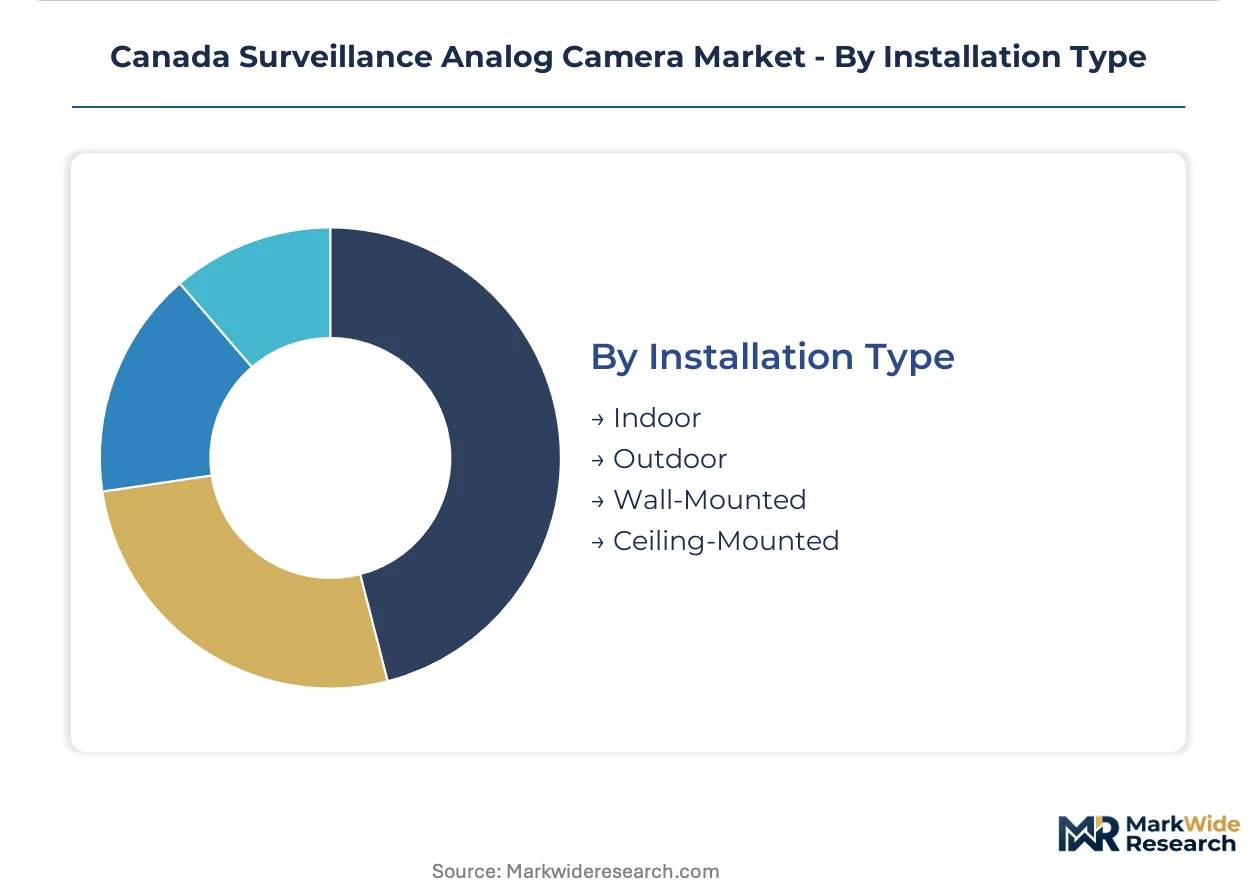
- Indoor:Climate-controlled environments with standard electrical enclosures dominate retail and education deployments. These installations avoid the CSA Group environmental sealing premiums required for outdoor ratings.
- Outdoor:Weather-sealed housings with IP66 or higher ratings and integrated heater-blower assemblies. Subarctic temperature extremes in Manitoba and Saskatchewan demand cold-start ratings below minus forty degrees Celsius.
- Wall-Mounted:Cantilevered arm assemblies for perimeter and corridor applications. Transportation yards specify these configurations for flexible repositioning without structural ceiling access.
- Ceiling-Mounted:Recessed or surface-mount brackets for dome camera integration. Government corridors in Ontario standardize on these installations for aesthetic uniformity and vandal resistance.
Outdoor installation types lead procurement value, with ceiling-mounted configurations showing steepest expansion as government facility modernization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario's correctional infrastructure network sustains the largest provincial procurement volume for analog surveillance equipment in Canada. Federal penitentiaries and provincial detention centers across the province prioritize legacy coaxial systems for operational security. The Office of the Privacy Commissioner of Canada maintains active oversight of camera deployments near sensitive government facilities.
Ontario
Toronto's transit authority and provincial correctional facilities drive sustained analog camera demand for legacy system compatibility. Health Canada guidelines restrict cloud-connected surveillance in healthcare-adjacent properties. Manufacturing corridors around Hamilton and Kitchener-Waterloo maintain analog installations where network latency disrupts real-time monitoring requirements.
British Columbia
Vancouver port terminals and rail yards require cold-rated bullet cameras with subarctic temperature specifications. The province's Privacy Act enforcement creates procurement delays for surveillance projects in public spaces. Mining operations in the Interior and northern resource corridors depend on coaxial-based systems where fiber infrastructure remains absent.
Alberta
Long-term care operators in Calgary and Edmonton retrofit analog systems with localized DVR storage to satisfy data-sovereignty requirements. Provincial health-sector privacy mandates from Health Canada tighten retention protocols for cameras near patient areas. Agricultural cooperatives across the southern prairie negotiate volume supply agreements directly with manufacturers.
Quebec
Retail loss-prevention departments in Montreal shopping centers prioritize discrete dome installations with explicit signage protocols mandated by provincial privacy commissioners. The province's language and data-localization requirements favor integrators with French-language technical support. Industrial sites around Quebec City maintain legacy box camera configurations for customizable field-of-view adaptation.
Prairie Provinces
Saskatchewan and Manitoba agricultural operations and remote industrial sites lack fiber infrastructure, making coaxial-based analog systems the only viable surveillance option. Provincial tenders across the region sustain procurement of cold-climate-rated units. Independent dealers in Winnipeg and Regina lose specification influence to direct manufacturer relationships as national security firms consolidate regional specialists.
Canada Surveillance Analog Camera Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue hybrid-encoder convergence and northern territorial expansion. The vendor base concentrates around three strategic archetypes: diversified technology conglomerates with broad distribution networks, specialized vision-system manufacturers with climate-hardened product lines, and regional security integrators with CSA Group certification advantages. Competitive positioning depends on firmware customization capabilities for Canadian privacy regulations and cold-climate housing designs. M&A activity targets prairie-region specialists, while capacity investments concentrate on hybrid analog-digital bridge devices.
Among Asia-based technology conglomerates, Hangzhou Hikvision Digital Technology and Hanwha Vision exemplify scale-driven market presence through volume availability and localized technical support structures. Bosch Sicherheitssysteme GmbH represents the European industrial archetype with ruggedized engineering credentials. These three anchors demonstrate how geographic origin and organizational structure shape competitive positioning without dictating specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Teledyne FLIR |
| Hangzhou Hikvision Digital Technology |
| Hanwha Vision |
| Bosch Sicherheitssysteme |
| ACTi Corporation |
| Zhejiang Uniview Technologies |
| Honeywell International |
| Pelco |
| Zosi Technology |
| Others |
Pricing and Supply Chain Analysis
Health Canada's cold-climate equipment mandates gate qualified supply for subarctic-rated analog cameras, restricting premium-tier pricing access to vendors with CSA Group environmental sealing certifications. This regulatory filter compresses margins for uncertified imports while elevating price floors for compliant domestic integrators serving prairie-region agricultural buyers.
Pricing Analysis
Input-cost pass-through from CCD and CMOS sensor procurement governs contract negotiations between Canadian security integrators and Asian semiconductor foundries. Three-tier pricing structure across premium, standard, and economy levels separates CSA-certified cold-climate units from indoor-rated configurations and uncertified imports. Cost compression in the standard tier is intensifying because prairie-region agricultural cooperatives negotiate provincial volume supply agreements directly with manufacturers. Municipal buyers in Saskatchewan and Manitoba exhibit highest price sensitivity due to budget-constrained procurement cycles, while federal correctional facilities in Ontario demonstrate lowest sensitivity given operational security mandates.
Supply Chain Analysis
Freight cost escalation from Asian manufacturing hubs to Vancouver and Montreal ports elevates landed costs for analog camera assemblies by fifteen to twenty percent over domestic North American sourcing alternatives. Supply concentrates in China, South Korea, and Taiwan for image sensor fabrication, DSP chipset production, and lens module assembly. Raw material dependencies span polycarbonate dome housings, coaxial cable copper conductors, and heater-blower assemblies for subarctic operation. Single-source vulnerability in CCD sensor supply creates procurement risk during foundry capacity constraints. Distribution runs through national security firms acquiring regional prairie specialists, bypassing traditional Winnipeg and Regina wholesaler networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a geographic-arbitrage play between Ontario's correctional infrastructure mandates and the prairie provinces' network-infrastructure gaps, exploiting the cost differential between legacy coaxial deployment and fiber-dependent IP alternatives.
For Market Incumbents: Lock in CSA Group certification pathways for electrical safety and environmental sealing to create regulatory moats against uncertified import competition. Deepen backward integration into cold-climate housing production to defend margin position against Hanwha Vision and Bosch Sicherheitssysteme's localized technical support advantages. Prioritize firmware customization capabilities for Health Canada privacy compliance as provincial retention protocols tighten.
For New Entrants and Emerging Players: Launch via direct manufacturer relationships with prairie-region agricultural cooperatives, bypassing consolidated national security integrators. Underpenetrated demand in Yukon, Northwest Territories, and Nunavut presents the most penetrable geography where satellite backhaul costs prohibit IP-system deployment. Target education-sector PTZ replacement cycles with mechanical reliability guarantees that eliminate network latency concerns.
For Investors and Strategic Acquirers: Roll-up economics work for regional CSA-certified integrators because channel consolidation in Manitoba and Saskatchewan has collapsed independent dealer margins below sustainable thresholds. Five-to-ten year viability hinges on hybrid analog-digital bridge device adoption extending equipment lifecycles. Watch provincial privacy commissioner audit frequency acceleration as the inflection signal for compliance-service revenue expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| CSA Group Certification Investment | Electrical safety and environmental sealing standards filter non-compliant imports from Health Canada-regulated deployments. |
| Hybrid Encoder Product Development | Analog-to-IP bridge devices enable staged infrastructure upgrades for budget-constrained Saskatchewan municipal buyers. |
| Prairie Region Channel Acquisition | Consolidation of Winnipeg and Regina specialists captures agricultural cooperative procurement bypassing wholesaler networks. |
| Cold-Climate Housing Manufacturing Scale-Up | Subarctic temperature ratings below minus forty degrees Celsius address Manitoba and Saskatchewan outdoor installation demand. |
| Privacy Compliance Service Expansion | Localized DVR storage retrofitting satisfies Health Canada data-sovereignty requirements for Alberta long-term care operators. |
Research Methodology
Direct dialogue with security integrators, correctional facility procurement officers, prairie-region agricultural cooperative managers, and CSA Group certification engineers grounded qualitative insights in operational reality. Secondary validation drew from Health Canada surveillance deployment guidelines, Office of the Privacy Commissioner of Canada rulings, provincial tender documentation, and customs import records for analog camera assemblies. Bottom-up equipment shipment estimates triangulated against top-down infrastructure spending allocations across the analysis window.
Unit economics and value projections emerged from segmented modeling across product type, end user, technology architecture, and installation geography dimensions. CAGRs were derived through logistic diffusion curves applied to hybrid migration pathways and replacement cycle timing. Forecast inputs incorporated coaxial technician workforce demographics, provincial privacy audit acceleration schedules, and northern territorial satellite backhaul cost structures.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated IP-camera substitution in urban commercial applications or prolonged semiconductor foundry capacity constraints. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Global CCTV Market
Video Surveillance Systems
Europe Video Surveillance As a Service Market
Video Surveillance Systems
AI Surveillance System Market
Video Surveillance Systems
North America Surveillance Analog Camera Market
Video Surveillance Systems
United States Surveillance IP Camera Market
Video Surveillance Systems
United States Surveillance Camera Market
Video Surveillance Systems
Europe Surveillance Camera Market
Video Surveillance Systems
Night Vision Outdoor Camera Market
Video Surveillance Systems
China Video Surveillance Market
Video Surveillance Systems
Smart Outdoor Cameras Market
Video Surveillance Systems
United Arab Emirates Surveillance Camera Market
Video Surveillance Systems
Mexico Surveillance IP Camera Market
Video Surveillance Systems
China Surveillance IP Camera Market
Video Surveillance Systems
China Surveillance Camera Market
Video Surveillance Systems
In-Vehicle Video Surveillance Market
Video Surveillance Systems
Employee Monitoring Solutions (Automated) Market