
 Hosted Video Surveillance Market | 2026-2036
Hosted Video Surveillance Market Size, Share, and Industry Trends Forecast 2026-2036
Hosted Video Surveillance Market Analysis
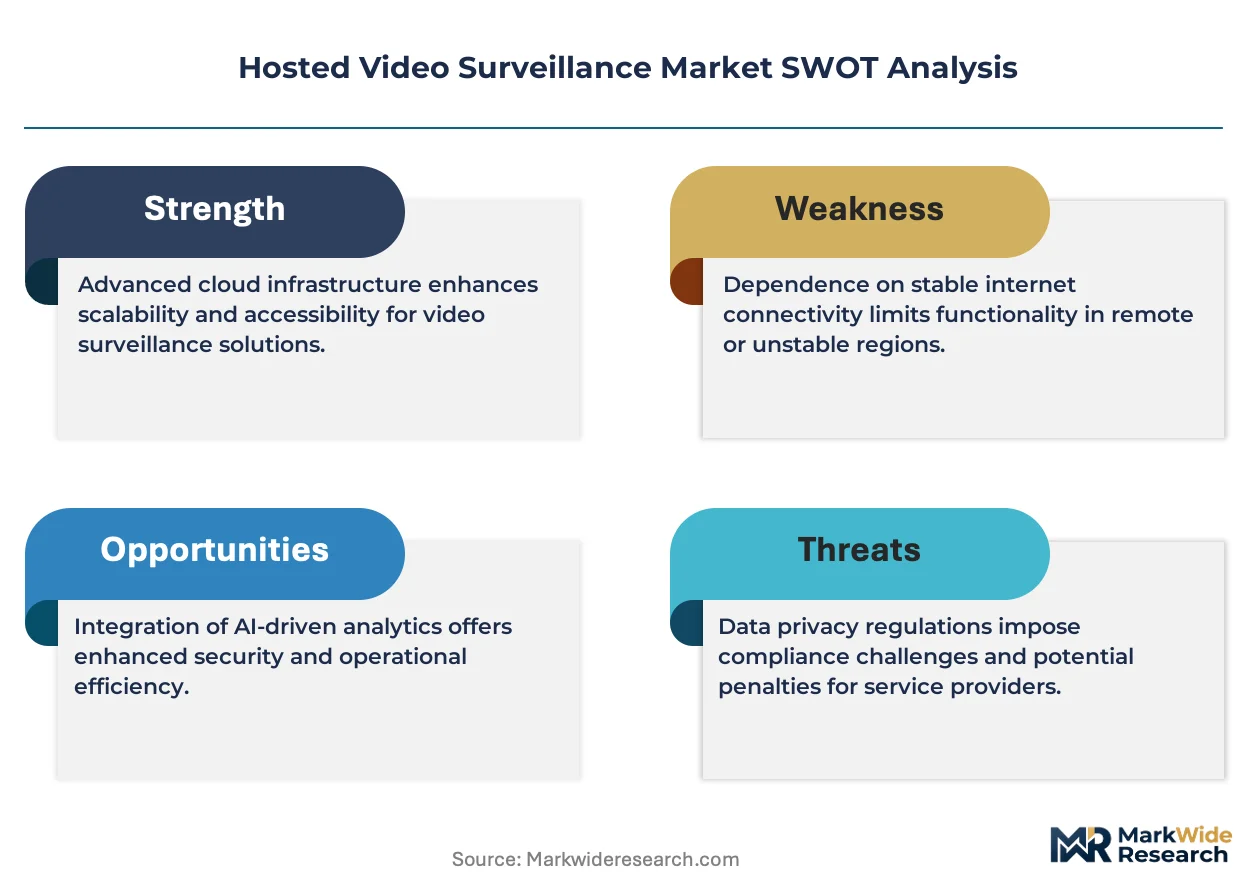
The pool of certified cybersecurity engineers with cloud video architecture expertise is collapsing across North America and Western Europe, creating a bottleneck that slows enterprise deployment timelines. Axis Communications AB leverages its Nordic R&D base to sustain deep competency in edge-to-cloud encryption protocols. Honeywell International Inc. anchors its position through backward integration into building management systems that bundle surveillance with HVAC and access control. Bosch Security Systems differentiates via its in-house manufacturing of IP cameras and video analytics chipsets.
Hosted video surveillance delivers remotely managed video capture, storage, and analytics through cloud infrastructure, typically processing 1080p to 4K resolution streams with AI-enabled object detection at the edge or in centralized data centers. The primary commercial purpose centers on reducing capital expenditure for security infrastructure while enabling real-time threat response across distributed facilities. Cloud-based service deployments now dominate new installations as organizations abandon on-premises server maintenance, while multi-tenant architectures capture the mid-market by pooling infrastructure costs across multiple clients. IP Cameras and Video Management Systems constitute the mature revenue base, though Analytics Software represents the fastest-expanding margin pool as behavioral recognition and predictive alerting command premium pricing.
FCC guidelines on broadband reliability and data transmission standards shape baseline connectivity expectations for cloud video delivery in the United States, while GDPR and the EU AI Act in Europe impose strict limitations on facial recognition retention and automated decision-making transparency. Japan's METI promotes edge computing standards that accelerate domestic adoption of low-latency video processing. Stakeholders must weigh regulatory fragmentation against the operational efficiency gains of unified cloud platforms when selecting deployment architectures and geographic expansion priorities.
Market Dynamics
Enterprise abandonment of on-premises NVR infrastructure is compressing hardware replacement cycles and forcing vendors to rearchitect around cloud-native video pipelines. This shift concentrates purchasing power among hyperscale platform operators while marginalizing traditional security integrators.
Growth Catalysts
- EU AI Act compliance mandates:Facial recognition deployment restrictions in public spaces are accelerating demand for privacy-preserving edge analytics that process biometric data locally.
- Retail chain cloud migration:Multi-location operators are consolidating surveillance operations onto single-tenant cloud platforms to eliminate branch-level server maintenance.
- 4K stream compression advances:H.265 and AV1 codecs are reducing bandwidth requirements for high-resolution video transmission over standard broadband connections.
Market Restraints
- Semiconductor supply concentration:IP camera SoC fabrication depends on a limited number of Taiwanese and South Korean foundries, creating vulnerability to geopolitical disruption.
- GDPR data localization requirements:Cross-border video storage restrictions force redundant infrastructure deployment across European member states.
- Cellular bandwidth cost structure:4G/5G data plans for mobile surveillance deployments remain prohibitively expensive for continuous streaming applications.
Strategic Opportunities
- German industrial facility modernization:Factory automation investments are creating demand for video analytics integrated with robotic safety systems.
- Japan METI edge computing standards:Low-latency processing requirements are opening domestic markets for localized AI inference hardware.
- Subscription-based channel models:Managed service providers are capturing mid-market accounts through bundled hardware-software monthly pricing.
Industry Challenges
- Cloud architecture certification scarcity:The shortage of engineers credentialed in AWS and Azure video pipelines is extending deployment timelines by 4-8 weeks.
- Legacy analog infrastructure integration:Hybrid environments requiring coax-to-IP bridge devices introduce latency and maintenance complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hosted Video Surveillance Market |
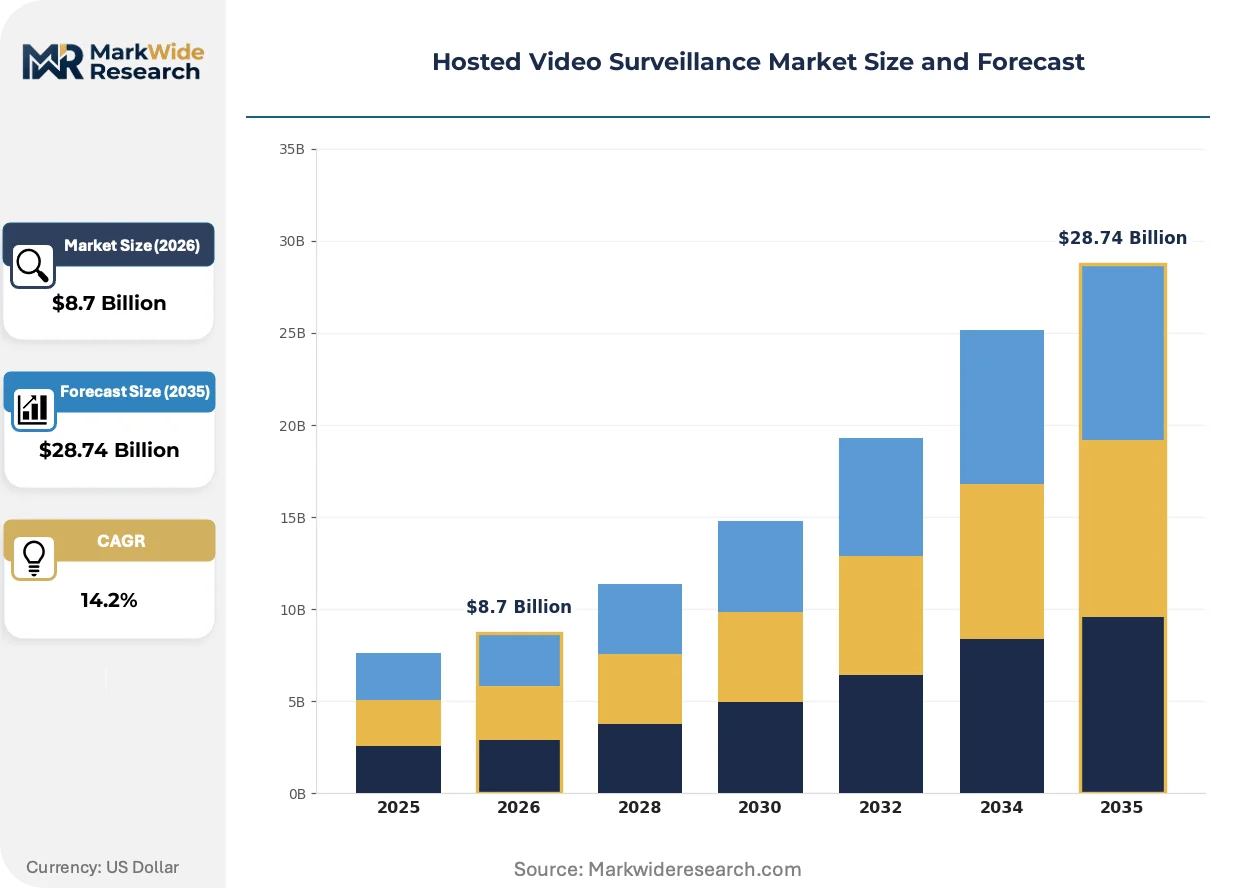
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cloud-based, On-premises, Hybrid, Managed Services Deployment Model: Public Cloud, Private Cloud, Multi-tenant, Single-tenant End User: Retail, Transportation, Hospitality, Healthcare Technology: IP Cameras, Analytics Software, Video Management Systems, Edge Computing |
| Companies Covered | Hangzhou Hikvision Digital Technology Co., Ltd., Dahua Technology Co., Ltd., Axis Communications AB, Honeywell International Inc., Motorola Solutions, Inc., Hanwha Techwin Co., Ltd., Bosch Security Systems, Teledyne FLIR LLC, Avigilon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hosted Video Surveillance Market Emerging Trajectories
Edge AI inference is redistributing computational load away from centralized data centers toward camera-mounted processors. This architectural inversion is reshaping hardware specifications, network topology requirements, and vendor competitive positioning simultaneously.
On-device neural processing units are displacing server-based video analytics for real-time object detection and behavioral recognition. Large retail and logistics operators are deploying these systems at scale to eliminate round-trip latency for theft prevention alerts. The shift is compressing margins for traditional VMS software vendors while elevating camera manufacturers with proprietary silicon capabilities.
GDPR Article 35 data protection impact assessments and the EU AI Act's risk classification framework are mandating algorithmic transparency documentation for automated surveillance systems. Vendors must now provide technical files demonstrating bias testing and human oversight protocols. European public sector procurement is increasingly favoring suppliers with pre-certified compliance packages over those requiring custom assessment.
Security operations centers are unbundling hardware procurement from monitoring services, with enterprise buyers directly sourcing cameras and cloud storage while contracting monitoring separately. This disintermediation is eroding the traditional integrator model in the United States and Germany. Mid-market buyers in particular are adopting self-configuration tools and direct-to-manufacturer purchasing channels previously reserved for large accounts.
Hosted Video Surveillance Market Segmentation
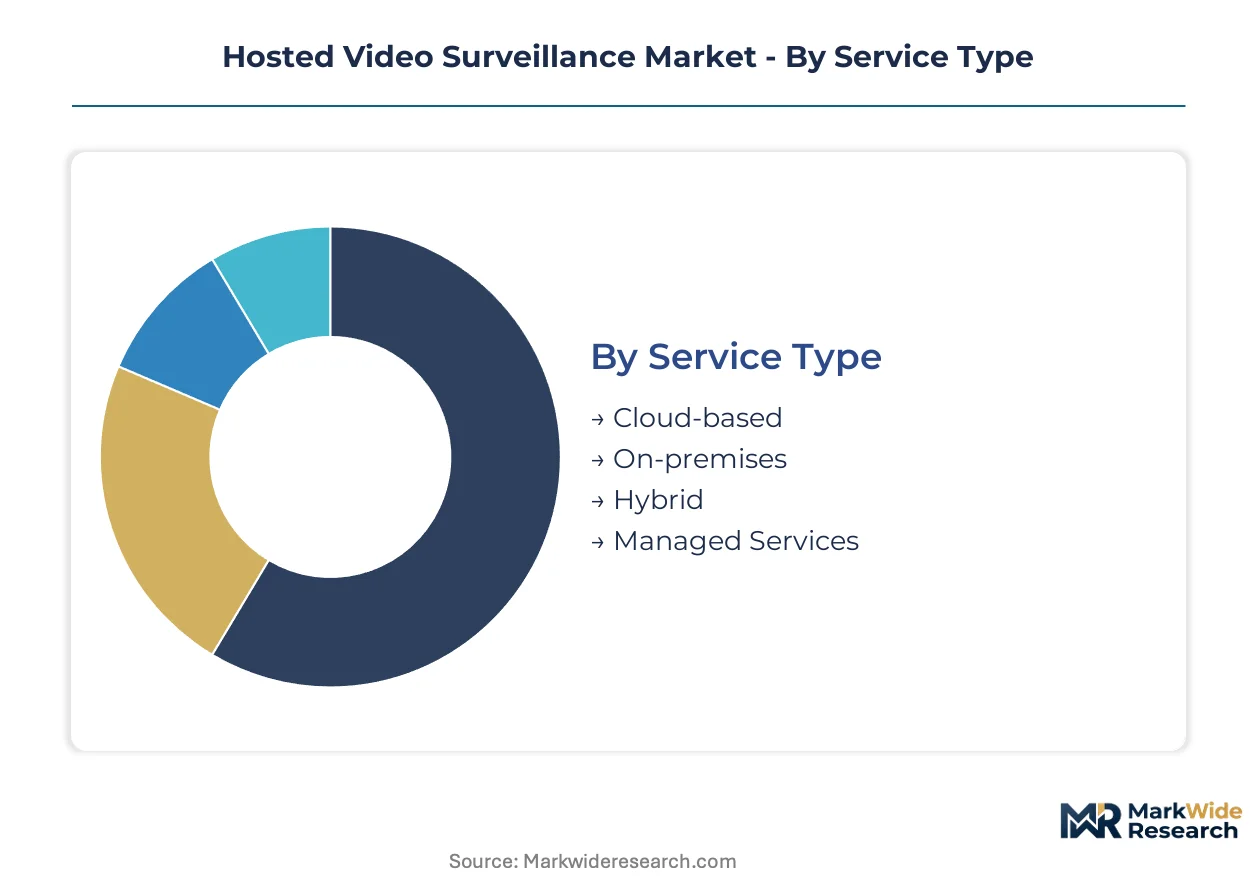
Segmentation reveals how architectural choices and deployment contexts reshape competitive dynamics across the hosted video surveillance landscape. Each dimension carries distinct substitution pressures that determine vendor investment priorities and customer migration patterns.
Service Type:
Cloud-based deployments face the most acute substitution threat from edge-native alternatives that promise lower recurring costs and reduced data egress exposure.
- Cloud-based:Delivers video capture, storage, and analytics through off-premises data centers with centralized management portals. Retail chains across Germany and Japan are consolidating branch operations onto these platforms to eliminate on-site server maintenance and enable unified security policy enforcement.
- On-premises:Retains video processing and storage within facility-controlled infrastructure, typically leveraging existing network-attached storage arrays. Healthcare facilities in the United States continue specifying these deployments to satisfy HIPAA requirements for physical data custody and audit trail control.
- Hybrid:Combines local edge recording with cloud tiering for archival footage and centralized analytics. Transportation authorities favor this architecture for balancing real-time incident response with long-term evidentiary retention.
- Managed Services:Bundles hardware provisioning, software licensing, and 24/7 monitoring under fixed monthly fees. Mid-market hospitality operators are adopting these packages to internalize cybersecurity and firmware update responsibilities.
Cloud-based retains volume leadership; Managed Services holds the steepest expansion curve.
Deployment Model:
Cost tier differentiation separates enterprise-grade isolation from pooled infrastructure economics, with mid-market buyers gravitating toward architectures that minimize per-site overhead.
- Public Cloud:Leverages hyperscale provider infrastructure with shared compute and storage resources across unrelated tenants. Small retail footprints in the United States deploy these instances for rapid provisioning without capital expenditure.
- Private Cloud:Dedicated infrastructure environments provisioned for single-organization exclusive use, often within sovereign data center boundaries. German industrial facilities specify these deployments to satisfy GDPR data localization mandates and prevent cross-border transfer restrictions.
- Multi-tenant:Software architectures that partition logical tenant separation atop shared hardware stacks, spreading infrastructure costs across numerous clients. Regional security service providers utilize this model to serve distributed franchise networks with standardized feature sets.
- Single-tenant:Isolated software instances with dedicated database and compute resources per customer. Large Japanese logistics operators demand these configurations for predictable performance during high-throughput analytics processing.
Multi-tenant captures the broadest addressable base; Single-tenant commands the highest average contract values.
End User:
Application-specific compliance burdens and operational tempo requirements fragment vendor go-to-market strategies across vertical contexts.
- Retail:Multi-location chains require synchronized video analytics across hundreds of endpoints with centralized loss prevention dashboards. Cloud migration accelerates as operators replace aging DVR infrastructure with subscription-based platforms.
- Transportation:Airports, rail networks, and fleet operators demand low-latency edge processing for passenger safety and traffic flow optimization. H.265 compression adoption reduces bandwidth costs for continuous mobile video transmission.
- Hospitality:Hotels and resorts balance guest privacy expectations with liability coverage requirements for common area monitoring. GDPR Article 35 impact assessments increasingly shape procurement criteria for European properties.
- Healthcare:Hospitals and clinics enforce strict access controls over video archives containing patient-identifiable footage. The United States HIPAA Security Rule mandates encryption standards that favor vendors with healthcare-specific compliance certifications.
Retail generates the highest camera density per site; Healthcare imposes the most stringent data governance requirements.
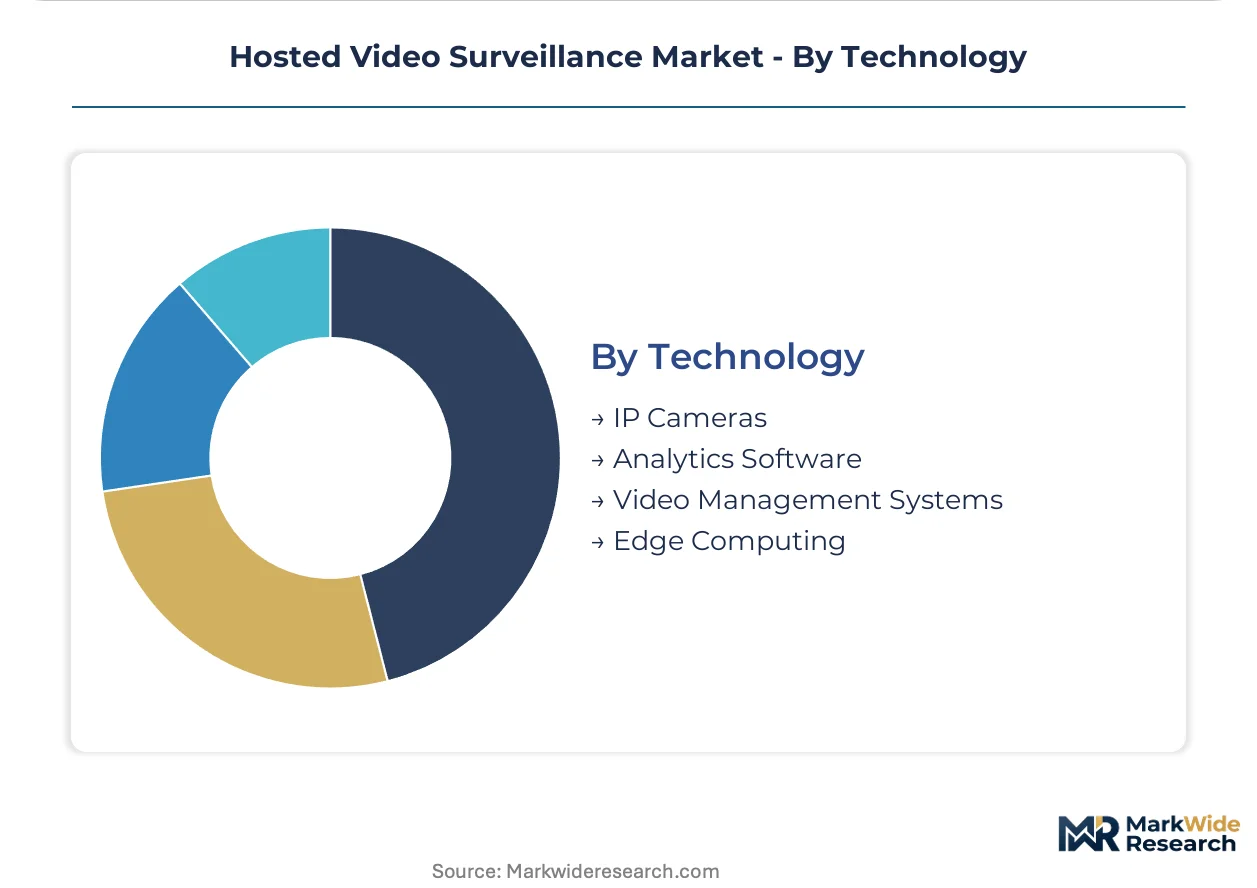
Technology:
Margin concentration follows silicon capabilities and software differentiation, with hardware commoditization pressuring camera vendors to develop proprietary analytics stacks.
- IP Cameras:Network-connected capture devices supporting 1080p to 4K resolution with Power-over-Ethernet connectivity. On-device neural processing units from Ambarella and Intel are displacing server-dependent analytics for real-time object detection.
- Analytics Software:AI-enabled modules for behavioral recognition, predictive alerting, and automated incident classification. Behavioral recognition commands premium pricing in retail loss prevention and perimeter security applications.
- Video Management Systems:Centralized platforms for live viewing, playback, and system health monitoring across distributed camera estates. Open-platform architectures face margin compression as native cloud alternatives eliminate on-premises licensing.
- Edge Computing:Localized processing hardware that executes AI inference at the camera or gateway level without round-trip to centralized data centers. Japan's METI edge computing standards accelerate domestic certification requirements for low-latency deployments.
IP Cameras retain volume leadership; Analytics Software holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC guidelines on broadband reliability and data transmission standards shape baseline connectivity expectations for cloud video delivery in the United States, while GDPR and the EU AI Act impose strict limitations on facial recognition retention across European markets.
United States
Enterprise abandonment of on-premises NVR infrastructure and retail chain consolidation are accelerating cloud migration. HIPAA Security Rule mandates encryption standards that favor vendors with healthcare-specific compliance certifications. Security operations centers in the Northeast Corridor are unbundling hardware procurement from monitoring services.
Germany
Industrial facility modernization and factory automation investments are creating demand for video analytics integrated with robotic safety systems. GDPR data localization requirements force redundant infrastructure deployment across member states. Manufacturing clusters in Bavaria and Baden-Württemberg specify private cloud deployments to satisfy cross-border transfer restrictions.
Japan
METI edge computing standards are accelerating domestic adoption of low-latency video processing for transportation and logistics applications. Low-latency processing requirements are opening domestic markets for localized AI inference hardware. Large logistics operators in the Kanto region demand single-tenant configurations for predictable analytics performance.
United Kingdom
Mid-market hospitality operators are adopting managed service packages to internalize cybersecurity responsibilities. GDPR Article 35 data protection impact assessments increasingly shape procurement criteria for surveillance systems. London-based financial services firms are consolidating distributed camera estates onto unified cloud platforms.
India
Smart city initiatives and transportation infrastructure expansion are driving demand for hybrid architectures balancing real-time response with archival retention. BIS certification requirements for electronic security products are elevating compliance barriers for imported equipment. Industrial corridors in Maharashtra and Gujarat are deploying edge-native systems to reduce recurring cloud costs.
Hosted Video Surveillance Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier that concentrates on vertical applications or regional service delivery. The upper tier commands pricing power through bundled hardware-software offerings and compliance certification packages. Three archetypes dominate: silicon-integrated camera manufacturers, hyperscale cloud platform operators, and building systems integrators with captive surveillance divisions. Competitive moves center on backward integration into semiconductor design and geographic expansion through managed service provider partnerships.
Within the integrated hardware tier, Hangzhou Hikvision Digital Technology Co., Ltd. and Dahua Technology Co., Ltd. exemplify the scale-driven manufacturing archetype with captive supply of imaging components. Axis Communications AB occupies a position representing the Nordic engineering-focused specialist model with concentrated expertise in encryption protocols.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Dahua Technology Co., Ltd. |
| Axis Communications AB |
| Honeywell International Inc. |
| Motorola Solutions, Inc. |
| Hanwha Techwin Co., Ltd. |
| Bosch Security Systems |
| Teledyne FLIR LLC |
| Avigilon Corporation |
| Others |
Supply Flow & Price Mechanics
Hyperscale cloud infrastructure utilization curves determine unit economics across the hosted video surveillance value chain, compressing price floors for mid-market multi-tenant deployments while sustaining premium tiers for single-tenant isolation. Taiwanese foundry capacity allocation for camera SoCs and South Korean memory supply shape hardware cost structures that cascade into subscription pricing.
Pricing Analysis
United States-Germany price spreads reflect divergent compliance cost absorption, with EU AI Act documentation requirements adding certification premiums to European deployments. Three-tier pricing structure across premium, standard, and economy levels segments by edge AI capability and data residency guarantees. Cost compression in standard tiers intensifies as Ambarella and Intel NPU commoditization erodes hardware differentiation. Mid-market hospitality operators exhibit highest price sensitivity; German industrial facilities demonstrate lowest.
Supply Chain Analysis
Inventory buffers for IP camera SoCs stretched to 16-20 weeks following foundry allocation shifts, exposing downstream vulnerability to demand spikes. Fabrication concentrates in Taiwan and South Korea; final assembly clusters in China and Vietnam. Image sensor supply draws from Sony and Omnivision production networks. Single-source vulnerability in 7nm edge AI chip production threatens tier-1 vendor roadmaps. Distribution runs through authorized security integrators and direct-to-manufacturer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise deployment timelines extend 4-8 weeks due to acute scarcity of AWS and Azure video pipeline certified engineers, creating competitive advantage for vendors with captive implementation teams. This capability gap rewards backward integration into professional services and training infrastructure.
For Market Incumbents: Fortify cloud-native architecture investments to defend against edge-native substitution threatening multi-tenant revenue pools. Accelerate in-house NPU development to escape Ambarella dependency. Pursue GDPR pre-certification packages to capture European public sector procurement preference. For New Entrants and Emerging Players: BIS fast-track certification for Indian smart city tenders creates immediate white-space access. Target mid-market managed services in United Kingdom hospitality where cybersecurity bundling commands premium positioning. Lead with self-configuration tools to bypass traditional integrator gatekeeping. For Investors and Strategic Acquirers: Nordic encryption-specialist engineering teams represent priority acquisition archetypes given collapsing North American and Western Europe talent pools. Long-term viability hinges on silicon-software integration depth rather than pure hardware scale. Monitor edge AI inference latency benchmarks as inflection signal for architectural winners.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Chip Development | On-device NPU integration reduces hyperscale dependency for Axis Communications and Bosch. |
| GDPR Pre-Certification Investment | Algorithmic transparency documentation accelerates German industrial facility procurement cycles. |
| Managed Service Provider Partnership | Monthly hardware-software bundling captures mid-market accounts from traditional integrators. |
| Cloud-Native Pipeline Migration | AWS and Azure video architecture expertise compresses enterprise deployment timelines. |
| Backward Integration into SoC Design | Captive silicon capabilities elevate Hanwha Techwin and Hikvision margin structures. |
Methodological Framework
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings. Security operations center directors, cloud platform engineers, and European data protection officers provided deployment timeline and compliance cost data. Secondary sources included FCC broadband reliability guidelines, EU AI Act technical documentation requirements, and METI edge computing standards. Bottom-up camera shipment analysis and top-down cloud infrastructure spend estimates were reconciled.
Sensitivity analysis tested forecast robustness across bandwidth cost scenarios and foundry capacity assumptions. The projection framework models service type, deployment model, end-user vertical, and technology stack dimensions. CAGRs were derived from segment-level growth rate reconciliation. Edge AI inference adoption curves and H.265 compression penetration served as industry-specific demand drivers.
Underlying assumptions cover broadband reliability maintenance and foundry allocation stability, with deviation risk concentrated in geopolitical disruption to Taiwanese semiconductor supply. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Middle East and Africa Surveillance Analog Camera Market
Video Surveillance Systems
Global Night Vision System and Driver Monitoring System Market
Video Surveillance Systems
Europe Surveillance Camera Market
Video Surveillance Systems
Gunshot Detection System Market
Video Surveillance Systems
North America Crawler Camera System Market
Video Surveillance Systems
Video Surveillance Software Market
Video Surveillance Systems
Asia-Pacific Video Surveillance Systems Market
Video Surveillance Systems
Mexico Surveillance Analog Camera Market
Video Surveillance Systems
Middle East and Africa Surveillance IP Cameras Market
Video Surveillance Systems
Security and Surveillance Storage Market
Video Surveillance Systems
Wearable and Body-Worn Cameras Market
Video Surveillance Systems
Asia-Pacific Surveillance Analog Camera Market
Video Surveillance Systems
Video Surveillance and Vsaas Market
Video Surveillance Systems
Middle East and Africa Video Surveillance Storage Market
Video Surveillance Systems
Privacy Filters Market
Video Surveillance Systems
Global CCTV Market