
 Europe Video Surveillance Systems Market | 2026-2036
Europe Video Surveillance Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Video Surveillance Systems Market Analysis
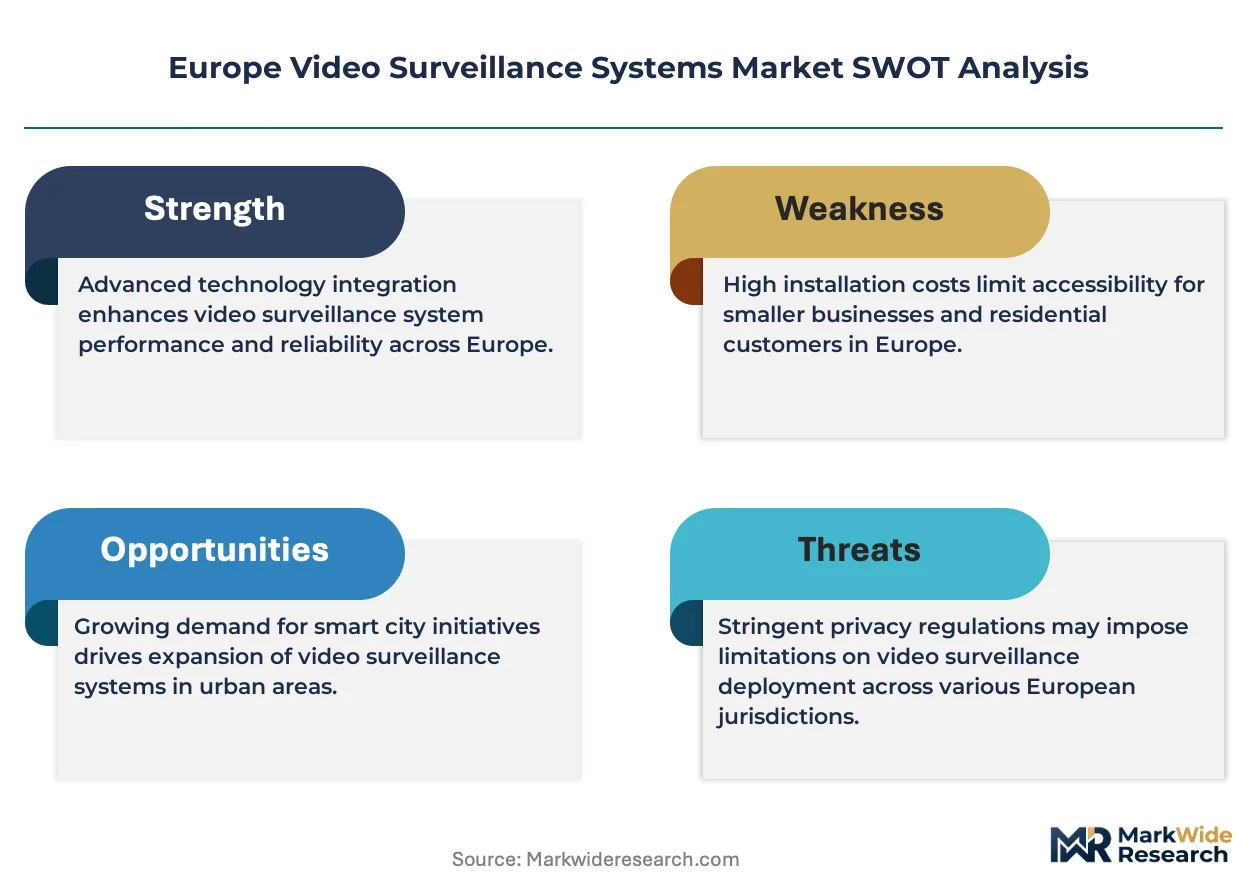
The EU AI Act is pivoting the cost-of-entry calculus for biometric-enabled surveillance across European member states. Axis Communications AB leverages its Nordic engineering heritage to sustain leadership in edge-computing camera architectures. Robert Bosch GmbH anchors its competitive position through deep manufacturing scale in automotive-grade sensor production that extends into security applications. Hanwha Vision Co., Ltd. competes aggressively on price-performance ratios in the IP camera segment while navigating complex CE marking and GDPR compliance requirements.
Video surveillance systems encompass networked camera arrays, video management software, and storage infrastructure designed for real-time monitoring and forensic analysis, typically operating at resolutions from 2MP to 8MP with H.265 compression protocols. These systems serve commercial and governmental entities for asset protection, crowd management, and incident reconstruction. IP Cameras now dominate hardware value pools as analog infrastructure ages out across European installed bases. Cloud-Based technology represents the fastest-expanding architecture as transportation hubs and retail chains shift from on-premise NVRs to subscription-managed platforms. Edge Computing deployments are concentrating margin in specialized chipsets where MOBOTIX AG and Milestone Systems have built defensible positions.
GDPR enforcement by national data protection authorities and the EU AI Act's risk-classification framework are reshaping product certification timelines and biometric feature roadmaps. ETSI standards and CE marking requirements under the EU Radio Equipment Directive govern radio-enabled camera hardware, while the EU Green Deal pressures suppliers to disclose embodied carbon in device manufacturing. Stakeholders must monitor how member-state transpositions of the AI Act create divergent compliance costs that could fragment procurement specifications across Germany, France, and Italy.
Market Dynamics
The EU AI Act's high-risk classification of biometric analytics is compressing product development cycles while elevating compliance costs for system integrators across European member states. Municipal procurement departments in Germany and France are rewriting technical specifications to mandate GDPR-by-design architectures.
Growth Catalysts
- Smart city infrastructure mandates:German and French municipal governments are accelerating procurement of AI-enabled camera networks for traffic management and public safety applications.
- Critical infrastructure protection requirements:Transportation hubs and nuclear facilities in France are driving premium-grade installations with hardened cybersecurity specifications.
- Edge computing chip advancement:Specialized processors are enabling real-time video analytics at the camera level, reducing bandwidth costs and latency for distributed deployments.
Market Restraints
- GDPR enforcement escalation:National data protection authorities in Germany, France, and Italy are imposing substantial fines for biometric data mishandling, extending certification timelines.
- Semiconductor supply concentration:Dependency on East Asian foundries for image sensors and AI accelerators creates vulnerability to trade friction and logistics disruption.
- Legacy analog infrastructure lock-in:Aging coaxial cable installations in Southern European public buildings retard IP migration due to rewiring cost burdens.
Strategic Opportunities
- Eastern European underpenetration:Poland, Romania, and Czechia present whitespace for cloud-managed surveillance platforms as retail chains modernize loss prevention systems.
- EU Green Deal carbon disclosure:Suppliers with verified embodied carbon data in device manufacturing can differentiate in public sector tenders with environmental scoring criteria.
- Healthcare facility surveillance:Patient monitoring and dementia care applications in French and Dutch eldercare institutions represent an emerging vertical with distinct compliance pathways.
Industry Challenges
- AI Act transposition divergence:Member-state implementations creating fragmented procurement specifications across Germany, France, and Italy complicate pan-European product strategies.
- Embedded systems cybersecurity certification:ETSI standards and CE marking under the EU Radio Equipment Directive demand extended testing protocols for radio-enabled hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Video Surveillance Systems Market |
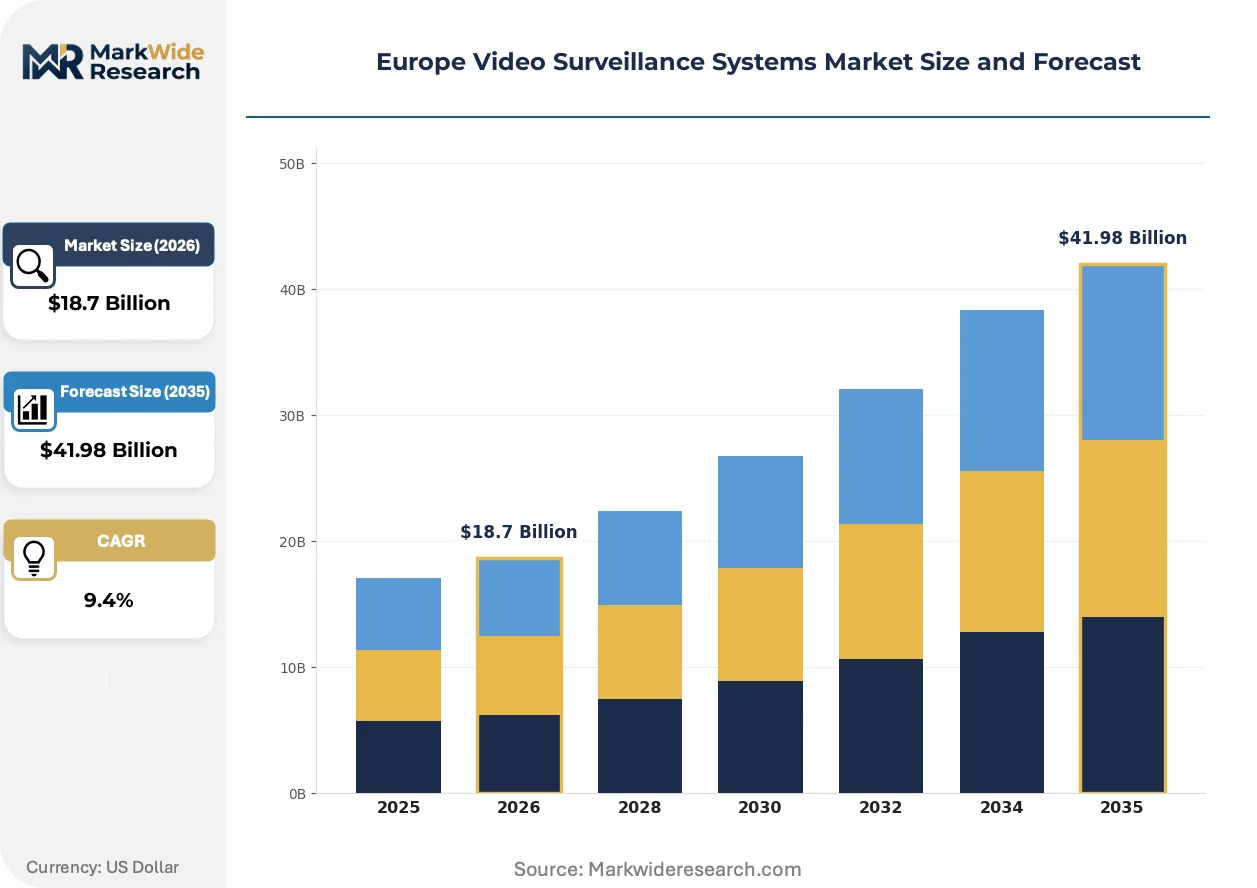
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CCTV Cameras, IP Cameras, PTZ Cameras, Video Analytics Technology: Analog, Digital, Cloud-Based, Edge Computing End User: Retail Stores, Transportation Hubs, Government Buildings, Residential Areas Installation Type: Indoor, Outdoor, Integrated Systems, Do-It-Yourself |
| Companies Covered | Hanwha Vision Co., Ltd., Milestone Systems, Axis Communications AB, ABUS Security Tech Germany, Videotec SpA, Robert Bosch GmbH, MOBOTIX AG, Infinova Corporation, Hangzhou Hikvision Digital Technology Co Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Video Surveillance Systems Market Emerging Trajectories
Three distinct vectors are reshaping European video surveillance architectures: computational migration to network peripheries, regulatory reclassification of biometric capabilities, and procurement model evolution toward subscription platforms.
Edge computing is expanding into camera hardware as specialized chipsets enable on-device AI inference for facial recognition and behavioral analytics. Transportation authorities in the Netherlands and Belgium are deploying these systems at port facilities and rail terminals to reduce backhaul bandwidth requirements. The technology is compressing value capture toward semiconductor suppliers and firmware developers while marginalizing traditional NVR vendors.
The EU AI Act's risk-based classification framework is forcing redesigns of biometric analytics pipelines before the compliance deadline. System integrators must now document algorithmic transparency and human oversight protocols for law enforcement and border control deployments. French critical infrastructure operators are most affected, requiring third-party conformity assessments that extend procurement cycles by several quarters.
Buyer preferences are rotating toward cloud-native video management platforms that replace capital-intensive on-premise servers with operational expenditure models. Retail chains in Germany and Scandinavia are leading this transition, unbundling hardware acquisition from software licensing and maintenance services. The shift is most visible in mid-market commercial applications where IT departments lack specialized security infrastructure expertise.
Europe Video Surveillance Systems Market Segmentation
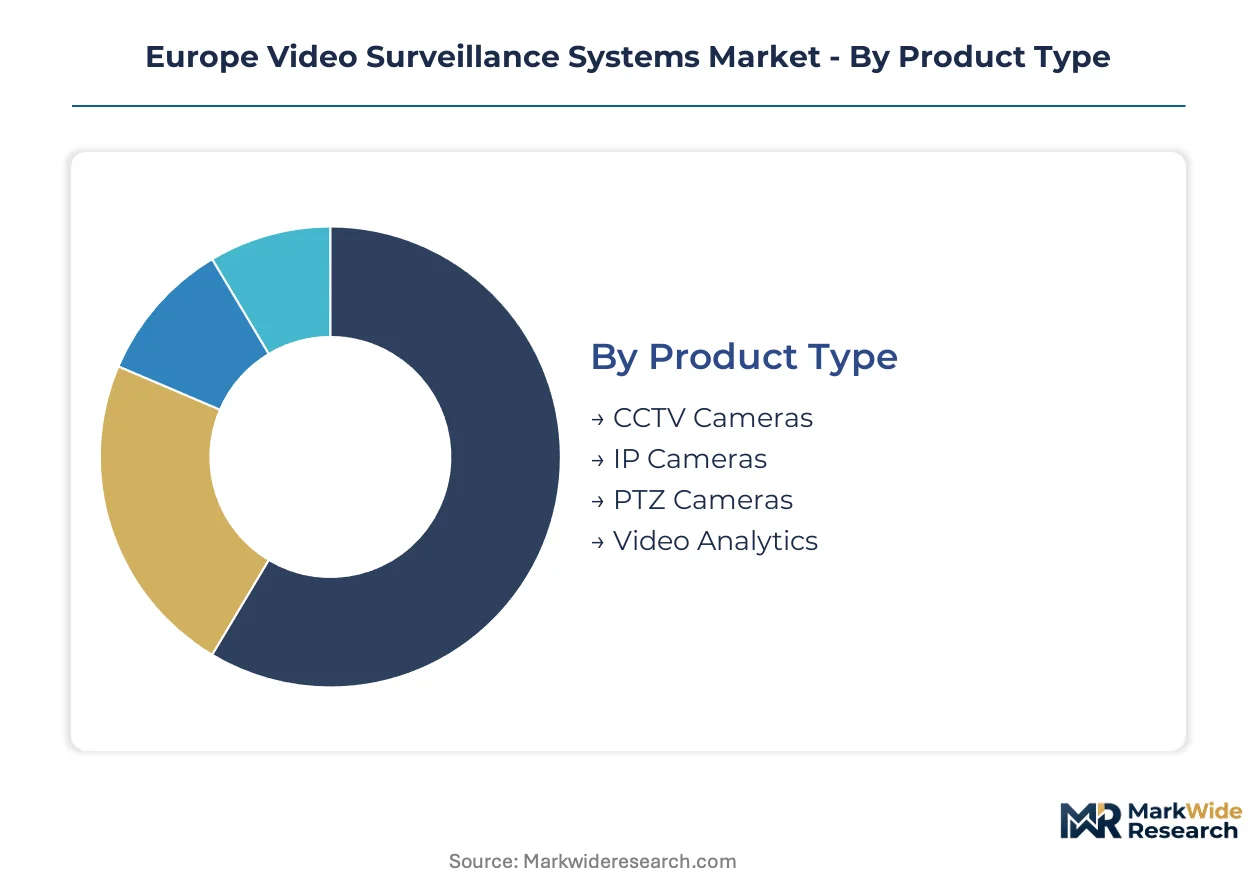
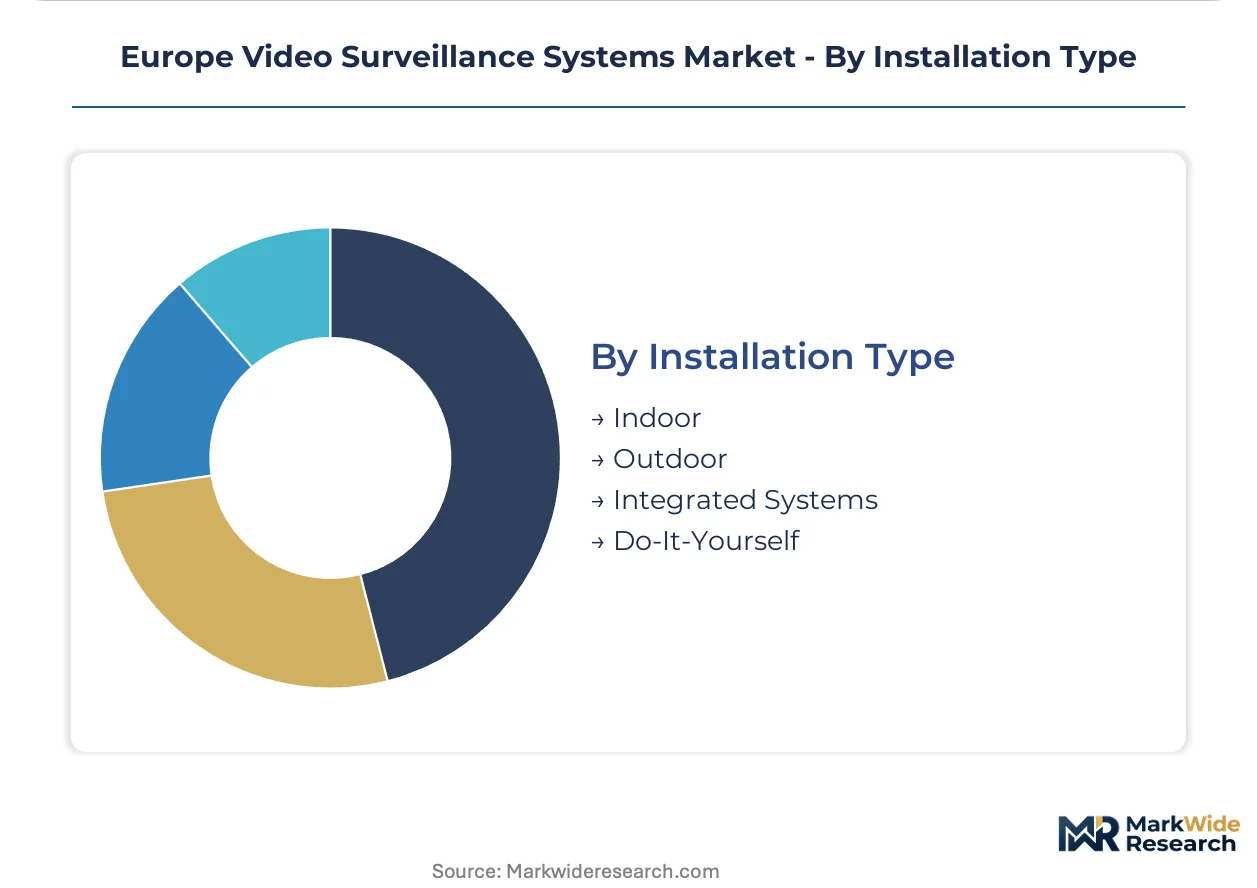
Segmentation in European video surveillance reveals how procurement priorities diverge across compliance regimes and infrastructure maturity. Buyers balance legacy migration costs against AI-enabled feature requirements, with GDPR and the EU AI Act forcing distinct architectural choices in each category.
Product Type:
Customization intensity varies sharply across this category, from commoditized fixed-lens units to application-specific thermal and multi-sensor arrays requiring firmware tailoring.
- IP Cameras:Network-enabled devices with Power-over-Ethernet connectivity and H.265 compression now dominate procurement in German and French municipal tenders. Transportation authorities in the Netherlands specify these for rail terminals requiring encrypted backhaul and remote firmware management under GDPR data minimization mandates.
- CCTV Cameras:Coaxial-based analog infrastructure persists in Southern European public buildings where rewiring costs stall migration. Italian and Spanish facility managers face budget constraints that extend replacement cycles despite end-of-life codec vulnerabilities.
- PTZ Cameras:Pan-tilt-zoom mechanisms with optical zoom ranges serve perimeter monitoring at French nuclear facilities and Belgian port authorities.
- Video Analytics:AI-enabled behavioral detection and facial recognition modules trigger high-risk classification under the EU AI Act, mandating third-party conformity assessments.
Most installed capacity flows through IP Cameras. Expansion is steepest in Video Analytics.
Technology:
Cost tiering separates capital-intensive on-premise architectures from subscription-managed operational expenditure models favored by mid-market retail chains.
- Cloud-Based:Subscription video management platforms with browser-based access and automatic security patching attract German and Scandinavian retail chains lacking in-house IT security expertise. French data localization requirements under GDPR limit multi-tenant deployments, creating demand for sovereign cloud instances.
- Edge Computing:Specialized chipsets enable on-device AI inference, reducing bandwidth costs for distributed Belgian port installations and Dutch smart city deployments. MOBOTIX AG and Milestone Systems capture margin in this firmware-intensive segment.
- Digital:Hybrid NVR-DVR architectures bridge analog legacy and IP migration in Eastern European commercial buildings.
- Analog:End-of-life coaxial infrastructure concentrates in Southern European residential and small commercial installations.
Legacy Digital systems retain the largest installed base. Cloud-Based platforms are climbing the fastest as procurement shifts to operational expenditure models.
End User:
Application-specific compliance pathways create divergent certification requirements across verticals, with critical infrastructure demanding hardened cybersecurity specifications absent in residential deployments.
- Transportation Hubs:Rail terminals, airports, and port facilities in France and the Netherlands require IEC 62676-4 compliant video analytics with real-time crowd density monitoring. Belgian authorities specify edge-computing architectures to minimize backhaul latency for automated incident response.
- Government Buildings:Municipal procurement in Germany mandates GDPR-by-design architectures with documented algorithmic transparency for law enforcement deployments. The EU AI Act's high-risk classification extends certification timelines for biometric-enabled access control systems.
- Retail Stores:Loss prevention systems in Polish and Czechia retail chains drive demand for cloud-managed platforms with integrated point-of-sale correlation analytics.
- Residential Areas:Consumer-grade WiFi cameras with mobile app management face limited GDPR enforcement but growing CE marking scrutiny under the EU Radio Equipment Directive.
Transportation Hubs command premium pricing for hardened specifications. Retail Stores are gaining share fastest as Eastern European modernization accelerates.
Installation Type:
Customer type stratification separates enterprise integrator-led deployments from self-install consumer channels, with margin concentration in integrated systems requiring subsystem coordination.
- Outdoor:Weather-sealed housings with IP66+ ratings and integrated heaters serve French nuclear perimeter protection and German autobahn traffic monitoring. ETSI electromagnetic compatibility standards and CE marking under the EU Radio Equipment Directive extend testing protocols for radio-enabled units.
- Integrated Systems:Multi-subsystem deployments combining video, access control, and intrusion detection concentrate in German critical infrastructure and Dutch healthcare facilities. System integrators capture value through unified cybersecurity certification spanning camera, storage, and analytics layers.
- Indoor:Dome and turret form factors with vandal-resistant polycarbonate housings dominate commercial office and retail interiors.
- Do-It-Yourself:Battery-powered wire-free cameras with cloud storage subscriptions penetrate residential markets in the UK and Scandinavia.
Outdoor specifications anchor the value pool for hardened infrastructure. Integrated Systems are expanding most quickly as cybersecurity convergence demands unified architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Video surveillance manufacturing traces its European lineage to German engineering clusters that pioneered industrial camera systems in the late twentieth century. Today, procurement patterns diverge sharply across member states as GDPR enforcement and the EU AI Act create uneven compliance landscapes. National data protection authorities in Berlin, Paris, and Rome now shape deployment timelines more than technology availability.
Germany
Smart city infrastructure in Berlin and Hamburg drives municipal procurement of AI-enabled traffic monitoring networks. The Federal Data Protection Authority enforces GDPR biometric restrictions that extend certification cycles for facial recognition deployments. Bavaria's industrial corridor hosts system integrators specializing in automotive-grade sensor adaptation for security applications.
France
Critical infrastructure protection at nuclear facilities and Charles de Gaulle Airport sustains premium-grade installation demand with hardened cybersecurity specifications. CNIL, the national data protection commission, mandates algorithmic transparency documentation for law enforcement camera networks. The Île-de-France region concentrates edge-computing deployments at rail terminals requiring real-time crowd analytics.
United Kingdom
Transportation hubs in London and Manchester are migrating from on-premise NVRs to cloud-managed platforms with subscription pricing models. The Information Commissioner's Office enforces GDPR-derived biometric consent protocols that complicate retail loss prevention deployments. Southeast England hosts cybersecurity certification laboratories testing radio-enabled camera hardware under ETSI electromagnetic compatibility standards.
Netherlands
Port authorities in Rotterdam deploy edge-computing architectures to minimize backhaul latency for automated incident response at container terminals. The Dutch Data Protection Authority scrutinizes cloud storage arrangements for cross-border data flows under GDPR localization requirements. Eindhoven's semiconductor ecosystem supplies specialized chipsets enabling on-device AI inference for behavioral analytics.
Poland
Retail chains in Warsaw and Kraków drive whitespace demand for cloud-managed surveillance platforms modernizing loss prevention systems. The Personal Data Protection Office aligns enforcement with EU AI Act transpositions still pending final parliamentary approval. Silesia's manufacturing belt attracts assembly investment serving Eastern European price-sensitive procurement segments.
Europe Video Surveillance Systems Market Vendor Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive sensor manufacturing capabilities. Nordic engineering heritage sustains premium positioning in edge-computing architectures, while East Asian electronics groups compete aggressively on price-performance ratios in standardized IP camera segments. Three archetypes dominate: automotive-grade sensor specialists, firmware-intensive edge computing developers, and cloud-native platform operators. Consolidation pressure is concentrating procurement relationships around vertically integrated suppliers, while regulatory compliance costs are forcing smaller integrators toward niche vertical specialization.
Among Nordic-origin specialists, Axis Communications AB exemplifies the engineering-intensive archetype with sustained investment in network camera architectures. German industrial conglomerate Robert Bosch GmbH anchors the diversified manufacturing tier, leveraging automotive sensor production scale that extends into security applications. Korean electronics group Hanwha Vision Co., Ltd. occupies the volume-competitive position, navigating CE marking and GDPR requirements while driving price-performance optimization in the IP camera segment.
| Leading Market Players |
|---|
| Hanwha Vision Co., Ltd. |
| Milestone Systems |
| Axis Communications AB |
| ABUS Security Tech Germany |
| Videotec SpA |
| Robert Bosch GmbH |
| MOBOTIX AG |
| Infinova Corporation |
| Hangzhou Hikvision Digital Technology Co Ltd |
| Others |
Supply Flow & Price Mechanics
EU Green Deal carbon disclosure mandates gate qualified supply and premium-tier pricing access for video surveillance hardware, forcing suppliers to document embodied carbon in device manufacturing before tendering for public sector contracts. Compliance-ready manufacturers capture pricing power in German and French municipal procurement, while uncertified competitors face exclusion from premium infrastructure segments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates European video surveillance procurement, with differentiation driven by cybersecurity certification grade under ETSI standards and geographic delivery cost to Eastern European markets. Pricing pressure stems from Korean electronics groups competing aggressively on price-performance ratios in standardized IP camera segments. Retail chains in Poland and Czechia exhibit highest price sensitivity, while French nuclear facility operators show lowest sensitivity due to hardened specification requirements.
Supply Chain Analysis
Image sensor and AI accelerator supply rests on Taiwanese and South Korean foundries, with Japanese specialty chemical producers anchoring photoresist and advanced packaging materials. German automotive-grade sensor manufacturers and Chinese optics suppliers feed downstream assembly operations. Single-source vulnerability concentrates in EUV lithography equipment for edge-computing chipsets. Distribution runs through system integrators serving German critical infrastructure and Dutch healthcare facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Video Surveillance Systems Market functions as a stable compounder, with regulatory compliance mandates driving steady replacement cycles and premium-tier procurement across member states.
For Market Incumbents: Cement market position by deepening captive production of automotive-grade image sensors and acquiring CE marking certification laboratories to compress product launch timelines. Cloud-native platform operators threaten traditional NVR vendors; backward integration into edge-computing chip design defends margin pools in firmware-intensive segments.
For New Entrants and Emerging Players: Begin with Eastern European retail modernization whitespace, specifically cloud-managed loss prevention platforms for Polish and Czechia retail chains where incumbent presence remains thin. Sovereign cloud instances for French data localization requirements offer a defensible go-to-market angle against multi-tenant competitors.
For Investors and Strategic Acquirers: Roll-up economics work for specialized edge-computing firmware developers because EU AI Act compliance costs are forcing smaller integrators toward niche vertical specialization or exit. Five-to-ten year viability favors vertically integrated suppliers with captive sensor manufacturing. Watch for divergence in member-state AI Act transpositions as fragmentation inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| GDPR-by-Design Architecture Certification | Accelerates municipal procurement approval in Germany and France under Federal Data Protection Authority oversight. |
| Edge Computing Chipset Development | Captures margin in behavioral analytics firmware where MOBOTIX AG and Milestone Systems hold defensible positions. |
| Sovereign Cloud Platform Launch | Addresses French data localization requirements under GDPR that restrict multi-tenant deployments. |
| Eastern European Distribution Expansion | Targets whitespace demand in Polish and Czechia retail chains modernizing loss prevention systems. |
| Embodied Carbon Disclosure Program | Unlocks premium-tier access to EU Green Deal-scored public tenders with environmental criteria. |
Methodological Framework
Direct dialogue with system integration specialists, municipal procurement officers, data protection compliance consultants, and semiconductor supply managers grounded qualitative findings, cross-referenced with customs trade data, SEC filings from diversified industrial conglomerates, ETSI standards documentation, and national data protection authority enforcement records. Bottom-up demand modeling triangulated against top-down market sizing across hardware, software, and services value pools.
Segment-level revenue outputs trace product type, technology architecture, end-use vertical, and installation complexity across the projection horizon. CAGRs derive from regression analysis of historical municipal procurement cycles, IP migration patterns from analog infrastructure, and cloud platform subscription growth trajectories. Edge computing deployment density and AI Act compliance cost pass-through assumptions inform margin trajectory modeling.
Several conditions sit outside the modeled scope, including potential trade friction disruptions to East Asian foundry supply, member-state AI Act transposition delays, and unanticipated GDPR enforcement escalations. Forecasts embed documented assumptions about semiconductor availability and regulatory timeline adherence. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
United Kingdom Surveillance Camera Market
Video Surveillance Systems
Night Vision Outdoor Camera Market
Video Surveillance Systems
Canada Surveillance Camera Market
Video Surveillance Systems
United Kingdom Surveillance IP Camera Market
Video Surveillance Systems
Italy Video Surveillance Market
Video Surveillance Systems
Mexico Surveillance IP Camera Market
Video Surveillance Systems
Inspection Camera System Market
Video Surveillance Systems
Asia-Pacific Video Surveillance Systems Market
Video Surveillance Systems
Mexico Surveillance Analog Camera Market
Video Surveillance Systems
In-Vehicle Video Surveillance Market
Video Surveillance Systems
Middle East and Africa Video Surveillance Market
Video Surveillance Systems
North America Video Surveillance Systems Market
Video Surveillance Systems
China Video Surveillance Market
Video Surveillance Systems
France Surveillance Analog Camera Market
Video Surveillance Systems
Connected Enterprise Video Surveillance Solutions Market
Video Surveillance Systems
Europe Surveillance IP Camera Market