
 Global CCTV Market | 2026-2036
Global CCTV Market Size, Share, and Industry Trends Forecast 2026-2036
Global CCTV Market Analysis
ISO/IEC 27001 certification is unwinding competitive access across enterprise and government procurement channels, favoring vendors with verified information security management systems. Hikvision Digital Technology Co., Ltd. leverages vertical integration across sensor design and video analytics firmware to sustain cost leadership in IP camera volumes. Axis Communications AB differentiates through open-platform architecture that anchors premium positioning in banking and critical infrastructure verticals.
Closed-circuit television (CCTV) denotes a private video surveillance system where cameras transmit signals to designated monitors, recorders, or network video recorders through coaxial cable, fiber optic, or encrypted IP protocols, typically operating at resolutions from 1080p to 4K with frame rates between 15 and 30 fps for forensic-grade evidence capture. Its primary commercial purpose centers on real-time situational awareness, post-incident investigation support, and automated threat detection for asset protection and public safety. Dome cameras and PTZ cameras concentrate margin pools in transportation hubs and casino environments where 360-degree coverage and operator-driven tracking justify premium pricing. IP technology leads unit economics as Power-over-Ethernet deployments reduce cabling costs, while wireless installations remain nascent outside temporary event security and remote construction sites.
The EU AI Act and GDPR constrain biometric analytics deployment across member states, forcing manufacturers to segment product lines between privacy-compliant jurisdictions and unrestricted markets. China's GB standards and MIIT cybersecurity certifications govern domestic procurement, creating divergent compliance pathways for multinational suppliers. India's BIS mandatory certification for electronic products adds a third regulatory layer that shapes factory qualification timelines. Stakeholders must monitor whether convergence toward common encryption and data sovereignty standards will fragment R&D budgets or enable modular platform strategies that span multiple compliance regimes.
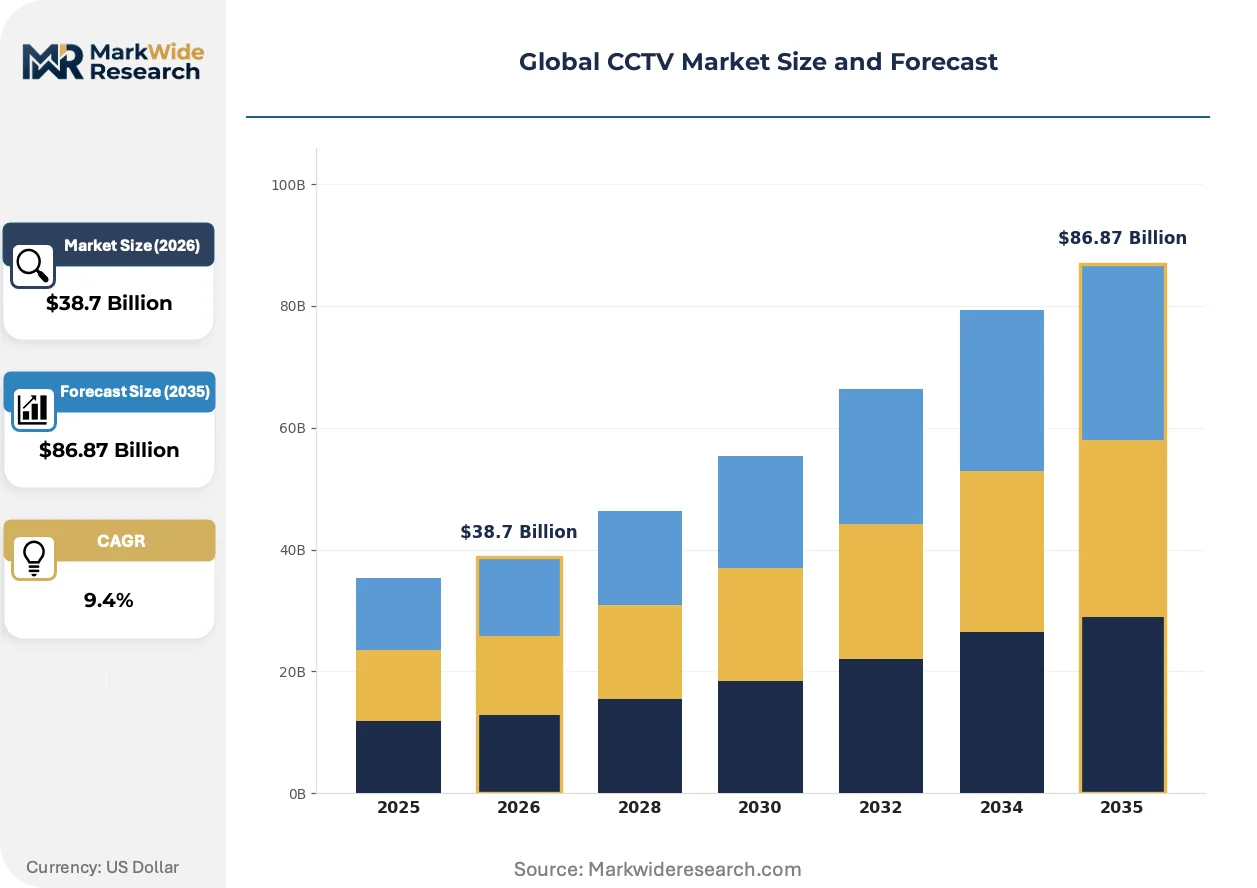
Market Dynamics
The Global CCTV Market pivots on regulatory fragmentation forcing manufacturers to engineer parallel product architectures for divergent compliance regimes across privacy-sensitive jurisdictions.
Growth Catalysts
- Smart city infrastructure mandates:Southeast Asian governments are accelerating networked surveillance procurement for urban traffic management and public safety modernization.
- EU AI Act biometric restrictions:These regulations are compressing R&D cycles as vendors race to deploy privacy-compliant analytics before enforcement deadlines.
- Railway safety investments:India's dedicated freight corridors and metro expansions are generating sustained demand for platform monitoring and intrusion detection systems.
Market Restraints
- Image sensor supply concentration:CMOS sensor fabrication concentrates among a handful of East Asian foundries, exposing procurement to geopolitical disruption.
- GDPR-EU AI Act compliance layering:Dual regulatory frameworks impose redundant certification costs that compress margins on European-bound product lines.
- Cloud storage substitution:Edge-to-cloud architectures threaten traditional NVR hardware attach rates in enterprise deployments.
Strategic Opportunities
- India BIS certification pipeline:Early factory qualification under India's mandatory electronics standards creates first-mover access to government tenders.
- Edge AI-video analytics convergence:On-device inference chips enable real-time threat detection without network dependency, opening remote infrastructure applications.
- Subscription-based video surveillance-as-a-service:Channel partners in North America are pivoting from hardware resale to recurring revenue managed service models.
Industry Challenges
- ISO/IEC 27001 certification timelines:Enterprise procurement gates now require verified information security management, extending vendor qualification cycles.
- Legacy coaxial infrastructure integration:Hybrid deployments demand engineering resources to bridge analog backbones with IP endpoints.
- Computer vision talent scarcity:Firmware development for embedded analytics competes with broader AI sector hiring, inflating compensation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global CCTV Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bullet Cameras, Dome Cameras, PTZ Cameras, IP Cameras Technology: Analog, HD-TVI, IP, Wireless End User: Retail, Transportation, Banking, Government Installation Type: Indoor, Outdoor, Covert, Remote |
| Companies Covered | Hikvision Digital Technology Co., Ltd., Dahua Technology Co., Ltd., Axis Communications AB, Honeywell International Inc., Bosch Security Systems GmbH, Hanwha Vision Co., Ltd., Motorola Solutions, Inc., Zhejiang Uniview Technologies Co., Ltd., Teledyne FLIR LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global CCTV Market Emerging Trajectories
Computational photography and on-device inference are compressing the traditional hardware-software boundary, while procurement patterns tilt toward integrated security platforms over standalone camera sales.
Multi-spectral imaging is miniaturizing. Sensors capturing visible and near-infrared spectra within single packages now enable 24-hour forensic-grade capture without mechanical filter switching. Critical infrastructure operators in the UAE and Saudi Arabia are standardizing on these unified modules for perimeter defense. The technology is miniaturizing enclosure sizes and reducing power budgets, enabling deployment in thermally constrained desert environments where active cooling fails.
REACH substance restrictions and RoHS recast directives are phasing out specific flame retardants and stabilizers used in cable jacketing and PCB laminates. European manufacturers face reformulation costs or supply base switches to maintain CE marking eligibility. The restrictions hit budget IP camera lines hardest, as premium vendors absorbed compliance costs earlier through proactive material substitution programs.
Consolidated security platform procurement is displacing point-solution buying. Banking and data center operators now issue single-vendor tenders combining access control, video management, and analytics under unified command interfaces. System integrators in Germany and France report compressed hardware margins offset by software licensing and professional services attach. This bundling concentrates vendor relationships and raises switching costs for incumbent equipment suppliers.
Global CCTV Market Segmentation
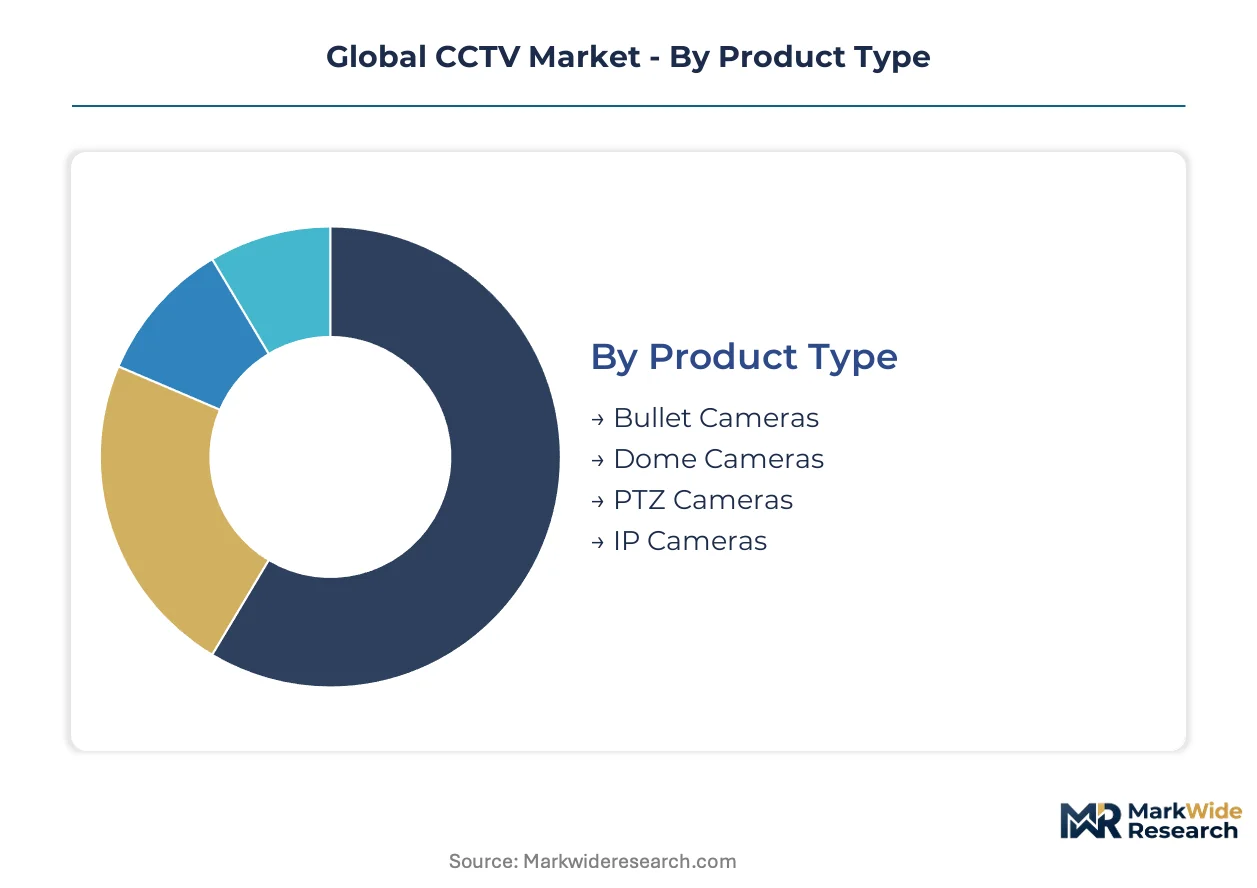
CCTV procurement patterns diverge sharply across deployment contexts, with technology substitution pressures and compliance requirements reshaping segment prioritization. Understanding these fault lines enables vendors to align R&D pipelines with defensible revenue pools.
Product Type:
IP cameras face the most acute substitution pressure as edge-to-cloud architectures and smartphone-based surveillance erode dedicated hardware demand in consumer and small commercial verticals.
- IP Cameras:Network-enabled devices transmit encrypted video over Ethernet or Wi-Fi, supporting Power-over-Ethernet deployment that slashes cabling costs. Demand concentrates in India's railway modernization and smart city tenders where BIS-certified units anchor government procurement. Cybersecurity mandates from EU AI Act and GDPR compliance layers favor vendors with ISO/IEC 27001-verified firmware pipelines.
- Dome Cameras:Vandal-resistant enclosures house fixed or varifocal lenses for 360-degree coverage in high-abuse environments. Transportation hubs in Singapore and casino floors in Macau sustain premium pricing through operator-driven situational awareness requirements. The form factor dominates where aesthetic concealment and mechanical protection outweigh pure image quality specifications.
- Bullet Cameras:Weather-sealed cylindrical housings mount on exterior walls for perimeter surveillance with infrared illumination arrays.
- PTZ Cameras:Motorized pan-tilt-zoom mechanisms enable operator-controlled tracking of moving subjects across wide areas.
IP cameras retain volume leadership; PTZ cameras hold the steepest expansion curve as critical infrastructure operators automate threat response.
Technology:
Cost tier stratification separates legacy infrastructure preservation from greenfield digital deployment, with hybrid migration paths consuming disproportionate engineering resources.
- IP:Digital packet-switched transmission enables 4K resolution, embedded analytics, and seamless VMS integration at the expense of network bandwidth and storage infrastructure. Banking and data center operators in Germany and France mandate IP as baseline for consolidated security platform procurement. Edge AI inference chips are compressing server dependency for real-time analytics.
- Analog:Coaxial-based composite video persists in budget-conscious retrofit scenarios where existing cable plant depreciation cycles delay full replacement. Small retailers and aging municipal systems in Southeast Asian secondary cities extend operational life through DVR hybridization rather than wholesale infrastructure overhaul.
- HD-TVI:High-definition transport video interface delivers 1080p over coaxial cable without IP network dependency.
- Wireless:Radio-frequency transmission eliminates cabling for temporary event security and remote construction site monitoring.
Analog retains installed base dominance in value terms; IP technology climbs the fastest as Power-over-Ethernet deployment economics improve.
End User:
Application-specific compliance burdens fragment vendor qualification requirements, with government and banking verticals imposing the steepest certification barriers to entry.
- Government:Urban policing modernization and national security frameworks drive large-scale networked surveillance with mandatory encryption and data sovereignty provisions. India's railway safety investments and UAE critical infrastructure protection sustain demand for multi-spectral imaging and perimeter analytics. Procurement gates require factory audits and BIS or equivalent cybersecurity certifications.
- Banking:Integrated security platform mandates combine access control, video management, and facial recognition analytics under unified command interfaces. GDPR and EU AI Act biometric restrictions compress R&D cycles as institutions race to deploy privacy-compliant systems before enforcement deadlines.
- Retail:Loss prevention and customer flow analytics dominate deployment decisions with compressed hardware margins.
- Transportation:Platform monitoring and intrusion detection systems for metro expansions and freight corridors generate sustained demand.
Government captures the largest contract values; banking exhibits the most rapid compliance-driven refresh cycles.
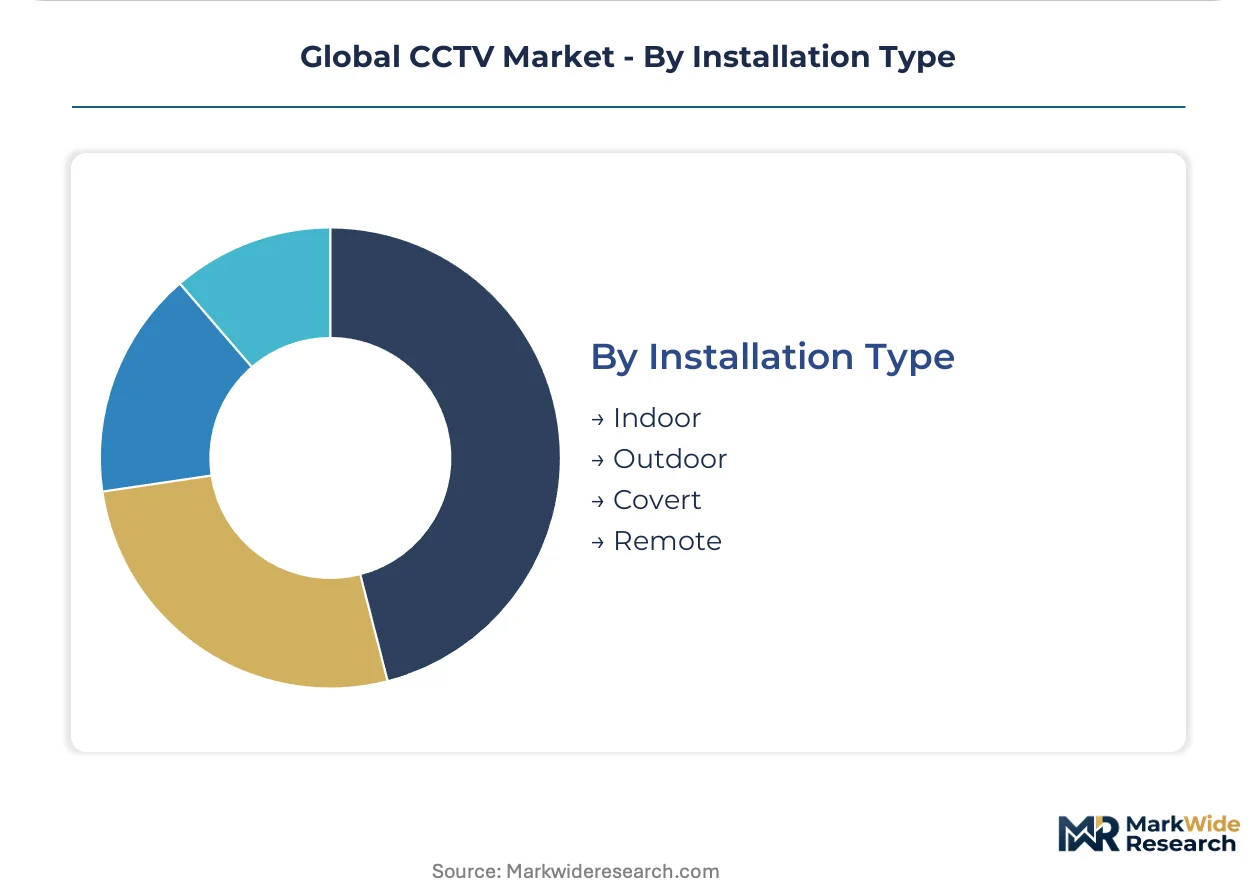
Installation Type:
Environmental exposure severity and concealment requirements determine enclosure engineering priorities and maintenance cost structures.
- Outdoor:IP66/IP67-rated housings with heater-blower assemblies withstand temperature extremes and particulate ingress for perimeter defense and traffic monitoring. Desert deployments in Saudi Arabia and the UAE standardize on thermally efficient multi-spectral modules where active cooling fails.
- Indoor:Controlled environment installations prioritize aesthetic integration and acoustic discretion over weather sealing.
- Covert:Disguised or miniature form factors enable evidence gathering without subject awareness.
- Remote:Solar-powered cellular-connected units serve pipeline monitoring and wildlife tracking beyond grid infrastructure.
Outdoor installations command the highest unit economics; remote deployment is gaining share fastest as cellular bandwidth costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UAE's Khalifa Port expansion and Saudi Arabia's Red Sea coastal development anchor Middle Eastern demand for perimeter surveillance and port security systems. India's Dedicated Freight Corridors and metro rail networks are generating sustained procurement volumes for platform monitoring equipment.
United States
Critical infrastructure protection mandates from the Department of Homeland Security drive demand for cybersecurity-hardened surveillance at power generation and water treatment facilities. The FCC's equipment authorization requirements and NDAA Section 889 procurement restrictions reshape vendor qualification for federal deployments. Data center clusters in Northern Virginia and Dallas-Fort Worth anchor enterprise demand for integrated security platforms combining video management with access control.
China
GB standards and MIIT cybersecurity certifications govern domestic procurement for smart city and railway safety applications, creating divergent compliance pathways from export markets. The national video surveillance network expansion for urban policing sustains volume demand across tier-one and tier-two municipalities. Manufacturing concentration in Hangzhou and Shenzhen supports cost leadership in IP camera production through captive sensor supply and firmware development.
Germany
Banking and automotive verticals mandate GDPR-compliant analytics with privacy-by-design architectures for facial recognition deployments. The EU AI Act's biometric identification restrictions compress R&D cycles as institutions race to deploy compliant systems before enforcement deadlines. Industrial security demand concentrates in Stuttgart and Munich, where manufacturing facilities integrate video analytics with operational technology monitoring.
India
BIS mandatory certification for electronic products creates first-mover advantages for vendors qualifying factories under India's electronics standards. Urban policing modernization and railway safety investments across Mumbai, Delhi, and Bengaluru drive large-scale networked surveillance procurement. Metro rail expansions in Chennai and Hyderabad generate sustained demand for platform monitoring and intrusion detection systems with data sovereignty provisions.
Singapore
Smart nation infrastructure mandates accelerate procurement of AI-enabled traffic management and public safety systems with strict data governance requirements. The Personal Data Protection Act constrains biometric analytics deployment, forcing privacy-compliant product segmentation. Marina Bay and Changi Airport anchor premium demand for dome and PTZ cameras where 360-degree coverage and operator-driven tracking justify higher unit economics.
Global CCTV Market Vendor Landscape
Listed leaders compete with private specialists across cybersecurity certification and vertical integration depth, creating a tiered structure where scale advantages clash with niche customization capabilities. The vendor base fragments across three strategic archetypes: integrated platform providers anchoring banking and critical infrastructure, component-integrated volume manufacturers serving government tenders, and specialist analytics developers targeting edge AI applications. Dominant competitive moves include backward integration into sensor fabrication to secure supply, and strategic partnerships with systems integrators to capture recurring software revenue.
Within the integrated platform tier, Hikvision Digital Technology Co., Ltd. and Axis Communications AB exemplify divergent positioning strategies. Hikvision represents the vertically integrated archetype with in-house production spanning sensor design through video analytics firmware. Axis Communications AB occupies a position emphasizing open-platform architecture for premium banking and critical infrastructure verticals. Dahua Technology Co., Ltd. sits within the volume-manufacturing cluster alongside Zhejiang Uniview Technologies Co., Ltd., both representing Chinese-origin suppliers navigating divergent compliance regimes across privacy-sensitive jurisdictions.
| Leading Market Players |
|---|
| Hikvision Digital Technology Co., Ltd. |
| Dahua Technology Co., Ltd. |
| Axis Communications AB |
| Honeywell International Inc. |
| Bosch Security Systems GmbH |
| Hanwha Vision Co., Ltd. |
| Motorola Solutions, Inc. |
| Zhejiang Uniview Technologies Co., Ltd. |
| Teledyne FLIR LLC |
| Others |
Supply Flow & Price Mechanics
ISO/IEC 27001 certification gates both supply qualification and price differentiation simultaneously, as enterprise procurement channels now require verified information security management systems before contract eligibility, while vendors absorb compliance costs that stratify offerings across certification tiers.
Pricing Analysis
Volume-discount tiering structures anchor government tender economics, with BIS-certified manufacturers in India commanding premium positioning against uncertified competitors. Three-tier pricing structure across premium, standard, and economy levels separates ISO/IEC 27001-verified firmware pipelines from baseline offerings, with cybersecurity-hardened units carrying brand premiums in banking and critical infrastructure. Cost compression in economy IP camera lines intensifies because REACH substance restrictions force reformulation of cable jacketing and PCB laminates. Small retailers and aging municipal systems in Southeast Asian secondary cities exhibit highest price sensitivity, while UAE critical infrastructure operators demonstrate lowest sensitivity due to thermal reliability requirements.
Supply Chain Analysis
Strategic stockpile preferences dominate CMOS sensor procurement as manufacturers buffer against foundry concentration risk in Taiwan and South Korea. Image sensor fabrication draws from East Asian foundries, with cable assemblies and enclosure metals sourcing from China and Vietnam. Single-source vulnerability concentrates in advanced CMOS fabrication nodes, where geopolitical disruption threatens component availability. Distribution runs through systems integrators in Germany and France, with channel partners in North America pivoting toward recurring revenue managed service models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as smartphone-based surveillance and edge-to-cloud architectures erode dedicated hardware demand in consumer and small commercial verticals.
For Market Incumbents: Consolidate firmware development capabilities to anchor differentiated analytics offerings against smartphone-based surveillance encroachment. Deepen backward integration into sensor design to secure supply continuity amid East Asian foundry concentration. Prioritize ISO/IEC 27001 certification investment to maintain enterprise procurement channel access as cybersecurity mandates tighten. For New Entrants and Emerging Players: Differentiate on edge AI-video analytics convergence for remote infrastructure applications beyond grid connectivity. Target India's BIS certification pipeline for first-mover access to railway safety and urban policing tenders. Pursue white-space in solar-powered cellular-connected remote deployments as cellular bandwidth costs decline. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across edge AI inference chip development as on-device processing becomes table stakes. Long-term viability favors vendors with modular platform strategies spanning multiple compliance regimes rather than single-jurisdiction specialists. Watch for convergence toward common encryption standards as inflection indicator for R&D budget efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Fabrication | Secures captive supply continuity against Taiwan and South Korea foundry concentration risk. |
| ISO/IEC 27001 Certification Investment | Unlocks enterprise and government procurement channels requiring verified information security management. |
| Edge AI Inference Chip Development | Enables real-time threat detection without network dependency for remote infrastructure applications. |
| Subscription-Based Surveillance-as-a-Service Pivot | Captures recurring revenue streams as North American channel partners abandon hardware resale models. |
| Multi-Spectral Imaging Module Standardization | Addresses UAE and Saudi Arabia perimeter defense requirements in thermally constrained desert environments. |
Methodological Framework
A standing panel of video management software architects, railway safety procurement officers, casino security directors, and systems integration specialists provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against SEC filings, BIS certification registries, EU AI Act implementation guidance, and smart city tender databases. Bottom-up unit economics triangulated against top-down market sizing across product type, technology, end user, and installation type segmentation.
Consistency checks validated volume and value outputs against hyperscaler capex disclosures for data center security investments and government budget appropriations for railway modernization. The analytical framework modeled IP versus analog technology substitution, dome versus bullet versus PTZ form factor preferences, and indoor versus outdoor installation economics across the projection horizon. CAGRs derived from installed base depreciation cycles and greenfield deployment pipelines, with edge AI adoption curves and regulatory compliance timelines as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained infrastructure investment levels or accelerated EU AI Act enforcement timelines would require recalibration. Forecasts reflect documented assumptions regarding technology substitution rates and certification timeline stability. Revision becomes warranted when CMOS sensor supply disruption or geopolitical tariff escalation crosses operational continuity thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Video Surveillance Market
Video Surveillance Systems
Italy Video Surveillance Market
Video Surveillance Systems
United Kingdom Surveillance Camera Market
Video Surveillance Systems
Latin America Surveillance IP Cameras Market
Video Surveillance Systems
In-Vehicle Video Surveillance Market
Video Surveillance Systems
Security Camera Software Market
Video Surveillance Systems
United Kingdom Surveillance Analog Camera Market
Video Surveillance Systems
Night Vision Outdoor Camera Market
Video Surveillance Systems
3D Surveillance Software Market
Video Surveillance Systems
Canada Surveillance IP Camera Market
Video Surveillance Systems
Video Surveillance and Vsaas Market
Video Surveillance Systems
Farm Video Surveillance System Market
Video Surveillance Systems
France Surveillance Camera Market
Video Surveillance Systems
Concealed Weapon Detection Systems Market
Video Surveillance Systems
Privacy Filters Market
Video Surveillance Systems
Wireless Home Security Camera Market