
 Turkey Third Party Logistics (3PL) Market | 2026-2036
Turkey Third Party Logistics (3PL) Market Size, Share, and Industry Trends Forecast 2026-2036
Turkey Third Party Logistics (3PL) Market Analytics
Shift from captive fleet operations toward outsourced multi-provider networks is pivoting how Turkish manufacturers structure supply chain expenditure. DHL Supply Chain leverages its European network density to anchor cross-border freight consolidation from Istanbul. Arkas Logistics competes through port-centric vertical integration, controlling container handling at Mersin and Izmir terminals. Maersk extends its ocean freight dominance into hinterland distribution, positioning integrated sea-rail offerings for automotive clients.
Turkey Third Party Logistics encompasses transportation management, warehousing operations, inventory control, and value-added services performed by external providers on behalf of shippers, typically governed by service-level agreements specifying delivery windows, inventory accuracy thresholds, and cost-per-unit metrics. The primary commercial purpose centers on converting fixed logistics assets into variable costs while injecting operational expertise that shippers rarely maintain in-house. Transportation and warehousing together absorb the dominant share of contract value, though value-added services command superior margins through specialized handling requirements. E-commerce client types represent the fastest-expanding demand pool, pressuring providers to deploy cloud-based warehouse management systems with real-time inventory visibility.
Turkey's Ministry of Transport and Infrastructure, alongside the Trade Ministry's customs modernization directives, shapes market access through digital border clearance mandates and cold-chain certification standards for pharmaceutical shipments. The country's alignment with EU transport acquis through the Customs Union Technical Committee forces incremental fleet emission compliance and driver hour regulations on domestic operators. Stakeholders must monitor how Istanbul's planned logistics master plan and canal infrastructure alter hinterland routing economics before committing to long-term warehouse leases.
Market Dynamics
Turkish automotive and pharmaceutical manufacturers are accelerating their shift from captive fleet ownership toward outsourced multi-provider logistics networks, compressing contract structures from multi-year fixed commitments toward variable-cost service-level agreements with real-time performance dashboards.
Growth Catalysts
- EU Customs Union Technical Committee alignment:Fleet emission compliance mandates and driver hour regulations are forcing domestic operators toward professionalized 3PL partnerships with certified compliance infrastructure.
- Pharmaceutical cold-chain certification:Turkey's Trade Ministry directives on digital border clearance and temperature-validated pharmaceutical shipments are expanding specialized warehousing demand around Istanbul's industrial corridor.
- Multimodal connectivity at Mersin port:Container handling integration with rail and road hinterland networks is creating competitive distribution advantages for automotive just-in-time delivery providers.
Market Restraints
- Fuel cost volatility:Diesel price fluctuations absorb 35-45% of transportation contract value, compressing margins for asset-heavy operators without fuel surcharge mechanisms.
- Driver shortage concentration:Qualified commercial license holders cluster disproportionately around Istanbul and Izmir, leaving Anatolian interior routes underserved and rates elevated.
- Customs system fragmentation:Partial digitalization of Turkey's customs modernization creates clearance delays at land borders with Bulgaria and Greece, extending transit times for cross-border freight.
Strategic Opportunities
- Southeast Anatolia manufacturing zones:Underpenetrated industrial parks near Gaziantep and Diyarbakir lack integrated logistics providers, creating first-mover advantages for warehouse developers with rail siding access.
- Cloud-based warehouse management convergence:Integration of IoT sensor networks with AI-driven inventory forecasting is enabling real-time visibility services that command premium pricing from e-commerce clients.
- Canal infrastructure tailwind:Istanbul's planned logistics master plan and waterway development will reroute Black Sea container traffic, repositioning warehouse economics in the city's European hinterland.
Industry Challenges
- Warehouse automation technician scarcity:Maintenance and programming skills for automated storage and retrieval systems concentrate in Istanbul, constraining deployment timelines for regional facilities.
- Legacy enterprise resource planning integration:Turkish mid-market manufacturers operate on fragmented software platforms, requiring expensive custom API development for 3PL data exchange.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turkey Third Party Logistics (3PL) Market |
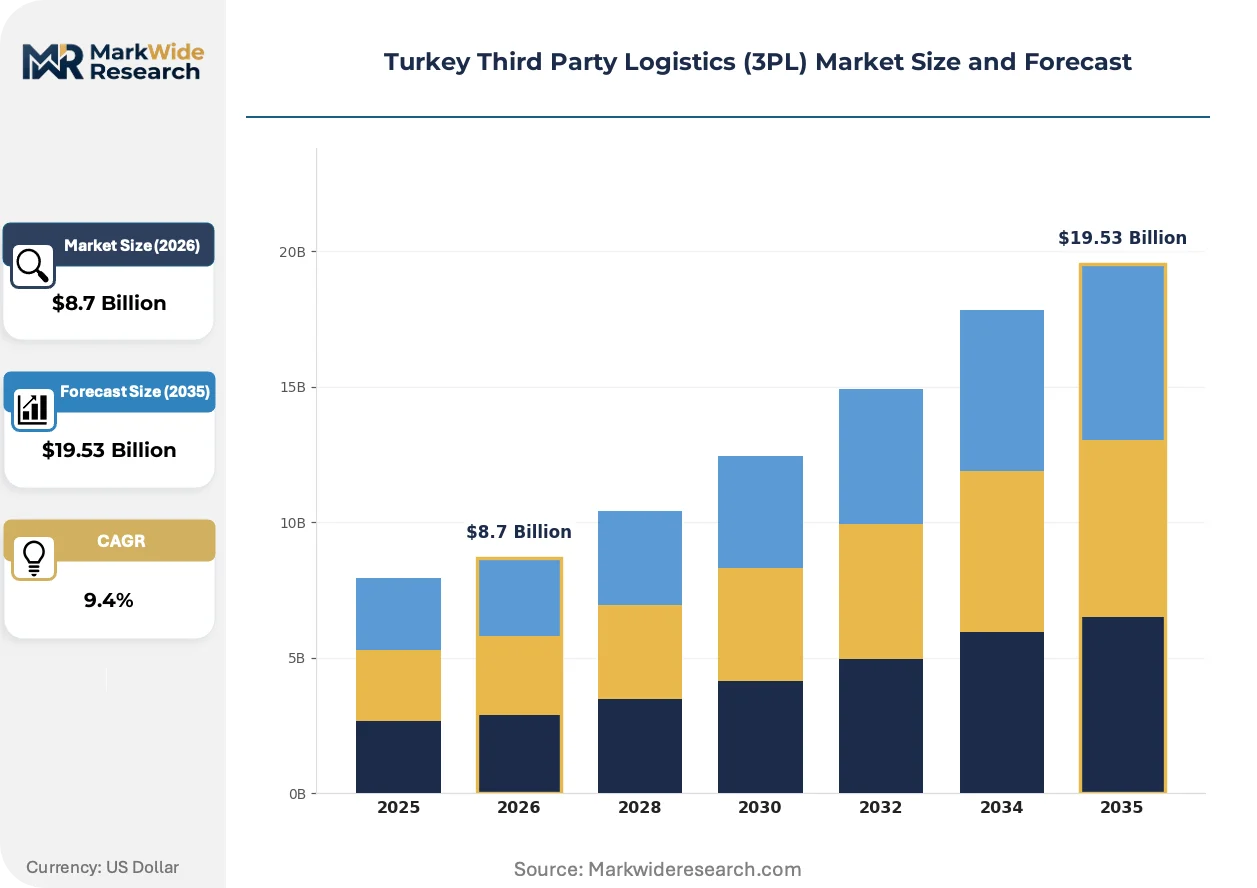
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Distribution, Value-Added Services Client Type: Retail, E-commerce, Manufacturing, Automotive Technology: Cloud-based Systems, Automation, Tracking Solutions, IoT End Use Industry: Pharmaceuticals, Consumer Goods, Electronics, Others |
| Companies Covered | UPS, Maersk, CEVA Logistics, Neta International Transportation, GEFCO, DHL Supply Chain, DSV Panalpina, Arkas Logistics, DB Schenker, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turkey Third Party Logistics (3PL) Market Evolving Landscape
Digital infrastructure investments are compressing the gap between ocean freight visibility and last-mile execution, creating unified control towers that span Turkey's port-to-warehouse continuum. Three developments are restructuring competitive requirements for providers.
Automated guided vehicles and robotic picking systems are consolidating fragmented warehouse operations across Turkey's e-commerce fulfillment centers. Major retailers in Istanbul are deploying these technologies at 40% faster rates than traditional distributors. The technology is consolidating smaller regional warehouses into fewer, larger automated facilities with 24-hour turnaround capabilities.
Turkey's Ministry of Transport and Infrastructure mandates on digital customs declarations and advance cargo information are accelerating pre-arrival clearance adoption. These directives reduce port dwell times from 72 hours toward same-day release for compliant operators. Pharmaceutical and automotive importers around Mersin are restructuring supplier contracts to front-load documentation compliance.
Shippers are unbundling transportation and warehousing contracts into modular service components with discrete performance metrics. Turkish automotive manufacturers now source port drayage, cross-dock consolidation, and final-mile delivery from separate providers rather than single-source 3PL arrangements. This pattern concentrates most visibly among OEM suppliers in the Kocaeli industrial zone seeking cost transparency.
Turkey Third Party Logistics (3PL) Market Segmentation
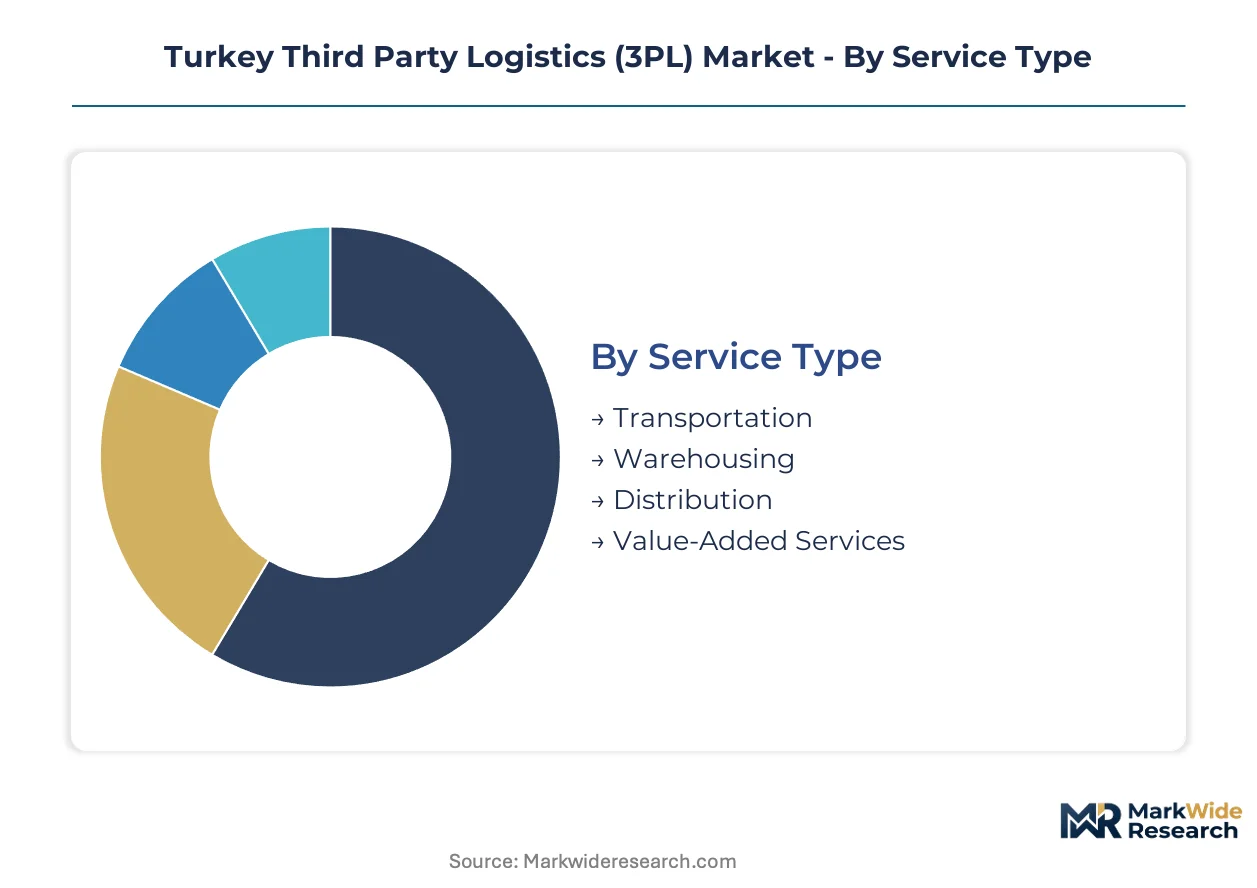
Turkey's 3PL market segments along four functional axes that determine contract structure, margin profile, and technology deployment intensity. Service type and client vertical together dictate whether providers compete on asset density or software integration.
Service Type:
Technology intensity and asset ownership requirements separate transportation from value-added offerings.
- Transportation:Fleet-based road freight dominates contract value, with diesel exposure absorbing 35-45% of operating costs. Automotive manufacturers around Kocaeli and Bursa drive demand for just-in-time delivery windows with penalty clauses.
- Warehousing:Temperature-controlled facilities command premium rates in Istanbul's industrial corridor, where pharmaceutical cold-chain certification requirements from the Trade Ministry restrict eligible providers. Automation adoption concentrates in e-commerce fulfillment centers with 24-hour turnaround mandates.
- Distribution:Cross-dock consolidation services link Mersin port container handling with Anatolian interior routes, creating margin pressure from driver shortage concentration.
- Value-Added Services:Packaging, labeling, and quality inspection generate superior margins through specialized handling requirements and limited qualified labor pools.
Transportation leads on scale; value-added services lead on momentum.
Client Type:
Procurement sophistication and contract duration vary sharply across buyer categories.
- Retail:Seasonal volume spikes and promotional calendars require flexible capacity contracts with surge pricing mechanisms. Istanbul-based department stores dominate this segment.
- E-commerce:Real-time inventory visibility demands and same-day delivery expectations are expanding fastest among Istanbul and Izmir metropolitan consumers. Cloud-based warehouse management system integration is non-negotiable for contract awards.
- Manufacturing:Long-term agreements with fixed asset dedication characterize textile and food processors in Gaziantep and Denizli.
- Automotive:OEM suppliers in the Kocaeli industrial zone unbundle contracts into modular service components, sourcing port drayage, cross-dock consolidation, and final-mile delivery from separate providers.
Manufacturing anchors contract value; e-commerce commands the steepest expansion trajectory.
Technology:
Deployment maturity and capital requirements structure competitive access.
- Cloud-based Systems:Warehouse management platforms with API connectivity to shipper ERP systems are becoming table stakes for mid-market contract eligibility. Turkish mid-market manufacturers on fragmented software platforms require expensive custom integration development.
- Automation:Automated storage and retrieval systems consolidate fragmented operations into fewer, larger facilities. Maintenance technician scarcity in Anatolia constrains regional deployment timelines.
- Tracking Solutions:GPS and RFID visibility tools bridge ocean freight and last-mile execution gaps for Mersin port hinterland distribution.
- IoT:Sensor networks for temperature and humidity monitoring enable pharmaceutical cold-chain compliance documentation required by Trade Ministry directives.
Cloud-based systems lead on penetration; automation leads on investment intensity.
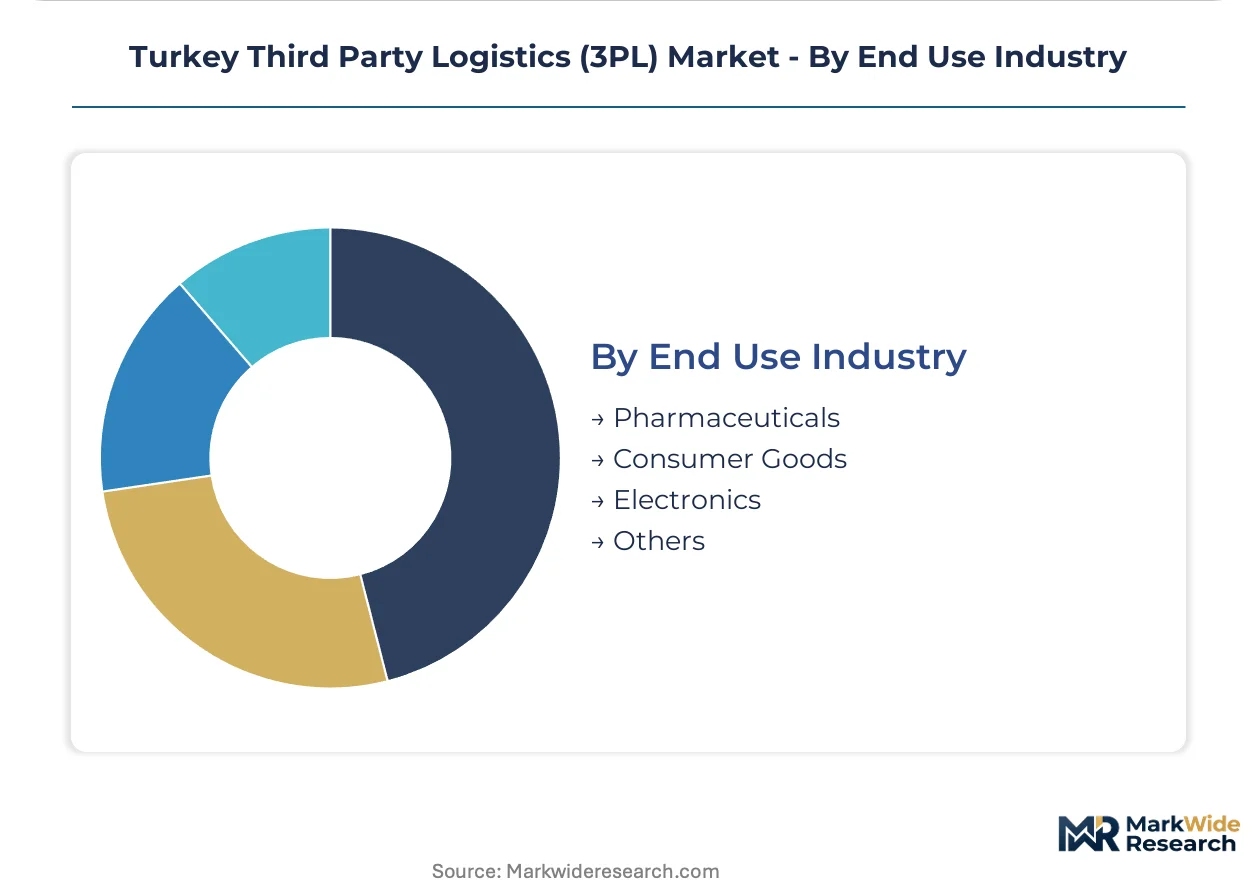
End Use Industry:
Regulatory compliance burden and service level requirements define provider selection criteria.
- Pharmaceuticals:Temperature-validated shipments and digital customs documentation mandates from the Trade Ministry restrict eligible warehouse operators. Demand concentrates around Istanbul's industrial corridor.
- Consumer Goods:High-velocity replenishment cycles and promotional volatility favor providers with scalable labor pools and flexible storage contracts.
- Electronics:Security protocols and anti-static handling requirements limit warehouse eligibility for smartphone and component distributors.
- Others:Chemicals, automotive parts, and industrial equipment span heterogeneous handling requirements with limited standardization.
Pharmaceuticals lead on compliance intensity; consumer goods lead on volume volatility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Istanbul's industrial corridor anchors Turkey's 3PL demand concentration, with multimodal connectivity at Mersin port and the Kocaeli automotive cluster generating complementary distribution requirements across the country's northwest-southeast axis.
Marmara Region
Automotive OEM suppliers in Kocaeli and Gebze drive just-in-time delivery contracts with penalty clauses for missed windows. Turkey's Ministry of Transport digital customs mandates reduce port dwell times for compliant operators. Istanbul's European hinterland warehouses are repositioning ahead of planned canal infrastructure that will reroute Black Sea container traffic.
Aegean Region
Textile exporters in Denizli and food processors in Manisa require flexible capacity contracts with seasonal surge mechanisms. The Trade Ministry's cold-chain certification standards for pharmaceutical shipments restrict eligible warehouse operators. Izmir's port-centric logistics providers are consolidating container handling with rail siding access to Anatolian interior routes.
Mediterranean Region
Automotive manufacturers expanding outsourced logistics footprints seek specialized providers for temperature-sensitive components. Customs modernization directives from the Trade Ministry accelerate pre-arrival clearance adoption at Mersin terminals. The port's hinterland distribution networks integrate container handling with road-rail multimodal connectivity toward Gaziantep manufacturing zones.
Southeast Anatolia Region
Underpenetrated industrial parks near Gaziantep and Diyarbakir lack integrated logistics providers despite manufacturing growth. The Ministry of Transport infrastructure investments in rail connectivity are reducing transit times to Mersin port. First-mover warehouse developers with rail siding access are capturing long-term lease commitments from textile and food processors.
Central Anatolia Region
Qualified commercial license holders cluster disproportionately around Ankara, leaving Konya and Kayseri routes underserved with elevated rates. Driver shortage concentration in interior regions compresses margins for asset-heavy operators without fuel surcharge mechanisms. Regional distribution centers are consolidating fragmented operations into fewer automated facilities with 24-hour turnaround capabilities.
Turkey Third Party Logistics (3PL) Market Competitive Landscape
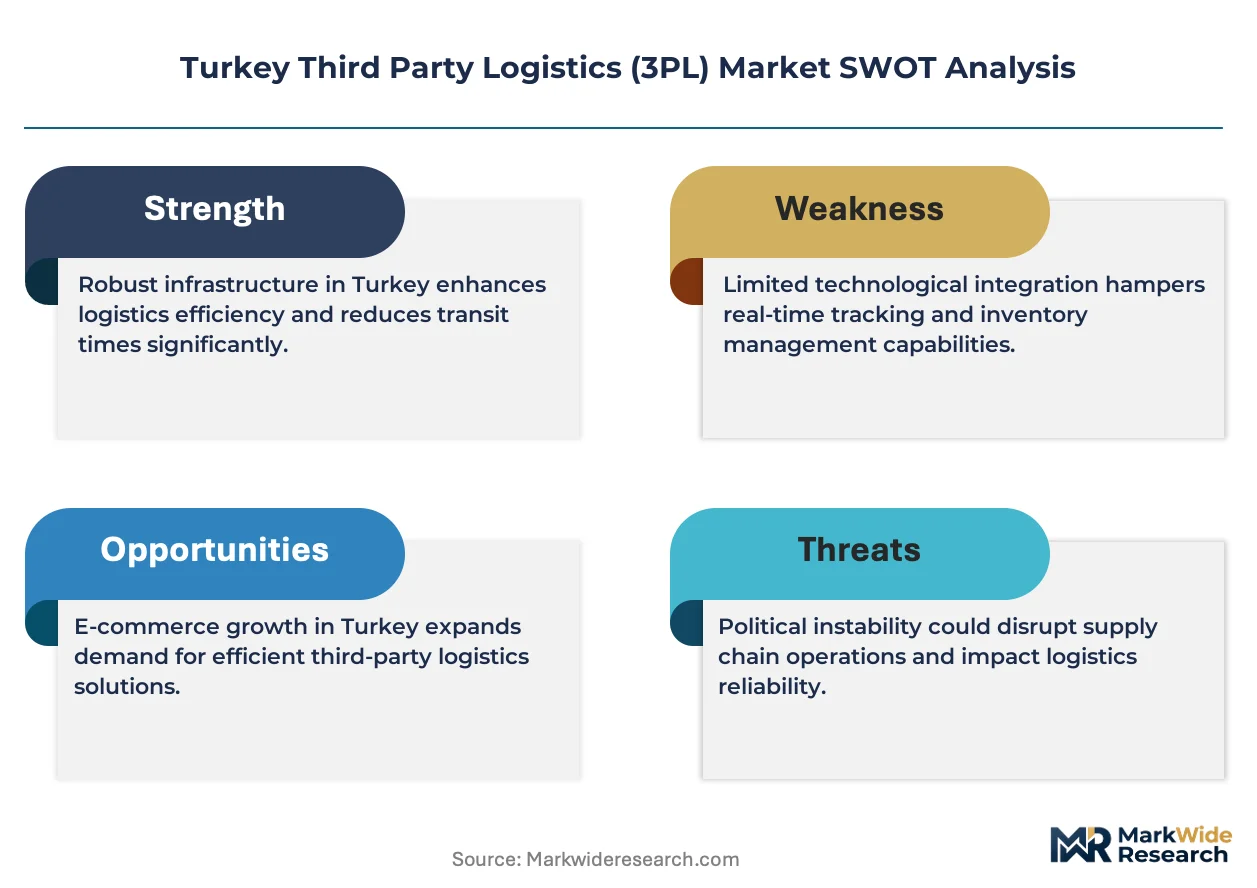
Global majors compete with regional champions across Turkey's 3PL sector through differentiated network density and port-centric vertical control. The market structures around three tiers: integrated European networks with cross-border freight consolidation capabilities, Turkish port operators with captive container terminal access, and specialized cold-chain providers with pharmaceutical certification infrastructure. Strategic moves concentrate on warehouse automation deployment and modular service unbundling that separates transportation from warehousing contracts.
Within the integrated network tier, DHL Supply Chain and Maersk exemplify archetypes leveraging European density and ocean freight dominance respectively. Arkas Logistics occupies a position among port-centric regional champions controlling container handling at Mersin and Izmir terminals. These three anchors represent distinct competitive vectors: cross-border consolidation, integrated sea-rail offerings, and terminal-to-warehouse vertical control.
| Leading Market Players |
|---|
| UPS |
| Maersk |
| CEVA Logistics |
| Neta International Transportation |
| GEFCO |
| DHL Supply Chain |
| DSV Panalpina |
| Arkas Logistics |
| DB Schenker |
| Others |
Value Network & Pricing Analysis
Automotive OEM procurement teams in Kocaeli are unbundling single-source 3PL contracts into modular service components, forcing providers to compete on discrete cost-per-unit metrics rather than bundled relationship pricing. This procurement fragmentation concentrates pricing power with buyers who can pit specialized port drayage, cross-dock consolidation, and final-mile providers against one another.
Pricing Analysis
Diesel cost pass-through clauses dominate transportation contract structures, with fuel absorbing 35-45% of operating costs and surcharge mechanisms determining provider survival. Price differentiation hinges on Trade Ministry cold-chain certification tiers for pharmaceutical clients and automation-enabled 24-hour turnaround guarantees for e-commerce fulfillment. Pricing pressure stems from driver shortage concentration around Istanbul and Izmir, which elevates rates on Anatolian interior routes. Small and mid-market manufacturers exhibit highest price sensitivity, while pharmaceutical shippers prioritize compliance over cost.
Supply Chain Analysis
Direct-to-automotive channels handle just-in-time delivery demand from Kocaeli and Gebze clusters through dedicated fleet arrangements with penalty-backed service windows. Geographic supply concentration centers on Turkey's Marmara corridor, with Mersin port and Izmir terminal operations anchoring container throughput. The supply chain draws from EU-sourced fleet equipment, domestic warehousing construction materials, and German automation technology. Single-source vulnerability runs through qualified commercial license holder pools clustered disproportionately around Istanbul. Distribution runs through multimodal rail-road networks toward underpenetrated Southeast Anatolia manufacturing zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Turkey's 3PL sector offers stable compounding characteristics anchored by persistent infrastructure investment from the Ministry of Transport and irreversible outsourcing trends among automotive and pharmaceutical manufacturers.
For Market Incumbents: Extend warehouse automation deployment timelines in Istanbul's European hinterland ahead of canal infrastructure rerouting Black Sea container traffic. Deepen captive control over Mersin and Izmir terminal operations to defend against Maersk's integrated sea-rail encroachment. Prioritize Trade Ministry cold-chain certification maintenance as pharmaceutical compliance mandates tighten eligible provider pools. For New Entrants and Emerging Players: Launch via rail-siding warehouse development in Gaziantep and Diyarbakir industrial parks where integrated logistics providers remain scarce. Target textile and food processing manufacturers with flexible capacity contracts featuring seasonal surge mechanisms absent from incumbent fixed-asset offerings. Differentiate through cloud-based warehouse management system integration addressing mid-market manufacturers' fragmented ERP platforms. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized cold-chain operators possessing Trade Ministry pharmaceutical certification and established Istanbul corridor real estate. Five-to-ten year viability favors providers combining port terminal access with automation deployment capability rather than pure-play transportation asset owners. Monitor Ministry of Transport digital customs modernization milestones as inflection indicators for compliant operator margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Warehousing Automation Deployment | Consolidates fragmented regional operations into 24-hour turnaround facilities serving Istanbul e-commerce demand. |
| Cold-Chain Certification Investment | Secures eligibility for pharmaceutical contracts under Trade Ministry temperature-validation mandates. |
| Rail Siding Access Development | Captures long-term lease commitments from Southeast Anatolia textile manufacturers seeking Mersin port connectivity. |
| Modular Service Unbundling | Aligns contract structures with automotive OEM procurement preferences for cost transparency across discrete logistics functions. |
| Cloud-Based WMS Integration | Enables real-time inventory visibility required by e-commerce clients and mid-market manufacturers with fragmented ERP systems. |
Research Methodology
Direct dialogue with 3PL operations directors, automotive procurement managers at Kocaeli industrial zone suppliers, pharmaceutical supply chain leads, and Ministry of Transport infrastructure planners grounded qualitative findings. Secondary validation drew from Turkish Statistical Institute trade data, EU Customs Union Technical Committee regulatory filings, Transport Ministry infrastructure investment disclosures, and container throughput statistics at Mersin and Izmir port authorities. Bottom-up service provider capacity assessments and top-down national logistics expenditure estimates were triangulated to establish market sizing.
Segment-level projections across transportation, warehousing, distribution, and value-added services were generated over the analysis window using modeled interactions between automotive outsourcing penetration rates, e-commerce fulfillment automation adoption curves, and pharmaceutical cold-chain compliance expansion. CAGRs were derived from regression analysis linking historical contract value growth to infrastructure investment cycles and regulatory modernization timelines. Forecast inputs incorporated diesel price volatility scenarios and driver labor pool concentration patterns around Istanbul and Izmir.
Forecast precision tightens around the base case; tail outcomes carry wider variance under fuel price shock conditions or accelerated EU emission compliance mandates. Projections reflect assumptions regarding Ministry of Transport digital customs implementation schedules and canal infrastructure completion timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
China Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
New Zealand Freight and Logistics Market
Logistics and Shipping
Estonia Freight and Logistics Market
Logistics and Shipping
UAE Contract Logistics Market
Logistics and Shipping
North America Cargo Handling Equipment Market
Logistics and Shipping
Saudi Arabia Last Mile Delivery Market
Logistics and Shipping
China Project Logistics Market
Logistics and Shipping
Central and Eastern Europe Cold Chain Logistics Market
Logistics and Shipping
South Korea International Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
India Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Inbound Logistics Market
Logistics and Shipping
United States Chartered Air Freight Transport Market
Logistics and Shipping
Mexico Freight Forwarding Market
Logistics and Shipping
GCC Secure Logistics Market
Logistics and Shipping
Malaysia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Warehousing and Distribution Logistics Market