
 Global 5PL Solutions Market | 2026-2036
Global 5PL Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Global 5PL Solutions Market Analysis
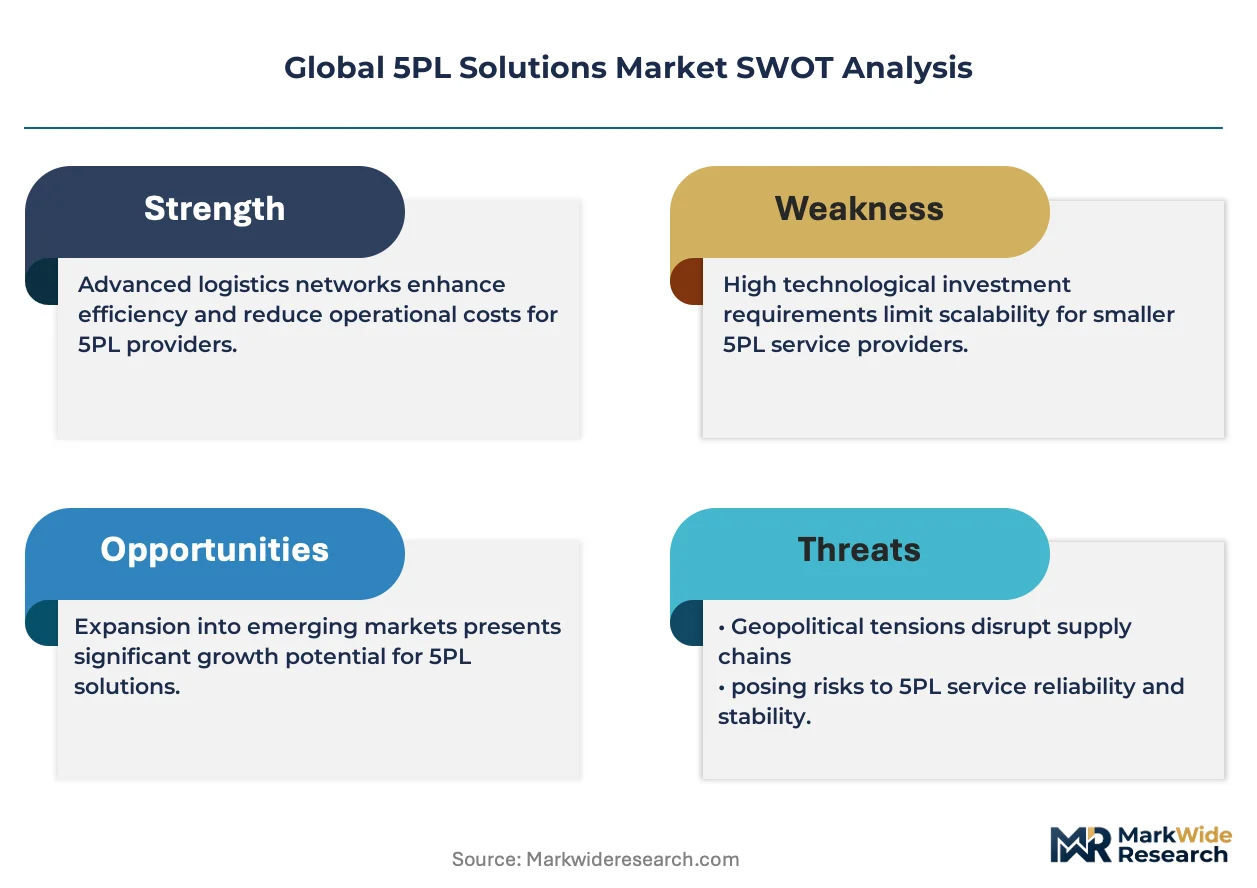
REACH compliance is broadening the cost-of-entry calculus for 5PL providers managing chemical and pharmaceutical supply chains across Europe. DHL Supply Chain leverages its control tower infrastructure to anchor complex multi-modal networks for industrial clients. FedEx Supply Chain differentiates through specialized healthcare logistics capabilities that navigate temperature-sensitive distribution requirements.
5PL solutions represent fully outsourced supply chain orchestration where a single provider manages the entire logistics network, including subcontractor coordination, through cloud-based control towers integrating real-time visibility across tiers. These systems employ API-driven data exchange protocols and predictive analytics engines to synchronize inventory positions across geographically dispersed supplier bases. Transportation Management services currently dominate revenue contribution as shippers prioritize freight cost optimization, while Artificial Intelligence capabilities represent the fastest-expanding technology layer as neural network demand forecasting displaces static planning models. Cloud-based deployment models capture the majority of new implementations, though hybrid architectures retain traction among defense and pharmaceutical clients with data sovereignty requirements.
The EU AI Act, FDA track-and-trace mandates, and China's GB standards for logistics data security collectively tighten algorithmic transparency and product provenance requirements across jurisdictions. ECHA substance restrictions and EPA emissions reporting obligations further compel 5PL operators to embed compliance monitoring directly into network orchestration platforms. Stakeholders must evaluate whether their control tower architectures can absorb emerging regulatory layers without fragmenting into jurisdiction-specific silos.
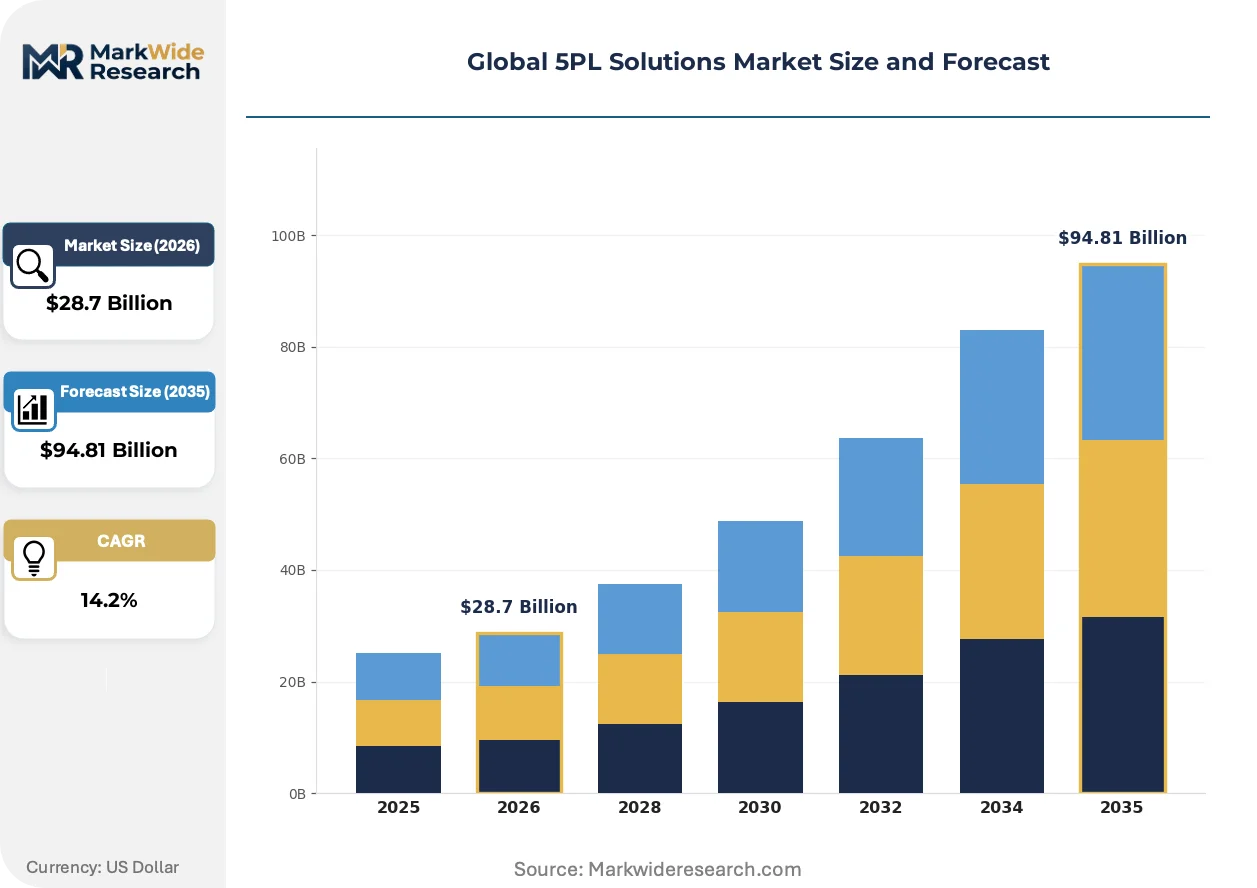
Market Dynamics
Cloud-native control tower architectures are compressing the timeline for multi-tier supply chain visibility from months to weeks, forcing incumbent logistics operators to rebuild orchestration stacks around API-first data fabrics rather than legacy EDI protocols.
Growth Catalysts
- EU AI Act compliance mandates:Automated logistics networks across Europe must embed algorithmic transparency and human oversight mechanisms, creating pull for 5PL providers with pre-certified AI governance frameworks.
- Neural network demand forecasting:Pharmaceutical and chemical manufacturers are adopting predictive inventory positioning that displaces static safety-stock models, requiring real-time supplier synchronization only control towers deliver.
- Germany's industrial manufacturing density:Automotive and machinery producers concentrated in Baden-Württemberg and Bavaria seek integrated visibility across multi-tier supplier bases, accelerating 5PL adoption for complex outbound networks.
Market Restraints
- REACH substance compliance costs:ECHA registration and restriction protocols for chemical logistics impose fixed-cost burdens that squeeze margins for 5PL operators managing European pharmaceutical supply chains.
- Data sovereignty fragmentation:China's GB standards for logistics data security, the EU AI Act's algorithmic audit requirements, and FDA track-and-trace mandates create incompatible jurisdictional silos that fragment platform architectures.
- Skilled control tower analyst scarcity:The intersection of supply chain operations, data science, and regulatory expertise concentrates talent in Rotterdam, Singapore, and Chicago, inflating personnel costs for network orchestration centers.
Strategic Opportunities
- India's pharmaceutical export corridor:CDSCO serialization mandates and DGFT trade documentation requirements create white space for 5PL providers offering integrated compliance-plus-logistics bundles for API and formulation shipments.
- Digital twin convergence with blockchain provenance:Temperature-sensitive biologics distribution is adopting synchronized virtual network models that combine real-time simulation with immutable custody records, opening premium service tiers.
- Japan's METI carbon accounting standards:Industrial manufacturers under Scope 3 disclosure pressure seek 5PL partners with embedded emissions tracking across subcontractor tiers, creating first-mover advantage for certified providers.
Industry Challenges
- Legacy ERP integration complexity:SAP and Oracle systems deployed by industrial clients in the 2010s lack native API connectivity, forcing expensive middleware development for control tower data ingestion.
- Multi-jurisdiction certification timelines:Simultaneous FDA, EMA, and NMPA validation for pharmaceutical logistics networks extends platform deployment cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 5PL Solutions Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $94.81 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation Management, Order Fulfillment, Network Optimization, Inventory Management Client Type: Manufacturers, Retailers, Wholesalers, E-Commerce Technology: Automation, Artificial Intelligence, IoT Solutions, Cloud Computing Deployment Model: On-premises, Cloud-based, Hybrid, Managed Services |
| Companies Covered | DHL Supply Chain, UPS Supply Chain Solutions, FedEx Supply Chain, Kuehne+Nagel, DB Schenker, CEVA Logistics, A.P. Moller - Maersk, C.H. Robinson, XPO Logistics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 5PL Solutions Market Emerging Trajectories
Generative AI is rewriting how supply chain orchestration platforms generate exception-handling protocols, compressing the gap between data anomaly detection and automated resolution pathways.
Digital twin technology is expanding into pharmaceutical cold chain networks by creating virtual replicas of temperature-controlled distribution lanes. Biologics manufacturers in Switzerland and Singapore are deploying these systems to simulate lane risk before physical shipment. The technology is expanding into subcontractor tier visibility, enabling 5PL operators to model supplier failure scenarios without disrupting live operations.
The EU AI Act's risk classification framework for automated decision systems is forcing logistics platforms to implement human-in-the-loop overrides for critical routing algorithms. Industrial manufacturers in Germany and France must now document algorithmic training data provenance for customs clearance automation. Pharmaceutical 5PL networks are responding by segregating EU-bound control tower functions into dedicated compliance instances with audit-ready logging architectures.
Shippers are unbundling freight procurement from inventory management, creating separate vendor relationships for transportation execution and network orchestration. E-commerce retailers in the United States and South Korea now contract specialized 5PL providers for control tower functions while retaining direct carrier agreements for last-mile delivery. This bifurcation is most visible in consumer electronics, where brand manufacturers seek strategic control over final-mile customer experience while outsourcing upstream supplier synchronization.
Global 5PL Solutions Market Segmentation
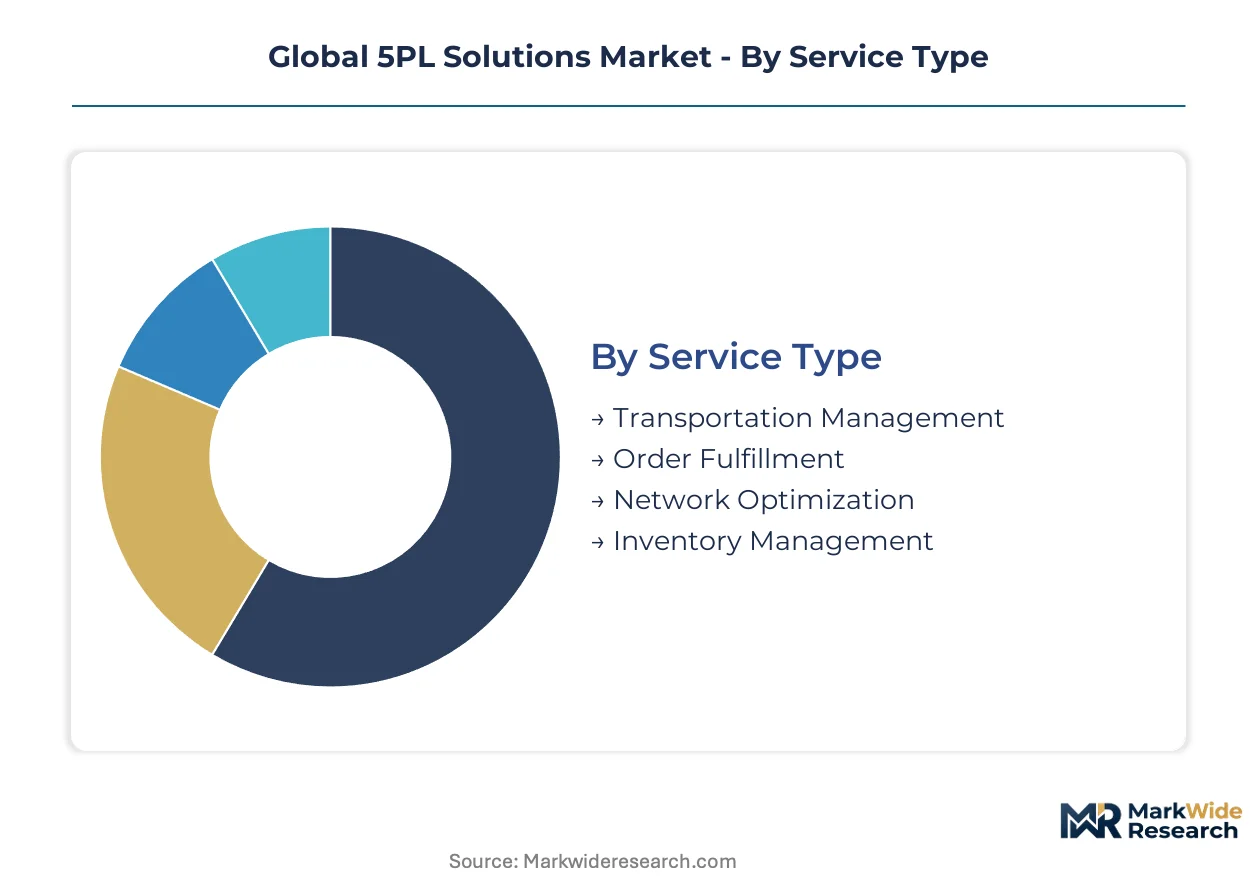
5PL solutions fragment across service layers, client sophistication, and technology maturity. Buyers prioritize control tower visibility depth and regulatory certification over pure cost metrics. Segmentation reveals where orchestration value concentrates versus where commoditization pressures build.
Service Type:
Industrial buyers select service tiers based on network complexity and subcontractor tier depth rather than shipment volume alone.
- Transportation Management:Freight procurement, carrier allocation, and multi-modal execution coordinated through API-connected TMS platforms. Automotive manufacturers in Germany and pharmaceutical exporters in Switzerland anchor demand here, prioritizing lane cost optimization across fragmented carrier bases.
- Order Fulfillment:Warehouse orchestration, pick-pack operations, and last-mile handoff management integrated with client OMS systems. E-commerce retailers in the United States and South Korea concentrate procurement here, driven by customer delivery window compression and returns complexity.
- Network Optimization:Topology modeling, facility location analysis, and flow path simulation using digital twin architectures.
- Inventory Management:Safety stock positioning, demand sensing, and supplier synchronization across multi-tier supply bases.
Volume sits with Transportation Management; growth tilts toward Network Optimization.
Client Type:
Contract structures diver sharply between asset-heavy manufacturers seeking control tower unification and digital-native retailers demanding modular API access.
- Manufacturers:Industrial producers with complex inbound supplier networks and outbound distribution requirements. Machinery and chemical producers in Baden-Württemberg and Bavaria drive adoption, compelled by REACH compliance documentation and multi-tier visibility mandates.
- E-Commerce:Digital retailers with volatile demand patterns and fragmented last-mile requirements. Cross-border sellers in the Netherlands and fulfillment platforms in the United States expand fastest, requiring real-time inventory positioning across distributed warehouse networks.
- Retailers:Omnichannel operators balancing store replenishment with direct-to-consumer fulfillment.
- Wholesalers:Distribution intermediaries seeking inventory pooling and consolidated procurement leverage.
Manufacturers contribute the largest contract values; E-Commerce climbs the fastest.
Technology:
Technology procurement tracks regulatory pressure intensity, with AI governance frameworks now prerequisite for EU-bound deployments.
- Artificial Intelligence:Neural network demand forecasting, routing optimization, and exception handling with embedded audit logging for algorithmic transparency. Pharmaceutical networks across Europe and industrial manufacturers in Japan prioritize certified AI governance architectures compliant with EU AI Act risk classifications.
- Cloud Computing:Scalable control tower infrastructure with API-first data fabrics replacing legacy EDI protocols. Mid-market logistics operators in Singapore and the United States migrate here, escaping on-premises maintenance burdens.
- IoT Solutions:Sensor networks for asset tracking, condition monitoring, and geofenced custody verification.
- Automation:Robotic process automation for documentation, customs filing, and carrier appointment scheduling.
Cloud Computing captures the majority of new deployments; Artificial Intelligence shows the steepest expansion trajectory.
Deployment Model:
Data sovereignty requirements and validation timelines split procurement between cloud-native speed and hybrid compliance rigor.
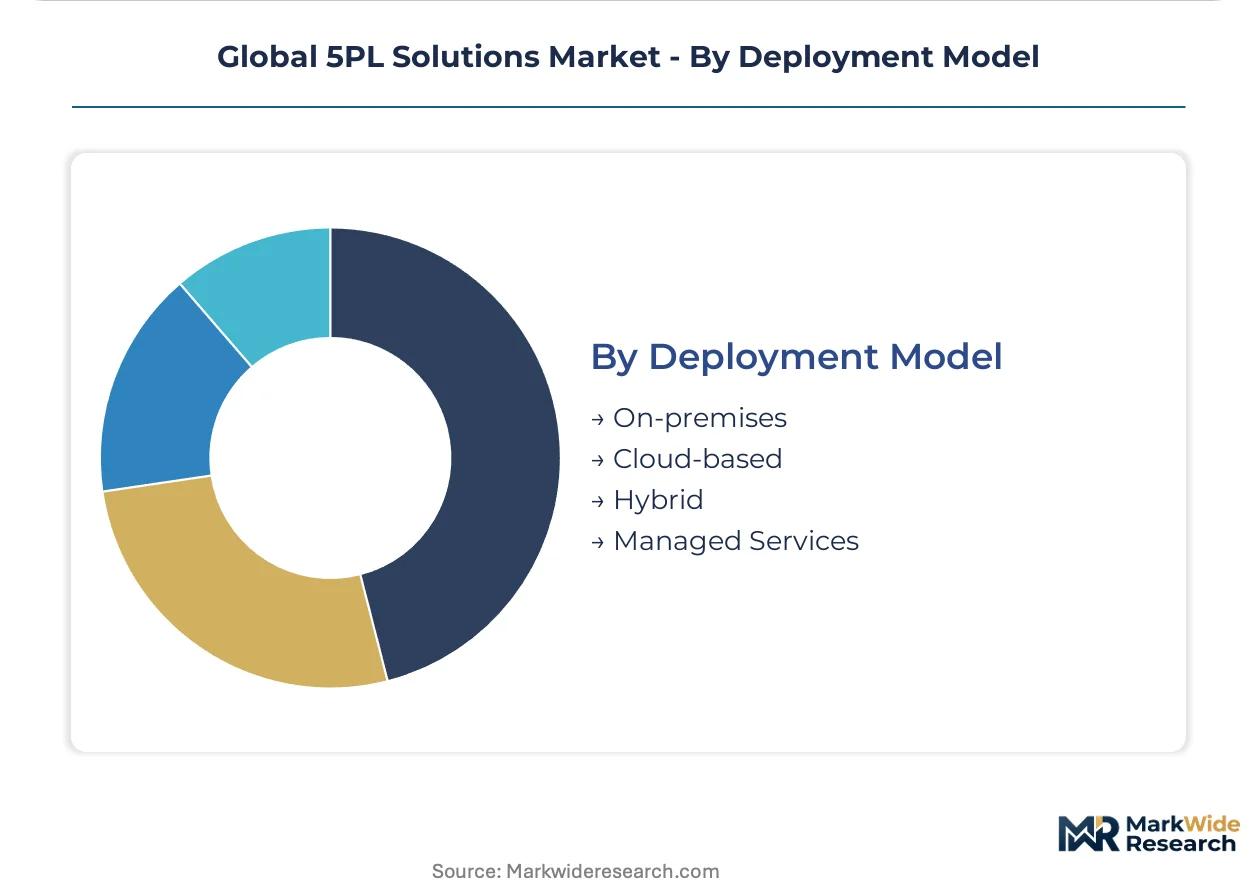
- Cloud-based:Fully hosted control tower platforms with subscription pricing and rapid implementation timelines. Consumer electronics and fashion retailers in the United States and Germany default here, prioritizing speed-to-visibility over customization depth.
- Hybrid:Split architectures with sensitive data resident on client infrastructure and orchestration logic cloud-hosted. Pharmaceutical manufacturers and defense contractors in Switzerland and France require this model to satisfy FDA, EMA, and national security data localization rules.
- On-premises:Legacy dedicated installations with full client control over hardware and data residency.
- Managed Services:Outsourced operational control with provider staff embedded in client network orchestration.
Cloud-based deployments dominate new implementations; Hybrid models retain pricing premiums in regulated verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Singapore and Dubai concentrate 5PL control tower operations serving cross-border pharmaceutical and electronics corridors. Tax-advantaged logistics parks in Rotterdam and Hamburg anchor European network orchestration hubs. Industrial manufacturing clusters across Germany, Switzerland, and the Netherlands generate concentrated demand for multi-tier supplier visibility.
Germany
Automotive and machinery producers in Baden-Württemberg and Bavaria drive adoption of integrated control tower platforms for complex outbound networks. The EU AI Act mandates algorithmic transparency and human oversight for automated logistics networks, compelling providers to embed certified AI governance frameworks. Stuttgart and Munich industrial corridors concentrate procurement of neural network demand forecasting for supplier synchronization.
United States
E-commerce retailers and pharmaceutical distributors prioritize cloud-native control towers with API-first data fabrics replacing legacy EDI protocols. FDA track-and-trace mandates for pharmaceutical supply chains extend platform deployment timelines, favoring providers with pre-validated compliance architectures. Chicago and Memphis logistics clusters anchor demand for real-time inventory positioning across distributed warehouse networks.
Switzerland
Biologics manufacturers in Basel and Geneva deploy digital twin architectures for temperature-controlled distribution lane simulation before physical shipment. Swissmedic pharmaceutical regulations and data sovereignty requirements sustain hybrid deployment models with sensitive data resident on client infrastructure. The Lake Geneva biotech corridor concentrates premium service tiers combining virtual network modeling with immutable custody records.
China
Domestic pharmaceutical exporters and cross-border e-commerce platforms navigate GB standards for logistics data security that fragment platform architectures. NMPA serialization mandates and dual carbon disclosure pressures create demand for embedded emissions tracking across subcontractor tiers. Shanghai and Shenzhen free trade zones concentrate control tower operations serving API and formulation export corridors.
India
Pharmaceutical exporters in Hyderabad and Ahmedabad seek integrated compliance-plus-logistics bundles for active pharmaceutical ingredient shipments. CDSCO serialization mandates and DGFT trade documentation requirements create white space for providers offering bundled regulatory and orchestration services. The Mumbai-Pune pharmaceutical belt anchors procurement of multi-tier visibility platforms for export corridor optimization.
Global 5PL Solutions Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the 5PL solutions market. Global integrated logistics operators leverage existing transportation networks to anchor control tower offerings, while technology-native specialists build API-first orchestration platforms without legacy asset constraints. Strategic archetypes include asset-heavy network integrators, cloud-native software specialists, and vertical-focused healthcare logistics providers. Competitive moves concentrate on M&A for control tower technology acquisition and strategic partnerships for regulatory certification across jurisdictions.
Within the asset-heavy integrator tier, DHL Supply Chain and FedEx Supply Chain exemplify providers leveraging established multi-modal infrastructure to anchor complex network orchestration. Kuehne+Nagel occupies a position among European-headquartered specialists with concentrated pharmaceutical and industrial manufacturing expertise. These three operators represent the dominant archetype competing on regulatory certification depth and multi-tier visibility capabilities.
| Leading Market Players |
|---|
| DHL Supply Chain |
| UPS Supply Chain Solutions |
| FedEx Supply Chain |
| Kuehne+Nagel |
| DB Schenker |
| CEVA Logistics |
| A.P. Moller - Maersk |
| C.H. Robinson |
| XPO Logistics |
| Others |
Supply Flow & Price Mechanics
Cloud infrastructure cost indices and API gateway licensing fees cascade through 5PL provider economics, compressing margins for operators without scale while enabling SaaS-tiered pricing for cloud-native entrants serving mid-market e-commerce retailers.
Pricing Analysis
Lead-time premiums for rapid control tower deployment command three-tier pricing structure across premium, standard, and economy levels, with pharmaceutical manufacturers in Switzerland and Germany paying certification-grade rates for EU AI Act-compliant instances. Price differentiation hinges on regulatory validation depth and geographic data residency requirements, with hybrid deployments carrying 40-60% premiums over cloud-native alternatives. Cost compression in standard-tier transportation management services is intensifying because mid-market logistics operators are replicating basic API connectivity without orchestration depth. E-commerce retailers exhibit highest price sensitivity, while biologics manufacturers accept premium positioning for temperature-sensitive digital twin capabilities.
Supply Chain Analysis
FDA, EMA, and NMPA qualification protocols gate software vendor participation in pharmaceutical 5PL networks, extending certification timelines and concentrating qualified provider pools. Control tower technology development centers on Germany, Singapore, and the United States, with cloud infrastructure anchoring in Ireland and the Netherlands for EU data sovereignty compliance. The supply chain draws from specialized talent pools in Rotterdam, Chicago, and Singapore for control tower analysts, and from semiconductor fabrication in Taiwan and South Korea for IoT sensor components. Single-source vulnerability concentrates in API gateway providers and hyperscaler cloud platforms. Distribution runs through free trade zones in Dubai, Singapore, and Rotterdam for cross-border pharmaceutical and electronics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory certification complexity is forcing consolidation among sub-scale operators unable to sustain multi-jurisdiction validation costs, creating acquisition opportunities for well-capitalized platforms.
For Market Incumbents: Acquire specialized AI governance software assets to compress EU AI Act compliance timelines and defend against cloud-native entrants with pre-certified orchestration stacks. DHL Supply Chain and FedEx Supply Chain should deepen backward integration into digital twin simulation engines for pharmaceutical cold chain networks, while Kuehne+Nagel prioritizes EMA certification depth for biologics distribution lanes. For New Entrants and Emerging Players: API-first orchestration platforms offer the lowest-friction entry vector, enabling modular control tower deployment without legacy EDI migration burdens. Target India's pharmaceutical export corridor for CDSCO-compliant compliance-plus-logistics bundles, and Japan's industrial manufacturing clusters for METI carbon accounting-certified network visibility. White-label control tower modules for mid-market 3PL operators seeking rapid digitization represent the most penetrable beachhead. For Investors and Strategic Acquirers: The window for entry favors technology-native specialists with pre-built regulatory certification architectures over asset-heavy integrators burdened by legacy infrastructure. Long-term viability centers on platforms capable of absorbing emerging jurisdiction-specific compliance layers without fragmentation. Watch for FDA validation timeline extensions as the inflection signal indicating regulatory complexity is outrunning sub-scale operator adaptation capacity.| Strategic Initiative | Industry Significance |
|---|---|
| AI Governance Framework Certification | EU AI Act compliance becomes table stakes for European pharmaceutical network orchestration contracts. |
| Digital Twin Platform Acquisition | Temperature-sensitive biologics distribution in Switzerland demands virtual lane simulation capabilities. |
| Hybrid Cloud Infrastructure Expansion | Data sovereignty requirements in France and Switzerland sustain premium pricing for split-architecture deployments. |
| India Pharmaceutical Corridor Entry | CDSCO serialization mandates create bundled compliance-plus-logistics service opportunities for API exporters. |
| Control Tower Talent Hub Establishment | Analyst scarcity in Rotterdam and Singapore inflates personnel costs, favoring geographic diversification. |
Methodological Framework
Trade publications, customs documentation databases, and hyperscaler infrastructure investment disclosures formed the secondary backbone, cross-referenced against primary interviews with control tower operations directors, pharmaceutical supply chain executives, regulatory affairs leads at logistics operators, and EMA compliance officers. Bottom-up triangulation aggregated service-level contract values across transportation management, order fulfillment, and network optimization tiers, while top-down validation referenced macro logistics spend patterns in Germany, the United States, and Switzerland.
Bottom-up modeling built volume and value outputs from individual service line deployments across the projection horizon, segmented by deployment model, client sophistication tier, and regulatory certification intensity. CAGRs derived from fitted growth curves incorporating neural network adoption velocity, EU AI Act implementation timelines, and pharmaceutical serialization mandate expansion. Forecast inputs included cloud infrastructure cost trajectories and control tower analyst wage inflation in Rotterdam, Singapore, and Chicago logistics clusters.
The model holds under stable regulatory certification timelines; deviation in FDA, EMA, or NMPA validation extension would shift deployment cycle assumptions and provider concentration dynamics. Forecasts reflect base-case assumptions regarding API-first platform migration velocity and hybrid architecture retention in regulated verticals. A model refresh is warranted upon material change in EU AI Act enforcement intensity or pharmaceutical data localization rule expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
US Express Delivery Market
Logistics and Shipping
Middle East and Africa Freight & Logistics Market
Logistics and Shipping
Armenia Freight and Logistics Market
Logistics and Shipping
US Event Logistics Market
Logistics and Shipping
Logistics Outsourcing Market
Logistics and Shipping
Intra-Asia Freight Forwarding Market
Logistics and Shipping
Central and Eastern Europe Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Europe Domestic Courier Market
Logistics and Shipping
Thailand E-Commerce Logistics Market
Logistics and Shipping
Romania Freight and Logistics Market
Logistics and Shipping
US Air Freight Transport Market
Logistics and Shipping
North America Last Mile Delivery Market
Logistics and Shipping
Global Drone Logistics and Transportation Market
Logistics and Shipping
Flat Rack Containers Market
Logistics and Shipping
Saudi Arabia Contract Logistics Market
Logistics and Shipping
Egypt Courier, Express, and Parcel (CEP) Market