
 Poland Cold Chain Logistics Market | 2026-2036
Poland Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Cold Chain Logistics Market Analytics
Pharmaceutical distribution is expanding faster than food logistics within Poland's cold chain sector. DHL sustains one of the largest temperature-controlled warehouse networks near Warsaw. Raben Group specializes in multi-temperature fleet operations serving regional pharmaceutical clients. NewCold Logistics dominates automated high-bay frozen storage with facilities in Poland serving pan-European retail chains.
Poland cold chain logistics encompasses the temperature-managed movement and storage of perishable goods, typically maintained between minus 25°C and plus 8°C depending on product sensitivity, utilizing vapor-compression refrigeration, insulated vehicle bodies, and real-time telemetry to preserve product integrity across distribution cycles. Refrigerated warehousing anchors the value pool due to land scarcity near major Polish transport corridors and high capital barriers for automated racking systems. Temperature-controlled transport competes on fleet utilization and driver certification density, while monitoring systems are gaining traction as pharmaceutical shippers mandate continuous data logging for EU Good Distribution Practice compliance.
Poland's cold chain operators navigate oversight from the EU F-Gas Regulation, the EU Green Deal emission benchmarks, and national sanitary inspection protocols enforced by Poland's Chief Sanitary Inspectorate. These frameworks tighten refrigerant phase-down schedules, mandate energy efficiency disclosures for new warehouse builds, and require validated temperature records for pharmaceutical shipments. Stakeholders must weigh automation capex against tightening carbon compliance and evolving pharmaceutical traceability standards.
Market Dynamics
The EU F-Gas Regulation's refrigerant phase-down schedule is compressing operating margins across Polish cold chain facilities while accelerating capital redeployment toward ammonia-CO2 cascade systems and automated high-bay warehouses.
Growth Catalysts
- Pharmaceutical Distribution Networks:Poland's Chief Sanitary Inspectorate mandates validated temperature records for vaccine shipments, expanding demand for GDP-compliant warehousing along the Warsaw-Łódź corridor.
- EU Green Deal Benchmarks:Energy efficiency disclosure requirements for new warehouse builds are incentivizing operators to install solar-integrated refrigeration and recover waste heat from compressor systems.
- Pan-European Retail Consolidation:Centralized frozen food procurement by continental grocery chains is pulling automated pallet handling and multi-temperature cross-docking capacity into Silesian logistics parks.
Market Restraints
- Refrigerant Input Cost Volatility:HFC quota reductions under the EU F-Gas Regulation have tripled R-404A replacement costs, squeezing smaller Polish operators unable to finance natural refrigerant conversions.
- Land Scarcity Near Transport Corridors:Speculative development of last-mile e-commerce facilities has consumed zoned industrial plots around Warsaw Modlin and Kraków-Balice, elevating greenfield cold storage land premiums.
- Driver Certification Density Limits:Poland's qualification requirements for ATP-certified refrigerated transport operators lag fleet expansion, constraining temperature-controlled road capacity during peak agricultural harvest windows.
Strategic Opportunities
- Underpenetrated Podlaskie and Warmia-Mazury:Eastern Poland's dairy and berry production regions lack sufficient pre-cooling and frozen storage infrastructure, creating first-mover advantage for regional hub development.
- Battery-Electric Refrigerated Transport:Convergence of high-density battery packs and electric vapor-compression units is enabling zero-emission last-mile delivery trials in Kraków's low-emission zone.
- EU CSRD Disclosure Mandates:Scope 3 emissions reporting requirements are forcing food manufacturers to source certified green cold chain partners, creating premium pricing power for carbon-verified Polish operators.
Industry Challenges
- Refrigeration Technician Shortage:Poland's vocational training pipeline produces insufficient ammonia system specialists to service the wave of natural refrigerant conversions triggered by F-Gas compliance deadlines.
- Legacy Warehouse Management System Integration:Mid-sized Polish cold storage operators struggle to embed real-time telemetry and predictive maintenance modules into decades-old ERP architectures without operational disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Cold Chain Logistics Market |
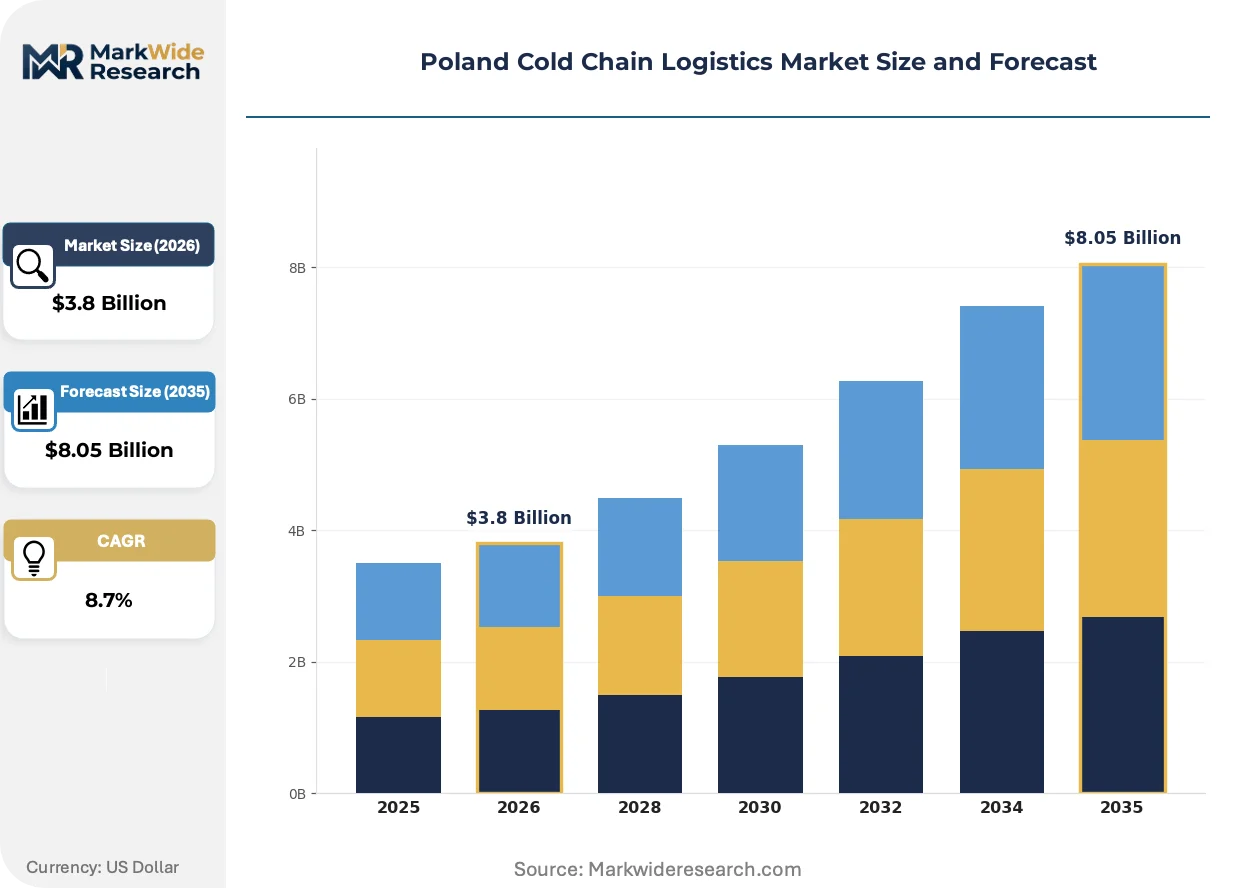
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerated Warehousing, Temperature-Controlled Transport, Monitoring Systems, Packaging Solutions End User: Pharmaceuticals, Food & Beverage, Biotechnology, Floral Service Type: Transportation, Storage, Distribution, Inventory Management Technology: IoT Solutions, Blockchain Logistics, Advanced Analytics, Automation |
| Companies Covered | Kuehne + Nagel, DHL, Fructus Transport, NewCold Logistics, DB Schenker, Artrans Transport, Yusen Logistics, Raben Group, Arra Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Cold Chain Logistics Market Evolving Landscape
Automation and refrigerant chemistry are converging to reshape capital deployment patterns across Polish temperature-controlled logistics, with regulatory pressure acting as the primary accelerant rather than market pull alone.
Automated high-bay frozen storage is consolidating market share in Poland's cold chain value pool. Pan-European retail chains are commissioning 40-meter rack systems with satellite shuttle technology for pallet retrieval. This consolidation is compressing the viability of conventional forklift-operated warehouses near Warsaw and Łódź.
EU F-Gas Regulation enforcement is tightening refrigerant compliance timelines for existing Polish warehouse operators. Industrial consequence includes accelerated amortization of HFC-based equipment and mandatory leak detection system installation. Pharmaceutical shippers are responding by auditing carrier refrigerant transition plans before contract renewal.
Shipper consolidation around integrated logistics providers is displacing fragmented broker networks in Poland's temperature-controlled freight market. Food manufacturers are aggregating frozen, chilled, and ambient distribution under single-source contracts with asset-heavy operators. This pattern is most visible in the Mazowieckie Voivodeship, where dairy processors have halved their carrier base since 2022.
Poland Cold Chain Logistics Market Segmentation
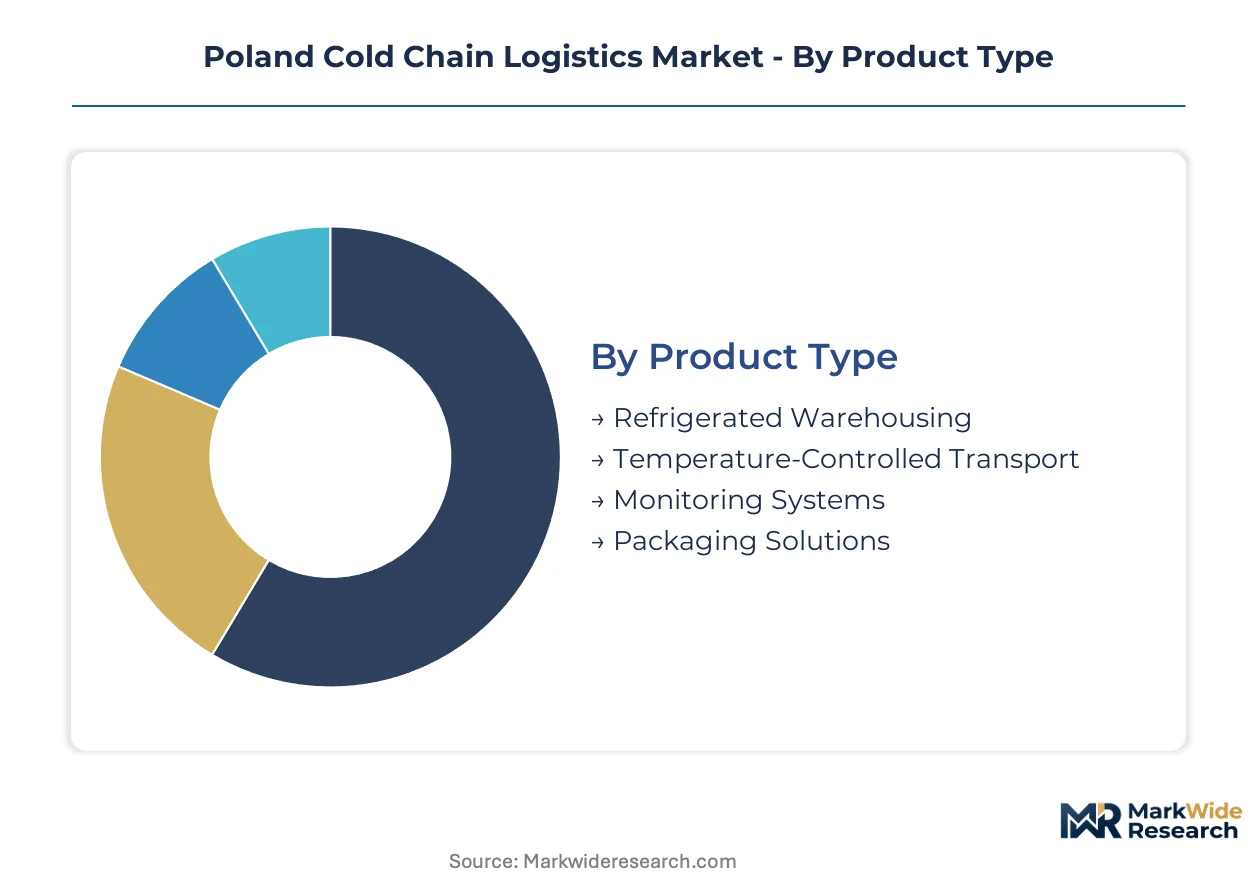
Poland's cold chain logistics market fragments across four dimensions that determine capital deployment and margin capture. Product type dictates infrastructure intensity, while end-user specifications shape compliance architecture. Service and technology choices separate asset-heavy integrators from software-enabled specialists competing for pharmaceutical and retail contracts.
Product Type:
Capital intensity and land scarcity near the Warsaw-Łódź corridor drive buyer priorities across storage and transport assets.
- Refrigerated Warehousing:Automated high-bay facilities with ammonia-CO2 cascade refrigeration dominate new builds near Silesian logistics parks. EU F-Gas Regulation phase-down schedules are accelerating HFC equipment retirement, compressing returns for conventional rack-clad warehouses around Kraków-Balice.
- Temperature-Controlled Transport:Multi-temperature trailers with electric vapor-compression units serve pharmaceutical distribution networks requiring validated temperature bands between minus 25°C and plus 8°C. ATP certification density constraints limit fleet expansion during peak berry and dairy harvest windows in Podlaskie.
- Monitoring Systems:Real-time telemetry with EU GDP-compliant data logging anchors pharmaceutical shipper contracts.
- Packaging Solutions:Phase-change materials and insulated containers address last-mile gaps in Warmia-Mazury's underpenetrated cold chain.
Volume sits with refrigerated warehousing; growth tilts toward monitoring systems.
End User:
Regulatory stringency and product value density determine service premiums and contract duration.
- Pharmaceuticals:Vaccine and biologics distribution mandates validated cold chains with continuous temperature documentation under Poland's Chief Sanitary Inspectorate protocols. GDP compliance requirements are consolidating carrier relationships around integrated logistics providers with dedicated pharmaceutical licenses.
- Food & Beverage:Frozen retail consolidation by pan-European grocery chains is pulling automated pallet handling capacity into Mazowieckie Voivodeship distribution centers.
- Biotechnology:Cell and gene therapy logistics require cryogenic storage below minus 150°C.
- Floral:Seasonal rose and tulip exports from central Poland demand rapid pre-cooling and controlled atmosphere transport.
Revenue concentrates in pharmaceuticals; expansion accelerates fastest in biotechnology.
Service Type:
Asset control depth separates integrated operators from fragmented broker networks competing on spot pricing.
- Transportation:Fleet ownership with ATP-certified drivers commands premium rates during agricultural harvest peaks. Battery-electric refrigerated trials in Kraków's low-emission zone are testing zero-emission last-mile economics.
- Storage:Automated high-bay frozen facilities with satellite shuttle retrieval systems capture multi-year contracts from retail consolidators. Land scarcity near Warsaw Modlin has elevated greenfield premiums for temperature-controlled builds.
- Distribution:Multi-temperature cross-docking at Silesian logistics parks enables consolidated frozen, chilled, and ambient freight.
- Inventory Management:WMS integration with predictive maintenance modules remains challenging for mid-sized operators with legacy ERP architectures.
Margins favor storage; contract velocity is climbing fastest in inventory management.
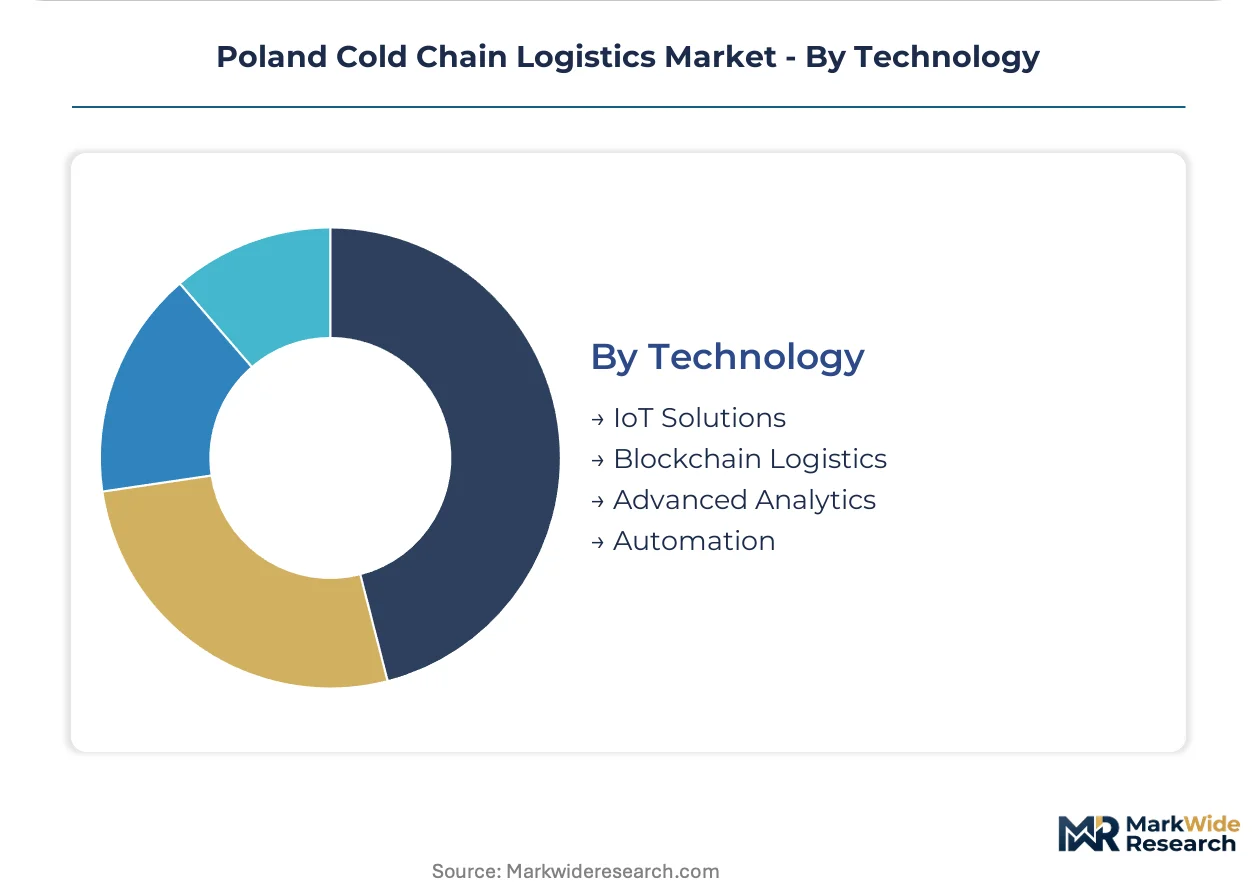
Technology:
Regulatory disclosure mandates and pharmaceutical traceability requirements are forcing technology adoption ahead of pure ROI thresholds.
- IoT Solutions:Sensor networks with continuous temperature, humidity, and location tracking underpin EU GDP compliance for vaccine shipments. Poland's Chief Sanitary Inspectorate audits are validating telemetry accuracy before license renewal.
- Automation:40-meter rack systems with satellite shuttle technology consolidate pallet retrieval in pan-European retail distribution centers. Technician shortages for ammonia system maintenance constrain deployment speed.
- Blockchain Logistics:Immutable chain-of-custody records address pharmaceutical traceability requirements.
- Advanced Analytics:Predictive maintenance modules reduce compressor downtime in high-bay warehouses.
Deployment concentrates in IoT solutions; automation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland's Special Economic Zones (SEZ) program accelerates cold chain concentration through tax relief and land cost subsidies, drawing pan-European retail distribution investment into designated logistics corridors. These zones compress project timelines for automated warehouse builds while aligning with EU Cohesion Fund infrastructure priorities.
Mazowieckie Voivodeship
Warsaw-Łódź corridor demand concentrates around pharmaceutical GDP compliance and vaccine distribution networks. Poland's Chief Sanitary Inspectorate enforces validated temperature documentation for biologics shipments. Silesian logistics parks absorb frozen retail consolidation through multi-temperature cross-docking facilities near Katowice.
Małopolskie Voivodeship
Kraków-Balice airport zone drives perishable air cargo pre-cooling and floral export infrastructure for central Polish rose and tulip producers. EU F-Gas Regulation refrigerant phase-down deadlines pressure conventional rack-clad warehouse operators. NewCold Logistics anchors automated high-bay frozen storage serving continental grocery chains.
Podlaskie Voivodeship
Dairy and berry production regions generate unmet demand for pre-cooling and frozen storage infrastructure during peak harvest windows. ATP certification density limits constrain temperature-controlled road capacity expansion. Białystok regional hub development offers first-mover positioning for cold storage investors.
Wielkopolskie Voivodeship
Poznań logistics cluster integrates with German distribution networks for automotive and food manufacturing supply chains. EU Green Deal energy efficiency disclosures incentivize solar-integrated refrigeration in new warehouse builds. Raben Group operates multi-temperature fleet services for regional pharmaceutical clients.
Pomeranian Voivodeship
Gdańsk port corridor handles Baltic seafood imports and re-exports requiring rapid cold chain transfer. Battery-electric refrigerated transport trials test zero-emission last-mile economics in urban low-emission zones. DHL sustains temperature-controlled warehouse networks serving northern pharmaceutical distribution.
Poland Cold Chain Logistics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated logistics providers capturing pharmaceutical contracts while regional fleet operators dominate agricultural spot markets. The vendor base concentrates around asset-heavy warehouse operators with ammonia-CO2 cascade systems and multi-temperature transport specialists with ATP-certified driver networks. Three archetypes define positioning: pan-European integrators with pharmaceutical licenses, regional multi-temperature fleet operators, and automated storage specialists with satellite shuttle technology. Competitive moves center on M&A consolidation of fragmented broker networks and capacity expansion into underpenetrated eastern regions.
Among pan-European integrators, Kuehne + Nagel and DB Schenker occupy positions anchoring pharmaceutical GDP-compliant distribution, while DHL exemplifies the scale-driven warehouse network archetype near Warsaw. Regional specialists include Raben Group, which sits within the multi-temperature fleet tier serving pharmaceutical and food clients across Poland's logistics corridors.
| Leading Market Players |
|---|
| Kuehne + Nagel |
| DHL |
| Fructus Transport |
| NewCold Logistics |
| DB Schenker |
| Artrans Transport |
| Yusen Logistics |
| Raben Group |
| Arra Group |
| Others |
Value Network & Pricing Analysis
Captive ammonia-CO2 cascade refrigeration systems anchor both supply security and pricing power for automated warehouse operators near Warsaw and Łódź, insulating asset-heavy incumbents from HFC refrigerant cost volatility while compressing margins for conventional rack-clad competitors dependent on spot refrigerant markets.
Pricing Analysis
Short lead-time premiums for pharmaceutical GDP-compliant warehousing separate pricing tiers across the Polish cold chain, with validated temperature documentation and continuous telemetry commanding contract premiums against spot-market frozen storage rates. Price differentiation hinges on EU F-Gas Regulation refrigerant transition status and ATP certification density for transport fleets. Cost compression in conventional HFC-dependent warehousing is intensifying because quota-phase-down schedules have tripled R-404A replacement expenses. Food manufacturers show highest price sensitivity during harvest windows, while vaccine distributors accept premium rates for validated cold chains.
Supply Chain Analysis
Single-source vulnerability sits with German and Italian compressor manufacturers supplying ammonia-CO2 cascade systems to Polish automated warehouse builds. Equipment procurement draws from Denmark, Germany, and Italy for refrigeration machinery, with domestic Polish fabrication limited to insulated panel assemblies. Supply chain risk centers on EU F-Gas Regulation enforcement timelines compressing installation windows for natural refrigerant conversions. Distribution runs through Silesian logistics parks for pan-European retail consolidation, with last-mile fragmentation in eastern voivodeships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poland's cold chain operates as a supply-constrained market where land scarcity near Warsaw-Łódź transport corridors props pricing power for incumbent automated warehouse operators.
For Market Incumbents: Anchor pharmaceutical GDP compliance capabilities through Chief Sanitary Inspectorate license renewal investments, defending against integrated logistics providers consolidating carrier relationships. Prioritize ammonia-CO2 cascade system maintenance contracts to lock in technician capacity amid vocational training pipeline shortages. Expand satellite shuttle automated storage capacity in Silesian logistics parks before greenfield land premiums escalate further. For New Entrants and Emerging Players: Battery-electric refrigerated transport trials offer a technology-first wedge into Kraków's low-emission zone enforcement perimeter, bypassing ATP certification density constraints plaguing conventional fleet expansion. Target Podlaskie and Warmia-Mazury dairy pre-cooling infrastructure gaps with modular cold storage units. Lead with EU CSRD Scope 3 emissions reporting compliance as the go-to-market angle for food manufacturers sourcing certified green cold chain partners. For Investors and Strategic Acquirers: Exit pathways concentrate in pan-European retail distribution center consolidation plays and pharmaceutical logistics platform roll-ups. Mid-term viability through the projection horizon rests on natural refrigerant conversion completion rates and automation deployment speed. Watch ammonia system technician training program expansion as the inflection signal for cascade refrigeration deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Ammonia-CO2 Cascade System Conversion | EU F-Gas Regulation compliance insulates operators from HFC quota cost volatility. |
| Automated High-Bay Warehouse Expansion | 40-meter rack systems with satellite shuttle technology capture multi-year retail contracts. |
| Pharmaceutical GDP License Investment | Chief Sanitary Inspectorate validation opens vaccine and biologics distribution networks. |
| Battery-Electric Fleet Pilot Programs | Zero-emission trials in Kraków's low-emission zone test last-mile economics ahead of mandate expansion. |
| Eastern Regional Hub Development | Podlaskie and Warmia-Mazury dairy infrastructure gaps offer first-mover positioning. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted among cold storage facility managers, pharmaceutical logistics directors, ATP-certified transport operators, and refrigeration system technicians. Bottom-up capacity modeling triangulated against top-down EU F-Gas Regulation phase-down schedules and Poland's Chief Sanitary Inspectorate licensing databases. Secondary sources included EU ECHA refrigerant quota disclosures, Polish Central Statistical Office industrial production indices, and customs records for refrigeration machinery imports.
Data-stream reconciliation across facility-level capacity surveys, fleet operator ATP certification registries, and pharmaceutical shipper contract disclosures generated volume and value estimates across the analysis window. Segmentation dimensions modeled encompassed product type, end-user regulatory stringency, service asset intensity, and technology adoption tier. CAGRs derived from facility investment pipelines, refrigerant transition cost curves, and pharmaceutical distribution network expansion plans. Industry-specific forecast inputs included EU Green Deal energy efficiency disclosure timelines and ammonia system technician training graduation rates.
Several conditions sit outside the modeled scope, including unannounced EU F-Gas Regulation enforcement acceleration, unexpected refrigerant technology breakthroughs, and geopolitical disruptions to compressor equipment supply chains. Forecasts reflect documented assumptions regarding regulatory adherence schedules and capital deployment patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Tanker Shipping Market
Logistics and Shipping
First and Last Mile Delivery Market
Logistics and Shipping
Central and Eastern Europe Cold Chain Logistics Market
Logistics and Shipping
Finished Vehicle Logistics Market
Logistics and Shipping
North America Shipping Agency Market
Logistics and Shipping
Philippines Freight and Logistics Market
Logistics and Shipping
Event Logistics Market
Logistics and Shipping
Czech Republic Third-Party Logistics Market
Logistics and Shipping
ASEAN Warehousing and Distribution Logistics Market
Logistics and Shipping
Express Delivery Market
Logistics and Shipping
Slovakia Freight and Logistics Market
Logistics and Shipping
North America Last Mile Delivery Market
Logistics and Shipping
Australia Freight Forwarding Market
Logistics and Shipping
UAE Logistics Market
Logistics and Shipping
North America Cargo Inspection Market
Logistics and Shipping
New York Freight and Logistics Market