
 Spare Part Logistics Market | 2026-2036
Spare Part Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Spare Part Logistics Market Analytics
Market Context
OEM-grade parts certification is redrawing competitive boundaries in spare part logistics. DHL Group leverages its global pharmaceutical and automotive cold-chain infrastructure to dominate same-day critical component deliveries across European manufacturing corridors. FedEx Supply Chain anchors its position through proprietary SenseAware monitoring technology that sustains temperature and shock documentation for aerospace and medical device spares. UPS Supply Chain Solutions competes by extending its Parts Fast network into secondary metropolitan zones, occupying a niche between premium emergency response and scheduled maintenance logistics.
Technical Definition and Structural Segments
Spare part logistics encompasses the specialized movement, storage, and fulfillment of replacement components required to maintain or restore capital equipment, vehicles, and industrial machinery to operational status, with critical performance parameters including order accuracy above 99.5 percent, pick-to-ship cycle times under four hours for emergency tiers, and reverse logistics capability for core returns and warranty exchanges. Delivery services lead the service type dimension due to the premium placed on velocity, while inventory management represents the fastest-growing segment as predictive analytics reduce safety stock requirements. Within end users, manufacturers command the largest volume flows, though e-commerce channels are capturing margin pools by disintermediating traditional dealer networks for standard consumables.
Regulatory Frame and Outlook
The EU Green Deal and REACH compliance frameworks are reshaping packaging, transport mode selection, and cross-border documentation for chemical and hazardous material spares moving through European distribution channels. In the United States, NHTSA recall protocols and FAA airworthiness directives mandate traceable chain-of-custody records that elevate technology requirements across RFID and cloud computing segments. Japan's METI circular economy guidelines and China's GB standards for remanufactured components are creating divergent compliance obligations that logistics providers must navigate simultaneously. Stakeholders should monitor how carbon border adjustment mechanisms redefine cost structures for long-haul spare part movements before committing to regional hub placement.
Market Dynamics
IoT-enabled inventory tracking systems are compressing safety stock requirements while simultaneously elevating service-level expectations, forcing logistics providers to reconfigure warehouse automation and last-mile dispatch protocols.
Growth Catalysts
- EU Green Deal compliance:Packaging and transport mode mandates for hazardous material spares are accelerating investment in multimodal European distribution corridors.
- Predictive maintenance analytics:Industrial manufacturers are embedding sensor networks that trigger automated parts replenishment before failure events occur.
- Germany:Dense automotive manufacturing clusters with just-in-time supply requirements are concentrating demand for same-day critical component delivery.
Market Restraints
- Lithium-ion battery volatility:Thermal runaway risks in EV spare part shipments are elevating insurance premiums and packaging certification costs.
- Semiconductor supply concentration:Taiwan and South Korea fabrication bottlenecks are extending lead times for electronic control module replacements.
- REACH documentation friction:Cross-border chemical spare movements face extended customs clearance timelines due to substance registration verification requirements.
Strategic Opportunities
- India aftermarket expansion:PLI scheme incentives for domestic automotive manufacturing are creating parallel demand for localized spare part fulfillment infrastructure.
- Drone delivery corridors:FAA Part 135 certification pathways for beyond-visual-line-of-sight operations are opening rural and remote industrial site access.
- AI-driven demand sensing:Machine learning platforms that integrate equipment telemetry with weather and operational data are compressing forecast error rates.
Industry Challenges
- Warehouse robotics integration:Retrofitting legacy distribution centers with autonomous mobile robots requires substantial facility downtime and workforce retraining.
- OEM-grade certification timelines:ISO/TS 16949 quality system audits for aftermarket parts suppliers extend supplier onboarding cycles by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spare Part Logistics Market |
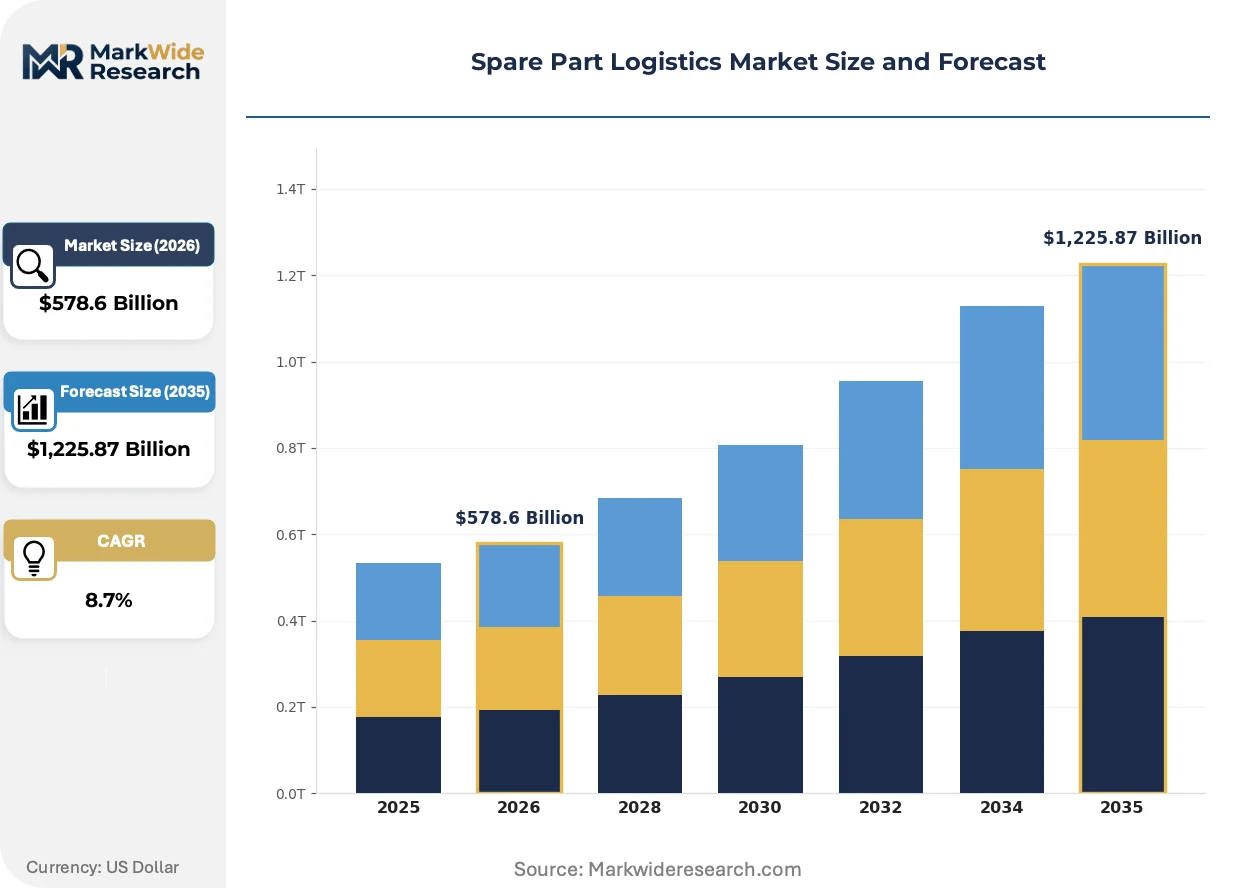
| Market Size in 2026 | $578.6 Billion |
| Market Size in 2035 | $1,225.87 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Delivery, Warehousing, Inventory Management, Order Fulfillment End User: Manufacturers, Distributors, Retailers, E-Commerce Technology: RFID, Barcode Scanning, Automation, Cloud Computing Distribution Channel: Direct Sales, Online Platforms, Third-Party Logistics, Dealer Networks |
| Companies Covered | UPS Supply Chain Solutions, DSV, DHL Group, XPO Logistics, FedEx Supply Chain, Kuehne + Nagel, CEVA Logistics, Nippon Express, DB Schenker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spare Part Logistics Market Evolving Landscape
Digital twin technology is merging with physical fulfillment networks, creating synchronized inventory visibility that collapses the gap between planned maintenance schedules and actual parts availability.
Autonomous mobile robots with vision-based picking capabilities are displacing manual warehouse labor in high-SKU spare part operations. Tier-one automotive suppliers are deploying these systems across European regional distribution centers. The technology is displacing traditional zone-picking workflows by enabling dynamic batch consolidation that reduces order cycle times.
REACH chemical substance restrictions are forcing logistics providers to segregate hazardous spare inventories into dedicated climate-controlled zones. Industrial chemical distributors must now maintain dual stock-keeping units for compliant and non-compliant formulations. The regulation most heavily impacts cross-border movements between Germany and Eastern European manufacturing zones, where providers are establishing bonded warehouse arrangements.
Maintenance service unbundling is fragmenting historical dealer-captive parts relationships. Fleet operators are sourcing consumables directly through B2B marketplaces while reserving critical component relationships with OEM-authorized channels. This bifurcation is most pronounced in North American commercial vehicle segments, where telematics-enabled usage tracking supports dynamic procurement decisions.
Spare Part Logistics Market Segmentation
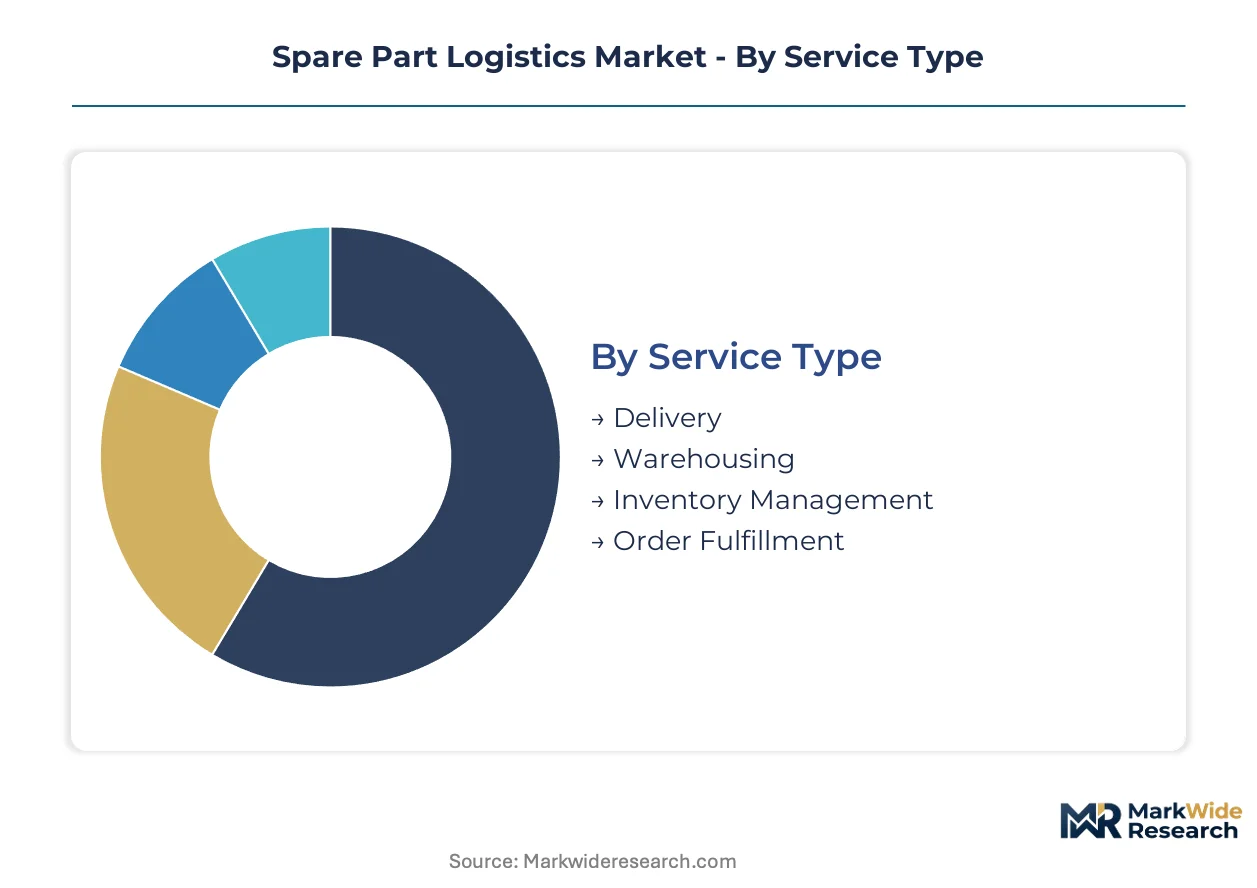
Spare part logistics operators configure service portfolios around velocity tiers and inventory criticality. Segment boundaries shift as predictive maintenance contracts bundle fulfillment with technical support, compressing standalone warehousing margins.
Service Type:
Domestic networks anchor scheduled maintenance flows, while export corridors concentrate emergency response capabilities near manufacturing clusters.
- Delivery:Time-definite transportation modes ranging from same-day courier to scheduled LTL, with temperature-controlled vehicles handling chemical and electronic components. Automotive corridors in Germany and aerospace hubs in France concentrate premium emergency capacity as just-in-time contracts mandate sub-four-hour response windows.
- Inventory Management:Sensor-enabled stock positioning, demand forecasting, and safety stock optimization across distributed node networks. Predictive analytics adoption is compressing buffer requirements while elevating service-level guarantees in industrial manufacturing.
- Warehousing:Climate-controlled storage with bonded status for cross-border duty deferral.
- Order Fulfillment:Pick-pack-ship operations with kitting and sequencing for assembly line replenishment.
Delivery commands the established base. The steepest expansion runs through Inventory Management.
End User:
Procurement sophistication varies sharply across buyer categories, with volume concentration dictating contract structures and technology integration depth.
- Manufacturers:Captive production facilities and tier-one suppliers requiring sequenced line-side delivery and vendor-managed inventory programs. German automotive OEMs and Japanese precision equipment makers drive standardization of EDI-triggered automatic replenishment.
- E-Commerce:Digital marketplaces disintermediating traditional dealer networks for standard consumables and non-critical replacement parts. Fleet operators in North America are shifting brake pad and filter procurement to B2B platforms with telematics-validated fitment.
- Distributors:Independent intermediaries consolidating fragmented supplier bases for regional coverage.
- Retailers:Brick-and-mortar parts counters serving walk-in trade and service bay customers.
Manufacturers retain the volume anchor. E-Commerce is climbing the fastest.
Technology:
Capital deployment intensity separates legacy operators from digitally native competitors, with cloud infrastructure enabling network effects at scale.
- RFID:Passive and active radio-frequency identification enabling real-time location tracking without line-of-sight requirements. REACH-mandated chemical segregation in EU distribution centers is accelerating tag deployment for hazardous material lot traceability.
- Cloud Computing:Distributed data architectures synchronizing inventory visibility across multi-node networks. Tier-one providers are migrating warehouse management systems to SaaS platforms that collapse deployment timelines for new facility onboarding.
- Barcode Scanning:Linear and 2D symbology for discrete item identification and verification.
- Automation:Robotic picking, sortation, and autonomous vehicle systems for labor substitution.
RFID holds the installed base. Cloud Computing is gaining share fastest.
Distribution Channel:
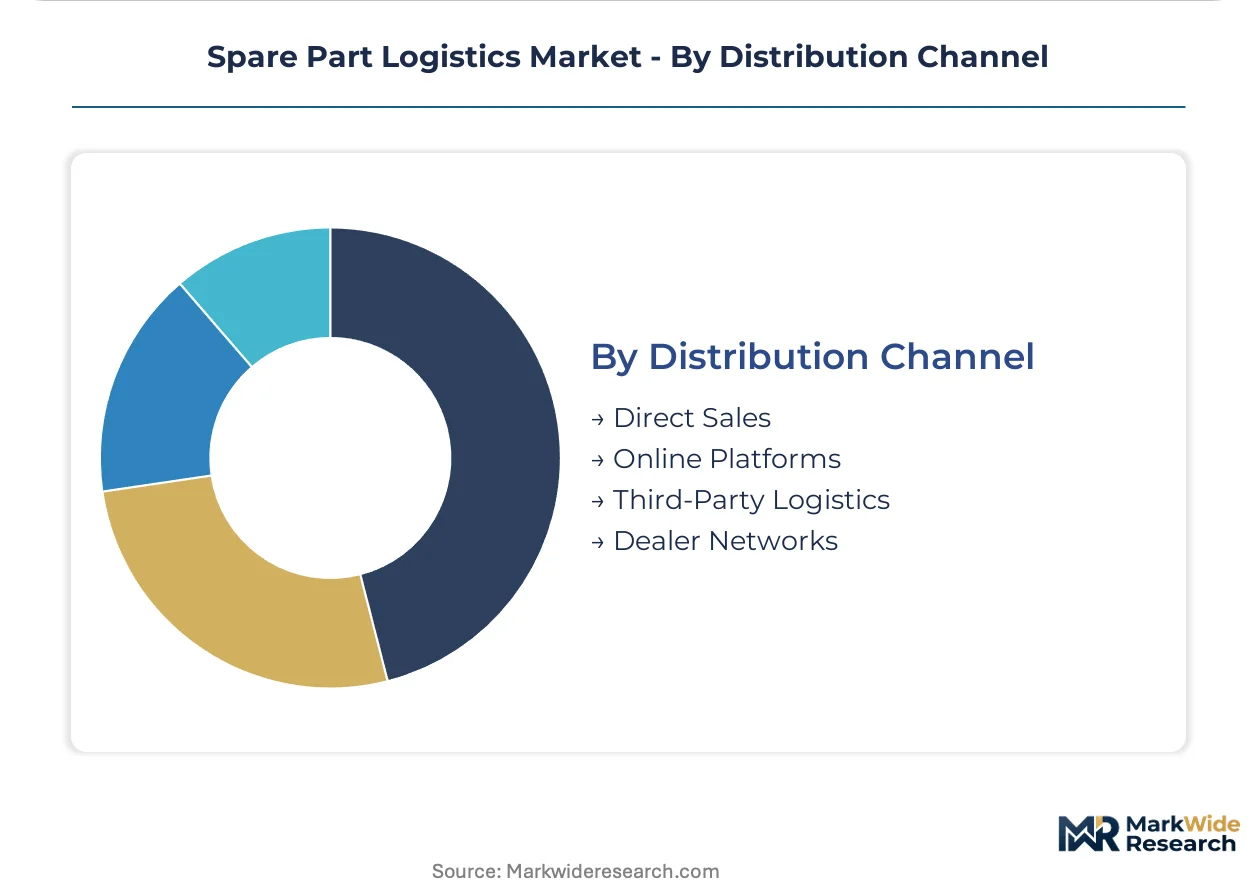
Channel selection determines margin capture and customer ownership, with direct relationships commanding premium pricing for critical components.
- Third-Party Logistics:Outsourced operators managing integrated transportation, warehousing, and fulfillment under long-term contracts. DHL Group and Kuehne+Nagel are anchoring European automotive corridors with dedicated parts campuses near Stuttgart and Munich.
- Online Platforms:Digital marketplaces aggregating supplier catalogs with search, comparison, and fulfillment orchestration. India's B2B spare part exchanges are expanding under PLI scheme manufacturing incentives that create parallel aftermarket demand.
- Direct Sales:Manufacturer-controlled channels for proprietary and warranty-critical components.
- Dealer Networks:Authorized intermediaries with exclusive territories and technical certification requirements.
Third-Party Logistics controls the revenue base. Online Platforms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in critical component flows are reshaping regional hub placement strategies. Germany and the United States run structural deficits in semiconductor-dependent spares, while China and Mexico concentrate outbound manufacturing shipments. Logistics providers are repositioning inventory forward to compress customs clearance exposure.
Germany
Automotive OEMs in Stuttgart and Munich mandate sub-four-hour emergency parts response under just-in-time contracts. The EU Green Deal REACH framework imposes hazardous material segregation requirements on cross-border chemical spare movements. The Rhine-Ruhr corridor hosts dedicated parts campuses where DHL Group and Kuehne+Nagel operate bonded warehouses for Eastern European manufacturing zones.
United States
NHTSA recall protocols and FAA airworthiness directives elevate chain-of-custody documentation requirements for automotive and aerospace spares. The IRA domestic content provisions are accelerating reshoring of battery and electronic component logistics infrastructure. Detroit and Dallas-Fort Worth anchor competing automotive and aerospace spare part distribution networks with divergent temperature-control specifications.
China
GB standards for remanufactured components and dual carbon goals are bifurcating domestic spare part certification pathways. MIIT regulations mandate traceable lot records for industrial machinery replacement parts. The Yangtze River Delta concentrates electronics spare production, while Pearl River Delta logistics providers manage outbound automotive component flows to Southeast Asian assembly plants.
India
PLI scheme incentives for domestic automotive and electronics manufacturing are creating parallel aftermarket demand for localized fulfillment infrastructure. BIS quality certification requirements extend supplier onboarding timelines for imported spare components. Maharashtra and Tamil Nadu automotive clusters are attracting third-party logistics investment for sequenced line-side delivery contracts.
Japan
METI circular economy guidelines prioritize remanufactured component flows over virgin spare production. Precision equipment makers in Nagoya and Osaka drive standardization of EDI-triggered automatic replenishment systems. Kyushu semiconductor fabrication concentration creates specialized logistics demand for clean-room compatible spare part transportation.
Spare Part Logistics Market Competitive Landscape
Concentration sits with integrated global networks possessing dedicated automotive and aerospace infrastructure. Three tiers structure competitive positioning: multinational parcel carriers with captive air freight capacity, European road-rail specialists with bonded warehouse networks, and Asia-Pacific freight forwarders leveraging manufacturing proximity. M&A activity targets last-mile technology platforms, while capacity expansion focuses on climate-controlled regional campuses near German and US manufacturing clusters.
Among integrated parcel carriers, UPS Supply Chain Solutions, DHL Group, and FedEx Supply Chain exemplify the premium emergency response archetype. DHL Group leverages pharmaceutical and automotive cold-chain infrastructure across European manufacturing corridors. FedEx Supply Chain anchors positioning through proprietary monitoring technology for temperature-sensitive aerospace and medical device spares. UPS Supply Chain Solutions occupies the niche between premium emergency response and scheduled maintenance logistics through network extension into secondary metropolitan zones.
| Leading Market Players |
|---|
| UPS Supply Chain Solutions |
| DSV |
| DHL Group |
| XPO Logistics |
| FedEx Supply Chain |
| Kuehne + Nagel |
| CEVA Logistics |
| Nippon Express |
| DB Schenker |
| Others |
Value Network & Pricing Analysis
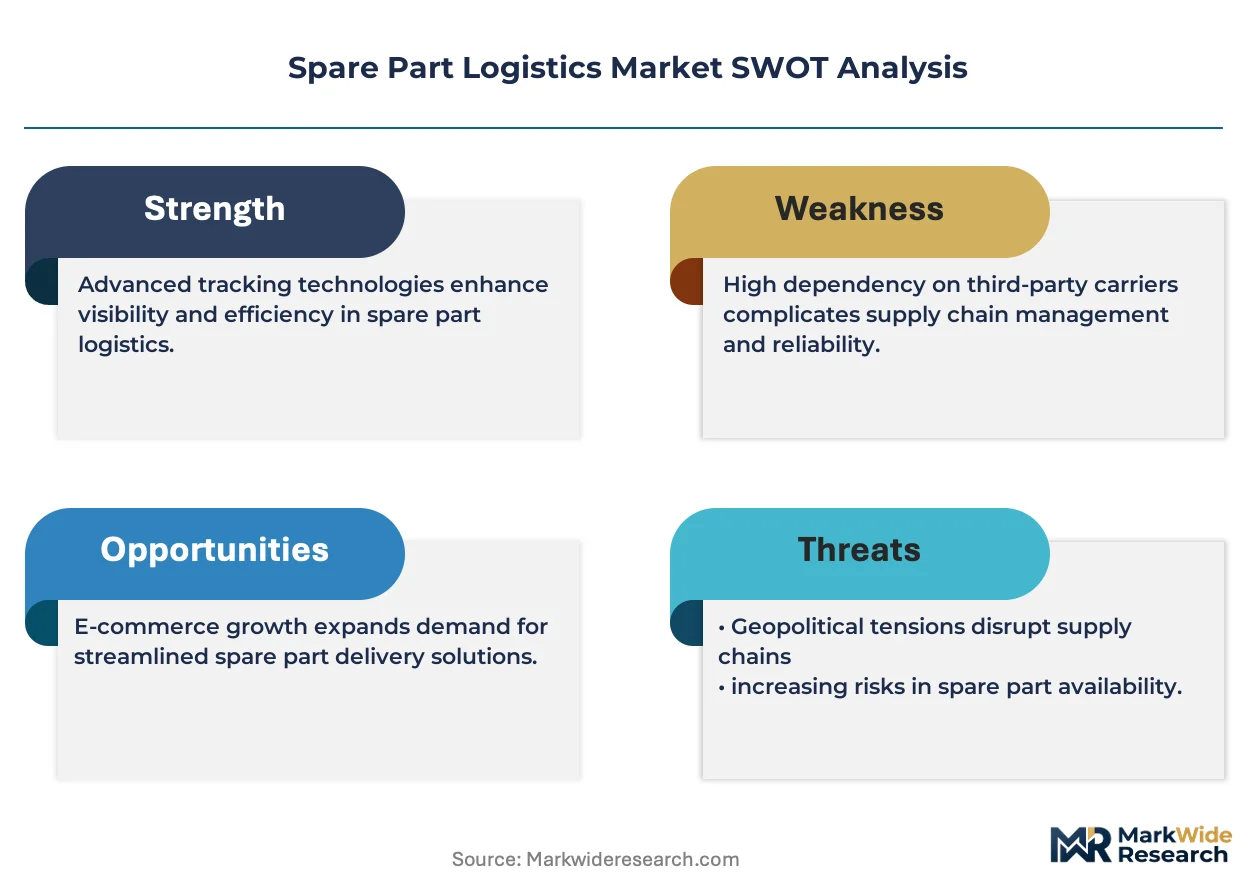
EU Green Deal REACH compliance gates supplier qualification and price differentiation simultaneously, forcing hazardous material handlers to absorb segregation infrastructure costs while OEM-grade certification unlocks premium tiers for same-day automotive corridors.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Certification grade and volume scale drive price differentiation, with ISO/TS 16949-audited suppliers commanding substantial premiums over uncertified competitors. Cost compression in the economy tier is intensifying because e-commerce marketplaces disintermediate traditional dealer networks for consumables. Fleet operators exhibit highest price sensitivity for standard brake pads and filters, while aerospace maintenance departments show lowest sensitivity for airworthiness-critical components.
Supply Chain Analysis
Safety stock compression from IoT-enabled tracking is tethering inventory positioning to sub-four-hour response windows in German automotive clusters. Supply concentrates in Germany, China, and Mexico for precision-engineered components, with semiconductor-dependent modules drawing from Taiwan and South Korea fabrication. Lithium-ion battery thermal runaway risks present single-source vulnerability for EV spare shipments. Distribution runs through bonded regional campuses near Stuttgart and Dallas-Fort Worth, with last-mile courier networks handling emergency tier fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting as B2B marketplaces disintermediate dealer-captive relationships, with telematics-validated fitment data creating interoperability standards that collapse search costs for fleet procurement.
For Market Incumbents: Compound cold-chain infrastructure advantages into predictive maintenance contracts that bundle fulfillment with sensor-triggered replenishment. Defend against e-commerce disintermediation by deepening ISO/TS 16949 certification barriers and securing exclusive line-side delivery agreements with German OEMs.
For New Entrants and Emerging Players: Anchor in India's PLI-scheme aftermarket expansion, where localized fulfillment infrastructure lags domestic manufacturing growth. Target Maharashtra and Tamil Nadu automotive clusters with sequenced delivery capabilities. Pursue drone corridor certification under FAA Part 135 pathways for rural industrial site access.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across warehouse robotics integration, favoring scaled operators with SaaS-deployed warehouse management systems. Long-term viability centers on cloud-native platforms enabling network effects across multi-node inventory visibility. Target autonomous mobile robot technology providers as acquisition archetype. Monitor carbon border adjustment mechanism announcements as inflection indicator for regional hub repositioning economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Contracting | Bundles sensor-triggered replenishment with fulfillment, compressing standalone warehousing margins. |
| Warehouse Robotics Integration | Vision-based picking systems displace manual labor in high-SKU European regional distribution centers. |
| Drone Delivery Certification | FAA Part 135 pathways unlock beyond-visual-line-of-sight access to remote industrial sites. |
| Bonded Warehouse Expansion | Eastern European manufacturing zones require REACH-compliant hazardous material segregation infrastructure. |
| Cloud Platform Migration | SaaS warehouse management systems collapse deployment timelines for new facility onboarding. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC logistics provider filings, automotive production databases, and EU regulatory registries. Logistics provider operations executives, OEM procurement directors, aftermarket distributor channel managers, and warehouse automation engineers contributed structured interviews. Bottom-up service-type demand modeling triangulates against top-down regional consumption estimates.
Segmentation dimensions modeled span service type, end user category, technology deployment, and distribution channel across the analysis window. CAGRs derive from fitted growth curves applied to historical volume trajectories, with predictive maintenance adoption rates and IoT sensor penetration serving as automotive-specific forecast inputs.
Material uncertainties — semiconductor supply concentration, lithium-ion battery shipping restrictions, carbon border adjustment implementation — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory stability and technology diffusion curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Italy Courier Market
Logistics and Shipping
Bangladesh Freight and Logistics Market
Logistics and Shipping
Big Data in Logistics Market
Logistics and Shipping
APAC Contract Logistics Market
Logistics and Shipping
North America Freight Forwarding Market
Logistics and Shipping
Logistics Automation Market
Logistics and Shipping
Malaysia Road Freight Transport Market
Logistics and Shipping
Australia Last Mile Delivery Market
Logistics and Shipping
Liquid Chemical Tanker Shipping Market
Logistics and Shipping
Chile Cold Chain Logistics Market
Logistics and Shipping
Japan E-Commerce Logistics Market
Logistics and Shipping
Australia Freight and Logistics Market
Logistics and Shipping
Autonomous Last Mile Delivery Market
Logistics and Shipping
United Kingdom Contract Logistics Market
Logistics and Shipping
Europe Domestic Courier Market
Logistics and Shipping
Russia Freight and Logistics Market