
 United States 3PL Market | 2026-2036
United States 3PL Market Size, Share, and Industry Trends Forecast 2026-2036
United States 3PL Market Analytics
Software-defined freight brokerage is restructuring how transportation capacity gets priced and procured in the United States 3PL market. C.H. Robinson leverages its digital freight-matching platform to sustain dominance in truckload intermediation. J.B. Hunt anchors intermodal volumes through controlled container and chassis assets across the domestic rail network. Amazon competes aggressively on fulfillment speed, operating proprietary last-mile infrastructure that bypasses traditional carrier networks.
Third-party logistics encompasses the outsourcing of supply chain functions—transportation, warehousing, inventory management, and value-added services—to specialized providers operating under contract. The sector relies on transportation management systems integrating real-time visibility, carrier scorecards, and automated tendering to coordinate freight movements across modes. Order fulfillment services lead revenue contribution as e-commerce merchants outsource pick-pack-ship operations to avoid fixed warehouse investments. Cloud-based solutions represent the fastest-growing technology segment as 3PLs deploy scalable platforms for client onboarding and network optimization without heavy on-premise infrastructure.
The Federal Motor Carrier Safety Administration enforces hours-of-service rules and electronic logging device compliance that constrain driver availability and push shippers toward brokered capacity. The Surface Transportation Board oversees rail rate reasonableness, affecting intermodal competitiveness against over-the-road alternatives. OSHA warehouse safety standards influence automation investment decisions as 3PLs balance labor costs with ergonomic compliance. Stakeholders must monitor how autonomous trucking pilots reshape driver economics and whether warehouse automation achieves payback thresholds before labor rate escalation accelerates.
Market Dynamics
Software-defined freight brokerage is compressing carrier procurement cycles and eroding traditional broker margins through algorithmic spot pricing and automated tendering workflows. The Federal Motor Carrier Safety Administration's electronic logging device mandate continues constraining driver hours and pushing shippers toward outsourced capacity management.
Growth Catalysts
- E-commerce fulfillment surge:Direct-to-consumer order volumes are forcing merchants to outsource pick-pack-ship operations rather than build fixed warehouse infrastructure. Retailers now require same-day and next-day delivery commitments that strain in-house logistics capabilities.
- Hours-of-service enforcement:FMCSA regulations limiting driver availability are accelerating demand for brokered capacity and intermodal alternatives that extend effective shipping windows through rail substitution.
- Cloud-based TMS deployment:Third-party logistics providers are adopting scalable software platforms that reduce client onboarding friction and enable network optimization without heavy capital expenditure.
Market Restraints
- Driver labor scarcity:The commercial driver shortage limits capacity expansion and inflates wage costs across over-the-road networks, constraining margin recovery for asset-light intermediaries.
- Chassis and container availability:Intermodal service quality depends on controlled equipment pools concentrated among major railroads and large asset-owning 3PLs, creating bottlenecks during volume spikes.
- Fuel price volatility:Diesel cost fluctuations directly impact linehaul economics and surcharge recovery mechanics, complicating long-term contract pricing for transportation management services.
Strategic Opportunities
- Mid-market warehouse automation:Robotic picking and sortation systems are reaching payback thresholds that enable 3PLs to serve smaller e-commerce merchants with competitive unit economics previously reserved for enterprise clients.
- Texas freight corridor densification:The Dallas-Fort Worth to Houston lane offers land availability and inland port infrastructure that supports distribution center clustering for central U.S. fulfillment.
- OSHA ergonomic compliance investment:Warehouse safety standards are accelerating automation deployment as 3PLs replace manual material handling with mechanized systems that reduce injury exposure and insurance costs.
Industry Challenges
- Transportation management system integration:Legacy shipper ERP architectures resist API-based connectivity, forcing expensive custom middleware development for real-time visibility and automated tendering.
- Autonomous trucking readiness:Regulatory frameworks for driverless commercial vehicle operation remain fragmented across state jurisdictions, delaying fleet modernization roadmaps and capital allocation decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States 3PL Market |
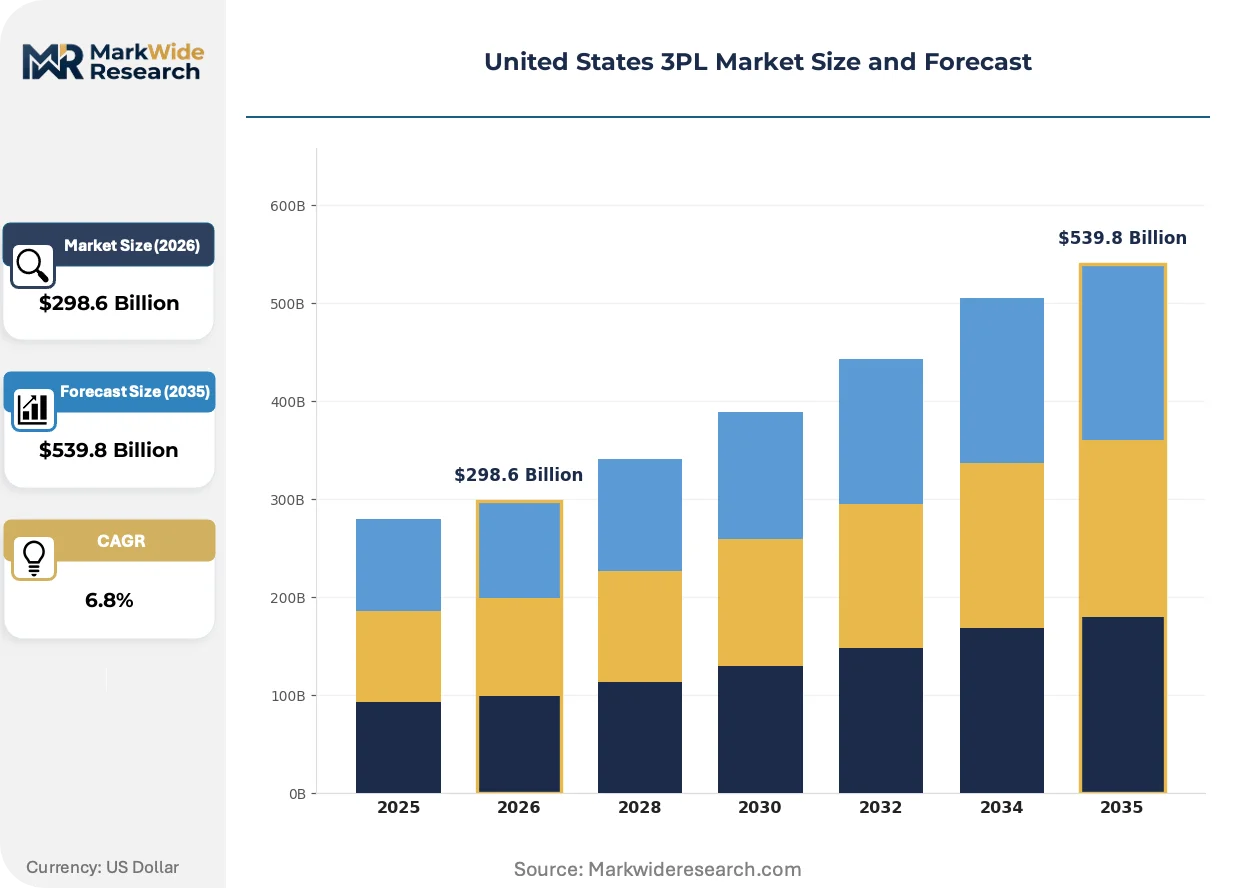
| Market Size in 2026 | $298.6 Billion |
| Market Size in 2035 | $539.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Order Fulfillment, Freight Forwarding End User: E-commerce, Retail, Automotive, Consumer Goods Technology: Cloud-Based Solutions, TMS, WMS, AI Analytics Distribution Channel: Direct, Indirect, Omni-Channel, B2B |
| Companies Covered | Amazon, C.H. Robinson, GXO Logistics, J.B. Hunt, UPS Supply Chain Solutions, Expeditors, Ryder Supply Chain Solutions, Kuehne + Nagel, DSV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States 3PL Market Evolving Landscape
Digital freight-matching platforms are restructuring how transportation capacity gets priced and procured, compressing the time between load posting and carrier acceptance from hours to minutes.
Autonomous mobile robots are automating warehouse pick-and-pack workflows through vision-guided navigation and collaborative human-robot station designs. E-commerce fulfillment centers are deploying these systems at accelerating pace to reduce labor dependency during peak season surges. The technology is automating inventory putaway and order consolidation tasks that previously required manual cart transport and scan verification.
The FMCSA electronic logging device mandate continues reshaping carrier compliance and capacity planning across interstate operations. Hours-of-service tracking enforcement has reduced effective driving windows and pushed freight toward intermodal rail alternatives for lanes exceeding 500 miles. Large shippers are responding by diversifying modal mix and extending lead time tolerances to access lower-cost rail options.
Merchant expectations for delivery speed are compressing fulfillment network design cycles and forcing 3PLs to position inventory closer to end consumers. Same-day and next-day service commitments are displacing traditional two-day standards as the baseline for competitive positioning. This shift concentrates demand for urban last-mile infrastructure in major metropolitan zones including Chicago, Los Angeles, and New York.
United States 3PL Market Segmentation
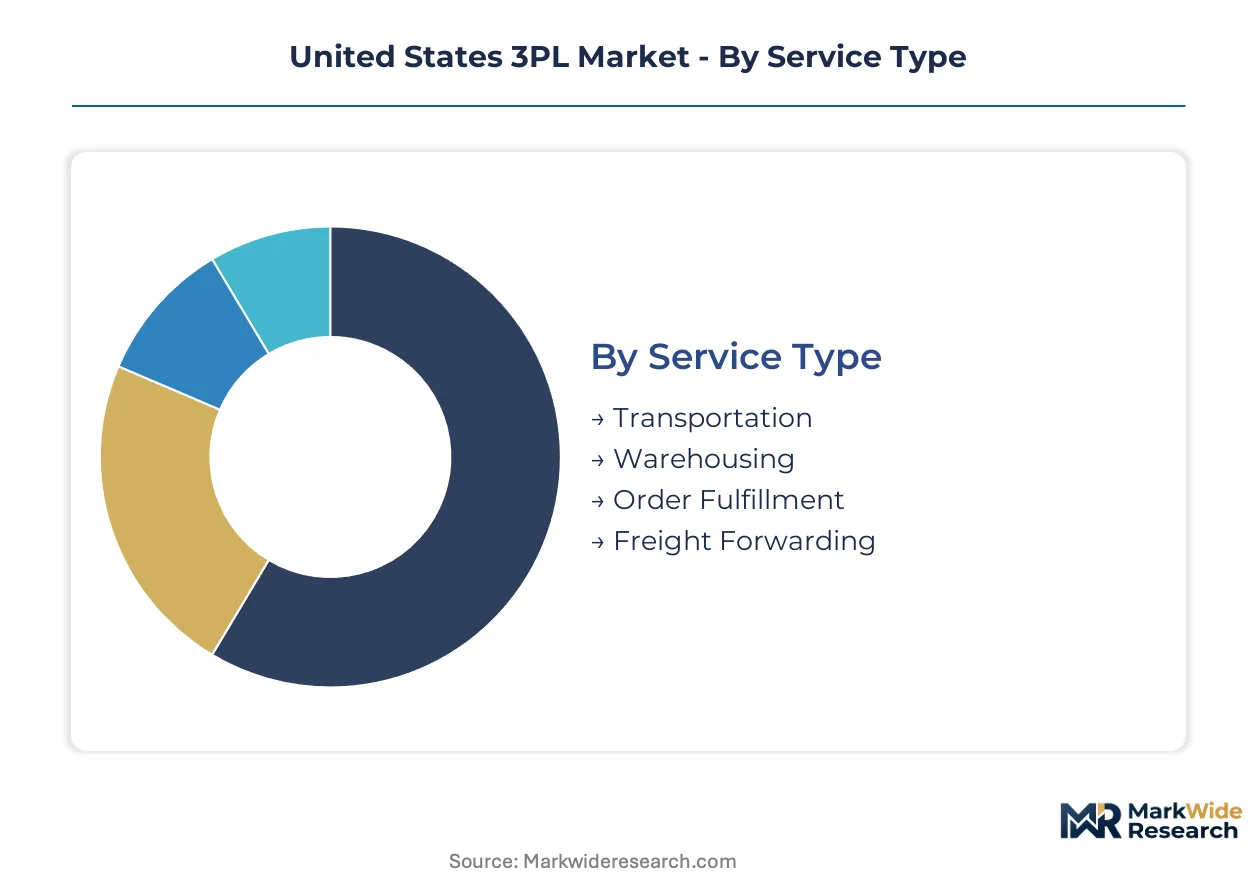
Segmentation in the United States 3PL market reveals how service specialization, technology adoption, and channel configuration determine competitive positioning. Each axis exposes distinct margin profiles and capital intensity requirements that shape provider strategy across the freight corridor from Dallas-Fort Worth to Houston.
Service Type:
Technology intensity varies sharply across service categories, with asset-light digital platforms commanding different economics than fixed-warehouse operations.
- Transportation:Truckload and less-than-truckload brokerage dominate transaction volumes. The FMCSA electronic logging device mandate compresses driver availability, pushing shippers toward outsourced capacity management and intermodal substitution for lanes exceeding 500 miles.
- Order Fulfillment:Pick-pack-ship operations for direct-to-consumer merchants require dense urban last-mile positioning. E-commerce volume concentration in Chicago, Los Angeles, and New York metro areas drives facility location decisions.
- Warehousing:Dedicated and shared-space contracts support inventory positioning strategies. OSHA ergonomic compliance is accelerating automation investment to reduce injury exposure and insurance costs.
- Freight Forwarding:International documentation and customs brokerage services coordinate cross-border movements. Demand concentrates among automotive and consumer goods importers sourcing through Gulf Coast ports.
Mature deployment sits with Transportation. Newer deployment is concentrated in Order Fulfillment.
End User:
Customer verticals exhibit divergent service-level requirements, with speed tolerance and order profile complexity determining 3PL selection criteria.
- E-commerce:Direct-to-consumer merchants require same-day and next-day delivery commitments. Amazon's proprietary last-mile infrastructure forces independent 3PLs to differentiate through flexible capacity and specialized handling.
- Retail:Omnichannel replenishment and store distribution demand seasonal surge flexibility. The Texas freight corridor supports central U.S. fulfillment positioning for mass merchants.
- Automotive:Just-in-time sequencing and inbound parts logistics require precision timing. FMCSA hours-of-service enforcement complicates long-haul component movements from Mexico-border assembly plants.
- Consumer Goods:High-velocity packaged goods need temperature-controlled and hazmat-certified handling capabilities. Cloud-based TMS deployment enables real-time visibility for brand owners.
Volume concentration sits with E-commerce. Margin expansion is concentrated in Automotive.
Technology:
Platform architecture choices determine scalability and integration friction with shipper ERP systems.
- Cloud-Based Solutions:Scalable SaaS platforms reduce client onboarding time and enable network optimization without heavy on-premise infrastructure. E-commerce merchants with variable demand patterns represent the primary adoption cohort.
- Transportation Management Systems (TMS):Real-time visibility, carrier scorecards, and automated tendering coordinate freight movements across modes. Legacy shipper ERP architectures resist API connectivity, forcing custom middleware development.
- Warehouse Management Systems (WMS):Inventory tracking and labor optimization modules support pick-pack-ship throughput targets. Autonomous mobile robot integration is automating putaway and order consolidation workflows.
- AI Analytics:Demand forecasting and dynamic routing algorithms improve asset utilization. Pilot deployments concentrate among large asset-owning 3PLs with sufficient data volume for model training.
Installed base concentration sits with TMS. Deployment velocity is climbing fastest in Cloud-Based Solutions.
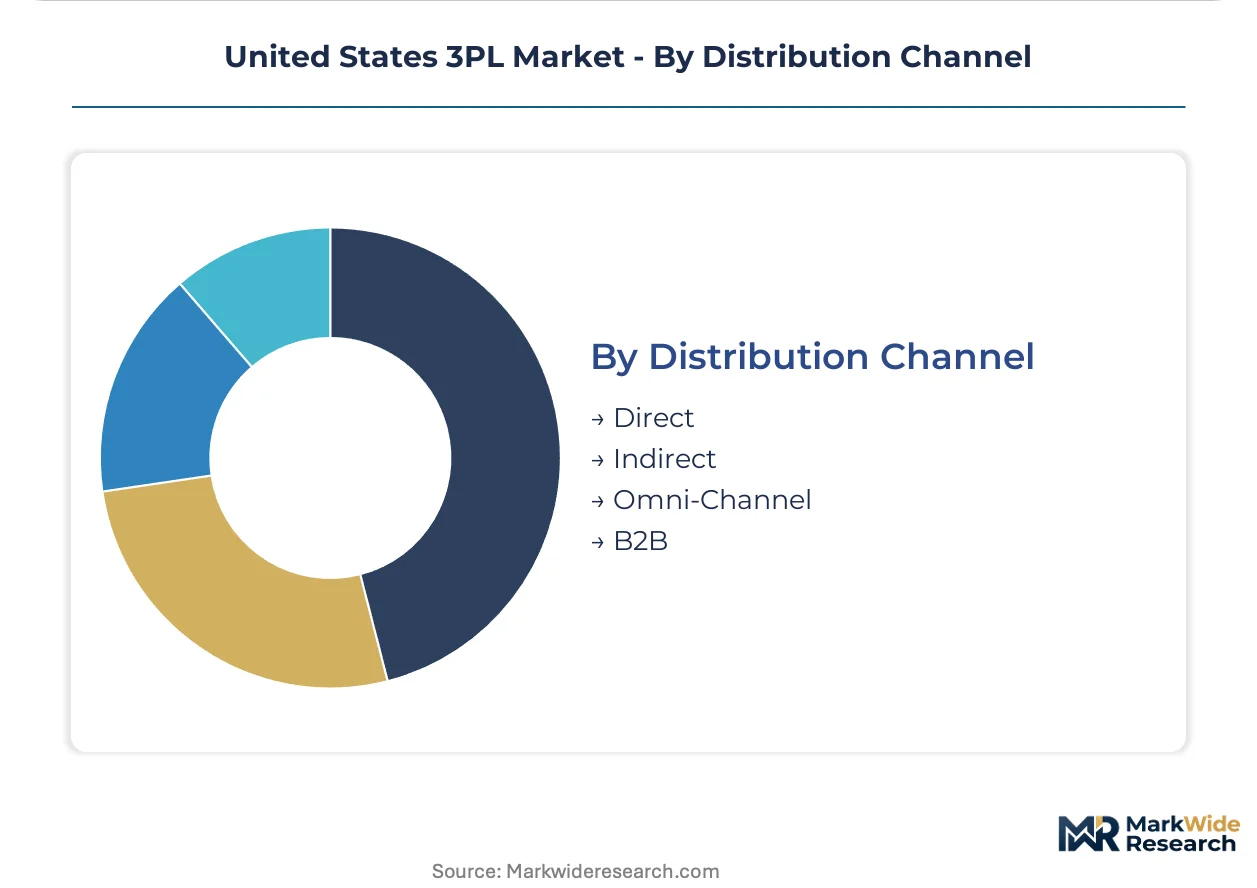
Distribution Channel:
Channel structure reflects shipper size and integration depth requirements, with direct relationships commanding premium pricing.
- Direct:Large shippers contract directly with 3PLs for dedicated capacity and customized SLAs. Long-term agreements spanning three to five years support capital investment in specialized facilities.
- Omni-Channel:Unified inventory pools serving retail, wholesale, and direct-to-consumer demand streams require sophisticated order orchestration. This configuration is gaining share fastest among mid-market merchants.
- Indirect:Freight brokers and logistics aggregators intermediate between small shippers and capacity providers. Digital freight-matching platforms are compressing margins through algorithmic spot pricing.
- B2B:Industrial and wholesale distribution emphasizes palletized handling and scheduled delivery windows. The Dallas-Fort Worth to Houston corridor supports manufacturing supply chain clustering.
Revenue concentration sits with Direct. Share expansion is accelerating in Omni-Channel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes logistics services at volumes exceeding domestic production capacity, creating persistent reliance on cross-border freight flows and international gateway ports. Consumption concentrates in coastal population centers while production and distribution infrastructure clusters in interior freight corridors. This geographic mismatch drives demand for intermediated capacity and multi-modal transfer facilities.
Texas
The Dallas-Fort Worth to Houston corridor anchors central U.S. fulfillment positioning with land availability supporting distribution center clustering. FMCSA hours-of-service enforcement limits driver availability on long-haul lanes, pushing freight toward intermodal rail substitution. The Port of Houston and inland port infrastructure at AllianceTexas facilitate containerized import distribution throughout the South-Central region.
California
Los Angeles and Long Beach ports handle the nation's largest container import volumes, driving drayage and transload demand into the Inland Empire warehouse cluster. CARB emissions regulations accelerate zero-emission truck mandates for port-adjacent operations. The Southern California logistics basin concentrates e-commerce fulfillment centers serving Pacific Coast consumer markets with same-day delivery commitments.
Illinois
Chicago's intermodal rail terminals and O'Hare air cargo infrastructure position the region as the primary Midwest freight transfer hub. OSHA warehouse safety standards influence automation investment decisions as 3PLs balance labor costs with ergonomic compliance. The I-55 corridor southwest of the metro area supports cold chain and packaged goods distribution for national retail networks.
Georgia
Atlanta's Hartsfield-Jackson airport and Savannah Port expansion drive Southeast logistics demand for automotive and consumer goods importers. Georgia Department of Transportation freight planning prioritizes interstate corridor improvements linking the port to interior markets. The I-75 and I-85 intersection supports regional distribution center clustering for time-definite delivery services.
Pennsylvania
Eastern Pennsylvania's Lehigh Valley and Harrisburg corridors offer last-mile positioning for Northeast metropolitan markets without urban land costs. Pennsylvania Department of Transportation weight enforcement and bridge restrictions influence truck routing and modal selection. The region's warehouse density supports pharmaceutical and medical device distribution requiring temperature-controlled handling.
United States 3PL Market Competitive Landscape
Capital-heavy asset owners compete with asset-light digital intermediaries for shipper contracts across transportation and fulfillment segments. The market structure divides between integrated providers controlling containers, chassis, and warehouse square footage, and technology platforms matching freight demand with available carrier capacity. Three archetypes dominate: railroad-affiliated intermodal operators, e-commerce-integrated fulfillment networks, and software-defined freight brokerages. Consolidation pressures favor scale players with balance sheet capacity for automation investment, while niche specialists defend positions through vertical industry expertise and dedicated contract structures.
Within the asset-heavy tier, J.B. Hunt anchors intermodal service through controlled container and chassis assets across the domestic rail network. C.H. Robinson occupies the digital brokerage position, leveraging freight-matching technology to sustain volume leadership in truckload intermediation. Amazon represents the vertically integrated fulfillment archetype, operating proprietary last-mile infrastructure that bypasses traditional carrier networks entirely.
| Leading Market Players |
|---|
| Amazon |
| C.H. Robinson |
| GXO Logistics |
| J.B. Hunt |
| UPS Supply Chain Solutions |
| Expeditors |
| Ryder Supply Chain Solutions |
| Kuehne + Nagel |
| DSV |
| Others |
Value Network & Pricing Analysis
E-commerce merchants demanding same-day delivery commitments are forcing 3PLs to position inventory in expensive urban infill locations, compressing margins and accelerating cost pass-through negotiations in contract renewals. This demand-side service escalation reshapes how providers structure capacity pricing across transportation and fulfillment segments.
Pricing Analysis
Margin tightening in truckload brokerage reflects algorithmic spot pricing platforms eroding traditional broker spreads through automated tendering workflows. Three-tier pricing structure across premium, standard, and economy levels differentiates service based on transit time guarantees and visibility granularity. Cost-down pressure on mid-market warehousing accelerates because robotic automation investments demand volume commitments that smaller merchants struggle to meet. E-commerce direct-to-consumer shippers exhibit highest price sensitivity, while automotive just-in-time contracts show lowest elasticity due to penalty cost exposure.
Supply Chain Analysis
Regional distribution centers cluster along the Dallas-Fort Worth to Houston corridor where land availability supports million-square-foot fulfillment campuses with intermodal rail access. Equipment sourcing draws from domestic chassis manufacturers, Mexican cross-border trucking capacity, and Chinese warehouse automation hardware suppliers. Single-source vulnerability concentrates in controlled container pools held by major railroads and large asset-owning 3PLs. Distribution runs through hub-and-spoke configurations with urban last-mile spokes positioned in Chicago, Los Angeles, and New York metro zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States 3PL market operates as a cost-of-compliance story where FMCSA hours-of-service enforcement and electronic logging device mandates create regulatory moats favoring capitalized incumbents with dedicated compliance infrastructure.
For Market Incumbents: To counter digital freight-matching platforms compressing spot brokerage margins, anchor intermodal competitiveness through controlled container and chassis assets across BNSF and Union Pacific networks. Prioritize OSHA ergonomic compliance investment in warehouse automation to reduce injury exposure and insurance cost escalation that erodes labor-intensive competitors. For New Entrants and Emerging Players: FMCSA electronic logging device enforcement in interstate operations opens a window for specialized compliance-as-a-service offerings targeting small carriers lacking in-house regulatory technology. White-space concentrates in mid-market e-commerce fulfillment where robotic picking systems reach payback thresholds previously reserved for enterprise clients. Go-to-market positioning should emphasize flexible capacity without fixed warehouse commitments. For Investors and Strategic Acquirers: The window for entry favors asset-heavy regional 3PLs with controlled real estate in the Texas freight corridor and established intermodal relationships. Long-term viability hinges on automation deployment velocity and cloud-based TMS scalability rather than pure brokerage volume. Watch autonomous trucking regulatory clarity across state jurisdictions as the inflection signal for fleet modernization capital allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Warehouse Automation Deployment | OSHA ergonomic compliance accelerates robotic picking investment to reduce injury liability exposure. |
| Intermodal Capacity Expansion | Controlled container pools on BNSF and Union Pacific networks extend effective shipping windows beyond driver hour limits. |
| Cloud-Based TMS Integration | Scalable SaaS platforms reduce client onboarding friction for e-commerce merchants with variable demand patterns. |
| Last-Mile Infrastructure Partnership | Urban fulfillment positioning in Chicago, Los Angeles, and New York metros enables same-day delivery commitments. |
| Regulatory Compliance Technology | FMCSA electronic logging device mandates create service opportunities for specialized compliance infrastructure providers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with transportation procurement directors, warehouse operations managers, intermodal rail planners, and freight brokerage executives. FMCSA compliance databases, Surface Transportation Board rate filings, OSHA injury statistics, and carrier safety measurement system records provided foundational validation. Bottom-up service provider revenue estimates triangulated against top-down national logistics expenditure benchmarks from Bureau of Transportation Statistics and Census Bureau trade data.
Data-stream reconciliation across transportation management system deployment metrics, warehouse square footage absorption, and intermodal volume trends informed the analytical framework over the projection horizon. Segmentation dimensions modeled include service type, end-user vertical, technology platform architecture, and distribution channel configuration. CAGRs derived from trend extrapolation of e-commerce fulfillment penetration, cloud-based solution adoption velocity, and FMCSA regulatory enforcement intensity across the modeling period.
Caveats apply where autonomous trucking regulatory fragmentation, diesel price volatility, or chassis availability shocks could materially shift the outlook. Forecasts reflect documented assumptions regarding e-commerce growth trajectory and labor market tightness. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Tennessee Freight and Logistics Market
Logistics and Shipping
ISO Shipping Container Market
Logistics and Shipping
Singapore Last Mile Delivery Market
Logistics and Shipping
Middle East Freight Forwarding Market
Logistics and Shipping
Russia Courier Service Market
Logistics and Shipping
Dry Van Container Market
Logistics and Shipping
China Project Logistics Market
Logistics and Shipping
Peru Freight and Logistics Market
Logistics and Shipping
US Air Freight Transport Market
Logistics and Shipping
Asia-Pacific Container Drayage Market
Logistics and Shipping
India Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Hazardous Goods Logistics Market
Logistics and Shipping
North America Cross Border Road Freight Transport Market
Logistics and Shipping
Fleet of Containers Market
Logistics and Shipping
Netherlands Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Last Mile Delivery Transportation Market