
 LAOS Freight and Logistics Market | 2026-2036
LAOS Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
LAOS Freight and Logistics Market Foresight
Mining and hydropower project logistics is expanding as foreign capital pours into Lao resource zones and energy infrastructure. DHL Group leverages its express network to capture time-critical shipments for multinational contractors in Savannakhet and Vientiane. China Merchants Group anchors much of the north-south cargo flow through its Sinotrans subsidiary, which controls key cross-border routes into Yunnan. Kerry Logistics Network specializes in temperature-controlled distribution for agri-export chains moving through Wattay International Airport.
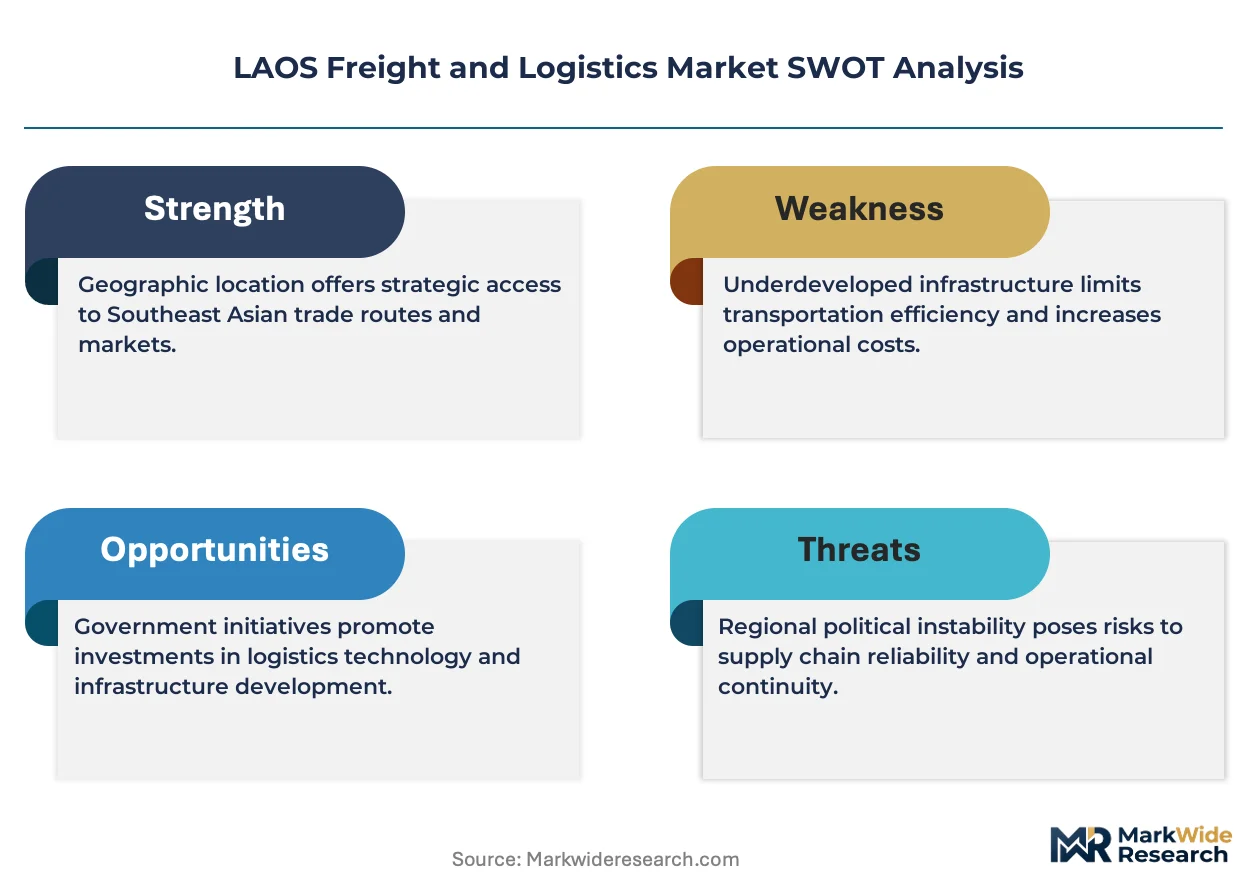
Freight and logistics encompasses the physical movement, storage, and customs clearance of goods across multimodal networks, typically measured by tonnage throughput, dwell time, and customs clearance velocity. In Laos, this sector manages everything from bulk mineral haulage on the Mekong River to bonded warehousing at the Vientiane Logistics Park, with road freight dominating due to limited rail penetration outside the China-Laos line. Road freight leads in volume terms but faces margin compression from fuel volatility and informal competition, while rail freight represents the fastest-growing mode as the Boten-Vientiane corridor absorbs containerized cargo previously moved by truck. Third-party logistics captures the deepest margin pools by bundling customs brokerage with inland distribution, particularly for manufacturers relocating from higher-cost ASEAN neighbors.
The Ministry of Public Works and Transport enforces axle-load limits and cross-border vehicle standards that directly shape fleet investment decisions for domestic operators. Customs Department regulations aligned with ASEAN trade facilitation commitments are reducing documentary inspection rates at Thanaleng and Lao Bao checkpoints, accelerating clearance times for bonded cargo. Stakeholders must monitor how Lao PDR's accession to the Regional Comprehensive Economic Partnership reshapes rules-of-origin verification and whether planned dry-port investments at Luang Namtha create viable alternatives to Thai port dependency.
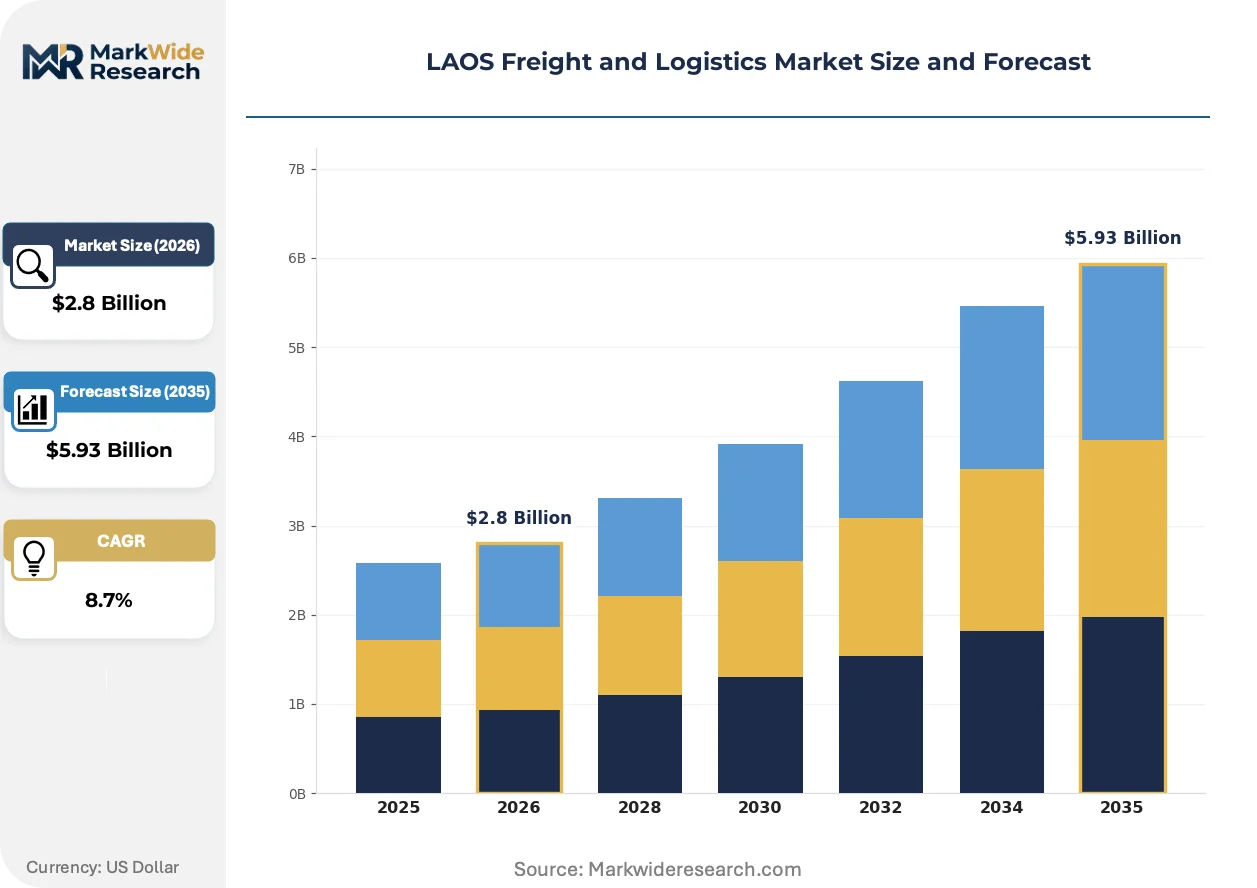
Market Dynamics
The Boten-Vientiane railway is compressing transit times between China and Thailand, forcing road hauliers to reposition toward last-mile distribution and bonded warehousing as rail absorbs long-haul container volumes.
Growth Catalysts
- ASEAN Single Window:Cross-border trade facilitation protocols are slashing documentary inspection rates at Thanaleng and Lao Bao checkpoints, accelerating customs clearance velocity for bonded cargo.
- Hydropower construction:Foreign direct investment into Nam Theun and Xayaburi dam extensions is generating outsized demand for heavy-lift project logistics and specialized transport equipment.
- China-Laos Economic Corridor:The Vientiane Logistics Park and associated dry-port investments are anchoring multimodal consolidation nodes that capture transshipment flows previously routed through Thai ports.
Market Restraints
- Diesel price volatility:Road freight operators face margin compression from fuel cost swings, with no viable alternative propulsion systems available for Laos's mountainous terrain and limited electrification infrastructure.
- Thai port dependency:Over 70% of containerized trade still flows through Laem Chabang and Bangkok, creating concentration risk and vulnerability to congestion or policy shifts by Thai authorities.
- Axle-load enforcement gaps:Inconsistent application of Ministry of Public Works and Transport weight limits across provincial checkpoints distorts fleet investment decisions and accelerates road degradation.
Strategic Opportunities
- Luang Namtha dry-port zone:Planned inland container depot investments near the Chinese border offer alternatives to Thai port dependency for northern provinces and Yunnan-originating cargo.
- Temperature-controlled agri-logistics:Rising Chinese demand for Lao bananas and durians creates white space for cold-chain infrastructure along the Boten corridor and Wattay International Airport perimeter.
- Regional Comprehensive Economic Partnership accession:Lao PDR's participation is tightening rules-of-origin verification requirements, creating demand for integrated customs brokerage and certificate-of-origin management services.
Industry Challenges
- Qualified customs broker scarcity:Shortage of personnel fluent in ASEAN trade facilitation protocols and Chinese customs documentation standards creates bottlenecks at high-volume border crossings.
- Rail-road intermodal coordination:Misaligned scheduling systems and incompatible container specifications between China Railway and Lao domestic hauliers generate dwell time penalties and cargo damage disputes.
- Legacy fleet modernization:Aging Euro 2 and Euro 3 trucks dominate domestic road freight, facing escalating compliance costs as environmental standards tighten for cross-border operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAOS Freight and Logistics Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Freight Forwarding, Warehousing, Transportation, Customs Brokerage Mode: Road, Rail, Air, Water Client Type: Manufacturers, Retailers, E-commerce, Government Delivery Model: Direct Delivery, Drop Shipping, Third-Party Logistics, Last-Mile Delivery |
| Companies Covered | China Merchants Group - cmhk (Including Sinotrans, Ltd.), DHL Group, CMA CGM Group (Including CEVA Logistics), DSV A/S (Including DB Schenker), Linfox Pty, Ltd., GEOTRANS Logistics and Movers Co., Ltd., Sayfon Logistics Co., Ltd., DP World (Including Savan Logistics Co., Ltd.), Kerry Logistics Network Group, Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAOS Freight and Logistics Market Shifts & Advancements
Digital freight platforms and automated customs systems are restructuring how cargo moves across Laos's fragmented transport network, compressing coordination costs and shifting competitive advantage toward data-integrated operators.
GPS-enabled fleet management systems combined with electronic logging devices are automating dispatch decisions for domestic road hauliers. Mining contractors in Savannakhet and construction material suppliers along Route 13 are adopting these platforms fastest, drawn by fuel theft prevention and real-time cargo tracking. The technology is automating route optimization previously handled by experienced dispatchers, reducing headcount in back offices while improving asset utilization rates.
The Customs Department's alignment with ASEAN trade facilitation commitments is mandating pre-arrival processing and risk-based inspection protocols at Thanaleng and Lao Bao. This regulatory shift is compressing clearance times from days to hours for compliant traders while concentrating volume toward operators with integrated documentation systems. Bonded warehouse operators and third-party logistics providers are responding by embedding customs brokerage capabilities directly into their service offerings.
Consolidation of procurement authority among multinational mining and hydropower developers is shifting freight purchasing from fragmented project-level contracting toward multi-year framework agreements with integrated logistics providers. Tier-1 contractors in the power sector are bundling transport, warehousing, and customs clearance into single-source arrangements. This pattern is most visible in the Vientiane-Pakse corridor, where Chinese and Thai EPC contractors now specify logistics performance metrics in construction contracts rather than treating transport as a pass-through cost.
LAOS Freight and Logistics Market Segmentation
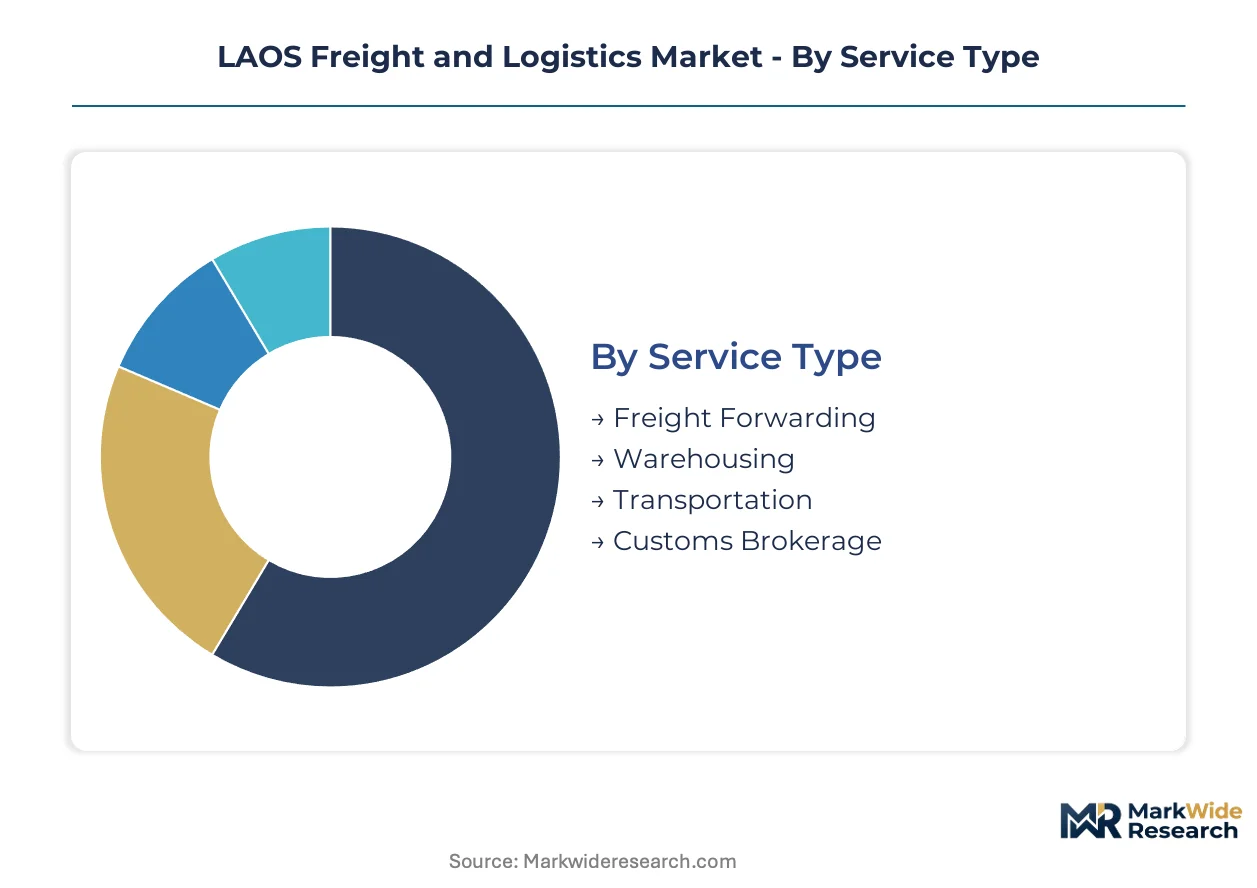
Segmentation in the Lao freight and logistics market reveals how service capabilities align with infrastructure constraints and cross-border trade flows. Understanding these divisions exposes where margin pools concentrate and which delivery models capture value as the China-Laos Economic Corridor matures.
Service Type:
Standalone service providers compete against embedded logistics arms of mining and construction conglomerates, with integration depth determining contract tenure and pricing power.
- Freight Forwarding:Coordination of multimodal cargo movement across the Lao-Thai border and Boten-Vientiane corridor. Demand concentrates with multinational mining contractors in Savannakhet and hydropower developers requiring heavy-lift documentation for Chinese customs clearance.
- Warehousing:Bonded storage and inventory management at nodes like Vientiane Logistics Park and Thanaleng dry port. Fastest expansion belongs to temperature-controlled facilities serving banana and durian exporters at Wattay International Airport perimeter.
- Transportation:Asset-based carriage by road, rail, and waterway. Fleet operators along Route 13 face margin pressure from diesel volatility while rail intermodal providers capture volume on the Boten line.
- Customs Brokerage:Documentation processing and duty optimization at Thanaleng, Lao Bao, and Boten checkpoints. Scarce personnel fluent in ASEAN Single Window protocols and Chinese customs standards create bottlenecks at high-volume crossings.
Volume placements concentrate in Transportation; the faster expansion belongs to Customs Brokerage as RCEP accession tightens rules-of-origin verification requirements.
Mode:
Cost tier differentiation separates capital-intensive rail infrastructure from flexible road networks, with each mode serving distinct cargo profiles and transit time requirements.
- Road:Dominant volume mode handling 70% plus of domestic freight, from bulk mineral haulage on Route 13 to last-mile distribution in Vientiane. Euro 2 and Euro 3 legacy fleets face escalating compliance costs as cross-border environmental standards tighten.
- Rail:Fastest-climbing mode as the Boten-Vientiane corridor absorbs containerized cargo previously moved by truck. China Railway scheduling misalignment with Lao domestic hauliers generates dwell time penalties at intermodal handoffs.
- Air:Time-critical shipments of electronics and perishables through Wattay International Airport. Premium pricing captures agri-export cold chains and multinational contractor urgent spares.
- Water:Bulk commodity movement on the Mekong River, constrained by seasonal draft limitations and Thai navigation protocols. Sand, gravel, and agricultural inputs dominate tonnage.
Revenue concentration sits with Road; the steepest expansion trajectory belongs to Rail as dry-port investments at Luang Namtha reduce Thai port dependency.
Client Type:
Procurement sophistication varies sharply across customer categories, with multinationals demanding integrated solutions and government entities prioritizing local content requirements.
- Manufacturers:Relocated production facilities from Thailand and Vietnam seeking lower-cost ASEAN access. These clients bundle transport, warehousing, and customs clearance into multi-year framework agreements.
- Retailers:Distribution networks serving Vientiane and provincial urban centers. Inventory velocity requirements drive adoption of GPS-enabled fleet tracking and automated replenishment systems.
- E-commerce:Emerging demand from cross-border platforms serving Chinese consumer markets. Last-mile fragmentation across mountainous terrain limits penetration outside major corridors.
- Government:Public works and state-owned enterprise logistics, including hydropower construction materials and civil servant supply chains. Procurement cycles follow fiscal year budgeting with extended payment terms.
Contract value concentrates with Manufacturers; the fastest volume gains belong to E-commerce as digital freight platforms penetrate secondary cities.
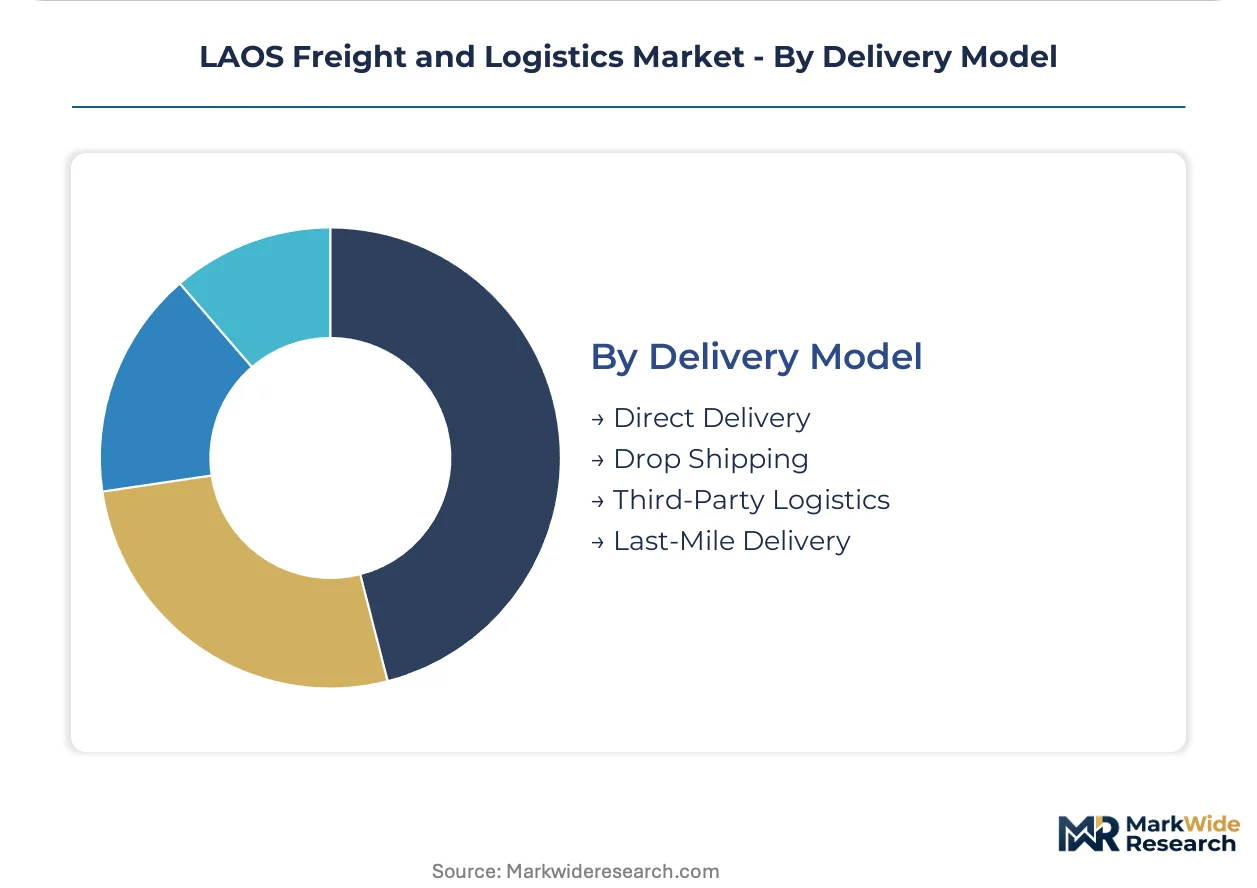
Delivery Model:
Margin structure separates asset-heavy operators from coordination-focused intermediaries, with customer control preferences dictating model selection.
- Direct Delivery:Shipper-controlled fleet operations, common among mining and hydropower developers with specialized equipment requirements. High fixed costs limit flexibility during project completion phases.
- Drop Shipping:Inventory-free fulfillment from supplier to end customer, gaining traction in agricultural inputs and construction materials. Documentation complexity at Lao-Thai crossings constrains adoption.
- Third-Party Logistics:Bundled service provision capturing the deepest margin pools by integrating customs brokerage with inland distribution. Tier-1 providers embed compliance capabilities directly into service offerings.
- Last-Mile Delivery:Final segment distribution in Vientiane, Pakse, and Savannakhet urban zones. Informal motorbike couriers compete with formal operators on cost, eroding service standardization.
Profitability concentrates in Third-Party Logistics; the most rapid expansion belongs to Last-Mile Delivery as e-commerce penetration extends beyond capital corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Savan-Seno Special Economic Zone drives logistics concentration in Savannakhet Province, offering tax holidays and duty exemptions that attract bonded warehousing investments along the Lao-Thai border corridor.
Vientiane Capital
Multinational mining contractors and hydropower developers cluster around Wattay International Airport and the Vientiane Logistics Park, demanding integrated customs brokerage and temperature-controlled storage. The Ministry of Public Works and Transport enforces axle-load regulations that shape fleet procurement decisions for domestic operators. Cold-chain infrastructure expansion accelerates near the airport perimeter as Chinese demand for Lao bananas and durians intensifies.
Luang Namtha Province
Planned dry-port investments near the Chinese border aim to divert containerized cargo from Thai port dependency, capturing Yunnan-originating freight for northern provinces. The ASEAN Single Window initiative streamlines documentary processing at Boten checkpoint, reducing clearance friction for cross-border traders. Rail-road intermodal coordination challenges persist as China Railway scheduling misalignment with Lao domestic hauliers generates dwell time penalties.
Savannakhet Province
Heavy-lift project logistics dominates as foreign direct investment flows into resource extraction and energy infrastructure development. Customs Department regulations aligned with ASEAN trade facilitation commitments accelerate bonded cargo clearance at Thanaleng and Lao Bao checkpoints. GPS-enabled fleet management systems penetrate fastest here among mining contractors seeking fuel theft prevention and real-time cargo tracking.
Champasak Province
Pakse anchors southern distribution networks serving relocated manufacturing facilities from Thailand and Vietnam seeking lower-cost ASEAN market access. The Regional Comprehensive Economic Partnership tightens rules-of-origin verification requirements, stimulating demand for integrated certificate-of-origin management services. Third-party logistics providers embed compliance capabilities directly into multi-year framework agreements with tier-1 contractors.
LAOS Freight and Logistics Market Competitive Landscape
Top-tier vendors anchor integrated multimodal service provision, while mid-tier specialists compete on corridor-specific expertise and customs brokerage depth. Market structure tilts toward consolidation as multinational developers bundle transport, warehousing, and clearance into single-source arrangements. Three archetypes dominate: express network operators capturing time-critical shipments, state-linked conglomerates controlling cross-border rail corridors, and regional 3PL platforms specializing in temperature-controlled agri-logistics. Capacity expansion at dry-port nodes and strategic partnerships with Chinese railway operators represent the dominant competitive vectors.
Among Asia-Pacific-based integrated logistics groups, China Merchants Group, Kerry Logistics Network, and DHL Group exemplify contrasting market positions. China Merchants Group anchors north-south cargo flow through its Sinotrans subsidiary, occupying a position tied to China-Laos Economic Corridor infrastructure. Kerry Logistics Network sits within the temperature-controlled specialization tier, representing the agri-export cold-chain archetype around Wattay International Airport. DHL Group occupies the express network tier, exemplifying time-critical service provision for multinational contractors in Savannakhet and Vientiane.
| Leading Market Players |
|---|
| China Merchants Group - cmhk (Including Sinotrans, Ltd.) |
| DHL Group |
| CMA CGM Group (Including CEVA Logistics) |
| DSV A/S (Including DB Schenker) |
| Linfox Pty, Ltd. |
| GEOTRANS Logistics and Movers Co., Ltd. |
| Sayfon Logistics Co., Ltd. |
| DP World (Including Savan Logistics Co., Ltd.) |
| Kerry Logistics Network Group, Ltd. |
| Others |
Supply & Pricing Matrix
GPS-enabled fleet management systems and electronic logging devices are compressing coordination costs for Lao road hauliers while simultaneously concentrating pricing power among operators with integrated data capabilities. This technology transition rewards asset-heavy players who can amortize platform investments across larger fleets, squeezing informal competitors on Route 13 and reshaping how transport services are procured by mining contractors in Savannakhet.
Pricing Analysis
Lead-time-driven pricing premiums dominate contract structures, with multinational mining and hydropower developers paying substantial markups for guaranteed 48-hour delivery windows on heavy-lift equipment while spot market rates for non-urgent bulk minerals trade at discounts. Three-tier pricing structure across premium, standard, and economy levels separates bonded warehousing with integrated customs brokerage from basic road haulage and informal last-mile motorbike delivery. Cost compression in standard-tier road freight is intensifying because diesel price volatility erodes margins faster than operators can pass through fuel surcharges. Government procurement entities exhibit highest price sensitivity due to fiscal year budgeting constraints, while Chinese EPC contractors demonstrate lowest sensitivity when logistics performance guarantees are embedded in construction contracts.
Supply Chain Analysis
Workforce availability constraints in Thai manufacturing zones and Vietnamese industrial corridors are pushing relocation decisions toward Laos, where lower labor costs attract secondary sourcing for automotive components and electronics assembly. Geographic supply concentration centers on China for rolling stock and signaling equipment, Thailand for refined petroleum products and automotive parts, and Vietnam for construction materials and packaging inputs. Raw material dependencies include Chinese steel for rail infrastructure, Thai diesel for road fleets, and imported refrigerants for cold-chain equipment. Single-source vulnerability runs through China Railway's scheduling systems, which misalign with Lao domestic haulier operations. Distribution runs through the Lao-Thai border corridor for southern provinces and the Boten-Vientiane rail line for northern cargo originating in Yunnan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rail-road intermodal technology is displacing legacy road-only logistics models, creating asymmetric opportunities for operators who can bridge China Railway scheduling systems with Lao domestic fleet capabilities.
For Market Incumbents: Lock in multi-year framework agreements with Chinese and Thai EPC contractors before dry-port investments at Luang Namtha mature, anchoring revenue streams that informal competitors cannot match. Deepen backward integration into bonded warehousing at Vientiane Logistics Park to capture customs brokerage margins that currently leak to standalone brokers. The threat of qualified customs broker scarcity creates leverage for integrated operators who embed compliance capabilities directly into service offerings. For New Entrants and Emerging Players: Cold-chain infrastructure operators represent the most penetrable white-space target, as Chinese demand for Lao bananas and durians outstrips temperature-controlled storage capacity around Wattay International Airport. Target the Luang Namtha dry-port zone for intermodal coordination services that resolve dwell time penalties between China Railway and Lao domestic hauliers. A go-to-market angle anchored in ASEAN Single Window protocol fluency addresses the bottleneck created by personnel shortages at Thanaleng and Lao Bao checkpoints. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by Asia-Pacific integrated logistics groups seeking China-Laos Economic Corridor exposure. Long-term viability hinges on operators who control multimodal nodes rather than single-mode asset bases. Acquisition target archetype: regional 3PL platforms with embedded customs brokerage and temperature-controlled capabilities. The signal to watch is RCEP rules-of-origin verification tightening, which will concentrate volume toward providers with integrated certificate-of-origin management systems.| Strategic Initiative | Industry Significance |
|---|---|
| Rail-Road Intermodal Integration | Resolves China Railway scheduling misalignment with Lao domestic hauliers at Boten-Vientiane handoffs. |
| Temperature-Controlled Warehouse Expansion | Captures Chinese import demand for Lao bananas and durians through Wattay International Airport perimeter. |
| Customs Brokerage Capability Embedding | Addresses qualified broker scarcity at Thanaleng and Lao Bao checkpoints through in-house documentation teams. |
| Luang Namtha Dry-Port Investment | Diverts northern province containerized cargo from Thai port dependency toward Yunnan-originating rail flows. |
| ASEAN Single Window Compliance Integration | Compresses documentary inspection rates through pre-arrival processing and risk-based inspection protocols. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with fleet operators, customs brokerage managers, mining procurement leads, and dry-port developers. Secondary sources included Ministry of Public Works and Transport axle-load enforcement records, Customs Department clearance time statistics, China Railway scheduling disclosures, and ASEAN Single Window implementation reports. Bottom-up tonnage throughput modeling triangulated against top-down GDP-trade elasticity estimates to validate market size calculations.
Granularity-level modeling operated at service type, transport mode, client category, and delivery model dimensions, with additional disaggregation by provincial corridor density and cross-border checkpoint volume. CAGRs were derived from trend extrapolation of historical throughput data, adjusted for infrastructure completion timelines and regulatory implementation schedules. Forecast inputs included China-Laos Economic Corridor investment flows, hydropower construction pipeline visibility, and RCEP accession compliance cost assumptions.
Several conditions sit outside the modeled scope, including potential Thai port congestion policy shifts, China Railway pricing regime changes, and unannounced mining project cancellations. Forecasts reflect documented assumptions about diesel price trajectory, axle-load enforcement consistency, and dry-port construction schedules. A small set of named triggers warrants ongoing watch: Regional Comprehensive Economic Partnership rules-of-origin verification implementation, Luang Namtha dry-port operational launch, and China Railway cross-border scheduling system upgrades.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Indonesia Freight and Logistics Market
Logistics and Shipping
France Last Mile Delivery Market
Logistics and Shipping
Mexico 3PL Market
Logistics and Shipping
LAMEA Last Mile Delivery Market
Logistics and Shipping
Russia Courier Service Market
Logistics and Shipping
Bangladesh Freight and Logistics Market
Logistics and Shipping
GCC Secure Logistics Market
Logistics and Shipping
Georgia Freight and Logistics Market
Logistics and Shipping
Europe less-Than Container Load Market
Logistics and Shipping
North America Logistics Automation Market
Logistics and Shipping
Autonomous Last Mile Delivery Market
Logistics and Shipping
Asia-Pacific Last Mile Delivery Market
Logistics and Shipping
Morocco Freight and Logistics Market
Logistics and Shipping
Ocean Freight Forwarding Market
Logistics and Shipping
Maritime Logistics and Services Market
Logistics and Shipping
Japan Third-Party Logistics (3PL) Market