
 Chile Courier, Express, and Parcel (CEP) Market | 2026-2036
Chile Courier, Express, and Parcel (CEP) Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Courier, Express, and Parcel (CEP) Market Insights
ISO 9001 quality management certification is bifurcating the competitive landscape between established operators and newer entrants in Chile's CEP sector. Chilexpress sustains its domestic network dominance through extensive last-mile coverage across regional cities. Deutsche Post DHL Group leverages its international gateway infrastructure to control cross-border parcel volumes into Santiago. FedEx differentiates through specialized temperature-controlled and time-definite services for Chile's mining and pharmaceutical supply chains.
Courier, express, and parcel services encompass the physical movement of documents and goods under defined time commitments, utilizing integrated sorting hubs, multi-modal transport, and digital tracking protocols with barcode or RFID scanning at each handling node. The primary commercial purpose is enabling reliable business-to-business and business-to-consumer exchange across geographically dispersed locations. Same-day delivery and next-day delivery segments command premium pricing and attract the highest investment in urban micro-fulfillment networks, while standard shipping retains volume leadership in cost-sensitive B2B corridors. International shipping represents the fastest-growing structural segment as Chilean SMEs expand marketplace selling to Mercosur and North American buyers.
Chile's Customs Service and the central bank's foreign exchange regulations shape cross-border CEP demand through import documentation requirements and duty collection protocols. The Consumer Protection Agency enforces delivery time transparency and compensation standards for service failures, directly influencing carrier operational investments. Stakeholders must monitor regulatory alignment between Chile's evolving e-commerce taxation framework and carrier technology platforms to sustain market access and margin structures.
Market Dynamics
E-commerce platform consolidation in Santiago and Valparaíso is compressing delivery windows and forcing carriers to reconfigure last-mile networks around same-day fulfillment expectations. This demand acceleration is restructuring capital allocation across sorting infrastructure and urban micro-fulfillment nodes.
Growth Catalysts
- Customs Service Modernization:Digital import processing requirements are accelerating cross-border parcel clearance speeds, reducing dwell times at Santiago's international gateway and expanding SME marketplace access to Mercosur buyers.
- Urban Millennial Consumption:Metropolitan Region households are driving B2C volume expansion through mobile-first purchasing patterns that prioritize delivery speed over cost minimization.
- Temperature-Controlled Infrastructure:Specialized cold chain investments for pharmaceutical and fresh produce segments are opening premium service tiers previously dominated by general freight operators.
Market Restraints
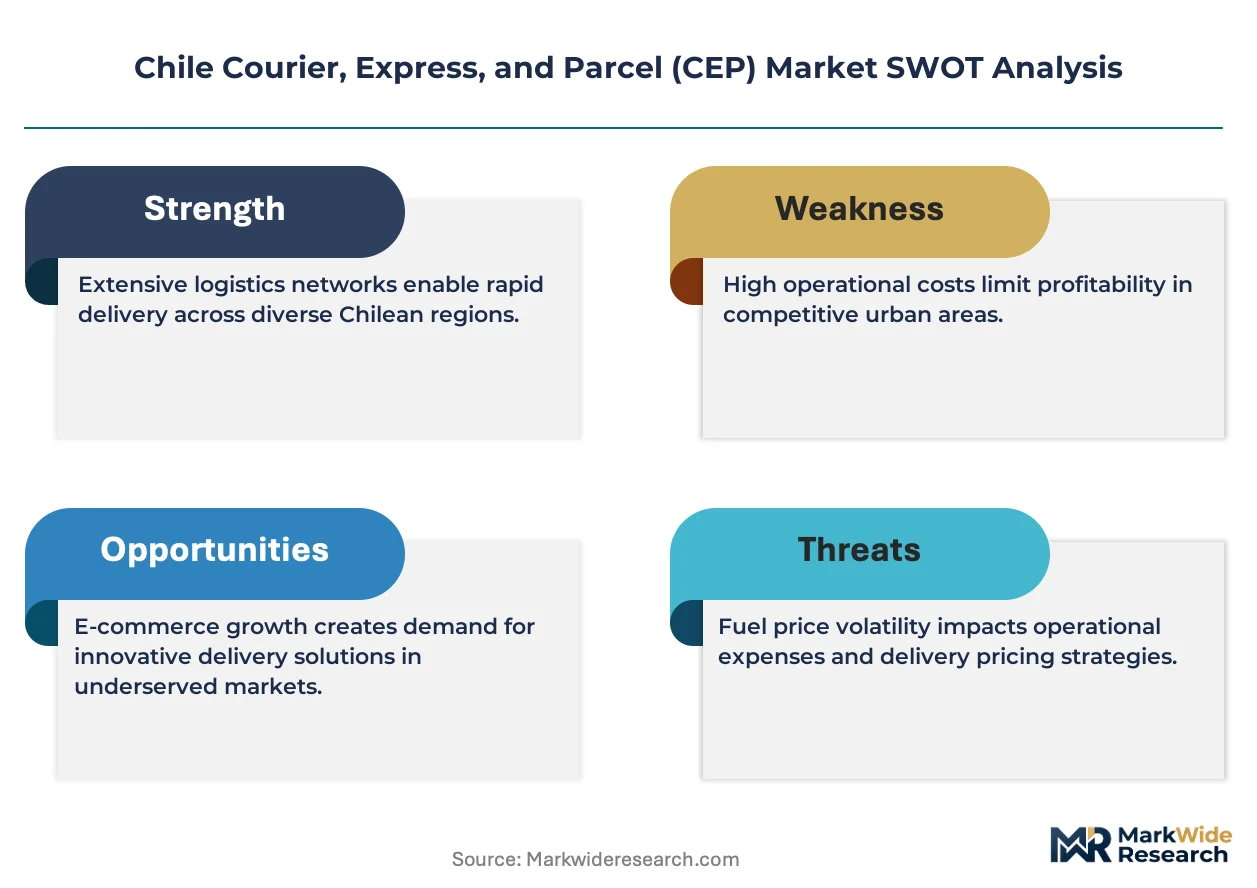
- Fuel Cost Volatility:Diesel price fluctuations directly compress margins on long-haul corridors connecting Santiago to regional cities, constraining network expansion into peripheral zones.
- Last-Mile Labor Scarcity:Driver availability limitations in dense urban cores are creating service reliability gaps during peak e-commerce windows, particularly in Valparaíso port districts.
- Foreign Exchange Regulations:Central bank documentation requirements for cross-border shipments introduce friction in international payment settlements, delaying SME onboarding to global marketplaces.
Strategic Opportunities
- Regional City Penetration:Concepción and La Serena present underdeveloped last-mile density where established carriers can deploy hub-and-spoke models ahead of competitor entry.
- Consumer Protection Agency Alignment:Delivery transparency mandates are creating first-mover advantages for carriers that integrate real-time tracking with automated compensation protocols.
- Barcode-RFID Convergence:Hybrid scanning technologies are enabling granular inventory visibility that supports dynamic route optimization and predictive exception management.
Industry Challenges
- ISO 9001 Certification Timeline:Quality management system implementation demands 12-18 month compliance cycles that strain mid-tier operator cash flows and technical staffing capacity.
- Legacy System Integration:ERP modernization for route planning and customer notification platforms requires substantial capital commitment without immediate revenue offset.
- Skills Gap in Data Analytics:Shortage of personnel capable of interpreting RFID-generated throughput metrics is limiting operational optimization in regional sorting facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Courier, Express, and Parcel (CEP) Market |
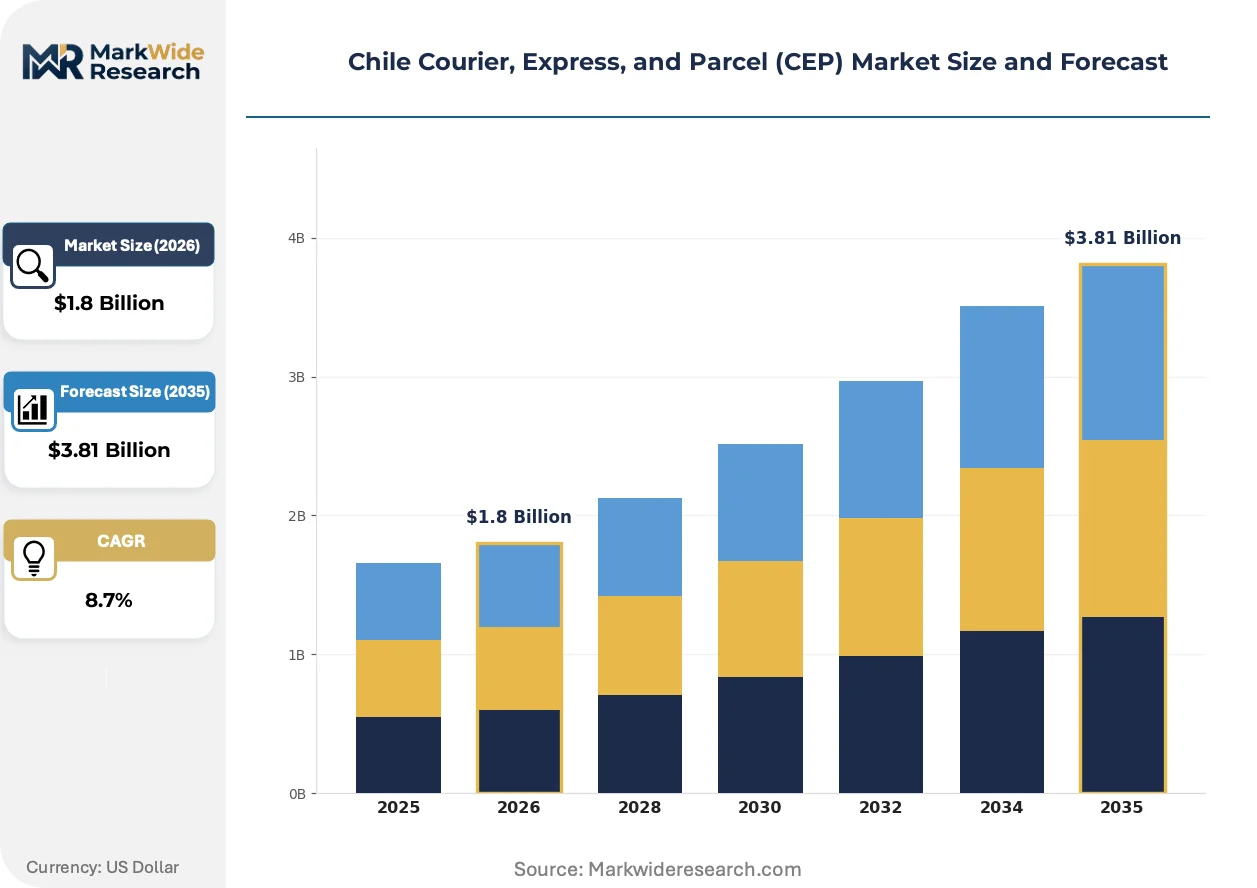
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Same-Day Delivery, Next-Day Delivery, Standard Shipping, International Shipping Delivery Mode: Door-to-Door, Curbside Pickup, Drop-off Points, Locker Services Customer Type: B2B, B2C, E-commerce, Retail Packaging Type: Poly Mailers, Corrugated Boxes, Padded Envelopes, Specialized Packaging |
| Companies Covered | Chilexpress, Correos de Chile, Deutsche Post DHL Group, FedEx, United Parcel Service of America Inc (UPS), DSV A/S, Empresas Copec SA, Redmegacentro SA, Yango Deliver, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Courier, Express, and Parcel (CEP) Market Trends and Innovations
Digital tracking protocols are redefining service level agreements across Chile's CEP sector, with real-time visibility becoming a baseline expectation rather than a premium feature. This technological foundation is enabling new operational models that compress delivery commitments.
Hybrid barcode-RFID scanning systems are bifurcating carrier performance tiers. Large operators deploy item-level tracking through integrated sorting hubs, while smaller competitors remain constrained to zone-level visibility. Metropolitan Region B2C shippers are migrating volume toward carriers offering scan-at-every-node transparency, compressing margins for legacy operators dependent on batch-scan methods.
Chile's Customs Service digital import processing requirements are reshaping cross-border operational compliance. Automated documentation submission and pre-arrival clearance protocols are reducing port dwell times for international parcels. SME marketplace sellers in Santiago are responding by consolidating shipments through compliant carrier partnerships that integrate directly with customs platforms.
Buyer expectations around delivery transparency are hardening service differentiation. Urban millennials in the Metropolitan Region now treat real-time tracking and proactive delay notification as standard requirements, displacing price-only selection criteria. Small business marketplace sellers are absorbing this preference shift by contracting carriers with integrated customer communication platforms, particularly for Mercosur-bound exports.
Chile Courier, Express, and Parcel (CEP) Market Segmentation
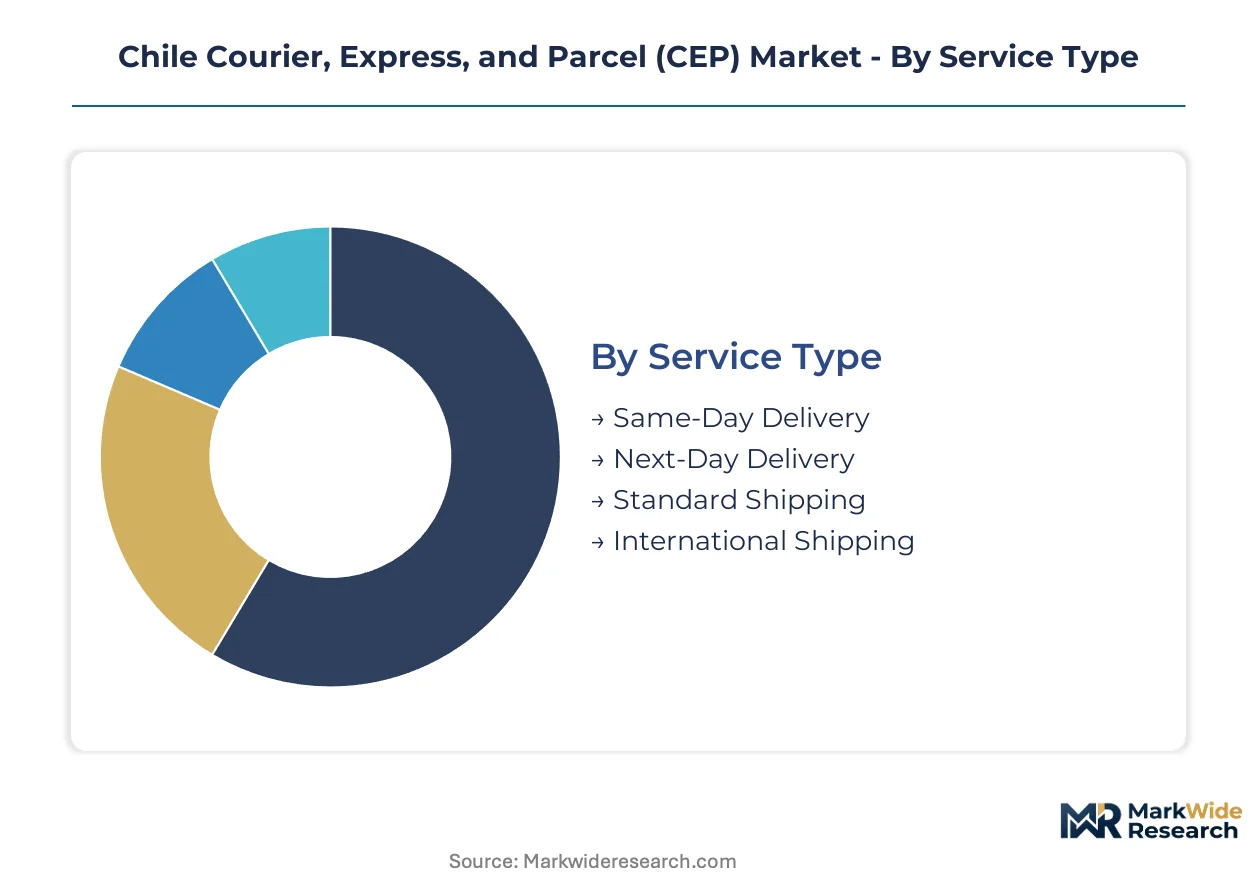
Chile's CEP market segments reflect divergent regulatory pressures and operational cost structures. Service-level differentiation increasingly maps to customs compliance capabilities and last-mile density investments rather than speed alone.
Service Type:
Chile's Customs Service digital import processing requirements are bifurcating carrier capabilities between domestic-optimized and cross-border-ready operators.
- Same-Day Delivery:Ultra-compressed fulfillment windows demand urban micro-fulfillment nodes in Santiago and Valparaíso. Metropolitan Region millennials absorb premium pricing for immediate gratification, compressing carrier margins through redundant inventory positioning.
- Next-Day Delivery:Hub-and-spoke sorting infrastructure with evening cutoff times defines operational viability. Concepción and La Serena corridors require dedicated line-haul capacity to meet morning delivery commitments.
- Standard Shipping:Cost-optimized B2B corridors between regional cities. Chilexpress leverages extensive domestic coverage to maintain volume leadership on non-urgent lanes.
- International Shipping:Fastest-expanding structural segment as SME marketplace sellers target Mercosur and North American buyers. Deutsche Post DHL Group controls gateway infrastructure for customs-compliant cross-border flows.
Standard Shipping handles the majority of throughput; International Shipping is expanding most quickly on share.
Delivery Mode:
Last-mile cost tiers stratify around labor intensity and real estate requirements in dense urban cores.
- Door-to-Door:Labor-intensive final delivery with highest cost per stop. Valparaíso port district driver scarcity creates service reliability gaps during peak windows.
- Curbside Pickup:Reduced dwell time through pre-staged collection protocols. Retail anchor tenants in Santiago metropolitan malls deploy dedicated pickup zones.
- Drop-off Points:Third-party retail partnerships extend reach without owned infrastructure. Regional city penetration relies on gas station and pharmacy networks.
- Locker Services:Automated collection infrastructure with 24/7 availability. Metro station deployments in Santiago concentrate volume in commuter corridors.
Door-to-Door retains volume dominance; Locker Services are climbing the fastest as urban real estate costs escalate.
Customer Type:
Procurement authority and volume concentration determine contract structures and technology integration depth.
- B2B:Contractual relationships with negotiated service levels and dedicated account management. Mining and pharmaceutical supply chains demand temperature-controlled and time-definite capabilities.
- B2C:Transactional purchasing with delivery speed prioritization over cost minimization. Metropolitan Region households drive mobile-first volume expansion.
- E-commerce:Platform-integrated fulfillment with API-driven order injection. Marketplace sellers in Santiago consolidate through carriers with direct customs platform integration.
- Retail:Omnichannel replenishment and customer fulfillment convergence. Same-day expectations from physical store inventory reshape carrier allocation models.
B2C commands the steepest expansion trajectory; B2B maintains revenue concentration through premium service tiers.
Packaging Type:
Material specifications align with product protection requirements and dimensional weight pricing optimization.
- Poly Mailers:Lightweight flexible packaging for apparel and soft goods. E-commerce apparel sellers in Santiago optimize shipping costs through dimensional efficiency.
- Corrugated Boxes:Rigid protection for electronics and home goods. Standardized sizes enable automated sorting hub throughput maximization.
- Padded Envelopes:Cushioned protection for small electronics and jewelry. Cross-border SME sellers favor this format for Mercosur-bound shipments.
- Specialized Packaging:Temperature-controlled and hazardous materials containment. Pharmaceutical cold chain investments open premium service tiers previously served by general freight.
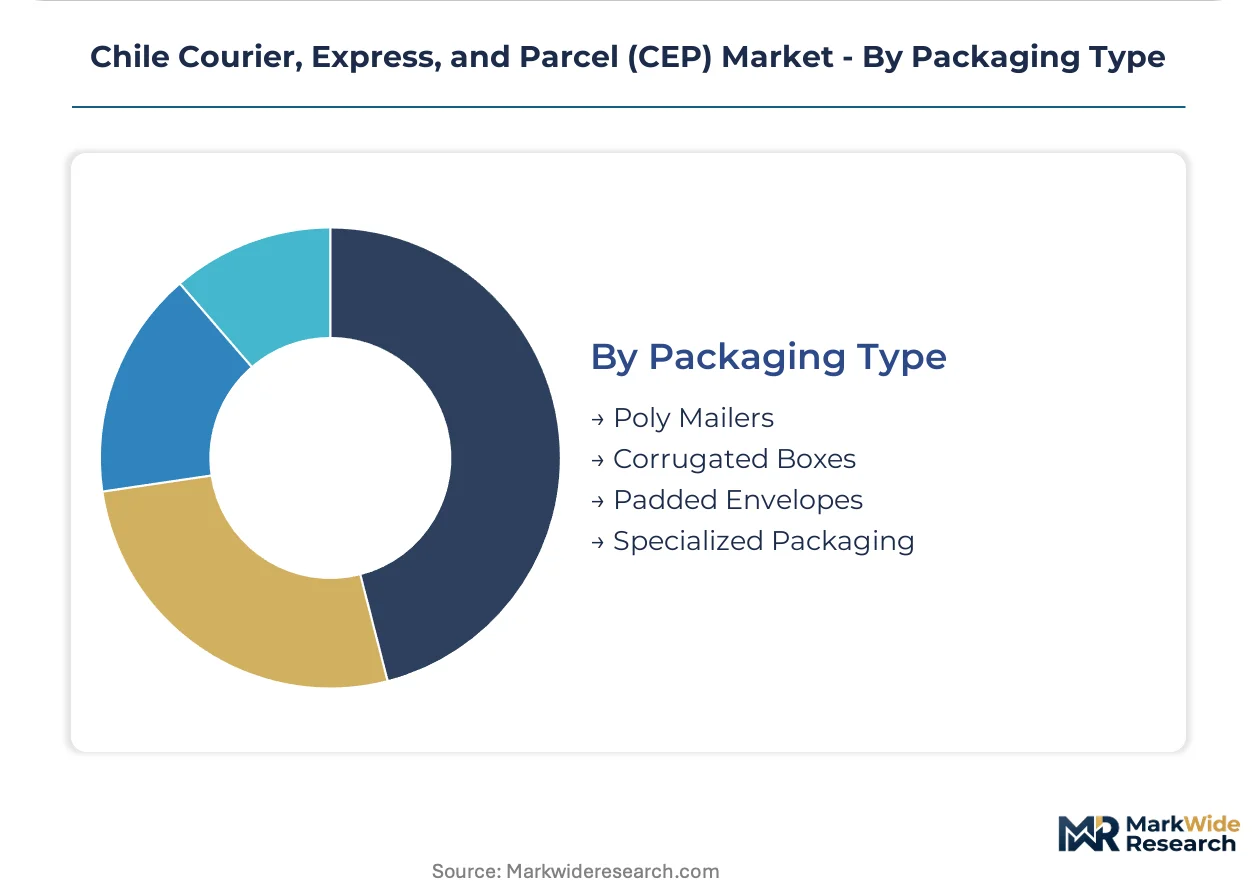
Corrugated Boxes handle the majority of parcel volume; Specialized Packaging is gaining share fastest through pharmaceutical and fresh produce segment expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chile's national logistics modernization programs are redistributing CEP demand across metropolitan and regional corridors. Sub-regional performance varies with e-commerce penetration, mining supply chain density, and cross-border gateway proximity.
Metropolitan Region
Santiago anchors national CEP volume through concentrated e-commerce fulfillment and SME marketplace seller density. Chile's Customs Service digital import processing requirements accelerate clearance for international parcels entering through Arturo Merino Benítez International Airport. Last-mile micro-fulfillment nodes proliferate in Providencia and Las Condes to support same-day delivery commitments.
Valparaíso Region
Port-centric logistics and commuter corridor density shape delivery network design around the Pacific gateway. The Consumer Protection Agency enforces delivery transparency standards that influence carrier technology investments in real-time tracking platforms. Viña del Mar and Valparaíso city centers experience acute driver scarcity during peak e-commerce windows.
Biobío Region
Concepción's industrial base generates B2B parcel flows tied to manufacturing and construction supply chains. Central bank foreign exchange documentation requirements introduce friction for SME exporters accessing Mercosur markets. Hub-and-spoke line-haul investments are expanding next-day delivery coverage from Santiago.
Coquimbo Region
La Serena presents underdeveloped last-mile density where carriers can establish network presence ahead of competitor entry. Temperature-controlled infrastructure investments support pharmaceutical and fresh produce segments moving through the agricultural corridor. Digital tracking adoption lags metropolitan benchmarks, constraining service tier differentiation.
Antofagasta Region
Mining supply chains dominate B2B express demand with time-definite and specialized cargo requirements. Deutsche Post DHL Group and FedEx maintain presence to serve extractive industry logistics needs. Remote location premiums and fuel cost volatility compress margins on long-haul corridors from Santiago.
Chile Courier, Express, and Parcel (CEP) Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and service-level positioning. The market structures around three tiers: established domestic networks with ISO 9001 quality credentials, international gateway operators controlling cross-border flows, and technology-enabled entrants targeting urban same-day segments. Consolidation pressures concentrate among mid-tier operators lacking compliance scale. Dominant competitive moves include sorting hub automation investments and strategic partnerships with e-commerce platforms for API-integrated fulfillment.
Within the established domestic tier, Chilexpress and Correos de Chile anchor national coverage through extensive last-mile infrastructure across regional cities. Among international gateway operators, Deutsche Post DHL Group exemplifies cross-border compliance integration with customs platforms, while FedEx occupies a position serving specialized industrial segments. These three companies represent the archetypal competitive positions: domestic network density, international gateway control, and premium service specialization.
| Leading Market Players |
|---|
| Chilexpress |
| Correos de Chile |
| Deutsche Post DHL Group |
| FedEx |
| United Parcel Service of America Inc (UPS) |
| DSV A/S |
| Empresas Copec SA |
| Redmegacentro SA |
| Yango Deliver |
| Others |
Pricing and Supply Chain Analysis
ISO 9001 certification gates both supplier qualification and price tiering in Chile's CEP sector, forcing mid-tier operators into costly compliance cycles while enabling certified incumbents to capture premium spreads on cross-border and temperature-controlled segments.
Pricing Analysis
Certification level creates the primary spread between domestic network operators and cross-border specialists. Pricing stratifies across premium, standard, and economy tiers, with ISO 9001-credentialed carriers commanding 15-25% uplifts on pharmaceutical and mining supply chain contracts. Cost compression in standard shipping intensifies as Chilexpress leverages extensive regional coverage to absorb volume from price-sensitive B2B shippers. Metropolitan Region millennials exhibit lowest price sensitivity, prioritizing same-day delivery speed over cost minimization.
Supply Chain Analysis
Chile and Brazil anchor South American sorting infrastructure for Mercosur-bound parcel flows, while the United States and Germany control international gateway capacity into Santiago. Diesel fuel, RFID scanning hardware, and refrigerated vehicle units constitute critical input dependencies. Single-source vulnerability concentrates in long-haul line-haul capacity connecting Santiago to regional cities. Distribution runs through hub-and-spoke networks with evening cutoff times, supplemented by urban micro-fulfillment nodes in Providencia and Las Condes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital freight platforms and crowd-sourced delivery models threaten incumbent volume capture, forcing established carriers to defend substitution risk through certification moats and technology integration depth.
For Market Incumbents: Shield core B2B relationships by deepening backward integration into temperature-controlled fleet assets and accelerating ERP modernization for real-time tracking compliance with Consumer Protection Agency mandates. Anchor defensive positioning against Yango Deliver and other platform-native entrants through API-locked e-commerce partnerships. For New Entrants and Emerging Players: Anchor in Concepción and La Serena corridors where last-mile density remains underdeveloped and established carrier coverage gaps create white-space opportunity. Target SME marketplace sellers in the Biobío Region with simplified customs documentation services integrated directly with Chile's Customs Service digital platforms. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated sorting infrastructure and cold chain vehicle fleets, favoring scaled operators with existing ISO 9001 credentials. Acquisition targets should display regional city hub-and-spoke presence combined with direct customs platform integration. Monitor diesel price volatility and driver availability indices as inflection signals for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Sorting Hub Deployment | Item-level RFID tracking enables scan-at-every-node transparency demanded by Metropolitan Region millennials. |
| Cold Chain Fleet Expansion | Temperature-controlled capacity captures pharmaceutical and fresh produce segments from general freight operators. |
| Customs Platform Integration | Direct API connectivity with Chile's Customs Service accelerates SME onboarding for Mercosur exports. |
| Urban Micro-Fulfillment Network | Providencia and Las Condes nodes compress same-day delivery windows against platform-native competitors. |
| ISO 9001 Certification Acceleration | Quality credentials bifurcate competitive tiers and unlock premium pricing on cross-border segments. |
Research Methodology
The analysis maps same-day delivery, next-day delivery, standard shipping, and international shipping segments, each validated through carrier operations directors, e-commerce platform logistics managers, customs brokerage specialists, and SME marketplace sellers. Primary fieldwork combined with secondary validation from Chile Customs Service documentation, central bank foreign exchange regulation filings, Consumer Protection Agency enforcement records, and carrier fleet investment disclosures. Bottom-up volume modeling triangulated against top-down macroeconomic consumption indicators.
Consistency checks validated outputs against external benchmarks across service type, delivery mode, customer type, and packaging type segmentation dimensions. CAGRs were derived through trend extrapolation and driver elasticity modeling across the projection horizon. Forecast inputs incorporated e-commerce penetration rates in Santiago and Valparaíso, diesel price volatility indices, and regional city infrastructure development timelines.
Decision-makers should treat outputs as directional under assumptions of sustained Customs Service modernization and stable foreign exchange documentation requirements; material deviation in regulatory alignment or fuel cost trajectories would warrant model refresh. Recalibration cycles align with material shifts in e-commerce platform consolidation patterns and last-mile labor availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Czech Republic Third-Party Logistics Market
Logistics and Shipping
United States FTL Freight Brokerage Market
Logistics and Shipping
Turkey Courier Express and Parcel (CEP) Market
Logistics and Shipping
Chile Air Freight Transport Market
Logistics and Shipping
Europe Container Terminal Operations Market
Logistics and Shipping
China Freight Forwarding Market
Logistics and Shipping
US Fourth-Party Logistics (4PL) Market
Logistics and Shipping
US Mexico Cross Border FTL Freight Transport Market
Logistics and Shipping
ASEAN Cross Border Road Freight Transport Market
Logistics and Shipping
Canada Freight and Logistics Market
Logistics and Shipping
UK Logistics Market
Logistics and Shipping
North America Cross Border Road Freight Transport Market
Logistics and Shipping
New Zealand Freight and Logistics Market
Logistics and Shipping
Iraq Freight and Logistics Market
Logistics and Shipping
Apparel Logistics Market
Logistics and Shipping
Indonesia Cold Chain Logistics Market