
 India Courier, Express, and Parcel (CEP) Market | 2026-2036
India Courier, Express, and Parcel (CEP) Market Size, Share, and Industry Trends Forecast 2026-2036
India Courier, Express, and Parcel (CEP) Market Insights
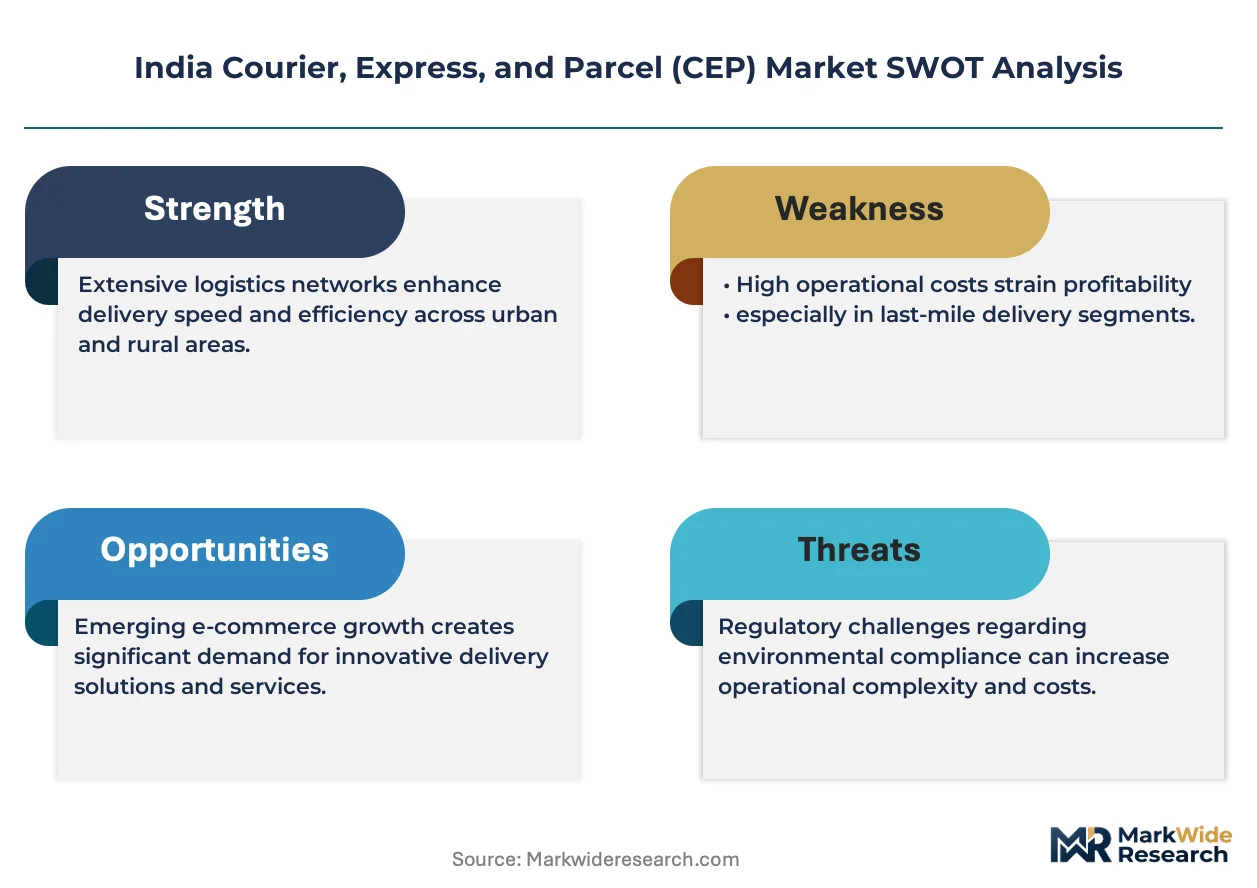
Last-mile delivery economics is rewriting margin allocation across the India CEP landscape. Delhivery Ltd. leverages its proprietary logistics operating system to control fulfillment density in dense urban corridors. Blue Dart Express Ltd anchors premium express services through its dedicated aviation network and temperature-controlled infrastructure. DTDC Express Ltd competes via franchisee penetration into semi-urban and rural pin codes where organized competition remains thin.
India Courier, Express, and Parcel (CEP) services constitute time-definite logistics solutions encompassing document handling, package consolidation, multimodal transportation, and doorstep delivery with track-and-trace capabilities. The sector operates on hub-and-spoke distribution architectures with automated sorting facilities, real-time inventory visibility, and dynamic route optimization algorithms serving B2B procurement cycles, B2C fulfillment, and cross-border trade facilitation. Standard delivery and next-day delivery segments absorb the majority of parcel volumes as e-commerce marketplaces negotiate bulk rate contracts, while same-day delivery commands premium pricing in metropolitan zones where warehouse proximity shortens fulfillment windows. B2C and e-commerce customer types generate the fastest volume expansion as direct-to-consumer brands bypass traditional retail distribution, though B2B contracts sustain higher per-shipment yields through enterprise SLA structures.
BIS standards for packaging integrity, DGCA drone operational guidelines, and state-level motor vehicle regulations for electric logistics fleets collectively shape compliance costs and technology investment priorities across the sector. The PLI scheme for logistics infrastructure accelerates automated sorting capex as operators seek subsidy-linked capacity expansion in designated freight corridors. Stakeholders must monitor evolving drone delivery permissions and EV charging infrastructure mandates as these frameworks determine next-generation network economics and competitive moat durability.
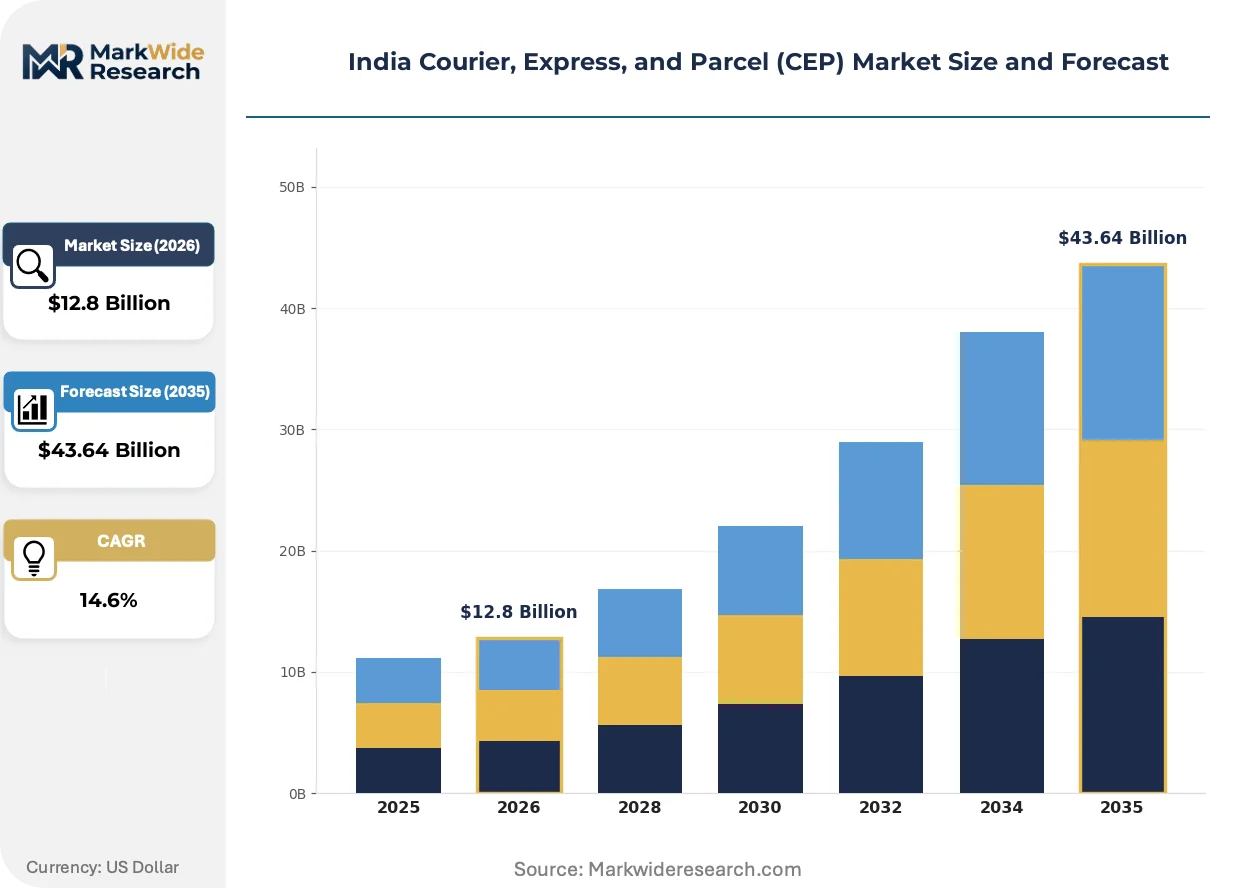
Market Dynamics
Hub-and-spoke network densification in tier-2 and tier-3 Indian cities is compressing fulfillment windows and forcing capex into automated sorting infrastructure. The PLI scheme for logistics infrastructure accelerates subsidy-linked capacity expansion as operators chase density economics in emerging consumption corridors.
Growth Catalysts
- E-commerce penetration:Direct-to-consumer brands bypass traditional retail distribution, generating parcel volume expansion in semi-urban pin codes where organized logistics presence remains nascent.
- DGCA drone guidelines:Operational permissions for beyond-visual-line-of-sight trials enable last-mile aerial delivery pilots in dense urban corridors, reducing ground congestion costs.
- PLI scheme incentives:Subsidy-linked automated sorting capex accelerates network modernization as operators expand capacity in designated freight corridors.
Market Restraints
- Diesel price volatility:Fuel constitutes 25-30% of last-mile operating costs, compressing margins on standard delivery segments where rate competition is intense.
- Aviation slot scarcity:Premium express services face capacity constraints at Mumbai and Delhi airports, limiting overnight network expansion.
- Real estate inflation:Fulfillment center rents in Maharashtra and Karnataka industrial zones outpace revenue per shipment growth.
Strategic Opportunities
- Northeast India corridor:Guwahati and Imphal emerge as underserved fulfillment hubs with thin organized competition and rising smartphone commerce penetration.
- Temperature-controlled pharma logistics:CDSCO cold chain mandates for biologics distribution create specialized service tiers with premium yield structures.
- EV fleet mandates:State-level electric logistics vehicle regulations in Delhi and Maharashtra accelerate charging infrastructure partnerships and green brand positioning.
Industry Challenges
- Warehouse management system integration:Legacy ERP architectures at mid-market e-commerce clients resist API-native track-and-trace connectivity, delaying real-time visibility deployment.
- Sorting automation talent:Robotics maintenance and conveyor optimization skills concentrate in Bengaluru and Pune, creating wage inflation for specialized technicians.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Courier, Express, and Parcel (CEP) Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $43.64 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard Delivery, Same-Day Delivery, Next-Day Delivery, International Shipping Customer Type: B2B, B2C, E-commerce, Retail Delivery Mode: Ground, Air, Sea, Rail Package Size: Small Parcel, Medium Parcel, Large Parcel, Bulky Goods |
| Companies Covered | Delhivery Ltd., Blue Dart Express Ltd, DTDC Express Ltd, DHL Express (India) Pvt Ltd, FedEx Express, India Post, Allcargo Gati Ltd, XpressBees Logistics Pvt Ltd, Shadowfax Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Courier, Express, and Parcel (CEP) Market Trends and Innovations
Digital freight matching and predictive routing algorithms are compressing empty-mile ratios across Indian CEP networks. Technology convergence between IoT sensors and machine learning platforms enables dynamic capacity allocation that responds to demand spikes within hours rather than days.
Cloud-native logistics operating systems are virtualizing dispatch and route optimization functions that previously required on-premise infrastructure. Mid-tier e-commerce sellers adopt software-as-a-service fulfillment platforms at accelerating pace. This virtualization is compressing the capital barrier for network participation, enabling asset-light competitors to coordinate third-party capacity through algorithmic matching.
BIS standards for packaging integrity mandate drop-test certifications and tamper-evident seals for cross-border shipments. Compliance costs concentrate on small exporters lacking in-house testing facilities. Pharmaceutical and electronics verticals face the steepest adaptation timelines as they retrofit existing packaging workflows to meet documentation requirements.
Direct brand-to-consumer shipping is displacing marketplace-fulfilled models as merchants seek margin recovery and customer data ownership. Fashion and personal care verticals lead this channel pivot, building captive delivery promises through hybrid owned-contracted fleet structures. Gujarat and Tamil Nadu manufacturing clusters show the highest merchant adoption rates as export-oriented producers pivot to domestic direct sales.
India Courier, Express, and Parcel (CEP) Market Segmentation
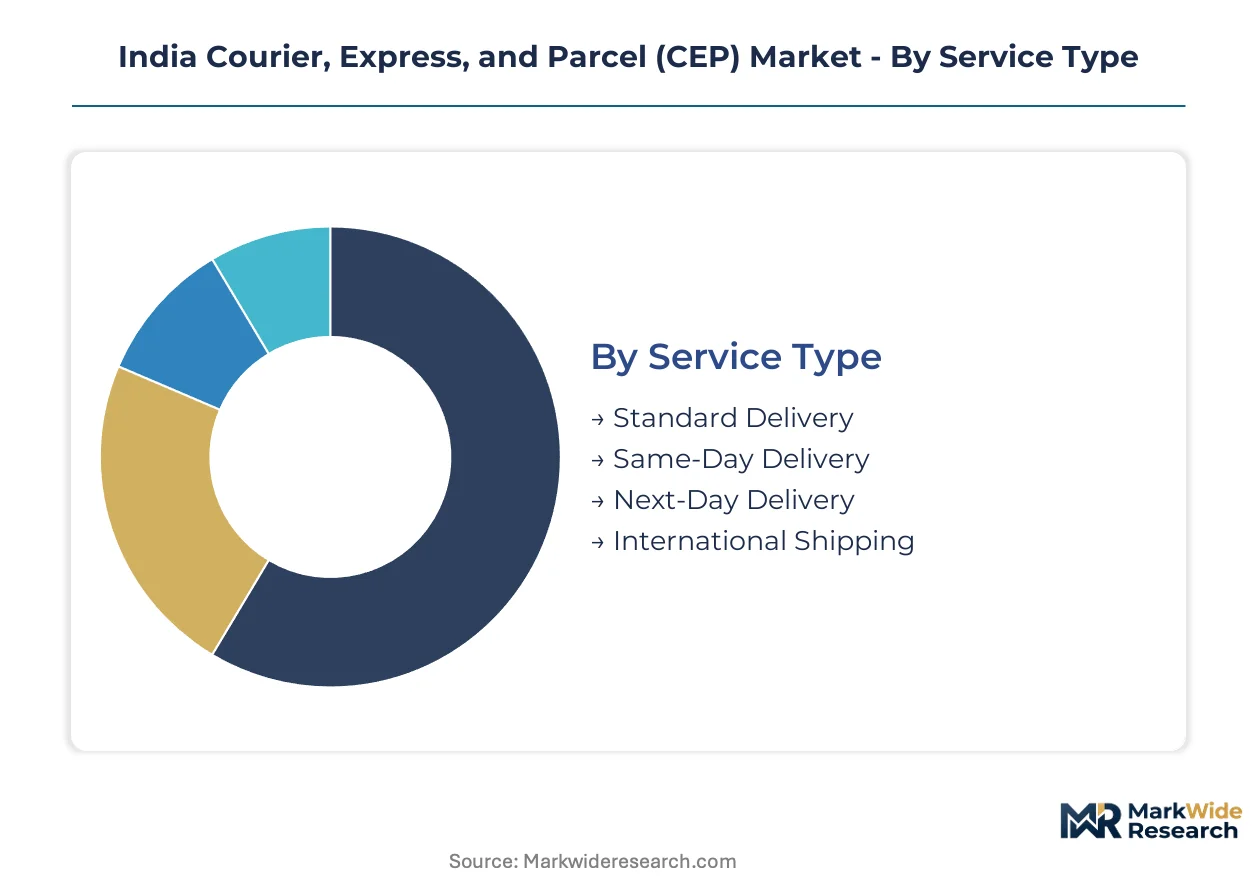
India CEP operators calibrate network capacity through granular service tiers that match fulfillment velocity to customer willingness to pay. Segment-specific infrastructure requirements—from aviation slots for express to rail containerization for bulk—determine capital allocation and margin profiles across the value chain.
Service Type:
Cycle times compress from 72-hour standard windows to sub-24-hour express commitments, creating distinct asset intensity requirements across the service spectrum.
- Standard Delivery:Hub-and-spoke ground networks consolidate parcels through automated sorting facilities with 48-72 hour commitment windows. E-commerce marketplaces negotiate bulk rate contracts for Maharashtra and Karnataka fulfillment corridors where warehouse density supports cost-efficient batch processing.
- Next-Day Delivery:Overnight aviation networks and midnight sortation shifts compress fulfillment to sub-24-hour cycles. Mumbai and Delhi airport slot scarcity constrains capacity expansion for premium express commitments.
- Same-Day Delivery:Hyperlocal micro-fulfillment nodes within 15-kilometer radii of dense urban cores enable sub-6-hour delivery windows. Bengaluru and Hyderabad metro zones absorb concentrated demand from quick-commerce platforms.
- International Shipping:Customs-bonded express corridors and DGFT documentation workflows facilitate cross-border parcel flows. Gujarat Mundra port cluster anchors export-oriented CEP volumes for SME manufacturers.
Standard delivery dominates installed base through e-commerce volume aggregation. Same-day delivery is where expansion concentrates as quick-commerce platforms extend service promises.
Customer Type:
Contract structures diverge sharply between enterprise SLA frameworks and transactional consumer fulfillment, reshaping revenue predictability and working capital requirements.
- B2B:Enterprise procurement cycles with defined SLAs sustain higher per-shipment yields through dedicated account management and scheduled pickup windows. Manufacturing clusters in Tamil Nadu and Gujarat generate concentrated contract logistics demand.
- E-commerce:Marketplace-fulfilled and seller-fulfilled models drive volume expansion through return logistics integration and COD reconciliation infrastructure. Tier-2 and tier-3 city penetration accelerates smartphone commerce adoption.
- B2C:Direct-to-consumer brands bypass retail intermediaries, building captive delivery promises through hybrid fleet ownership. Fashion and personal care verticals lead channel pivot toward customer data ownership.
- Retail:Omnichannel fulfillment bridges physical store inventory with online order capture, requiring real-time stock synchronization across distributed POS systems.
B2B contracts anchor revenue stability through annual rate negotiations. E-commerce is climbing the fastest as marketplace sellers expand into semi-urban pin codes.
Delivery Mode:
Modal selection trades speed against unit economics, with aviation premiums justified only for time-critical or high-value cargo categories.
- Ground:Diesel-powered and emerging electric truck fleets handle 80-plus percent of domestic parcel volumes through national highway corridors. State-level EV mandates in Delhi and Maharashtra accelerate charging infrastructure partnerships.
- Air:Dedicated freighter and belly-hold cargo capacity supports premium express commitments with next-morning delivery guarantees. DGCA operational guidelines shape network reliability metrics.
- Sea:Containerized less-than-container-load consolidation serves cost-sensitive bulk shipments with 7-14 day transit tolerance. Coastal manufacturing clusters leverage this mode for inter-city distribution.
- Rail:Indian Railways parcel services and private container operators offer intermediate speed-cost positioning for non-urgent freight corridors.
Ground transport commands installed base dominance through last-mile density requirements. Air freight is gaining share fastest as premium express services expand aviation networks.
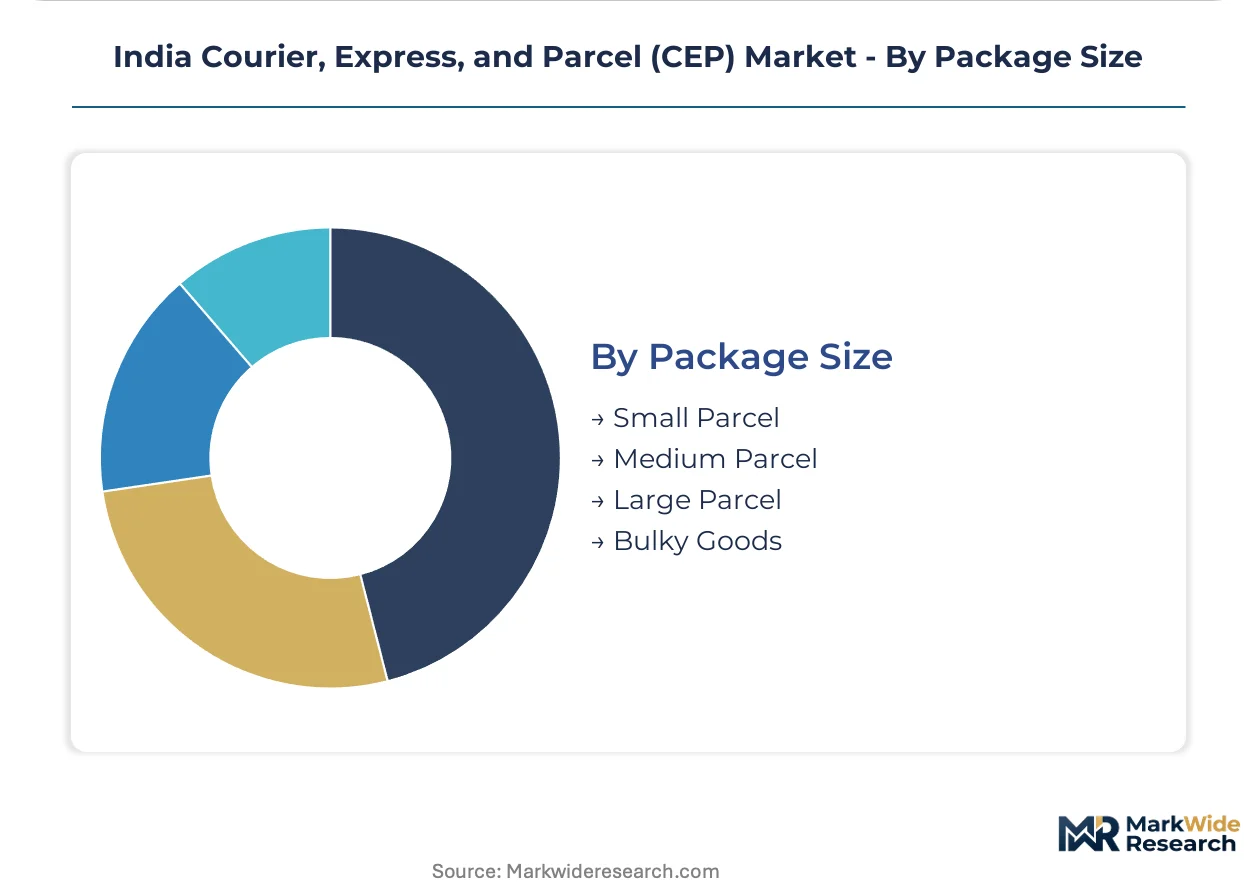
Package Size:
Dimensional weight pricing and sorting automation compatibility segment handling infrastructure and labor intensity requirements.
- Small Parcel:Document envelopes and smartphone-scale electronics fit automated conveyor systems with minimal manual intervention. BIS packaging integrity standards mandate drop-test certifications for cross-border flows.
- Medium Parcel:Apparel, footwear, and consumer electronics constitute the volume core for e-commerce fulfillment, optimizing automated sortation throughput.
- Large Parcel:Home appliances and furniture require specialized handling equipment and two-person delivery crews with installation capabilities.
- Bulky Goods:Industrial equipment and construction materials demand flatbed trucking and crane-assisted unloading, operating outside standard CEP network economics.
Medium parcels dominate throughput volume through e-commerce standardization. Small parcels represent the steepest expansion trajectory as direct-to-consumer brands shrink package profiles for cost efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra concentrates premium express volumes through Mumbai's aviation corridor while Gujarat dominates export-oriented bulk flows; Karnataka and Tamil Nadu split e-commerce fulfillment density between Bengaluru's tech corridors and Chennai's manufacturing hinterlands.
Maharashtra
Mumbai and Pune absorb the highest premium express parcel densities as financial services and pharmaceutical enterprises demand sub-24-hour delivery commitments. The state's EV logistics mandates under the Maharashtra Electric Vehicle Policy accelerate charging infrastructure deployment along the Mumbai-Pune Expressway. Thane-Bhiwandi industrial belt anchors automated sorting investments as operators chase last-mile density in the Mumbai Metropolitan Region.
Gujarat
Ahmedabad and Surat manufacturing clusters generate concentrated B2B contract logistics demand through textile and chemical export corridors. DGFT documentation workflows at Mundra and Hazira ports facilitate cross-border express volumes for SME exporters. Sanand-Vithalapur automotive belt drives specialized handling requirements as component suppliers adopt just-in-time delivery structures.
Karnataka
Bengaluru's quick-commerce platforms command same-day delivery density in Whitefield and Electronic City corridors where micro-fulfillment nodes cluster. The state's PLI scheme for logistics infrastructure subsidizes automated sorting capex in Hoskote and Nelamangala freight zones. Mysuru and Mangalore emerge as secondary fulfillment hubs as smartphone commerce penetrates tier-2 Karnataka districts.
Tamil Nadu
Chennai's Sriperumbudur-Oragadam automotive corridor sustains high-yield B2B contracts with defined SLA structures for component logistics. CDSCO cold chain mandates for pharmaceutical distribution create specialized temperature-controlled service tiers in the Chennai pharma cluster. Coimbatore and Tiruppur textile exporters drive international shipping volumes through streamlined customs-bonded express channels.
Telangana
Hyderabad's pharmaceutical and electronics manufacturing generates premium express demand through Genome Valley and Pocharam industrial corridors. The Telangana EV policy mandates electric logistics fleet adoption in Hyderabad Metropolitan Development Authority zones by 2027. Shamshabad airport cargo terminal expansion supports overnight aviation network growth for time-critical biologics distribution.
India Courier, Express, and Parcel (CEP) Market Competitive Landscape
Capability concentration sits with integrated express operators commanding dedicated aviation networks; scale advantage sits with ground-network consolidators leveraging franchisee penetration. The market structures around three tiers: premium express specialists with temperature-controlled infrastructure, mid-market e-commerce fulfillment platforms with proprietary logistics operating systems, and asset-light hyperlocal coordinators. Dominant competitive moves include automated sorting capex expansion in designated freight corridors and strategic partnerships with quick-commerce platforms for micro-fulfillment node access.
Within the premium express tier, Blue Dart Express Ltd anchors dedicated aviation network coverage through controlled temperature infrastructure. Delhivery Ltd exemplifies the integrated platform archetype with proprietary logistics operating systems spanning fulfillment density management. DTDC Express Ltd occupies the franchisee-scale position with penetration into semi-urban and rural pin codes where organized competition remains thin. These three represent distinct strategic postures rather than direct substitutability.
| Leading Market Players |
|---|
| Delhivery Ltd. |
| Blue Dart Express Ltd |
| DTDC Express Ltd |
| DHL Express (India) Pvt Ltd |
| FedEx Express |
| India Post |
| Allcargo Gati Ltd |
| XpressBees Logistics Pvt Ltd |
| Shadowfax Technologies |
| Others |
Pricing and Supply Chain Analysis
Diesel price volatility between Indian refineries and last-mile operators compresses margin spreads across standard delivery tiers while forcing network redesign toward electric fleet partnerships. This fuel dependency simultaneously widens the premium-to-economy price gap and accelerates hub consolidation in designated freight corridors where PLI subsidies offset infrastructure capex.
Pricing Analysis
Long-term offtake contracts with e-commerce marketplaces anchor revenue predictability for ground-network operators, while spot pricing governs ad-hoc SME shipments and peak-season surge capacity. Price differentiation hinges on delivery velocity commitments and BIS packaging certification tiers, with same-day metro premiums widening against standard delivery compression. Pricing pressure stems from diesel cost pass-through limitations in bulk-rate B2C contracts. E-commerce marketplace sellers exhibit highest price sensitivity, while pharmaceutical enterprises accept premium express rates for temperature-controlled SLAs.
Supply Chain Analysis
Tariff exposure between Indian customs authorities and cross-border SME exporters concentrates compliance costs on documentation workflows at Gujarat port clusters. Domestic network infrastructure draws from Maharashtra sorting hub concentration, Karnataka robotics talent pools, and Tamil Nadu manufacturing hinterlands. Critical dependencies include aviation turbine fuel, automated conveyor systems, and electric vehicle batteries. Single-source vulnerability sits with Mumbai and Delhi airport slot allocations for premium express capacity. Distribution runs through franchisee-owned last-mile nodes in tier-2 and tier-3 pin codes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India CEP market sits in a cyclical recovery phase driven by e-commerce penetration normalization after pandemic-era distortion. Tier-2 and tier-3 city expansion sustains volume momentum as smartphone commerce matures.
For Market Incumbents: Harden automated sorting infrastructure in PLI-designated freight corridors to defend density economics against asset-light challengers. Lock in exclusive micro-fulfillment node partnerships with quick-commerce platforms before competitor encroachment. Prioritize backward integration into electric fleet leasing to offset diesel volatility exposure.
For New Entrants and Emerging Players: Establish a beachhead in temperature-controlled pharmaceutical logistics where CDSCO mandates create specialized service gaps. Target Northeast India corridor white space in Guwahati and Imphal with thin organized competition. Pursue SaaS-native fulfillment platform positioning to bypass heavy sorting capex requirements.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated platform operators with proprietary logistics operating systems. Acquisition targets should demonstrate captive aviation network coverage or franchisee scale in underserved pin codes. Watch DGCA drone delivery permission expansion as the signal for next-generation network economics inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Sorting Capacity Expansion | PLI scheme subsidies in Maharashtra and Karnataka freight zones accelerate subsidy-linked modernization timelines. |
| Electric Fleet Partnership | State-level EV mandates in Delhi and Maharashtra create charging infrastructure co-investment opportunities with grid operators. |
| Micro-Fulfillment Node Network | Quick-commerce platform alliances in Bengaluru and Hyderabad corridors secure sub-6-hour delivery density. |
| Temperature-Controlled Infrastructure | CDSCO cold chain mandates for biologics distribution unlock premium-yield pharmaceutical vertical specialization. |
| Drone Delivery Pilot Program | DGCA beyond-visual-line-of-sight permissions enable last-mile aerial trials reducing ground congestion costs. |
Research Methodology
The analysis maps standard delivery, express delivery, same-day delivery, and international shipping segments, each validated through logistics operating system architects, franchisee network operators, e-commerce fulfillment managers, and aviation cargo coordinators. Primary intelligence combined structured interviews with secondary validation against DGCA operational guidelines, BIS packaging standards, PLI scheme notifications, and customs-bonded express documentation workflows. Bottom-up parcel volume modeling and top-down GDP-correlation approaches were triangulated for convergence.
Assumptions held fixed include prevailing DGCA drone regulations, state-level EV fleet mandates, and PLI subsidy eligibility criteria; variables tested across diesel price bands, e-commerce penetration rates, and aviation slot availability scenarios. Segmentation dimensions modeled encompass service velocity tiers, customer contract structures, modal transport categories, and package size profiles. CAGRs were derived from logistic curve fitting to smartphone commerce adoption patterns and fulfillment center density trajectories. Forecast inputs incorporated tier-2 and tier-3 pin code penetration rates alongside quick-commerce platform expansion timelines.
Stress conditions across fuel cost volatility, regulatory permission delays, and real estate inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on subsidy continuity and infrastructure buildout schedules. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Global Retail 3PL Market
Logistics and Shipping
Multicarrier Shipping Software Market
Logistics and Shipping
Europe Courier Market
Logistics and Shipping
Remanufacturing and Core Returns Logistics Management Market
Logistics and Shipping
North America Logistics Automation Market
Logistics and Shipping
Global Drone Logistics and Transportation Market
Logistics and Shipping
Global 5PL Solutions Market
Logistics and Shipping
Switzerland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Autonomous Last Mile Delivery Market
Logistics and Shipping
Latin America Contract Logistics Market
Logistics and Shipping
Japan Cross-Border E-Commerce Logistics Market
Logistics and Shipping
Slovakia Freight and Logistics Market
Logistics and Shipping
Philippines Freight and Logistics Market
Logistics and Shipping
GCC Trailer Market
Logistics and Shipping
Outbound Logistics Market
Logistics and Shipping
Saudi Arabia Secure Logistics Market