
 Control Towers Market | 2026-2036
Control Towers Market Size, Share, and Industry Trends Forecast 2026-2036
Control Towers Market Intelligence
Platform licensing revenue is fragmenting between modular SaaS providers and legacy ERP incumbents. SAP SE leverages its embedded customer base across manufacturing verticals to sustain recurring integration contracts. Kinaxis Inc. differentiates through concurrent planning algorithms that anchor high-margin aerospace and pharmaceutical accounts. E2open, LLC competes on multi-tier supplier visibility, controlling data exchange protocols across automotive networks.
A control tower integrates real-time data streams from ERP, WMS, TMS, and IoT sensor networks into a unified decision layer, typically processing millions of events per hour to enable predictive exception management and automated response triggering. Cloud deployment configurations lead segment economics due to lower capital barriers and faster implementation cycles, while edge computing architectures represent the fastest-growing configuration as latency-sensitive applications expand in transportation and cold-chain logistics. AI and machine learning technology layers capture disproportionate margin pools through subscription-based predictive analytics modules.
The EU AI Act, GDPR, and ISO 27001 frameworks impose algorithmic transparency and data residency requirements that shape procurement criteria for European control tower deployments. The US FDA and NHTSA regulate traceability standards in pharmaceutical and automotive supply chains, directly mandating audit-ready visibility infrastructure. Stakeholders must monitor how divergent sovereignty requirements across Germany, the United States, and China reshape architecture decisions for multi-national implementations.
Market Dynamics
Automotive manufacturers are consolidating supplier networks around cloud-native orchestration layers that mandate real-time data sovereignty compliance across German, US, and Chinese regulatory jurisdictions simultaneously.
Growth Catalysts
- EU AI Act transparency mandates:The regulation's algorithmic audit requirements force automotive and pharmaceutical manufacturers to deploy auditable decision-support infrastructure, directly expanding control tower procurement budgets.
- Cold-chain IoT sensor density:Temperature-sensitive pharmaceutical distribution networks in Germany and the United States now require sub-second latency exception management, accelerating edge computing architecture adoption.
- Automotive multi-tier visibility:Tier-1 suppliers in China face OEM-mandated data exchange protocols that necessitate unified control tower platforms spanning three or more supplier tiers.
Market Restraints
- GDPR data residency costs:European deployments require sovereign cloud infrastructure that adds 15-25% implementation overhead compared to standard cloud configurations.
- Legacy ERP integration complexity:SAP and Oracle embedded bases create switching friction that extends sales cycles and inflates professional services requirements.
- ISO 27001 certification timelines:Six-to-twelve-month audit cycles delay production deployments for aerospace and defense contractors with classified supply chain requirements.
Strategic Opportunities
- India manufacturing corridor expansion:PLI scheme incentives for electronics and automotive OEMs create first-mover advantage for control tower vendors establishing localized data centers.
- Digital twin convergence:Integration of control tower event streams with physics-based simulation models enables predictive scenario planning for semiconductor supply networks.
- Brazil agricultural logistics:ANVISA traceability mandates for pharmaceutical distribution and expanding soy export corridors generate demand for multi-modal visibility platforms.
Industry Challenges
- Concurrent planning expertise scarcity:Kinaxis-style algorithmic optimization requires specialized supply chain mathematicians that command premium compensation packages exceeding standard ERP consultant rates.
- Multi-sovereignty architecture complexity:Implementations spanning German GDPR, Chinese data localization, and US FDA requirements demand jurisdictional data partitioning that fragments platform economics.
- Sensor interoperability gaps:Proprietary IoT protocols from WMS and TMS vendors create data normalization bottlenecks that consume 30-40% of implementation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Control Towers Market |
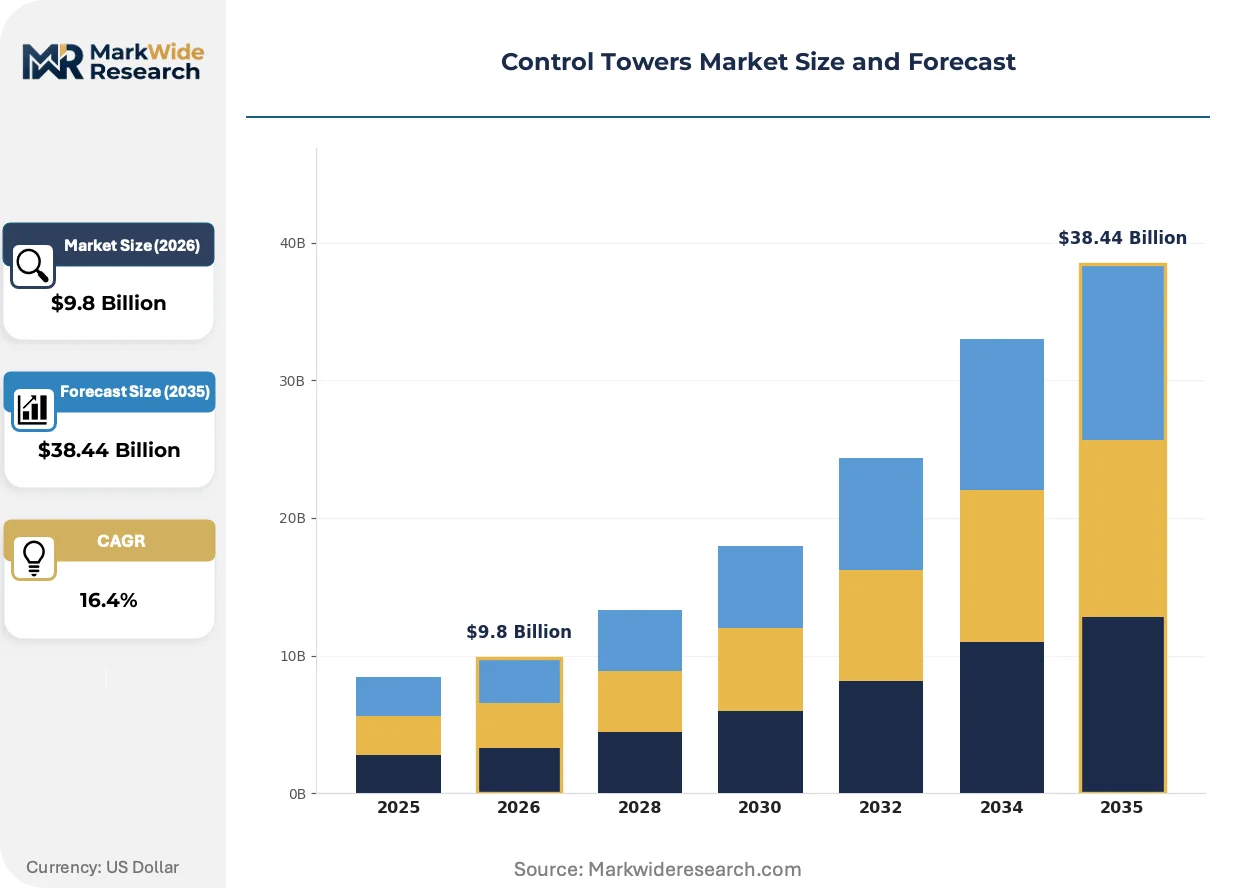
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $38.44 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT, AI, Big Data, Machine Learning Deployment: Cloud, On-Premises, Hybrid, Edge End User: Manufacturing, Logistics, Retail, Transportation Application: Supply Chain Management, Inventory Control, Risk Management, Order Fulfillment |
| Companies Covered | Kinaxis Inc., E2open, LLC, SAP SE, Coupa Software Inc., Infor, Blue Yonder Group, Inc., IBM Corporation, One Network Enterprises, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Control Towers Market Strategic Shifts & Innovations
Control tower architectures are bifurcating between centralized cloud intelligence and distributed edge autonomy, with regulatory latency requirements determining deployment topology across transportation verticals.
Digital twin technology is migrating from static simulation models to live digital shadows that ingest real-time ERP, WMS, and IoT streams for continuous supply chain state representation. Automotive manufacturers in Germany and the United States are deploying these synchronized replicas to compress scenario planning cycles from weeks to hours. The technology is migrating from pilot programs to production-scale deployments that anchor competitive tender requirements for aerospace contracts.
The EU AI Act's risk-based classification system imposes documentation and human oversight requirements on high-risk supply chain automation decisions. Pharmaceutical distributors must now maintain algorithmic audit trails that satisfy both EMA pharmacovigilance standards and national competent authority inspections. German control tower deployments are responding by embedding explainable AI modules that generate natural-language rationale for automated procurement recommendations.
Subscription-based predictive analytics modules are displacing perpetual-license forecasting tools as buyers prioritize operational expenditure alignment with value realization. Large pharmaceutical wholesalers in the United States now demand outcome-based pricing tied to inventory reduction metrics rather than seat-based licensing. This procurement model compression is most visible in cold-chain logistics where carriers bundle visibility services with transportation rates to capture integrated spend.
Control Towers Market Segmentation
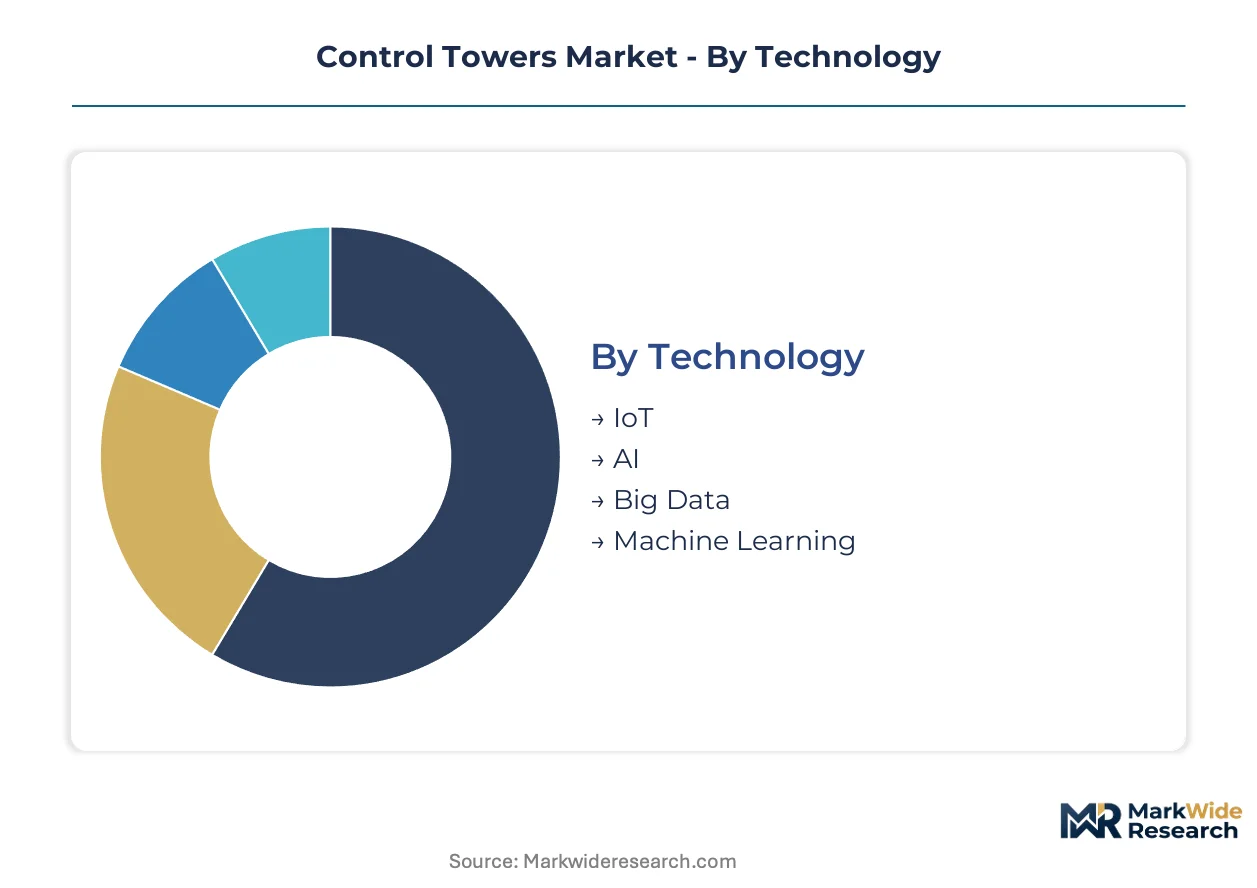
Control tower procurement cycles vary dramatically across technology layers and deployment topologies, with AI modules refreshing every 18-24 months while infrastructure commitments extend to 5-7 years. Understanding these velocity differentials helps vendors align subscription pricing with customer value realization timelines and regulatory recertification schedules.
Technology:
IoT sensor layers turn over fastest as hardware commoditization accelerates replacement cycles, while machine learning cores require longer calibration periods before trust-based deployment.
- IoT:Sensor networks aggregate real-time telemetry from WMS, TMS, and cold-chain monitoring devices. German pharmaceutical distributors deploy these most densely to satisfy EMA pharmacovigilance standards for temperature excursion documentation.
- AI:Explainable decision-support modules generate natural-language rationale for automated procurement recommendations under EU AI Act transparency mandates. Aerospace manufacturers in the United States anchor demand here due to NHTSA and FAA audit requirements.
- Big Data:Unified data lakes normalize ERP, WMS, and IoT streams into queryable event histories for exception pattern analysis.
- Machine Learning:Predictive demand forecasting algorithms require 12-18 month training cycles on proprietary customer data before production deployment.
IoT anchors the volume base while AI gains share at the steepest rate.
Deployment:
Cost tier stratification separates capital-light cloud configurations from sovereign infrastructure investments that carry 15-25% implementation premiums.
- Cloud:Multi-tenant SaaS configurations minimize upfront capital barriers and compress implementation cycles to 8-12 weeks. Automotive OEMs in China favor these for rapid supplier network onboarding.
- On-Premises:Dedicated hardware installations satisfy classified supply chain requirements for aerospace and defense contractors facing ISO 27001 certification timelines.
- Hybrid:Jurisdictional data partitioning splits sensitive planning data on-premises while routing non-sensitive analytics to cloud tiers.
- Edge:Distributed computing nodes process sub-second latency exceptions for cold-chain logistics and autonomous transportation corridors.
Cloud configurations dominate current procurement volumes while edge architectures are expanding most quickly.
End User:
Application maturity separates manufacturing's predictive planning sophistication from transportation's emerging visibility requirements.
- Manufacturing:Multi-tier supplier orchestration platforms mandate real-time data exchange across three or more supplier tiers. German automotive OEMs lead deployment density here.
- Logistics:Multi-modal visibility platforms track container, rail, and last-mile movements through unified event streams.
- Retail:Inventory positioning systems balance stock availability against fulfillment cost optimization.
- Transportation:Carrier-integrated control towers bundle visibility services with transportation rates to capture integrated spend.
Manufacturing anchors the volume base while transportation gains share at the steepest rate.
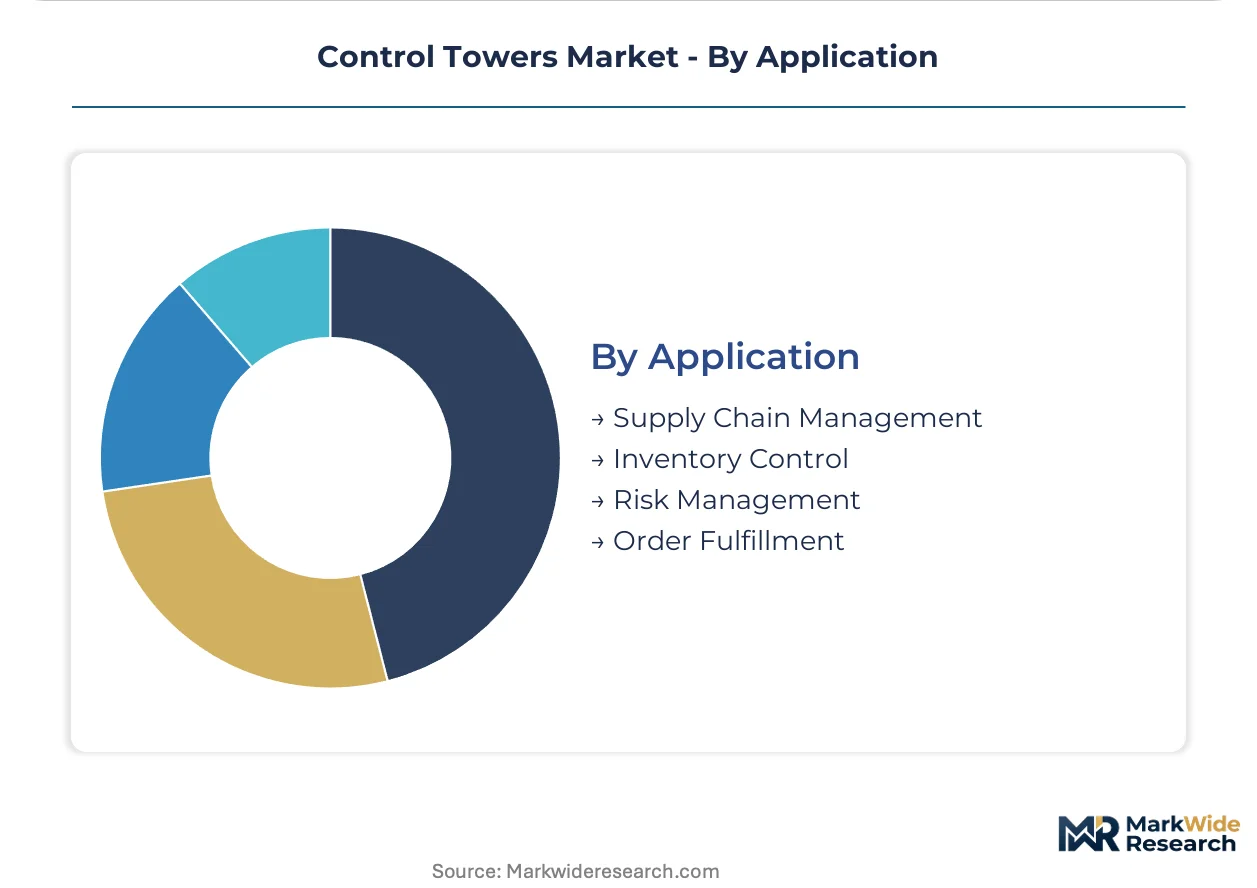
Application:
Margin concentration follows risk exposure, with supply disruption scenarios commanding premium pricing over operational efficiency modules.
- Supply Chain Management:End-to-end orchestration layers integrate procurement, production, and distribution planning into synchronized decision workflows. Pharmaceutical wholesalers in the United States prioritize these for FDA traceability compliance.
- Inventory Control:Automated replenishment algorithms balance service levels against carrying cost minimization.
- Risk Management:Scenario simulation engines model supplier failure, port congestion, and demand shock impacts on network resilience.
- Order Fulfillment:Promise-to-delivery optimization aligns customer commitments with available-to-promise inventory and capacity.
Supply chain management anchors the volume base while risk management gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany demonstrate the lowest price elasticity as EU AI Act compliance mandates override procurement cost considerations, while Chinese automotive OEMs exhibit acute sensitivity to implementation timelines over licensing premiums.
Germany
Automotive manufacturers in Bavaria and Baden-Württemberg mandate real-time multi-tier supplier visibility to satisfy KBA traceability requirements. The EU AI Act's algorithmic transparency obligations force pharmaceutical distributors in Frankfurt-Rhine-Main to embed explainable AI modules. Stuttgart's dense OEM engineering clusters anchor the highest control tower deployment density in Europe.
United States
FDA traceability mandates for pharmaceutical cold chains drive edge computing investments among wholesalers in New Jersey and Pennsylvania. NHTSA audit requirements for automotive suppliers in Michigan and Ohio accelerate concurrent planning platform procurement. The Dallas-Fort Worth logistics corridor generates concentrated demand for multi-modal visibility infrastructure.
China
Automotive OEMs in Shanghai and Guangzhou enforce tier-1 through tier-3 supplier data exchange protocols under MIIT smart manufacturing directives. SAMR data localization requirements fragment platform architectures for multinational deployments. The Yangtze River Delta electronics manufacturing belt generates fastest-growing demand for cloud-native orchestration layers.
India
PLI scheme incentives for electronics and automotive OEMs in Tamil Nadu and Karnataka create first-mover opportunities for localized data center deployments. The country's national pharmaceutical regulator mandates traceability infrastructure that aligns with US FDA export requirements. Maharashtra's automotive supplier clusters in Pune and Chakan drive pilot implementations of multi-tier visibility platforms.
Brazil
ANVISA traceability mandates for pharmaceutical distribution networks in São Paulo and Rio de Janeiro generate demand for temperature-monitoring control towers. Expanding soy export corridors through Santos port drive multi-modal logistics platform procurement. The Southeast industrial belt concentrates implementation resources for cold-chain IoT sensor networks.
Control Towers Market Key Industry Players
Capability concentration sits with specialized algorithmic vendors; scale advantage sits with embedded ERP incumbents. The market structure bifurcates between modular SaaS providers competing on implementation velocity and legacy platform holders defending integration moats. Three archetypes dominate: concurrent planning specialists, multi-tier visibility orchestrators, and ERP-anchored suite providers. Competitive moves center on strategic partnerships with IoT sensor networks and vertical integration into edge computing hardware.
Within the concurrent planning tier, Kinaxis Inc. exemplifies algorithmic optimization positioning for aerospace and pharmaceutical accounts with complex supply network constraints. SAP SE anchors the ERP-embedded archetype, leveraging manufacturing vertical relationships to sustain recurring integration contracts across German and US automotive clusters. E2open, LLC occupies the multi-tier visibility position, controlling data exchange protocols that span automotive supplier networks in China and North America.
| Leading Market Players |
|---|
| Kinaxis Inc. |
| E2open, LLC |
| SAP SE |
| Coupa Software Inc. |
| Infor |
| Blue Yonder Group, Inc. |
| IBM Corporation |
| One Network Enterprises |
| Oracle Corporation |
| Others |
Cost & Logistics Intelligence
Overcapacity in cloud infrastructure across Germany and the United States compresses SaaS hosting margins while simultaneously expanding vendor pricing flexibility for control tower implementations. This utilization dynamic forces platform providers to absorb sovereign cloud premiums internally rather than passing full GDPR compliance costs to European automotive and pharmaceutical buyers.
Pricing Analysis
Long-term subscription contracts anchor the dominant pricing structure, with three-year SaaS agreements locking in recurring revenue for modular providers competing against legacy ERP incumbents. Price differentiation rests on ISO 27001 certification tier and vertical specialization depth, with aerospace-grade deployments commanding substantial premiums over standard manufacturing configurations. Cost compression in mid-market cloud tiers intensifies as Kinaxis-style algorithmic modules commoditize basic predictive analytics. Chinese automotive OEMs exhibit acute price sensitivity focused on implementation velocity, while German pharmaceutical distributors prioritize audit-ready transparency over licensing expenditure.
Supply Chain Analysis
Tariff exposure between the United States and China fragments semiconductor component sourcing for edge computing hardware deployed in automotive control towers. Supply concentration centers on Taiwan for advanced sensors, Germany for precision manufacturing equipment, and China for commodity IoT hardware. Raw material dependencies span silicon wafers, lithium-ion cells for cold-chain monitoring devices, and rare earth elements for magnetic sensors in transportation applications. Single-source vulnerability in concurrent planning algorithm development creates bottlenecks as Kinaxis-style mathematical optimization expertise remains scarce. Distribution runs through direct enterprise sales for large automotive OEMs, with channel partners handling mid-market manufacturing accounts in India and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The control towers market represents a high-growth disruption as EU AI Act transparency mandates force immediate procurement of auditable decision-support infrastructure across automotive and pharmaceutical supply chains.
For Market Incumbents: Insulate embedded customer relationships in German automotive clusters by accelerating ISO 27001 certification timelines and embedding explainable AI modules that preempt regulatory audit requirements. Defend against modular SaaS entrants by deepening API integration moats with SAP and Oracle ERP bases, while capturing edge computing hardware partnerships to control latency-sensitive cold-chain deployments. For New Entrants and Emerging Players: Establish a beachhead in India's PLI scheme manufacturing corridors by deploying localized data centers that satisfy CDSCO traceability mandates for pharmaceutical exports to the United States. Target Brazil's ANVISA-regulated pharmaceutical distribution networks with temperature-monitoring control towers bundled with multi-modal logistics visibility, leveraging channel partnerships with existing WMS providers to compress sales cycles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native orchestration layers as hyperscaler infrastructure commoditizes hosting costs, improving software margin profiles for platform vendors. Acquisition targets should demonstrate concurrent planning algorithm differentiation or multi-tier supplier data exchange protocol control in China or North America. Monitor EU AI Act enforcement patterns as the critical signal for demand inflection in explainable AI module procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Hardware Partnership | Captures sub-second latency requirements for German pharmaceutical cold-chain compliance under EMA standards. |
| Explainable AI Module Development | Satisfies EU AI Act audit mandates for automotive OEMs in Stuttgart and pharmaceutical distributors in Frankfurt. |
| Localized Data Center Deployment | Addresses SAMR data localization requirements for multinational control tower architectures spanning China. |
| Multi-Tier Supplier Protocol Integration | Controls data exchange standards across tier-1 through tier-3 automotive networks in Shanghai and Guangzhou. |
| Concurrent Planning Algorithm Acquisition | Secures scarce mathematical optimization expertise for aerospace accounts facing NHTSA and FAA audit requirements. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with supply chain directors at automotive OEMs, pharmaceutical distribution executives, cloud platform procurement officers, and IoT sensor network engineers. Secondary validation drew from SEC 10-K filings of publicly traded software vendors, EMA pharmacovigilance inspection reports, MIIT smart manufacturing directives, and customs data on IoT hardware trade flows. Bottom-up sizing of module-level subscription revenue triangulated against top-down enterprise IT expenditure surveys across German, US, and Chinese manufacturing clusters.
Calibration against historical deployment timelines for SAP, Kinaxis, and E2open implementations refined the analytical framework across the analysis window. Segmentation dimensions modeled include deployment topology, technology layer, end-user vertical, and application function, with additional granularity on regulatory jurisdiction clusters affecting data residency architecture. CAGRs were derived from S-curve adoption modeling calibrated to cloud SaaS penetration rates in manufacturing, with specific inputs from automotive production forecasts and pharmaceutical cold-chain expansion patterns.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting enterprise software capital allocation or geopolitical friction disrupting China-Germany automotive supplier relationships would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement intensity and cloud infrastructure cost curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Myanmar Freight and Logistics Market
Logistics and Shipping
China Project Logistics Market
Logistics and Shipping
Japan Dangerous Goods Logistics Market
Logistics and Shipping
Peru Freight and Logistics Market
Logistics and Shipping
Australia Cold Chain Logistics Market
Logistics and Shipping
Asia-Pacific Shipping Agency Services Market
Logistics and Shipping
North America Freight Forwarding Market
Logistics and Shipping
Japan Freight Forwarding Market
Logistics and Shipping
Global 5PL Solutions Market
Logistics and Shipping
China Freight and Logistics Market
Logistics and Shipping
India E-Commerce Logistics Market
Logistics and Shipping
Inbound Logistics Market
Logistics and Shipping
GCC Freight and Logistics Market
Logistics and Shipping
Estonia Freight and Logistics Market
Logistics and Shipping
United States Chemical Logistics Market
Logistics and Shipping
Cross-Border Logistics Services Market