
 Third-Party Logistics (3PL) Market | 2026-2036
Third-Party Logistics (3PL) Market Size, Share, and Industry Trends Forecast 2026-2036
Third-Party Logistics (3PL) Market Analysis
India is narrowing its infrastructure gap through dedicated freight corridors and port modernization, drawing capital into contract logistics. DHL Supply Chain leverages its pharmaceutical cold-chain certification to dominate temperature-controlled distribution. Kuehne + Nagel sustains its ocean freight forwarding leadership through digital booking platforms. C.H. Robinson anchors North American truckload brokerage through its proprietary shipper-carrier matching technology.
Third-party logistics encompasses outsourced supply chain management functions including transportation execution, inventory storage, order fulfillment, and reverse logistics, typically governed by service-level agreements specifying on-time delivery rates and inventory accuracy thresholds. Its primary purpose is to replace fixed warehouse and fleet assets with variable-cost operating structures. Transportation services command the largest revenue pool within the 3PL value chain, while value-added services such as kitting, labeling, and last-mile customization capture expanding margin pools as shippers seek differentiation. E-commerce end users are driving the fastest structural growth, with healthcare logistics emerging as a premium segment due to temperature-sensitive handling requirements and regulatory compliance burdens.
The EPA enforces emissions standards for heavy-duty trucking fleets operating across the United States, compelling 3PL providers to electrify or face operational restrictions. The EU Green Deal mandates progressive carbon intensity reductions for commercial transport, reshaping route planning and modal selection across European networks. OSHA warehouse safety regulations influence facility design and labor deployment patterns in domestic distribution centers. Stakeholders must monitor regulatory compliance costs alongside automation deployment timelines as these forces jointly determine competitive survival in contracted logistics services.
Market Dynamics
E-commerce fulfillment velocity requirements are compressing delivery windows from days to hours, forcing 3PL providers to reconfigure warehouse networks around micro-fulfillment nodes positioned within urban cores rather than exurban distribution parks.
Growth Catalysts
- EU Green Deal carbon mandates:Progressive emissions intensity reductions for commercial transport fleets are accelerating modal shift investments toward rail and electric last-mile vehicles across European logistics corridors.
- Healthcare cold-chain expansion:Temperature-sensitive biologics distribution is creating specialized infrastructure demand requiring GDP-compliant warehousing and real-time thermal monitoring systems.
- India's dedicated freight corridors:The Eastern and Western Dedicated Freight Corridors are reducing transit times between manufacturing belts and container ports, drawing contract logistics investment toward Delhi-Mumbai industrial zones.
Market Restraints
- Diesel price volatility:Fuel represents 25-35% of road freight operating costs, and geopolitical supply disruptions transmit directly to margin compression for asset-heavy 3PL operators.
- Warehouse labor concentration:Fulfillment center employment clusters in specific metropolitan areas create localized wage spirals and unionization pressure that constrain network flexibility.
- Cross-border customs friction:Post-Brexit regulatory divergence between the United Kingdom and European Union member states adds documentation burden and dwell time to just-in-time supply chains.
Strategic Opportunities
- Southeast Asian manufacturing migration:Vietnam and Indonesia are absorbing electronics and textile production capacity, creating greenfield demand for integrated logistics parks near Ho Chi Minh City and Jakarta.
- Battery supply chain logistics:Cell manufacturing and raw material processing require hazardous materials handling certification that few incumbent providers possess, creating white space for qualified entrants.
- ISO 14001 environmental certification:Corporate sustainability reporting mandates under CSRD are making verified green logistics credentials a procurement differentiator for EU-headquartered shippers.
Industry Challenges
- Warehouse automation technician scarcity:Deploying autonomous mobile robots and goods-to-person systems requires mechatronics expertise that outpaces vocational training pipeline output.
- Multi-client WMS integration complexity:Harmonizing disparate warehouse management systems during onboarding creates data mapping errors and inventory visibility gaps that degrade service-level performance.
- OSHA ergonomic compliance:Repetitive-motion injury prevention mandates in US distribution centers require workflow redesign and exoskeleton pilot programs that disrupt established picking productivity benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Third-Party Logistics (3PL) Market |
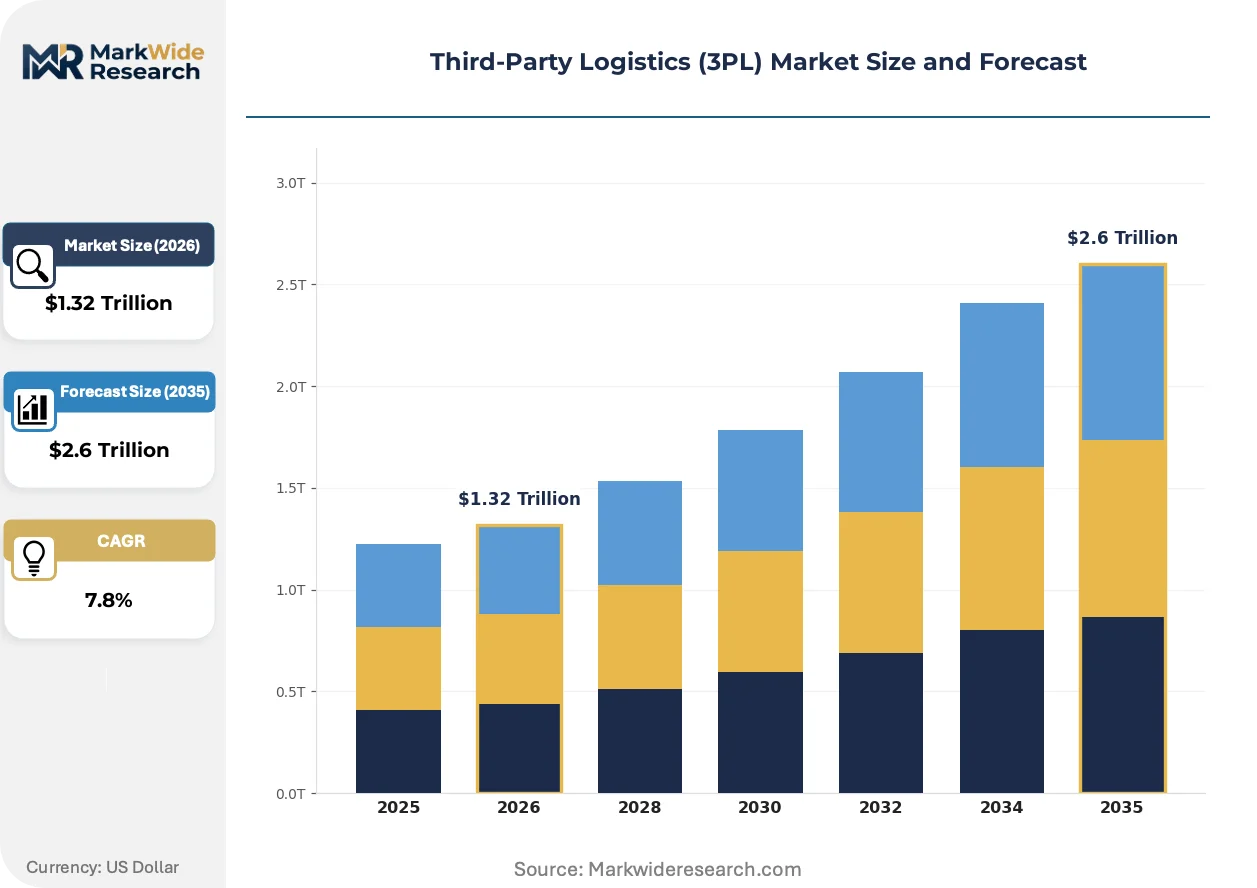
| Market Size in 2026 | $1.32 Trillion |
| Market Size in 2035 | $2.6 Trillion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Value-Added Services End User: E-commerce, Retail, Manufacturing, Healthcare Technology: Warehouse Management Systems, Transportation Management Systems, Inventory Systems, IoT Solutions Distribution Channel: Direct Sales, Online Platforms, Resellers, Partnerships |
| Companies Covered | Amazon, DHL Supply Chain, Kuehne + Nagel, DSV, CEVA Logistics, Nippon Express, C.H. Robinson, DB Schenker, UPS Supply Chain Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Third-Party Logistics (3PL) Market Emerging Trajectories
Digital twin technology is virtualizing physical supply chain operations, enabling 3PL providers to simulate network disruptions and optimize inventory positioning before capital deployment. This capability is compressing the traditional pilot-to-scale timeline for network reconfigurations.
Digital twin platforms are virtualizing warehouse layout and flow optimization by creating real-time virtual replicas of fulfillment operations. Pharmaceutical and automotive shippers with complex SKU portfolios are adopting these systems fastest. The technology is virtualizing capital allocation decisions, allowing providers to test automation scenarios without physical retrofit costs.
EPA heavy-duty vehicle emissions standards are compelling fleet operators to accelerate electric and hydrogen fuel cell truck pilots. The regulatory pressure is restructuring procurement criteria toward total-cost-of-ownership models that incorporate carbon pricing. California's Advanced Clean Trucks regulation is creating a compliance laboratory that other US states are observing for policy replication.
Shippers are unbundling transportation management from integrated 3PL contracts, opting instead for control-tower visibility platforms that aggregate multiple provider performance. This disintermediation is compressing contract durations and forcing providers to compete on data transparency rather than asset ownership. The pattern is most pronounced among North American retail and consumer electronics verticals with volatile demand forecasting requirements.
Third-Party Logistics (3PL) Market Segmentation
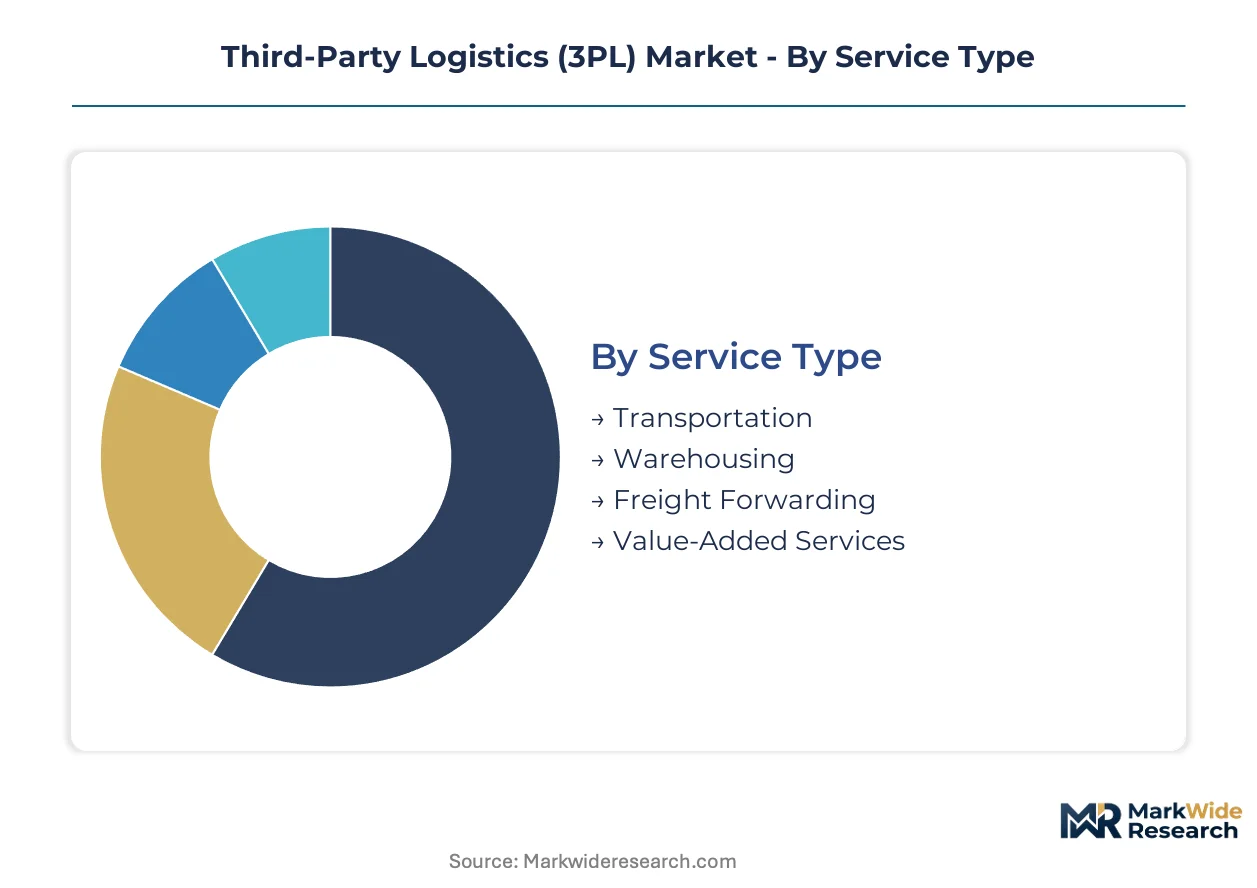
Segmentation in third-party logistics reveals how service velocity, regulatory intensity, and technology maturity create divergent margin profiles across customer verticals. Contract structures and asset requirements vary dramatically between high-frequency e-commerce fulfillment and project-driven industrial logistics.
Service Type:
Transportation services turn inventory fastest with same-day billing cycles, while warehousing contracts lock capital into multi-year facility leases with slower amortization.
- Transportation:Road, rail, air, and ocean freight execution commands the largest revenue pool through variable-cost pricing tied to fuel indices and lane density. E-commerce retailers in Germany's Rhine-Ruhr corridor are compressing delivery windows to two hours, forcing fleet operators to deploy electric last-mile vehicles to meet EU Green Deal urban access restrictions.
- Warehousing:Dedicated and multi-client facilities provide inventory storage, cross-docking, and fulfillment processing governed by SLA-defined accuracy thresholds. India's Dedicated Freight Corridors are drawing contract logistics investment toward Delhi-Mumbai industrial zones where modernized port connectivity reduces dwell times.
- Freight Forwarding:International shipment coordination through NVOCC and customs brokerage relationships.
- Value-Added Services:Kitting, labeling, and last-mile customization capture expanding margin pools as shippers seek differentiation.
Transportation anchors the volume base while value-added services gain share at the steepest rate.
End User:
Cost tiers separate capital-light digital retailers from asset-heavy industrial shippers with specialized handling requirements.
- E-commerce:Direct-to-consumer fulfillment demands micro-fulfillment nodes positioned within urban cores rather than exurban distribution parks. Micro-fulfillment concentration in Frankfurt and Hamburg is creating localized labor competition that drives automation investment.
- Healthcare:Temperature-sensitive biologics distribution requires GDP-compliant warehousing and real-time thermal monitoring systems. Pharmaceutical cold-chain certification creates specialized infrastructure demand with premium pricing power.
- Retail:Omnichannel inventory pooling across brick-and-mortar and digital channels.
- Manufacturing:Just-in-time component delivery and vendor-managed inventory programs.
E-commerce commands the largest addressable spend while healthcare climbs the fastest on regulatory compliance premiums.
Technology:
Application maturity separates legacy ERP-integrated systems from emerging IoT sensor networks with unproven ROI documentation.
- Warehouse Management Systems:Multi-client WMS platforms harmonize inventory visibility across disparate shipper systems during onboarding. Data mapping errors during integration create service-level degradation that constrains provider scalability.
- IoT Solutions:Real-time location tracking and environmental monitoring enable predictive exception management. California's Advanced Clean Trucks regulation is creating a compliance laboratory where telematics data proves electrification ROI for fleet operators.
- Transportation Management Systems:Load optimization and carrier procurement automation.
- Inventory Systems:Demand forecasting and safety stock optimization modules.
Warehouse Management Systems dominate installed base while IoT Solutions expand most quickly on sensor cost reduction.
Distribution Channel:
Customer type stratification separates enterprise direct relationships from aggregated SME demand through platform intermediaries.
- Direct Sales:Dedicated account teams negotiate multi-year contracts with customized SLA frameworks. North American retail and consumer electronics verticals with volatile demand forecasting requirements are unbundling transportation management from integrated contracts.
- Online Platforms:Digital booking interfaces aggregate spot market demand with instant pricing transparency. Digital freight platforms are compressing contract durations and forcing providers to compete on data transparency rather than asset ownership.
- Resellers:Regional logistics brokers with localized shipper relationships.
- Partnerships:Strategic alliances with complementary service providers for geographic or capability extension.
Direct Sales retains the highest contract value concentration while Online Platforms capture the steepest expansion trajectory on SME market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major economies: Germany and the United States prioritize pharmaceutical cold-chain density, while India and China concentrate investment in e-commerce fulfillment velocity and dedicated freight infrastructure.
Germany
Industrial manufacturing clusters and pharmaceutical exports drive contract logistics demand around Frankfurt and Hamburg. The EU Green Deal mandates progressive carbon intensity reductions for commercial transport fleets, accelerating electric last-mile vehicle deployment. The Rhine-Ruhr corridor hosts micro-fulfillment concentration that intensifies localized labor competition and automation investment.
United States
E-commerce retailers and healthcare distributors anchor demand for temperature-controlled warehousing and rapid fulfillment networks. The EPA enforces emissions standards for heavy-duty trucking fleets, compelling electrification pilots and hydrogen fuel cell trials. California's Advanced Clean Trucks regulation creates a compliance laboratory observed by other states for policy replication.
India
Manufacturing belt expansion and port modernization draw capital into contract logistics serving domestic consumption and export markets. The Dedicated Freight Corridor project reduces transit times between Delhi and Mumbai industrial zones. Gujarat and Maharashtra industrial corridors attract integrated logistics park development near Mundra and JNPT container terminals.
China
Electronics manufacturing migration and battery supply chain localization reshape logistics demand across coastal and inland provinces. Dual carbon goals and MIIT regulations accelerate fleet electrification and warehouse energy efficiency mandates. The Yangtze River Delta and Pearl River Delta maintain concentration in high-velocity fulfillment infrastructure.
Vietnam
Electronics and textile production absorption from regional competitors generates greenfield demand for integrated logistics parks. The country's national trade facilitation programs streamline customs procedures for export-oriented manufacturing. Ho Chi Minh City and surrounding industrial zones concentrate contract logistics investment serving ASEAN supply chain reconfiguration.
Third-Party Logistics (3PL) Market Vendor Landscape
Capability concentration sits with specialized cold-chain and pharmaceutical-certified providers; scale advantage sits with integrated global networks possessing proprietary digital platforms. The market structures around three tiers: asset-heavy integrated operators, technology-enabled freight brokers, and niche-certified specialists. Strategic moves center on M&A for geographic density and strategic partnerships for last-mile electrification.
Within the integrated-network tier, DHL Supply Chain and Kuehne + Nagel occupy positions defined by pharmaceutical certification and ocean freight digitalization respectively. C.H. Robinson represents the technology-enabled brokerage archetype, anchoring North American truckload matching through proprietary platforms. These three exemplify how regulatory compliance depth and platform scale create divergent competitive moats in contracted logistics services.
| Leading Market Players |
|---|
| Amazon |
| DHL Supply Chain |
| Kuehne + Nagel |
| DSV |
| CEVA Logistics |
| Nippon Express |
| C.H. Robinson |
| DB Schenker |
| UPS Supply Chain Solutions |
| Others |
Supply Flow & Price Mechanics
The Rhine-Ruhr corridor's warehouse capacity crunch feeds directly into pricing power for providers holding GDP-compliant pharmaceutical certification, while diesel volatility erodes margins for asset-heavy road freight operators lacking modal flexibility.
Pricing Analysis
Road freight rates diverge sharply between Germany's urban cores and India's emerging industrial belts, with EU Green Deal compliance premiums widening spreads. Contract logistics pricing stratifies across premium certified tiers, standard multi-client facilities, and economy spot brokerage, with certification grade and volume scale as primary differentiation levers. Cost compression in standard warehousing intensifies as automation capex amortization pressures compete with labor wage spirals. E-commerce retailers exhibit highest price sensitivity due to fulfillment velocity requirements, while pharmaceutical shippers accept premium pricing for temperature integrity guarantees.
Supply Chain Analysis
Tariff exposure between the United Kingdom and European Union member states dominates supply chain risk planning for just-in-time manufacturing networks. Warehouse automation equipment concentrates in Germany, China, and the United States, while cold-chain packaging materials draw from specialized converters in the Netherlands and Japan. Single-source vulnerability in lithium-ion battery cell supply chains is tethering to concentrated Asian manufacturing. Distribution runs through hub-and-spoke networks anchored by dedicated freight corridors and port-centric logistics parks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified technicians capable of deploying autonomous mobile robots and goods-to-person systems are scarcer than available capital, creating a bottleneck that favors incumbents with established training pipelines over well-funded entrants.
For Market Incumbents: Entrench pharmaceutical cold-chain certification as a defensive moat against technology-enabled freight brokers unbundling transportation management from integrated contracts. Deepen backward integration into last-mile electric vehicle fleets to offset EPA emissions compliance costs and capture EU Green Deal subsidies before policy replication spreads beyond California. For New Entrants and Emerging Players: Establish a beachhead in battery supply chain logistics serving hazardous materials handling requirements that incumbent providers lack. Vietnam and Indonesia absorb manufacturing migration fastest, creating greenfield demand near Ho Chi Minh City and Jakarta where ISO 14001 certification opens doors to EU-headquartered shippers. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because scale advantages in proprietary shipper-carrier matching technology compound faster than niche certification premiums. Target mid-cap specialists with dense regional networks and dormant pharmaceutical credentials. Watch OSHA ergonomic compliance mandates as the signal indicating automation capex acceleration and distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Certification Investment | GDP-compliant warehousing opens pharmaceutical biologics distribution with premium pricing power. |
| Electric Fleet Deployment | California's Advanced Clean Trucks regulation creates compliance laboratory for EPA-aligned electrification. |
| Digital Twin Platform Integration | Virtual supply chain replicas compress pilot-to-scale timelines for network reconfiguration decisions. |
| Micro-Fulfillment Node Expansion | Urban core positioning addresses EU Green Deal last-mile access restrictions in Frankfurt and Hamburg. |
| Multi-Client WMS Harmonization | Data mapping accuracy during onboarding determines scalability and service-level performance retention. |
Methodological Framework
Desk research of customs trade databases, EPA regulatory filings, and EU Green Deal implementation directives preceded structured interviews with 3PL operations directors, pharmaceutical supply chain managers, freight brokerage technology leads, and warehouse automation engineers. Primary fieldwork validated secondary findings through facility site assessments and carrier procurement pattern analysis. Bottom-up service revenue modeling triangulated against top-down macroeconomic consumption projections.
Baseline assumptions held fuel price indices and emissions regulatory trajectories fixed across the projection horizon, while e-commerce penetration rates and healthcare cold-chain volumes were stress-tested across optimistic and constrained scenarios. Segmentation modeling incorporated service type, end-user vertical, technology deployment tier, and geographic regulatory cluster dimensions. CAGRs derived from historical revenue trajectories adjusted for corridor-specific infrastructure investment timelines and modal shift elasticity parameters.
Stress conditions across diesel price volatility bands, warehouse labor availability thresholds, and cross-border customs friction scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about Dedicated Freight Corridor completion schedules and EPA electrification incentive continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Vietnam Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Freight Management System Market
Logistics and Shipping
Russia Courier Service Market
Logistics and Shipping
Italy Courier Market
Logistics and Shipping
Europe Container Terminal Operations Market
Logistics and Shipping
Thailand Courier Express Parcel (CEP) Market
Logistics and Shipping
Europe Contract Logistics Market
Logistics and Shipping
Freight Transport Management Market
Logistics and Shipping
China Same Day Delivery Market
Logistics and Shipping
Latin America Stevedoring and Marine Cargo Handling Market
Logistics and Shipping
Remanufacturing and Core Returns Logistics Management Market
Logistics and Shipping
North America Last Mile Delivery Market
Logistics and Shipping
Event Logistics Market
Logistics and Shipping
Georgia Freight and Logistics Market
Logistics and Shipping
Uruguay Freight and Logistics Market
Logistics and Shipping
US Cross-Border Road Freight Transport Market