
 United Kingdom Soy Protein Market | 2026-2036
United Kingdom Soy Protein Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Soy Protein Market Analytics
Buyer concentration among United Kingdom food manufacturers is restructuring as supermarket private-label programs consolidate procurement while specialist vegan startups fragment demand across niche suppliers. Cargill, Incorporated leverages its integrated supply chain to secure bulk supply contracts with major retail chains. Kerry Group PLC anchors its position through formulation expertise serving branded food processors. VBites Foods Ltd specializes in finished product innovation rather than commodity ingredient supply, occupying a distinct tier in the value chain.
United Kingdom soy protein encompasses protein isolates, concentrates, textured proteins, and flours derived from dehulled, defatted soybean meal through aqueous extraction and isoelectric precipitation, typically achieving protein contents of 50-90% depending on processing intensity, with primary application as functional ingredients in formulated foods requiring emulsification, water binding, or structural integrity. Isolates command premium positioning in sports nutrition and clinical nutrition applications where protein purity thresholds exceed 90%. Textured protein competes aggressively in meat alternative formulations where fiber alignment and bite simulation determine consumer acceptance. Concentrates sustain volume leadership across bakery and extended meat applications where cost-performance ratios favor moderate protein enrichment.
The Food Standards Agency enforces allergen labeling mandates and novel food authorization requirements that directly shape soy protein market access and product positioning in Great Britain. BSI standards for plant-based food claims create additional compliance layers affecting how manufacturers communicate protein content and nutritional equivalence. Trading relationships with the EU post-Brexit introduce dual regulatory alignment pressures through retained REACH provisions and diverging GB-specific chemical safety assessments. Stakeholders must monitor evolving precision fermentation regulations that could reshape competitive boundaries between traditional extraction and alternative protein production methods.
Market Dynamics
Supermarket private-label consolidation is compressing procurement timelines across Britain's soy protein value chain, forcing ingredient suppliers to reconfigure service models around shorter development cycles and volume guarantees.
Growth Catalysts
- Food Standards Agency novel food pathways:Streamlined authorization processes for textured protein applications accelerate product launch velocity for meat alternative developers.
- East Midlands food processing corridor concentration:Proximity of manufacturing assets reduces logistics friction for ingredient suppliers serving bakery and extended meat sectors.
- Precision fermentation regulatory clarity:Emerging guidance from British regulators creates definitional boundaries that protect traditional extraction-based soy protein market segments.
Market Restraints
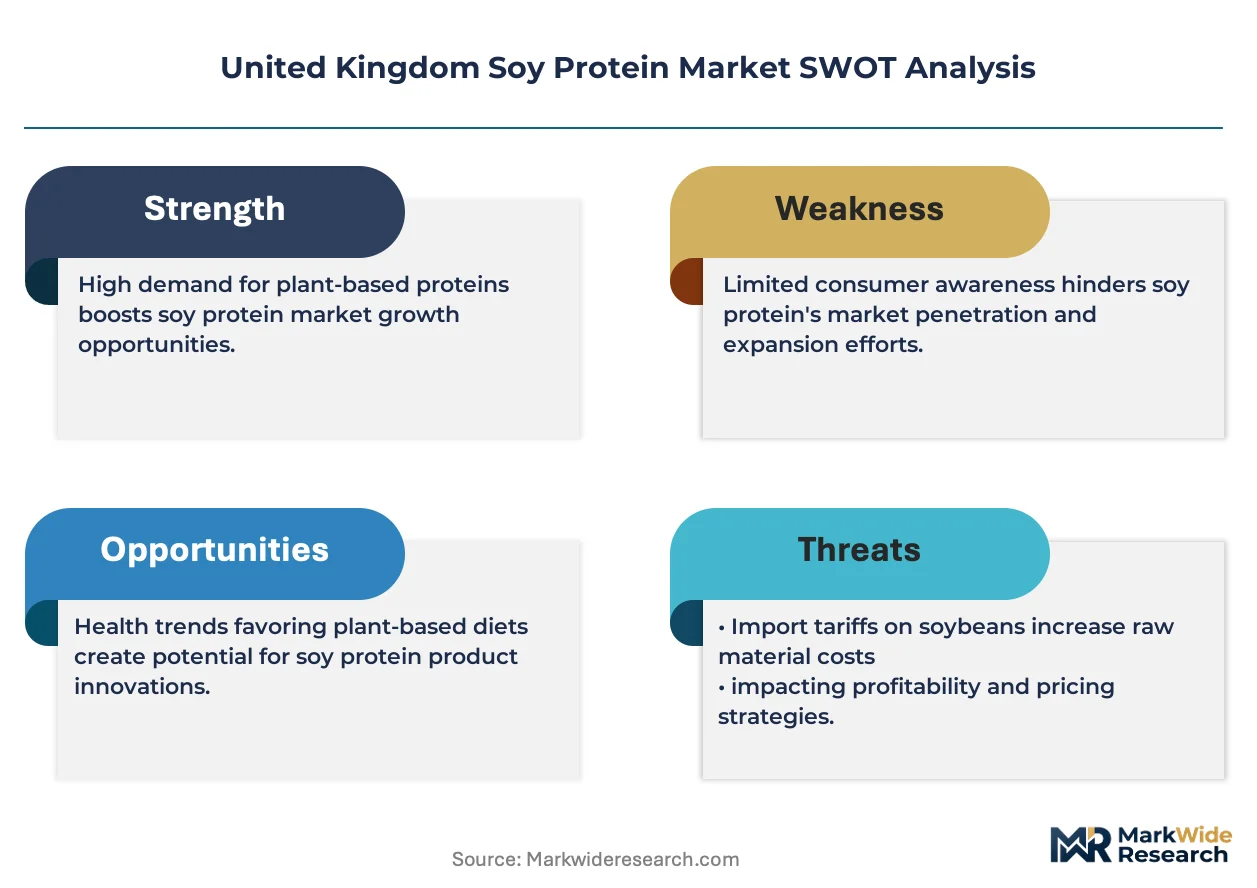
- Input cost volatility in defatted soybean meal:Global oilseed processing margins transmit price instability directly to UK protein isolate economics.
- EU-GB dual regulatory alignment:Retained REACH provisions alongside diverging GB chemical safety assessments multiply compliance expenditure for cross-border suppliers.
- Pea protein substitution threat:Allergen-free positioning and comparable functional performance erode soy concentrate share in clean-label formulations.
Strategic Opportunities
- Greater Manchester formulation services gap:Technical support infrastructure lags behind ingredient demand, creating whitespace for integrated solution providers.
- Clinical nutrition application expansion:Protein purity requirements above 90% isolate specification open premium positioning beyond sports nutrition saturation.
- BSI plant-based claims standardization:Certification-driven procurement preferences favor suppliers with pre-validated nutritional equivalence documentation.
Industry Challenges
- Food technologist skill scarcity:Fiber alignment and bite simulation expertise for textured protein applications commands premium compensation and extended recruitment cycles.
- Legacy ERP integration friction:Specialist vegan startups lack compatible systems for automated procurement with established ingredient distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Soy Protein Market |
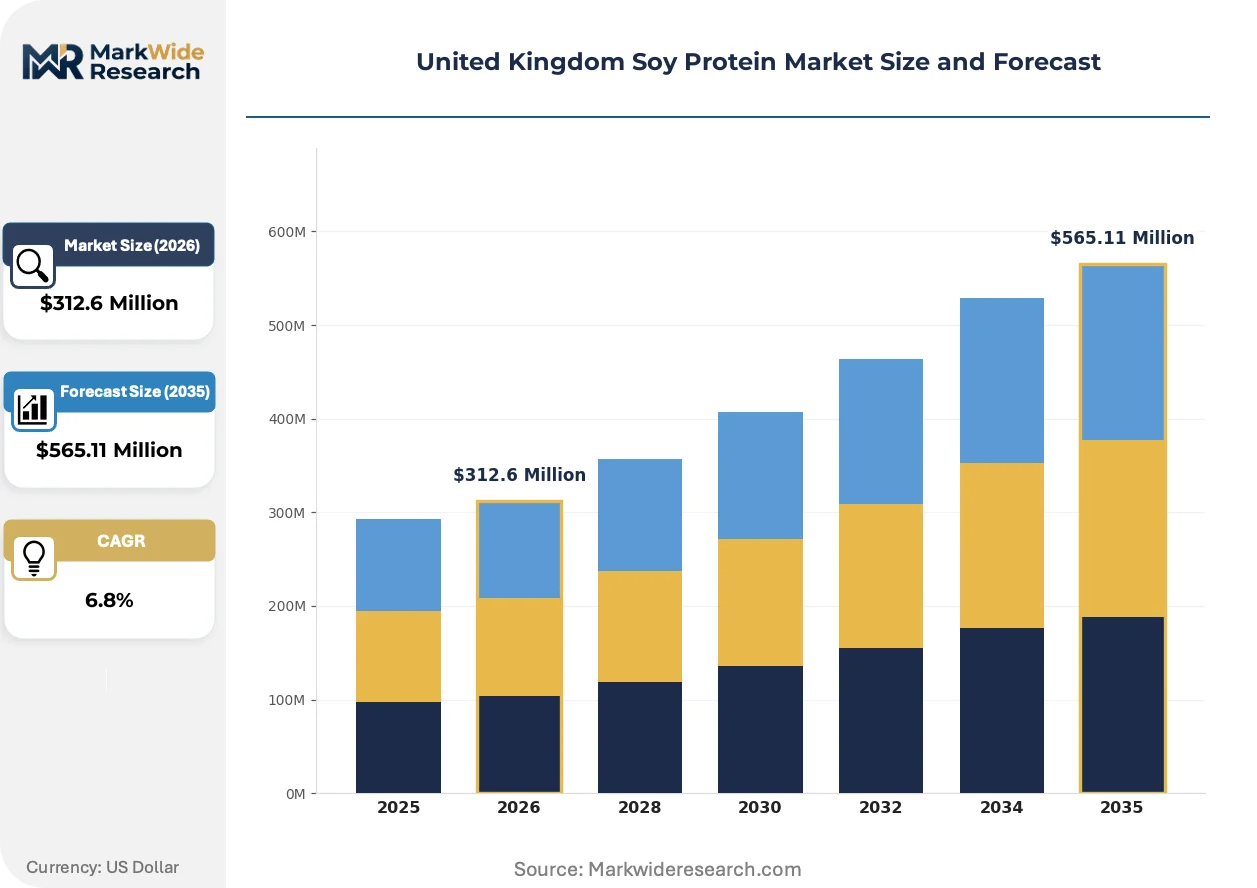
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $565.11 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolates, Concentrates, Textured Protein, Flour Application: Meat Alternatives, Dairy Alternatives, Protein Supplements, Bakery Products Form: Powder, Granules, Liquid, Bars End User: Food Industry, Nutraceuticals, Dietary Supplements, Animal Feed |
| Companies Covered | Archer Daniels Midland Company, Brenntag SE, International Flavors & Fragrances, Inc., Kerry Group PLC, Wilmar International Ltd, Cargill, Incorporated, Soya UK Ltd, VBites Foods Ltd, Quorn Foods, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Soy Protein Market Evolving Landscape
Processing technology convergence and procurement model compression are restructuring how soy protein flows from extraction facilities to finished food manufacturers across Britain.
Extrusion technology is unifying previously separate hydration and texturization stages into continuous production lines. Meat alternative manufacturers in the East Midlands are adopting these integrated systems at accelerating replacement cycles. Equipment consolidation is compressing capital deployment timelines and reducing batch-to-batch variability that previously required manual intervention.
Retained EU REACH provisions alongside emerging GB-specific chemical safety assessments are creating dual-track substance evaluation obligations. Ingredient importers now maintain parallel registration dossiers for cross-border material flows. Soy protein concentrate suppliers serving both GB and Northern Ireland markets face the most complex compliance architecture.
Buyer consolidation among supermarket private-label programs is displacing fragmented procurement through specialist distributors. Branded food processors in England's food manufacturing corridor are consolidating supplier panels and demanding direct technical service relationships. Channel compression is most visible in bakery applications where volume concentration enables specification customization.
United Kingdom Soy Protein Market Segmentation
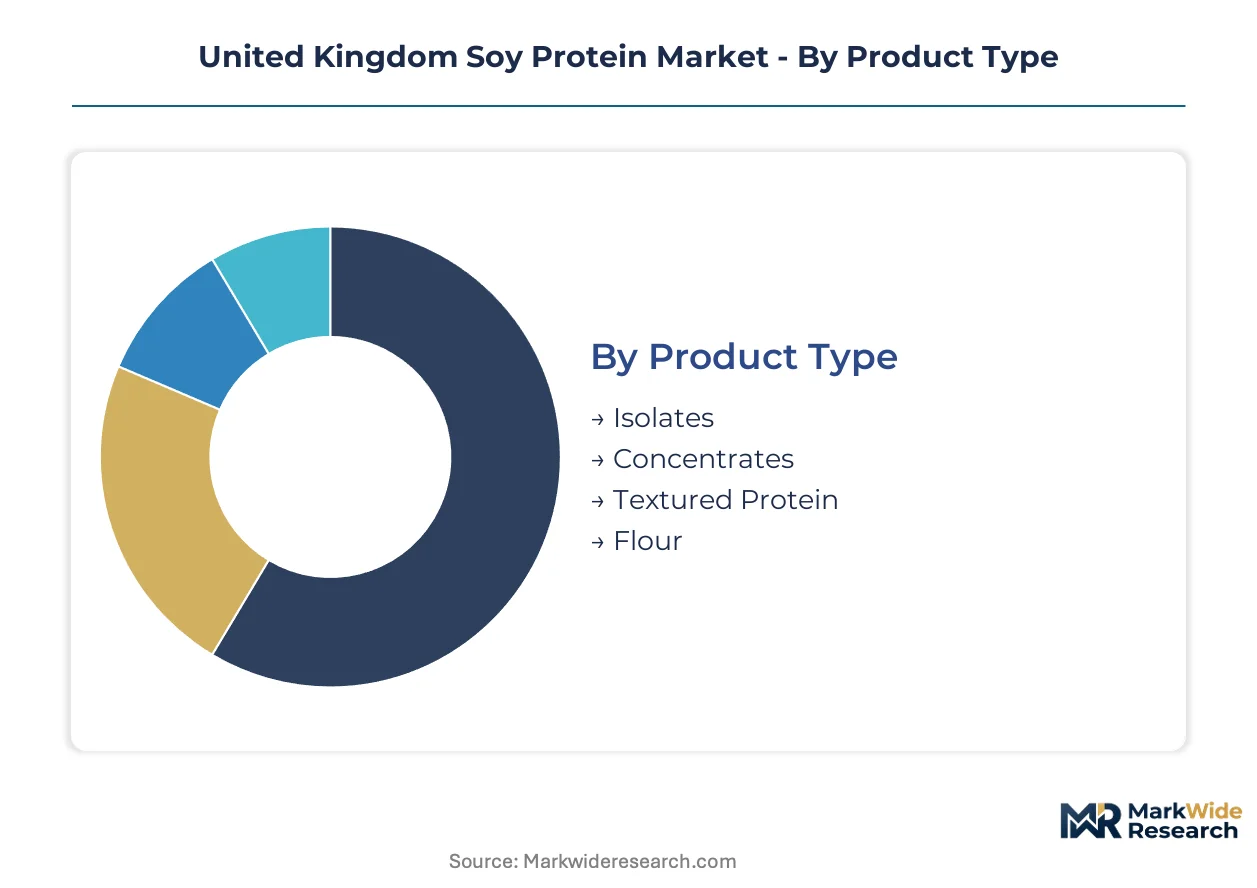
Soy protein procurement patterns across Britain diverge sharply by processing intensity and end-use specification. Food manufacturers prioritize functional performance thresholds over commodity pricing, while nutraceutical buyers enforce protein purity minimums that isolate suppliers alone can satisfy.
Product Type:
Cost tier separates commodity buyers from premium-positioned formulators seeking specific functional signatures.
- Isolates:Protein purity exceeds 90% through isoelectric precipitation and membrane filtration. Sports nutrition brands in England's manufacturing corridor specify isolates for amino acid completeness. Clinical nutrition applications in Greater Manchester demand batch-certified immunogenicity profiles.
- Concentrates:50-70% protein content retains soluble carbohydrates for water-binding functionality. Bakery processors across the East Midlands leverage concentrates for dough conditioning without premium isolate economics. Extended meat applications favor this tier for cost-controlled protein enrichment.
- Textured Protein:Extruded fiber structures simulate meat bite through controlled hydration. Meat alternative startups specify textured protein for structural integrity in private-label retail programs.
- Flour:Full-fat or defatted base material carries 40-50% protein with minimal processing. Animal feed compounders and traditional baked goods manufacturers source flour for bulk protein supplementation.
Volume sits with Concentrates; growth tilts toward Isolates.
Application:
Customer type determines specification rigor — retail-facing brands face stricter nutritional equivalence claims than ingredient suppliers.
- Meat Alternatives:Textured protein alignment and bite simulation requirements command food technologist expertise. East Midlands manufacturers specify fiber orientation parameters for supermarket private-label acceptance.
- Dairy Alternatives:Emulsion stability and mouthfeel matching drive isolate procurement for beverage applications. Clean-label formulators balance protein content against allergen disclosure obligations.
- Protein Supplements:Purity thresholds and amino acid scoring distinguish sports nutrition from clinical segments. Powder format dominates ready-to-mix applications.
- Bakery Products:Dough rheology and shelf-life extension guide concentrate selection. Industrial bakers prioritize water-binding over protein percentage in cost-sensitive formulations.
Procurement concentrates in Meat Alternatives; margin expansion favors Protein Supplements.
Form:
Supply chain configuration dictates format selection — powder handling infrastructure favors established processors while liquid investments suit integrated beverage operations.
- Powder:Dominant format for isolate and concentrate distribution. Bulk pneumatic handling systems at Greater Manchester formulation centers reduce labor intensity.
- Granules:Agglomerated particles improve dispersibility in high-speed mixing environments. Meat alternative extrusion lines specify granule size for hydration uniformity.
- Liquid:Pre-hydrated concentrates serve ready-to-drink dairy alternatives. Cold-chain distribution requirements limit supplier pool to integrated beverage manufacturers.
- Bars:Pre-formulated protein inclusions bind with carbohydrate matrices. Sports nutrition contract manufacturers source bar formats for co-extrusion efficiency.
Powder commands volume leadership; liquid formats climb fastest on beverage sector investment.
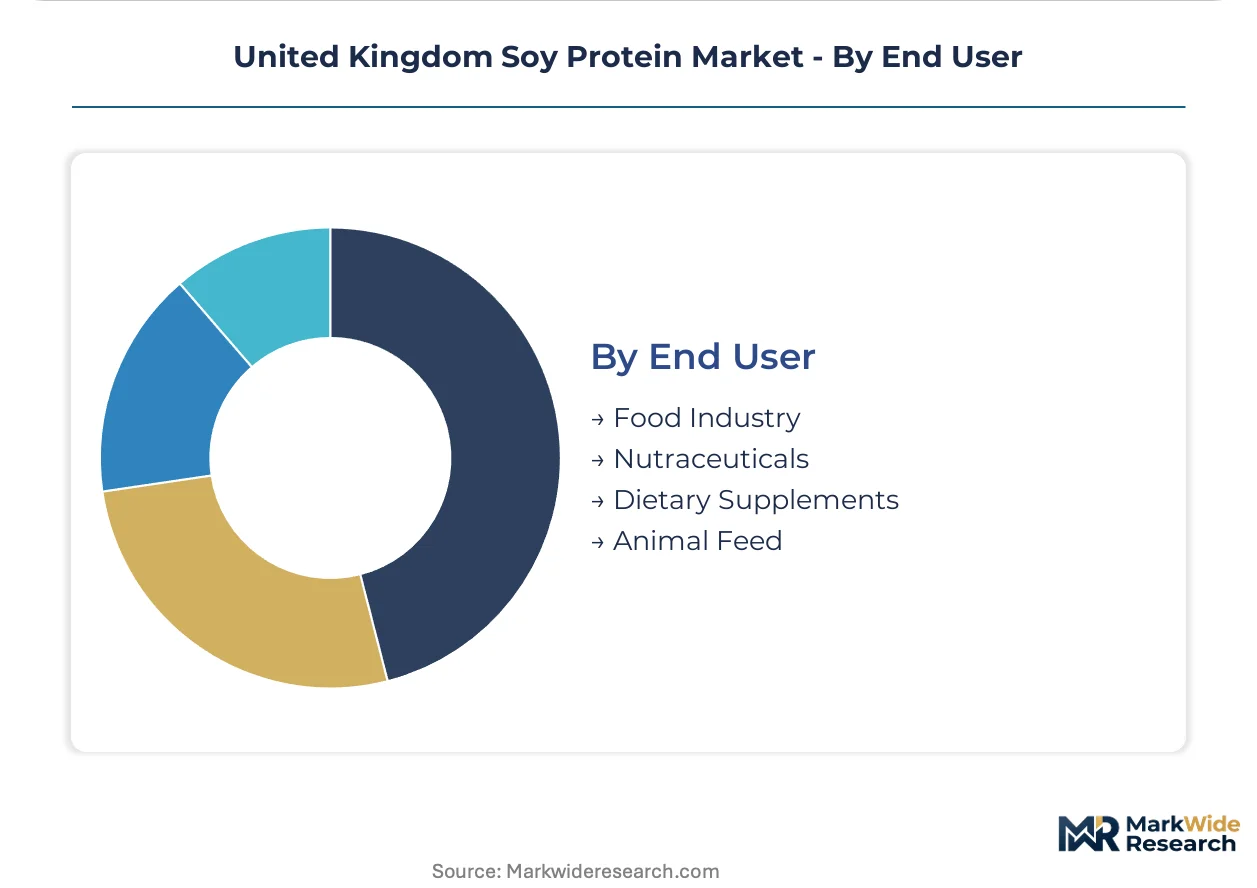
End User:
Margin structure varies dramatically — food industry procurement squeezes ingredient suppliers while nutraceutical buyers accept premium positioning for certification documentation.
- Food Industry:Branded processors and supermarket private-label programs consolidate supplier panels. Technical service relationships determine contract renewal beyond commodity pricing.
- Nutraceuticals:Clinical nutrition and medical food specifications require isolate-grade purity with traceability documentation. MHRA borderline classification creates regulatory navigation complexity.
- Dietary Supplements:Sports nutrition saturation pressures margin compression. Direct-to-consumer brands fragment demand across niche suppliers with speed-to-market advantages.
- Animal Feed:Defatted soy flour serves compound feed operations with minimal functional specification. Price sensitivity limits supplier differentiation to logistics reliability.
Food Industry anchors volume scale; Nutraceuticals deliver steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defatted soybean meal shipments from crushing facilities in Liverpool and Hull anchor ingredient flows into Britain's food manufacturing corridor. These port-adjacent processing nodes reduce inland logistics costs for protein isolate and concentrate production.
Greater Manchester
Food technologist talent pools and formulation service providers concentrate in this northern hub. The Food Standards Agency's novel food guidance shapes product approval timelines for meat alternative developers. Trafford Park industrial estates host extrusion equipment clusters serving private-label retail programs.
East Midlands
Bakery processors and extended meat manufacturers dominate concentrate procurement in this central corridor. BSI plant-based food claims standards create compliance documentation requirements for nutritional equivalence assertions. Nottingham and Derby manufacturing zones sustain volume-scale ingredient handling infrastructure.
West Midlands
Dairy alternative beverage production drives isolate demand for emulsion stability applications. Retained EU REACH provisions alongside diverging GB chemical safety assessments multiply substance evaluation obligations for cross-border suppliers. Birmingham logistics hubs coordinate liquid concentrate distribution to ready-to-drink operations.
Scotland
Clinical nutrition and medical food specifications command isolate-grade purity with traceability documentation. MHRA borderline classification creates regulatory navigation complexity for protein suppliers. Glasgow and Edinburgh research corridors attract sports nutrition brand development activity.
Southeast England
Supermarket headquarters and private-label program decision-makers concentrate procurement authority in this region. Precision fermentation regulatory clarity from British regulators creates definitional boundaries affecting competitive positioning. London-adjacent distribution centers manage just-in-time inventory for fragmented vegan startup demand.
United Kingdom Soy Protein Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue precision fermentation and alternative protein technologies. The vendor base stratifies around integrated supply chain control versus specialized formulation expertise. Three archetypes dominate: global trading houses with crushing assets, European ingredient distributors with technical service capabilities, and domestic finished-product innovators with captive formulation knowledge. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure volume guarantees with consolidating retail procurement programs.
Within the integrated supply chain tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify global trading houses with upstream crushing and oilseed processing assets. Kerry Group PLC represents the European technical service archetype, anchoring formulation expertise relationships with branded food processors. VBites Foods Ltd occupies a distinct position as a domestic finished-product innovator rather than commodity ingredient supplier, illustrating how value chain segmentation creates non-overlapping competitive spaces.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Brenntag SE |
| International Flavors & Fragrances, Inc. |
| Kerry Group PLC |
| Wilmar International Ltd |
| Cargill, Incorporated |
| Soya UK Ltd |
| VBites Foods Ltd |
| Quorn Foods |
| Others |
Value Network & Pricing Analysis
Food technologist scarcity across Greater Manchester and the East Midlands widens labor-cost differentials that translate directly into pricing-tier spreads, with fiber-alignment expertise commanding premium compensation that isolates concentrate buyers from isolate-grade formulators.
Pricing Analysis
Volume concentrates in bakery-grade concentrates while margins concentrate in clinical-nutrition isolates. Three-tier pricing structure across premium, standard, and economy levels separates immunogenicity-certified isolates from commodity concentrates and feed-grade flour. Pricing pressure stems from pea protein substitution in clean-label formulations, compressing soy concentrate economics. Supermarket private-label programs exhibit highest price sensitivity; nutraceutical buyers accept premium positioning for MHRA-traceable documentation.
Supply Chain Analysis
Post-Brexit domestic-content alignment pressures reshape sourcing toward retained EU crushing partnerships while GB-specific chemical safety assessments proliferate. Defatted soybean meal flows from Argentina, Brazil, and US Gulf crushing facilities. Supply chain risk centers on single-source vulnerability at Liverpool and Hull port-adjacent processing nodes. Distribution runs through direct technical-service relationships with consolidating retail procurement programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom soy protein market sits in a technology-transition phase where precision fermentation regulatory clarity is displacing traditional extraction-based competitive boundaries.
For Market Incumbents: Deploy formulation-service bundling to defend against precision fermentation entrants. Anchor technical relationships with East Midlands meat-alternative developers through fiber-alignment expertise. Invest in BSI plant-based claims pre-certification to lock supermarket private-label specifications before alternative proteins achieve regulatory equivalence. For New Entrants and Emerging Players: Enter via Greater Manchester formulation-services whitespace where technical infrastructure lags ingredient demand. Target clinical-nutrition applications requiring isolate-grade purity with traceability documentation. Pursue speed-to-market advantages through direct-to-consumer sports nutrition brands. For Investors and Strategic Acquirers: Re-rating potential sits with integrated technical-service providers given Food Standards Agency novel-food pathway acceleration. Five-to-ten-year viability favors European ingredient distributors with GB-specific regulatory navigation capabilities. Monitor precision fermentation regulatory boundary definitions as inflection indicator for traditional extraction asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crushing Assets | Cargill and ADM secure defatted soybean meal supply through Liverpool and Hull port facilities. |
| Formulation Service Expansion | Kerry Group PLC deepens technical relationships with East Midlands meat-alternative developers. |
| BSI Certification Pre-Investment | Suppliers lock supermarket private-label procurement through pre-validated nutritional equivalence documentation. |
| Clinical Nutrition Application Development | Isolate-grade producers capture premium positioning beyond saturated sports nutrition segments. |
| Precision Fermentation Regulatory Monitoring | Stakeholders track British regulator guidance for definitional boundaries protecting traditional extraction markets. |
Research Methodology
Food Standards Agency novel-food authorization records, BSI plant-based claims documentation, and HMRC trade statistics formed the secondary backbone. Primary interviews with food technologists at East Midlands extrusion facilities, procurement leads at supermarket private-label programs, regulatory affairs specialists navigating retained REACH provisions, and formulation directors at Greater Manchester innovation centers combined with bottom-up and top-down triangulation.
Historical trendline analysis tracked protein isolate, concentrate, textured protein, and flour volume flows across product type, application, form, and end-user segmentation dimensions. CAGRs derived from curve-fitting against input cost volatility patterns and procurement consolidation trajectories. Forecast inputs incorporated Food Standards Agency authorization velocity and precision fermentation regulatory timeline assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under dual EU-GB regulatory divergence scenarios and defatted soybean meal price spikes. Forecasts reflect documented assumptions about supermarket private-label consolidation rates and novel-food pathway streamlining. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
South America Meat Substitute Market
Plant Based Food
Yellow Pea Protein Market
Plant Based Food
Plant Based Collagen Market
Plant Based Food
Vegan Pasta Market
Plant Based Food
Plant Based Cheese Market
Plant Based Food
Vegan Protein Foods Market
Plant Based Food
United States Plant Protein Market
Plant Based Food
Vegan Flavor Market
Plant Based Food
Plant-Based Flour Market
Plant Based Food
France Plant Protein Market
Plant Based Food
Oat Protein Market
Plant Based Food
Plant-Based Diet Market
Plant Based Food
Vegan Flour Market
Plant Based Food
Plant-Based Chicken Market
Plant Based Food
Plant Based Eggs Market
Plant Based Food
Plant-Based Margarine Market