
 South America Meat Substitute Market | 2026-2036
South America Meat Substitute Market Size, Share, and Industry Trends Forecast 2026-2036
South America Meat Substitute Market Analytics
The price-performance gap between premium mycoprotein lines and commodity soy isolates is hardening across South America. Beyond Meat Inc. sustains its position through frozen patty distribution into Brazilian retail chains. NotCo anchors regional innovation with AI-driven flavor replication for pea-protein formulations. Cargill Incorporated leverages its existing soy processing footprint in Argentina to supply wheat-protein concentrates to mid-tier brands.
Meat substitutes encompass protein-rich food products engineered to replicate the sensory and nutritional properties of conventional meat, typically achieving 15-25 grams of protein per 100-gram serving through extrusion or fermentation processes. Their primary commercial purpose is to serve as direct replacements in household cooking and food service preparation across temperature-stable and chilled formats. Soy protein dominates volume production due to established crushing infrastructure in Brazil and Argentina, while pea protein captures premium positioning in chilled ready-to-eat applications where allergen labeling requirements favor non-GMO declarations. Frozen form leads household penetration through extended shelf life, though chilled formats command higher per-unit margins in Brazilian and Colombian supermarket channels.
ANMAT in Argentina enforces pre-market safety assessments for novel proteins, while ANVISA in Brazil mandates allergen disclosure and nutritional equivalence claims on plant-based meat labeling. These frameworks elevate compliance costs for imported brands while creating protected terrain for regional manufacturers with established regulatory relationships. Stakeholders must weigh localization investments against the accelerating pace of Mercosur harmonization talks on novel food standards.
Market Dynamics
Regulatory divergence between Brazil's ANVISA and Argentina's ANMAT is fragmenting product approval pathways while soy protein supply concentrates in the Paraná-Paraguay river basin, forcing brands to choose between harmonization lobbying or dual-track compliance investments.
Growth Catalysts
- ANVISA Nutritional Equivalence Mandates:Brazil's labeling requirements for allergen disclosure and protein content verification are accelerating domestic manufacturing capacity investments as imported brands face extended clearance timelines.
- Quick-Service Restaurant Expansion:Brazilian fast-food chains now maintain dedicated plant-based menu sections, creating pull-through demand for frozen patty and sausage formats in São Paulo's urban food service corridor.
- Extrusion Technology Maturation:High-moisture extrusion systems capable of replicating muscle fiber texture are reducing formulation costs for mid-tier brands serving Colombian and Chilean retail channels.
Market Restraints
- Input Cost Volatility:Pea protein isolate prices fluctuate with Canadian and Ukrainian yellow pea harvests, compressing margins for premium chilled-format producers in Brazilian supermarket channels.
- Supply Concentration Risk:Wheat gluten concentrate production clusters in Buenos Aires province, exposing mid-tier brands to Argentine peso devaluation and export tariff unpredictability.
- Technical Limitation:Mycoprotein fermentation requires sterile bioreactor infrastructure unavailable at scale outside southern Brazil, limiting geographic expansion of premium product lines.
Strategic Opportunities
- Colombian Retail Underpenetration:Bogotá and Medellín supermarket chains lack dedicated plant-based protein sections, creating first-mover positioning for brands establishing direct distribution relationships.
- Mercosur Harmonization Tailwind:Pending alignment of novel food standards across member states would eliminate redundant safety assessments for products crossing Brazil-Argentina-Paraguay borders.
- Food Service Technology Convergence:Combination of AI-driven flavor mapping and precision fermentation is enabling custom protein development for regional cuisine applications in Peruvian and Ecuadorian restaurant chains.
Industry Challenges
- Specialized Talent Scarcity:Food technologists with extrusion process optimization expertise command premium salaries in São Paulo, constraining R&D expansion for second-tier manufacturers.
- ANMAT Certification Timelines:Argentina's pre-market safety assessment protocols for novel proteins extend product launch windows by 14-18 months versus Brazilian ANVISA pathways.
- Legacy Cold Chain Integration:Chilled-format distribution requires temperature-controlled logistics partnerships that remain underdeveloped in Paraguayan and Bolivian retail corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Meat Substitute Market |
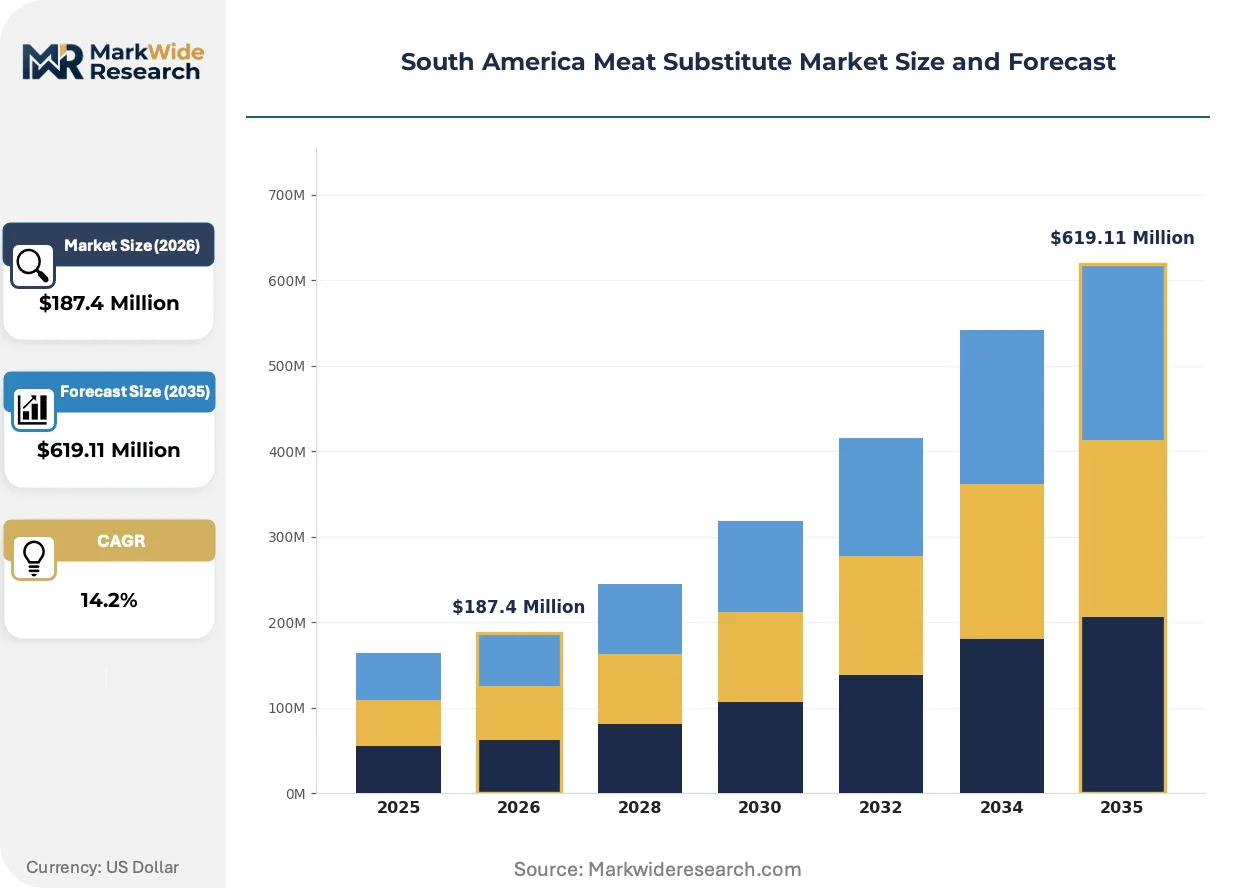
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tofu, Tempeh, Seitan, Jackfruit Form: Frozen, Chilled, Dried, Ready-to-Eat Source: Pea Protein, Soy Protein, Wheat Protein, Mycoprotein End User: Households, Restaurants, Cafés, Food Service Providers |
| Companies Covered | Beyond Meat Inc., Impossible Foods Inc., Tyson Foods Inc., Kellogg's Company, Turtle Island Foods (Tofurky), NotCo, NaturAlba, Green Eats, Cargill Incorporated, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Meat Substitute Market Evolving Landscape
Artificial intelligence is restructuring how South American producers replicate sensory profiles of traditional meats, while regulatory frameworks harden around protein content claims and novel ingredient safety assessments.
Precision fermentation infrastructure is integrating into Brazilian biotechnology parks to produce heme and dairy proteins that enhance umami depth in plant-based formulations. São Paulo-based research institutes are licensing this capacity to mid-sized food manufacturers seeking differentiation from commodity soy isolates. The technology is integrating flavor replication capabilities previously restricted to multinational R&D budgets into regional supply chains.
ANMAT's 2023 tightening of novel food ingredient registration protocols in Argentina is extending pre-market review periods for mycoprotein and fermented protein entrants. This regulatory friction is diverting investment toward Brazilian manufacturing bases with established ANVISA relationships. Chilled ready-to-eat applications face the steepest compliance burden under the revised safety assessment requirements.
Urban Brazilian consumers are rotating protein purchases toward frozen multi-serve formats as inflation compresses household food budgets. Supermarket chains in Rio de Janeiro and São Paulo are responding by expanding private-label plant-based ranges at price points below branded alternatives. This behavioral shift is most visible in working-class neighborhoods where traditional meat price spikes have accelerated trial conversion.
South America Meat Substitute Market Segmentation
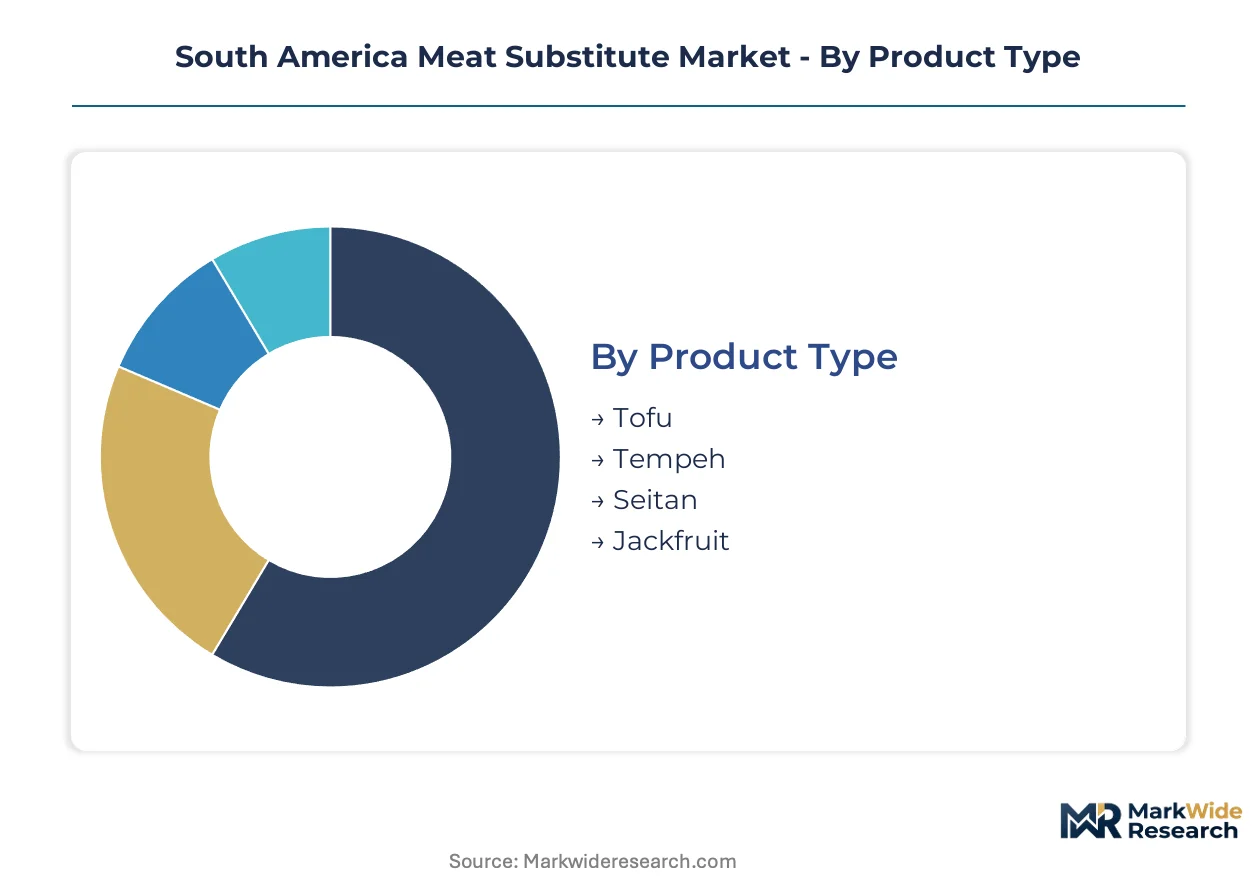
Product architecture in South America reflects divergent consumer priorities across temperature stability, protein source familiarity, and preparation convenience. Manufacturers calibrate positioning across these dimensions to capture distinct usage occasions from São Paulo household kitchens to Colombian quick-service operations.
Product Type:
Upgrade cycles vary sharply by culinary tradition, with heritage formats retaining volume while engineered alternatives capture premium positioning.
- Tofu:Coagulated soy protein blocks with neutral flavor profiles serve as foundational ingredients in Brazilian and Peruvian home cooking. Demand clusters in São Paulo's Asian-descendant communities and health-conscious urban households seeking versatile meat alternatives for stir-fry applications.
- Tempeh:Fermented whole soybean cakes deliver firmer texture and higher fiber content than tofu, commanding premium placement in Brazilian natural product channels. Argentine consumers in Buenos Aires province increasingly substitute tempeh for traditional beef in milanesa preparations as price spreads narrow.
- Seitan:Wheat gluten concentrate with chewy, fibrous texture replicates poultry mouthfeel in Brazilian churrasco-style preparations.
- Jackfruit:Unripe fruit flesh mimics pulled pork texture in Colombian and Venezuelan street food applications.
Volume placements concentrate in tofu; the faster expansion belongs to tempeh.
Form:
Cost tier stratification separates mass-market frozen formats from chilled premium lines serving distinct retail channels.
- Frozen:Blast-frozen patties, nuggets, and grounds achieve 12-18 month shelf stability through cryogenic tunnel systems. Brazilian supermarket chains in Rio de Janeiro and São Paulo dedicate increasing freezer space to multi-serve bags targeting inflation-pressured households.
- Chilled:Refrigerated fresh formats with 14-21 day shelf life command per-unit premiums in Colombian and Chilean upscale retail. Bogotá supermarket operators report strongest velocity in marinated strips and sausage links positioned adjacent to conventional meat cases.
- Dried:Dehydrated textured vegetable protein requires rehydration before use, concentrating in Brazilian food service procurement.
- Ready-to-Eat:Pre-cooked shelf-stable formats target camping and institutional channels across Andean markets.
Household penetration runs deepest through frozen; chilled formats gain share fastest in urban supermarket channels.
Source:
Supply concentration around crushing infrastructure and import dependencies shapes competitive access to each protein base.
- Soy Protein:Isolated and concentrated proteins from defatted soy meal dominate volume production through established Brazilian and Argentine crushing capacity. Paraná-Paraguay river basin processors supply commodity isolates to mid-tier brands serving price-sensitive retail segments.
- Pea Protein:Yellow pea isolates deliver non-GMO positioning and allergen-friendly labeling for premium chilled applications. Brazilian manufacturers face margin compression when Canadian and Ukrainian harvest volatility elevates import costs.
- Wheat Protein:Vital wheat gluten concentrates production in Buenos Aires province, exposing brands to Argentine currency fluctuation.
- Mycoprotein:Fermented fungal biomass requires sterile bioreactor infrastructure concentrated in southern Brazil biotechnology parks.
Commodity scale concentrates in soy protein; mycoprotein climbs the fastest despite infrastructure constraints.
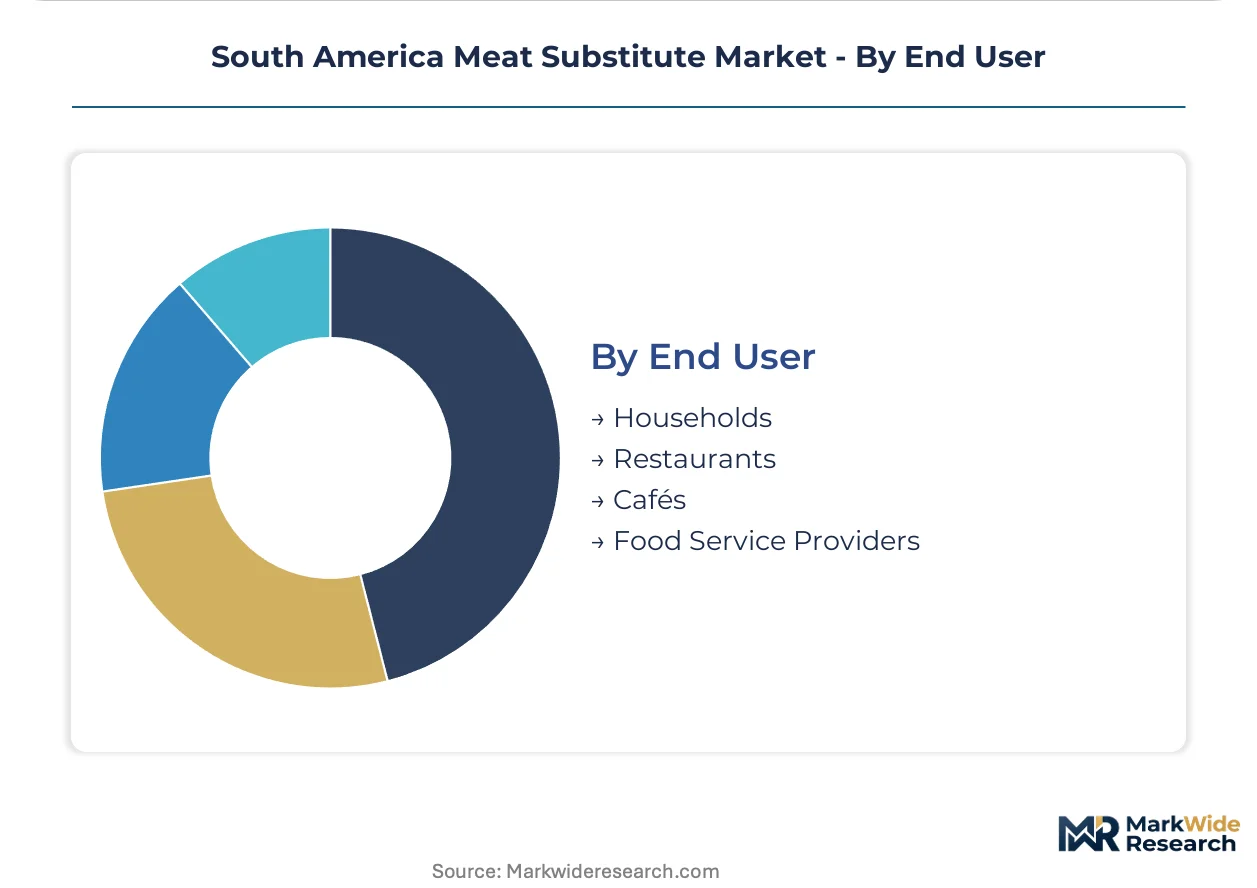
End User:
Application maturity separates established household trial from emerging food service integration across national markets.
- Households:Retail purchasers in Brazilian urban centers drive volume through supermarket and e-commerce channels, with private-label penetration accelerating in working-class neighborhoods.
- Restaurants:Full-service operators in São Paulo and Buenos Aires add dedicated plant-based sections to menus, creating pull-through for frozen patty and ground formats.
- Cafés:Specialty coffee chains in Colombian cities trial breakfast sandwich applications with chilled sausage alternatives.
- Food Service Providers:Institutional caterers and contract food operators across Chilean mining camps and Brazilian corporate dining facilities source bulk frozen formats.
Transaction volume concentrates in households; restaurant adoption shows steepest expansion trajectory as menu integration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's urban food service corridor concentrates meat substitute demand through quick-service restaurant chains and supermarket retail, anchoring Brazilian market development while regulatory divergence between ANVISA and ANMAT shapes cross-border trade patterns.
Brazil
ANVISA nutritional equivalence mandates accelerate domestic manufacturing investments as frozen patty distribution expands through Rio de Janeiro and São Paulo supermarket chains. Quick-service operators now dedicate menu sections to plant-based proteins, pulling volume through São Paulo's urban food service corridor. Southern Brazil biotechnology parks concentrate precision fermentation infrastructure for heme protein production.
Argentina
Buenos Aires province consumers substitute tempeh for traditional beef in milanesa preparations as price spreads narrow between plant and animal proteins. ANMAT's 2023 tightening of novel food registration protocols extends pre-market review periods by 14-18 months versus Brazilian pathways. Wheat gluten concentrate production clusters in Buenos Aires province, exposing brands to peso devaluation risk.
Colombia
Bogotá and Medellín supermarket chains lack dedicated plant-based protein sections, creating first-mover positioning for direct distribution relationships. Chilled sausage alternatives trial in specialty coffee chain breakfast applications. Colombian retail underpenetration offers expansion runway as extrusion technology maturation reduces formulation costs for mid-tier brands.
Chile
Institutional caterers across Chilean mining camps source bulk frozen formats for corporate dining facilities. Upscale retail in Santiago commands per-unit premiums for marinated strips and sausage links positioned adjacent to conventional meat cases. Cold chain infrastructure gaps constrain chilled-format penetration in secondary cities.
Peru
Lima restaurant chains integrate AI-driven flavor mapping with precision fermentation for custom protein development targeting regional cuisine applications. Tofu serves foundational ingredient demand in Peruvian home cooking among health-conscious urban households. Asian-descendant communities in metropolitan Lima drive stir-fry application volume.
South America Meat Substitute Market Competitive Landscape
Premium-margin players sit above commodity-margin players across protein source and format sophistication, with mycoprotein and precision fermentation lines commanding price multiples over soy isolate commodities. The vendor base stratifies into three tiers: multinational frozen patty distributors with established retail relationships, regional AI-driven flavor replication specialists, and agricultural processors leveraging existing crushing infrastructure. Strategic moves concentrate on regulatory relationship building with ANVISA and ANMAT, plus cold chain partnership development for chilled-format expansion.
Within the multinational frozen distribution tier, Beyond Meat Inc. and Impossible Foods Inc. occupy positions defined by retail channel access and brand recognition. NotCo exemplifies the regional innovation archetype through AI-driven formulation capabilities. Cargill Incorporated anchors the agricultural processor tier, leveraging commodity soy processing footprints for wheat-protein concentrate supply to mid-tier brands. These three archetypes represent distinct competitive vectors: technology licensing, regulatory navigation, and upstream supply control.
| Leading Market Players |
|---|
| Beyond Meat Inc. |
| Impossible Foods Inc. |
| Tyson Foods Inc. |
| Kellogg's Company |
| Turtle Island Foods (Tofurky) |
| NotCo |
| NaturAlba |
| Green Eats |
| Cargill Incorporated |
| Others |
Value Network & Pricing Analysis
Yellow pea protein isolate futures volatility cascades through South American meat substitute manufacturing, compressing margins for premium chilled-format producers while anchoring frozen commodity tiers to Brazilian soy crushing economics.
Pricing Analysis
Protein content equivalence anchors value-based pricing tiers across Brazilian retail channels. Three-tier pricing structure across premium mycoprotein, standard pea-protein, and economy soy-isolate levels stratifies by sensory fidelity and clean-label positioning. Pricing pressure stems from Argentine peso devaluation elevating wheat gluten concentrate import costs. Household buyers in São Paulo's working-class neighborhoods exhibit highest price sensitivity, while Colombian food service operators absorb premiums for chilled sausage formats.
Supply Chain Analysis
Dual-sourcing requirements from Brazilian quick-service chains mandate qualified suppliers across both Paraná-Paraguay river basin soy processors and Canadian yellow pea importers. Geographic supply concentration centers on Brazil, Argentina, and Canada for protein inputs. Raw material dependencies include defatted soy meal, yellow pea isolates, and vital wheat gluten. Single-source vulnerability runs through Buenos Aires province wheat gluten clusters. Distribution runs through São Paulo urban food service corridor cold chain partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where ANMAT's 2023 novel food registration tightening erects barrier-to-entry moats favoring incumbents with established regulatory relationships.
For Market Incumbents: Anchor defensive positioning through backward integration into Paraná-Paraguay soy crushing capacity and ANVISA certification maintenance. Threat from precision fermentation entrants with heme protein capabilities demands R&D investment in high-moisture extrusion texture replication. Channel control through exclusive frozen distribution agreements with Rio de Janeiro and São Paulo supermarket chains protects volume share. For New Entrants and Emerging Players: Begin with Colombian retail underpenetration in Bogotá and Medellín supermarket chains lacking dedicated plant-based sections. White-space targets include chilled sausage alternatives for specialty coffee chain breakfast applications and private-label supply contracts for inflation-pressured Brazilian working-class neighborhoods. Go-to-market angle centers on direct distribution relationships bypassing established importer networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional AI-driven flavor replication specialists in Brazilian biotechnology parks with ANVISA relationships already established. Long-term viability over the mid-term projection horizon hinges on Mercosur harmonization eliminating redundant safety assessments. Signal to watch is ANMAT certification timeline compression as regulatory capacity expands.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Infrastructure Buildout | Heme protein production in southern Brazil biotechnology parks differentiates umami depth for premium lines. |
| ANVISA Regulatory Relationship Investment | Established clearance pathways accelerate product launch timelines versus ANMAT-extended review periods. |
| Colombian Direct Distribution Partnership | First-mover positioning in Bogotá and Medellín supermarket chains captures underpenetrated retail whitespace. |
| High-Moisture Extrusion Capacity Addition | Textured vegetable protein systems reduce formulation costs for mid-tier brands serving Chilean channels. |
| Mercosur Harmonization Lobbying Coalition | Cross-border standard alignment eliminates redundant safety assessments for Brazil-Argentina-Paraguay product flows. |
Research Methodology
ANVISA regulatory filings, Argentine ANMAT registration databases, and Brazilian supermarket chain procurement records formed the secondary backbone, cross-referenced with primary interviews with food technology R&D directors, quick-service restaurant procurement managers, and cold chain logistics operators. Bottom-up volume triangulation from Paraná-Paraguay soy crushing capacity and top-down value estimation from São Paulo retail channel audits converged on segment-level outputs.
Historical trendline analysis of frozen versus chilled format velocity across Brazilian and Colombian supermarket channels anchored the projection framework. Segmentation dimensions modeled include product type, temperature format, protein source, and end-user application across the analysis window. CAGRs derived from elasticity-adjusted demand curves incorporating pea protein import cost volatility and extrusion technology cost reduction curves.
ANMAT certification timeline extensions, Canadian yellow pea harvest volatility, and Argentine peso devaluation are the dominant revision risks to forecast assumptions. Deviation in Mercosur harmonization progress would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Vegan Protein Blend Market
Plant Based Food
Chickpea-Based Products Market
Plant Based Food
France Plant Protein Market
Plant Based Food
Vegan Asian Food Market
Plant Based Food
Plant-Based Milk Alternatives Market
Plant Based Food
Middle East Plant Protein Market
Plant Based Food
India Pea Protein Market
Plant Based Food
Plant Based Breads Market
Plant Based Food
Insoluble Pea Protein Market
Plant Based Food
Vegan Gelatin Market
Plant Based Food
USA Plant-Based Creamers Market
Plant Based Food
Canada Plant-Based Food and Beverages Market
Plant Based Food
Meatless Meat Market
Plant Based Food
Global Tofu Market
Plant Based Food
India Plant Based Milk Market
Plant Based Food
Plant-Based Beef Market