
 Vegan Flavor Market | 2026-2036
Vegan Flavor Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Flavor Market Analytics
Europe is reconfiguring vegan flavor production capacity as fermentation-derived and botanical extraction facilities expand across the Netherlands, Germany, and France. Givaudan SA leverages its Swiss R&D base to sustain leadership in natural-identical flavor molecules. Symrise AG anchors its position through deep biotechnology investments in plant protein masking solutions. Kerry Group competes by controlling integrated supply chains from raw botanical sourcing to finished flavor systems.
Vegan flavors comprise volatile and non-volatile compounds derived exclusively from plant, microbial, or mineral sources, formulated without animal-derived carriers or processing aids such as castoreum, bone char, or lactose-based diluents. These formulations typically achieve flavor intensity at 0.01–0.5% usage rates in finished food matrices, primarily to replicate or enhance sensory profiles in plant-based alternatives where base proteins introduce off-notes. Flavoring agents dominate current revenue pools due to their universal applicability across applications, while extracts represent the fastest-expanding category as manufacturers seek single-ingredient clean-label positioning. Dairy alternatives concentrate margin capture because masking bitterness in oat, pea, and soy bases demands premium customized solutions rather than standard off-the-shelf compounds.
The European Food Safety Authority enforces Novel Food regulations that classify precision-fermented flavor precursors, directly impacting registration timelines and commercialization pathways for biotechnology-derived ingredients. The U.S. Food and Drug Administration maintains GRAS self-affirmation pathways but intensifies scrutiny of natural flavor claims amid litigation risk. Stakeholders must monitor evolving regulatory distinctions between naturally derived and nature-identical classifications, as these definitions increasingly determine market access and pricing power across jurisdictions.
Market Dynamics
Fermentation-derived flavor precursors are redrawing ingredient sourcing maps as precision biotechnology displaces conventional solvent extraction, forcing facilities to co-locate with bioreactor infrastructure rather than traditional agricultural processing zones.
Growth Catalysts
- EU Novel Food regulations:EFSA's streamlined approval pathways for microbial-derived ingredients accelerate commercialization timelines for precision-fermented vanillin and dairy lactones, reducing regulatory uncertainty for biotech entrants.
- Plant-based dairy alternatives:Oat and pea protein bases generate persistent off-notes requiring specialized masking flavors, creating sustained demand for customized bitterness-blocking formulations across beverage and frozen dessert applications.
- Clean-label positioning:Consumer rejection of synthetic additives drives food manufacturers toward single-ingredient botanical extracts, expanding premium positioning opportunities for certified organic flavor houses.
Market Restraints
- Raw material volatility:Climate-driven supply fluctuations in vanilla orchid cultivation from Madagascar and Indonesia create price instability for natural vanilla extracts, compressing margins for extract-dependent portfolios.
- Bioreactor capacity concentration:Precision-fermentation infrastructure clusters heavily in the Netherlands and Denmark, creating geographic supply risk and transportation cost premiums for southern European flavor compound buyers.
- Technical substitution limits:Heat-stable natural alternatives to synthetic benzaldehyde in baked goods applications remain functionally inferior, constraining clean-label migration in high-temperature processing segments.
Strategic Opportunities
- French gastronomy sector:Traditional cuisine's gradual plant-based adaptation creates demand for umami-rich vegan flavor systems that replicate aged cheese and fermented meat profiles without animal-derived substrates.
- EU Green Deal procurement mandates:Public sector foodservice contracts increasingly require carbon-footprint disclosures, favoring suppliers with verified fermentation-based production over energy-intensive solvent extraction methods.
- Direct-to-manufacturer platforms:Digital sampling and AI-driven flavor matching tools bypass traditional distributor networks, enabling mid-sized plant-based startups to access previously cost-prohibitive custom formulation services.
Industry Challenges
- Flavor chemist specialization gap:The intersection of food science and biotechnology requires hybrid expertise in metabolic engineering and sensory evaluation, with European universities producing insufficient cross-trained graduates.
- Novel Food dossier preparation:EFSA's requirement for comprehensive toxicological data on new microbial strains extends registration timelines to 18-24 months, delaying revenue recognition for biotech-derived launches.
- Legacy equipment retrofit costs:Conventional extraction facilities face capital-intensive bioreactor installation and contamination-control upgrades to pivot toward precision-fermentation production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Flavor Market |
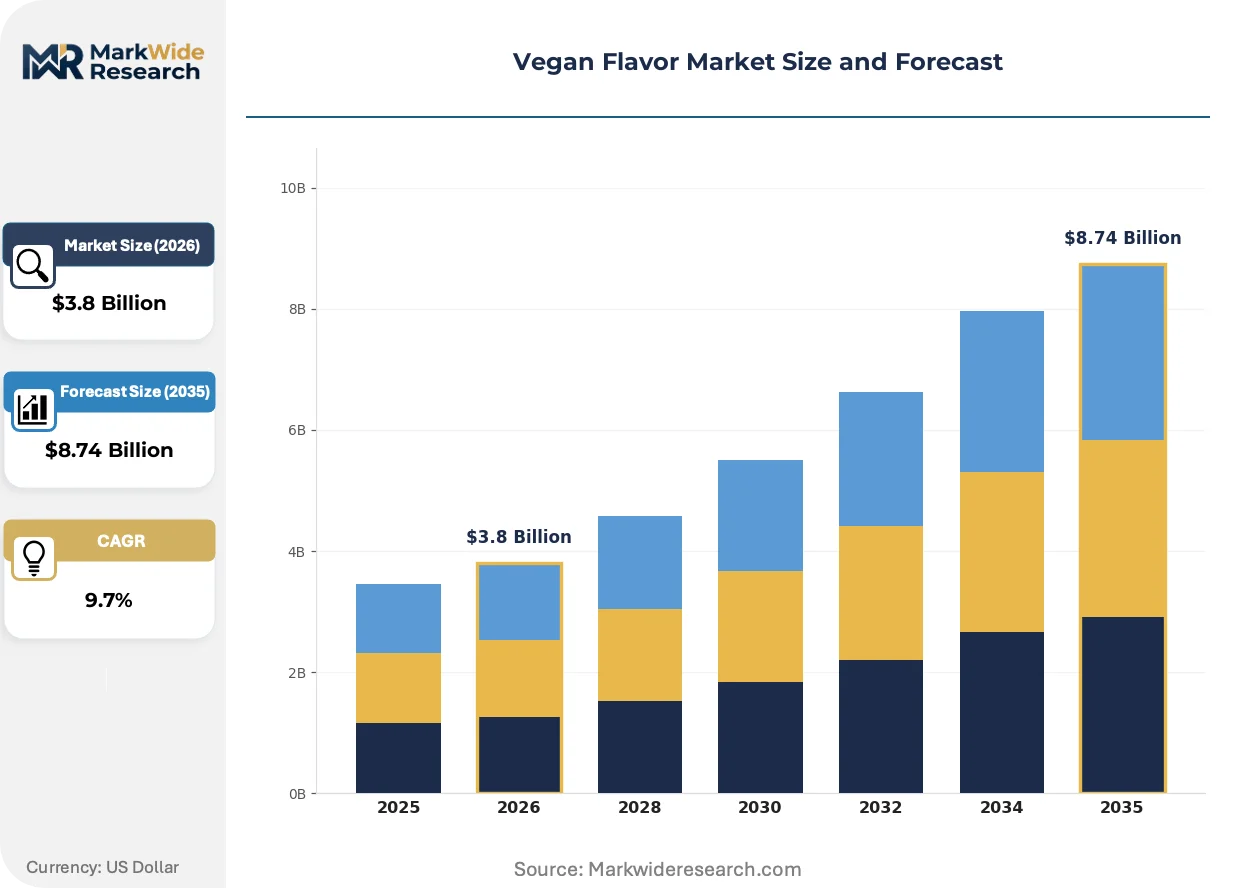
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavoring Agents, Coatings, Seasonings, Extracts Application: Beverages, Snacks, Sauces, Dairy Alternatives End User: Food Manufacturers, Restaurants, Retail, Online Stores Distribution Channel: Supermarkets, E-commerce, Specialty Stores, Direct Sales |
| Companies Covered | Givaudan SA, Symrise AG, Kerry Group, International Flavors & Fragrances Inc., Sensient Technologies Corporation, Takasago International Corporation, Firmenich, Mane SA, Döhler GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Flavor Market Evolving Landscape
Biotechnology and regulatory stringency are converging to compress the advantage window for conventional extraction methods, while demand-side purchasing reforms redistribute margin capture across the value chain.
Precision fermentation of flavor molecules using engineered yeast strains is rendering obsolete energy-intensive botanical cultivation and solvent-based extraction for high-value compounds like saffron-derived crocin and raspberry ketone. Plant-based meat and dairy manufacturers in Germany and the Netherlands are adopting these ingredients at accelerated procurement cycles, compressing the cost premium between natural-identical and conventionally natural positioning.
EFSA's 2023 guidance on labeling of precision-fermented ingredients as "natural flavoring" under EU food law is creating regulatory divergence with member-state interpretations, forcing multinationals to maintain dual formulation specifications. The Netherlands and Denmark align with EFSA's permissive stance, while France and Italy pursue stricter disclosure requirements, segmenting market access by national enforcement intensity.
Food manufacturers are consolidating supplier relationships around integrated flavor-and-texture system providers rather than discrete ingredient vendors, unbundling traditional procurement categories. This concentration favors suppliers offering co-development partnerships with dedicated application labs, most visible in Nordic plant-based dairy where oat milk producers demand end-to-end sensory optimization rather than standalone flavor compounds.
Vegan Flavor Market Segmentation
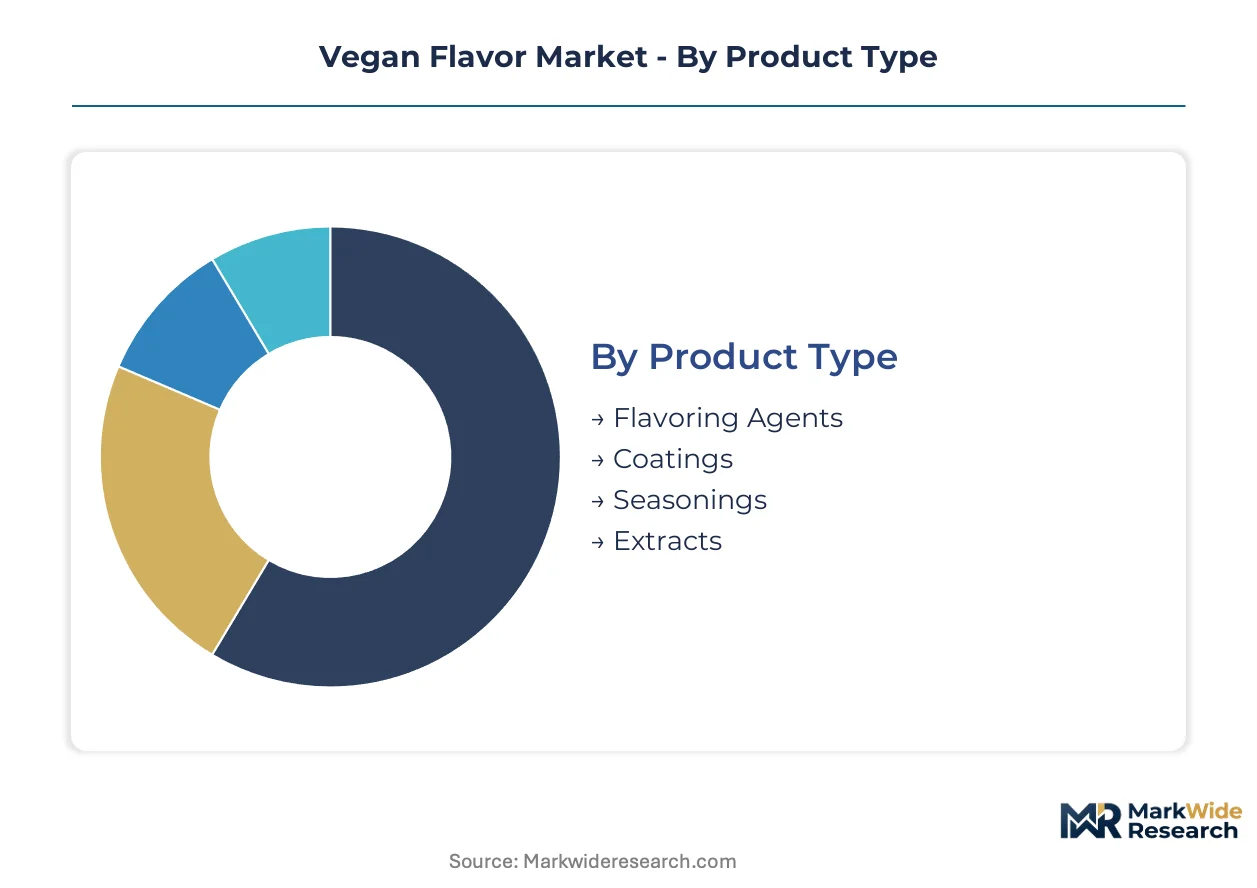
Vegan flavor procurement cycles vary dramatically by formulation complexity. Standardized flavoring agents move through annual contracts, while customized masking systems for plant-based proteins require 18-month development timelines. Understanding these velocity differences enables suppliers to align inventory and R&D investment with segment-specific demand patterns.
Product Type:
Flavoring agents turn inventory fastest due to standardized specifications and broad applicability, while extracts require extended cultivation and extraction cycles that stretch working capital requirements.
- Flavoring Agents:Concentrated synthetic-identical and natural-identical compounds formulated at 0.01–0.5% usage rates. Dairy alternative manufacturers in Germany and the Netherlands drive procurement of bitterness-masking variants for oat and pea protein bases. EFSA's streamlined Novel Food pathways for microbial-derived molecules accelerates formulation refresh cycles.
- Extracts:Single-ingredient botanical concentrates including vanilla, citrus, and spice distillates. Clean-label positioning in French and Italian retail channels prioritizes certified organic extracts despite price premiums from Madagascar and Indonesian supply volatility. These represent the fastest-expanding category as manufacturers pursue ingredient transparency.
- Coatings:Surface-applied flavor systems for snack and confectionery applications. Heat-stable formulations for baked goods remain technically constrained.
- Seasonings:Blended spice and herb compounds for savory applications. Foodservice demand concentrates in German plant-based meat alternatives.
Flavoring agents dominate installed base. Extracts are where expansion concentrates.
Application:
Margin structure separates commodity beverage applications from premium customized systems for protein alternatives.
- Dairy Alternatives:Specialized masking and mouthfeel modulation for oat, soy, and pea milk bases. Nordic producers in Sweden and Denmark demand integrated flavor-texture co-development partnerships rather than standalone compounds. Precision-fermented dairy lactones command premium positioning.
- Beverages:Ready-to-drink applications favor cost-optimized flavoring agents with rapid formulation turnaround. German private-label retailers drive volume procurement.
- Snacks:Extruded and puffed applications require heat-stable natural alternatives to synthetic benzaldehyde that remain functionally inferior.
- Sauces:Umami-rich systems replicating aged cheese and fermented profiles for French gastronomy sector adaptation.
Dairy alternatives capture premium margin pools. Beverages anchor volume throughput.
End User:
Technical sophistication and procurement scale create distinct service requirements across customer types.
- Food Manufacturers:Large-scale plant-based protein processors requiring dedicated application labs and co-development partnerships. Kerry Group and Symrise AG compete through integrated supply chain control and biotechnology investments respectively.
- Restaurants:Foodservice operators seeking consistent flavor delivery at scale. EU Green Deal procurement mandates increasingly require carbon-footprint disclosures.
- Retail:Private-label and branded product developers with moderate technical capabilities. Digital sampling platforms reduce barrier to custom formulation access.
- Online Stores:Direct-to-consumer specialty brands with fragmented demand and high formulation customization requirements.
Food manufacturers anchor technical partnership investment. Restaurants are where sustainability compliance requirements intensify.
Distribution Channel:
Channel economics reflect customer acquisition costs versus lifetime value tradeoffs.
- Direct Sales:Technical consultation-intensive relationships with major food manufacturers. Givaudan SA leverages its Swiss R&D base through direct technical service teams.
- E-commerce:Digital sampling and AI-driven flavor matching tools enable mid-sized plant-based startups to access previously cost-prohibitive services. Procurement cycles compress versus traditional distributor networks.
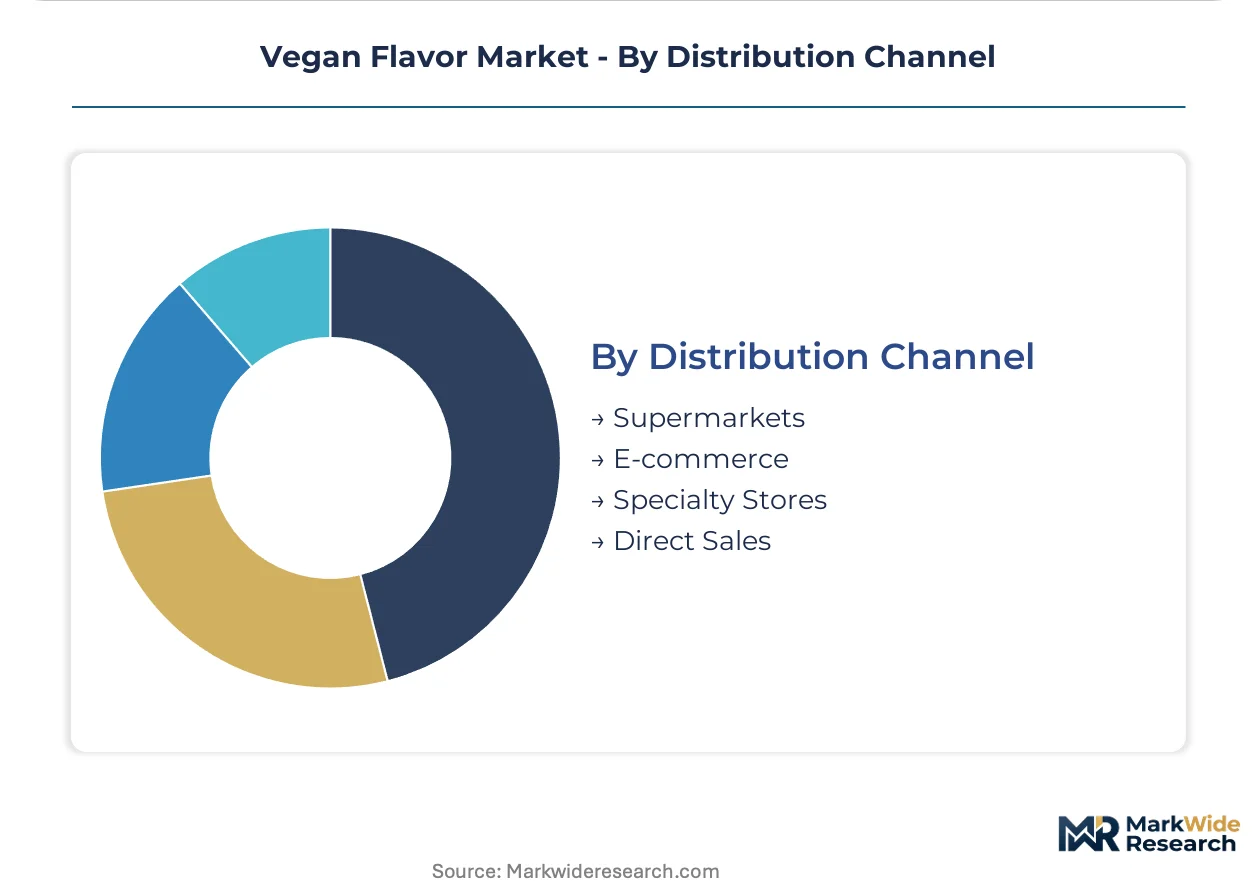
- Supermarkets:Mass-market retail placement for standardized flavoring agents with limited technical support.
- Specialty Stores:Certified organic and clean-label extracts targeting premium consumer segments in France and Italy.
Direct sales dominate relationship value. E-commerce is where customer acquisition economics improve most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA's Novel Food regulations in Europe anchor the most concentrated geography for vegan flavor commercialization. The regulatory framework shapes production location decisions and market access timelines across continental markets.
Germany
Plant-based dairy manufacturers in Hamburg and Cologne drive demand for bitterness-masking oat and pea protein formulations. The EU Green Deal procurement mandates for public sector foodservice require carbon-footprint disclosures, favoring fermentation-based suppliers. Bavaria hosts precision-fermentation facility expansions as bioreactor infrastructure clusters around Munich's biotechnology corridor.
Netherlands
Wageningen University's food innovation ecosystem accelerates precision-fermentation research partnerships with flavor houses. EFSA's streamlined approval pathways for microbial-derived ingredients reduce registration timelines for novel compounds. Rotterdam and Amsterdam harbor zones concentrate bioreactor manufacturing capacity serving northern European markets.
France
Traditional gastronomy's gradual plant-based adaptation creates demand for umami-rich vegan flavor systems replicating aged cheese profiles. ANSM and national regulators pursue stricter disclosure requirements for precision-fermented ingredients than EFSA guidance permits. Lyon and Paris foodservice clusters drive premium extract procurement for clean-label positioning.
United States
FDA GRAS self-affirmation pathways sustain faster formulation refresh cycles than European regulatory timelines. Litigation risk around natural flavor claims intensifies scrutiny of ingredient sourcing documentation. California's plant-based protein startups in San Francisco and Los Angeles anchor demand for customized masking solutions.
Denmark
Nordic plant-based dairy producers demand integrated flavor-texture co-development partnerships rather than standalone compounds. Copenhagen's fermentation infrastructure attracts capacity investments from multinational flavor suppliers. National regulators align with EFSA's permissive stance on precision-fermented ingredient labeling.
Vegan Flavor Market Competitive Landscape
Integrated multinationals and specialized biotechnology firms split the market into distinct capability tiers. Consolidation concentrates around firms controlling fermentation infrastructure and botanical extraction networks. Three archetypes dominate: Swiss-German flavor houses with integrated R&D, Irish-Dutch ingredient platforms with supply chain control, and Japanese specialists in natural-identical molecules. Competitive moves center on precision-fermentation capacity expansion and co-development partnerships with plant-based protein processors.
Among the integrated multinational tier, Givaudan SA and Symrise AG exemplify divergent strategic positioning within European markets. Kerry Group occupies a position anchoring supply chain integration from raw botanical sourcing through finished flavor systems. These three entities represent the dominant competitive archetypes: fermentation-led biotechnology investment, integrated supply chain control, and natural-identical molecular expertise respectively.
| Leading Market Players |
|---|
| Givaudan SA |
| Symrise AG |
| Kerry Group |
| International Flavors & Fragrances Inc. |
| Sensient Technologies Corporation |
| Takasago International Corporation |
| Firmenich |
| Mane SA |
| Döhler GmbH |
| Others |
Value Network & Pricing Analysis
Raw material volatility in Madagascar and Indonesian vanilla orchid cultivation compresses margin structures across extraction-dependent portfolios while simultaneously forcing buyers toward precision-fermented alternatives. This commodity-driven risk vector widens pricing spreads between certified organic botanical extracts and microbial-derived natural-identical compounds, reshaping procurement tier boundaries and bioreactor co-location decisions.
Pricing Analysis
Geographic price spreads separate northern European fermentation facilities from southern European buyers facing transportation cost premiums. Three-tier pricing structure across premium certified-organic extracts, standard natural-identical compounds, and economy synthetic-identical formulations dominates contract structures. Cost compression in premium tiers is intensifying because climate-driven supply instability in tropical cultivation zones erodes predictability. Food manufacturers with dedicated application labs exhibit lowest price sensitivity, while retail private-label developers drive volume procurement at economy tiers.
Supply Chain Analysis
Contract manufacturing concentration rests with integrated flavor houses operating captive fermentation capacity in the Netherlands, Germany, and Denmark. Raw material dependencies draw from Madagascar vanilla orchids, Indonesian spice cultivation, and engineered yeast strain suppliers. Single-source vulnerability concentrates in tropical botanical extraction where climate shocks propagate rapidly through ingredient availability. Distribution runs through direct technical service teams for major food manufacturers and digital sampling platforms for mid-sized plant-based startups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision-fermented flavor molecules threaten incumbent extraction-dependent portfolios as biotechnology achieves cost parity with botanical cultivation. Incumbents must navigate this substitution defense by controlling fermentation infrastructure and masking-technology IP.
For Market Incumbents: Build biotechnology moats through precision-fermentation capacity expansion in Munich and Wageningen corridors. Secure captive supply of engineered yeast strains to reduce dependency on tropical botanical volatility. Deepen masking-technology IP portfolios to defend against emerging biotech entrants offering standalone flavor molecules without integrated protein-modulation systems.
For New Entrants and Emerging Players: Build out white-space positions in French gastronomy sector umami systems and Italian clean-label extract certification. The most penetrable segment sits in mid-sized plant-based meat processors lacking dedicated application labs. Pursue co-development partnerships with Nordic oat milk producers seeking end-to-end sensory optimization rather than commodity flavor compounds.
For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors fermentation-capable platforms over extraction-dependent assets. Long-term viability over the coming decade hinges on regulatory navigation capabilities across EFSA Novel Food pathways and member-state labeling divergence. Target acquisition archetypes include Dutch precision-fermentation specialists with validated microbial strain libraries. Watch EFSA guidance harmonization pressure as inflection signal for cross-border formulation standardization.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision-Fermentation Capacity Expansion | Bioreactor installation in Netherlands and Denmark clusters reduces transportation cost premiums for southern European buyers. |
| Integrated Flavor-Texture System Development | Co-development partnerships with Nordic oat milk producers capture premium positioning beyond standalone compound sales. |
| EFSA Novel Food Dossier Investment | Streamlined microbial-derived ingredient pathways accelerate commercialization timelines versus extraction-dependent competitors. |
| Digital Sampling Platform Launch | AI-driven flavor matching tools compress procurement cycles for mid-sized plant-based startups previously excluded from custom services. |
| Certified Organic Extract Sourcing | Madagascar and Indonesian supply relationships defend premium positioning in French and Italian retail clean-label channels. |
Research Methodology
Cross-validation between primary interviews with flavor application scientists, plant-based protein R&D directors, and EFSA regulatory consultants anchors the qualitative findings. Secondary validation draws from EFSA Novel Food guidance documents, EU Green Deal procurement mandate texts, and customs trade data on botanical extract flows. Bottom-up triangulation across fermentation facility capacity announcements and top-down reconciliation with food manufacturer procurement disclosures ensures segment-level consistency.
Calibration against historical formulation refresh cycles and regulatory approval timelines informs the projection framework. Segmentation dimensions span product type, application, end user, and distribution channel with regional regulatory cluster overlays. CAGRs derive from weighted capacity expansion announcements and substitution elasticity estimates between extraction-derived and fermentation-derived compounds. Inputs include bioreactor installation pipelines and EFSA dossier submission velocities.
Stress conditions across vanilla orchid supply disruption, EFSA labeling guidance divergence, and precision-fermentation yield variance were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory harmonization pressure and biotechnology cost curves. Quarterly review of EFSA member-state enforcement divergence and bioreactor utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Vegan Pastry Market
Plant Based Food
India Plant Based Milk Market
Plant Based Food
Europe Plant-Based Food and Beverage Market
Plant Based Food
Europe Plant-Based Seafood Market
Plant Based Food
Europe Textured Vegetable Protein Market
Plant Based Food
North America Textured Vegetable Protein Market
Plant Based Food
Vegan Asian Food Market
Plant Based Food
Meatless Meat Market
Plant Based Food
Middle East and Africa Plant-Based Meat and Dairy Products Market
Plant Based Food
Vegan Drink Mixes Market
Plant Based Food
Global Organic Soy Protein Market
Plant Based Food
Asia-Pacific Pea Protein Market
Plant Based Food
Vegan Meat Alternatives Market
Plant Based Food
Low Fat Plant-Based Diet Market
Plant Based Food
Plant-Based Natural Flavor Market
Plant Based Food
Soy Protein Market