
 Vegan Protein Foods Market | 2026-2036
Vegan Protein Foods Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Protein Foods Market Analytics
Precision fermentation and high-moisture extrusion is reshaping protein texturization, enabling fat-mimicking mouthfeel and fibrous structures that replicate animal muscle tissue. Beyond Meat leverages proprietary extrusion systems to sustain brand positioning in retail and foodservice channels. Impossible Foods anchors its competitive edge through heme protein biotechnology, while Roquette Frères dominates pea protein isolate supply to downstream formulators.
Vegan protein foods encompass plant-derived or microbial protein formulations engineered to deliver complete amino acid profiles, typically containing 15–25 grams of protein per serving with PDCAAS scores exceeding 0.8. These products serve nutritional fortification, meat substitution, and sports recovery applications across consumer and commercial food systems. Meat alternatives command the largest revenue pool among product types, though protein powders generate superior margins in direct-to-consumer channels. Pea protein isolate is displacing soy as the fastest-growing source category, driven by allergen-free positioning and neutral flavor profiles that suit clean-label formulations.
The FDA governs protein content claims and allergen labeling under FDCA provisions, while the USDA oversees plant-based meat labeling disputes through FSIS jurisdiction. EFSA novel food authorizations and EU protein content thresholds shape market access for European entrants, and China's SAMR enforces GB standards for plant protein beverage fortification. Stakeholders must monitor evolving definitions of "meat" and "milk" analogs across jurisdictions, as classification rulings determine retail placement, tax treatment, and eligibility for public procurement contracts.
Market Dynamics
Precision fermentation infrastructure is concentrating protein production capabilities among biotechnology-capable formulators, compressing traditional commodity processing margins while enabling novel texture and nutritional claims that reshape competitive positioning across retail and foodservice channels.
Growth Catalysts
- Flexitarian Dietary Migration:Consumer protein diversification in Germany, the United States, and Brazil is expanding addressable demand beyond core vegan demographics into mainstream household purchasing.
- High-Moisture Extrusion Scale-Up:Equipment manufacturers are deploying next-generation systems that replicate animal muscle fiber architecture at industrial throughput rates.
- EU Green Deal Protein Transition:Farm-to-Fork Strategy targets are redirecting agricultural subsidies toward legume cultivation and novel protein processing capacity.
Market Restraints
- Pea Protein Isolate Supply Concentration:Roquette Frères and a limited supplier base control premium isolate output, creating input vulnerability for downstream formulators.
- Precision Fermentation Capex Barriers:Bioreactor infrastructure and strain development costs restrict market entry to well-capitalized biotechnology players.
- USDA-FSIS Labeling Disputes:Ongoing jurisdictional conflicts over "meat" and "milk" analog terminology create retail placement uncertainty and compliance fragmentation.
Strategic Opportunities
- Microbial Protein Regulatory Pathways:EFSA novel food authorization frameworks are opening accelerated market access for biomass fermentation products in European markets.
- Sports Nutrition Direct-to-Consumer:Protein powder brands are bypassing conventional retail through subscription models and athletic influencer distribution networks.
- Clean-Label Convergence:Pea protein isolate is hybridizing with precision fermentation-derived functional ingredients to deliver allergen-free, neutral-flavor formulations.
Industry Challenges
- Food Technologist Talent Scarcity:Formulation expertise spanning extrusion, fermentation, and sensory science commands premium compensation and extended recruitment cycles.
- PDCAAS Validation Complexity:Protein quality scoring requirements vary across FDA, EFSA, and China's SAMR jurisdictions, complicating multi-region product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Protein Foods Market |
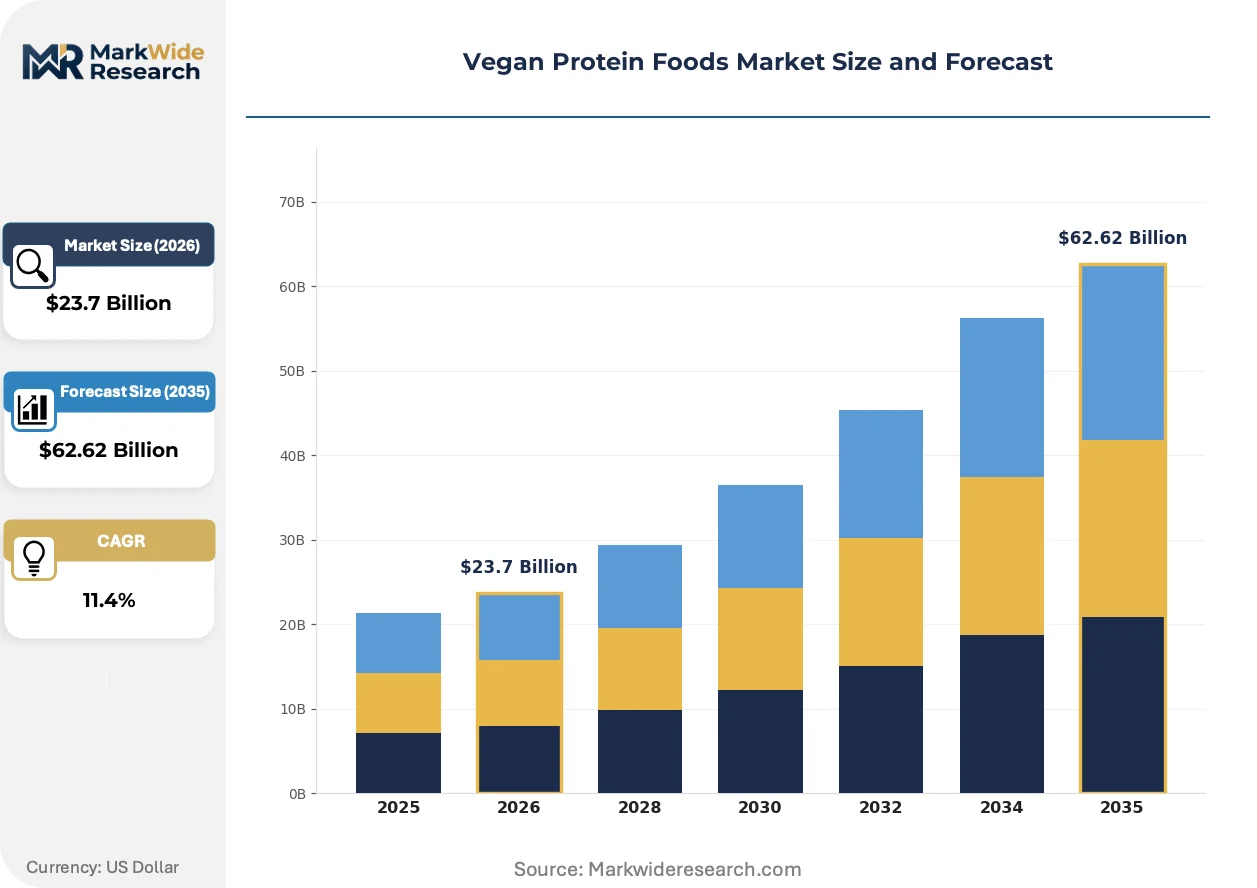
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plant-Based Protein Powder, Meat Alternatives, Protein Bars, Snacks Source: Pea Protein, Soy Protein, Rice Protein, Hemp Protein Form: Ready-to-Eat, Powder, Frozen, Canned End User: Athletes, Health-Conscious Consumers, Vegans, Fitness Enthusiasts |
| Companies Covered | Beyond Meat, Impossible Foods, Archer Daniels Midland Company, Cargill Incorporated, Nestlé, Roquette Frères, Kerry Group, Glanbia plc, Garden of Life, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Protein Foods Market Evolving Landscape
Biotechnology and mechanical processing are converging to solve texture and taste limitations that historically constrained plant-based protein adoption in mainstream food systems.
Precision fermentation is hybridizing with traditional extrusion methods to generate fat-mimicking mouthfeel and fibrous protein structures that replicate cooked animal tissue. Sports nutrition brands and foodservice operators are adopting these hybrid ingredients at accelerating rates. The technology is compressing the performance gap between plant-derived and animal-derived proteins in prepared food applications.
EFSA novel food authorization timelines and EU protein content thresholds are reshaping market access requirements for European entrants. Manufacturers must navigate divergent national implementations of shared regulatory frameworks. Plant-based meat analogs face the most stringent scrutiny under evolving definitions of "meat" and "milk" analogs.
Direct-to-consumer subscription models are displacing conventional retail distribution for protein powders and nutritional supplements. Athletic performance and recovery segments are driving this channel shift through personalized nutrition platforms. Germany and the United States exhibit the most pronounced migration toward recurring purchase relationships over single-transaction retail buying.
Vegan Protein Foods Market Segmentation
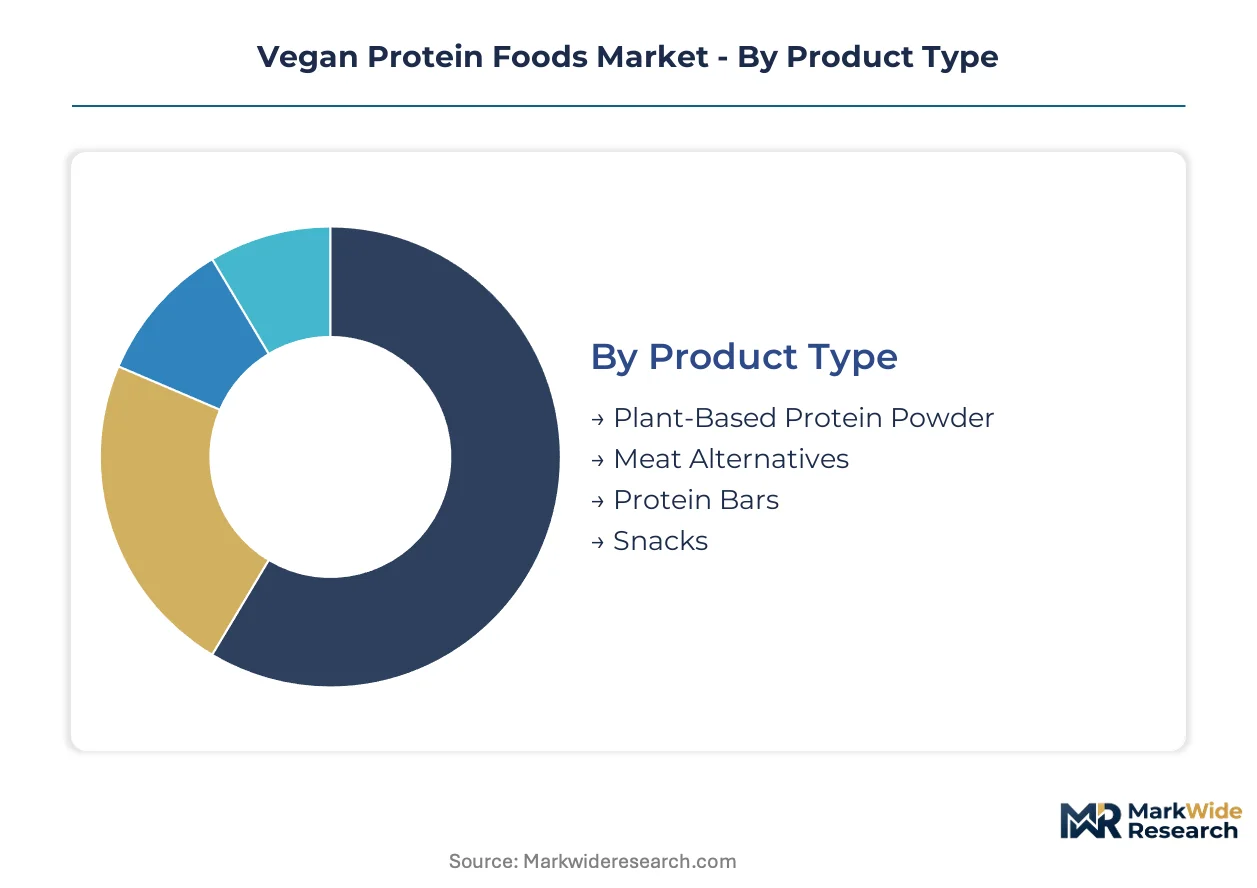
Segmentation in vegan protein foods reveals how formulation technology, consumption context, and protein source characteristics partition commercial opportunity. Each dimension carries distinct margin profiles, regulatory exposure, and supply chain requirements that shape go-to-market strategy.
Product Type:
Mature formats coexist with emerging categories as extrusion and fermentation technologies expand the functional possibilities of plant-derived proteins.
- Plant-Based Protein Powder:Concentrated isolates and concentrates delivering 15-25 grams protein per serving, formulated for solubility and flavor masking. Demand clusters in Germany and the United States through direct-to-consumer subscription channels driven by sports recovery applications.
- Meat Alternatives:High-moisture extruded products replicating animal muscle fiber architecture for retail and foodservice placement. Brazil's flexitarian households and US foodservice operators are accelerating uptake as extrusion scale-up reduces unit costs.
- Protein Bars:Shelf-stable convenience formats combining protein isolates with binding systems and flavor coatings.
- Snacks:Puffed, baked, or extruded bite-sized products targeting between-meal consumption occasions.
Meat alternatives retain volume leadership; protein powders hold the steepest expansion curve.
Source:
Cost tiers separate commodity legume proteins from specialty seed derivatives, with allergen positioning and amino acid completeness driving substitution patterns.
- Pea Protein:Isolate and concentrate fractions from yellow split peas, offering neutral flavor and absence of major allergens. Premium positioning in clean-label formulations across European markets is displacing soy in infant nutrition and sports applications.
- Soy Protein:Mature supply infrastructure with established PDCAAS validation, though GMO and allergen concerns constrain growth in premium segments.
- Rice Protein:Hypoallergenic option with complementary amino acid profile to legume sources, typically blended rather than standalone.
- Hemp Protein:Whole-seed fraction retaining fiber and omega fatty acids, commanding niche positioning in organic and wellness channels.
Pea protein dominates new product development; hemp protein occupies the narrowest volume band with the highest margin structure.
Form:
Distribution infrastructure requirements and perishability create distinct competitive arenas with varying capital intensity and shelf-life constraints.
- Ready-to-Eat:Shelf-stable or refrigerated prepared products requiring minimal consumer preparation. US retail and Brazilian convenience channels favor these formats for household penetration beyond core vegan demographics.
- Powder:Dry concentrates enabling flexible dosing and extended storage, dominating bulk purchasing and subscription models.
- Frozen:Extruded meat alternatives and prepared meals requiring cold chain integrity, constraining distribution reach but preserving texture quality.
- Canned:Retort-processed legume and prepared protein products, primarily bean-based rather than formulated isolates.
Powder forms command the widest distribution footprint; frozen products face the tightest throughput constraints.
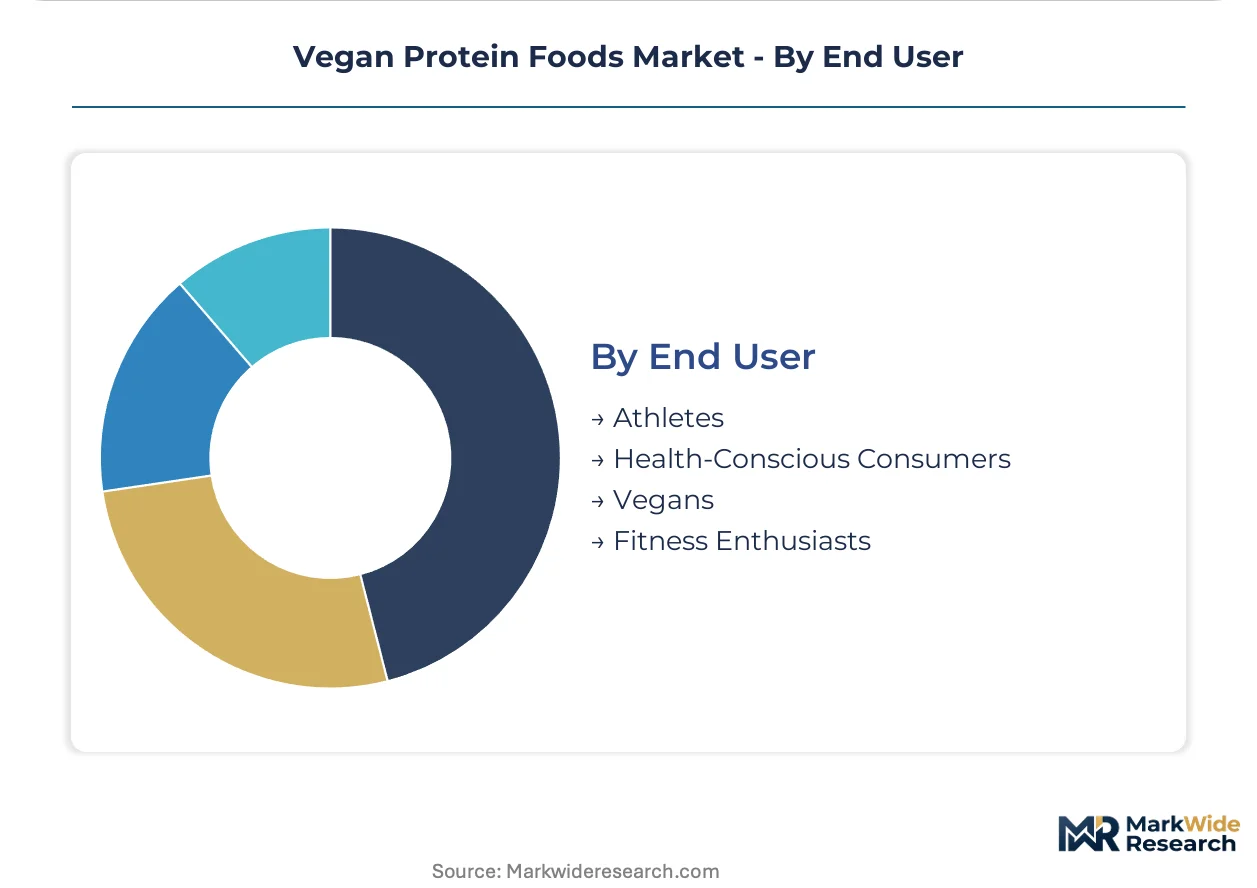
End User:
Customer type determines pricing tolerance, channel preference, and the relative importance of performance claims versus ethical positioning.
- Athletes:Consumers prioritizing protein content per serving, amino acid completeness, and third-party certification for banned substance testing. Sports nutrition brands in Germany and the United States target this segment through influencer networks and performance-focused formulation.
- Health-Conscious Consumers:Flexitarian households seeking protein diversification without full dietary commitment, responsive to clean-label and reduced-processing claims.
- Vegans:Core demographic requiring complete protein sources and ethical supply chain verification, accepting premium pricing for alignment values.
- Fitness Enthusiasts:Recreational exercisers with intermediate protein requirements, price-sensitive and channel-agnostic between retail and direct-to-consumer.
Health-conscious consumers represent the broadest addressable base; athletes generate the highest revenue per user.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flexitarian households in Germany, the United States, and Brazil concentrate purchasing power for vegan protein foods, with sports nutrition consumers and foodservice operators expanding demand beyond core vegan demographics into mainstream protein diversification.
United States
Foodservice operators and athletic performance consumers drive pea protein isolate demand through direct-to-consumer subscription channels. The FDA governs protein content claims under FDCA provisions while USDA-FSIS jurisdiction disputes over "meat" analog labeling create retail placement uncertainty. Chicago and Austin host concentrated extrusion technology development clusters serving national meat alternative brands.
Germany
Flexitarian households and sports nutrition consumers anchor European demand for clean-label protein formulations. The EU Green Deal Farm-to-Fork Strategy redirects agricultural subsidies toward legume cultivation and novel protein processing capacity. Berlin and Hamburg concentrate precision fermentation infrastructure development serving continental supply chains.
Brazil
Expanding middle-class flexitarian adoption and convenience-channel penetration accelerate meat alternative uptake in retail and foodservice. ANVISA enforces novel food authorization frameworks for microbial protein ingredients entering Brazilian markets. São Paulo anchors domestic extrusion manufacturing capacity serving Latin American distribution networks.
China
Urban health-conscious consumers and fitness enthusiasts drive plant protein beverage fortification demand in tier-one cities. SAMR enforces GB standards for protein content claims and allergen labeling in plant-based formulations. Shanghai and Shenzhen concentrate domestic pea protein isolate processing capacity alongside import-dependent premium ingredient channels.
United Kingdom
Health-conscious consumers and ethical purchasing segments sustain demand for allergen-free protein powders and ready-to-eat formats. EFSA novel food authorizations and divergent national implementations of EU protein thresholds shape market access requirements. London and Manchester host formulation R&D clusters serving European export markets.
Vegan Protein Foods Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tiers. Biotechnology-capable formulators concentrate precision fermentation infrastructure while commodity processors defend margin position through extrusion scale-up. Three archetypes dominate: heme protein biotechnologists, pea protein isolate suppliers, and sports nutrition direct-to-consumer brands. Capacity expansion and strategic partnerships constitute the dominant competitive moves reshaping supply relationships.
Within the biotechnology tier, Impossible Foods and Beyond Meat exemplify divergent protein texturization approaches. Among ingredient suppliers, Roquette Frères anchors premium isolate production. These three entities occupy positions spanning downstream brand control and upstream input concentration, representing the vertical spectrum from microbial strain development to retail shelf placement.
| Leading Market Players |
|---|
| Beyond Meat |
| Impossible Foods |
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Nestlé |
| Roquette Frères |
| Kerry Group |
| Glanbia plc |
| Garden of Life |
| Others |
Value Network & Pricing Analysis
Pea protein isolate supply concentration in France and Canada determines both pricing tier spreads and supply chain shape, as Roquette Frères and limited alternative sources compress margins for downstream formulators while enabling premium positioning for allergen-free certification tiers.
Pricing Analysis
Cost-plus contracts with pea protein indexation anchor supplier relationships, though precision fermentation inputs are shifting toward value-based arrangements. Three-tier pricing structure across premium isolate, standard concentrate, and economy commodity grades separates clean-label formulations from mass-market applications. Price differentiation hinges on PDCAAS validation completeness and organic certification status. Cost compression in economy tiers is intensifying because Brazilian and Chinese processors are expanding extrusion capacity. Fitness enthusiasts exhibit the highest price sensitivity, while sports nutrition direct-to-consumer subscribers accept recurring premiums for third-party tested formulations.
Supply Chain Analysis
Yellow split pea cultivation draws from Canada, France, and Russia, with protein extraction concentrated in Roquette Frères' European facilities and emerging Chinese processors. Critical inputs include fermentation feedstock sugars, bioreactor-grade nutrients, and high-moisture extrusion equipment from German and Italian manufacturers. Single-source vulnerability in premium isolate supply creates input security risks for mid-tier formulators lacking long-term offtake agreements. Distribution runs through foodservice broadline distributors in the United States, specialized sports nutrition wholesalers in Germany, and convenience retail networks in Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment in novel food authorizations protects incumbent positions against commodity protein substitutes.
For Market Incumbents: Pre-empt precision fermentation scale-up by securing captive bioreactor capacity in Germany or the United States before EFSA novel food pathways accelerate competitor entry. Anchor supply security through backward integration into pea protein isolate processing or exclusive cultivation partnerships in Canada. Precision fermentation entrants threaten extrusion-dependent meat alternative margins. For New Entrants and Emerging Players: Build out direct-to-consumer subscription infrastructure targeting Brazilian fitness enthusiasts, the most penetrable segment given limited incumbent digital presence. Prioritize hybrid formulations combining pea protein isolate with microbial biomass to differentiate against single-source competitors. Partner with athletic influencer networks for distribution rather than competing for retail shelf space. For Investors and Strategic Acquirers: EFSA novel food authorization timelines reshape the acquisition landscape by elevating biotechnology-capable formulators above commodity processors. Five-to-ten-year viability favors entities with integrated strain development and extrusion capabilities. Target acquisition archetypes include precision fermentation startups with validated biomass strains and established European regulatory relationships. Monitor EFSA authorization announcements as the critical inflection signal for valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Bioreactor capacity expansion in Berlin and Hamburg secures EFSA novel food pathway advantages. |
| Pea Protein Isolate Backward Integration | Captive processing in Manitoba or Saskatchewan insulates against Roquette Frères supply constraints. |
| Direct-to-Consumer Subscription Launch | Recurring revenue models bypass Brazilian retail concentration and capture flexitarian household lifetime value. |
| Hybrid Protein Formulation Development | Combining extruded textures with microbial fat mimics closes performance gaps against animal proteins. |
| Sports Nutrition Certification Investment | Informed Sport and NSF Certified for Sport credentials unlock premium pricing in German athletic channels. |
Research Methodology
The analysis maps protein powder, meat alternative, and microbial biomass segments, each validated through food technology R&D directors, sports nutrition brand managers, and extrusion equipment procurement leads. Primary interviews with plant protein formulators, precision fermentation scientists, and foodservice distribution executives combined with secondary validation from EFSA novel food registers, FDA FDCA guidance documents, ANVISA authorization databases, and customs trade flow records. Bottom-up capacity assessments and top-down consumption estimates triangulate market sizing.
Assumptions held fixed include regulatory authorization timelines and existing tariff structures, while variables included flexitarian adoption rates and precision fermentation yield improvements. Segmentation dimensions modeled encompass product type, protein source, distribution form, and end-user archetype across the projection horizon. CAGRs derive from installed capacity expansion schedules and per-capita protein consumption elasticity. Forecast inputs incorporate EU Green Deal subsidy allocations and Brazilian middle-class disposable income trajectories.
Practitioners should monitor EFSA novel food authorization delays and pea protein harvest yield volatility for early signals requiring forecast revision. Cross-checking against USDA-FSIS labeling dispute resolutions and SAMR GB standard updates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Vegan Meals Market
Plant Based Food
Fractionated Pulses Market
Plant Based Food
Black Rice Protein Market
Plant Based Food
Plant Based Eggs Market
Plant Based Food
China Plant-Based Food and Beverages Market
Plant Based Food
Plant Based Breads Market
Plant Based Food
Global Vegan Fast Foods Market
Plant Based Food
Vegan Margarine Market
Plant Based Food
Vegan Food Market
Plant Based Food
Asia-Pacific Rice Protein Market
Plant Based Food
United States Rice Protein Market
Plant Based Food
Asia Pacific Plant-Based Milk Market
Plant Based Food
New Jersey Vegan Products Market
Plant Based Food
Packed Vegan Foods Market
Plant Based Food
Vegan Dips Market
Plant Based Food
Pea Protein Isolate Market