
 France Plant Protein Market | 2026-2036
France Plant Protein Market Size, Share, and Industry Trends Forecast 2026-2036
France Plant Protein Market Foresight
Precision fermentation and enzymatic extraction is tilting the cost-performance curve for plant protein isolates in French manufacturing. Roquette Frères leverages its decades of pea protein expertise to anchor supply contracts with domestic dairy alternative producers. Kerry Group Plc competes through flavor-masked protein systems that extend its reach into sports nutrition applications. DuPont de Nemours Inc. differentiates via high-purity isolates that sustain premium positioning among nutraceutical customers.
France plant protein encompasses proteinaceous extracts derived from legumes, oilseeds, and cereals, typically containing 50-90% protein content by dry weight depending on processing grade, and serving as functional ingredients for emulsification, gelation, and nutritional fortification across formulated foods. Pea protein dominates current volumes given established cultivation networks in northern France and favorable allergen profiles relative to soy. Rice protein and hemp protein occupy faster-growing niches where clean-label positioning and amino acid complementarity command price premiums among organic and specialty food manufacturers. Sports nutrition and dairy alternatives concentrate the largest application-driven margin pools as consumer trial rates accelerate in urban centers.
France's national regulator ANSM oversees novel food safety assessments while EFSA provides centralized scientific opinions that shape market access timelines for innovative protein sources. The EU Green Deal's Farm to Fork strategy and France's national low-carbon labeling scheme are tightening carbon intensity thresholds for ingredient procurement, directly influencing reformulation roadmaps at food manufacturers. Stakeholders must monitor evolving protein content claim standards and traceability mandates that will determine which processing technologies and raw material sourcing models secure preferential retail placement.
Market Dynamics
France's plant protein sector is restructuring around enzymatic extraction technologies that compress processing costs while the EU Green Deal's carbon intensity thresholds force dairy alternative manufacturers to reformulate supply chains.
Growth Catalysts
- EU Green Deal Farm to Fork strategy:Mandatory carbon labeling schemes accelerate ingredient substitution away from animal-derived inputs among French food manufacturers.
- Paris-Ile-de-France food tech cluster concentration:Proximity of R&D facilities and major distributors enables rapid commercialization of novel protein isolates.
- Precision fermentation scale-up:Bioprocessing advances reduce unit economics for high-purity protein isolates destined for sports nutrition applications.
Market Restraints
- Pea protein supply concentration:Northern French cultivation networks face weather volatility that propagates through Roquette Frères' contract pricing.
- ANSM novel food assessment timelines:Extended safety evaluation periods delay market access for innovative protein sources like precision-fermented ingredients.
- Soy protein allergen substitution ceiling:Clean-label positioning limits reformulation options for manufacturers serving pediatric and hypoallergenic segments.
Strategic Opportunities
- Alsace-Lorraine organic hemp cultivation:Underdeveloped protein extraction infrastructure creates first-mover advantages for regional processing investments.
- EFSA protein content claim harmonization:Pending standardization enables premium positioning for isolates meeting 90% purity thresholds in nutraceutical channels.
- Direct-to-foodservice distribution:Bypassing traditional retail slotting fees unlocks margin recovery for artisanal dairy alternative producers in Lyon and Marseille.
Industry Challenges
- Enzymology specialist scarcity:French technical universities produce insufficient protein biochemists to staff expanding extraction facilities.
- Organic certification traceability:Multi-tier supply chains complicate documentation for hemp and rice protein sourcing under EU organic regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Plant Protein Market |
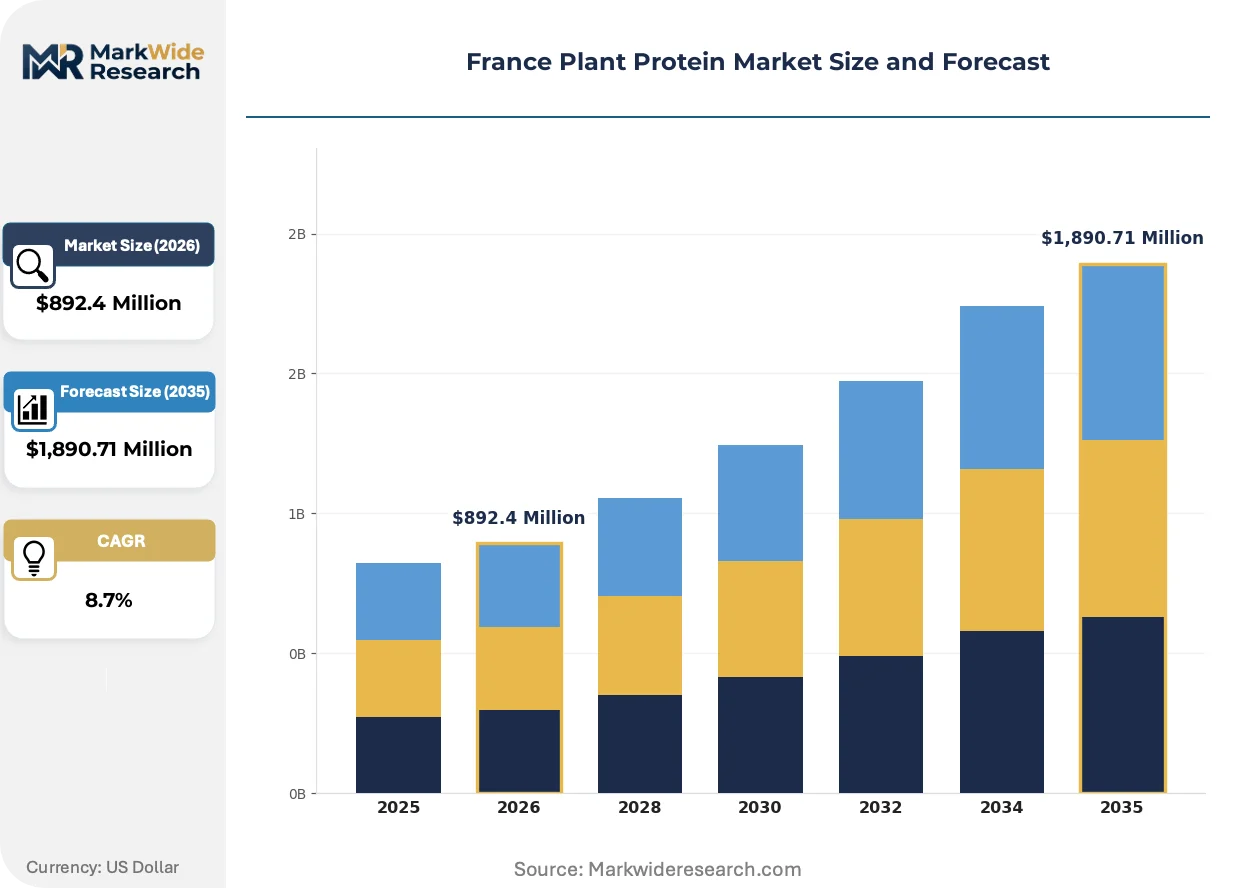
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,890.71 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pea Protein, Soy Protein, Rice Protein, Hemp Protein, Pumpkin Seed Protein Application: Sports Nutrition, Functional Foods, Infant Nutrition, Dairy Alternatives, Bakery Products Form: Powder, Concentrate, Isolate, Hydrolysate, Flakes Customer Type: Food Manufacturers, Nutraceutical Companies, Retail Chains, Catering Services, Private Labelers |
| Companies Covered | DuPont de Nemours Inc., Kerry Group Plc, Roquette Frères, Tereos, GEMEF Industries, Archer Daniels Midland Company, Ingredion Incorporated, Lantmännen, Cargill Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Plant Protein Market Shifts & Advancements
Enzymatic extraction and precision fermentation are compressing cost structures while regulatory carbon accounting reshapes procurement criteria across French food manufacturing.
Membrane filtration coupled with protease-assisted extraction is rendering obsolete conventional alkali-isoelectric precipitation for pea protein isolate production. Sports nutrition contract manufacturers in the Paris basin are adopting these systems at accelerated cadences. Legacy spray-dried concentrates face margin compression as enzymatic processes yield 15-20% higher protein recovery rates.
France's national low-carbon labeling scheme tightens Scope 3 emission disclosure requirements for ingredient suppliers. Food manufacturers must now document cultivation-to-facility carbon intensity for retail placement eligibility. Dairy alternative producers reformulating with domestic pea protein isolate secure preferential shelf positioning against imported soy alternatives.
Urban foodservice operators in Lyon, Bordeaux, and Toulouse are consolidating procurement through specialized plant protein distributors. Traditional broadline foodservice contracts fragment as chef-driven concepts demand traceable origin documentation and custom isolate blends. This channel shift concentrates volume among regional distributors with captive organic certification relationships.
France Plant Protein Market Segmentation
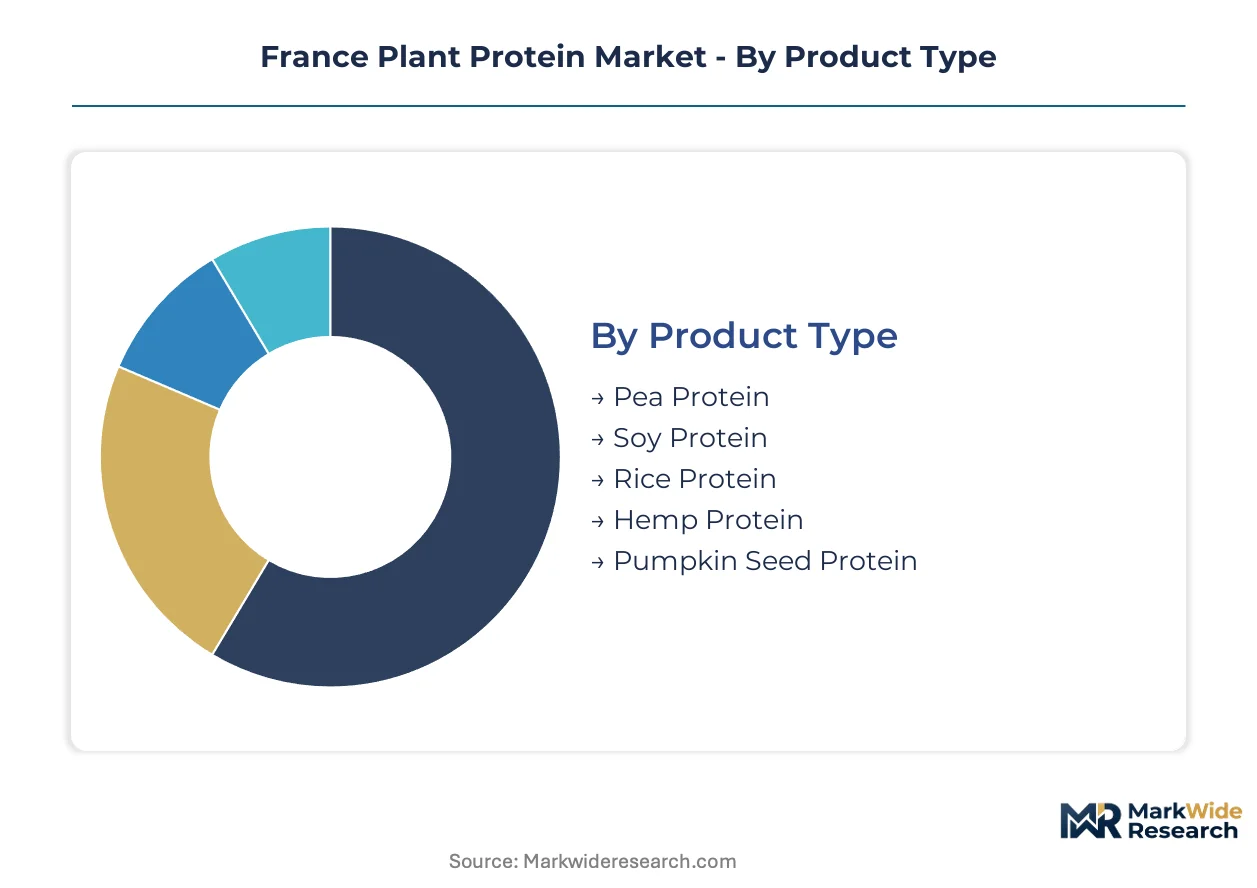
Segmentation reveals how enzymatic extraction capabilities and carbon labeling mandates reshape procurement patterns across French food manufacturing. Distinct protein grades and customer workflows determine pricing power and shelf placement eligibility.
Product Type:
Protein source selection hinges on allergen profiles, cultivation geography, and amino acid completeness for target applications.
- Pea Protein:Isolate grades achieve 80-90% protein content through wet-fractionation and membrane filtration. Northern French cultivation networks supply Roquette Frères and domestic dairy alternative manufacturers seeking low-carbon credentials under the national labeling scheme.
- Soy Protein:Concentrate and isolate forms dominate functional food applications despite allergen concerns. Import dependency creates procurement risk as EFSA novel food assessments delay domestic fermentation alternatives.
- Rice Protein:Hypoallergenic positioning commands premium pricing in pediatric and clean-label segments. Organic certification requirements complicate Asian sourcing documentation.
- Hemp Protein:Alsace-Lorraine cultivation expansion supports local extraction investments. Fiber content limits isolate purity versus competing oilseed proteins.
- Pumpkin Seed Protein:Niche positioning in sports nutrition leverages mineral density and sustainability narratives. Limited French cultivation constrains volume scalability.
The dominant share belongs to Pea Protein, while Hemp Protein is closing the gap fastest.
Application:
End-use differentiation separates high-margin nutraceutical formulations from commodity ingredient supply.
- Sports Nutrition:Protein isolates and hydrolysates with rapid amino acid absorption profiles dominate pre- and post-workout formulations. Paris-Ile-de-France contract manufacturers source enzymatically processed grades for premium positioning.
- Dairy Alternatives:Barista-grade foaming performance and neutral flavor masking determine supplier selection. Reformulation timelines accelerate as EU Green Deal carbon thresholds tighten.
- Functional Foods:Emulsification and gelation properties drive isolate specification for meat analogues and prepared meals.
- Infant Nutrition:ANSM safety assessments and hypoallergenic certification requirements limit approved protein sources.
- Bakery Products:Water-binding capacity and Maillard reaction compatibility influence concentrate versus isolate selection.
Sports Nutrition captures the highest margin pool, with Dairy Alternatives expanding most quickly.
Form:
Processing intensity determines protein content, functionality, and unit economics for ingredient buyers.
- Isolate:90%+ protein purity enables protein content claims and nutraceutical positioning. Membrane filtration and chromatographic separation add cost premium justified by EFSA claim eligibility.
- Concentrate:50-80% protein content serves cost-sensitive applications with moderate functional demands. Spray-dried legume concentrates face margin pressure from enzymatic extraction advances.
- Powder:Bulk handling and storage efficiency favor industrial food manufacturers with integrated blending operations.
- Hydrolysate:Pre-digested peptide forms accelerate absorption kinetics for clinical and sports applications.
- Flakes:Textural applications in cereal and snack manufacturing leverage visual differentiation and crunch properties.
Isolate commands premium positioning, though Concentrate retains volume leadership.
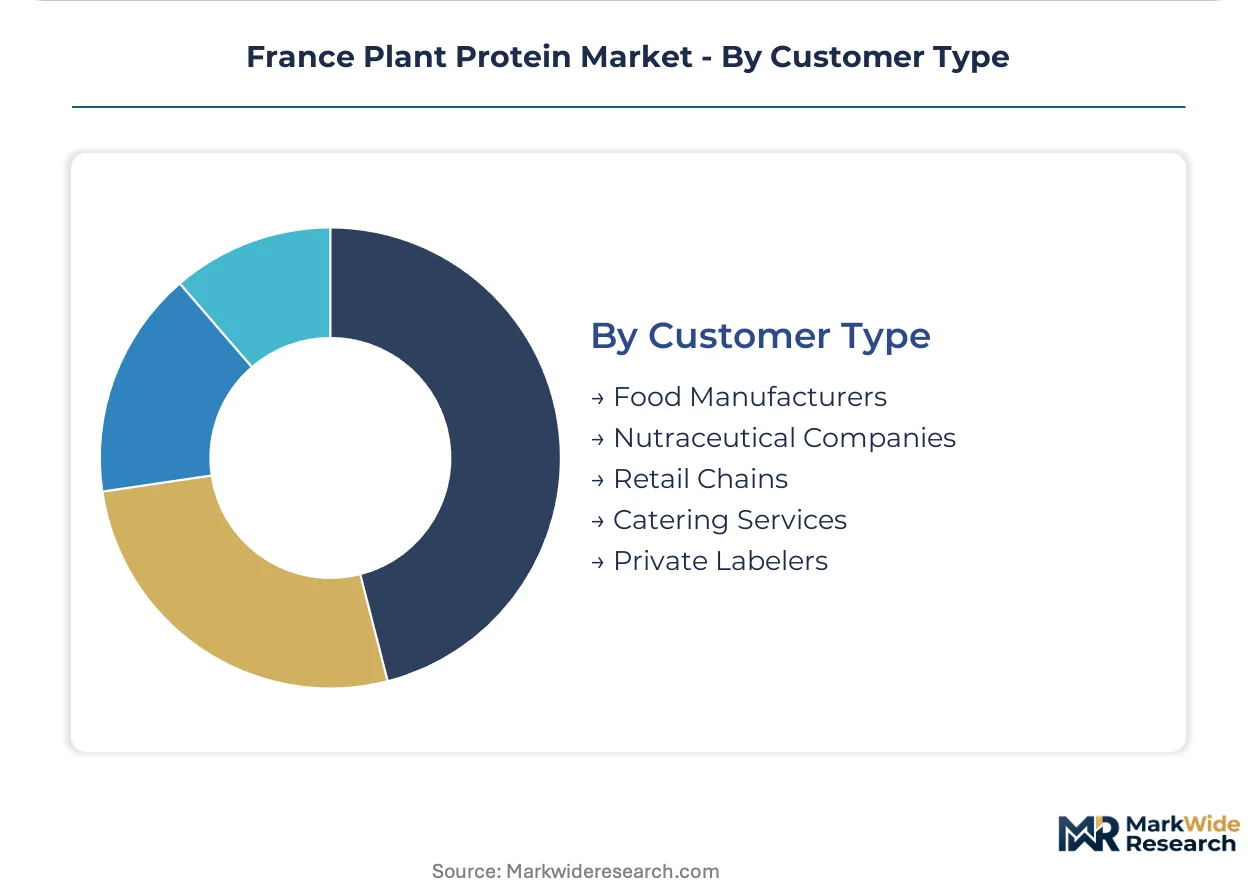
Customer Type:
Procurement sophistication and specification control vary sharply across buyer categories.
- Food Manufacturers:Integrated R&D teams specify custom protein blends with documented carbon intensity for retail placement. Direct supply contracts with Roquette Frères and Kerry Group Plc bypass distributor markups.
- Nutraceutical Companies:Purity certification and novel food safety dossiers determine supplier qualification. ANSM compliance timelines extend procurement cycles.
- Retail Chains:Private-label development teams demand traceable origin documentation and co-manufacturing flexibility.
- Catering Services:Lyon and Marseille foodservice operators consolidate through specialized distributors with captive organic certification.
- Private Labelers:Margin compression drives specification standardization and multi-source procurement strategies.
Food Manufacturers anchor demand volume, while Nutraceutical Companies generate steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France exports plant protein isolates and concentrates to neighboring EU markets and North African food manufacturers, with Rotterdam and Barcelona serving as primary distribution hubs for re-export throughout the Mediterranean basin.
Île-de-France
Paris anchors the nation's food tech R&D concentration with over forty startups developing enzymatic extraction platforms. ANSM regulatory filings cluster in this jurisdiction due to proximity to scientific advisory resources. Major distributors including Metro AG and Sysco France maintain national headquarters here, enabling rapid commercialization of novel isolates.
Hauts-de-France
Northern France's pea cultivation belt supplies Roquette Frères' primary processing facilities in Lestrem. The region's chalk soils and maritime climate support protein content levels exceeding 23% in dry pea varieties. Local agricultural cooperatives have consolidated contracting power with ingredient processors under the EU Green Deal's carbon accounting framework.
Auvergne-Rhône-Alpes
Lyon's foodservice market drives demand for barista-grade protein formulations among specialty coffee chains. The metropolitan area hosts three contract manufacturers producing sports nutrition powders for export to Swiss and Italian retail channels. Regional distributors have developed captive organic certification relationships with Alsace-Lorraine hemp growers.
Provence-Alpes-Côte d'Azur
Marseille's port infrastructure handles rice protein imports from Southeast Asian suppliers for redistribution to North African dairy alternative producers. Local foodservice operators concentrate procurement through specialized plant protein distributors rather than broadline contracts. The region's tourism economy sustains premium positioning for traceable-origin isolates.
Nouvelle-Aquitaine
Bordeaux's wine industry byproduct streams support emerging pumpkin seed protein extraction ventures targeting mineral-density positioning in sports nutrition. The regional chamber of agriculture has funded pilot facilities for oilseed protein valorization. Local organic certification bodies process documentation for export-bound hemp protein concentrates.
France Plant Protein Market Competitive Landscape
On the supply side, the industry is consolidating around integrated processors with captive raw material sourcing and proprietary extraction technologies. Three strategic archetypes dominate: legacy agribusiness conglomerates with oilseed processing heritage, specialized pea protein extractors with regional cultivation networks, and flavor-technology specialists serving branded food manufacturers. Capacity expansion and strategic partnerships represent the primary competitive vectors as participants secure preferential supply contracts with retail chains.
Within the specialized extraction tier, Roquette Frères exemplifies the regional-cultivation archetype through its decades-long presence in northern French pea processing. Kerry Group Plc occupies a position bridging flavor technology and protein systems integration. DuPont de Nemours Inc. represents the multinational diversified materials segment with nutraceutical-grade isolate positioning. These three entities anchor distinct competitive vectors rather than direct substitution relationships.
| Leading Market Players |
|---|
| DuPont de Nemours Inc. |
| Kerry Group Plc |
| Roquette Frères |
| Tereos |
| GEMEF Industries |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Lantmännen |
| Cargill Incorporated |
| Others |
Supply & Pricing Matrix
Northern French pea cultivation networks concentrate supply-side leverage, anchoring margin pools with dairy alternative manufacturers seeking carbon-labeled credentials while enzymatic extraction investments compress isolate premiums across the Paris basin.
Pricing Analysis
Enzymatic extraction versus legacy alkali-isoelectric precipitation creates the dominant technology-generation pricing gap. Three-tier pricing structure across premium isolate, standard concentrate, and economy-grade flour segments stratifies by protein purity certification under EFSA thresholds. Cost compression in concentrate tiers intensifies because membrane filtration yields 15-20% higher recovery rates. Food manufacturers exhibit lowest price sensitivity given direct supply contracts, while private-labelers face acute margin pressure driving multi-source procurement.
Supply Chain Analysis
Extended payment terms from Roquette Frères and Kerry Group Plc shape supplier-financing dynamics for mid-tier processors. Raw material sourcing draws from northern French pea cultivation, Alsace-Lorraine hemp expansion, and Southeast Asian rice protein imports. Single-source vulnerability concentrates in Roquette Frères' Lestrem processing complex. Distribution runs through specialized plant protein distributors serving Lyon and Marseille foodservice operators alongside traditional broadline channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France plant protein functions as a service-attach opportunity where custom formulation support and carbon accounting documentation expand faster than commodity isolate sales.
For Market Incumbents: Entrench position through backward integration into Alsace-Lorraine organic hemp cultivation and captive enzymology talent pipelines at French technical universities. Precision-fermented ingredient startups threaten premium isolate positioning. Certification investment in EU Green Deal carbon labeling secures retail placement preference against import competition. For New Entrants and Emerging Players: Artisanal dairy alternative producers in Lyon and Marseille represent the most penetrable entry point given fragmentation in direct-to-foodservice distribution. Regional organic hemp processing infrastructure remains underdeveloped relative to cultivation expansion. Custom isolate blending with traceable origin documentation offers differentiated go-to-market positioning. For Investors and Strategic Acquirers: Capital is best deployed toward enzymatic extraction specialists with captive northern French pea supply contracts and established ANSM regulatory dossiers. Long-term viability hinges on carbon intensity documentation capabilities tightening across the EU Green Deal implementation window. Watch EFSA protein content claim harmonization as inflection indicator for premium isolate pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Extraction Scale-Up | Membrane filtration investments at Roquette Frères compress unit economics for isolate production. |
| Backward Integration into Hemp Cultivation | Alsace-Lorraine processing facilities secure organic certification traceability for premium positioning. |
| Carbon Labeling Certification Program | EU Green Deal compliance documentation unlocks preferential retail shelf placement eligibility. |
| Direct-to-Foodservice Distribution Expansion | Lyon and Marseille specialized distributors bypass traditional retail slotting fee structures. |
| ANSM Novel Food Dossier Investment | Regulatory approval pathways for precision-fermented ingredients accelerate market access timelines. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EFSA scientific opinions, ANSM novel food registrations, and EU Green Deal implementation guidance. Primary interviews engaged extraction technology specialists at French technical universities, procurement leads at Paris-Ile-de-France dairy alternative manufacturers, regulatory affairs directors navigating novel food pathways, and category buyers at national retail chains. Secondary validation drew from customs trade data, agricultural cooperative production statistics, and foodservice distribution channel mapping. Bottom-up volume modeling triangulates against top-down market sizing across protein source and application segments.
Forecast inputs incorporate enzymatic extraction capacity expansion timelines, EU carbon labeling scheme adoption curves, and sports nutrition contract manufacturer procurement patterns. Segmentation dimensions span protein source, processing grade, end-use application, and customer procurement sophistication. CAGRs derive from modeled volume trajectories adjusted for technology substitution effects and regulatory compliance cost pass-through. Industry-specific inputs include pea protein content volatility in northern French cultivation zones and precision fermentation scale-up economics.
Macroeconomic conditions sit as an overlay; deviation in agricultural input costs, energy prices for extraction processing, or euro-zone inflation would shift the trajectory. Forecasts reflect documented assumptions regarding EFSA claim harmonization timing and EU Green Deal enforcement intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Fractionated Pulses Market
Plant Based Food
Vegan Cookies Market
Plant Based Food
Textured Pea Protein Market
Plant Based Food
Middle East and Africa Meat Substitute Market
Plant Based Food
Global Plant Based Food Market
Plant Based Food
India Plant Based Milk Market
Plant Based Food
Plant-Based Protein Food Market
Plant Based Food
Plant-Based Diet Market
Plant Based Food
Global Isolate Organic Soy Protein Market
Plant Based Food
Australia Plant Protein Market
Plant Based Food
Plant-Based Wellness Foods Market
Plant Based Food
Plant-Based Seafood Market
Plant Based Food
Vegan Pasta Market
Plant Based Food
Plant-Based Shrimp Market
Plant Based Food
Fermented Plant-Based Ingredient Market
Plant Based Food
Extruded Soy Products Market