
 Plant-Based Diet Market | 2026-2036
Plant-Based Diet Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Diet Market Insights
Clean-label certification tiers is unwinding commodity positioning across the Plant-Based Diet landscape. Beyond Meat Inc. leverages pea-protein extrusion scale to anchor North American foodservice penetration. Danone SA sustains fermentation-derived dairy alternatives leadership through European retail channel control. Nestlé S.A. competes across multiple ingredient platforms with global manufacturing footprint advantages.
A plant-based diet comprises nutritional regimes centered on foods derived from legumes, nuts, grains, and vegetables, excluding or minimizing animal products, with protein content typically benchmarked against animal-derived equivalents through amino acid scoring or digestibility-corrected amino acid scores. Industrial formulations employ high-moisture extrusion, precision fermentation, or enzymatic texturization to replicate functional properties of meat and dairy matrices for commercial food manufacturing. Meat alternatives command the largest current revenue pool, though precision fermentation dairy substitutes capture premium margin tiers as production costs decline. Online retail channels represent the fastest-growing distribution pathway, particularly for direct-to-consumer frozen foods and meal kit integrations.
The FDA governs allergen labeling and novel protein GRAS determinations in the United States, while EFSA establishes novel food safety assessments and nutrition claims standards across European markets, with both frameworks directly shaping product development timelines and cross-border market access requirements. BIS and FSSAI in India are developing plant protein fortification standards and front-of-pack labeling rules that will determine import eligibility for international suppliers. Stakeholders must monitor evolving definitions of "meat" and "dairy" in national food codes, as these terminological boundaries increasingly determine shelf placement, taxation, and advertising permissions across jurisdictions.
Market Dynamics
Clean-label certification tiers are unwinding commodity positioning across the Plant-Based Diet landscape, forcing manufacturers to restructure formulation pipelines and disclosure protocols or surrender shelf space to verified competitors.
Growth Catalysts
- EU Green Deal:Mandatory carbon footprint disclosures accelerate clean-label reformulations and drive foodservice procurement toward verified low-carbon suppliers.
- Precision fermentation:Declining production costs for dairy alternatives unlock premium margin tiers previously inaccessible to plant-based manufacturers.
- Germany:Retail shelf space expansion for meat alternatives and continental Europe's highest consumer trial rates concentrate demand pull in this market.
Market Restraints
- Pea protein supply concentration:North American ingredient sourcing creates vulnerability to crop yield volatility and price spikes.
- High-moisture extrusion capex:Specialized equipment requirements limit manufacturing scale-up for mid-tier producers.
- GRAS determination timelines:FDA novel protein safety assessments extend product development cycles and delay market entry.
Strategic Opportunities
- Direct-to-consumer frozen foods:Online retail channel growth enables margin capture bypassing traditional wholesale distribution.
- Meal kit integrations:Subscription-based culinary education accelerates trial conversion among hesitant consumer segments.
- Indian fortification standards:BIS and FSSAI plant protein rules create first-mover advantage for compliant international suppliers.
Industry Challenges
- Enzymatic texturization expertise:Scarce technical talent for replicating meat and dairy functional properties constrains R&D throughput.
- Novel food safety assessments:EFSA certification timelines create competitive lag for European market entrants versus established players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Diet Market |
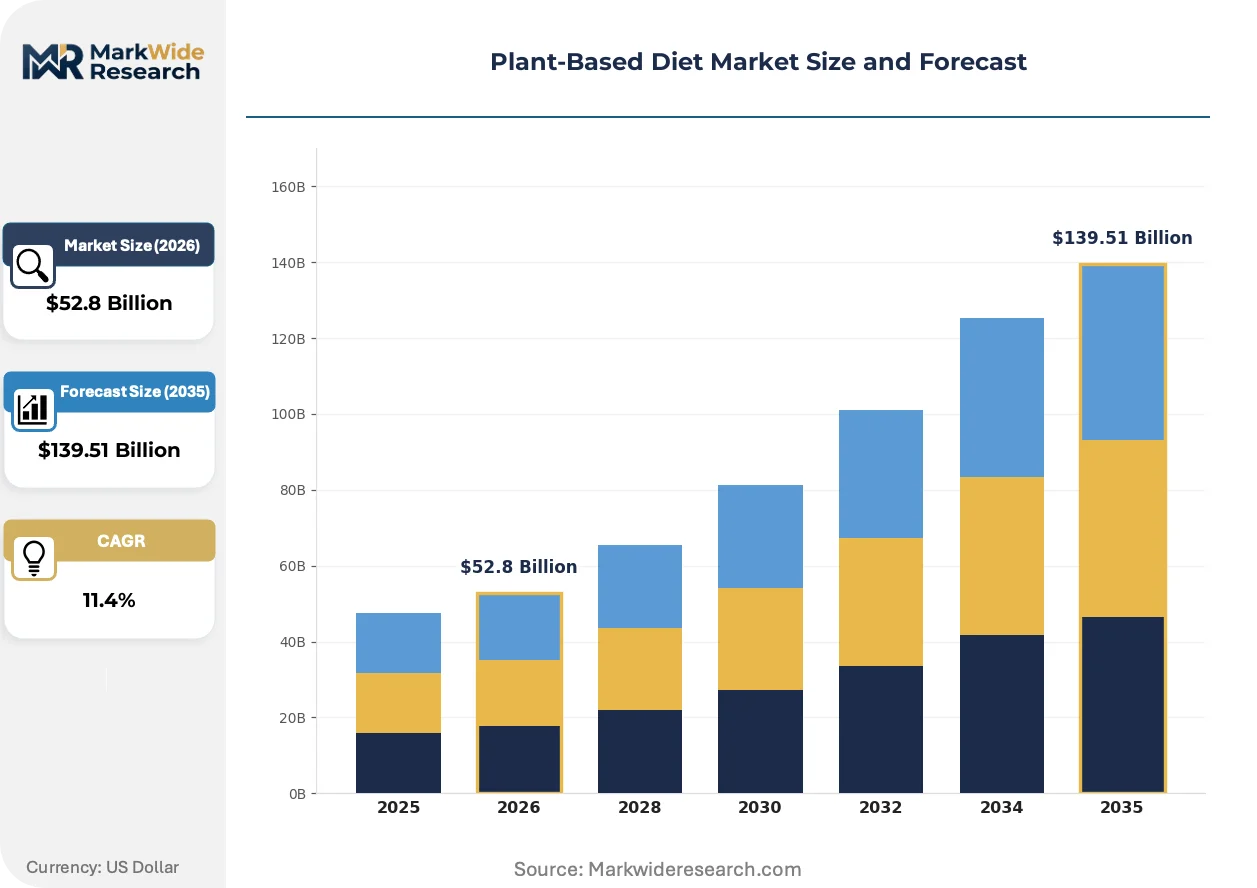
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $139.51 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meat Alternatives, Dairy Substitutes, Plant-Based Snacks, Frozen Foods Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Specialty Stores End User: Households, Restaurants, Cafes, Meal Kit Services Ingredient Source: Legumes, Nuts, Grains, Vegetables |
| Companies Covered | Beyond Meat Inc., Impossible Foods Inc., Danone SA, Nestlé S.A., Amy's Kitchen Inc., Atlantic Natural Foods LLC, Conagra Brands Inc., Nestle S.A., Califia Farms LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Diet Market Trends and Innovations
Formulation science and regulatory disclosure requirements are actively restructuring competitive advantage in plant-based nutrition, separating verified clean-label producers from commodity-positioned alternatives.
Precision fermentation for dairy protein analogs is bifurcating the alternative dairy segment. Foodservice operators in premium hospitality and specialty coffee chains adopt these ingredients for functional performance in foaming and melting applications. The technology is bifurcating margin structures, creating distinct premium tiers that commodity soy and oat bases cannot access regardless of price competition.
The EU F-Gas Regulation and accompanying CSRD disclosure mandates force refrigeration-dependent supply chains to document and reduce coolant emissions. Cold-chain logistics providers serving frozen plant-based categories must retrofit equipment or surrender contracts to compliant competitors. German retail chains lead implementation, using disclosure requirements as procurement filters for private-label plant-based assortments.
Restaurant chains now demand dedicated plant-based menu sections as standard offerings rather than experimental additions. Culinary procurement teams specify amino acid scoring benchmarks and digestibility-corrected amino acid scores in supplier contracts. North American fast-casual operators and European contract catering services drive this specification tightening, rejecting formulations that fail documented protein quality thresholds.
Plant-Based Diet Market Segmentation
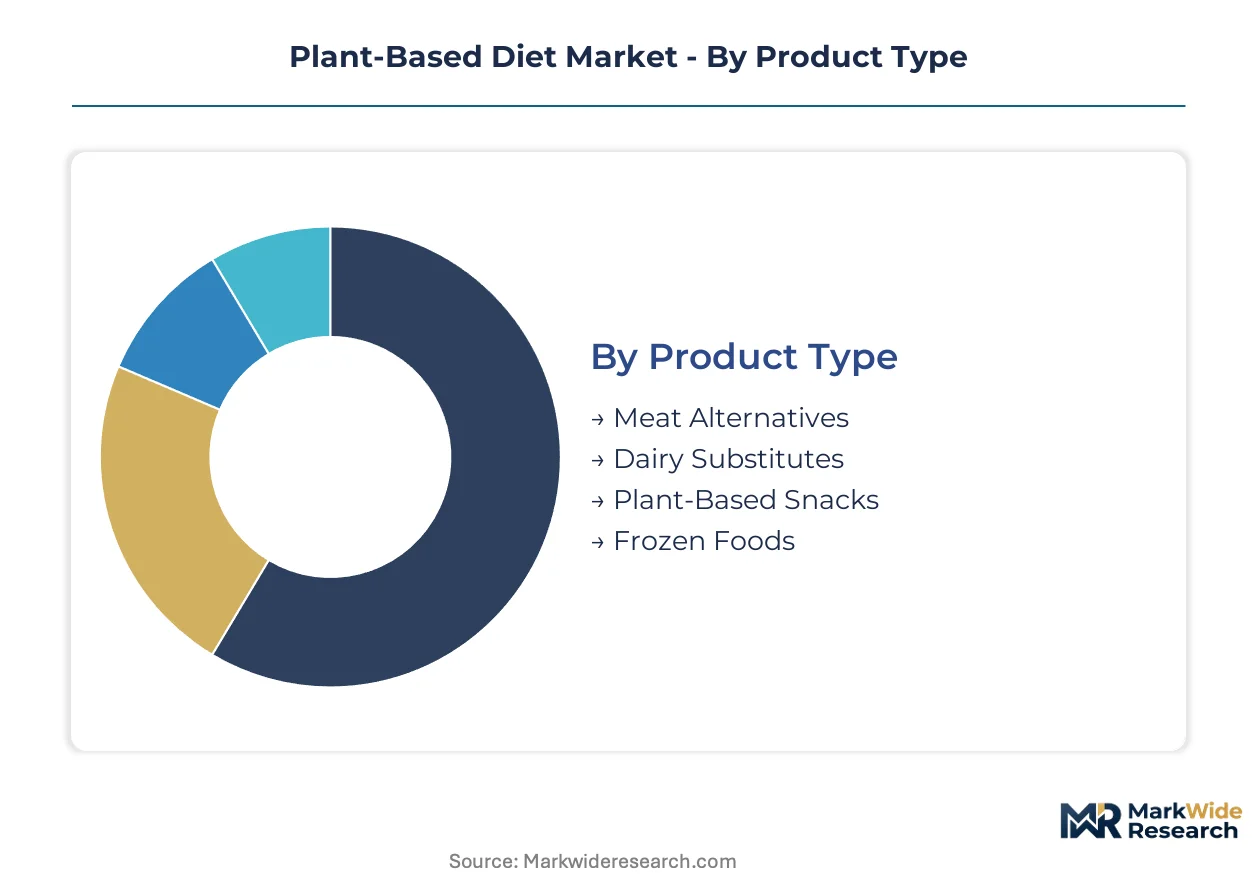
Segmentation in plant-based nutrition separates commodity-positioned offerings from verified clean-label tiers, determining which formulations capture retail shelf space and foodservice procurement contracts. Distinct protein quality benchmarks, distribution economics, and end-user specification requirements create divergent margin structures across each dimension.
Product Type:
Meat alternatives face the most intense substitution pressure from precision fermentation dairy and whole-food protein solutions, forcing continuous texturization innovation to defend positioning.
- Meat Alternatives:High-moisture extrusion and enzymatic texturization replicate myofibrillar protein structures for ground and whole-cut applications. Demand concentrates in German retail and North American fast-casual foodservice, where procurement teams specify amino acid scoring benchmarks in supplier contracts. Pea-protein supply concentration and extrusion equipment capex constrain mid-tier manufacturer scale-up.
- Dairy Substitutes:Precision fermentation-derived proteins unlock foaming and melting performance unattainable by commodity oat or soy bases. Specialty coffee chains and premium hospitality operators in Europe adopt these ingredients for functional superiority, creating premium margin tiers separated from price-competitive alternatives.
- Plant-Based Snacks:Extruded and puffed formats target convenience-oriented consumption occasions with shorter ingredient lists.
- Frozen Foods:Direct-to-consumer and meal kit channels drive fastest expansion, bypassing traditional wholesale distribution economics.
Meat alternatives anchor the volume base while precision fermentation dairy substitutes gain share at the steepest rate.
Distribution Channel:
Channel economics stratify around cold-chain infrastructure requirements and disclosure verification burdens, with carbon footprint documentation becoming a procurement filter.
- Supermarkets:German retail chains lead private-label assortment expansion, using EU F-Gas Regulation compliance and CSRD disclosure mandates as vendor selection criteria. Shelf space allocation for meat alternatives has expanded substantially, concentrating continental Europe's highest consumer trial rates in this channel.
- Online Retail:Frozen foods and meal kit integrations expand most quickly through subscription-based culinary education models. Direct-to-consumer distribution enables margin capture unavailable through wholesale intermediaries, particularly for temperature-controlled products requiring specialized logistics.
- Health Food Stores:Clean-label certification and organic positioning command premium pricing among wellness-focused consumers.
- Specialty Stores:Curated assortments emphasize regional ingredient provenance and artisanal production methods.
Supermarkets dominate current revenue contribution while online retail climbs the fastest.
End User:
Specification tightening separates institutional procurement from household purchasing, with foodservice operators demanding documented protein quality thresholds absent in consumer markets.
- Restaurants:North American and European chains now require dedicated plant-based menu sections as standard offerings rather than experimental additions. Culinary procurement teams specify digestibility-corrected amino acid scores and amino acid scoring benchmarks, rejecting formulations failing documented thresholds.
- Meal Kit Services:Subscription models accelerate trial conversion among hesitant consumer segments through controlled culinary education. Integration with precision fermentation ingredients and high-protein formulations targets nutrition-conscious subscribers willing to pay premium positioning.
- Households:Retail purchasing decisions increasingly reference front-of-pack labeling and certification marks.
- Cafes:Beverage-focused applications prioritize foaming performance and clean flavor profiles.
Restaurants anchor foodservice volume while meal kit services expand most quickly.
Ingredient Source:
Supply concentration and crop yield volatility create sourcing vulnerabilities that differentiate vertically integrated processors from commodity-dependent competitors.
- Legumes:Pea protein dominates extrusion-scale manufacturing for meat alternatives, with North American sourcing concentration creating price spike vulnerability. Beyond Meat anchors foodservice penetration through captive supply agreements and proprietary extrusion scale.
- Nuts:Almond and cashew bases command premium positioning in dairy substitutes, though water intensity and allergen labeling requirements constrain formulation flexibility. EFSA and FDA allergen protocols directly shape product development timelines for nut-containing formulations.
- Grains:Oat protein provides cost-competitive dairy alternative bases with established consumer familiarity.
- Vegetables:Whole-food and minimally processed positioning targets clean-label certification tiers.
Legumes anchor industrial formulation scale while nuts capture premium margin tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision fermentation-derived dairy proteins to specialty coffee chains across the Netherlands and Scandinavia, while US pea-protein extruders supply North American fast-casual operators expanding dedicated plant-based menu sections.
United States
Fast-casual procurement teams specify digestibility-corrected amino acid scores in supplier contracts, rejecting formulations below documented thresholds. The FDA governs novel protein GRAS determinations, extending product development cycles for emerging entrants. California's Bay Area hosts precision fermentation startups targeting premium hospitality applications with functional foaming performance.
Germany
Retail chains have expanded meat alternative shelf space substantially, capturing continental Europe's highest consumer trial rates. The EU F-Gas Regulation and CSRD disclosure mandates force cold-chain logistics providers to document coolant emissions or surrender contracts. Berlin-based private-label manufacturers lead clean-label certification adoption for supermarket assortments.
Netherlands
Specialty coffee chains source precision fermentation dairy alternatives for functional superiority in foaming applications unavailable to commodity oat bases. EFSA novel food safety assessments shape product development timelines for European market entrants. The Randstad logistics cluster retrofits refrigeration equipment to comply with EU Green Deal procurement filters.
United Kingdom
Meal kit subscription services accelerate trial conversion among hesitant consumer segments through controlled culinary education. EFSA nutrition claims standards influence cross-border product positioning for suppliers accessing continental markets. London's foodservice procurement hubs demand dedicated plant-based menu sections as standard restaurant offerings.
India
Plant protein fortification standards under BIS and FSSAI development create first-mover positioning for compliant international suppliers. Front-of-pack labeling rules under formulation determine import eligibility and retail placement permissions. Maharashtra's Mumbai-Pune industrial corridor concentrates domestic extrusion capacity for legume-based meat alternatives.
Plant-Based Diet Market Competitive Landscape
Listed leaders compete with private specialists across certification tier access, with publicly traded entities leveraging capital markets for extrusion scale while venture-backed fermentation startups capture premium margin pools. The vendor base stratifies around three archetypes: pea-protein extruders anchoring foodservice volume, precision fermentation operators unlocking functional dairy performance, and diversified conglomerates spanning multiple ingredient platforms. Consolidation pressure concentrates among mid-tier extrusion-dependent manufacturers facing equipment capex barriers. Dominant competitive moves include backward integration into captive pea-protein supply and strategic partnerships with cold-chain logistics providers for direct-to-consumer frozen distribution.
Within the fermentation-specialist tier, Beyond Meat Inc. and Danone SA exemplify divergent platform strategies, with the former representing North American extrusion-scale penetration and the latter anchoring European fermentation-derived dairy leadership through retail channel control. Nestlé S.A. occupies a diversified position spanning multiple ingredient technologies and global manufacturing footprints.
| Leading Market Players |
|---|
| Beyond Meat Inc. |
| Impossible Foods Inc. |
| Danone SA |
| Nestlé S.A. |
| Amy's Kitchen Inc. |
| Atlantic Natural Foods LLC |
| Conagra Brands Inc. |
| Califia Farms LLC |
Pricing and Supply Chain Analysis
Extrusion-scale manufacturing in North America and fermentation capacity buildouts in Europe anchor divergent cost structures that stratify pricing power across ingredient platforms. Pea-protein processors with captive supply agreements command defensible price floors against commodity-dependent competitors facing yield volatility, while precision fermentation operators capture premium tiers through functional performance gaps.
Pricing Analysis
Current-generation high-moisture extrusion, prior-generation commodity soy isolates, and next-generation precision fermentation proteins occupy distinct pricing strata. Three-tier pricing structure across premium, standard, and economy levels separates functional-performance-verified fermentation dairy from extruded meat alternatives and commodity grain bases. Cost compression in standard-tier extruded products is intensifying because of pea-protein supply concentration and equipment capex barriers. Foodservice procurement teams exhibit lowest price sensitivity for precision fermentation ingredients with documented foaming performance, while retail private-label buyers drive hardest bargain on undifferentiated extruded formats.
Supply Chain Analysis
Container availability constraints on North Atlantic trade lanes and EU F-Gas Regulation retrofit requirements inflate inbound logistics costs for temperature-controlled plant-based frozen distribution. Manufacturing concentration in the United States, Germany, and the Netherlands feeds continental supply networks with divergent regulatory compliance burdens. Raw material dependencies on Canadian yellow pea crops, European fermentation feedstocks, and Indian mung bean supplies create multi-source anchoring. Single-source vulnerability in North American pea-protein extraction capacity exposes mid-tier manufacturers to price spike risk. Distribution runs through cold-chain logistics providers with documented carbon disclosure compliance, particularly for German retail and North American fast-casual channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant-based nutrition sits in early-cycle expansion, with EU Green Deal procurement mandates and precision fermentation cost curves creating sustained adoption tailwinds across foodservice and retail channels.
For Market Incumbents: Consolidate extrusion-scale capacity through selective acquisition of mid-tier manufacturers facing equipment capex barriers, and deepen backward integration into captive pea-protein supply to defend margin position against crop yield volatility. Certification investment in EU F-Gas Regulation compliance and CSRD disclosure protocols secures German retail shelf space against verified competitors.
For New Entrants and Emerging Players: Direct-to-consumer frozen fulfillment infrastructure represents an under-served service layer where incumbents rely on third-party logistics with limited temperature-control specialization. Target meal kit subscription channels with precision fermentation ingredient integration, leveraging culinary education content to accelerate trial conversion among hesitant consumer segments. Go-to-market through specialty coffee chain partnerships bypasses supermarket slotting fee barriers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision fermentation specialists with demonstrated functional performance in foaming and melting applications over extrusion-dependent commodity processors. Long-term viability across the projection horizon rests on regulatory clearance velocity for novel proteins and carbon disclosure compliance infrastructure. Acquisition target archetype: fermentation operators with EFSA novel food safety assessments in progress. Signal to watch: GRAS determination timeline compression for emerging protein sources.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Unlocks premium margin tiers in specialty coffee and hospitality channels previously inaccessible to commodity bases. |
| Backward Integration into Pea Protein | Captive supply agreements insulate against North American crop yield volatility and price spikes. |
| EU F-Gas Compliance Certification | Documentation of coolant emissions secures German retail procurement contracts and private-label placement. |
| Direct-to-Consumer Frozen Launch | Bypasses wholesale distribution economics and captures margin through temperature-controlled subscription logistics. |
| Meal Kit Platform Partnership | Culinary education integration accelerates trial conversion among nutrition-conscious subscribers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with foodservice procurement directors, retail category managers, precision fermentation R&D leads, cold-chain logistics operators, and regulatory affairs specialists at EFSA and FDA. Secondary validation drew from EU F-Gas Regulation implementation filings, FDA GRAS determination dockets, German retail audit data, and SEC disclosures from listed plant-based protein manufacturers. Bottom-up volume modeling and top-down value triangulation were applied across all segmentation dimensions.
Across the analysis window, forecasts were derived from analytical frameworks modeling product type, distribution channel, end-user specification tier, and ingredient source platform. CAGRs were computed from annualized growth trajectory fitting across the projection horizon. Industry-specific inputs included amino acid scoring benchmark adoption curves, precision fermentation production cost decline rates, and EU Green Deal procurement mandate implementation timelines.
Underlying assumptions cover sustained EU regulatory enforcement, stable pea-protein crop yields, and precision fermentation scale-up execution, with deviation risk concentrated in FDA novel protein approval delays and cold-chain logistics capacity constraints. Recalibration cycles align with material shifts in EFSA safety assessment timelines and German retail private-label expansion rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Vegan Bacon Market
Plant Based Food
Plant-Based Margarine Market
Plant Based Food
Vegan Food Market
Plant Based Food
South America Rice Protein Market
Plant Based Food
Plant-Based Milk Alternatives Market
Plant Based Food
Europe Textured Vegetable Protein Market
Plant Based Food
Indonesia Plant-Based Food and Beverages Market
Plant Based Food
China Rice Protein Market
Plant Based Food
Asia-Pacific Plant-Based Seafood Market
Plant Based Food
Extruded Soy Products Market
Plant Based Food
Vegan Marshmallows Market
Plant Based Food
North America Rice Protein Market
Plant Based Food
Insoluble Pea Protein Market
Plant Based Food
Vegan Meals Market
Plant Based Food
Plant-Based Food Ingredients Market
Plant Based Food
Plant-Based Flour Market