
 Oat Protein Market | 2026-2036
Oat Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Oat Protein Market Outlook
Ingredient distribution through legacy foodservice brokers is fragmenting as direct procurement from oat processors expands. Cargill Inc. leverages its global grain handling infrastructure to secure raw oat supply chains. ADM sustains North American processing dominance through wet-milling investments. Oatly AB competes via captive demand from its own beverage and dairy-alternative product lines.
Oat protein refers to protein fractions extracted from Avena sativa, typically containing globulin and avenin fractions with protein content ranging from 50% in concentrates to 90% in isolates, produced via aqueous extraction or dry fractionation for emulsification, foaming, and nutritional fortification in food systems. Application in protein supplements leads current volume due to sports nutrition demand, while meat alternatives represent the fastest-expanding segment as extruded oat protein improves textural fidelity in plant-based formulations. End-user demand from vegan consumers anchors premium pricing, though food manufacturers drive bulk volume through industrial-scale procurement.
EU Green Deal sustainability criteria and REACH chemical safety standards shape ingredient sourcing requirements for European processors, while FDA GRAS determinations govern novel protein ingredient approvals in the United States. Stakeholders must monitor evolving protein content labeling thresholds and carbon intensity reporting rules that will determine which oat fractionation technologies achieve scalable regulatory compliance.
Market Dynamics
Direct procurement from oat processors is fragmenting legacy foodservice broker networks across Central Europe, compressing margin capture for intermediaries while concentrating supply relationships around processing clusters in Germany and Sweden.
Growth Catalysts
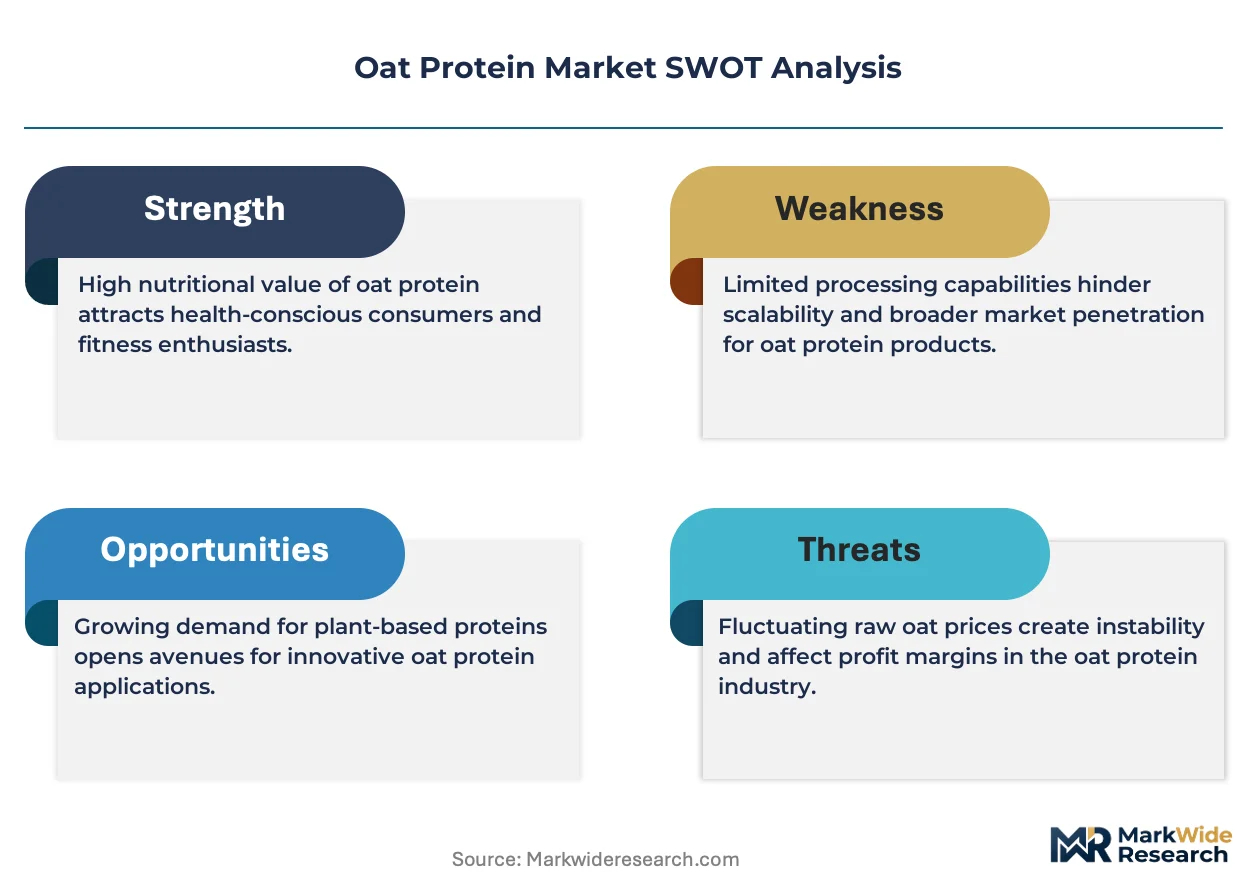
- EU Green Deal sustainability criteria:Mandatory carbon intensity reporting for crop processing is redirecting procurement toward oat fractionation facilities with verified low-emission operations, favoring Nordic and Baltic suppliers with integrated renewable energy.
- Sports nutrition formulation demand:Clean-label protein fortification requirements from athletic supplement brands are pulling oat protein concentrates into pre-workout and recovery product lines, displacing soy and pea alternatives in premium positioning.
- Wet-milling technology advancement:Improved aqueous extraction yields at 90% protein isolate purity are opening meat alternative applications where textural fidelity previously required animal or soy protein bases.
Market Restraints
- Oat raw material price volatility:Weather-driven yield fluctuations in Nordic growing regions create input cost instability that fractionation plants cannot fully hedge through forward contracts.
- REACH chemical safety compliance:ECHA registration requirements for novel protein isolates impose multi-year approval timelines and testing costs that deter mid-scale processors from isolate production.
- Pea and fava protein substitution:Established supply chains for legume proteins in meat alternatives and dairy alternatives limit oat protein penetration in price-sensitive industrial formulations.
Strategic Opportunities
- CSRD corporate sustainability reporting:Mandatory Scope 3 emissions disclosure for EU food manufacturers is creating preferential sourcing status for oat protein with certified low-carbon cultivation and processing.
- Pediatric and geriatric nutrition:Hypoallergenic protein positioning is opening medical and clinical nutrition applications where soy and dairy proteins carry allergen labeling constraints.
- Direct-to-manufacturer digital platforms:B2B ingredient marketplaces are collapsing traditional broker layers, enabling oat processors to capture margin and access formulation data from food manufacturers.
Industry Challenges
- Protein content standardization gaps:Absence of harmonized ISO methods for oat protein quantification creates contract disputes between processors and buyers over concentrate versus isolate grading.
- Extrusion technology retrofit costs:Meat alternative manufacturers face capital expenditure requirements to adapt twin-screw extruders optimized for soy or wheat gluten to oat protein rheology.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oat Protein Market |
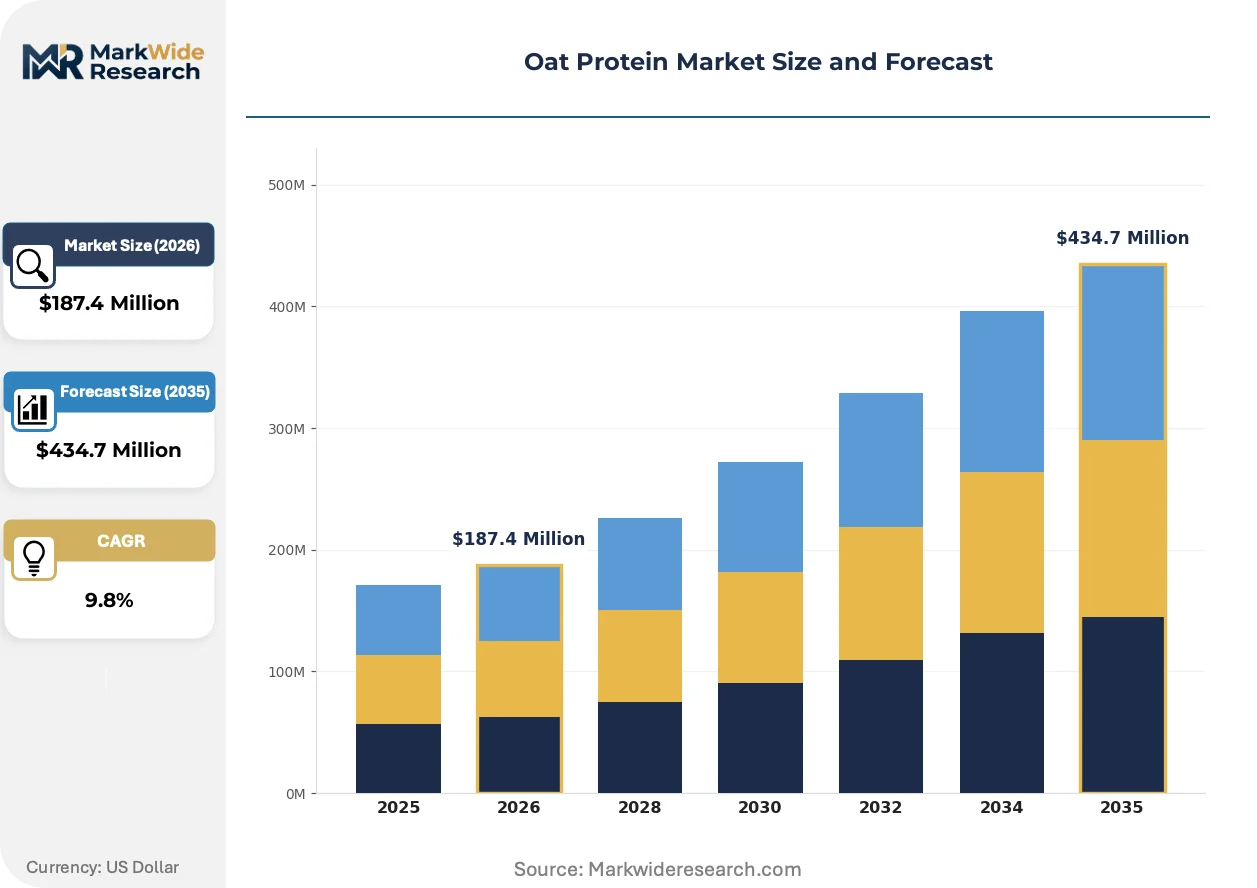
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $434.7 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrate, Isolate, Flour, Whole Oat Application: Protein Supplements, Bakery Products, Meat Alternatives, Snacks End User: Sports Nutrition, Health-Conscious Consumers, Vegan Consumers, Food Manufacturers Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops |
| Companies Covered | Cargill Inc., ADM, Tate & Lyle PLC, Roquette Freres, Lantmännen, Kerry Group PLC, Ingredion Incorporated, Oatly AB, Avena Foods Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oat Protein Market Strategic Shifts
Fractionation technology advances and regulatory disclosure mandates are compressing traditional supply chain structures while opening new application categories for oat protein isolates and concentrates.
Dry fractionation using air classification and electrostatic separation is rendering obsolete energy-intensive wet-milling approaches for 50-70% protein concentrate production. Food manufacturers in Germany and the Netherlands are adopting these systems at pilot scale, cutting water use and energy consumption while maintaining functional properties for bakery and beverage applications. This shift is compressing capital barriers for regional oat processors seeking to enter protein ingredient markets.
REACH chemical safety standards and impending EFSA novel food determinations for high-purity isolates are extending approval timelines for new oat protein suppliers. European processors must demonstrate protein digestibility and amino acid bioavailability data that legume protein incumbents established years earlier. Meat alternative manufacturers are responding by locking multi-year supply agreements with approved suppliers, freezing out newer entrants until regulatory clarity emerges.
Ingredient buyers are consolidating vendor relationships around processors with integrated sustainability certification and carbon accounting capabilities. Food manufacturers in Scandinavia are replacing spot purchasing with annual contracts tied to verified Scope 3 emissions reductions, directing volume toward oat processors with farm-level traceability systems. This concentration is most visible in Sweden and Denmark, where dairy alternative and bakery brands have eliminated broker intermediaries entirely.
Oat Protein Market Segmentation
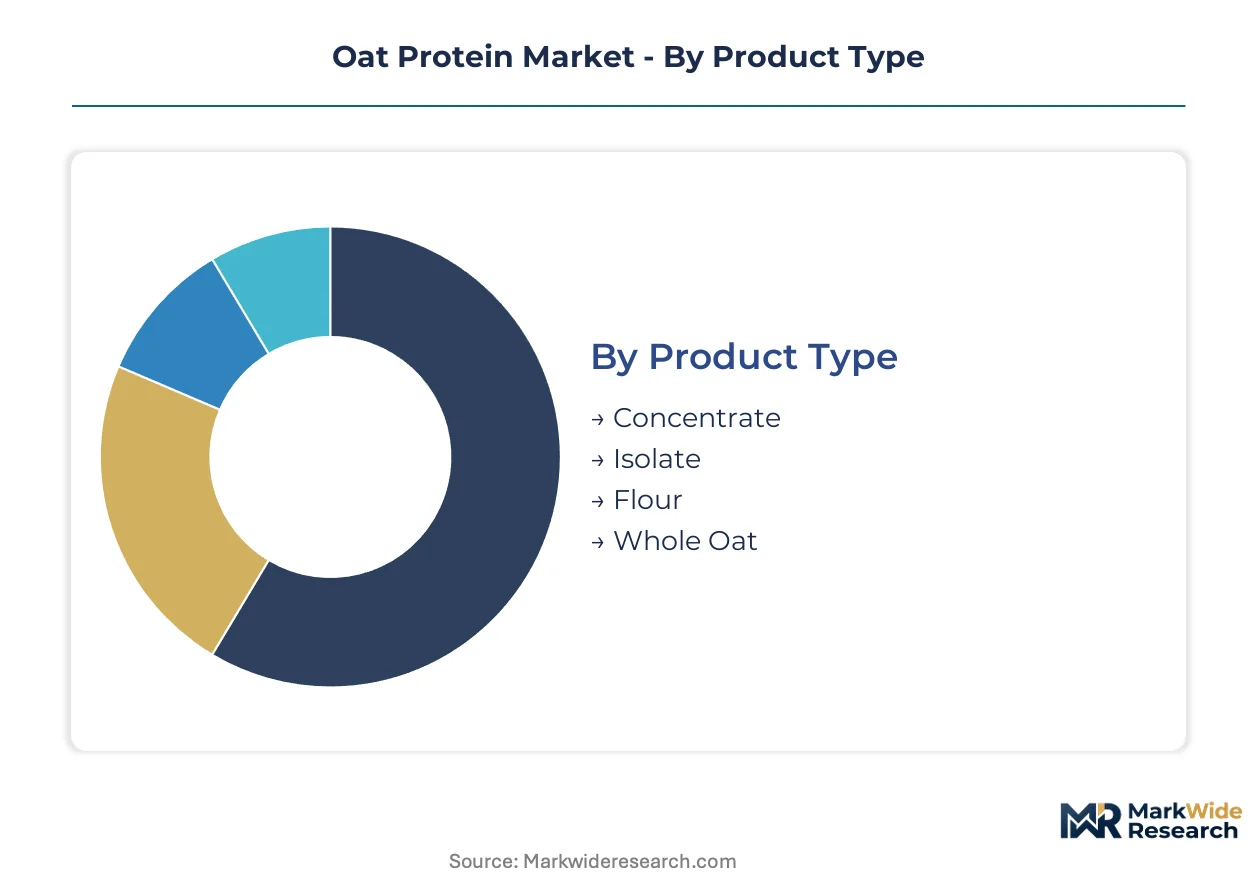
Oat protein segmentation reflects divergent technical specifications and procurement cycles across food manufacturing tiers. Concentrates and isolates command longer development timelines with formulation partners, while whole oat and flour segments turn inventory rapidly through commodity channels.
Product Type:
Cycle times vary dramatically: isolates require 18-24 month qualification periods with meat alternative developers, while whole oat protein moves through bakery supply chains in quarterly replenishment cycles.
- Concentrate:Protein content ranges from 50-70% with retained fiber fractions that enhance water-binding in extruded applications. Sports nutrition brands in Germany specify concentrates for clean-label protein bars where cost positioning must compete with pea isolates.
- Isolate:Aqueous extraction yields 90% protein purity with minimal off-flavor carryover, enabling neutral taste profiles in dairy alternatives. Nordic processors with integrated wet-milling capacity capture premium pricing from meat alternative manufacturers seeking soy replacement.
- Flour:Ground oat fractions with 15-20% native protein serve rapid-turn bakery applications.
- Whole Oat:Minimally processed groats retain complete nutritional matrices for clinical nutrition and infant formula.
Concentrate anchors the volume base while isolate gains share at the steepest rate.
Application:
Cost tiers separate commodity bakery incorporation from premium meat alternative texturization, with formulation complexity driving margin stratification across end-uses.
- Protein Supplements:Pre-workout and recovery formulations demand 80%+ protein purity with instant dispersibility. Athletic nutrition brands source isolates directly from Swedish processors, bypassing legacy ingredient distributors.
- Meat Alternatives:Extruded oat protein achieves fibrous textures through high-moisture extrusion, displacing soy in European clean-label positioning. Dutch and German plant-based meat developers lock multi-year supply agreements to secure fractionation capacity.
- Bakery Products:Concentrates fortify bread and pastry matrices without gluten network disruption.
- Snacks:Puffed and extruded formats utilize lower-purity fractions for nutritional claim compliance.
Protein supplements dominate current procurement volume while meat alternatives expand most quickly.
End User:
Customer type determines specification stringency: food manufacturers enforce batch-to-batch consistency protocols that vegan consumers bypass through direct-to-brand purchasing.
- Sports Nutrition:Formulation houses demand certificate of analysis documentation for every lot, with amino acid profiling and heavy metal screening. Pre-workout brands specify Nordic-sourced isolates for leucine content optimization.
- Food Manufacturers:Industrial bakeries and meat alternative producers negotiate annual contracts with price-volume bands tied to carbon intensity reporting. German dairy alternative processors integrate oat protein into beverage stabilization systems.
- Vegan Consumers:Direct purchasing through brand websites values ethical sourcing certifications over technical specifications.
- Health-Conscious Consumers:Functional food buyers prioritize beta-glucan retention alongside protein content.
Food manufacturers anchor the volume base while sports nutrition gains share at the steepest rate.
Distribution Channel:
Supply concentration favors direct procurement: online platforms and specialty shops collapse traditional broker layers that supermarkets still maintain for mass-market penetration.
- Online Retail:B2B ingredient marketplaces enable oat processors to capture margin and access formulation data from food manufacturers. Direct-to-manufacturer platforms eliminate 15-20% distributor markups in Central European transactions.
- Health Food Stores:Regional chains in Scandinavia stock branded oat protein isolates for home baking and smoothie applications, with staff training driving premium positioning.
- Supermarkets:Mass retail channels move lower-margin flour and concentrate formats through private label programs.
- Specialty Shops:Boutique nutrition retailers serve clinical and athletic segments with customized blending services.
Supermarkets anchor the volume base while online retail gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's grain handling infrastructure anchors Central European oat protein distribution, connecting Nordic cultivation zones to German processing clusters and onward to continental food manufacturers.
Germany
Sports nutrition brands in Bavaria and North Rhine-Westphalia source oat protein concentrates for clean-label protein bars. The EU Green Deal's carbon intensity reporting requirements favor processors with renewable energy integration. Münsterland's oat milling cluster serves as the primary fractionation hub for Central European meat alternative manufacturers.
Sweden
Oatly AB's captive demand from beverage lines drives isolate consumption in Skåne County. REACH compliance timelines extend approval periods for novel protein suppliers. Lund's food technology corridor hosts wet-milling facilities supplying 90% purity isolates to Dutch plant-based meat developers.
Netherlands
High-moisture extrusion trials in Wageningen advance oat protein texturization for meat alternatives. EFSA novel food determinations govern isolate approval pathways. The Food Valley cluster coordinates formulation partnerships between Swedish processors and Dutch plant-based meat brands.
United States
FDA GRAS determinations shape novel protein ingredient approvals for sports nutrition applications. Wet-milling investments in the Midwest sustain North American processing capacity. Minnesota's grain handling infrastructure connects Prairie oat cultivation to ingredient distribution networks.
Denmark
Dairy alternative brands in Copenhagen eliminate broker intermediaries through direct processor procurement. CSRD Scope 3 disclosure mandates drive annual contracting with carbon-certified suppliers. Arla Foods' innovation campus tests oat protein stabilization for beverage applications.
Oat Protein Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream. The oat protein market structures around three tiers: global grain traders with fractionation capacity, regional oat processors with wet-milling specialization, and captive demand players with integrated product lines. Strategic archetypes include infrastructure-leveraged traders, Nordic pure-play processors, and brand-integrated verticals. Dominant competitive moves encompass direct procurement platform development and sustainability certification stacking.
Among North American grain handlers, Cargill Inc. and ADM exemplify infrastructure-leveraged positioning through global supply chain control. Oatly AB represents the brand-integrated archetype, anchoring captive demand through proprietary beverage and dairy-alternative product lines. These three occupy distinct competitive spaces: traders securing raw material flows, processors commanding fractionation technology, and verticals internalizing demand.
| Leading Market Players |
|---|
| Cargill Inc. |
| ADM |
| Tate & Lyle PLC |
| Roquette Freres |
| Lantmännen |
| Kerry Group PLC |
| Ingredion Incorporated |
| Oatly AB |
| Avena Foods Limited |
| Others |
Value Chain & Pricing Dynamics
The Port of Hamburg's grain handling corridors anchor Central European oat protein distribution, with freight cost fluctuations compressing margins for Nordic processors while amplifying price differentiation between carbon-certified isolates and commodity-grade concentrates. Supply concentration around German and Swedish fractionation clusters enables volume-based tiering that rewards annual contracting over spot purchasing.
Pricing Analysis
Volume-discount tiering structures separate annual contract holders from spot-market buyers, with three-tier pricing stratification across premium isolates, standard concentrates, and economy-grade flour fractions. Price differentiation hinges on EU Green Deal carbon certification status and wet-milling purity grades, with REACH-compliant isolates commanding substantial premiums. Pricing pressure intensifies from pea protein substitution in meat alternatives, squeezing oat concentrate positioning. Food manufacturers exhibit highest price sensitivity through formula-flexible procurement, while sports nutrition brands absorb premiums for leucine-optimized Nordic isolates.
Supply Chain Analysis
Export-control regimes governing novel food approvals under EFSA and FDA GRAS pathways restrict isolate flows from unqualified suppliers, lengthening qualification timelines for new entrants. Geographic supply concentrates in Sweden, Germany, and the Netherlands, with Nordic cultivation zones feeding Central European fractionation hubs. Raw material dependencies center on Avena sativa cultivation in Baltic and Prairie growing regions, aqueous extraction chemicals, and renewable energy inputs for low-carbon processing. Single-source vulnerability persists around wet-milling equipment suppliers. Distribution runs through direct-procurement platforms that disintermediate legacy foodservice brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oat protein sits in early-cycle expansion, with meat alternative formulation pull and CSRD-mandated Scope 3 disclosure creating structural demand tailwinds that outpace supply readiness.
For Market Incumbents: Pre-empt pea protein recapture in meat alternatives by locking multi-year supply agreements with Dutch and German extrusion partners before EFSA novel food approvals widen the supplier base. Fortify backward integration into Nordic oat cultivation to hedge raw material volatility and secure carbon accounting traceability for CSRD-compliant customers. For New Entrants and Emerging Players: Establish a beachhead in pediatric and geriatric clinical nutrition, where hypoallergenic positioning against soy and dairy proteins faces minimal incumbent saturation. Target direct-to-manufacturer digital platforms as the go-to-market angle, bypassing broker layers that Cargill and ADM dominate. For Investors and Strategic Acquirers: Carve-out targets emerge from regional grain cooperatives with underutilized fractionation assets and EU Green Deal compliance infrastructure already in place. Long-term viability centers on processors with integrated sustainability certification and wet-milling technology access. Watch meat alternative brand consolidation as the inflection signal—serial acquisition activity would concentrate procurement power and freeze out sub-scale suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Certification Stacking | EU Green Deal compliance secures preferential status with CSRD-bound food manufacturers in Germany. |
| Wet-Milling Capacity Expansion | 90% isolate purity unlocks meat alternative applications displacing soy protein bases. |
| Direct Procurement Platform Development | B2B marketplaces eliminate 15-20% distributor markups and capture formulation data. |
| Clinical Nutrition Partnership | Hypoallergenic positioning opens pediatric and geriatric segments with premium pricing power. |
| Baltic Cultivation Integration | Farm-level traceability systems anchor Scope 3 emissions reporting for annual contracting. |
Study Parameters
Cross-validation between primary interviews with oat processors, sports nutrition formulators, and meat alternative R&D directors and secondary sources including EFSA novel food determinations, EU Green Deal implementation reports, and SEC filings from grain handling majors anchors the qualitative findings. Bottom-up volume estimates from fractionation capacity utilization triangulate against top-down demand projections from food manufacturer procurement surveys.
Calibration against historical protein ingredient adoption curves and regulatory approval timelines shapes the analytical framework across the projection horizon. Segmentation dimensions span product type tiers, application categories from supplements to meat alternatives, end-user archetypes, and distribution channel evolution. CAGRs derive from elasticity-adjusted demand modeling incorporating sports nutrition clean-label substitution rates and meat alternative extrusion technology penetration.
Stress conditions across oat yield volatility, REACH approval timeline extensions, and pea protein price competition were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on carbon intensity reporting adoption and wet-milling yield improvements. Material shifts in EFSA novel food determination timelines or EU Green Deal enforcement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Yogurt Market
Plant Based Food
Global Vegan Fast Foods Market
Plant Based Food
Vegan Meals Market
Plant Based Food
Vegan Asian Food Market
Plant Based Food
Organic Pea Protein Market
Plant Based Food
Plant-Based Hot Dogs Market
Plant Based Food
Plant-Based Frozen Dessert Market
Plant Based Food
United States Meat Substitutes Market
Plant Based Food
Europe Pea Protein Market
Plant Based Food
Brazil Soy Beverages Market
Plant Based Food
Global Isolate Organic Soy Protein Market
Plant Based Food
Global Plant Protein Market
Plant Based Food
Japan Plant Protein Market
Plant Based Food
Asia Pacific Plant-Based Milk Market
Plant Based Food
Organic Rice Protein Market
Plant Based Food
Plant-Based Sausages Market