
 Plant Based Eggs Market | 2026-2036
Plant Based Eggs Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Based Eggs Market Analytics
Subscription-based recipe and replenishment services are decoupling plant-based egg purchases from traditional retail occasions. Eat Just, Inc. leverages its cultivated-foods R&D pipeline to sustain brand authority in foodservice channels. Follow Your Heart anchors the North American retail segment through decades of vegan specialty distribution. Zero Egg competes on price parity benchmarks in commercial bakery and manufacturing accounts.
Plant-based eggs are formulated emulsions or dried preparations derived from legume proteins, starches, and hydrocolloids, designed to replicate the binding, leavening, and coagulation properties of avian eggs in cooking and baking applications, typically achieving functional equivalence at protein concentrations between four and eight percent. The liquid format leads commercial adoption due to operational familiarity in kitchen environments, while powder formulations carry higher margin pools through extended shelf stability and reduced cold-chain dependency. Pea protein dominates ingredient-base discussions because of its neutral flavor profile and scalable supply, though chickpea-derived variants are gaining traction in allergen-sensitive product lines.
FDA nutrition labeling rules and EFSA novel food assessments shape compositional thresholds and marketing claims for plant-based egg entrants in the United States and European Union. India's FSSAI and China's SAMR are developing parallel frameworks for alternative protein classification that will determine market access timelines in those jurisdictions. Stakeholders must monitor regulatory divergence on protein-equivalence claims and fortification allowances as these definitions will determine which formulations qualify for institutional procurement contracts.
Market Dynamics
Foodservice procurement programs are consolidating plant-based egg purchasing around functional equivalence benchmarks, compressing supplier margins while expanding volume commitments from quick-service restaurant chains.
Growth Catalysts
- EU Novel Food Framework:EFSA assessments for legume-derived proteins are clarifying compositional thresholds, accelerating retail distribution approvals across Germany and the United Kingdom.
- Commercial Bakery Automation:Powder formulations integrate into existing dry-mix production lines without cold-chain retrofit, reducing operational friction for industrial-scale manufacturers.
- India:FSSAI alternative protein classification pathways are opening institutional procurement channels for hospitality and food processing sectors.
Market Restraints
- Pea Protein Concentration:Supply chains depend on North American and Baltic region crop cycles, exposing margins to agricultural yield volatility and commodity price swings.
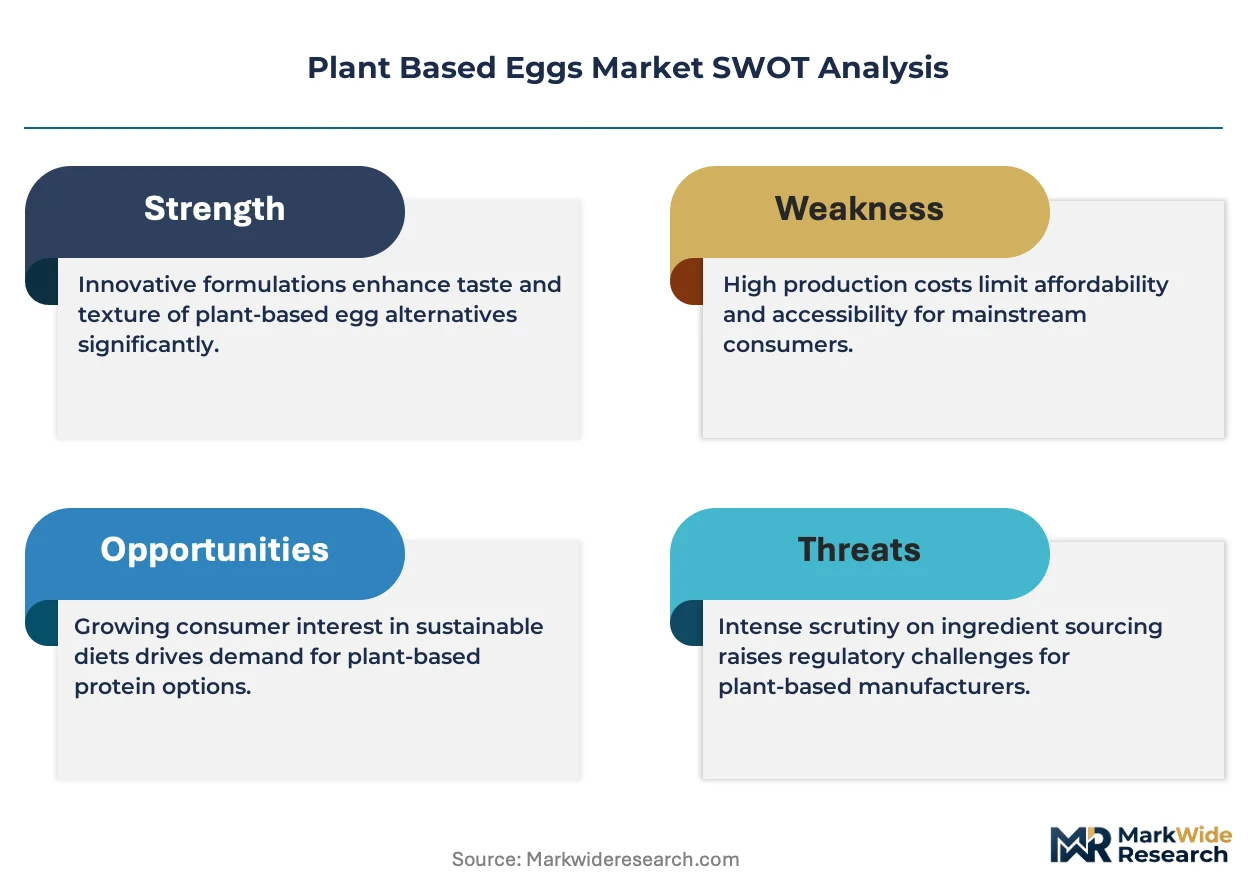
- Functional Ceiling:Current hydrocolloid and starch systems fail to replicate egg-white foaming stability in high-altitude baking applications, limiting penetration into artisanal segments.
- REACH Compliance Burden:Novel protein ingredient disclosure requirements are extending product registration timelines for European Union market entry by 12-18 months.
Strategic Opportunities
- China SAMR Framework:Pending alternative protein classification standards will unlock foodservice and retail distribution for compliant formulations in tier-one cities.
- Subscription Replenishment Models:Direct-to-consumer recipe services are decoupling purchase occasions from traditional grocery retail, building recurring revenue streams.
- Chickpea Protein Convergence:Allergen-free positioning combined with neutral flavor profiles is opening penetration into school nutrition and pediatric foodservice contracts.
Industry Challenges
- Formulation Talent Scarcity:Food science expertise at the intersection of protein chemistry and hydrocolloid systems commands premium compensation, constraining R&D scaling.
- Cold-Chain Infrastructure:Liquid format distribution requires refrigerated logistics investments that strain working capital for regional distributors entering the category.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Based Eggs Market |
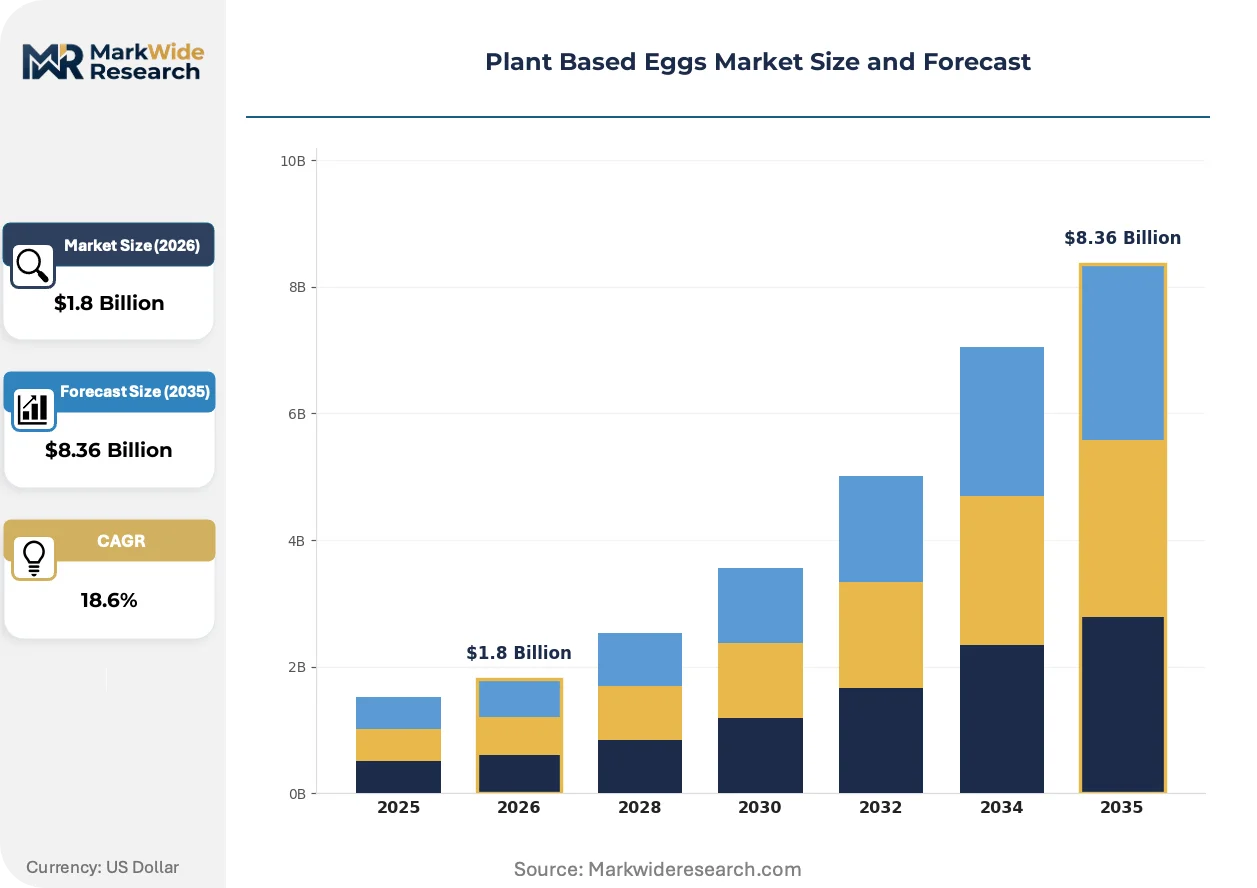
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Freeze Dried, Scrambled Ingredient Base: Flaxseed, Chickpea, Pea Protein, Potato Starch Formulation Type: Ready-to-Cook, Prepared, Ready-to-Consume, Concentrate Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops |
| Companies Covered | Eat Just, Inc., Crackd, Follow Your Heart, Vezlay Foods Pvt. Ltd, Plantmade, Zero Egg, Float Foods, The Vegg, Oggs Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Based Eggs Market Evolving Landscape
Protein extraction and emulsion stabilization technologies are converging to close functional gaps with conventional eggs, while regulatory clarity and procurement centralization reshape competitive entry points.
Precision fermentation of functional proteins is electrifying formulation capabilities for plant-based egg developers. Startups and ingredient suppliers are deploying microbial hosts to produce ovalbumin analogs with binding properties matching avian proteins. Quick-service restaurant chains are piloting these ingredients in breakfast menu items, compressing the timeline for clean-label claims without sacrificing performance benchmarks.
REACH labeling expansions are tightening disclosure requirements for novel protein ingredients across European Union member states. Manufacturers must now document supply chain provenance and allergen cross-contamination protocols before retail placement. German and United Kingdom distributors are responding by consolidating supplier relationships around pre-certified ingredient houses, raising barriers for unvalidated entrants.
Foodservice procurement teams are consolidating purchasing decisions into centralized category management functions, displacing decentralized restaurant-level ordering. Large hospitality groups and contract catering operators now negotiate enterprise-wide supply agreements with liquid and powder egg alternative producers. This concentration is most visible in United States quick-service chains, where procurement directors mandate functional equivalence testing before menu integration approvals.
Plant Based Eggs Market Segmentation
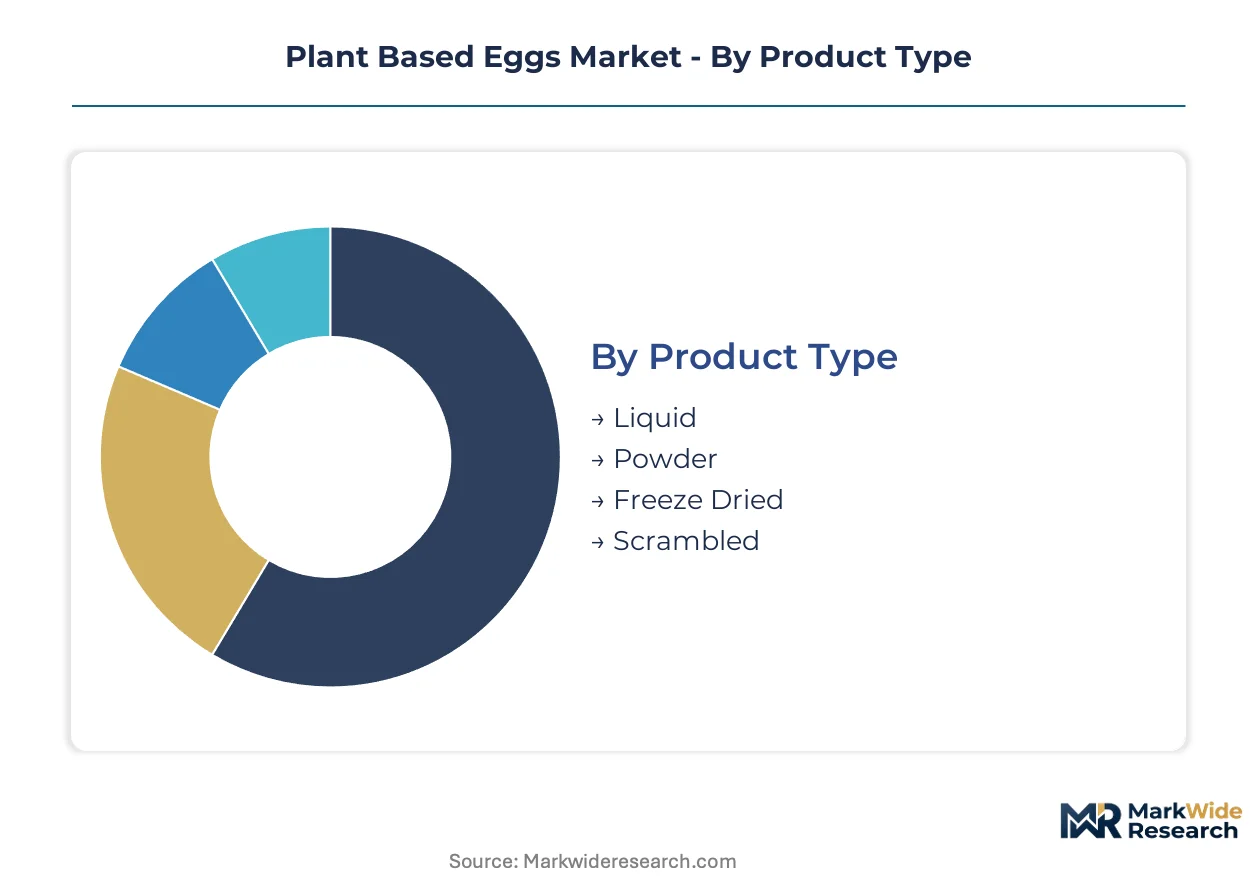
Segmentation in plant-based eggs reveals how functional requirements, supply chain constraints, and procurement channels fragment addressable demand. Buyers prioritize format compatibility with existing kitchen workflows over ingredient provenance, creating divergent margin pools across liquid and powder alternatives.
Product Type:
Operational familiarity drives format selection, with foodservice buyers weighing cold-chain capacity against shelf stability needs.
- Liquid:Pourable emulsions of legume proteins and hydrocolloids replicate avian egg viscosity for scrambling and binding applications. Quick-service restaurant chains in the United States specify liquid formats for breakfast menu integration, though refrigerated logistics constrain regional distributor expansion.
- Powder:Spray-dried protein concentrates and starch blends reconstitute with water for baking and dry-mix manufacturing. Commercial bakery automation lines in Germany favor powder for integration without cold-chain retrofit, capturing extended shelf-life economics.
- Freeze Dried:Lyophilized protein matrices target emergency food supply and military procurement channels requiring ambient storage.
- Scrambled:Pre-seasoned, heat-stable preparations serve ready-meal manufacturers seeking finished-product ingredient streams.
Liquid leads on scale; powder leads on momentum.
Ingredient Base:
Protein functionality and supply security determine sourcing decisions, with flavor neutrality and allergen positioning creating tiered procurement premiums.
- Pea Protein:Isolated globulins from yellow peas deliver emulsification and gelation at four-to-eight percent protein concentration. North American crop cycles dominate supply, exposing margins to agricultural yield volatility.
- Chickpea:Allergen-free protein concentrates penetrate school nutrition and pediatric foodservice contracts in the United Kingdom where clean-label positioning commands procurement preference.
- Flaxseed:Mucilage-rich meals provide egg-binding functionality in artisanal and home-baking segments with limited industrial scale.
- Potato Starch:Amylopectin structures contribute moisture retention and crumb structure in gluten-free bakery applications.
Pea protein anchors volume; chickpea claims the steepest expansion trajectory.
Formulation Type:
Processing intensity separates margin tiers, with convenience positioning extracting value from time-constrained consumer segments.
- Ready-to-Cook:Unseasoned liquid or reconstituted powder formats require heat activation, dominating foodservice procurement for operational flexibility.
- Prepared:Pre-mixed batters and doughs reduce labor input for commercial bakery accounts seeking throughput efficiency.
- Ready-to-Consume:Shelf-stable, fully cooked preparations target grab-and-go retail and contract catering channels.
- Concentrate:High-solids formulations dilute for industrial-scale manufacturing, minimizing transport cost per functional unit.
Ready-to-cook commands procurement volume; ready-to-consumer captures retail premium expansion.
Distribution Channel:
Channel selection reflects buyer sophistication and purchase frequency, with subscription models decoupling replenishment from traditional retail occasions.
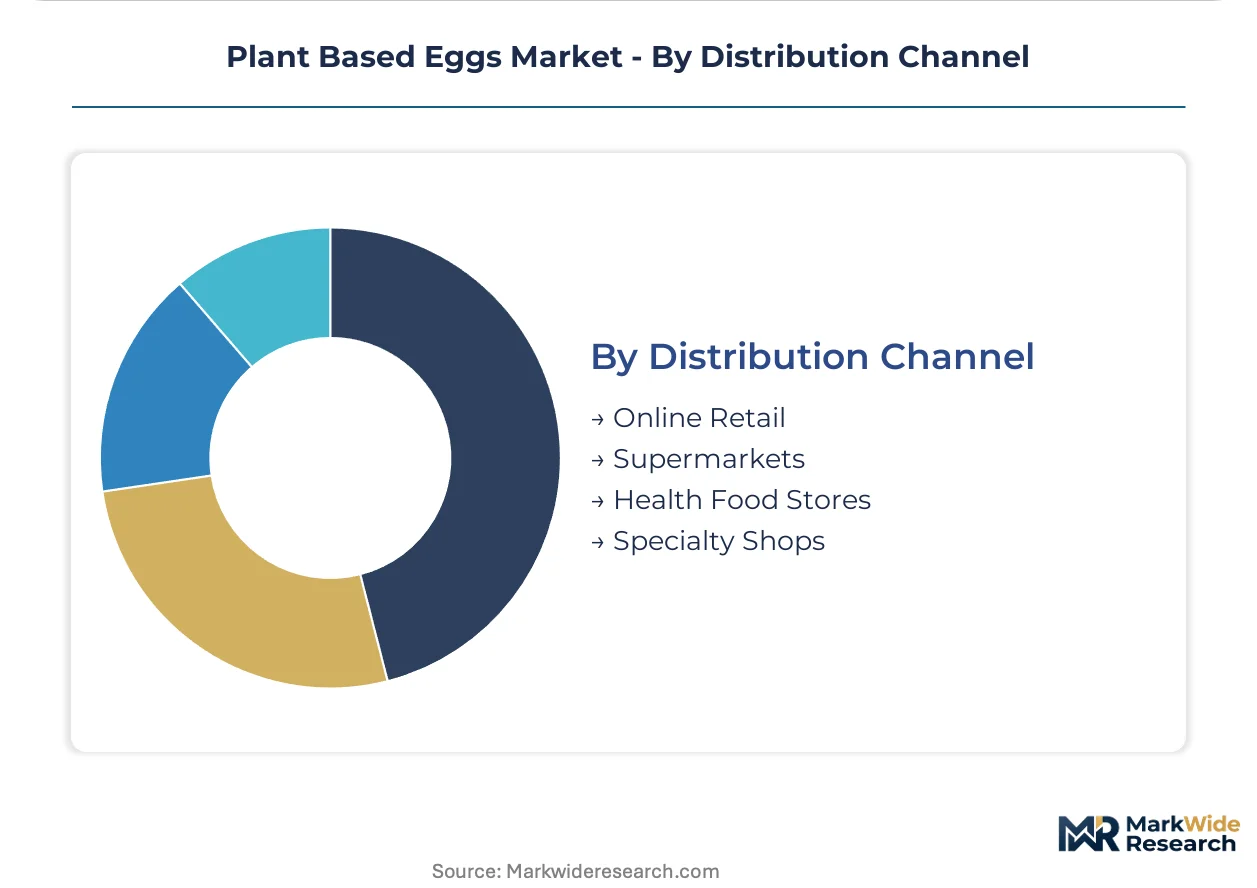
- Supermarkets:Refrigerated and ambient shelf placement in United States and German grocery chains builds trial among flexitarian consumers.
- Online Retail:Direct-to-consumer platforms and subscription services enable recipe-linked replenishment with recurring revenue capture.
- Health Food Stores:Specialty retail in the United Kingdom provides education-intensive environments for allergen-free and organic-positioned variants.
- Specialty Shops:Vegan and natural food boutiques sustain brand authority for premium-positioned formulations.
Supermarkets anchor mass-market penetration; online retail gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States foodservice procurement outpaces German retail velocity, while India's regulatory pathway accelerates faster than China's pending SAMR classification. Demand clusters diverge between quick-service chain integration and specialty retail education.
United States
Quick-service restaurant chains drive liquid format adoption through centralized procurement mandates. FDA nutrition labeling rules govern protein-equivalence claims for institutional contracts. Chicago and Dallas hospitality clusters host pilot programs for breakfast menu integration.
Germany
Commercial bakery automation favors powder formulations for dry-mix production line compatibility. REACH disclosure requirements extend registration timelines for novel protein entrants. Hamburg and Munich distribution hubs consolidate supplier relationships around pre-certified ingredient houses.
United Kingdom
Retail flexitarian trial builds through supermarket refrigerated placement and health food store education. EFSA novel food assessments clarify compositional thresholds for legume-derived proteins. London and Birmingham procurement teams negotiate enterprise-wide supply agreements with alternative protein producers.
India
Hospitality and food processing sectors open institutional channels through FSSAI alternative protein classification. School nutrition programs pilot allergen-free formulations in metropolitan contracts. Mumbai and Bangalore foodservice operators test powder integration in commercial bakery applications.
China
Tier-one city foodservice and retail distribution await SAMR alternative protein classification standards. Precision fermentation startups target microbial ovalbumin production for clean-label positioning. Shanghai and Beijing quick-service chains evaluate functional equivalence benchmarks for menu integration.
Plant Based Eggs Market Competitive Landscape
Top-tier vendors anchor foodservice procurement contracts, while mid-tier specialists compete on allergen-free positioning and price parity benchmarks. The vendor base stratifies across cultivated-foods R&D pipelines, decades-long vegan specialty distribution networks, and commercial bakery manufacturing accounts. Three archetypes dominate: technology-forward innovators, legacy vegan brands, and industrial-scale commodity suppliers. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with procurement centralization forcing supplier consolidation.
Within the technology-forward tier, Eat Just, Inc. and Float Foods exemplify cultivated-foods R&D positioning, while Follow Your Heart anchors the legacy vegan specialty archetype through North American retail distribution depth. Zero Egg occupies a position within the industrial commodity tier, competing on price parity benchmarks for commercial bakery and manufacturing accounts. These three representations illustrate how procurement channel specialization fragments competitive entry points across foodservice, retail, and industrial segments.
| Leading Market Players |
|---|
| Eat Just, Inc. |
| Crackd |
| Follow Your Heart |
| Vezlay Foods Pvt. Ltd |
| Plantmade |
| Zero Egg |
| Float Foods |
| The Vegg |
| Oggs Ltd. |
| Others |
Value Network & Pricing Analysis
Pea protein concentrate costs flow from North American and Baltic region agricultural cycles through three-tier pricing structures across premium, standard, and economy levels, with cold-chain liquid formats commanding refrigerated logistics premiums against ambient-stable powder alternatives.
Pricing Analysis
Capacity additions in Germany and the United States are reshaping price floors for powder formulations as commercial bakery automation absorbs volume at contract rates. Three-tier pricing structure across premium, standard, and economy levels separates precision-fermented ingredients from commodity legume proteins from basic starch-hydrocolloid blends. Cost compression in the standard tier is intensifying because procurement directors at quick-service chains mandate functional equivalence testing before volume commitments. Foodservice buyers exhibit highest price sensitivity due to enterprise-wide supply agreement negotiations, while retail subscription services demonstrate lowest sensitivity through recipe-linked replenishment models.
Supply Chain Analysis
Refrigerated freight costs for liquid formats strain working capital for regional distributors entering the category, particularly where cold-chain infrastructure remains underdeveloped. Supply concentrates in the United States, Germany, and Canada for pea protein extraction, with chickpea sourcing diversifying into India and Turkey for allergen-sensitive lines. Raw material dependencies center on yellow pea isolate, hydrocolloid stabilizers, and spray-drying energy inputs. Single-source vulnerability in precision-fermented ovalbumin analog production threatens formulation continuity for clean-label positioning. Distribution runs through centralized foodservice procurement programs displacing decentralized restaurant-level ordering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement directors at quick-service chains now demand functional equivalence benchmarks that filter out substandard formulations.
For Market Incumbents: Acquire precision-fermentation capacity and cultivated-foods R&D pipelines to preempt clean-label substitution threats from microbial ovalbumin producers. Consolidate supplier relationships around pre-certified ingredient houses before REACH disclosure extensions raise registration barriers for unvalidated entrants. Backward integration into North American pea protein extraction secures margin control against agricultural yield volatility. For New Entrants and Emerging Players: Begin with chickpea-derived allergen-free positioning in United Kingdom school nutrition and pediatric foodservice contracts where clean-label procurement premiums remain underexploited. Target India's hospitality and food processing sectors through FSSAI alternative protein classification pathways opening institutional channels faster than China's pending SAMR framework. Deploy direct-to-consumer subscription models decoupled from traditional grocery retail to build recurring revenue before supermarket slotting fees escalate. For Investors and Strategic Acquirers: Consolidation pressure builds where formulation talent scarcity at the intersection of protein chemistry and hydrocolloid systems constrains R&D scaling for mid-tier players. Long-term viability favors technology-forward innovators with cultivated-foods pipelines and legacy vegan brands with decades of specialty distribution depth over undifferentiated commodity suppliers. The signal to watch is SAMR alternative protein classification standard release unlocking tier-one city foodservice distribution in China.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Microbial ovalbumin production enables clean-label claims without sacrificing functional benchmarks for quick-service chains. |
| Backward Integration into Pea Protein | Captive supply of yellow pea isolate insulates margins from North American agricultural yield volatility and commodity swings. |
| REACH Pre-Certification Investment | Documented supply chain provenance and allergen protocols accelerate European Union retail placement timelines by 12-18 months. |
| Subscription Replenishment Platform Launch | Recipe-linked direct-to-consumer models build recurring revenue streams decoupled from supermarket slotting fee escalation. |
| Chickpea Protein Line Extension | Allergen-free positioning penetrates school nutrition contracts in the United Kingdom where procurement premiums favor clean-label sourcing. |
Research Methodology
Bottom-up foodservice procurement modeling reconciled against top-down ingredient supplier tracking forms the analytical core of this study. Primary interviews with procurement directors at quick-service chains, commercial bakery automation engineers, alternative protein R&D leads, and regulatory affairs specialists at EFSA and FDA combined with secondary validation from REACH filings, FSSAI classification announcements, customs trade data, and SEC disclosures from publicly traded ingredient suppliers. Triangulation across these sources ensures volume and value estimates reflect actual contract commitments rather than aspirational capacity announcements.
Historical trendline analysis of liquid versus powder format adoption rates across United States, German, and United Kingdom foodservice channels established baseline growth trajectories. Segmentation dimensions modeled include product format, protein source, formulation type, and distribution channel complexity alongside regulatory framework clustering by jurisdiction. CAGRs derive from weighted average of bottom-up procurement pipeline visibility and top-down production capacity expansion schedules, with precision fermentation technology maturation curves and EFSA novel food approval timelines as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including pre-approval SAMR classification outcomes in China, extreme weather impacts on North American pea crop yields, and breakthroughs in high-altitude baking foam stability that would expand addressable demand into artisanal segments. Forecasts reflect assumptions documented across stakeholder interviews and secondary sources. A model refresh is warranted upon material change in EFSA compositional threshold rulings or SAMR alternative protein standard release.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Smart Plant Based Food Packaging Market
Plant Based Food
United States Meat Substitutes Market
Plant Based Food
Vegan Pastry Market
Plant Based Food
China Plant-Based Food and Beverages Market
Plant Based Food
Pea Protein Market
Plant Based Food
China Rice Protein Market
Plant Based Food
Meatless Meat Market
Plant Based Food
North America Rice Protein Market
Plant Based Food
Plant-Based Meatballs Market
Plant Based Food
Pea Protein Isolate Market
Plant Based Food
Plant-Based Bacon Market
Plant Based Food
Plant-Based Food Ingredients Market
Plant Based Food
Germany Plant Protein Market
Plant Based Food
United Kingdom Soy Protein Market
Plant Based Food
Plant-Based Natural Flavor Market
Plant Based Food
Global Textured Vegetable Protein Market