
 Textured Variegates Market | 2026-2036
Textured Variegates Market Size, Share, and Industry Trends Forecast 2026-2036
Textured Variegates Market Analytics
Italian marble-processing districts and Spanish ceramic belt producers is realigning capacity toward engineered stone-compatible variegate lines. Balchem leverages its encapsulation technology leadership to supply controlled-release pigment systems for high-temperature curing applications. Kerry Group anchors food-grade texture expertise adjacent to industrial coating markets through shared hydrocolloid platforms. PreGel Australia competes in premium decorative finishes by sustaining strong distributor relationships across Asia-Pacific specification channels.
Textured variegates are composite surface treatments combining mineral particulates, synthetic or natural colorants, and binding resins to create visual depth and tactile variation on substrates. These formulations typically achieve 50-200 micron particle dispersion with controlled light refraction indices for consistent batch-to-batch appearance. Natural variegates command premium positioning among architects pursuing LEED-compliant material palettes with verifiable recycled content. Synthetic variegates dominate automotive interior applications where UV stability and exact color matching override sustainability premiums. Construction applications absorb the largest volume share as facade renovation cycles accelerate across mature building stock.
EPA oversees VOC emission thresholds for architectural coatings in the US, while REACH mandates disclosure of Substances of Very High Concern in European decorative chemical imports. ECHA's ongoing restriction proposals for certain crystalline silica grades directly affect mineral-based variegate formulations and their manufacturing economics. Stakeholders must monitor evolving classification thresholds for synthetic microplastic additives under draft EU regulatory frameworks that could reshape formulation portfolios.
Market Dynamics
REACH crystalline silica restrictions and ECHA's evolving microplastic classifications are forcing reformulation investments across European mineral-based variegate supply chains. Stuttgart and Cologne coating clusters face immediate compliance cost pressures while architects accelerate specification of verified low-VOC alternatives.
Growth Catalysts
- Facade renovation cycles:Mature building stock across Germany, Italy, and Spain requires decorative surface upgrades. Stuttgart architects specify textured variegates for premium commercial recladding projects.
- LEED-compliant material demand:Natural variegate formulations with verifiable recycled content attract specification-grade procurement from sustainability-focused developers.
- Automotive interior UV stability requirements:Synthetic variegate systems dominate dashboard and trim applications where exact color matching overrides premium positioning.
Market Restraints
- Input cost volatility:Titanium dioxide and specialized mineral particulates face supply concentration from Chinese producers, compressing formulation margins.
- Regulatory friction:EPA VOC emission thresholds for architectural coatings create cross-border compliance complexity for US-European formulation transfers.
- Substitution threat:Digital printing and thin-film decorative laminates encroach on low-end interior cladding specifications.
Strategic Opportunities
- Underpenetrated specification channels:Australian premium decorative finish distributors sustain strong relationships across Asia-Pacific commercial construction procurement networks.
- Technology convergence:Encapsulation platforms from adjacent food-grade texture markets enable controlled-release pigment systems for high-temperature curing applications.
- Regulatory tailwind:EU Green Deal building renovation targets mandate surface treatment upgrades in public sector tenders, expanding addressable specification volume.
Industry Challenges
- Formulation chemist scarcity:Mineral-synthetic hybrid expertise concentrates in Italian marble-processing districts, limiting capacity expansion outside established clusters.
- Certification timeline compression:REACH Substances of Very High Concern disclosure requirements demand accelerated third-party testing for imported decorative chemical formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textured Variegates Market |
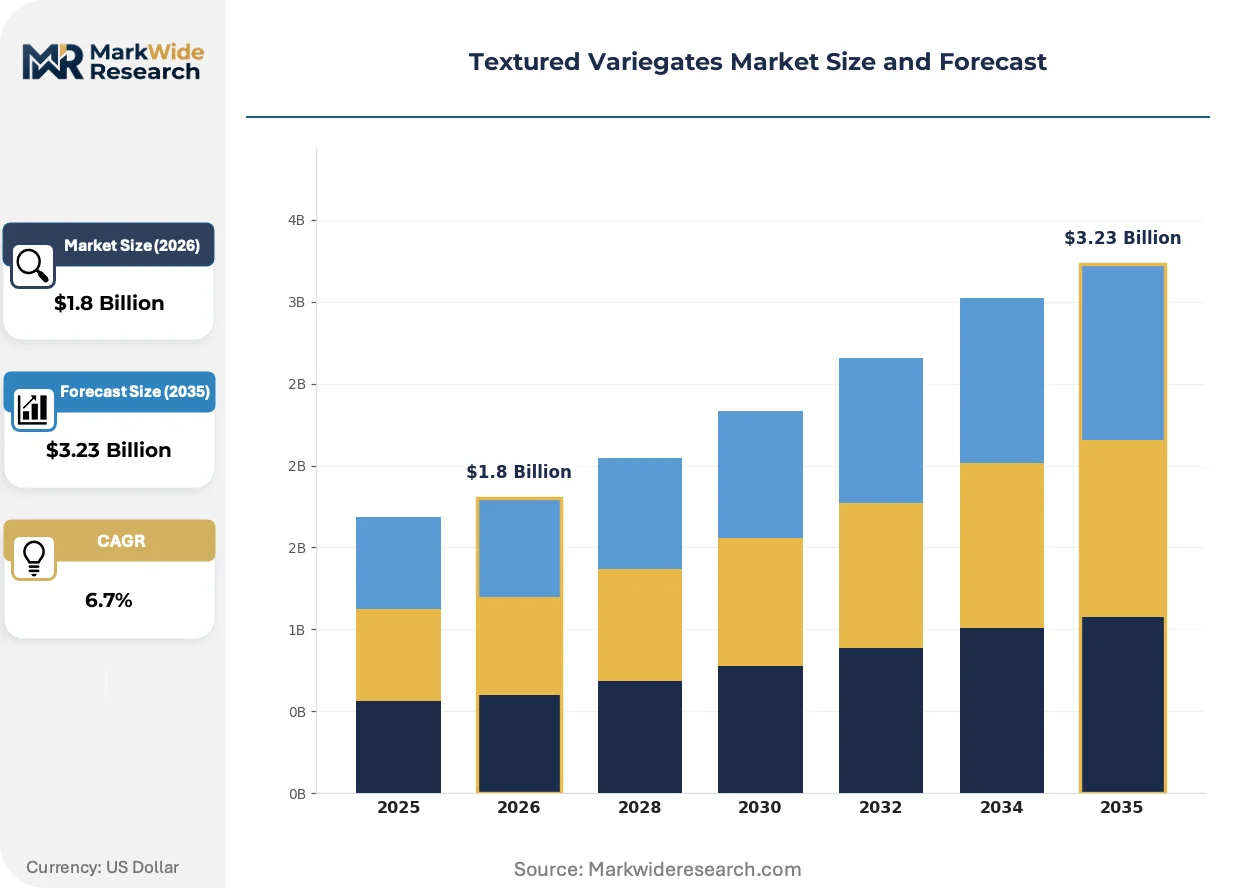
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Variegates, Synthetic Variegates, Mineral-Based Variegates, Organic Variegates Application: Construction, Automotive, Furniture, Packaging End User: Architects, Manufacturers, Designers, Retailers Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Schlotterbeck & Foss, Holland Manufacturing, Majors Group, Dippin Flavors, Chemroy, Montebianco, PreGel Australia, Balchem, Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textured Variegates Market Evolving Landscape
Surface engineering capabilities are bifurcating between precision-controlled synthetic systems and artisanal natural material palettes. This divergence reshapes R&D allocation and manufacturing asset configurations across formulation specialists.
Encapsulation technology is integrating controlled-release pigment architectures into high-temperature curing resin systems. Automotive tier-one suppliers adopt these formulations for interior trim components requiring batch-to-batch color consistency within 0.5 Delta E. The technology is integrating specification-grade performance into mass-production coating lines previously limited to standard pigmentation.
ECHA's crystalline silica restriction proposals directly affect mineral-based variegate economics. Formulators must substitute engineered aluminosilicate alternatives or absorb higher raw material costs. German specialty coating clusters around Stuttgart and Cologne face the most immediate reformulation pressure given their concentration of specification-grade architectural output.
Architect procurement patterns favor single-source responsibility for facade material packages. General contractors consolidate decorative surface specifications with structural cladding suppliers, compressing independent variegate distributor margins. This consolidation is most visible in German commercial renovation tenders where integrated facade system warranties dominate award criteria.
Textured Variegates Market Segmentation
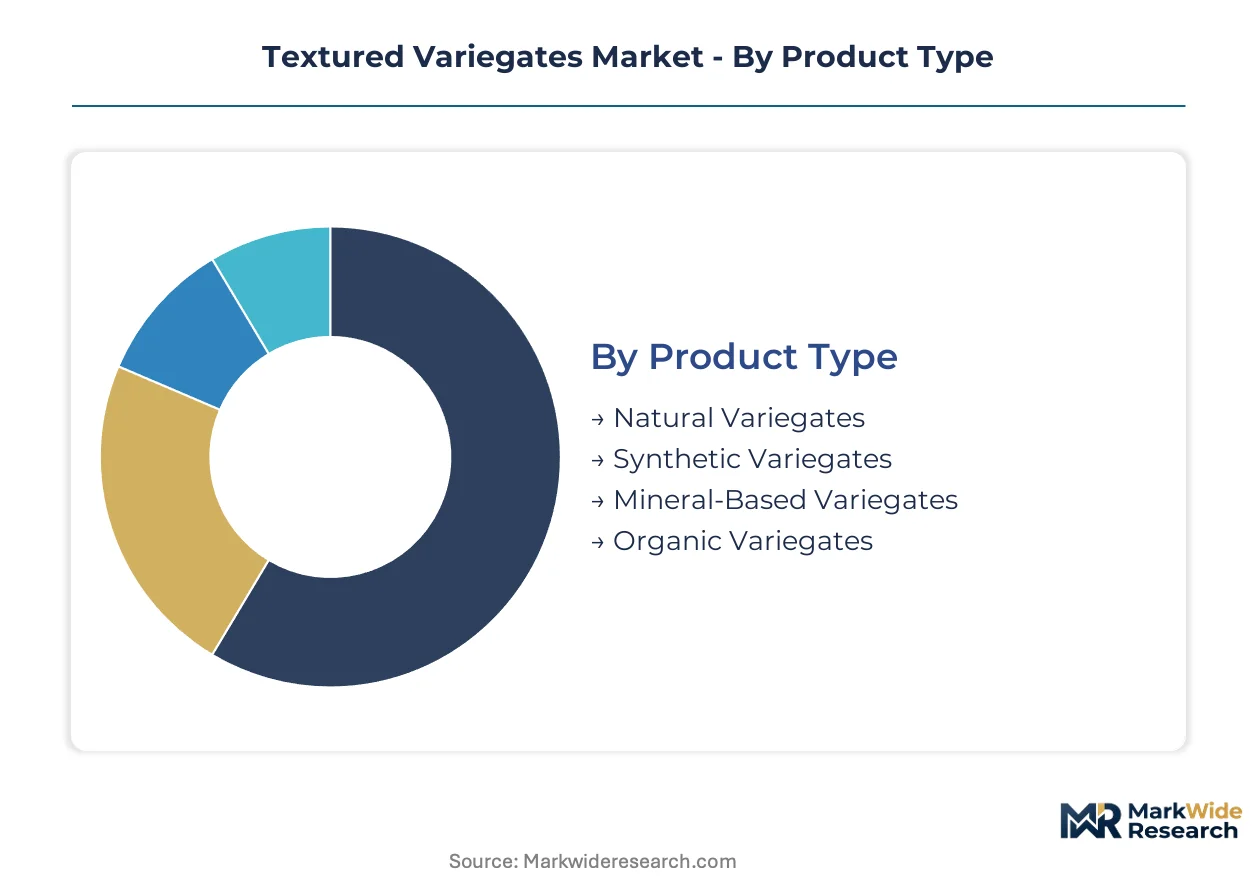
Segmentation reveals how capital deployment and technical specialization concentrate across formulation chemistry, end-use specifications, and procurement channels. Each dimension carries distinct margin profiles and regulatory exposure that reshape competitive positioning.
Product Type:
Capital intensity peaks in synthetic and mineral-based production lines requiring precision dispersion equipment and controlled-environment curing infrastructure.
- Natural Variegates:Formulations incorporate marble dust, ground minerals, and plant-derived binders with 50-150 micron particle sizing. Architects in Stuttgart and Cologne specify these for LEED-compliant commercial facades where recycled content verification commands specification premiums.
- Synthetic Variegates:Engineered polymer matrices with UV-stabilized pigments achieve exact Delta E color matching. Automotive tier-one suppliers in Germany absorb the largest volume for dashboard and interior trim applications where batch consistency overrides material provenance.
- Mineral-Based Variegates:Aluminosilicate and engineered particulate systems face ECHA crystalline silica restriction pressures. Italian marble-processing districts around Carrara and Verona hold concentrated reformulation expertise.
- Organic Variegates:Bio-resin binders with agricultural waste fillers serve niche sustainable packaging segments. PreGel Australia distributes these through Asia-Pacific specification channels for premium decorative finishes.
Most installed capacity flows through Synthetic Variegates. Expansion is steepest in Natural Variegates.
Application:
Volume concentration diverges sharply between long-cycle construction procurement and high-specification automotive supply chains.
- Construction:Facade recladding and interior cladding absorb the largest absolute volume as German commercial renovation cycles accelerate. Stuttgart architects specify textured variegates for premium commercial projects requiring integrated warranty packages from structural cladding suppliers.
- Automotive:Dashboard, door trim, and console applications demand UV stability and exact color matching within 0.5 Delta E. Encapsulation technology from adjacent food-grade texture markets enables controlled-release pigment systems for high-temperature curing resin lines.
- Furniture:Decorative surface treatments for premium residential and hospitality fixtures concentrate in Italian and Spanish manufacturing clusters. Specification-grade procurement favors single-source responsibility for material packages.
- Packaging:Specialty cartons and rigid containers employ organic variegate formulations for brand differentiation. Demand concentrates in Asia-Pacific premium cosmetic and spirits packaging channels.
Construction commands the dominant share of current volume. Automotive applications are gaining share fastest.
End User:
Procurement authority fragments between specification influencers and volume purchasers with divergent technical validation requirements.
- Architects:Design professionals in German commercial renovation markets specify textured variegates for facade material packages. Consolidated procurement with structural cladding suppliers compresses independent distributor margins.
- Manufacturers:Automotive tier-one suppliers and furniture producers drive formulation standardization for mass-production coating lines. Balchem supplies controlled-release pigment systems for high-temperature curing applications.
- Designers:Interior and product designers source artisanal natural material palettes for bespoke residential and hospitality projects. Italian marble-processing districts anchor this specification tier.
- Retailers:Home improvement and specialty finish retailers stock consumer-grade decorative treatments. Online retail channels expand access to DIY renovation segments.
Manufacturers represent the largest procurement volume. Architects are shifting specification authority fastest.
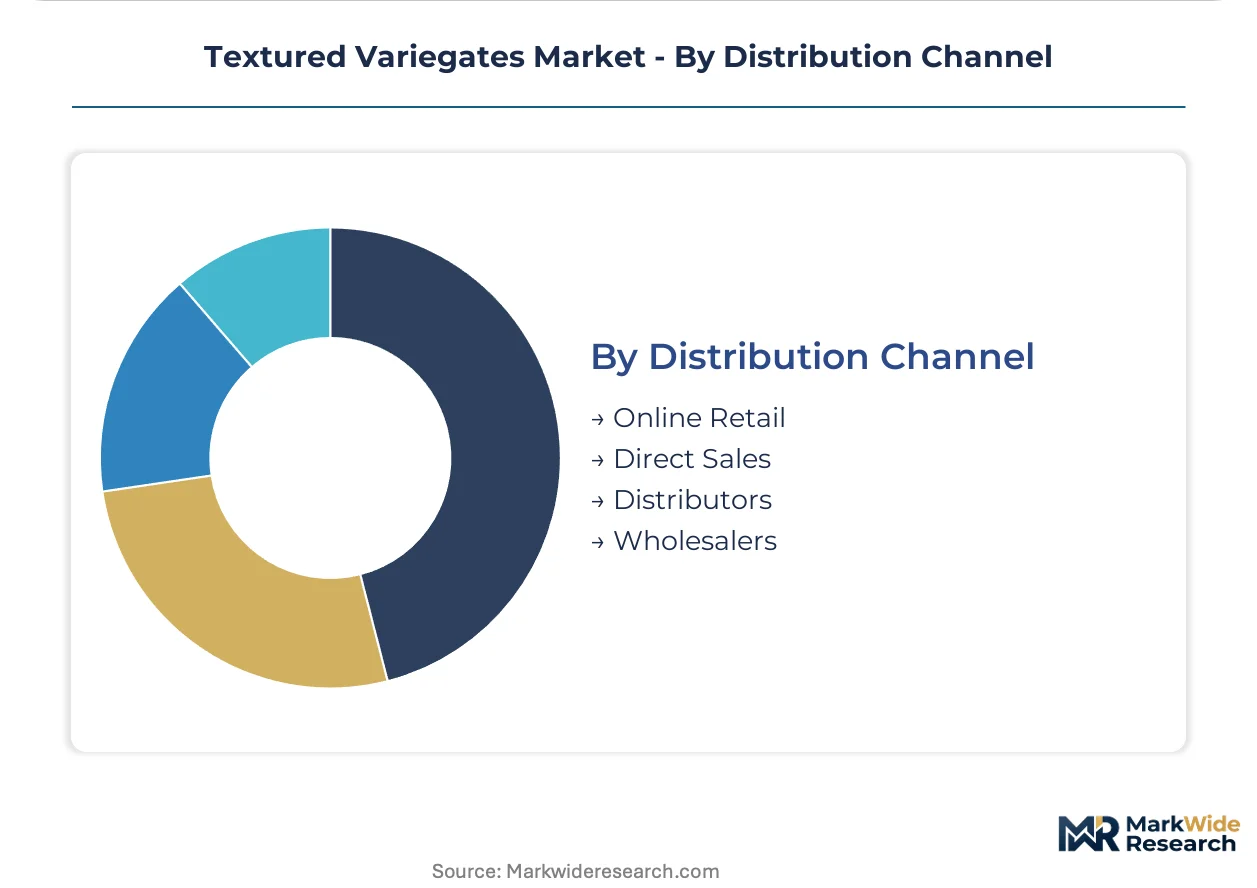
Distribution Channel:
Channel economics reflect the tension between specification-grade technical support and volume-driven cost efficiency.
- Direct Sales:Formulators maintain dedicated technical service teams for automotive and large construction accounts. Kerry Group anchors food-grade texture expertise adjacent to industrial coating markets through shared hydrocolloid platforms.
- Distributors:Independent networks sustain relationships across Asia-Pacific specification channels. PreGel Australia competes in premium decorative finishes through strong distributor relationships.
- Online Retail:E-commerce platforms serve small-batch architectural practices and residential renovation contractors. REACH Substances of Very High Concern disclosure requirements complicate cross-border digital sales.
- Wholesalers:Bulk procurement channels supply standardized formulations to mid-tier furniture and packaging manufacturers. Margin compression from digital printing substitution affects this tier most acutely.
Distributors handle the majority of specification-grade volume. Direct sales are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany absorbs specification-grade procurement volumes that outpace Italian output, while Australian distributors channel Asia-Pacific demand through premium decorative finish networks.
Germany
Stuttgart architects specify textured variegates for commercial facade recladding projects requiring integrated warranty packages. REACH crystalline silica restrictions from ECHA force reformulation investments across mineral-based supply chains. Cologne coating clusters face immediate compliance cost pressures while accelerating low-VOC alternative specifications.
Italy
Carrara and Verona marble-processing districts anchor artisanal natural material palettes for bespoke residential and hospitality projects. EU Green Deal building renovation targets mandate surface treatment upgrades in public sector tenders. Italian producers realign capacity toward engineered stone-compatible variegate lines to capture specification-grade procurement.
Spain
Ceramic belt producers expand decorative surface finish capacity for premium facade and interior cladding applications. RoHS frameworks tighten compositional standards for synthetic formulations exported to European markets. Valencia manufacturing clusters concentrate UV-stabilized pigment expertise for automotive interior applications.
Australia
PreGel Australia sustains strong distributor relationships across Asia-Pacific specification channels for premium decorative finishes. The country's national chemical regulator enforces disclosure requirements for imported decorative chemical formulations. Sydney and Melbourne commercial construction procurement networks drive demand for LEED-compliant material palettes with verifiable recycled content.
United States
Architects specify decorative surface finishes for premium facades and interior cladding in mature building stock renovation cycles. EPA VOC emission thresholds for architectural coatings create compliance complexity for formulation transfers from European suppliers. California and Texas construction markets absorb the largest absolute volume of textured variegate specifications.
Textured Variegates Market Competitive Landscape
German producers anchor one tier; Italian specialists hold artisanal natural material expertise. The vendor base concentrates around coating clusters with mineral-synthetic hybrid formulation capabilities. Three strategic archetypes dominate: encapsulation technology specialists, marble-processing district incumbents, and food-grade texture platform extenders. Competitive moves center on regulatory-driven reformulation partnerships and specification channel consolidation with structural cladding suppliers.
Within the encapsulation technology tier, Balchem occupies a position representing controlled-release pigment system supply for high-temperature curing applications. Kerry Group exemplifies food-grade texture expertise extension into adjacent industrial coating markets through shared hydrocolloid platforms. PreGel Australia anchors the Asia-Pacific premium decorative finish distributor tier, sustaining relationships across specification channels.
| Leading Market Players |
|---|
| Schlotterbeck & Foss |
| Holland Manufacturing |
| Majors Group |
| Dippin Flavors |
| Chemroy |
| Montebianco |
| PreGel Australia |
| Balchem |
| Kerry Group |
| Others |
Value Network & Pricing Analysis
Titanium dioxide price indices from Chinese producers cascade through textured variegate supply chains, compressing formulation margins for mineral-based and synthetic tiers while concentrating pricing power among encapsulation technology specialists serving automotive OEMs.
Pricing Analysis
Distributor margins absorb the steepest compression as general contractors consolidate facade material packages with structural cladding suppliers. Three-tier pricing structure across premium, standard, and economy levels separates LEED-certified natural formulations from specification-grade synthetics and commodity mineral blends. Pricing pressure stems from REACH crystalline silica compliance costs forcing reformulation investments. Small-batch architectural practices exhibit highest price sensitivity; automotive tier-one suppliers prioritize Delta E consistency over unit economics.
Supply Chain Analysis
Specialty mineral particulate supply rests on Chinese titanium dioxide producers, Italian Carrara marble-processing districts, and German Stuttgart-Cologne coating clusters. Key inputs span engineered aluminosilicates, UV-stabilized pigment systems, and hydrocolloid binding platforms. Single-source vulnerability concentrates in Chinese mineral feedstock concentration amid export licensing uncertainty. Distribution runs through specification-grade technical distributors in Asia-Pacific and direct sales teams for automotive accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal building renovation targets mandate surface treatment upgrades, expanding specification-grade procurement volume across public sector tenders.
For Market Incumbents: Lock in reformulation partnerships with Italian marble-processing districts to secure mineral-synthetic hybrid expertise ahead of ECHA crystalline silica restrictions. Deepen channel control through integrated facade system warranties that compress independent distributor margins. Prioritize certification investment for low-VOC alternatives specified by Stuttgart architects. For New Entrants and Emerging Players: EU Green Deal renovation mandates in Germany open a window for organic variegate formulations capturing LEED-compliant procurement from sustainability-focused developers. Target Asia-Pacific premium decorative finish channels where PreGel Australia's distributor relationships demonstrate penetrable white space. Pursue encapsulation technology licensing from adjacent food-grade texture markets as go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where formulation chemist scarcity concentrates in established Italian and German clusters. Mid-cap specialists with captive mineral sourcing and REACH pre-certified portfolios represent prime acquisition targets across a five-to-ten year viability window. Watch ECHA microplastic classification finalization as inflection indicator for synthetic formulation asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Feedstocks | Captive supply of Chinese titanium dioxide and Italian marble dust secures margin control against input volatility. |
| REACH Pre-Certification Investment | Accelerated Substances of Very High Concern disclosure enables specification access to German commercial renovation tenders. |
| Encapsulation Technology Licensing | Controlled-release pigment platforms from Balchem extend into high-temperature automotive curing applications. |
| Asia-Pacific Distributor Network Expansion | PreGel Australia's channel relationships demonstrate replicable model for premium decorative finish penetration. |
| Integrated Facade System Partnerships | Joint warranty structures with structural cladding suppliers compress independent distributor margins in procurement consolidation. |
Research Methodology
Direct dialogue with formulation chemists, automotive tier-one procurement leads, Stuttgart-based specification architects, and Asia-Pacific distributor principals grounded qualitative insights. Secondary validation drew from ECHA restriction proposals, EPA VOC emission filings, EU Green Deal tender databases, and customs trade data for titanium dioxide and mineral particulate flows. Bottom-up volume estimates triangulated against top-down construction spending and automotive production forecasts.
Bottom-up modeling segmented by formulation chemistry, end-use application, and procurement channel across the analysis window. Top-down cross-checks applied construction sector cladding spend ratios and automotive interior trim content-per-vehicle metrics. CAGRs derived from regression against renovation cycle frequency, regulatory compliance cost trajectories, and substitution elasticity from digital printing technologies.
Revisions become necessary when ECHA crystalline silica restrictions tighten beyond current proposals, Chinese export licensing disrupts titanium dioxide supply, or digital printing cost curves accelerate substitution in low-end interior specifications. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Turkey Carpet and Rugs Market
Flooring, Carpets, and Rugs
India Wood Flooring Market
Flooring, Carpets, and Rugs
Europe Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Germany Flooring Market
Flooring, Carpets, and Rugs
Asia-Pacific Floor Covering Market
Flooring, Carpets, and Rugs
Terrazzo Flooring Market
Flooring, Carpets, and Rugs
Global Carpet Tile Market
Flooring, Carpets, and Rugs
Resilient Floor Covering Market
Flooring, Carpets, and Rugs
US Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
Saudi Arabia Carpet and Rugs Market
Flooring, Carpets, and Rugs
GCC Floor Covering Market
Flooring, Carpets, and Rugs
Global Commercial Flooring Market
Flooring, Carpets, and Rugs
United States Floor Covering Market
Flooring, Carpets, and Rugs
Europe Carpet Tile Market
Flooring, Carpets, and Rugs
United States Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
US Terrazzo Market