
 GCC Flooring Market | 2026-2036
GCC Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Flooring Market Intelligence
A shortage of certified installation technicians across Saudi Arabia and Qatar is unwinding project timelines and inflating labor costs for premium flooring systems. RAK Ceramics leverages its integrated manufacturing base in Ras Al Khaimah to dominate ceramic and porcelain tile supply across the Gulf. Al Sorayai Group anchors its position through deep distribution networks and project-specific fabrication capabilities for commercial and hospitality clients. Floorworld LLC competes by controlling showroom channels in Dubai and Abu Dhabi, where specification decisions by architects and interior designers concentrate.
GCC flooring encompasses surface materials installed to provide structural support, thermal insulation, acoustic dampening, and aesthetic finish in built environments, with engineered products typically specified to 2-8 mm wear-layer thickness and slip-resistance ratings of R9-R11 for commercial applications. The primary purpose spans residential comfort, commercial durability, and hospitality brand expression under extreme temperature cycling and high-salinity ambient conditions. Vinyl surfaces lead volume in new commercial construction due to moisture resistance and lower installed cost, while hardwood commands margin pools in luxury residential and boutique hospitality segments where natural material authenticity drives specification. Laminated products occupy a contracting middle tier as price-competitive vinyl and thin-engineered hardwood displace traditional high-pressure laminate in mid-market residential applications.
Saudi Standards, Metrology and Quality Organization (SASO) and Emirates Authority for Standardization and Metrology (ESMA) enforce fire-resistance classifications and volatile organic compound limits that filter imported product eligibility and shape local manufacturing investment. The UAE's Al Sa'fat green building rating system and Saudi Building Code thermal performance chapters mandate cool-roof and underfloor insulation specifications that cascade into flooring system selection criteria. Stakeholders must monitor how Gulf Cooperation Council customs union harmonization progresses on construction product certification reciprocity, as divergence in national technical regulations continues fragmenting procurement strategies across member states.
Market Dynamics
Saudi Vision 2030 and UAE building energy codes are compressing specification cycles as developers race to meet tightened indoor air quality and thermal performance mandates ahead of project handovers.
Growth Catalysts
- Hospitality construction pipeline:Dubai and Riyadh hotel developments are accelerating luxury vinyl and engineered surface procurement for rapid-install, high-durability finishes.
- SASO fire-resistance classifications:Saudi Arabia's enforcement of stricter material standards is filtering out low-grade imports and elevating certified local manufacturing capacity.
- Thin-engineered hardwood:This material category is capturing specification share from traditional laminate in mid-market residential towers across Abu Dhabi.
Market Restraints
- Petrochemical input volatility:Vinyl flooring production faces margin pressure from fluctuating ethylene and plasticizer feedstock costs sourced from Gulf petrochemical complexes.
- Installation technician scarcity:Saudi Arabia and Qatar lack sufficient certified crews for premium flooring systems, forcing project timeline extensions and labor cost inflation.
- High-pressure laminate displacement:Price-competitive vinyl and thin-engineered alternatives are eroding this category's addressable market in mid-tier residential applications.
Strategic Opportunities
- Qatar's post-World Cup hospitality conversion:Stadium-adjacent properties are repurposing into hotels and commercial spaces requiring rapid flooring retrofit at scale.
- Al Sa'fat green building ratings:UAE's expanding mandatory certification scope for cool-roof and underfloor insulation is cascading into specification of thermally efficient flooring systems.
- Digital specification platforms:Architect and interior designer procurement in Dubai and Abu Dhabi is migrating to centralized showroom-to-project digital workflows.
Industry Challenges
- Certified installer pipeline gaps:Technical training capacity for moisture-barrier and floating-floor systems lags behind project award velocity in Riyadh and Jeddah.
- Customs union reciprocity fragmentation:Divergent national technical regulations across GCC member states complicate cross-border procurement and inventory positioning strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Flooring Market |
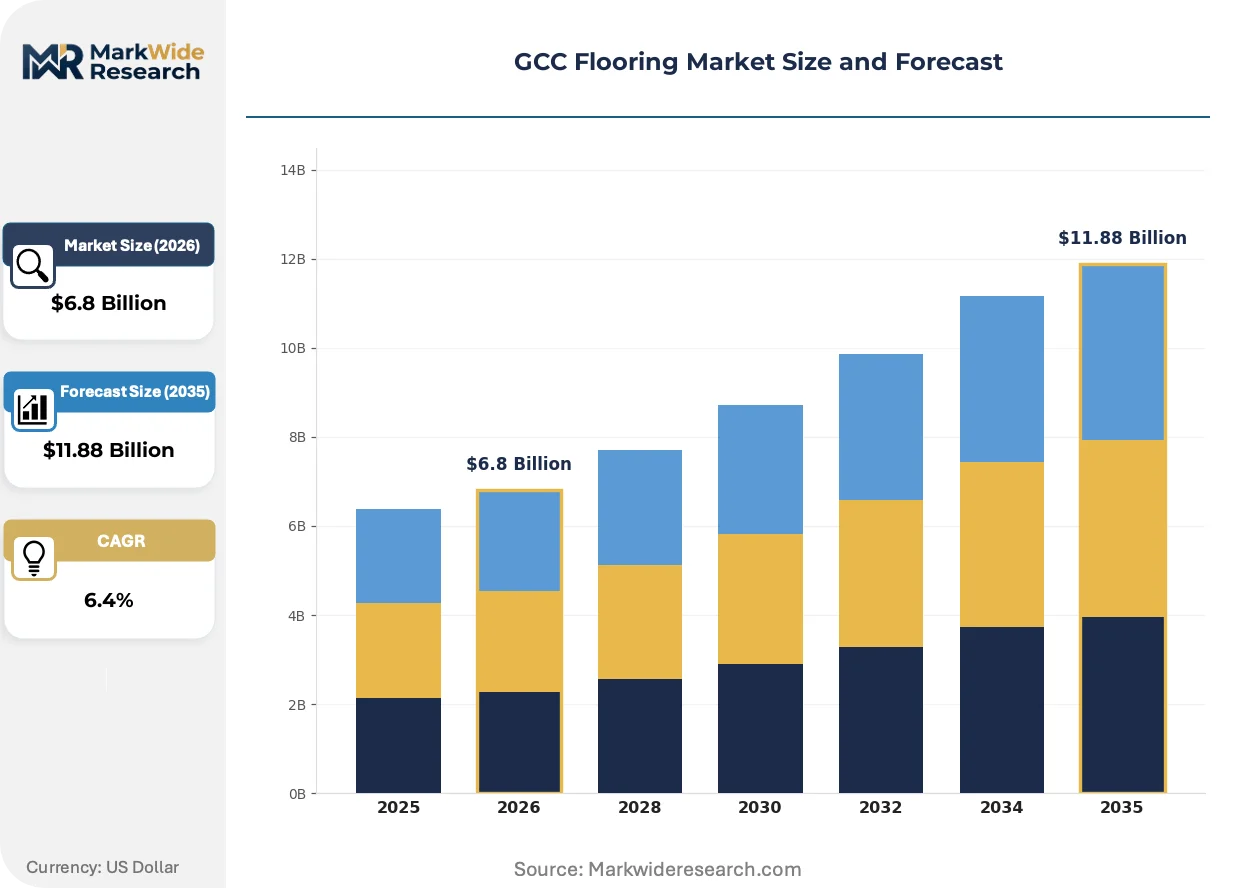
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laminated, Hardwood, Vinyl, Carpet Installation Method: Glue Down, Floating, Nail Down, Staple Down End User: Residential, Commercial, Industrial, Hospitality Distribution Channel: Online, Showroom, Wholesale, Retail |
| Companies Covered | Gerbur GmbH, AB Gustaf Kähr, RAK Ceramics, Al Sorayai Group, Floorworld LLC, Carpetland, Swiss Krono AG, Terrazzo, Swiss Hardwoods, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Flooring Market Strategic Shifts & Innovations
Material science advances and procurement digitization are compressing specification-to-installation cycles while regulatory tightening elevates performance-grade products over commodity alternatives.
Luxury vinyl tile with rigid core construction is miniaturizing wear-layer thickness tolerances while maintaining commercial-grade durability ratings. Hospitality developers in Dubai are specifying 2-4 mm rigid core products for rapid renovation cycles. This technology is miniaturizing the gap between vinyl cost efficiency and hardwood aesthetic authenticity.
ESMA volatile organic compound limits are forcing reformulation of adhesives and surface coatings across UAE-imported flooring products. Manufacturers serving Abu Dhabi and Dubai must now certify low-emission compliance prior to customs clearance. Commercial segments are responding by shifting specification toward pre-finished, click-lock systems that minimize on-site chemical application.
Architect-led procurement consolidation is displacing fragmented contractor purchasing in premium commercial and hospitality segments. Dubai-based specification firms now control material selection for multi-tower developments, compressing distributor influence. This concentration is most visible in Abu Dhabi's mega-project pipeline where single-source flooring packages dominate award structures.
GCC Flooring Market Segmentation
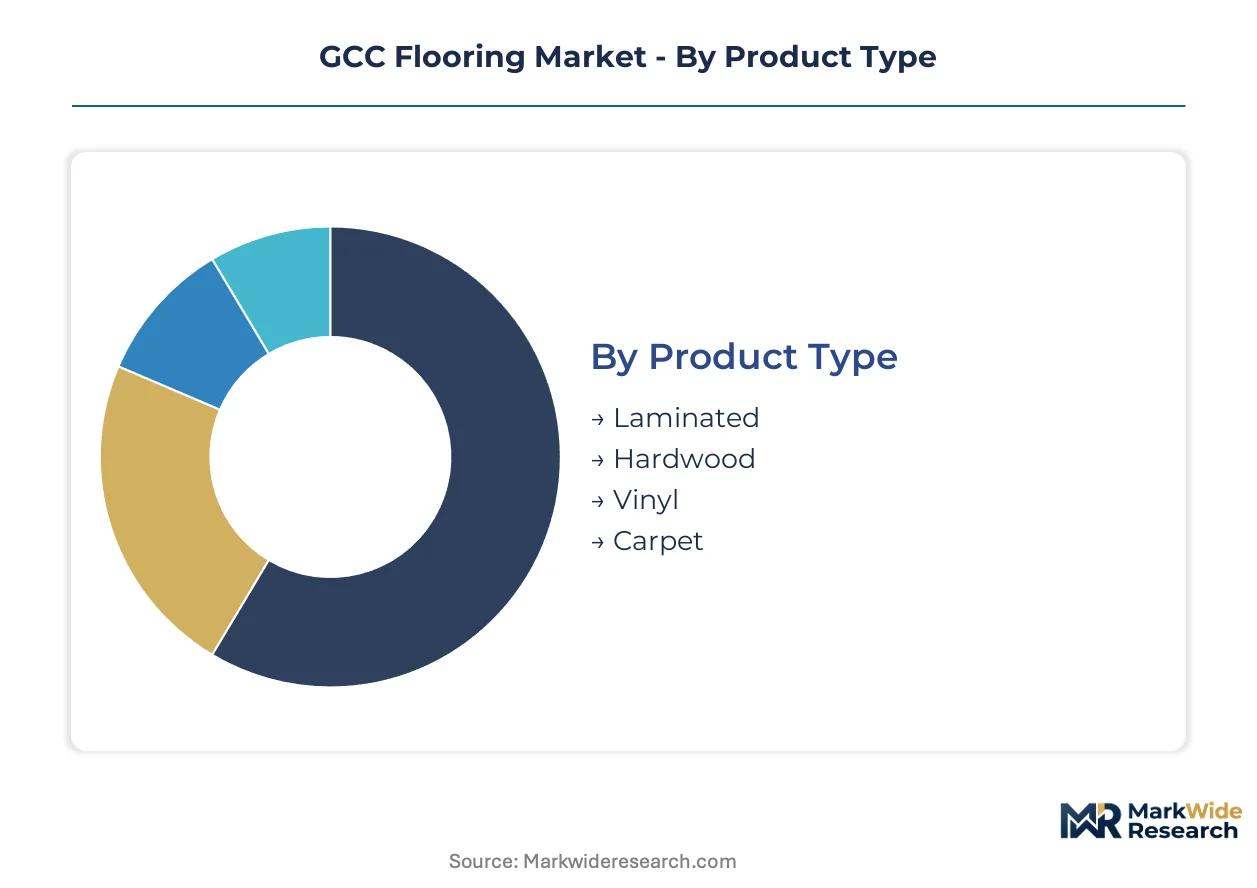
GCC flooring procurement operates through four distinct lenses that shape specification authority, margin capture, and project award structures across Saudi Arabia, the United Arab Emirates, Qatar, Kuwait, Bahrain, and Oman. Regulatory divergence between SASO and ESMA compliance regimes fragments product eligibility across these segment boundaries.
Product Type:
SASO fire-resistance classifications and ESMA volatile organic compound limits filter which surface materials qualify for cross-border trade within the GCC customs union, elevating certified products over commodity alternatives.
- Vinyl:Rigid core luxury vinyl tile with 2-4 mm wear layers dominates hospitality renovation cycles in Dubai due to moisture resistance and rapid installation protocols. Saudi Vision 2030 hotel pipelines in Riyadh and Jeddah are compressing specification timelines toward these surfaces.
- Hardwood:Thin-engineered products with 2-8 mm wear layers capture specification share from traditional laminate in Abu Dhabi mid-market residential towers. Natural material authenticity commands margin pools in luxury segments where thermal cycling durability under high-salinity conditions matters.
- Laminated:High-pressure laminate faces displacement pressure as price-competitive vinyl and engineered alternatives erode mid-tier residential positioning across the Gulf.
- Carpet:Commercial broadloom and modular tile persist in office and aviation segments where acoustic dampening requirements override hard-surface preferences in Doha and Manama.
Vinyl handles the majority of throughput in new commercial construction; hardwood is the fastest mover on share as engineered products miniaturize cost-aesthetic gaps.
Installation Method:
Cost tier differentiation separates premium certified crews from commodity labor pools, with scarcity in Saudi Arabia and Qatar inflating timelines for specialized systems.
- Floating:Click-lock and loose-lay systems minimize on-site chemical application, satisfying ESMA adhesive emission limits for UAE commercial projects. Pre-finished surfaces accelerate handover schedules in Dubai mega-developments.
- Glue Down:Full-spread adhesive installation demands certified moisture-barrier expertise that remains scarce across Riyadh and Jeddah construction markets. SASO compliance documentation for adhesive formulations adds procurement friction.
- Nail Down:Solid hardwood specification in luxury residential compounds across Kuwait City and Muscat relies on specialized subfloor preparation unavailable from generalist contractors.
- Staple Down:Engineered hardwood over plywood substrates persists in Bahrain villa construction where traditional methods align with established trade capacity.
Floating systems command the widest specification base; glue down is expanding most quickly as developers prioritize emission-compliant, rapid-install solutions.
End User:
Application concentration in hospitality and mega-project commercial segments concentrates procurement authority with architect-led specification firms in Dubai and Abu Dhabi.
- Hospitality:Dubai and Riyadh hotel developments specify rigid core vinyl and engineered surfaces for rapid renovation cycles and brand-standard durability under extreme occupancy turnover.
- Commercial:Office and retail towers across Doha's Lusail district and Abu Dhabi's Al Reem Island mandate slip-resistance ratings of R9-R11 for public circulation areas.
- Residential:Mid-market towers in Jeddah and Sharjah displace laminate with thin-engineered hardwood as price-performance positioning shifts.
- Industrial:Warehouse and logistics facilities in Saudi Arabia's King Abdullah Economic City prioritize chemical-resistant epoxy and polished concrete over decorative surfacing.
Hospitality directs the steepest volume trajectory; residential is gaining share fastest as engineered product accessibility expands.
Distribution Channel:
Customer type stratification separates specification-grade procurement controlled by architects from contractor-driven purchasing in volume segments.
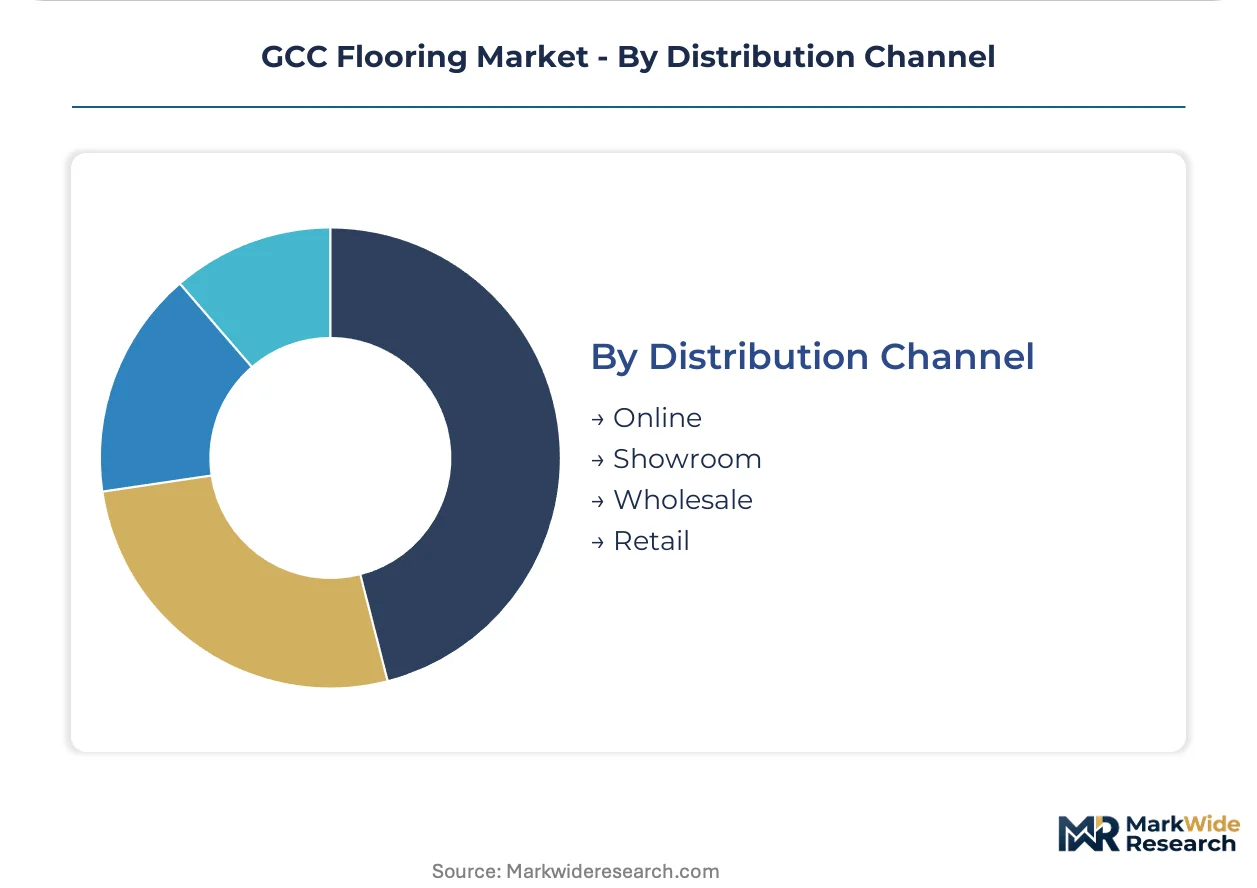
- Showroom:Dubai and Abu Dhabi specification hubs concentrate architect and interior designer decision-making, with Floorworld LLC and similar operators controlling material selection for multi-tower developments.
- Wholesale:Project-specific fabrication capabilities anchor supply to commercial and hospitality clients through Ras Al Khaimah integrated manufacturing bases.
- Retail:Fragmented contractor purchasing in residential renovation segments across smaller Gulf cities relies on inventory availability rather than specification authority.
- Online:Digital procurement platforms are migrating architect workflows in Dubai toward centralized showroom-to-project specification systems.
Showroom channels manage the dominant specification volume; online is climbing the fastest as digital workflows consolidate procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UAE concentrates specification authority for premium commercial and hospitality projects, while Saudi Arabia drives volume expansion through mega-project pipelines. Qatar and Kuwait maintain narrower but higher-margin segments. Oman and Bahrain absorb spillover supply from larger neighbors with distinct procurement patterns.
United Arab Emirates
Dubai's hospitality renovation cycles and Abu Dhabi's mega-project pipeline anchor regional consumption for rigid core vinyl and engineered surfaces. ESMA volatile organic compound limits filter imported product eligibility through customs clearance protocols. Specification firms in Dubai and Abu Dhabi control material selection for multi-tower developments through architect-led procurement consolidation.
Saudi Arabia
Riyadh and Jeddah hotel developments under Vision 2030 compress specification timelines toward rapid-install flooring systems. SASO fire-resistance classifications elevate certified local manufacturing capacity while filtering low-grade imports. King Abdullah Economic City industrial zones prioritize chemical-resistant surfacing for logistics facilities over decorative materials.
Qatar
Post-World Cup hospitality conversion of stadium-adjacent properties drives rapid flooring retrofit at scale in Doha and Lusail. The country's national standardization body enforces material performance benchmarks that shape procurement criteria. Lusail district office towers mandate slip-resistance ratings for public circulation areas.
Kuwait
Kuwait City luxury residential compounds sustain demand for solid hardwood specification requiring specialized subfloor preparation. National construction codes govern thermal performance standards that cascade into flooring system selection. Traditional trade capacity in villa construction segments supports staple-down engineered hardwood methods.
Oman
Muscat residential developments absorb thin-engineered hardwood displacement of laminate from price-competitive positioning shifts. The sultanate's building regulations adopt Gulf Cooperation Council technical harmonization with implementation lags. Smaller Gulf city procurement relies on inventory availability from UAE wholesale channels rather than specification authority.
GCC Flooring Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in GCC flooring supply. Ceramic and porcelain producers with captive manufacturing bases dominate volume segments, while showroom operators and distribution networks capture specification influence in premium commercial channels. Three archetypes prevail: integrated manufacturers with Ras Al Khaimah production bases, project-fabrication specialists serving hospitality clients, and specification-channel controllers in Dubai and Abu Dhabi. Competitive moves concentrate on geographic expansion through distribution partnerships and portfolio diversification into engineered surfaces.
Within the integrated manufacturing tier, RAK Ceramics anchors ceramic and porcelain supply through its Ras Al Khaimah production base. Al Sorayai Group exemplifies the project-fabrication specialist archetype through distribution networks serving commercial and hospitality segments. Floorworld LLC occupies the specification-channel controller position in Dubai and Abu Dhabi showroom markets where architect decisions concentrate.
| Leading Market Players |
|---|
| Gerbur GmbH |
| AB Gustaf Kähr |
| RAK Ceramics |
| Al Sorayai Group |
| Floorworld LLC |
| Carpetland |
| Swiss Krono AG |
| Terrazzo |
| Swiss Hardwoods |
| Others |
Cost & Logistics Intelligence
RAK Ceramics' Ras Al Khaimah manufacturing base exemplifies how captive production capacity anchors both supply concentration and price floors across ceramic and porcelain segments. Scale economies in integrated manufacturing compress per-unit costs while elevating barriers for import-dependent competitors facing ESMA compliance documentation and customs clearance friction.
Pricing Analysis
Project-based contract structures dominate premium commercial and hospitality segments where architect-led specification firms control material selection for multi-tower developments. Price differentiation rests on SASO fire-resistance certification tiers and wear-layer thickness specifications, with certified rigid core vinyl commanding premiums over commodity alternatives. Cost compression in mid-market residential tiers is intensifying as thin-engineered hardwood displaces traditional laminate. Contractor-driven retail channels exhibit highest price sensitivity, while specification-controlled showroom channels prioritize performance certification over unit economics.
Supply Chain Analysis
Inventory positioning and lead-time management concentrate around Ras Al Khaimah integrated manufacturing and UAE wholesale distribution hubs serving Saudi Arabia and Qatar construction markets. Raw material inputs draw from Gulf petrochemical complexes for vinyl resins, Southeast Asian timber suppliers for engineered hardwood cores, and European decorative paper mills for surface laminates. Single-source vulnerability runs through certified adhesive formulations subject to ESMA volatile organic compound limits. Distribution runs through Dubai and Abu Dhabi specification showrooms where architect decisions cascade into project-specific procurement.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation between SASO and ESMA compliance regimes creates structural white space for specialists capable of navigating dual certification pathways. Hospitality construction acceleration across Dubai and Riyadh fragments procurement authority between integrated manufacturers and niche specification-channel controllers.
For Market Incumbents: Compound showroom channel control in Dubai and Abu Dhabi through digital specification platform integration that captures architect workflow migration. Deepen captive manufacturing of emission-compliant adhesive systems to neutralize import dependency risks from ESMA regulatory tightening. Anchor position against thin-engineered hardwood substitution by accelerating rigid core vinyl wear-layer innovation cycles. For New Entrants and Emerging Players: SASO certification fast-track investment unlocks procurement eligibility for Saudi Vision 2030 hotel pipelines where certified installer scarcity has compressed project timelines. Target Qatar's post-World Cup hospitality conversion segment where rapid flooring retrofit demand outpaces established supply capacity. Pursue wholesale distribution partnerships with Ras Al Khaimah manufacturing bases to bypass showroom channel concentration. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specification-channel controllers with architect relationship networks over commodity manufacturing capacity. Long-term viability hinges on regulatory harmonization progress across GCC customs union technical reciprocity negotiations. Monitor ESMA-SASO certification convergence as inflection indicator for cross-border procurement consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Fast-Track Investment | SASO fire-resistance approval accelerates eligibility for Riyadh and Jeddah hospitality pipelines. |
| Digital Specification Platform Integration | Architect workflow capture in Dubai showrooms consolidates procurement authority for multi-tower developments. |
| Backward Integration into Adhesive Formulation | In-house production of ESMA-compliant bonding systems reduces import clearance friction and lead-time volatility. |
| Wholesale Distribution Partnership | Ras Al Khaimah manufacturing alliances bypass showroom channel concentration in smaller Gulf cities. |
| Certified Installer Training Program | Technical capacity building in Riyadh and Doha addresses scarcity inflating premium system labor costs. |
Research Approach
Operator-level perspectives from flooring procurement managers, architect specification leads, certified installation contractors, and hospitality development executives anchored the qualitative base. Secondary validation drew from SASO technical regulation filings, ESMA customs clearance protocols, Gulf Cooperation Council trade statistics, and project development databases across Dubai, Riyadh, and Doha. Bottom-up segment sizing triangulated with top-down construction expenditure tracking.
Sensitivity analysis tested forecast outputs against petrochemical feedstock volatility scenarios and regulatory harmonization acceleration cases across the projection horizon. Segmentation dimensions modeled include product type, installation method, end-use application, and distribution channel authority. CAGRs derived from construction pipeline tracking and specification trend analysis, with inputs from hospitality renovation cycle frequency and residential tower completion rates.
The analysis sits within stated boundaries; outcomes outside sustained Saudi Vision 2030 execution or ESMA regulatory stability would require recalibration. Forecasts reflect documented assumptions regarding certification reciprocity progress and installer training capacity expansion. Petrochemical input cost spikes or customs union fragmentation represent specific revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
China Floor Covering Market
Flooring, Carpets, and Rugs
Europe Carpet Tile Market
Flooring, Carpets, and Rugs
China Laminate Flooring Market
Flooring, Carpets, and Rugs
India Wood Flooring Market
Flooring, Carpets, and Rugs
GCC Floor Covering Market
Flooring, Carpets, and Rugs
United States Commercial Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
Turkey Carpet and Rugs Market
Flooring, Carpets, and Rugs
Entrance Matting Market
Flooring, Carpets, and Rugs
Carpet Floor Mats Market
Flooring, Carpets, and Rugs
North America Vinyl Flooring Market
Flooring, Carpets, and Rugs
United Kingdom Floor Covering Market
Flooring, Carpets, and Rugs
India Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Germany Flooring Market
Flooring, Carpets, and Rugs
Europe Laminate Flooring Market
Flooring, Carpets, and Rugs
Indoor Flooring Market
Flooring, Carpets, and Rugs
United States Laminate Flooring Market