
 United Kingdom Resilient Floor Covering Market | 2026-2036
United Kingdom Resilient Floor Covering Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Resilient Floor Covering Market Analytics
Buyer concentration among large property management groups and healthcare trusts is realigning procurement toward long-term maintenance contracts rather than spot purchases. Polyflor Ltd leverages its Manchester manufacturing base to dominate specification-led NHS projects. Tarkett S.A. competes through broad portfolio breadth across vinyl and rubber segments. James Halstead PLC anchors its position in transport and education sectors with specialized heavy-duty formulations.
Resilient floor covering comprises flexible surfacing materials—primarily vinyl, linoleum, rubber, and cork—engineered with wear layers between 0.3 mm and 0.7 mm and total thicknesses from 2.0 mm to 5.0 mm, manufactured through calendaring or extrusion processes to deliver impact absorption, acoustic dampening, and chemical resistance in high-traffic environments. Vinyl occupies the largest volume share due to cost efficiency and design versatility in commercial retrofits. Rubber commands premium positioning in healthcare and industrial settings where static control and slip resistance justify higher material outlays. The click-lock installation segment is gaining specification share as contractors prioritize speed and reduced subfloor preparation costs.
The UK Building Regulations Part M, BS EN 13845 safety flooring standards, and BSI Kitemark certification collectively mandate slip resistance, fire performance, and dimensional stability, filtering out uncertified imports and elevating compliance costs for market entrants. BSI scrutiny of environmental product declarations is intensifying under evolving UKCA marking requirements post-EU exit. Stakeholders must monitor specification shifts toward low-VOC and recycled-content formulations as public procurement frameworks embed stricter sustainability criteria.
Market Dynamics
UK Building Regulations Part M compliance pressure is forcing specification-grade safety flooring into standard commercial retrofits, compressing the price-performance gap between commodity vinyl and certified slip-resistant systems across healthcare, education, and transport infrastructure.
Growth Catalysts
- Healthcare infrastructure mandates:NHS estates teams specify BS EN 13845-certified safety flooring for all wet-area refurbishments, creating guaranteed volume pipelines through 2030.
- BSI Kitemark environmental scrutiny:Post-EU UKCA marking requirements now embed recycled-content thresholds, pulling forward renovation cycles in public procurement frameworks.
- London commercial density:Grade A office refurbishment activity in the capital and South East concentrates demand for acoustic-dampening luxury vinyl tile installations.
Market Restraints
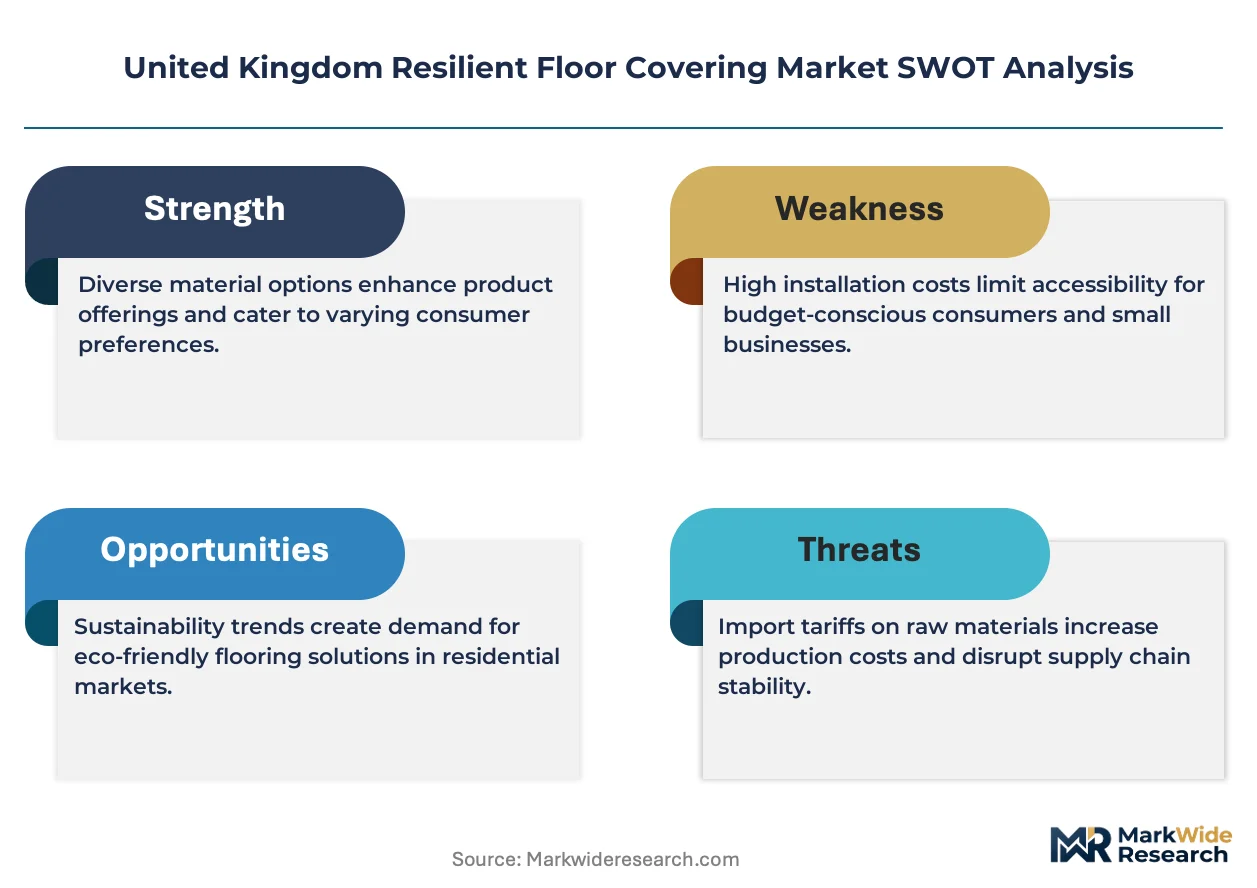
- Petrochemical input volatility:PVC resin and plasticizer costs fluctuate with crude oil indices, compressing margin visibility for calendaring-dependent manufacturers.
- Single-source supply risk:Wear-layer polymer additives concentrate among German and Dutch specialty chemical suppliers, exposing UK converters to Brexit-related customs friction.
- Linoleum substitution ceiling:Natural material alternatives face raw material constraints (linseed oil, cork flour) that limit scale beyond boutique commercial niches.
Strategic Opportunities
- North England manufacturing revival:Regional development funds in Greater Manchester and Yorkshire support reshoring of extrusion capacity to serve Scottish healthcare trusts.
- Click-lock installation penetration:Floating floor systems reduce subfloor preparation costs by 40% versus fully adhered methods, opening mid-market residential and SME commercial segments.
- Net-zero public procurement:Crown Commercial Service frameworks now weight embodied carbon scores, advantaging domestic producers with verified Environmental Product Declarations.
Industry Challenges
- Installer certification bottlenecks:BS 8203 moisture-testing and adhesive-application standards require specialized training that outpaces contractor workforce expansion.
- UKCA transition complexity:Dual-running of CE and UKCA marking systems through 2024-2025 creates documentation duplication and testing cost inflation for import-dependent distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Resilient Floor Covering Market |
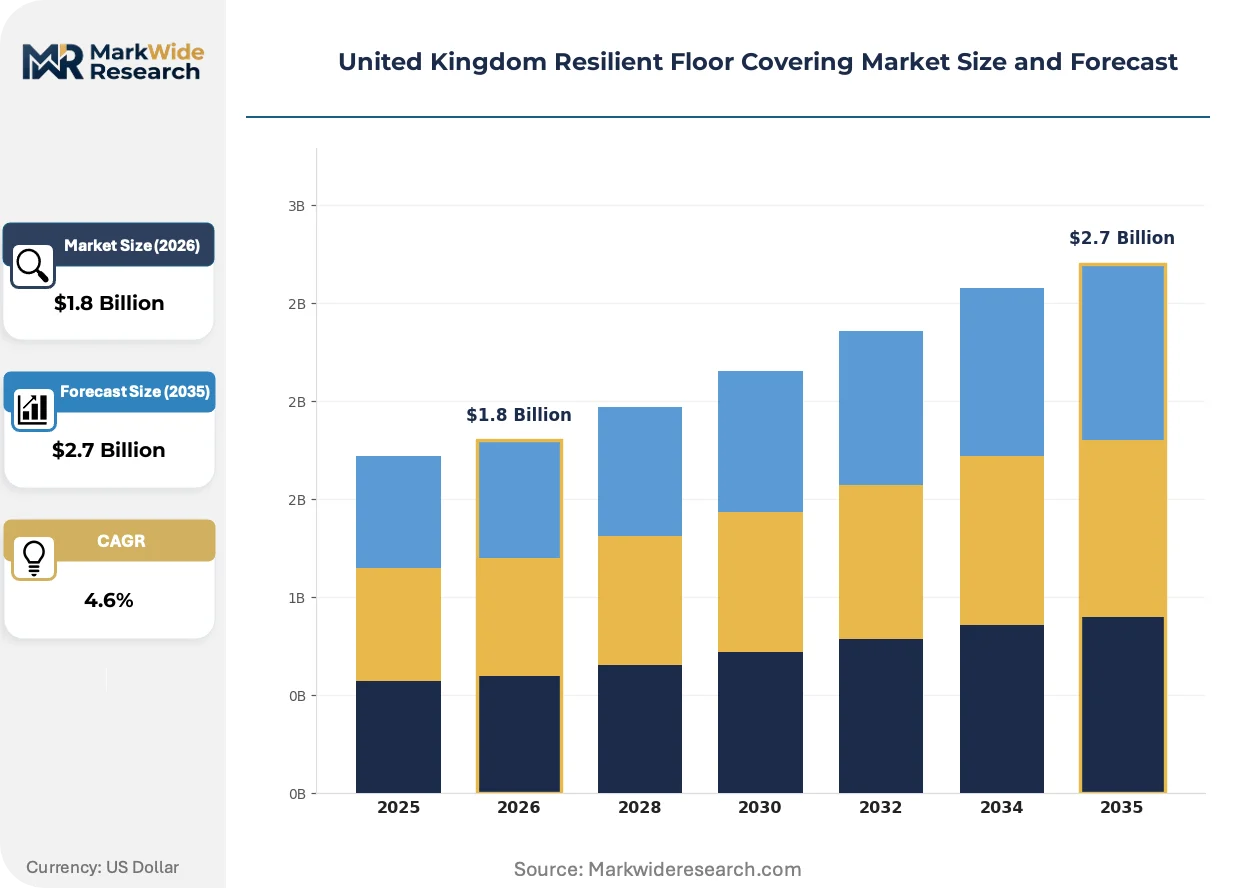
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinyl, Linoleum, Rubber, Cork Application: Residential, Commercial, Institutional, Industrial Installation Method: Glue-down, Loose-lay, Click-lock, Self-adhesive End User: Homeowners, Businesses, Contractors, Property Managers |
| Companies Covered | Polyflor Ltd, Tarkett S.A., Forbo Flooring Systems, Gerflor Ltd, Nora Systems GmbH, James Halstead PLC, Amtico, Milliken, Victoria PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Resilient Floor Covering Market Evolving Landscape
Digital specification tools and embedded sensor technologies are rewiring how architects, contractors, and facilities managers evaluate flooring performance across lifecycle cost, carbon intensity, and maintenance burden rather than upfront material price alone.
Photoluminescent egress path marking is converging with resilient sheet vinyl substrates to create integrated safety flooring systems for transport and healthcare corridors. Transport for London mandates these systems in Underground station refurbishments, compressing procurement cycles by embedding dual-function specifications into single-source contracts. The technology is converging with standard safety flooring procurement, eliminating the separate specification of adhesive-applied strips.
BS EN 13845:2022 slip-resistance testing protocols now mandate pendulum and ramp test dual certification, tightening the filter on uncertified imports. UK-based testing houses report 18-month backlogs for new product validation, forcing smaller distributors to abandon specification-grade segments. Healthcare estates teams in England and Wales delay project starts rather than accept untested alternatives, concentrating volume among pre-certified incumbent suppliers.
Facilities management consortia now bundle flooring maintenance into 10-year service contracts rather than capital-only purchases, unbundling installation from lifecycle performance guarantees. Interserve and Mitie frameworks lead this shift in NHS and Ministry of Defence estates. The model concentrates buying power among four national FM providers, marginalizing spot-market distributors in London and Birmingham commercial corridors.
United Kingdom Resilient Floor Covering Market Segmentation
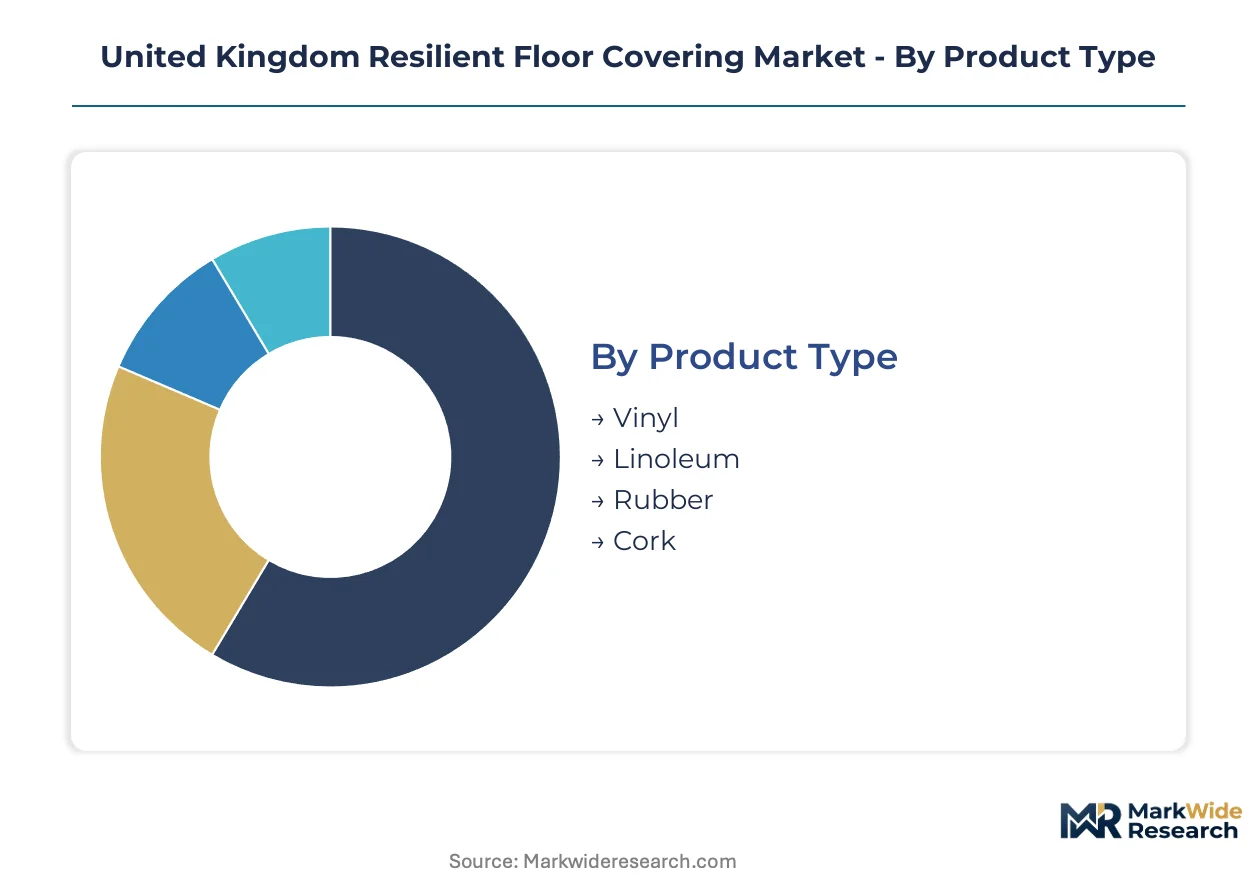
Segmentation in the UK resilient floor covering market reveals how specification-grade requirements diverge sharply from commodity procurement. Each dimension—material chemistry, installation physics, and buyer archetype—creates distinct margin pools and compliance burdens that reshape competitive positioning.
Product Type:
Supply concentration among domestic calendaring specialists tilts specification power toward vinyl and rubber formulations with verified UKCA marking.
- Vinyl:PVC-based compositions with wear layers from 0.3 mm to 0.7 mm dominate specification-led NHS and education refurbishments through cost efficiency and design versatility. London and South East commercial retrofits concentrate volume for luxury vinyl tile formats where acoustic dampening commands premium positioning.
- Rubber:Synthetic and natural rubber compounds deliver static control and slip resistance for healthcare wet areas and industrial settings. BS EN 13845 compliance mandates concentrate demand in NHS estates and Transport for London infrastructure where safety flooring justifies material outlays above commodity vinyl.
- Linoleum:Bio-based linseed oil and cork flour compositions face raw material constraints that limit manufacturing scale to boutique commercial niches in heritage building refurbishments.
- Cork:Renewable bark-derived surfacing occupies premium residential and wellness-focused commercial segments where acoustic and thermal properties offset higher unit costs.
Today's leader: Vinyl. Tomorrow's challenger: Rubber.
Application:
Cost tier stratification separates capital-intensive institutional mandates from discretionary residential spending and cyclical industrial investment.
- Commercial:Grade A office refurbishment in London and South East drives luxury vinyl tile specification where acoustic performance and rapid installation reduce tenant downtime. Crown Commercial Service frameworks embed recycled-content thresholds that filter procurement toward domestic producers with verified Environmental Product Declarations.
- Institutional:NHS estates, Ministry of Defence facilities, and education authorities mandate BS EN 13845-certified safety flooring through 10-year maintenance contracts. Interserve and Mitie frameworks bundle installation with lifecycle performance guarantees, concentrating buying power among four national FM providers.
- Residential:Home renovation demand concentrates in click-lock floating systems that reduce subfloor preparation costs by 40 percent versus fully adhered methods.
- Industrial:Heavy-traffic manufacturing and logistics facilities specify rubber and specialized vinyl formulations where chemical resistance and impact absorption justify premium material selection.
Institutional mandates anchor volume stability. Commercial retrofits offer the steepest expansion trajectory as Grade A office cycles recover.
Installation Method:
Volume concentration in glue-down specification-grade contracts contrasts with emerging click-lock penetration in cost-sensitive mid-market segments.
- Glue-down:Fully adhered application dominates healthcare, transport, and heavy commercial settings where dimensional stability and seamless hygiene surfaces are non-negotiable. BS 8203 moisture-testing and adhesive-application standards require specialized contractor certification that creates installer bottlenecks.
- Click-lock:Floating floor systems with mechanical locking edges reduce installation labor and subfloor preparation requirements. SME commercial and residential segments in Manchester and Birmingham corridors adopt these systems where speed-to-occupancy outweighs long-term durability premiums.
- Loose-lay:Friction-based installation without adhesive suits temporary retail and exhibition spaces requiring rapid deployment and removal cycles.
- Self-adhesive:Pressure-sensitive backing targets DIY residential and light commercial refurbishment where professional contractor availability is constrained.
Glue-down retains specification dominance. Click-lock gains share fastest in mid-market disruption.
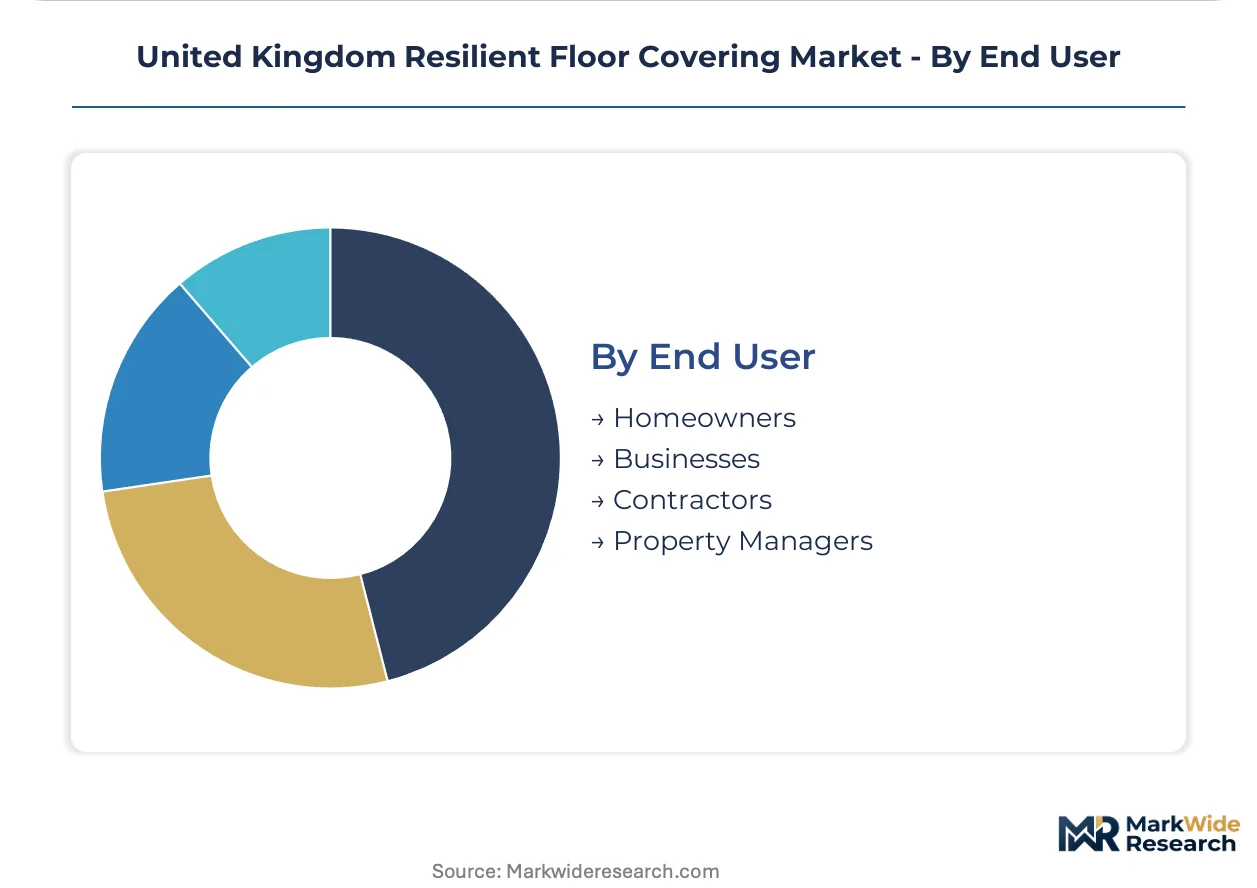
End User:
Customer type determines procurement rhythm: long-cycle framework contracts versus spot-market spot purchases versus project-bid volatility.
- Property Managers:Large estates consortia and healthcare trusts realign procurement toward 10-year maintenance contracts with lifecycle performance guarantees. Crown Commercial Service frameworks weight embodied carbon scores, advantaging domestic producers with verified supply chain transparency.
- Contractors:Installation specialists face certification backlogs for BS 8203 moisture-testing standards that outpace workforce expansion, creating capacity constraints in London and South East corridors.
- Businesses:Corporate occupiers in Grade A office refurbishments prioritize acoustic dampening and rapid installation to minimize tenant downtime.
- Homeowners:Discretionary renovation demand concentrates in click-lock luxury vinyl tile where design versatility and DIY accessibility offset durability trade-offs.
Property managers consolidate buying power. Contractors face capability scarcity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Installer certification networks concentrate in Greater London and the South East, anchoring specification-grade capacity where NHS trusts and commercial property managers cluster procurement decisions.
London and South East
Grade A office refurbishment drives luxury vinyl tile demand where acoustic dampening reduces tenant downtime. Crown Commercial Service frameworks embed recycled-content thresholds that filter procurement toward domestic producers. The M25 corridor hosts the densest concentration of BS 8203-certified contractors serving healthcare and transport infrastructure.
Midlands
Manufacturing heritage supports calendaring and extrusion capacity for vinyl and rubber formulations. Regional development funds target reshoring of wear-layer polymer processing to reduce import dependency. Birmingham and Coventry corridors concentrate distribution hubs serving education and Ministry of Defence estates.
North England
Greater Manchester anchors specification-led NHS projects through domestic manufacturing presence. Scottish healthcare trusts source through northern distribution networks to minimize logistics costs. Yorkshire development zones support click-lock floating system production for residential and SME commercial segments.
Scotland
NHS Scotland estates teams mandate BS EN 13845-certified safety flooring for all wet-area refurbishments. The country's building standards integrate UKCA marking requirements with additional thermal performance criteria. Glasgow and Edinburgh corridors concentrate installer training facilities addressing certification backlogs.
Wales
Public procurement frameworks align with English NHS standards while embedding additional Welsh language accessibility requirements in wayfinding-integrated flooring systems. Cardiff and Newport commercial corridors drive specification demand for photoluminescent egress path marking in transport infrastructure. The Welsh Government's construction procurement policy weights embodied carbon scores in resilient surfacing selection.
United Kingdom Resilient Floor Covering Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across specification-grade and commodity segments. The vendor base clusters into three archetypes: domestic calendaring specialists with verified UKCA marking, European rubber and linoleum fabricators with heritage positioning, and diversified flooring conglomerates with portfolio breadth across vinyl, rubber, and textile-backed systems. Competitive moves center on backward integration into wear-layer polymer supply and strategic partnerships with facilities management consortia for 10-year maintenance contract capture.
Among UK-anchored manufacturers, Polyflor Ltd exemplifies the domestic specification specialist archetype through its Manchester manufacturing base. Tarkett S.A. represents the diversified conglomerate model with portfolio coverage across vinyl and rubber segments. James Halstead PLC occupies a position within the transport and education-focused specialist tier. These three entities collectively illustrate how geographic anchoring, material chemistry focus, and end-use specialization segment competitive positioning.
| Leading Market Players |
|---|
| Polyflor Ltd |
| Tarkett S.A. |
| Forbo Flooring Systems |
| Gerflor Ltd |
| Nora Systems GmbH |
| James Halstead PLC |
| Amtico |
| Milliken |
| Victoria PLC |
| Others |
Value Network & Pricing Analysis
PVC resin and plasticizer costs fluctuate with crude oil indices, compressing margin visibility for calendaring-dependent manufacturers and forcing tiered pricing separation between specification-grade safety flooring and commodity vinyl across NHS estates, London commercial retrofits, and education frameworks.
Pricing Analysis
The bundled-vs-unbundled service split distinguishes capital-only spot purchases from 10-year maintenance contracts with lifecycle performance guarantees. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with BS EN 13845-certified safety flooring commanding material outlays above commodity vinyl. Pricing pressure stems from petrochemical input volatility and installer certification bottlenecks. Healthcare trusts and Crown Commercial Service frameworks show least price sensitivity due to mandated compliance, while SME commercial segments and residential renovators prioritize click-lock systems where speed-to-occupancy outweighs durability premiums.
Supply Chain Analysis
Direct-to-contractor channels handle specification-grade healthcare and transport infrastructure demand, while distributor networks serve spot-market commercial retrofits. Wear-layer polymer additives concentrate among German and Dutch specialty chemical suppliers, exposing UK converters to Brexit-related customs friction. PVC resin, plasticizers, and cork flour constitute critical raw material dependencies. Single-source supply risk for polymer additives creates vulnerability to documentation duplication under dual-running CE and UKCA marking systems. Distribution runs through Manchester manufacturing bases serving northern NHS trusts and London-South East commercial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom resilient floor covering market functions as a geographic-arbitrage play where Greater Manchester manufacturing costs undercut continental European imports while satisfying Crown Commercial Service embodied carbon thresholds that exclude uncertified overseas suppliers.
For Market Incumbents: Deepen backward integration into wear-layer polymer processing to reduce German and Dutch supplier dependency. Capture Scottish healthcare trust volume through northern distribution network expansion. Counter click-lock disruption by bundling specification-grade installation with 10-year maintenance guarantees that lock out spot-market competitors. For New Entrants and Emerging Players: Enter via photoluminescent egress path marking convergence with standard safety flooring substrates, where Transport for London mandates create guaranteed procurement pipelines. Target Welsh transport infrastructure and Cardiff commercial corridors where accessibility-integrated flooring requirements filter competition. Pursue BSI Kitemark certification early to avoid 18-month validation backlogs that exclude specification-grade segments. For Investors and Strategic Acquirers: Consolidation pressure builds where installer certification bottlenecks outpace contractor workforce expansion, concentrating specification-grade capacity among pre-certified incumbents. Five-to-ten year viability favors domestic calendaring specialists with verified UKCA marking and Crown Commercial Service framework access. Monitor Crown Commercial Service recycled-content threshold adjustments as inflection indicators for renovation cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Additives | Captive supply of wear-layer formulations reduces German-Dutch supplier dependency and Brexit customs exposure. |
| Click-Lock Floating System Expansion | Mechanical locking edges open Manchester and Birmingham SME commercial segments with 40% subfloor preparation cost reduction. |
| BSI Kitemark Certification Investment | Pre-certified status bypasses 18-month testing house backlogs that filter out specification-grade competitors. |
| Facilities Management Partnership | Interserve and Mitie framework alignment bundles installation with lifecycle guarantees, marginalizing spot-market distributors. |
| Photoluminescent Egress Integration | Dual-function substrates satisfy Transport for London Underground mandates while compressing procurement cycles. |
Research Methodology
Bottom-up NHS estates and commercial refurbishment modeling reconciled against top-down calendaring capacity and import volume tracking forms the analytical core. Primary interviews with facilities management procurement directors, BS 8203-certified installation contractors, Crown Commercial Service framework managers, and polymer additive procurement leads combined with secondary validation against UK Building Regulations compliance databases, BSI certification registries, NHS estates refurbishment pipelines, and Crown Commercial Service procurement disclosures. Triangulation across these sources anchors volume and value estimates.
The input-output matrix framing maps PVC resin and plasticizer cost indices against specification-grade and commodity tier demand across vinyl, rubber, linoleum, and cork chemistries. Segmentation dimensions include material chemistry, installation physics, application vertical, and end-user procurement archetype. CAGRs derive from elasticity-adjusted demand curves and replacement cycle modeling. Key forecast inputs encompass NHS wet-area refurbishment mandates and London Grade A office acoustic dampening specifications.
Inputs from BSI certification registries and Crown Commercial Service framework disclosures were available through the study window; gaps in real-time polymer additive inventory levels introduce uncertainty bands around margin compression estimates. Periodic stress-testing of base assumptions is recommended against UKCA marking transition timelines and NHS capital allocation revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Wall Art Market
Homecare and Decor
Wall Covering Products Market
Homecare and Decor
Bulletin Board Market
Homecare and Decor
Fragrant Drawer Liners Market
Homecare and Decor
Garden Sheds Market
Homecare and Decor
Europe Mattress Market
Homecare and Decor
US Wallcovering Market
Homecare and Decor
Bookends Market
Homecare and Decor
Middle East and Africa Christmas Tree Market
Homecare and Decor
US Steam Rooms Market
Homecare and Decor
United States Wall Coverings Market
Homecare and Decor
France Steam Rooms Market
Homecare and Decor
USA Bed Pillow Market
Homecare and Decor
India Wall Decor Market
Homecare and Decor
India Sustainable Home Decor Market
Homecare and Decor
Asia-Pacific Wall Covering Market