
 Wood Plastic Composite (WPC) Floorings Market | 2026-2036
Wood Plastic Composite (WPC) Floorings Market Size, Share, and Industry Trends Forecast 2026-2036
Wood Plastic Composite (WPC) Floorings Market Analytics
California Title 24 is decoupling energy-efficient building material requirements from conventional flooring cost structures, forcing manufacturers to certify thermal performance at higher specification tiers. Trex Company Inc. leverages its captive recycled polyethylene supply chain to control raw material volatility across production cycles. AZEK sustains premium positioning through capped-product chemistry that resists moisture ingress in humid climates. Anhui Sentai WPC Group anchors export volume to North American distributors with cost-optimized uncapped formulations.
Wood plastic composite flooring combines thermoplastic resins—typically high-density polyethylene or polypropylene—with wood flour or cellulose fibers at ratios between 50:50 and 70:30, extruded into boards with embossed grain surfaces that replicate timber aesthetics while eliminating rot susceptibility. Capped products command margin premiums for their enhanced UV stability and stain resistance in commercial applications, whereas uncapped variants dominate residential renovation budgets where first cost governs selection. Click-lock installation systems are displacing glue-down methods in the residential channel as floating-floor convenience reduces contractor labor hours and homeowner disruption.
The EPA regulates volatile organic compound emissions from composite wood products under TSCA Title VI, while the EU ECHA enforces REACH restrictions on phthalate plasticizers that historically softened WPC core layers. Homeowners, architects, and developers must now track evolving per- and polyfluoroalkyl substance restrictions that threaten stain-resistant capstock chemistries. Stakeholders should monitor regulatory divergence between US and European chemical safety frameworks when configuring product portfolios for cross-border distribution.
Market Dynamics
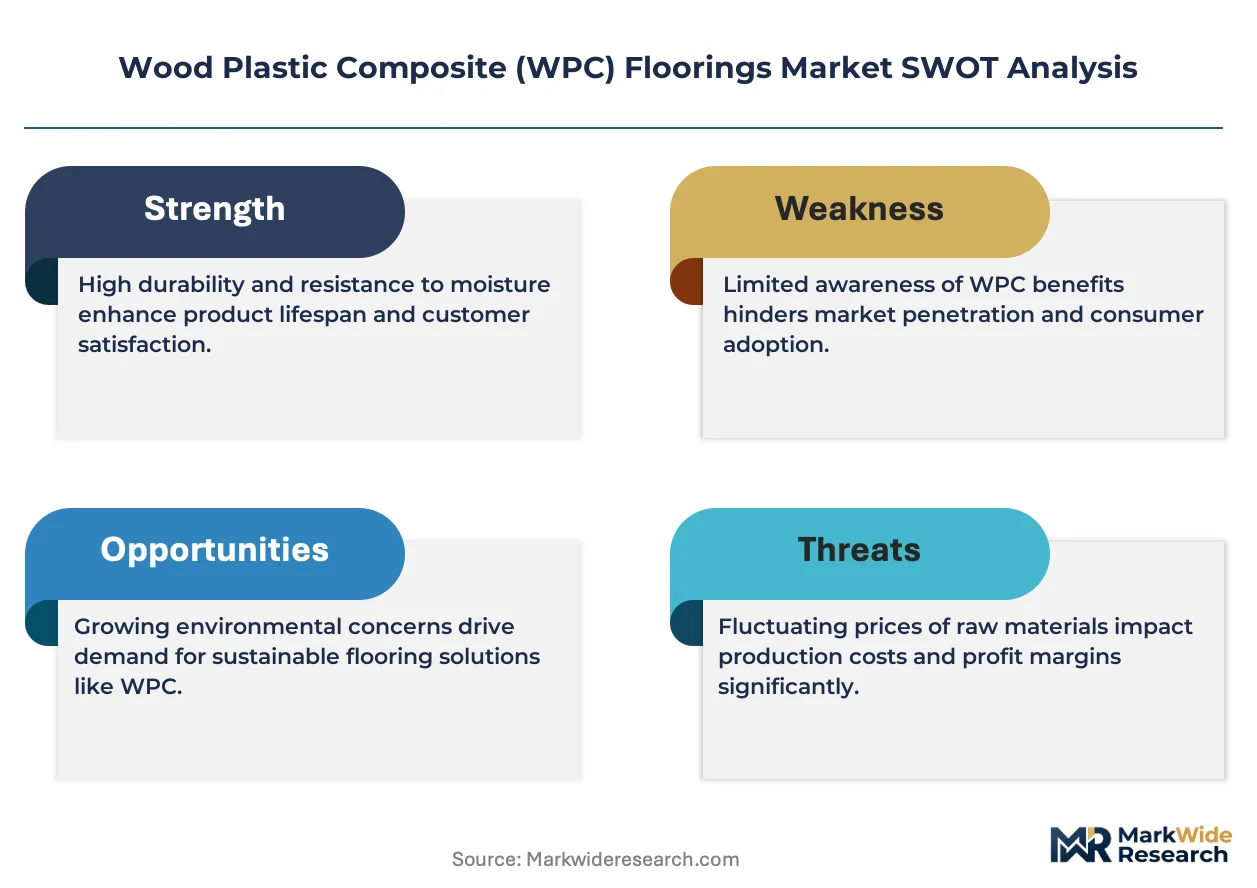
Moisture-resistant alternatives are displacing traditional hardwood in residential renovation, driven by coastal humidity concerns and termite resistance requirements that reshape specification decisions across North American and European distribution channels.
Growth Catalysts
- California Title 24 thermal performance mandates:Building efficiency standards force manufacturers to certify flooring at higher specification tiers, expanding addressable market for compliant WPC products.
- Click-lock floating floor systems:Installation technology reduces contractor labor hours and homeowner disruption, accelerating residential channel adoption over glue-down methods.
- EU REACH chemical restrictions:Phasing out legacy phthalate plasticizers creates competitive opening for WPC formulations with compliant core chemistries.
Market Restraints
- Recycled polyethylene supply concentration:Captive supply chains at major producers limit independent manufacturers' access to cost-stable raw material inputs.
- Per- and polyfluoroalkyl substance restrictions:Emerging chemical safety frameworks threaten stain-resistant capstock formulations in both US and European markets.
- Uncapped product commoditization:Cost-optimized formulations from export-oriented producers compress margin structures for mid-tier manufacturers.
Strategic Opportunities
- Commercial specification expansion:Capped product UV stability and stain resistance open hospitality and retail fit-out segments beyond residential renovation.
- EU Green Deal circular economy requirements:Recycled content mandates create demand pull for post-consumer plastic feedstock integration.
- Direct-to-contractor digital channels:Bypassing traditional distributor markups captures margin while reducing specification friction for small renovation projects.
Industry Challenges
- TSCA Title VI certification timelines:EPA volatile organic compound testing protocols extend product launch cycles and increase compliance documentation burden.
- Extrusion equipment specialization:Capital-intensive co-extrusion lines for capped products require significant upfront investment, constraining capacity expansion for emerging players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood Plastic Composite (WPC) Floorings Market |
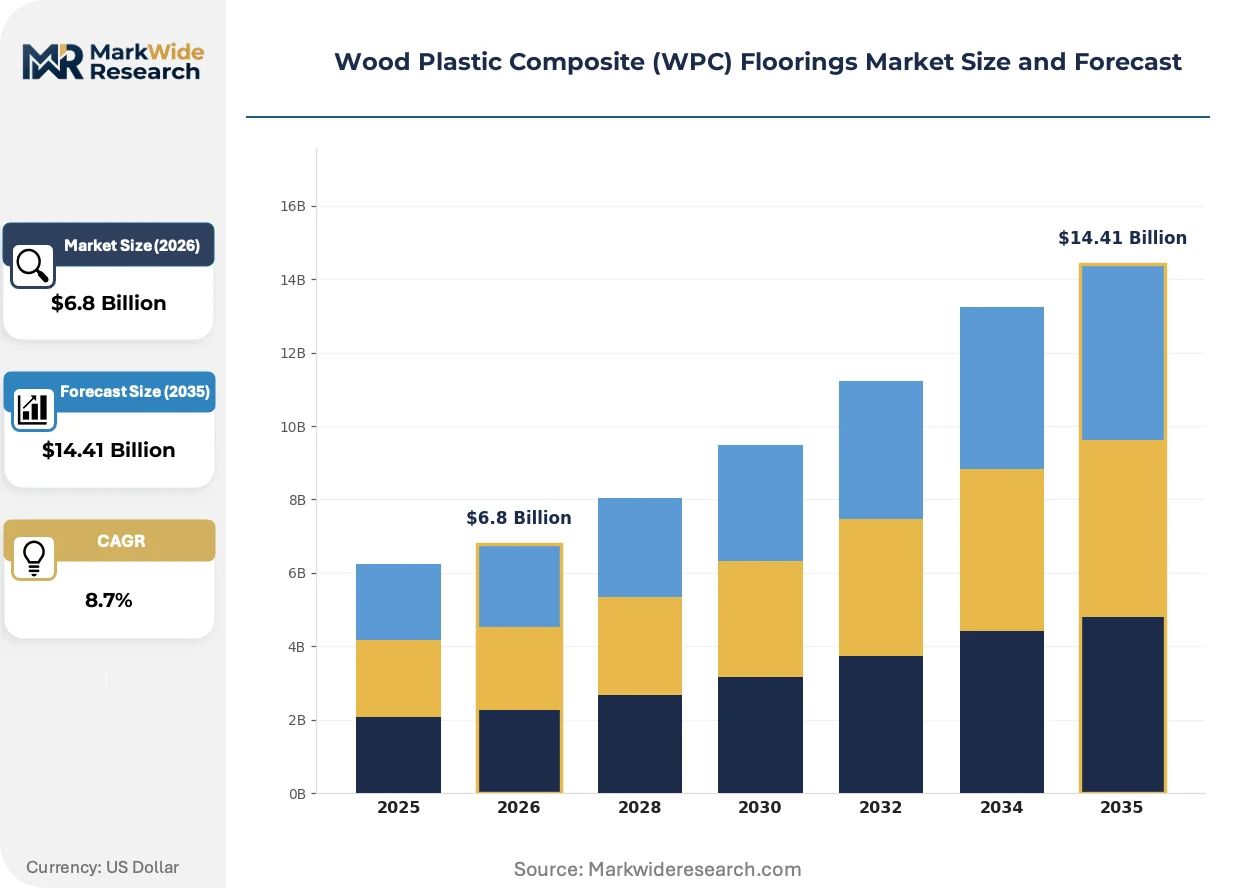
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Uncapped, Capped, Composite, Hybrid Application: Residential, Commercial, Industrial, Outdoor Installation Method: Glue-down, Click-lock, Nail-down, Loose-lay End User: Contractors, Homeowners, Architects, Developers |
| Companies Covered | Trex Company Inc., Armstrong Flooring Inc., The AZEK Company Inc., Fiberon, UFP Industries Inc., Mannington Mills Inc., Spectra Contract Flooring, Parterre Flooring Systems, Anhui Sentai WPC Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood Plastic Composite (WPC) Floorings Market Evolving Landscape
Material science advances and installation system evolution are compressing traditional flooring procurement cycles while expanding WPC addressable market into moisture-sensitive applications previously dominated by tile and vinyl.
Co-extrusion capstock technology applies a protective polymer shell over WPC cores, delivering enhanced UV stability and stain resistance. Commercial architects in hospitality and retail sectors specify these products for high-traffic areas previously reserved for porcelain or LVT. This performance tier is electrifying specification conversations, compressing the traditional premium flooring decision hierarchy.
EPA TSCA Title VI enforcement tightens volatile organic compound emission limits for composite wood products, extending testing and certification requirements to WPC substrates. Manufacturers must maintain third-party certification through accredited laboratories. California Air Resources Board maintains parallel standards that exceed federal thresholds, forcing dual compliance tracks for products entering that state.
Home renovation contractors increasingly source materials through integrated digital platforms that bundle specification tools, quantity takeoff software, and direct fulfillment. Traditional two-step distribution through building material dealers loses share in residential renovation projects under five thousand square feet. This channel migration concentrates most visibly in Florida and Gulf Coast states where humidity-driven WPC demand intersects with contractor technology adoption.
Wood Plastic Composite (WPC) Floorings Market Segmentation
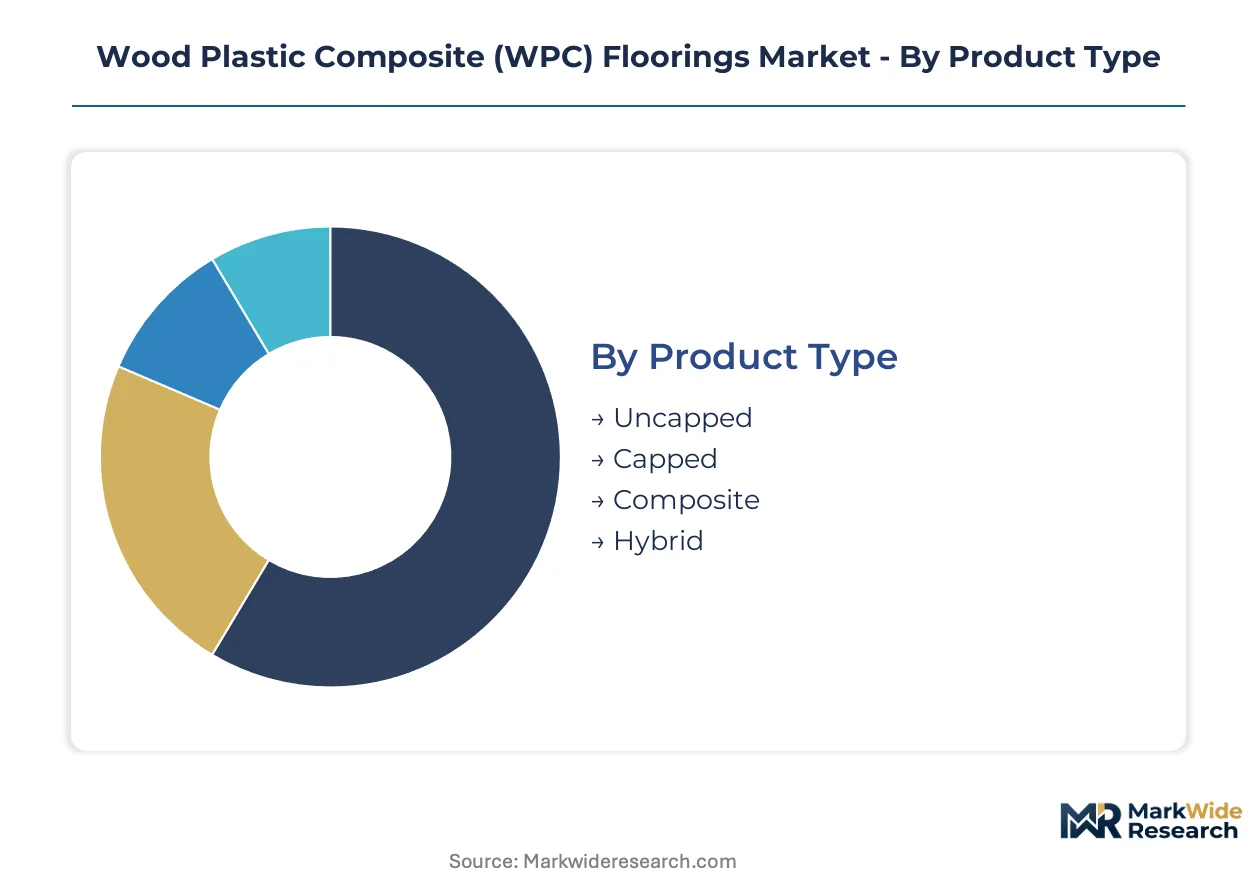
WPC flooring segmentation reveals how certification burdens, installation complexity, and end-user sophistication stratify demand across product tiers. Each dimension carries distinct regulatory and procurement implications that reshape competitive positioning.
Product Type:
EPA TSCA Title VI and California Air Resources Board certifications apply differentially across product tiers, with capped formulations facing extended testing timelines for volatile organic compound compliance.
- Capped:Co-extruded polymer shell encapsulates WPC core, delivering UV stability and stain resistance for high-traffic commercial specifications. Demand concentrates in coastal United States states where humidity degradation threatens uncapped alternatives, with hospitality fit-out projects driving specification volume.
- Uncapped:Single-extrusion boards without protective capstock trade durability for cost accessibility in residential renovation channels. Cost-optimized formulations from export-oriented producers dominate distributor procurement in price-sensitive Midwest and Southern United States markets.
- Composite:Standard WPC formulations with balanced wood-plastic ratios serve mid-tier residential replacement cycles.
- Hybrid:Multi-material constructions incorporating mineral fillers target specialized acoustic or thermal performance requirements.
Capped sits at the top of the volume ranking, with Hybrid climbing the fastest.
Application:
Cost tier stratification separates premium commercial specifications from economy residential renovations, with installation labor intensity driving total project economics.
- Residential:Homeowners prioritize moisture resistance and click-lock convenience over premium aesthetics in basement and bathroom renovations. Coastal United States markets from Florida to California anchor volume as humidity concerns displace traditional hardwood.
- Commercial:Retail and hospitality architects specify capped products for warranty-backed durability in high-traffic environments. LEED certification requirements in California and New York drive specification toward recycled-content formulations.
- Industrial:Chemical resistance and load-bearing specifications dominate warehouse and manufacturing facility procurement.
- Outdoor:Decking and patio applications require enhanced UV stabilization and drainage channel engineering.
Residential commands the largest installed base, with Commercial gaining share fastest.
Installation Method:
Customer type differentiation separates professional contractor channels from DIY homeowner purchases, with skill requirements and tool access governing method selection.
- Click-lock:Floating floor systems eliminate adhesive curing time and permit rapid reinstallation, reducing contractor labor hours by half versus glue-down alternatives. United States residential renovation contractors in Florida and Texas have standardized procurement around this method for projects under five thousand square feet.
- Glue-down:Permanent adhesion delivers acoustic dampening and subfloor stability for commercial specifications with heavy rolling loads. Industrial applications in manufacturing facilities specify this method for vibration resistance.
- Nail-down:Traditional fastening over wood subfloors persists in upper-tier residential renovations seeking authentic hardwood feel.
- Loose-lay:Friction-based installation enables rapid deployment and removal for temporary retail and event flooring.
Click-lock dominates contractor procurement, with Loose-lay expanding most quickly in temporary commercial applications.
End User:
Margin structure varies dramatically across decision-maker sophistication, with architects and developers commanding specification authority that homeowners and small contractors cannot access.
- Contractors:Small renovation firms source through emerging digital platforms that bundle quantity takeoff software with direct fulfillment, bypassing traditional distributor markups. Gulf Coast United States contractors show highest platform adoption rates where humidity-driven WPC demand intersects with technology uptake.
- Architects:Commercial specification gatekeepers prioritize capped product warranties and third-party certifications for liability protection in hospitality and retail portfolios.
- Homeowners:First-cost sensitivity dominates uncapped product selection in big-box retail channels.
- Developers:Multi-family construction volume purchasers negotiate direct manufacturer relationships for standardization across project portfolios.
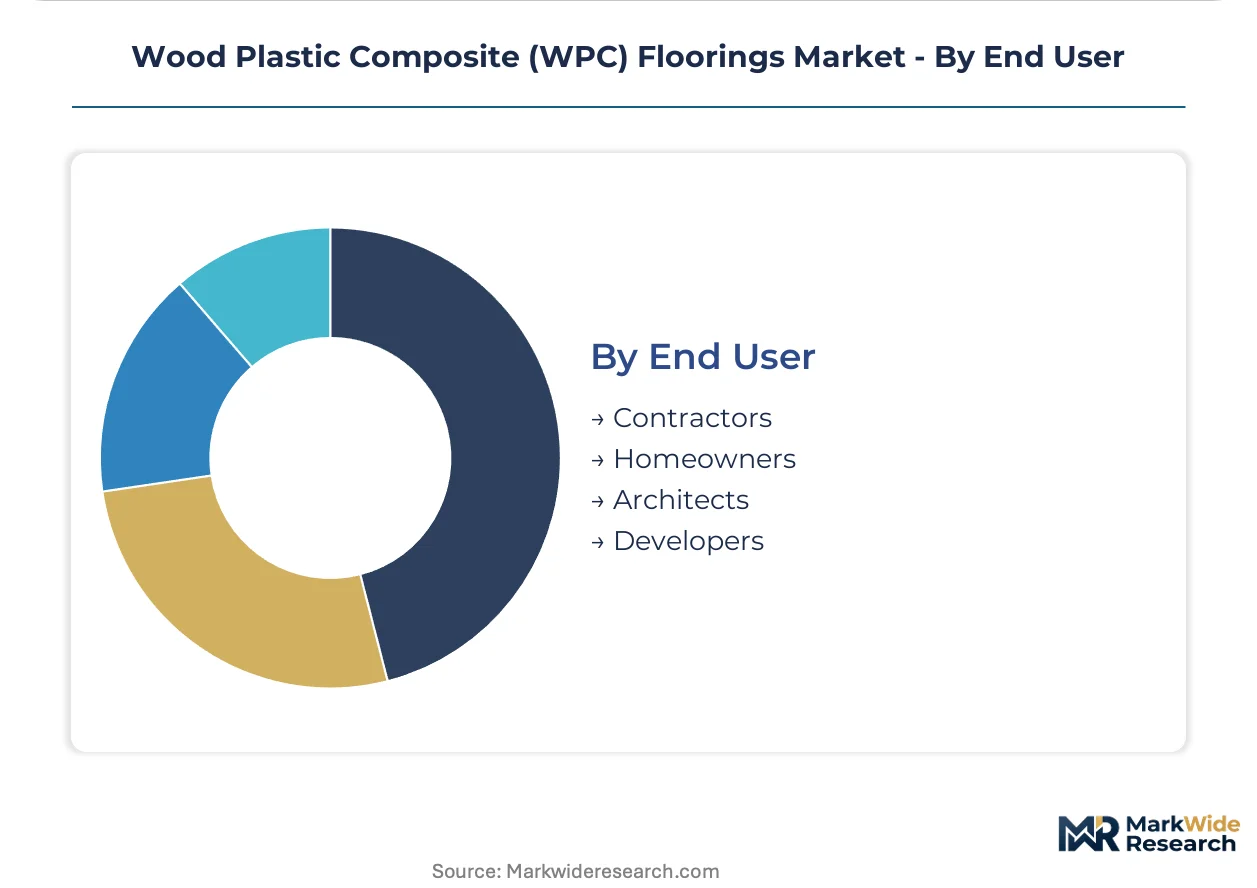
Contractors represent the largest transaction volume, with Architects driving the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled flooring installation contractors concentrate along the United States Gulf Coast and Atlantic seaboard, where humidity-resistant specifications drive specialized labor markets and distributor networks.
United States
Coastal states from Florida to California anchor residential renovation volume as homeowners replace moisture-damaged hardwood with WPC alternatives. EPA TSCA Title VI certification requirements extend product launch timelines for manufacturers serving California and New York markets. Texas and Florida contractor clusters standardize click-lock procurement through emerging digital platforms that bundle quantity takeoff with direct fulfillment.
Germany
Commercial architects in Berlin and Hamburg specify capped WPC products for hospitality fit-outs requiring warranty-backed durability in high-traffic environments. EU REACH restrictions on phthalate plasticizers accelerate compliant formulation adoption across German manufacturing operations. The Rhine-Ruhr industrial corridor hosts extrusion equipment specialists serving pan-European flooring producers with co-extrusion line upgrades.
China
Export-oriented producers in Anhui province supply cost-optimized uncapped formulations to North American distributors under private-label arrangements. The country's national standards regulator maintains GB standards for wood-plastic composite construction materials that diverge from EPA and EU testing protocols. Yangtze River Delta manufacturing clusters concentrate extrusion capacity for both domestic flooring consumption and overseas shipment.
Canada
Moisture-resistant basement renovation demand in Ontario and British Columbia pulls WPC specification away from traditional laminate products. Health Canada and PMRA maintain parallel chemical safety reviews that complicate capstock formulation compliance for US-origin imports. Toronto-area building material distributors stock capped products targeting multi-family developer portfolios seeking LEED certification compliance.
United Kingdom
London and Southeast England commercial developers specify recycled-content WPC for Green Building Council certification points on retail and office fit-outs. The country's national building standards regulator enforces reaction-to-fire performance classifications that capstock formulations must satisfy for high-rise applications. Manchester and Birmingham distribution hubs channel residential renovation volume through contractor merchant relationships.
Wood Plastic Composite (WPC) Floorings Market Competitive Landscape
The competitive structure tilts toward vertically integrated producers with captive recycled polyethylene supply chains. Trex Company Inc. and AZEK exemplify this archetype, leveraging backward integration into post-consumer plastic feedstock to buffer raw material volatility. A second archetype clusters export-oriented Chinese fabricators optimizing uncapped formulations for price-sensitive distributor procurement. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with co-extrusion line investments separating premium-tier producers from commodity suppliers.
Among North American integrated manufacturers, Trex Company Inc. occupies a position exemplifying captive supply chain control, while The AZEK Company Inc. represents the capped-product premium tier. Anhui Sentai WPC Group anchors the export-specialist archetype, supplying cost-optimized formulations to distributor networks across the United States and Canada. These three company structures illustrate how geographic origin and vertical integration depth stratify competitive positioning in residential and commercial specification channels.
| Leading Market Players |
|---|
| Trex Company Inc. |
| Armstrong Flooring Inc. |
| The AZEK Company Inc. |
| Fiberon |
| UFP Industries Inc. |
| Mannington Mills Inc. |
| Spectra Contract Flooring |
| Parterre Flooring Systems |
| Anhui Sentai WPC Group |
| Others |
Value Network & Pricing Analysis
Recycled polyethylene spot indices cascade through WPC flooring supply chains into three distinct pricing tiers, with coastal humidity requirements and California Title 24 thermal mandates compressing margin structures for non-compliant producers.
Pricing Analysis
Bundled installation services versus unbundled material-only procurement splits the market into divergent pricing models. Three-tier pricing structure across premium, standard, and economy levels stratifies by capstock technology and certification grade, with capped products commanding substantial premiums for UV stability warranties. Price erosion runs through uncapped residential segments as Anhui export specialists flood distributor channels with cost-optimized formulations. Big-box retail homeowners exhibit highest price sensitivity, while commercial architects in hospitality sectors demonstrate lowest elasticity due to liability protection requirements.
Supply Chain Analysis
Post-consumer plastic collection networks and end-of-life decking recovery programs are developing reverse-logistics infrastructure that feeds recycled content mandates. Manufacturing concentrates in China, the United States, and Germany, with Yangtze River Delta clusters anchoring export capacity and Texas-Oklahoma corridor housing integrated domestic producers. Raw material draws from post-consumer polyethylene film, wood flour from sawmill residuals, and mineral fillers for acoustic grades. Single-source vulnerability pervades captive recycled resin supply chains at major integrated manufacturers. Distribution runs through building material dealers, though digital platforms are capturing residential renovation volume under five thousand square feet.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory tailwinds into durable demand shifts, with EPA TSCA Title VI certification timelines and EU REACH chemical restrictions creating structural preference for compliant WPC formulations over conventional hardwood.
For Market Incumbents: Deepen backward integration into post-consumer plastic feedstock to buffer resin price volatility that threatens margin stability. Expand co-extrusion capacity in coastal United States markets where humidity-driven specification concentrates. Defend against Chinese export specialists by accelerating California Air Resources Board dual-certification timelines that extend competitor product launch cycles. For New Entrants and Emerging Players: Capture direct-to-contractor digital channels in Florida and Texas where humidity concerns and technology adoption intersect most intensely. Target loose-lay temporary flooring applications in retail event spaces that incumbent manufacturers underserve. Pursue EU Green Deal circular economy certification as a go-to-market wedge for pan-European distributor access. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier capped-product specialists possessing co-extrusion technical capability but lacking brand recognition for commercial specification. Five-to-ten year viability hinges on navigating per- and polyfluoroalkyl substance regulatory tightening without stranded capstock formulations. Monitor EU ECHA restriction proposals on stain-resistant chemistries as the critical inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Co-extrusion Capacity Expansion | Separates premium-tier producers from commodity uncapped suppliers in coastal specification channels. |
| Post-Consumer Feedstock Integration | Buffers raw material volatility while satisfying EU Green Deal recycled content mandates. |
| California Title 24 Dual Certification | Unlocks thermal performance specification tiers unavailable to single-certified competitors. |
| Direct-to-Contractor Digital Platform | Bypasses distributor markups in Florida and Texas renovation markets under five thousand square feet. |
| PFAS-Free Capstock Reformulation | Preempts regulatory restriction threats from EPA and EU ECHA emerging chemical safety frameworks. |
Research Methodology
Multiple input streams — extrusion equipment manufacturer interviews, building material distributor procurement data, and regulatory filing analysis — were reconciled to construct market estimates. Primary conversations with WPC flooring plant managers, residential renovation contractors, commercial architects, and EPA certification laboratory directors informed demand-side validation. Secondary sources included EPA TSCA Title VI certification databases, EU ECHA REACH restriction proposals, California Air Resources Board compliance listings, and trade flow customs records. Bottom-up volume builds by product tier and application were triangulated against top-down construction spending allocation models.
Data-stream reconciliation across the projection horizon applied segment-specific growth coefficients to derive value and volume trajectories. Modeled dimensions spanned product type tier, installation method complexity, end-user procurement sophistication, and regional regulatory cluster intensity. CAGRs were computed from fitted trend lines rather than simple endpoint comparisons. Industry-specific inputs incorporated California Title 24 thermal performance adoption curves and EU Green Deal recycled content mandate implementation schedules.
Feedstock price volatility, regulatory timeline acceleration, and capstock chemistry restriction scope are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented base-case assumptions regarding certification burden stability and contractor channel migration velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Canada Terrazzo Flooring Market
Flooring, Carpets, and Rugs
Decorative Rugs Market
Flooring, Carpets, and Rugs
Europe Laminate Flooring Market
Flooring, Carpets, and Rugs
Stone Flooring Market
Flooring, Carpets, and Rugs
Rugs Market
Flooring, Carpets, and Rugs
Fiberglass Flooring Market
Flooring, Carpets, and Rugs
Germany Flooring Market
Flooring, Carpets, and Rugs
China Engineered Wood Flooring Market
Flooring, Carpets, and Rugs
Saudi Arabia Carpet and Rugs Market
Flooring, Carpets, and Rugs
India Carpets and Rugs Market
Flooring, Carpets, and Rugs
China Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
US Flooring Market
Flooring, Carpets, and Rugs
Germany Resilient Flooring Market
Flooring, Carpets, and Rugs
Bamboo Flooring Market
Flooring, Carpets, and Rugs
China Floor Covering Market
Flooring, Carpets, and Rugs
Asia Pacific Flooring Market