
 North America Wood Flooring Market | 2026-2036
North America Wood Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
North America Wood Flooring Market Intelligence
Market Context
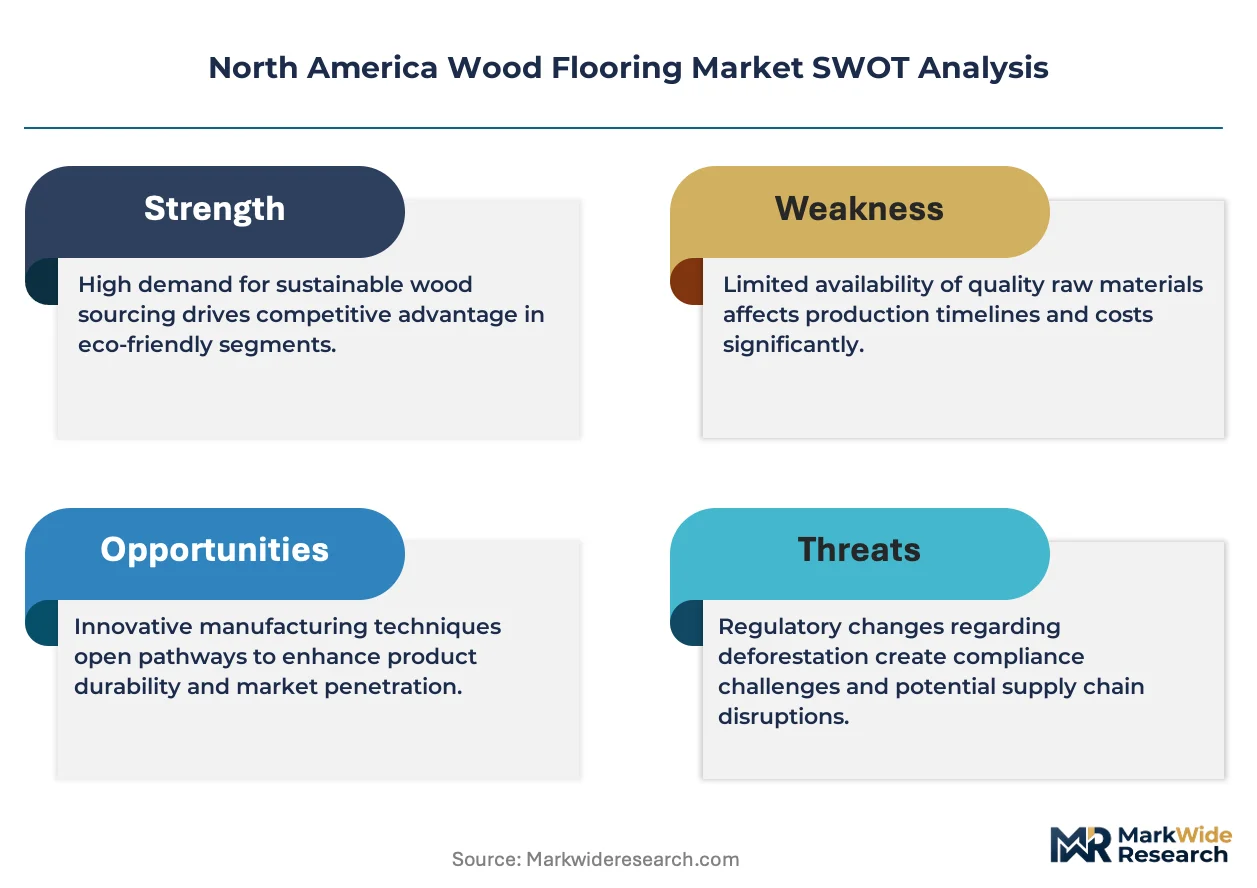
EPA TSCA Title VI is expanding compliance burdens for imported composite wood cores, forcing domestic producers to recertify supply chains. Mohawk Industries leverages captive timber holdings and in-house finishing capacity to absorb these regulatory costs without margin erosion. Shaw Industries Group anchors its position through advanced fiberboard engineering that preempts stricter emission benchmarks. Somerset Hardwood Flooring specializes in Appalachian-sourced solid planks that bypass composite-core scrutiny entirely.
Technical Definition and Segment Structure
North America wood flooring encompasses plank, strip, and parquet systems milled from hardwood species such as oak, maple, and hickory, typically finished with aluminum oxide or oil-based sealants for wear resistance and dimensional stability in high-traffic environments. Engineered wood, constructed from cross-laminated veneer layers bonded over plywood or high-density fiberboard substrates, dominates commercial specifications due to superior moisture tolerance and installation flexibility across concrete subfloors. Residential end users sustain the largest volume share, though institutional buyers in healthcare and education are shifting toward finished surface treatments that reduce on-site VOC exposure and accelerate project turnover.
Regulatory Frame and Outlook
CARB ATCM Phase 2 in California and the EPA's nationwide alignment under TSCA Title VI establish the binding emission thresholds for formaldehyde in composite wood products, directly influencing sourcing decisions and manufacturing locations across the continent. The U.S. Department of Agriculture's BioPreferred program and LEED v4.1 materials credits from the U.S. Green Building Council create parallel demand pull for certified sustainable hardwood and low-emitting adhesive systems. Stakeholders must monitor pending revisions to FSC chain-of-custody requirements and state-level embodied carbon legislation that could restructure procurement priorities for public-sector flooring contracts.
Market Dynamics
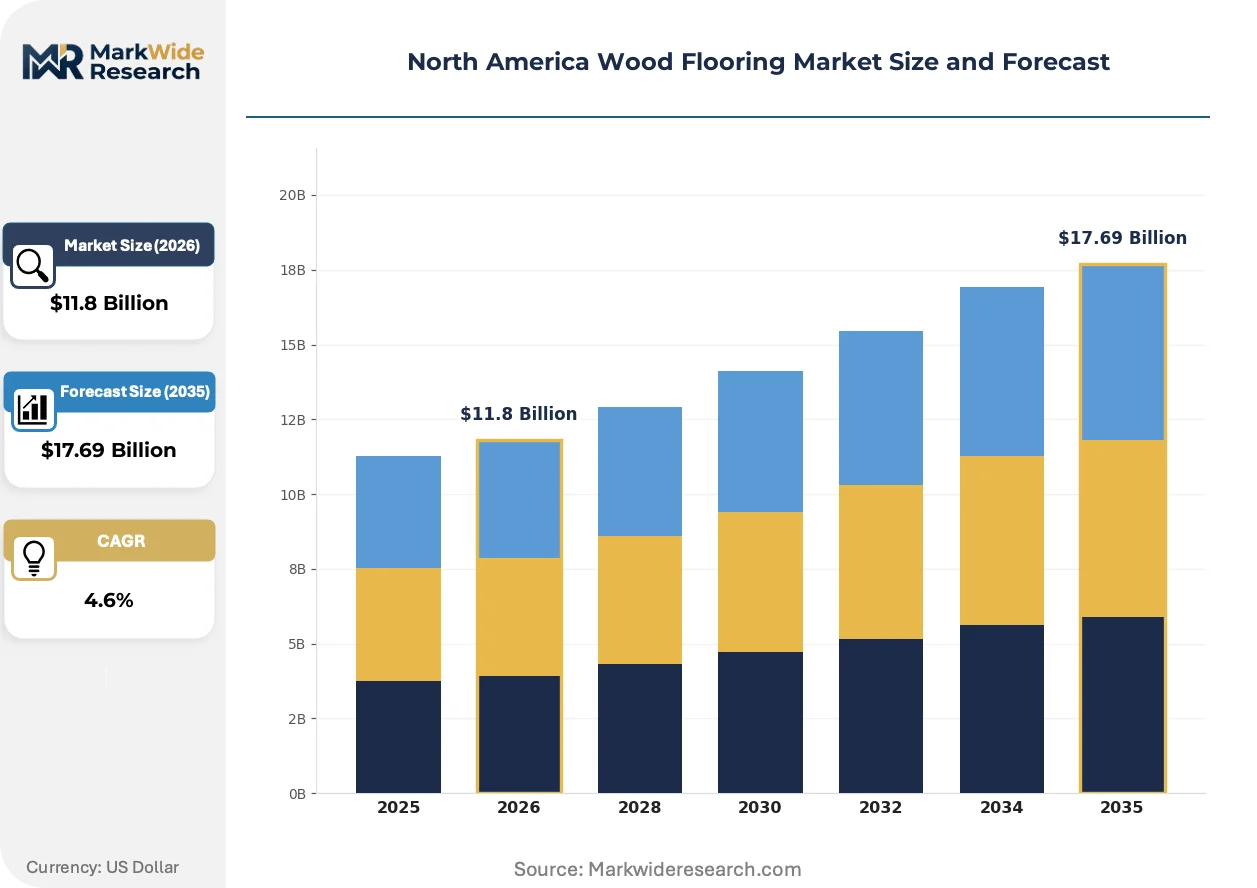
Residential renovation spending across the United States is accelerating demand for engineered wood products, while EPA TSCA Title VI compliance costs are restructuring manufacturer supply chains toward domestic timber sourcing and captive finishing capacity.
Growth Catalysts
- Engineered Wood Adoption:Cross-laminated veneer construction over plywood substrates dominates commercial specifications due to superior moisture tolerance across concrete subfloors in the U.S. Southeast.
- LEED v4.1 Materials Credits:The U.S. Green Building Council's certification framework pulls institutional buyers in healthcare and education toward low-emitting adhesive systems and certified sustainable hardwood.
- Appalachian Timber Access:Concentrated hardwood species availability in eastern Kentucky and West Virginia enables solid plank producers to bypass composite-core formaldehyde scrutiny entirely.
Market Restraints
- Oak and Maple Input Volatility:Domestic hardwood lumber prices fluctuate with logging capacity constraints and weather disruptions across the Appalachian supply basin.
- CARB ATCM Phase 2 Alignment:California's emission thresholds create a dual-track compliance burden for manufacturers distributing across state lines, raising certification costs for imported composite wood cores.
- Luxury Vinyl Tile Substitution:Waterproof synthetic alternatives capture moisture-sensitive residential segments, particularly in basement and bathroom applications where engineered wood underperforms.
Strategic Opportunities
- USDA BioPreferred Program:Federal procurement mandates for certified sustainable products open institutional flooring contracts to domestic hardwood suppliers meeting adhesive and chain-of-custody standards.
- Healthcare Surface Treatments:Pre-finished aluminum oxide sealants reduce on-site VOC exposure and accelerate project turnover for hospital and clinic renovation timelines.
- Direct-to-Contractor Digital Channels:Bypassing traditional distributor networks lets regional mills capture margin and capture specification data from commercial installers.
Industry Challenges
- FSC Chain-of-Custody Certification:Pending revisions to Forest Stewardship Council documentation requirements threaten to extend audit timelines and raise compliance costs for multi-source timber operations.
- Cross-Trained Installation Labor:Shortage of technicians proficient in both nail-down solid plank and floating engineered systems constrains residential renovation project velocity in high-growth metro areas.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Wood Flooring Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $17.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Hardwood, Engineered Wood, Laminate, Cork End User: Residential, Commercial, Industrial, Institutional Surface Treatment: Unfinished, Finished, Stained, Sealed Distribution Channel: Direct Sales, Retail Stores, Online Sales, Distributors |
| Companies Covered | Mohawk Industries, Inc., Shaw Industries Group, Inc., Armstrong Flooring, Inc., Mannington Mills, Inc., Tarkett S.A., Pergo, Beaulieu International Group, Somerset Hardwood Flooring, Inc., Goodfellow, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Wood Flooring Market Strategic Shifts & Innovations
Digital specification tools and pre-finished surface technologies are compressing traditional project timelines while regulatory pressure on formaldehyde emissions restructures material sourcing decisions across the value chain.
Water-based UV-cured finishing systems are rewriting the economics of on-site versus factory-applied sealants. Commercial contractors in education and healthcare sectors are specifying these pre-finished products to eliminate curing delays and reduce VOC exposure during occupied renovations. The technology is compressing installation schedules from weeks to days for large-format engineered planks.
EPA TSCA Title VI nationwide alignment with California's emission benchmarks is forcing imported composite core suppliers to recertify manufacturing locations. Domestic producers with captive plywood or fiberboard operations are absorbing compliance costs through vertical control over substrate supply. The regulation most affects manufacturers relying on offshore high-density fiberboard for engineered construction.
Specification decisions are migrating from distributor showrooms to architect and contractor digital platforms. Commercial project teams in Texas and Florida metro corridors are using BIM-integrated product libraries to filter flooring options by emission certification, species origin, and warranty terms before engaging suppliers. This shift concentrates influence with design firms and erodes traditional distributor specification control.
North America Wood Flooring Market Segmentation
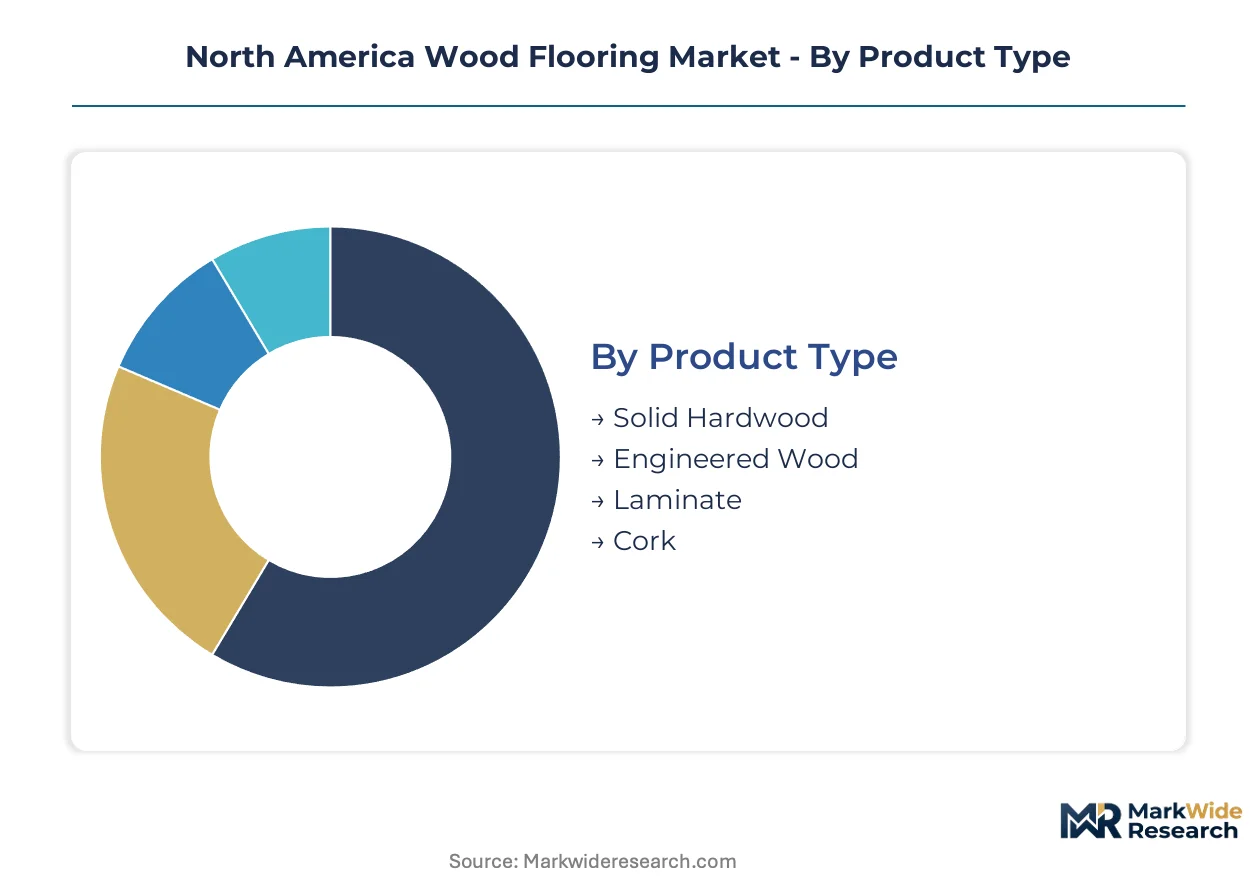
Wood flooring segmentation in North America tracks how buyers trade off installation speed, regulatory compliance, and lifecycle cost across residential renovation and commercial new-build channels. Specification decisions increasingly hinge on pre-finished surface technologies and formaldehyde certification tiers rather than species aesthetics alone.
Product Type:
Buyers in this category differentiate primarily by moisture tolerance requirements and subfloor compatibility rather than upfront material cost.
- Solid Hardwood:Milled from single-species lumber with tongue-and-groove profiles, typically 3/4-inch thickness. Appalachian-sourced oak and maple dominate residential renovation in the U.S. Southeast, where nail-down installation over plywood subfloors remains standard and buyers prioritize decades-long refinishing potential.
- Engineered Wood:Cross-laminated veneer layers bonded over plywood or high-density fiberboard substrates. Commercial specifications in Texas and Florida metro corridors favor engineered construction for its dimensional stability across concrete slabs, particularly in multi-family housing and retail fit-outs where moisture barriers are non-negotiable.
- Laminate:High-density fiberboard core with photographic wear layer and aluminum oxide surface. Budget-conscious residential buyers in suburban Midwest markets select laminate for basement installations where solid hardwood fails.
- Cork:Harvested bark composite with natural acoustic dampening properties. Institutional buyers in healthcare and education sectors specify cork for patient rooms and library spaces requiring sound absorption and underfoot resilience.
Engineered wood leads volumes today; cork is gaining share fastest among institutional specification teams prioritizing renewable material content.
End User:
Volume concentration varies sharply by project timeline pressure and VOC exposure protocols.
- Residential:Single-family homeowners and multi-family developers drive the majority of plank and strip volume, with renovation projects outpacing new construction in the U.S. Northeast and Pacific Northwest.
- Commercial:Retail chains and hospitality operators specify large-format engineered planks with factory-applied aluminum oxide finishes to minimize tenant downtime during occupied renovations.
- Industrial:Warehouse and light manufacturing facilities prioritize durability over aesthetics, typically selecting sealed surfaces with enhanced impact resistance for high-traffic loading zones.
- Institutional:Hospitals, schools, and government buildings mandate low-emitting adhesives and pre-finished surfaces that satisfy LEED v4.1 materials credits and accelerate project turnover without on-site curing delays.
Residential channels absorb the highest absolute volume; institutional procurement is expanding most quickly as federal and state green building mandates tighten.
Surface Treatment:
Installation economics and occupied-space constraints determine specification between factory-controlled and site-applied finishes.
- Unfinished:Raw sanded planks requiring on-site staining and sealing. Custom residential builders in high-end markets specify unfinished oak for color matching to existing millwork, accepting extended project timelines.
- Finished:Factory-applied UV-cured sealants delivering immediate walkability. Commercial contractors in healthcare and education sectors exclusively specify pre-finished products to eliminate curing delays and reduce VOC exposure during occupied renovations.
- Stained:Pigmented surface treatments applied before final sealant layers. Residential buyers seeking aesthetic coordination with cabinetry and trim specify stained products across mid-market renovation segments.
- Sealed:Protective topcoats emphasizing moisture resistance and wear protection. Basement and ground-floor installations in humid climates rely on sealed surfaces with enhanced vapor barrier compatibility.
Finished surfaces dominate commercial specifications today; sealed treatments are climbing fastest in moisture-sensitive residential applications.
Distribution Channel:
Specification influence is migrating from physical showrooms to digital platforms with embedded certification filtering.
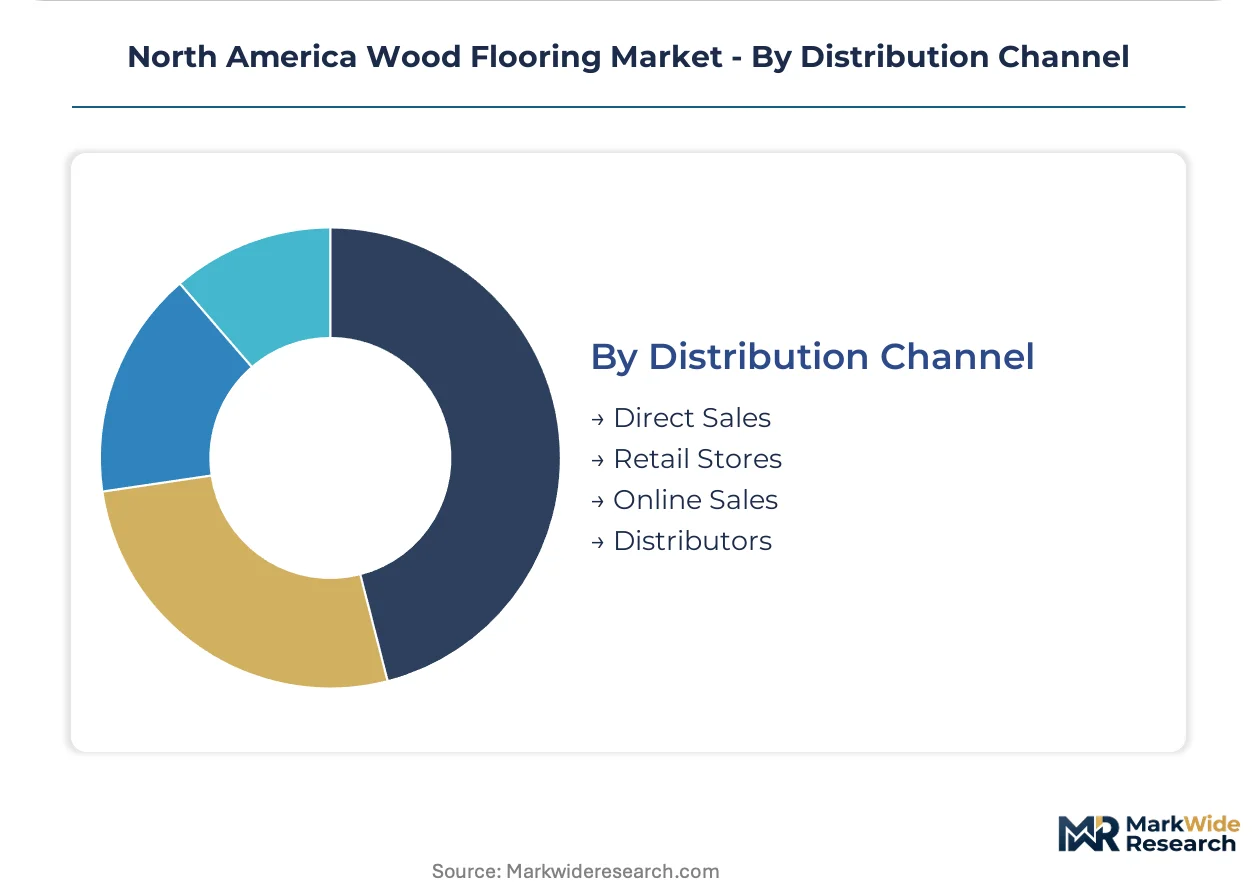
- Direct Sales:Manufacturer-to-contractor relationships bypassing distributor markups. Regional mills in the Appalachian basin leverage direct channels to capture margin and specification data from commercial installers.
- Retail Stores:Big-box and specialty flooring showrooms serving residential renovation buyers. California and New York markets concentrate retail foot traffic where CARB ATCM Phase 2 compliance labeling influences purchase decisions.
- Online Sales:E-commerce platforms with BIM-integrated product libraries. Texas and Florida project teams filter flooring options by emission certification and warranty terms before engaging suppliers, eroding traditional distributor specification control.
- Distributors:Regional warehousing networks stocking mixed manufacturer portfolios. Distributors retain influence in smaller metro areas where contractor relationships and just-in-time delivery remain critical.
Retail stores still transact the highest volume; online sales are expanding most quickly among commercial specification teams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled flooring installers and certified timber harvesters concentrate in the Appalachian hardwood belt and the U.S. Southeast, anchoring North American production capacity and installation labor pools for both residential renovation and commercial construction channels.
United States
Residential renovation spending in the U.S. Southeast outpaces national averages, with Florida and Georgia metro corridors driving engineered wood specifications for multi-family housing over concrete slabs. EPA TSCA Title VI compliance costs push manufacturers toward domestic timber sourcing and captive finishing capacity. Appalachian hardwood operations in eastern Kentucky and West Virginia supply solid plank producers with oak and maple that bypass composite-core formaldehyde scrutiny.
Canada
Quebec and Ontario manufacturers leverage proximity to U.S. Northeast renovation markets, shipping pre-finished engineered products across the border for healthcare and education sector projects. Health Canada maintains aligned emission standards with EPA benchmarks, reducing dual-track certification burdens for cross-border distributors. Toronto and Montreal anchor specification influence for institutional buyers prioritizing LEED v4.1 materials credits and FSC chain-of-custody documentation.
Mexico
Nuevo León and the Bajío Region concentrate manufacturing operations serving U.S. Southwest markets, with Monterrey-based facilities producing laminate and engineered substrates for price-sensitive residential segments. Mexican producers face heightened EPA TSCA Title VI scrutiny on imported composite cores, forcing recertification of high-density fiberboard supply chains. Mexico City Metro drives domestic commercial flooring demand from hospitality and retail fit-out sectors.
North America Wood Flooring Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions, with scale-driven manufacturers absorbing regulatory compliance costs through captive timber holdings and in-house finishing capacity. The vendor base stratifies into three archetypes: integrated forest-products conglomerates controlling upstream supply, regional mills leveraging Appalachian timber access, and synthetic flooring specialists cross-selling waterproof alternatives. Dominant competitive moves include backward integration into substrate manufacturing and direct-to-contractor digital channel expansion that bypasses traditional distributor networks.
Within the integrated conglomerate tier, Mohawk Industries, Inc. and Shaw Industries Group, Inc. occupy positions defined by captive supply chain control and multi-brand portfolio breadth. Somerset Hardwood Flooring, Inc. exemplifies the regional pure-play archetype, anchoring its market presence through Appalachian-sourced solid plank specialization that sidesteps composite-core regulatory complexity entirely.
| Leading Market Players |
|---|
| Mohawk Industries, Inc. |
| Shaw Industries Group, Inc. |
| Armstrong Flooring, Inc. |
| Mannington Mills, Inc. |
| Tarkett S.A. |
| Pergo |
| Beaulieu International Group |
| Somerset Hardwood Flooring, Inc. |
| Goodfellow, Inc. |
| Others |
Cost & Logistics Intelligence
Hardwood lumber input costs cascade through three distinct pricing tiers, with Appalachian oak and maple commanding premium positions over imported composite cores facing EPA TSCA Title VI recertification burdens. Installation service bundling separates full-service commercial contractors from price-sensitive residential renovation buyers sourcing through retail channels.
Pricing Analysis
Unbundled material-only transactions dominate residential renovation channels, while bundled installation-and-finishing packages capture commercial project value. Price differentiation rests on formaldehyde certification tier and factory-applied sealant technology, with CARB ATCM Phase 2-compliant products commanding sustained premiums. Cost compression in laminate and economy engineered tiers intensifies as luxury vinyl tile substitutes erode moisture-sensitive segments. Big-box retail buyers exhibit highest price sensitivity; institutional procurement teams prioritize lifecycle cost and compliance documentation over upfront material expense.
Supply Chain Analysis
Freight cost escalation from Appalachian timber basins to Texas and Florida metro corridors is reshaping regional mill location decisions. Supply concentrates in the United States, Canada, and Mexico, with cross-laminated veneer construction drawing from domestic plywood operations and offshore high-density fiberboard substrates. Tariff exposure on imported composite cores threatens margin structures for engineered wood assemblers lacking captive substrate capacity. Distribution runs through direct-to-contractor digital channels and regional distributor networks serving smaller metro areas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EPA TSCA Title VI alignment accelerating demand for certified low-emitting products and domestic timber sourcing.
For Market Incumbents: Hedge formaldehyde compliance exposure by securing captive plywood or fiberboard operations before pending FSC chain-of-custody revisions extend audit timelines. Absorb regulatory costs through backward integration into Appalachian timber holdings rather than passing price increases to price-sensitive residential segments. Pre-finished aluminum oxide capacity expansion addresses healthcare and education sector demand for accelerated project turnover. For New Entrants and Emerging Players: Digital specification tools offer a technology-first wedge into commercial contractor relationships, bypassing traditional distributor markups in Texas and Florida metro corridors. Target institutional procurement teams prioritizing LEED v4.1 materials credits and FSC documentation, where incumbent complacency around digital channel investment creates white space. Lead with BIM-integrated product libraries filtering by emission certification and warranty terms to capture specification influence upstream of purchase decisions. For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory compliance costs outstrip mid-scale manufacturer capital reserves. Long-term viability favors regional pure-plays with Appalachian timber access or integrated conglomerates with captive finishing capacity. Watch EPA formaldehyde standard enforcement intensity and state-level embodied carbon legislation adoption as inflection indicators for procurement priority shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Substrate Integration | Absorbs EPA TSCA Title VI compliance costs through in-house plywood or fiberboard production control. |
| Pre-Finished Surface Capacity Expansion | Captures healthcare and education sector demand for UV-cured sealants eliminating on-site curing delays. |
| Direct-to-Contractor Digital Channel | Bypasses distributor markups while capturing specification data from commercial installers in growth metros. |
| Appalachian Timber Supply Security | Locks in oak and maple access that bypasses composite-core formaldehyde scrutiny entirely. |
| LEED v4.1 Certification Investment | Opens institutional flooring contracts requiring low-emitting adhesive and chain-of-custody documentation. |
Research Approach
Coverage spans the United States, Canada, and Mexico, with primary inputs from each country informing cross-border regulatory alignment analysis. Primary interviews with flooring manufacturer executives, commercial contractor specification teams, institutional procurement managers, and regional distributor operators combined with secondary validation from EPA enforcement databases, USDA BioPreferred program records, and U.S. Census Bureau construction spending data. Bottom-up volume modeling and top-down value triangulation anchored regional demand estimates.
Granularity-level modeling tracked product type, end user segment, surface treatment, and distribution channel dimensions across the projection horizon. CAGRs derived from regression analysis against housing starts, renovation spending indices, and regulatory implementation timelines. Species-specific lumber price volatility and formaldehyde certification adoption curves served as industry-specific forecast inputs.
The model holds under steady EPA enforcement intensity and stable hardwood lumber supply; deviation in tariff regimes or FSC audit requirement severity would shift competitive positioning. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
India Wood Flooring Market
Flooring, Carpets, and Rugs
Global Vinyl Flooring Market
Flooring, Carpets, and Rugs
Global Flooring and Carpet Market
Flooring, Carpets, and Rugs
North America Vinyl Flooring Market
Flooring, Carpets, and Rugs
Entrance Matting Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tiles Market
Flooring, Carpets, and Rugs
India Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
US Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
Asia Pacific Flooring Market
Flooring, Carpets, and Rugs
Carpets and Rugs Market
Flooring, Carpets, and Rugs
Netherlands Floor Covering Market
Flooring, Carpets, and Rugs
Foam Flooring Products Market
Flooring, Carpets, and Rugs
Global Carpet Tile Market
Flooring, Carpets, and Rugs
US Vinyl Floorings Market
Flooring, Carpets, and Rugs
Flooring for Tile and Stone Market
Flooring, Carpets, and Rugs
Fiberglass Flooring Market