
 China Electric Vehicle Battery Materials Market | 2026-2036
China Electric Vehicle Battery Materials Market Size, Share, and Industry Trends Forecast 2026-2036
China Electric Vehicle Battery Materials Market Insights
GB/T 31485 battery safety qualification is unwinding the competitive landscape as smaller refiners face capital barriers to compliance. Contemporary Amperex Technology Co., Limited leverages integrated cathode precursor operations to lock in cost advantages. BYD Auto Co., Ltd. anchors its position through captive lithium iron phosphate supply chains. Ganfeng Lithium dominates upstream brine and spodumene sourcing across Qinghai and Sichuan.
China electric vehicle battery materials encompass refined metals, active powders, electrolytes, and separators engineered to specific energy density, cycle life, and thermal runaway thresholds for lithium-ion cell assembly. Cathode active materials require controlled stoichiometry in nickel-manganese-cobalt or lithium iron phosphate formulations to meet GB/T capacity and safety benchmarks. Lithium and nickel segments carry the deepest margin pools as high-nickel chemistries penetrate premium passenger vehicle platforms. Cobalt faces structural pressure from LFP substitution in mass-market buses and two-wheelers. Graphite anode supply extends through artificial and natural grades with diverging purity specifications.
MIIT production access rules, SAMR product quality audits, and GB/T battery safety standards collectively filter market entry and enforce traceability across material supply chains. NMPA-aligned environmental reviews from MEE constrain graphite and nickel refining expansions in key industrial zones. Stakeholders must monitor GB standard revision cycles and provincial dual carbon enforcement intensity to anticipate cost pass-through structures and qualification timelines.
Market Dynamics
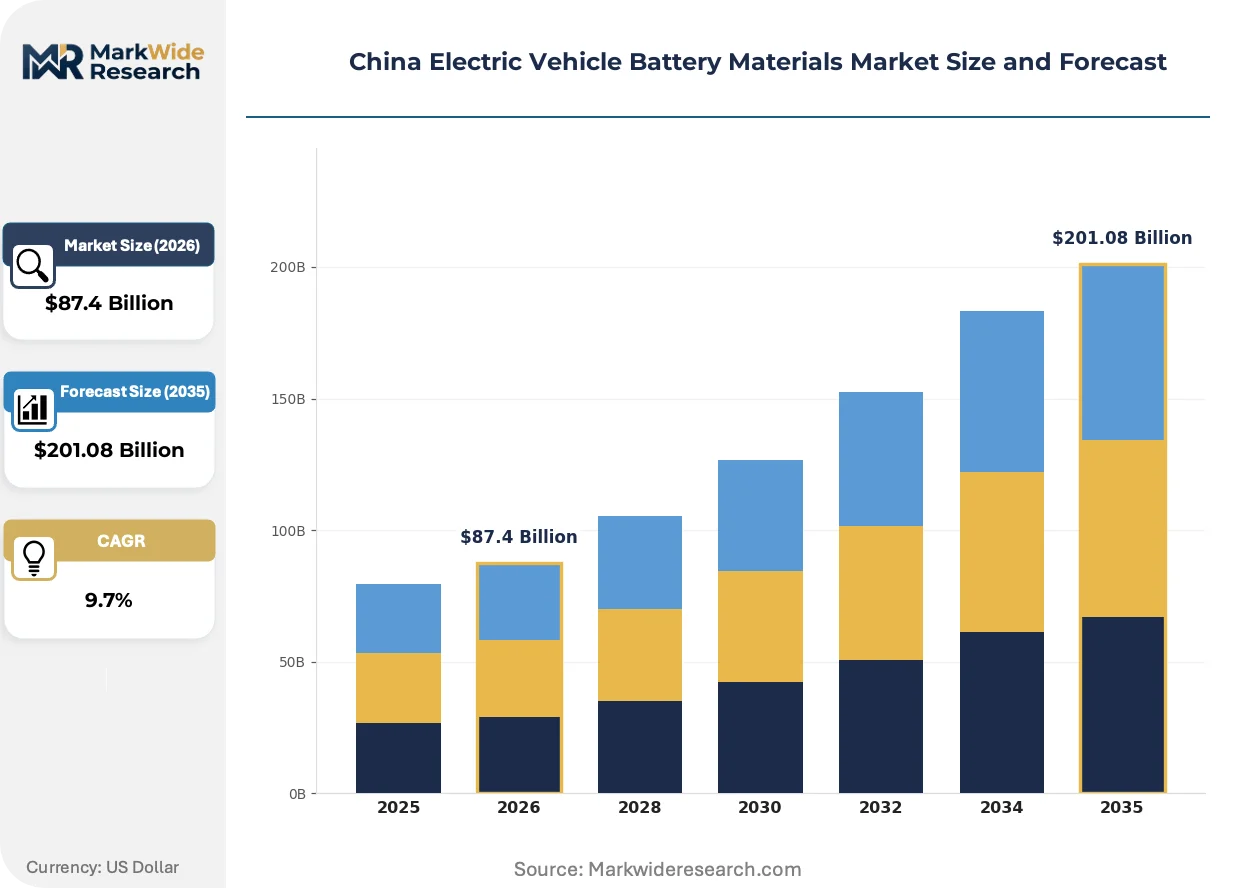
High-nickel cathode chemistry migration is compressing cobalt demand while amplifying lithium and nickel procurement intensity across China's passenger EV supply base. MIIT credit rules and GB/T safety thresholds are simultaneously filtering producer qualifications and reshaping margin pools toward integrated refiners.
Growth Catalysts
- MIIT NEV Credit Mandate:Automakers must accumulate credits through battery efficiency gains, forcing cathode upgrades toward higher energy density formulations.
- Jiangsu-Zhejiang Cluster Concentration:Proximity of precursor plants, cell factories, and recycling infrastructure reduces logistics friction and qualification timelines.
- LFP Chemistry Maturation:Lithium iron phosphate systems now meet range thresholds for mass-market buses and two-wheelers, expanding addressable cathode volume.
Market Restraints
- Spodumene Concentration Risk:Hard rock lithium feedstock dependence on Sichuan and Qinghai mining corridors creates geographic single-point vulnerability.
- Graphite Refining Bottlenecks:MEE environmental reviews constrain artificial graphite expansion in Hebei and Shandong industrial zones.
- Cobalt Demand Destruction:LFP substitution in commercial vehicles is structurally compressing cobalt offtake from historical baselines.
Strategic Opportunities
- Closed-Loop Recycling Infrastructure:Retired EV battery feedstock from Yangtze River Delta fleets offers secondary lithium, nickel, and cobalt recovery channels.
- Solid-State Electrolyte Convergence:Sulfide and oxide solid-state chemistries demand new precursor specifications, opening qualification windows for advanced material suppliers.
- SAMR Traceability Mandate:Battery passport requirements create service revenue pools for supply chain visibility software and testing laboratories.
Industry Challenges
- GB/T 31485 Certification Timeline:Smaller cathode refiners face 18-24 month qualification cycles for safety testing and MIIT production access.
- High-Nickel Sintering Expertise Gap:Precursor stoichiometry control for NCM 811 and 9-series chemistries requires specialized metallurgical talent scarce in inland provinces.
- Dual Carbon Enforcement Variance:Provincial MEE offices apply divergent carbon intensity thresholds, complicating multi-site expansion planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Electric Vehicle Battery Materials Market |
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $201.08 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Lithium, Cobalt, Nickel, Graphite Battery Chemistry: LFP, NMC, NCA, Lithium-ion End Use: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Buses Supplier Type: OEMs, Tier-1 Suppliers, Distributors, Others |
| Companies Covered | Ronbay Technology, China Aviation Lithium Battery, Contemporary Amperex Technology Co., Limited, EVE Energy Co., Ltd., Gotion Inc., BYD Auto Co., Ltd., BTR New Material, Sunwoda Electronic Co., Ltd., Ganfeng Lithium, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Electric Vehicle Battery Materials Market Trends and Innovations
Material processing techniques and regulatory traceability mandates are restructuring how cathode precursors, electrolytes, and anode grades are specified, tested, and contracted across China's cell manufacturing ecosystem.
Single-crystal high-nickel cathode technology is decomposing the traditional polycrystalline NCM supply chain. Premium passenger EV platforms from domestic OEMs are adopting single-crystal NCM 811 for superior cycle stability. This structural shift is compressing margins for conventional precursor producers while rewarding integrated refiners with in-house crystallization capabilities.
MIIT's battery traceability regulations now require full material provenance documentation from mine to cell. SAMR audits enforce batch-level testing against GB/T capacity and safety benchmarks. Cathode suppliers in Jiangsu and Fujian provinces are deploying blockchain-linked inventory systems to satisfy downstream qualification requirements.
Automakers are consolidating cathode procurement through direct precursor partnerships rather than merchant market purchases. Tier-one cell manufacturers now negotiate multi-year lithium and nickel offtake agreements with specified purity grades. This concentration is most visible in the Yangtze River Delta, where CATL and BYD have established captive supply corridors with dedicated refining capacity.
China Electric Vehicle Battery Materials Market Segmentation
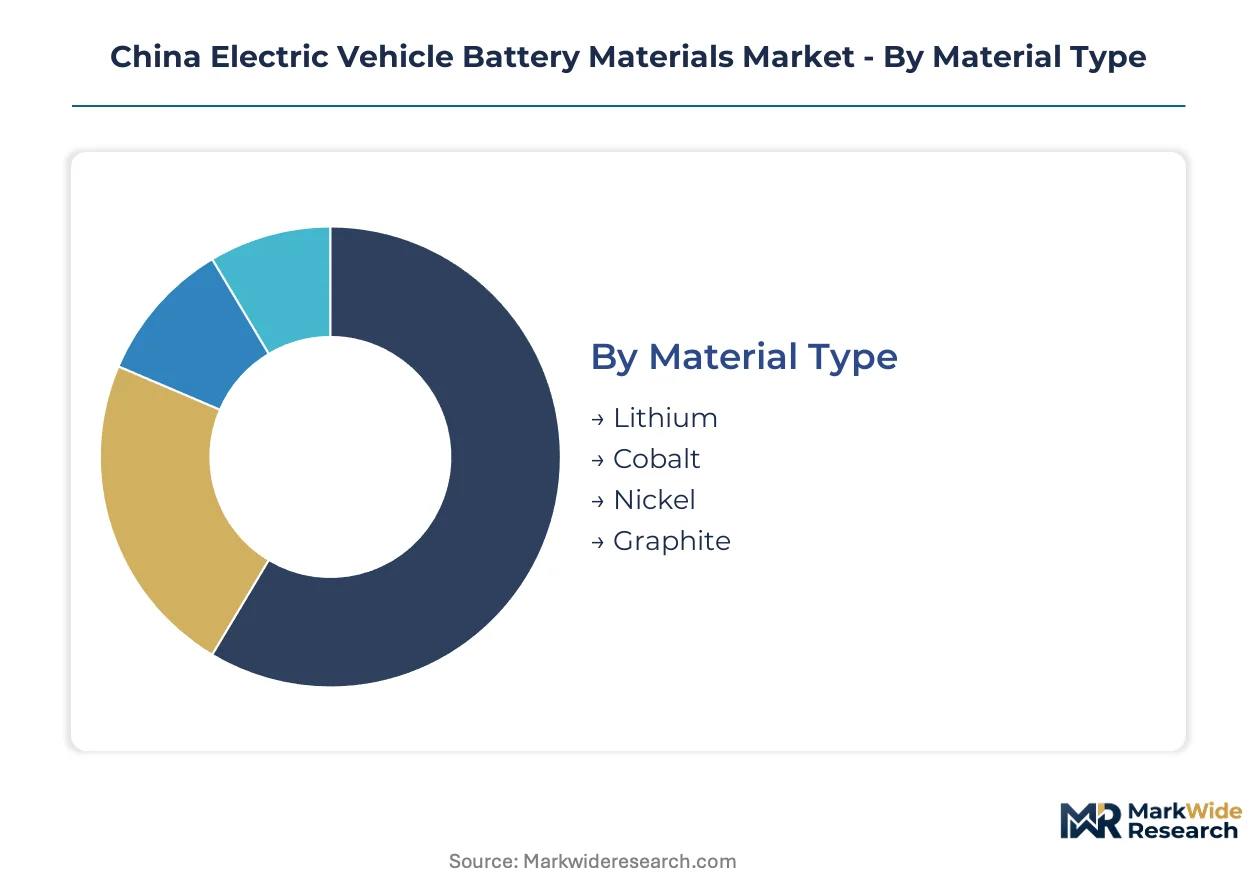
China's EV battery materials market fragments across four critical dimensions that determine procurement patterns, margin structures, and regulatory exposure. Material type and battery chemistry segments dominate capital allocation, while end-use and supplier type classifications shape contract terms and qualification timelines.
Material Type:
Domestic demand concentrates in lithium and graphite for captive supply to Yangtze River Delta cell factories, while nickel and cobalt segments retain heavier export linkage to Korean and Japanese cathode producers.
- Lithium:Extracted from Qinghai brine deposits and Sichuan spodumene corridors, this segment supplies carbonate and hydroxide grades for both LFP and high-nickel cathode systems. Jiangsu-based refiners are expanding conversion capacity to serve CATL and BYD direct offtake agreements.
- Graphite:Encompassing artificial and natural anode grades with diverging purity specifications, this segment faces MEE environmental review bottlenecks in Hebei and Shandong. Demand concentrates in spherical graphite for premium passenger EV platforms requiring fast-charge capability.
- Nickel:Intermediate nickel products from Indonesia-linked supply chains feed Jiangsu precursor plants. The segment is gaining domestic processing depth as high-nickel cathode penetration accelerates.
- Cobalt:Facing structural demand compression from LFP substitution in commercial vehicles and two-wheelers, this segment retains niche positioning in premium NCM 811 formulations for luxury passenger EVs.
Lithium commands the established base. The steepest expansion runs through nickel as cathode chemistry migration accelerates.
Battery Chemistry:
Cost tier differentiation separates mass-market penetration chemistries from premium performance formulations, with procurement patterns diverging sharply across vehicle price bands.
- LFP:Lithium iron phosphate systems dominate mass-market bus and two-wheeler segments with cost-optimized energy density. MIIT credit rules now recognize LFP efficiency gains, expanding qualification pathways for domestic producers.
- NMC:Nickel-manganese-cobalt formulations span 523, 622, and 811 stoichiometries with escalating nickel content. Single-crystal NCM 811 variants are displacing polycrystalline alternatives in premium passenger EV platforms from domestic OEMs.
- NCA:Nickel-cobalt-aluminum chemistry retains limited adoption among foreign-brand joint ventures targeting high energy density thresholds. The segment depends on imported precursor specifications.
- Lithium-ion:Legacy cylindrical and prismatic formats serve replacement markets and industrial applications outside mainstream EV procurement channels.
LFP anchors volume leadership. NMC variants are climbing the fastest as passenger EV range requirements intensify.
End Use:
Application-driven specification divergence creates distinct material purity and cycle life requirements across mobility categories, with fleet procurement concentrating in specific chemistry-material combinations.
- Passenger Vehicles:Premium platforms specify single-crystal NCM 811 for 600km-plus range targets, while mass-market models shift toward LFP for cost containment. Jiangsu-Zhejiang cluster proximity reduces logistics qualification friction for cathode suppliers.
- Commercial Vehicles:Delivery vans and light trucks favor LFP for thermal stability under high-utilization duty cycles. Fleet operators negotiate direct precursor contracts bypassing merchant market volatility.
- Two-Wheelers:Swappable battery networks in Shenzhen and Hangzhou standardize on LFP for safety and cycle life. The segment drives granular lithium carbonate demand from dedicated refining lines.
- Buses:Municipal procurement mandates GB/T 31485 safety certification, favoring established cathode suppliers with MIIT production access. LFP penetration nears saturation in this category.
Passenger vehicles command the established base. Commercial vehicles are expanding most quickly as logistics electrification accelerates.
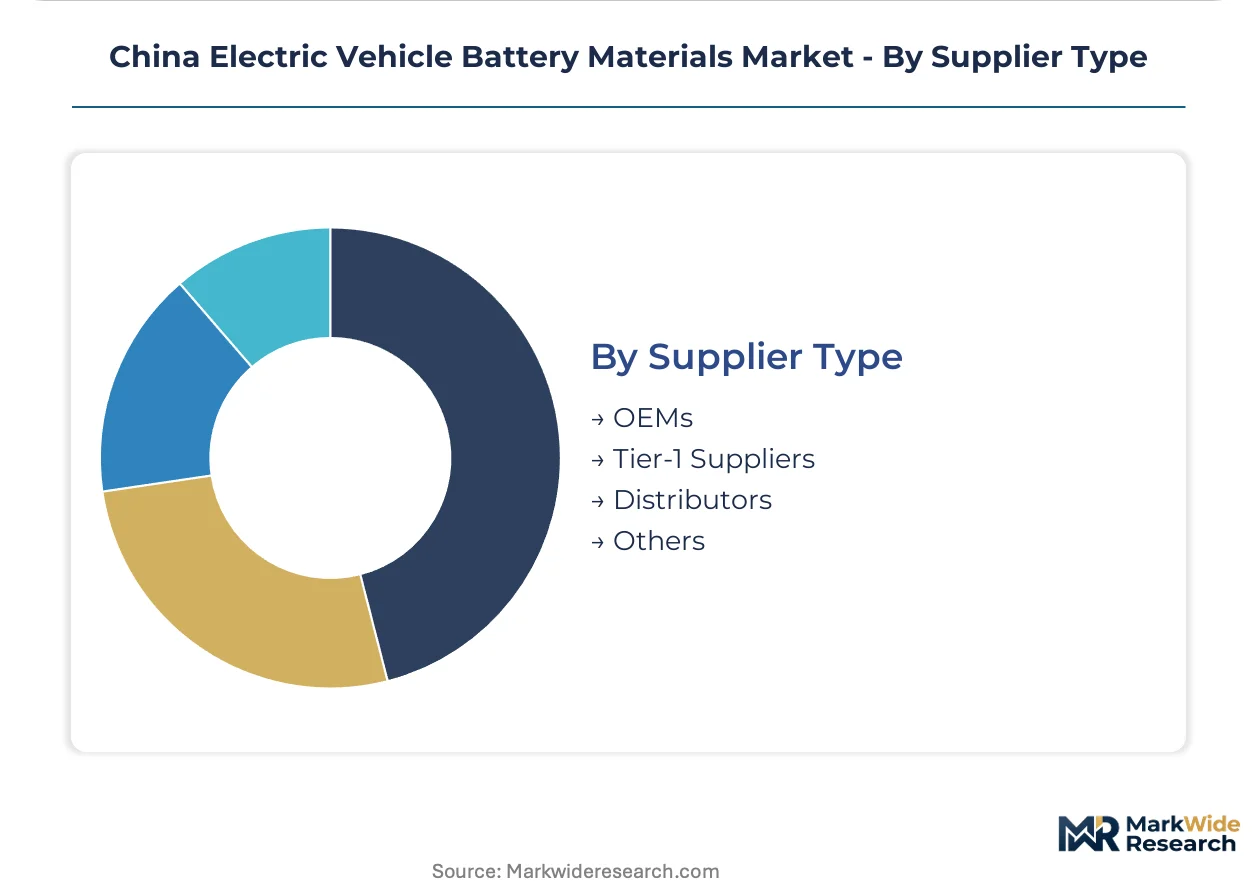
Supplier Type:
Customer-type stratification reveals concentration of margin pools toward integrated producers with captive refining, while distributor channels face compression from direct OEM procurement trends.
- OEMs:BYD and CATL operate backward into cathode precursor and lithium conversion, capturing margin pools historically retained by merchant refiners. SAMR traceability mandates reinforce captive supply advantages.
- Tier-1 Suppliers:Cell manufacturers negotiate multi-year offtake agreements with specified purity grades, consolidating procurement through dedicated refining capacity in the Yangtze River Delta.
- Distributors:Merchant market channels serve smaller cell producers and replacement battery assemblers with standardized material grades. GB/T certification requirements are elevating working capital barriers.
- Others:Recycling operators and trading houses occupy niche positions in secondary lithium and nickel recovery from retired EV fleets.
Tier-1 suppliers command the established base. OEM backward integration is gaining share fastest as direct procurement corridors mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic OEM procurement offices and tier-one cell manufacturers concentrate demand in coastal industrial clusters where GB standard certification labs and precursor refining capacity co-locate. Provincial dual carbon enforcement variance creates divergent cost structures across supply corridors.
Yangtze River Delta
Jiangsu and Zhejiang provinces host the densest concentration of cathode precursor plants and MIIT-qualified cell factories. SAMR traceability audits enforce batch-level GB/T testing at facilities in Changzhou and Ningbo. The Suzhou-Wuxi corridor anchors multi-year lithium offtake negotiations between integrated refiners and CATL procurement divisions.
Pearl River Delta
BYD's Shenzhen headquarters drives captive LFP supply chain coordination across Guangdong and Fujian provinces. MEE environmental reviews constrain graphite refining expansions in the Dongguan industrial zone. The Huizhou battery cluster specializes in high-nickel cathode qualification for export-oriented passenger EV platforms.
Sichuan-Chongqing
Spodumene mining corridors in western Sichuan feed lithium carbonate conversion lines serving western China cell factories. Provincial mining safety bureaus enforce tailings management standards at Yajiang and Daofu extraction sites. The Chengdu-Chongqing economic circle attracts precursor plant relocations seeking lower carbon intensity thresholds than coastal zones.
Shandong Peninsula
Artificial graphite anode refineries in Qingdao and Yantai face MEE air quality compliance deadlines under provincial dual carbon targets. The Weihai materials cluster processes spherical graphite grades for fast-charge passenger EV specifications. Local environmental bureaus are capping expansion permits for high-emission calcination operations.
Qinghai
Brine extraction operations at Chaerhan Salt Lake supply lithium hydroxide for high-nickel cathode systems. State-owned resource developers coordinate with Jiangsu refiners under long-term supply frameworks. The Golmud industrial park hosts integrated carbonate-to-hydroxide conversion capacity exempt from coastal environmental moratoriums.
China Electric Vehicle Battery Materials Market Competitive Landscape
Player mix skews toward integrated refiners with captive precursor operations and state-linked resource developers with upstream mining concessions. Market structure concentrates margin pools in the top five producers while mid-tier merchant refiners face GB/T 31485 qualification barriers. Strategic archetypes include backward-integrated cell manufacturers, state-owned lithium extractors, and specialized cathode precursor suppliers. Dominant competitive moves center on multi-year offtake agreements and direct OEM procurement corridor establishment.
Within the integrated manufacturer tier, Contemporary Amperex Technology Co., Limited and BYD Auto Co., Ltd. represent archetypes of backward integration into cathode precursor and lithium conversion. Ganfeng Lithium occupies a position bridging state-linked resource extraction and merchant market supply. These three entities exemplify how procurement concentration in the Yangtze River Delta rewards scale and captive supply chain control over pure merchant refining strategies.
| Leading Market Players |
|---|
| Ronbay Technology |
| China Aviation Lithium Battery |
| Contemporary Amperex Technology Co., Limited |
| EVE Energy Co., Ltd. |
| Gotion Inc. |
| BYD Auto Co., Ltd. |
| BTR New Material |
| Sunwoda Electronic Co., Ltd. |
| Ganfeng Lithium |
| Others |
Pricing and Supply Chain Analysis
Forty-five-day cathode precursor inventory cycles in the Yangtze River Delta concentrate pricing power among integrated refiners with captive lithium conversion, compressing margins for merchant market distributors dependent on spot carbonate procurement.
Pricing Analysis
Long-term offtake contracts indexed to Shanghai Metals Market lithium carbonate and London Metal Exchange nickel prices dominate procurement between CATL, BYD, and Jiangsu-based refiners. Price differentiation separates MIIT-certified cathode grades from unqualified merchant material, with GB/T 31485 certification commanding premium positioning. Pricing pressure stems from LFP substitution eroding cobalt-linked contract values. Mass-market bus fleet operators exhibit highest price sensitivity, while premium passenger EV platforms prioritize energy density over unit cost.
Supply Chain Analysis
Port congestion at Ningbo-Zhoushan and container availability constraints on Indonesia-nickel trade lanes inflate inbound logistics costs for Jiangsu precursor plants. Raw material supply draws from Qinghai brine, Sichuan spodumene, and Indonesia-linked nickel processing. Single-source vulnerability concentrates in hard-rock lithium corridors. Distribution runs through direct OEM procurement corridors rather than merchant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where MIIT production access rules and GB standard certification create entrenched switching costs for qualified suppliers.
For Market Incumbents: Fortify captive precursor operations through backward integration into Qinghai lithium conversion and Sichuan spodumene corridors. Expand single-crystal NCM 811 crystallization capacity in Changzhou to defend against LFP substitution in premium segments. Deepen SAMR traceability compliance to extend qualification advantages over mid-tier refiners facing capital barriers. For New Entrants and Emerging Players: Anchor in solid-state electrolyte precursor specifications where qualification windows remain open for sulfide and oxide chemistry suppliers. Target retired EV battery recycling infrastructure in the Yangtze River Delta as feedstock supply converges with environmental compliance mandates. Lead with blockchain-linked provenance systems to satisfy emerging battery passport requirements. For Investors and Strategic Acquirers: Carve-out targets emerge from state-owned resource developers spinning off lithium conversion assets as standalone entities. Five-to-ten-year viability hinges on cathode chemistry migration trajectories and solid-state adoption timelines. Monitor provincial MEE dual carbon enforcement intensity as the inflection signal for cost pass-through structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Conversion | CATL and BYD lock in cost advantages through captive Qinghai carbonate-to-hydroxide operations. |
| Single-Crystal Cathode Capacity Expansion | Jiangsu refiners capture premium positioning as domestic OEMs adopt NCM 811 for 600km-plus range targets. |
| Closed-Loop Recycling Infrastructure | Yangtze River Delta operators recover secondary lithium, nickel, and cobalt from retired EV fleets. |
| Solid-State Electrolyte Precursor Development | Advanced material suppliers open qualification windows for sulfide and oxide chemistry specifications. |
| Blockchain-Linked Traceability Deployment | Cathode suppliers satisfy SAMR battery passport mandates and downstream OEM audit requirements. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, encompassing cathode precursor plant managers, CATL and BYD procurement executives, MIIT certification auditors, and Jiangsu-Zhejiang logistics coordinators. Secondary validation drew from MIIT NEV credit system filings, SAMR product quality audit records, Shanghai Metals Market price data, and MEE environmental review disclosures. Bottom-up volume estimates triangulated with top-down market sizing across material type and battery chemistry segments.
Across the analysis window, the forecasting framework modeled lithium, nickel, cobalt, and graphite material flows by cathode chemistry formulation, end-use vehicle category, and supplier type classification. CAGRs were derived from regression analysis of historical procurement intensity ratios and projected EV penetration curves. Key inputs included MIIT production access rule revisions, GB standard update cycles, and provincial dual carbon enforcement trajectories.
Underlying assumptions cover sustained MIIT credit system stringency and GB/T 31485 certification continuity, with deviation risk concentrated in solid-state chemistry substitution timelines and Indonesia nickel processing expansion rates. Practitioners should keep alternative scenarios live as provincial environmental enforcement intensity and cathode chemistry migration patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Italy Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Canada EV Battery Pack Market
EV Batteries
Electric Vehicle Battery Coolant Market
EV Batteries
Cold-Climate Optimized EV Battery Systems Market
EV Batteries
Europe Electric Vehicle Battery Manufacturing Market
EV Batteries
North America Electric Vehicle Battery Materials Market
EV Batteries
Electric Vehicle Battery Conditioners Market
EV Batteries
EV Batteries Market
EV Batteries
Asia-Pacific Electric Vehicle Battery Market
EV Batteries
United Kingdom Electric Vehicle Battery Materials Market
EV Batteries
Asia-Pacific Electric Vehicle Solid State Battery Market
EV Batteries
Europe Electric Vehicle VRLA Batteries Market
EV Batteries
South Korea Electric Vehicle Battery Market
EV Batteries
Thermal Interface Material for EV Battery Market
EV Batteries
Europe Electric Vehicle Solid State Battery Market
EV Batteries
South America Electric Vehicle Battery Anode Market