
 Japan EV Battery Pack Market | 2026-2036
Japan EV Battery Pack Market Size, Share, and Industry Trends Forecast 2026-2036
Japan EV Battery Pack Market Insights
Direct OEM supply contracts is reconfiguring how Japanese automakers secure battery capacity and intellectual property. Panasonic leverages its long-standing Tesla partnership to sustain cylindrical cell expertise and manufacturing scale. Prime Planet Energy & Solutions anchors Toyota's hybrid and full-electric ambitions through dedicated prismatic cell output. CATL competes aggressively on cost, forcing domestic pack assemblers to differentiate through localized engineering and faster cycle development.
An EV battery pack integrates cells, modules, thermal management hardware, and battery management electronics into a sealed structural unit rated typically between 300 and 800 volts, with energy densities ranging from 150 to 300 watt-hours per kilogram depending on cathode chemistry. Its primary purpose is to store and deliver electrical energy to traction motors while maintaining thermal stability across temperature extremes and charge cycles. Lithium-ion chemistries still dominate installed capacity, though solid-state configurations are attracting disproportionate engineering investment due to their potential for higher energy density and reduced fire risk. Among end users, passenger vehicles command the largest share of pack value, while commercial vehicle electrification is expanding fastest as logistics operators face emissions compliance deadlines. Thermal management technology represents a critical margin pool because Japanese OEMs prioritize pack longevity in humid summer conditions.
METI enforces battery recycling mandates and domestic content targets that reshape supplier qualification requirements for pack integrators. JIS standards govern cell testing protocols, while PMDA oversight extends to materials safety in adjacent medical-device applications where battery reliability overlaps. Stakeholders must track how METI's next subsidy tranche allocates between solid-state pilot lines and existing lithium-ion capacity expansions, as this balance will determine which technology pathways receive manufacturing scale.
Market Dynamics
Japan's EV battery pack sector is reconfiguring around METI's solid-state technology roadmaps and the geographic concentration of cathode precursor supply chains in East Asia. Domestic OEMs now face binding choices between lithium-ion capacity expansion and pilot-line investment for next-generation chemistries.
Growth Catalysts
- Passenger vehicle electrification mandates:METI's domestic content targets force pack integrators to localize cell sourcing and module assembly. Tier-1 suppliers are qualifying Japanese-made cathode materials to meet subsidy thresholds.
- Commercial logistics compliance deadlines:Fleet operators in the Kanto corridor face emissions penalties that accelerate demand for heavy-duty pack configurations. Last-mile delivery electrification is pulling forward medium-format battery orders.
- Solid-state pilot production incentives:Government funding for sulfide-based electrolyte manufacturing is redirecting R&D expenditure toward dry electrode coating processes. This technology pathway promises higher volumetric energy density for premium passenger applications.
Market Restraints
- Lithium carbonate price volatility:Cathode material input costs swing with spot market conditions in South American and Australian mining jurisdictions. Japanese pack assemblers lack backward integration into upstream extraction.
- Cell supply concentration in Northeast Asia:Cylindrical and prismatic cell production clusters in South Korea and China expose Japanese OEMs to shipping disruptions and trade policy friction. Single-source dependencies for high-nickel cathodes amplify vulnerability.
- Recycling infrastructure maturity gaps:METI mandates aggressive recovery rates for cobalt and lithium, yet domestic hydrometallurgical processing capacity remains underdeveloped. Compliance costs fall disproportionately on smaller pack integrators.
Strategic Opportunities
- Second-life stationary storage applications:Retired automotive packs from Tokyo-Yokohama fleets are repurposed for grid-balancing installations in Hokkaido wind corridors. Degradation mapping and module reconditioning create aftermarket revenue streams.
- Dual-carbon policy alignment:METI's industrial decarbonization framework ties battery procurement to Scope 3 emissions accounting. Pack suppliers with verified low-carbon cell sourcing gain preferential qualification status.
- Silicon-anode technology convergence:Pre-lithiation methods and nanostructured silicon composites are extending cycle life in humid operating conditions. Japanese material suppliers with proprietary binder chemistries capture value from this interface innovation.
Industry Challenges
- Thermal management engineering talent scarcity:Pack integrators compete with semiconductor and aerospace sectors for computational fluid dynamics specialists. Simulation-driven design cycles stall without experienced hires.
- JIS certification timeline compression:Revised cell testing protocols for nail penetration and overcharge tolerance extend qualification periods. OEMs delay platform launches when pack variants fail accelerated aging validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan EV Battery Pack Market |
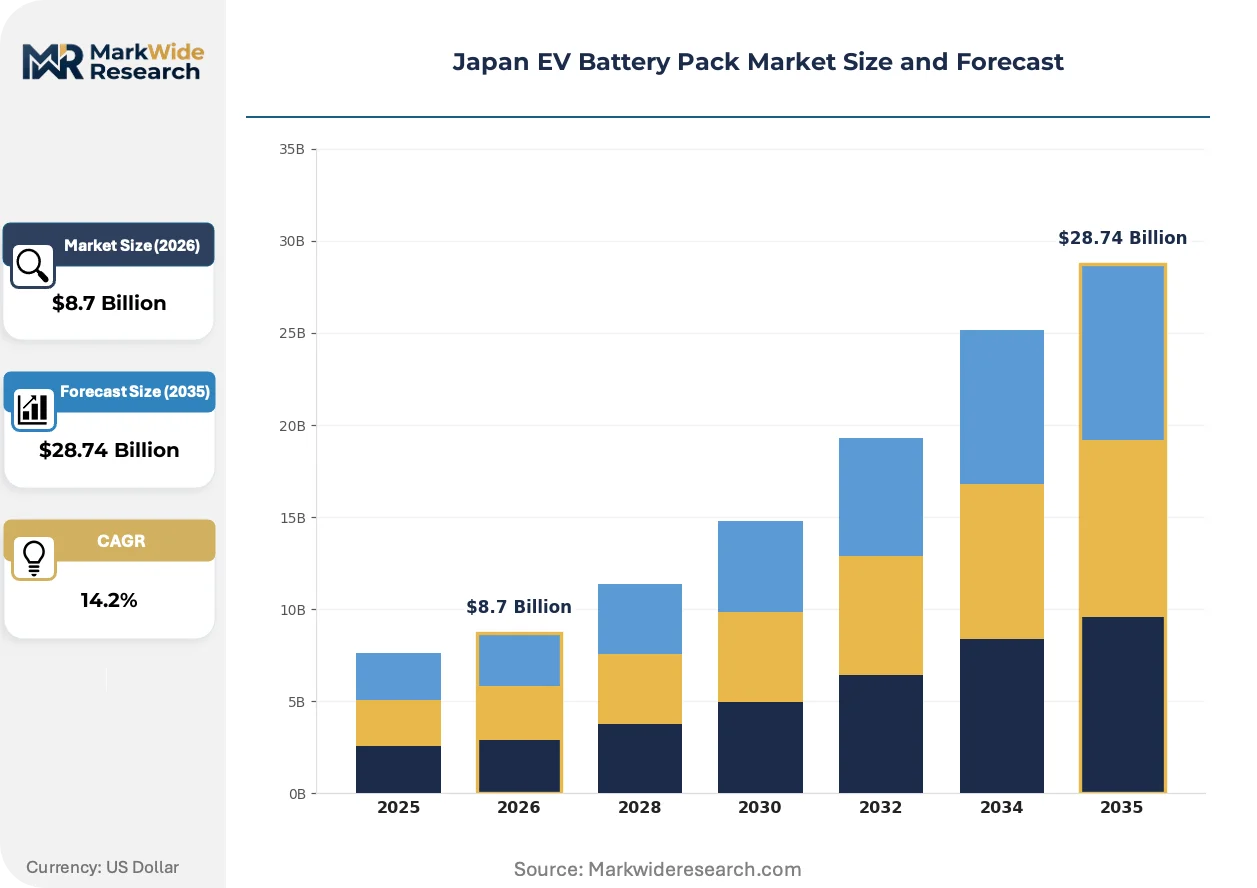
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel Manganese Cobalt, Solid-State, Lithium Iron Phosphate End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, E-Bikes Technology: Fast Charging, Modular Design, Battery Management Systems, Thermal Management Application: Grid Storage, Vehicle Electrification, Renewable Integration, Backup Power |
| Companies Covered | Panasonic, GS Yuasa Corporation, Prime Planet Energy & Solutions, Lithium Energy Japan, CATL, Toshiba Corporation, Hitachi Ltd, Primearth EV Energy, Mitsubishi Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan EV Battery Pack Market Trends and Innovations
Cell-to-pack architectures are eliminating module housings and interconnection hardware, compressing manufacturing cost structures while demanding precision in thermal interface materials. This structural simplification is reshaping supplier tiers and assembly automation requirements.
Cell-to-pack integration is collapsing the traditional module assembly tier. Panasonic and domestic competitors are adopting blade-style cell configurations that bond directly to the pack floorpan. Passenger OEMs in the Kanto region are qualifying these designs for 2027 platform launches. The structural consequence is a 15-20% reduction in non-cell mass that is collapsing the addressable market for aluminum module housings and wire-bonding equipment.
METI's battery supply chain resilience directives are mandating domestic cathode precursor production by 2030. The policy requires pack integrators to document provenance for lithium, nickel, and cobalt inputs. Tier-1 suppliers are forming offtake agreements with Japanese trading houses securing Australian and Canadian mining stakes. Pack assemblers serving Toyota and Nissan platforms face the strictest traceability audits, forcing ERP system upgrades and third-party verification contracts.
Fleet procurement is consolidating around total-cost-of-ownership contracts that bundle pack hardware with predictive maintenance analytics. Logistics operators in Osaka and Nagoya are rejecting traditional unit-price purchasing in favor of guaranteed uptime agreements. Channel intermediaries without diagnostic software capabilities are losing direct access to commercial vehicle accounts. This behavioral shift is most visible in refrigerated transport electrification, where thermal load profiles demand customized battery management calibration.
Japan EV Battery Pack Market Segmentation
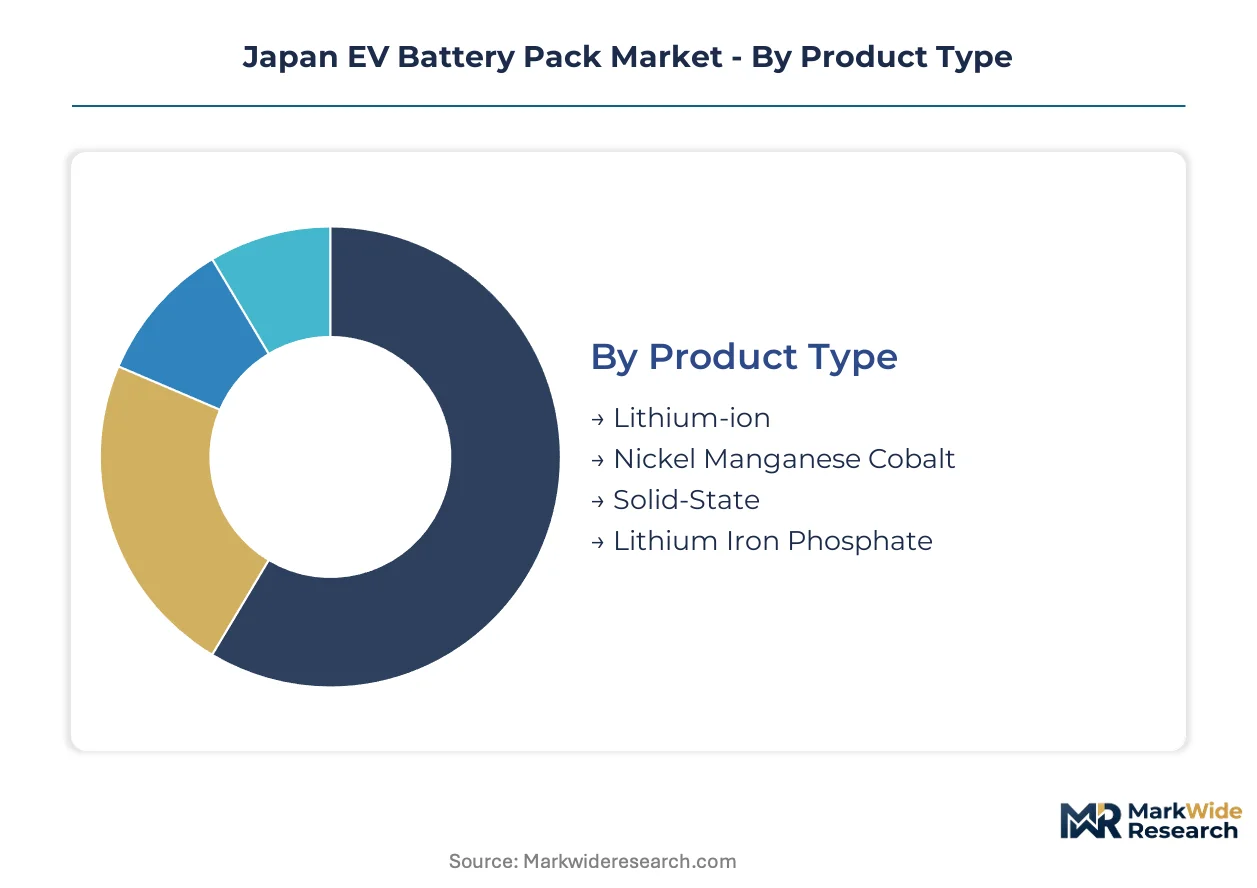
Segmentation in Japan's EV battery pack market reveals how METI policy, OEM platform requirements, and thermal engineering constraints fragment procurement patterns across chemistry types and end-use applications. Understanding these divisions exposes where pack integrators must build specialized capabilities versus scalable commodity production.
Product Type:
After-sales-service intensity varies sharply across chemistry families, with solid-state architectures demanding entirely different diagnostic protocols and technician certification than conventional lithium-ion systems.
- Lithium-ion:Dominant installed base using graphite anodes and layered oxide cathodes in cylindrical or prismatic formats. Kanto-region passenger OEMs specify these for current platform generations where supply chain maturity outweighs energy density gains.
- Nickel Manganese Cobalt:High-nickel variants deliver superior volumetric density for premium sedan applications. Toyota and Nissan procurement teams prioritize NMC for long-range configurations where pack mass directly impacts vehicle efficiency ratings.
- Solid-State:Sulfide-electrolyte pilot lines receive METI funding for 2030 commercialization targets. Dry electrode coating processes require new failure-mode analysis protocols before service networks can support field deployment.
- Lithium Iron Phosphate:Lower energy density compensated by thermal stability and cobalt-free supply chains. Commercial fleet operators in Osaka-Nagoya corridors specify LFP for duty cycles where battery longevity dominates acquisition cost.
By volume, Lithium-ion leads. By growth pace, Solid-State is ahead.
End User:
Customer procurement sophistication separates segments, with logistics fleets negotiating outcome-based contracts while passenger OEMs retain traditional unit-price frameworks.
- Passenger Vehicles:Platform-integrated pack designs with 400-800V architectures and liquid cooling circuits. Tokyo-Yokohama metropolitan demand concentrates here, driven by residential charging infrastructure expansion and emissions zone enforcement.
- Commercial Vehicles:Heavy-duty configurations with reinforced thermal management for continuous high-current discharge. Refrigerated transport electrification in the Kanto corridor pulls specialized pack orders with customized battery management calibration.
- Two-Wheelers:Compact swappable battery formats for delivery fleet standardization. Last-mile operators in dense urban districts prioritize interchangeability over energy density.
- E-Bikes:Lightweight pouch-cell assemblies with simplified management electronics. Municipal subsidy programs in Kyoto and Sapporo accelerate replacement of aging lead-acid systems.
Passenger Vehicles capture the largest revenue pool. Commercial Vehicles are climbing the fastest as compliance deadlines tighten.
Technology:
Technology selection determines which Japanese engineering subdisciplines—electrochemical modeling, thermal simulation, or power electronics—absorb R&D investment.
- Fast Charging:350kW-capable thermal architectures with advanced coolant flow distribution. Highway corridor charging infrastructure specifications from METI mandate these capabilities for intercity passenger applications.
- Modular Design:Serviceable subpack units enabling cell replacement without full pack retirement. Fleet operators with high utilization rates specify modularity to minimize downtime during maintenance windows.
- Battery Management Systems:Model-predictive control algorithms optimizing charge acceptance across temperature ranges. Silicon-anode chemistries particularly demand refined state-of-charge estimation to prevent lithium plating.
- Thermal Management:Computational fluid dynamics-optimized cold plate geometries and phase-change materials. Humid Japanese summers make this a non-negotiable specification for OEM qualification.
Thermal Management commands the highest engineering premium. Fast Charging is gaining share fastest as infrastructure investment accelerates.
Application:
Application context dictates whether pack designs prioritize cycle depth, standby longevity, or rapid response characteristics.
- Grid Storage:Containerized megawatt-hour installations using retired automotive cells. Hokkaido wind corridor developers source these for frequency regulation services.
- Vehicle Electrification:Structural pack integration with crashworthiness and NVH requirements. Platform engineering teams in Toyota City and Yokohama specify these for dedicated EV architectures.
- Renewable Integration:Buffer storage smoothing solar and wind output variability. Rural prefectures with high renewable penetration drive procurement here.
- Backup Power:Stationary installations for commercial and critical infrastructure resilience. Data center operators in Osaka specify these alongside uninterruptible power supply systems.
Vehicle Electrification dominates current output. Grid Storage represents the steepest expansion trajectory as second-life supply chains mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's subsidy frameworks and domestic content mandates are redistributing battery pack investment across Japan's industrial corridors, with procurement patterns diverging sharply between passenger OEM clusters and commercial fleet hubs.
Kanto
Tokyo-Yokohama metropolitan demand concentrates passenger vehicle pack procurement, driven by residential charging infrastructure buildout and emissions zone enforcement. METI's battery supply chain resilience directives require pack integrators to document cathode material provenance for qualification. Toyota City and Yokohama platform engineering teams specify structural pack integration with crashworthiness requirements for dedicated EV architectures launching through 2027.
Kansai
Osaka-Nagoya logistics corridors accelerate commercial vehicle electrification as fleet operators face binding emissions compliance deadlines. Fleet procurement is consolidating around total-cost-of-ownership contracts bundling pack hardware with predictive maintenance analytics. Nagoya-based pack assemblers are qualifying heavy-duty configurations with reinforced thermal management for refrigerated transport electrification.
Kyushu
Industrial decarbonization frameworks in Fukuoka and Kitakyushu are pulling grid storage installations using retired automotive packs from Kanto fleets. Hokkaido wind corridor developers source these containerized megawatt-hour systems for frequency regulation services. Second-life supply chain infrastructure is maturing around degradation mapping and module reconditioning capabilities.
Chubu
Nagoya's automotive supplier density supports cell-to-pack architecture adoption, with blade-style cell configurations bonding directly to pack floorpans. Dry electrode coating processes for sulfide-electrolyte pilot lines are redirecting R&D expenditure toward 2030 commercialization targets. Local pack integrators face JIS certification timeline compression for revised cell testing protocols.
Hokkaido
Rural renewable integration projects drive buffer storage procurement smoothing solar and wind output variability. Data center operators in Sapporo specify stationary backup power installations alongside uninterruptible power supply systems. Municipal subsidy programs accelerate replacement of aging lead-acid systems in e-bike applications.
Japan EV Battery Pack Market Competitive Landscape
On the supply side, the industry is consolidating around direct OEM supply contracts and dedicated joint ventures that lock in capacity and intellectual property. Japanese automakers are reconfiguring procurement relationships to secure cylindrical and prismatic cell expertise while defending against cost-competitive Chinese entrants. Three archetypes dominate: legacy electronics conglomerates with long-standing automotive relationships, battery specialists formed through OEM joint ventures, and Chinese scale players competing on unit economics. Capacity expansion and strategic partnerships represent the dominant competitive moves, with domestic players prioritizing solid-state pilot lines and foreign competitors establishing localized engineering presence.
Within the legacy conglomerate tier, Panasonic and Toshiba Corporation occupy positions anchored by decades of electronics manufacturing expertise and established automotive customer relationships. Prime Planet Energy & Solutions exemplifies the OEM-captive joint venture archetype, formed specifically to anchor Toyota's electrification roadmap through dedicated cell output. CATL represents the foreign scale entrant, forcing domestic pack assemblers to differentiate through faster cycle development and localized engineering services rather than manufacturing cost alone.
| Leading Market Players |
|---|
| Panasonic |
| GS Yuasa Corporation |
| Prime Planet Energy & Solutions |
| Lithium Energy Japan |
| CATL |
| Toshiba Corporation |
| Hitachi Ltd |
| Primearth EV Energy |
| Mitsubishi Corporation |
| Others |
Pricing and Supply Chain Analysis
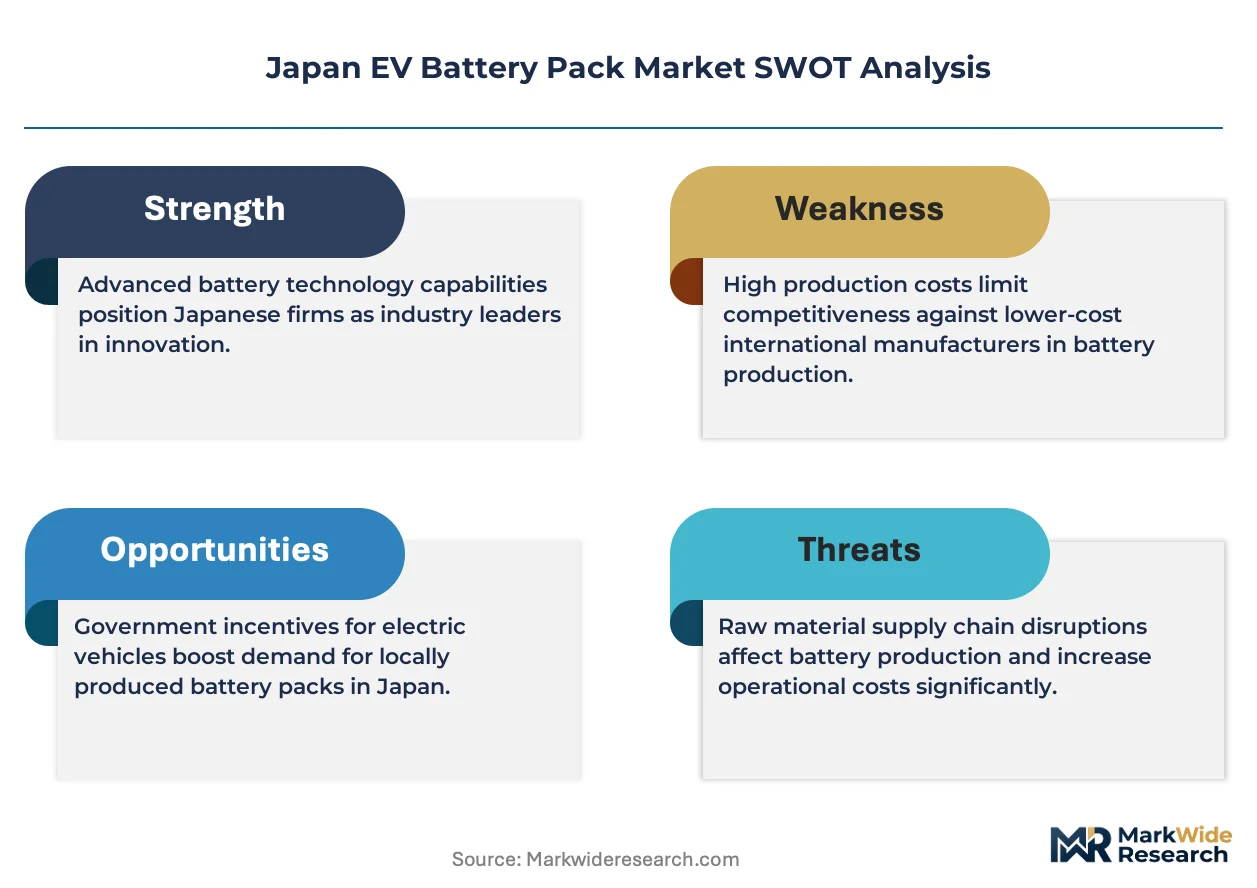
High-nickel cathode precursor concentration in South Korean and Chinese smelters funnels pricing power to trading houses controlling offtake contracts, leaving Japanese pack assemblers to extract margin from thermal management engineering and fast-cycle development services rather than cell commodity arbitrage.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement contracts, with differentiation driven by JIS certification grade and guaranteed cycle-life thresholds. Premium tiers bundle predictive maintenance analytics and extended warranty coverage for refrigerated transport fleets. Cost compression in the standard tier intensifies as CATL expands localized engineering presence. Commercial vehicle operators exhibit highest price sensitivity, while passenger OEMs prioritize qualification speed over unit cost.
Supply Chain Analysis
Export-control regimes limiting high-purity lithium hydroxide and nickel sulfate processing technology transfers constrain Japanese cathode material self-sufficiency ambitions. Cell production draws from South Korea, China, and domestic pilot lines. Raw material dependencies center on Australian spodumene, Chilean brine, and Indonesian nickel laterite. Single-source vulnerability in sulfide-electrolyte precursor supply amplifies risk exposure. Distribution runs through direct OEM supply contracts with dedicated joint venture structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where METI's domestic content mandates and JIS certification timelines create switching costs that protect qualified suppliers from cost-competitive foreign entrants.
For Market Incumbents: Pre-empt solid-state pilot line capacity allocation by securing METI subsidy tranches before qualification thresholds tighten. Lock in cathode precursor offtake with Australian and Canadian mining stakes to defend against trading house margin capture. Deepen backward integration into dry electrode coating equipment to preserve technology differentiation as Chinese cell producers expand localized service presence.
For New Entrants and Emerging Players: Kyushu's second-life grid storage infrastructure presents underpenetrated aftermarket service potential where degradation mapping capabilities remain scarce. Target Hokkaido wind corridor developers with containerized repurposed pack offerings bundled with predictive state-of-health monitoring. Enter through diagnostic software partnerships rather than manufacturing scale competition.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed thermal management engineering boutiques possessing computational fluid dynamics talent pools and JIS-certified testing facilities. Five-to-ten-year viability hinges on solid-state chemistry convergence timelines rather than lithium-ion commodity positioning. Monitor METI's subsidy allocation balance between pilot-line funding and existing capacity expansion as the inflection signal for technology pathway winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Pilot Line Investment | METI funding access determines which suppliers qualify for 2030 commercialization targets. |
| Cathode Precursor Offtake Agreement | Australian and Canadian mining stakes satisfy domestic content mandates for Toyota and Nissan qualification. |
| Thermal Management Engineering Acquisition | Computational fluid dynamics talent scarcity makes specialized boutiques attractive consolidation targets. |
| Second-Life Supply Chain Buildout | Kyushu grid storage demand creates aftermarket revenue streams from retired Kanto automotive packs. |
| Battery Management System Platform Integration | Predictive analytics bundling locks in commercial fleet accounts shifting to outcome-based contracts. |
Research Methodology
Operator-level perspectives from OEM platform engineers, Tier 1 procurement leads, thermal management specialists, and METI policy officers anchored the qualitative base. Secondary validation drew from JIS standard revision filings, METI subsidy disbursement records, vehicle production databases, and customs trade data for cathode material flows. Bottom-up cell capacity estimates triangulated against top-down passenger and commercial vehicle electrification targets.
Scenario-bracketing around solid-state commercialization timelines and lithium carbonate price volatility bands shaped the analytical framework. Segmentation dimensions modeled include chemistry family, end-use application, thermal architecture complexity, and regional production cluster. CAGRs derived from installed base growth curves and replacement cycle assumptions. Pack-level cost structures incorporated cell commodity indices and non-cell mass reduction trajectories from cell-to-pack adoption.
Practitioners should monitor METI subsidy reallocation between pilot-line and lithium-ion expansion tranches for early signals of technology pathway prioritization. Forecasts reflect assumptions around JIS certification timeline compression and trading house offtake contract structures. Material shifts in sulfide-electrolyte precursor supply availability or export-control regime expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Asia-Pacific Electric Vehicle Battery Market
EV Batteries
North America Electric Vehicle Battery Materials Market
EV Batteries
Middle-East Electric Vehicle Battery Market
EV Batteries
United Kingdom Electric Vehicle Battery Manufacturing Market
EV Batteries
EV Battery Heating System Market
EV Batteries
Canada Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
China Electric Vehicle Battery Materials Market
EV Batteries
North America Electric Vehicle VRLA Batteries Market
EV Batteries
Electronic Vehicle (EV) Cells Market
EV Batteries
EV Batteries Market
EV Batteries
Curved Lipo Battery Market
EV Batteries
Electric Vehicle Battery Thermal Management Systems Market
EV Batteries
Electric Vehicle Battery Coolant Market
EV Batteries
Italy Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
North America Electric Vehicle Battery Anode Market