
 Canada EV Battery Pack Market | 2026-2036
Canada EV Battery Pack Market Size, Share, and Industry Trends Forecast 2026-2036
Canada EV Battery Pack Market Insights
Cell-to-pack architecture is tilting Canadian battery assembly away from modular designs toward integrated thermal-electric structures. LG Energy Solution leverages its joint venture footprint in Ontario to anchor cell production near vehicle assembly plants. Tesla Inc. sustains proprietary 4680-format integration through its vertical cell-pack design philosophy. Northvolt AB competes on sustainable cathode chemistry sourcing to differentiate its expansion roadmap into North American supply chains.
An EV battery pack is an electrochemical energy storage system comprising cells, modules, thermal management layers, and battery management circuitry, typically operating at 300-800 volts DC and designed for cycle life exceeding 1,000 deep-discharge cycles in automotive duty. Its primary purpose is to deliver sustained propulsion power while maintaining thermal stability across ambient temperature ranges from -30°C to 60°C. Lithium-ion chemistry dominates installed capacity due to mature supply chains and energy density thresholds above 250 Wh/kg at cell level. Passenger vehicles command the largest application share, though commercial vehicle configurations are widening module form factors and cooling architectures. Fast charging technology is reshaping pack design priorities, pushing silicon-anode adoption and liquid-cooled connector standards to sustain 350 kW input rates without cell degradation.
Transport Canada enforces the Motor Vehicle Safety Act and CMVSS 305 electrical isolation standards, while Environment and Climate Change Canada administers the federal zero-emission vehicle mandate requiring escalating annual sales percentages. Health Canada/PMRA monitors electrolyte chemical handling protocols at gigafactory sites, and provincial regulators in Ontario and Quebec layer building code and fire suppression requirements on battery storage facilities. Natural Resources Canada funds critical mineral processing capacity to reduce import dependency for lithium, nickel, and cobalt feedstocks. Stakeholders must monitor how provincial ZEV rebate harmonization and interprovincial grid capacity investments alter pack sizing and charging infrastructure deployment timelines.
Market Dynamics
Cell-to-pack architecture is collapsing the modular intermediary layer between cell production and vehicle integration, forcing Windsor-to-Toronto corridor assemblers to retool thermal management and structural bonding capabilities simultaneously.
Growth Catalysts
- Federal ZEV Mandate Escalation:Environment and Climate Change Canada's annual sales percentage requirements compel OEMs to secure domestic pack assembly capacity, tightening supplier qualification timelines.
- Critical Mineral Processing Investments:Natural Resources Canada funding for lithium, nickel, and cobalt feedstock capacity reduces import dependency and shortens cathode active material supply chains.
- Silicon-Anode Chemistry Maturation:Fast-charging infrastructure deployment at 350 kW input rates drives adoption of advanced anode formulations, expanding pack energy density without cell degradation penalties.
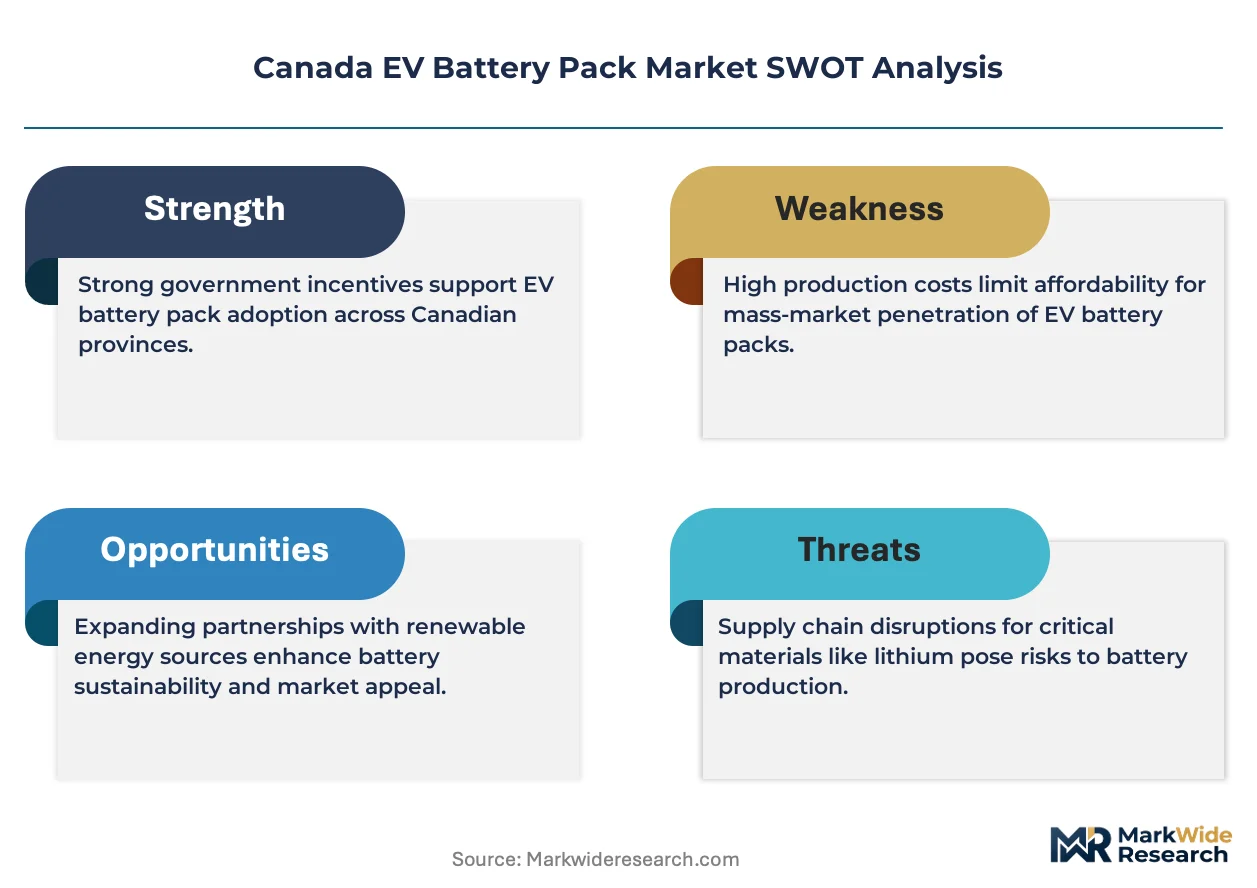
Market Restraints
- Electrolyte Chemical Handling Protocols:Health Canada/PMRA oversight of gigafactory site operations imposes layered compliance costs and extended permitting timelines.
- Skilled Labor Pool Concentration:Ontario's Windsor-to-Toronto corridor absorbs the majority of qualified thermal engineers and battery management system programmers, constraining expansion elsewhere.
- Cell Chemistry Import Dependency:Cathode precursor processing remains concentrated outside Canadian borders, exposing pack assemblers to feedstock price volatility and logistics bottlenecks.
Strategic Opportunities
- Quebec Grid-Coupled Storage Integration:Provincial hydroelectric capacity supports vehicle-to-grid pack architectures, creating second-life revenue streams for retired automotive batteries.
- Commercial Vehicle Module Widening:Heavy-duty truck and bus configurations demand expanded form factors and alternative cooling architectures, opening specialized assembly niches.
- Provincial ZEV Rebate Harmonization:Interprovincial alignment of consumer incentive programs would standardize pack sizing requirements and accelerate charging infrastructure deployment timelines.
Industry Challenges
- Battery Management System Firmware Integration:OEMs demand proprietary control algorithms, forcing pack assemblers to maintain parallel software development tracks.
- Fire Suppression Building Code Compliance:Ontario and Quebec provincial regulators impose divergent storage facility requirements, complicating multi-site operational standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada EV Battery Pack Market |
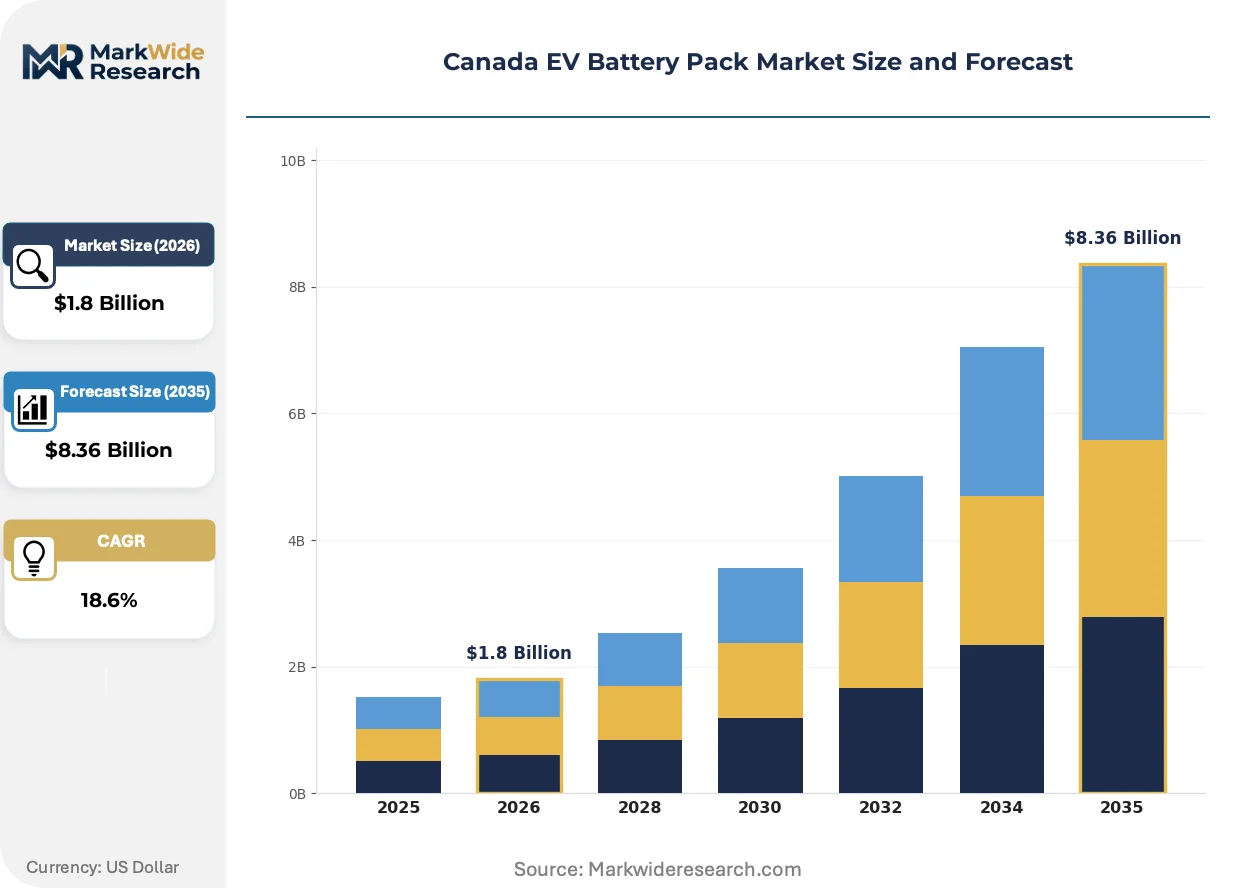
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead-acid, Nickel-metal Hydride, Solid-state End User: OEMs, Aftermarket Providers, Fleet Operators, Distributors Application: Passenger Vehicles, Commercial Vehicles, Two-wheelers, Specialty Vehicles Technology: Fast Charging, Wireless Charging, Battery Management Systems, Thermal Management Systems |
| Companies Covered | Tesla Inc., LG Energy Solution, BYD Company, Panasonic Corporation, Northvolt AB, Samsung SDI, Contemporary Amperex Technology Co. Limited, SK Innovation Co., Volkswagen Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada EV Battery Pack Market Trends and Innovations
Pack architecture is shedding redundant structural layers. Thermal-electric integration, regulatory chemistry disclosure, and procurement consolidation are compressing design cycles and supplier margins simultaneously.
Cell-to-pack bonding is collapsing the module frame and separate thermal interface materials into unified structural adhesives with embedded cooling channels. Ontario-based assemblers are adopting this approach to reduce mass and assembly steps. The consequence is collapsing the traditional tiered supplier structure where module specialists once captured intermediate value.
Transport Canada's CMVSS 305 electrical isolation standards are tightening verification protocols for high-voltage pack enclosures. This is forcing redesign of junction box sealing and disconnect actuator placement. Passenger vehicle OEMs are responding by consolidating validation testing at Windsor corridor facilities to reduce certification cycle times.
Fleet operators are consolidating procurement decisions at the provincial utility level rather than individual vehicle acquisition. This is displacing dealer-channel pack service contracts with direct OEM maintenance agreements. The shift is most visible in Quebec where Hydro-Québec's electrification programs bundle charging infrastructure with standardized pack warranty terms.
Canada EV Battery Pack Market Segmentation
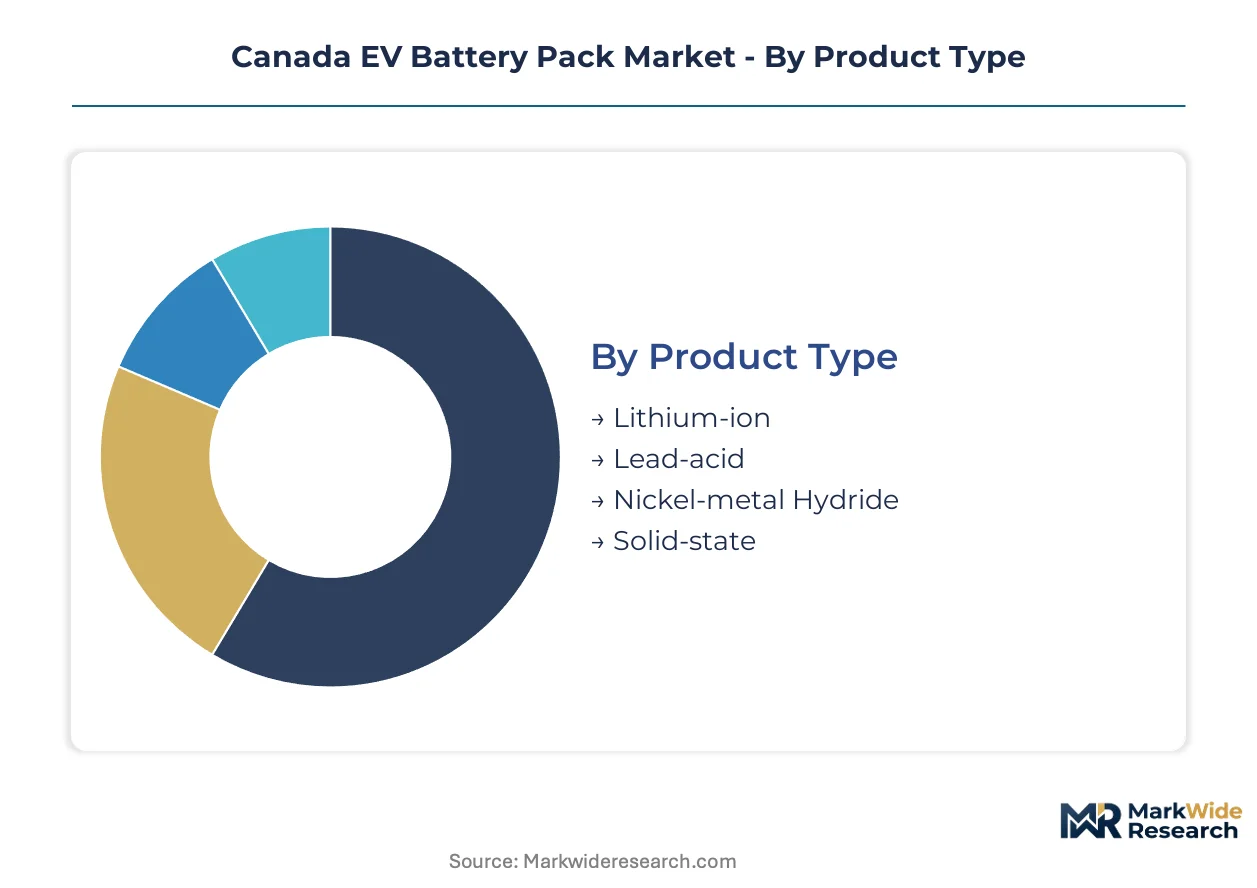
Canada's EV battery pack market segments along chemistry, customer type, vehicle class, and enabling technology. Each dimension carries distinct regulatory, thermal, and supply chain requirements that shape procurement patterns across Ontario's Windsor-to-Toronto corridor and beyond.
Product Type:
Cell chemistry determines energy density thresholds, thermal stability windows, and cathode precursor sourcing strategies across Canadian assembly facilities.
- Lithium-ion:Dominant chemistry employing nickel-manganese-cobalt or lithium-iron-phosphate cathodes with cell-level densities above 250 Wh/kg. OEM demand concentrates in Ontario passenger vehicle programs where federal ZEV mandates enforce minimum range specifications.
- Solid-state:Emerging architecture replacing liquid electrolytes with ceramic or polymer conductors to enable higher voltage operation and reduced thermal runaway risk. Quebec-based research partnerships with Hydro-Québec are accelerating prototype validation for next-generation vehicle integration.
- Lead-acid:Mature technology limited to auxiliary power applications and low-speed electric vehicles due to mass and cycle life constraints.
- Nickel-metal Hydride:Declining chemistry retained in select hybrid vehicle platforms where proven reliability outweighs energy density requirements.
The dominant share belongs to Lithium-ion, while Solid-state is closing the gap fastest.
End User:
Customer concentration patterns reflect procurement scale, technical integration depth, and service contract structures across the Canadian value chain.
- OEMs:Vehicle manufacturers specifying pack dimensions, thermal management interfaces, and battery management system firmware protocols. Windsor corridor assemblers qualify suppliers against CMVSS 305 electrical isolation standards and proprietary validation cycles.
- Fleet Operators:Provincial utility-led procurement programs in Quebec bundle standardized pack warranties with charging infrastructure deployment, displacing traditional dealer service channels.
- Aftermarket Providers:Independent service networks addressing replacement demand and second-life battery repurposing for stationary storage applications.
- Distributors:Intermediary channels serving regional repair facilities and specialty vehicle builders with smaller volume requirements.
OEMs command the largest procurement volumes, though Fleet Operators are expanding their share through utility-direct contracting models.
Application:
Vehicle class dictates pack form factor, cooling architecture, and duty cycle specifications across Canadian roads and industrial sites.
- Passenger Vehicles:Light-duty cars and SUVs requiring 60-100 kWh capacities with liquid-cooled cell-to-pack designs. Ontario's manufacturing corridor concentrates assembly capacity to serve Detroit Three and international brand programs.
- Commercial Vehicles:Heavy-duty trucks and buses demanding expanded module widths, alternative thermal architectures, and cycle life ratings exceeding 3,000 partial discharges. Natural Resources Canada funding targets this segment for depot-charging and long-haul electrification.
- Two-wheelers:Compact packs for electric motorcycles and scooters with simplified air-cooling and removable battery configurations.
- Specialty Vehicles:Customized solutions for mining equipment, agricultural machinery, and marine propulsion operating in extreme temperature ranges.
Passenger Vehicles retain the dominant position, while Commercial Vehicles are climbing fastest as federal and provincial freight electrification programs advance.
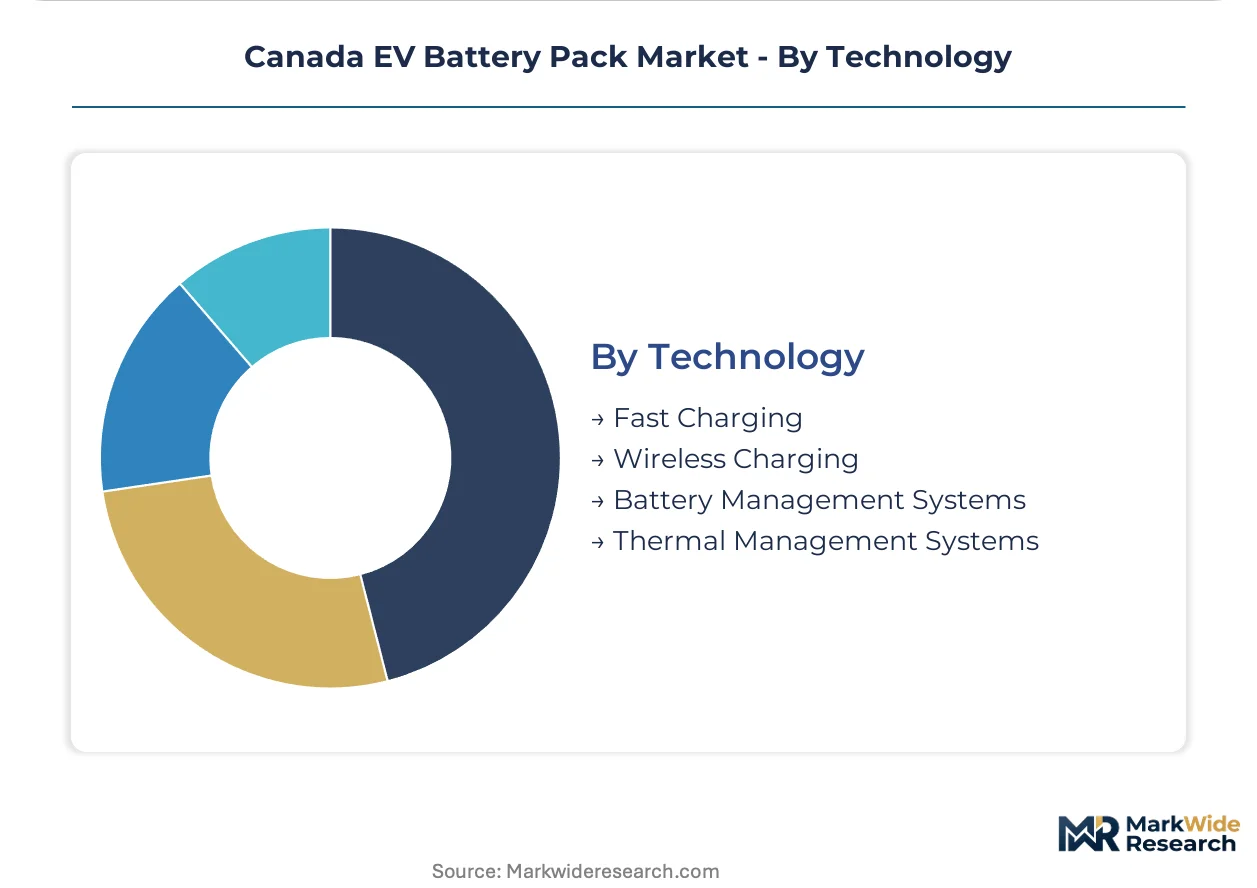
Technology:
Enabling systems determine charging speed, operational safety, and pack longevity across Canadian climate conditions from -30°C to 60°C.
- Fast Charging:350 kW input capability requiring silicon-anode chemistries and liquid-cooled connector standards to prevent lithium plating and cell degradation. Infrastructure deployment along Highway 401 corridor is driving pack design priorities.
- Thermal Management Systems:Integrated cooling channels, heat pumps, and phase-change materials maintaining cell temperature uniformity during high-rate discharge and regenerative braking. Ontario assemblers are adopting structural adhesive approaches that embed thermal pathways directly into pack enclosures.
- Battery Management Systems:Firmware and hardware monitoring cell voltages, temperatures, and state-of-charge with proprietary algorithms demanded by OEM customers.
- Wireless Charging:Inductive pad systems for fleet depot applications reducing connector wear and enabling automated charging sequences.
Fast Charging captures the largest technology investment, while Thermal Management Systems are gaining share fastest through cell-to-pack architectural transitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada exports EV battery packs predominantly to United States automotive assembly plants along the Great Lakes manufacturing belt. The Windsor-to-Toronto corridor functions as the primary production hub serving Detroit Three electrification programs. Cross-border supply chain integration intensifies as federal ZEV mandates on both sides of the border synchronize compliance timelines.
Ontario
Light-duty passenger vehicle OEM demand concentrates in the Windsor-to-Toronto corridor where cell-to-pack assembly investments absorb skilled thermal engineering labor. Environment and Climate Change Canada's federal ZEV mandate enforcement tightens supplier qualification timelines for St. Thomas and Alliston vehicle plants. LG Energy Solution anchors cell production through joint venture footprints in Windsor, co-locating cathode active material processing near final assembly operations.
Quebec
Hydro-Québec's provincial utility structure enables vehicle-to-grid pack architectures creating second-life revenue streams for retired automotive batteries. Health Canada/PMRA oversight of electrolyte chemical handling applies layered compliance costs to Bécancour gigafactory site operations. Northvolt AB competes on sustainable cathode chemistry sourcing from its Montreal-area research partnerships targeting North American supply chain expansion.
British Columbia
Provincial zero-emission vehicle mandate escalation predates federal requirements, compressing pack procurement lead times for Vancouver Island and Lower Mainland fleet operators. Natural Resources Canada critical mineral processing funding extends to British Columbia lithium exploration projects reducing import dependency. Vancouver tech clusters specialize in battery management system firmware development serving cross-border OEM customers.
Alberta
Commercial vehicle electrification programs target oil sands logistics and urban transit depot charging infrastructure expanding module form factor requirements. Provincial regulators layer building code and fire suppression requirements on Edmonton and Calgary battery storage facilities. Emerging cathode precursor research partnerships with University of Alberta laboratories address feedstock price volatility through domestic processing alternatives.
Canada EV Battery Pack Market Competitive Landscape
On the supply side, the industry is consolidating around integrated cell-to-pack assemblers with captive cathode material processing and thermal management capabilities. The vendor base stratifies between multinational battery specialists with joint venture footprints and vertically integrated automakers controlling proprietary cell formats. Two strategic archetypes dominate: chemistry-agnostic contract manufacturers serving multiple OEM programs, and captive producers optimizing pack-vehicle integration through in-house cell designs. Competitive moves center on securing critical mineral offtake agreements and accelerating cell-to-pack thermal bonding process yields.
Within the multinational specialist tier, LG Energy Solution and Panasonic Corporation occupy positions anchored by joint venture structures in Ontario manufacturing corridors. Tesla Inc. exemplifies the captive integration archetype through proprietary format control spanning cell design through vehicle assembly. Northvolt AB represents the sustainability-differentiated challenger model competing on cathode chemistry sourcing transparency for North American supply chain entry.
| Leading Market Players |
|---|
| Tesla Inc. |
| LG Energy Solution |
| BYD Company |
| Panasonic Corporation |
| Northvolt AB |
| Samsung SDI |
| Contemporary Amperex Technology Co. Limited |
| SK Innovation Co. |
| Volkswagen Group |
| Others |
Pricing and Supply Chain Analysis
The Highway 401 corridor's freight cost dynamics compress margins for cathode active material shipments while amplifying price differentiation between cell-to-pack assemblers and modular legacy suppliers. Supply concentration in Ontario's Windsor-to-Toronto manufacturing belt feeds downstream pricing power to OEMs with captive volume commitments, forcing tier-two pack integrators toward cost-plus contract structures.
Pricing Analysis
Current-generation lithium-ion NMC packs command premium positioning against prior-generation LFP configurations and pre-commercial solid-state prototypes. Contract-based long-term offtake dominates OEM procurement, with price differentiation resting on cathode chemistry grade and CMVSS 305 certification tier. Cost compression in standard-density packs is intensifying because silicon-anode tooling investments demand volume guarantees. Fleet operators exhibit highest price sensitivity, while captive OEM integrators absorb premium positioning for proprietary thermal management.
Supply Chain Analysis
Extended payment terms from OEM customers strain cathode precursor suppliers, accelerating supply-chain finance facility adoption among Korean and Japanese material processors. Geographic supply concentration centers on China for cathode active material, South Korea for electrolyte formulations, and Australia for spodumene concentrate. Raw material dependencies include lithium hydroxide, nickel sulfate, and cobalt metal. Single-source vulnerability in high-purity electrolyte solvents exposes assemblers to logistics chokepoint risk. Distribution runs through Windsor corridor direct-to-plant delivery, bypassing traditional warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against hydrogen fuel cell commercial vehicle platforms, which threaten long-haul battery pack demand as Alberta freight electrification programs mature.
For Market Incumbents: Build captive cathode precursor processing moats through backward integration into Bécancour refining capacity. Secure long-term offtake agreements with Australian spodumene miners to hedge feedstock volatility. Defend against Northvolt's sustainability-differentiated entry by accelerating carbon footprint certification for Ontario cell production.
For New Entrants and Emerging Players: Establish a beachhead in commercial vehicle module widening, where heavy-duty truck form factors remain underserved by incumbent passenger-focused assemblers. Target Alberta oil sands logistics electrification programs for pilot deployment. Lead with vehicle-to-grid integration capabilities that Hydro-Québec's utility structure rewards through standardized warranty bundling.
For Investors and Strategic Acquirers: Carve-out targets emerge from automotive OEMs spinning non-core battery management system firmware divisions. Five-to-ten-year viability hinges on cell-to-pack process yield mastery rather than chemistry IP alone. Monitor silicon-anode pilot production announcements as the inflection signal for next-generation energy density leadership.
| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Precursor Backward Integration | Bécancour refining capacity reduces import dependency for nickel sulfate and cobalt feedstocks. |
| Cell-to-Pack Thermal Bonding Scale-Up | Ontario assemblers adopting structural adhesive approaches collapse module supplier tier value capture. |
| Vehicle-to-Grid Firmware Development | Quebec Hydro-Québec bundling creates second-life revenue streams for retired automotive batteries. |
| Silicon-Anode Chemistry Partnership | Fast-charging infrastructure deployment along Highway 401 demands advanced anode formulations. |
| CMVSS 305 Certification Consolidation | Windsor corridor testing facilities reduce electrical isolation validation cycle times for OEM customers. |
Research Methodology
A standing panel of OEM platform engineers, Tier 1 supplier procurement leads, gigafactory operations managers, and Natural Resources Canada program officers provided ongoing calibration across primary interview cycles. Secondary validation drew from Transport Canada CMVSS filings, Environment and Climate Change Canada ZEV mandate enforcement data, IHS Markit vehicle production databases, and provincial utility electrification program disclosures. Bottom-up cell production capacity estimates triangulated against top-down OEM electrification platform announcements.
Scenario-bracketing framed projections across conservative, baseline, and accelerated ZEV mandate compliance pathways. Segmentation dimensions modeled include cell chemistry, vehicle class, thermal management architecture, and regional production cluster. CAGRs were derived from installed capacity buildout trajectories and OEM platform launch timelines. Forecast inputs incorporated cathode active material price elasticity and silicon-anode yield learning curves.
Stress conditions across lithium carbonate price volatility, federal ZEV mandate enforcement timing, and cross-border tariff exposure were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding cell-to-pack adoption rates and critical mineral processing capacity commissioning. Macroeconomic contraction, regulatory delay, or solid-state chemistry breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Canada Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Europe Electric Vehicle VRLA Batteries Market
EV Batteries
Italy Electric Vehicle Battery Manufacturing Market
EV Batteries
Europe Electric Vehicle Solid State Battery Market
EV Batteries
South America Electric Vehicle VRLA Batteries Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Electric Vehicle Battery Market
EV Batteries
Thermal Interface Material for EV Battery Market
EV Batteries
Electric Vehicle Battery Conditioners Market
EV Batteries
South America Electric Vehicle Battery Manufacturing Market
EV Batteries
Middle-East Electric Vehicle Battery Market
EV Batteries
United Kingdom Electric Vehicle Battery Manufacturing Market
EV Batteries
France EV Battery Pack Market
EV Batteries
Middle-East and Africa Electric Vehicle Battery Anode Market
EV Batteries
Canada Electric Vehicle Battery Manufacturing Market
EV Batteries
Asia-Pacific EV Battery Pack Market