
 United States Electric Vehicle Battery Manufacturing Market | 2026-2036
United States Electric Vehicle Battery Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
United States Electric Vehicle Battery Manufacturing Market Insights
Aftermarket service revenue for battery diagnostics and second-life repurposing is fragmenting as original equipment manufacturers build captive service networks. Tesla sustains vertical integration from raw material contracts through pack assembly at its Nevada operations. SK On anchors its position through joint ventures with domestic automakers in Georgia and Tennessee. Panasonic competes by specializing in high-energy cylindrical cells for performance-oriented platforms.
United States Electric Vehicle Battery Manufacturing encompasses the domestic production of electrochemical energy storage systems, typically featuring nickel-cobalt-manganese or lithium-iron-phosphate cathode formulations with graphite or silicon-composite anodes, assembled through electrode coating, calendering, electrolyte filling, and formation cycling for traction power in electrified transport. The primary purpose is to supply cost-competitive, thermally stable, high-cycle-life packs that meet OEM range and safety specifications for mass-market vehicle electrification. Lithium-ion chemistry dominates current installed capacity, though solid-state architectures are attracting capital as the fastest-growing technology segment due to their potential for higher energy density and reduced thermal runaway risk. Passenger vehicles absorb the majority of cell output, but commercial vehicle applications are deepening order backlogs as fleet operators electrify last-mile delivery and regional haul routes.
The EPA tailpipe emission standards and NHTSA fuel economy regulations are tightening compliance pathways, effectively mandating battery electric vehicle penetration across light-duty and medium-duty fleets. The Inflation Reduction Act's domestic content bonus credits and FERC interconnection reforms are reshaping where manufacturers site cell plants and how they secure qualifying mineral supply. Stakeholders must monitor how IRA foreign entity of concern rules evolve to determine which cathode active material suppliers remain eligible for consumer tax credits.
Market Dynamics
Domestic content requirements embedded in federal tax credit structures are forcing cathode active material suppliers to relocate processing capacity from Asia to North American soil, compressing established supply relationships and accelerating greenfield investment timelines.
Growth Catalysts
- IRA Domestic Content Bonuses:The Inflation Reduction Act's critical mineral and battery component thresholds create immediate pull-through for qualifying cell production, redirecting capital toward Michigan and Tennessee gigafactory corridors.
- Fleet Electrification Mandates:Last-mile delivery operators and regional haul carriers are electrifying vehicle pools under EPA tailpipe compliance pressure, generating concentrated demand for heavy-duty battery pack formats.
- Solid-State R&D Inflection:Silicon-composite anode architectures and sulfide electrolyte formulations are attracting venture capital at pre-commercial scale, promising energy density step-changes for premium passenger platforms.
Market Restraints
- Lithium Carbonate Volatility:Spodumene concentrate and brine-derived lithium prices swing on Australian and Chilean export volumes, compressing cell producer margins during upstream tightness.
- Cathode Concentration Risk:Nickel sulfate and cobalt hydroxide refining remains concentrated in Indonesian and Congolese processing hubs, exposing domestic manufacturers to foreign entity of concern disqualification under IRA eligibility rules.
- Graphite Supply Lock-In:Synthetic and natural anode material production is dominated by Chinese producers subject to tariff and sourcing scrutiny, limiting qualified supplier pools for US-assembled cells.
Strategic Opportunities
- Second-Life Repurposing:Retired EV packs retain 70-80% usable capacity for stationary storage applications, opening revenue streams for battery lifecycle managers serving Texas and California grid operators.
- Direct Lithium Extraction:Smackover Formation brine projects in Arkansas and California's Salton Sea promise domestic lithium carbonate supply, reducing import dependency for cathode precursor manufacturing.
- Commercial Vehicle Fast-Charging:Megawatt-scale charging infrastructure deployment along Interstate highway corridors enables battery-electric long-haul trucking, expanding addressable market beyond urban delivery routes.
Industry Challenges
- Electrolyte Formulation Expertise Gap:Domestic talent pools lack depth in non-flammable electrolyte salt chemistry and high-voltage additive stabilization, forcing reliance on imported technical specialists.
- Formation Cycling Bottlenecks:Cell conditioning and aging protocols require 14-21 days of controlled environment capacity, constraining throughput at greenfield facilities before yield optimization matures.
- UN 38.3 Certification Timelines:Lithium-ion cell transport safety testing and UN Manual of Tests and Criteria compliance create 4-6 month delays between production readiness and commercial shipment authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Electric Vehicle Battery Manufacturing Market |
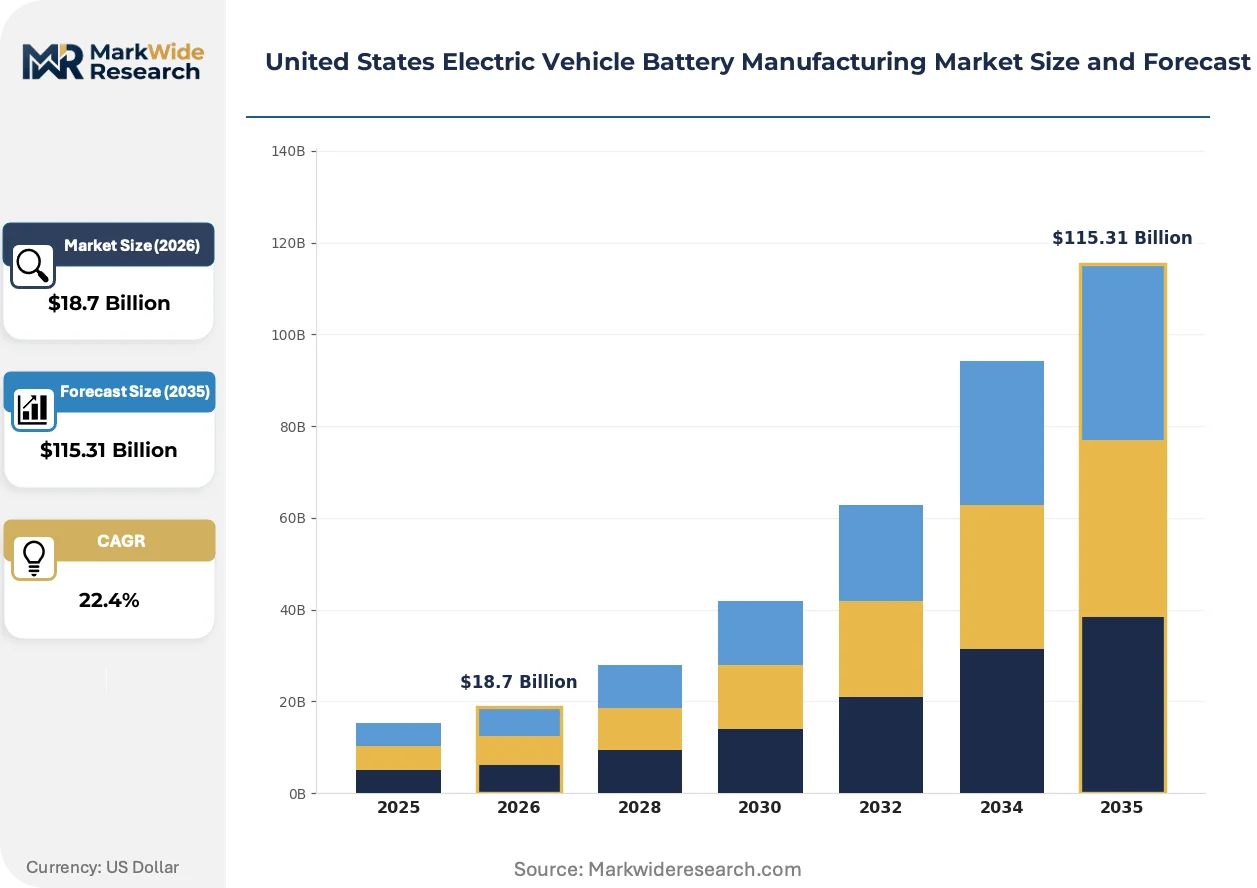
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-ion, Nickel-metal Hydride, Lead-acid, Solid-state End User: Automakers, Fleet Operators, Public Transport, E-Bike Manufacturers Technology: Fast Charging, Wireless Charging, Battery Management Systems, Energy Density Application: Passenger Vehicles, Commercial Vehicles, Industrial Equipment, Energy Storage |
| Companies Covered | LG Energy Solution, Tesla, Panasonic, SK On, General Motors, Samsung SDI, Ford Motor Company, Northvolt, Microvast, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Electric Vehicle Battery Manufacturing Market Trends and Innovations
Cell architecture evolution and cathode chemistry diversification are compressing legacy cost-performance tradeoffs, while IRA compliance mechanics reshape where and how manufacturers source qualifying materials.
Dry electrode coating is collapsing the capital intensity and solvent recovery burden of traditional wet slurry processes. SK On and domestic joint venture partners are piloting binder fibrillation techniques in Georgia facilities, eliminating N-methyl-2-pyrrolidone solvent handling and reducing drying oven footprints by 40%. This process compression enables faster production ramp and lower energy intensity per kilowatt-hour of cell output.
The EPA's finalized light-duty vehicle emission standards through 2032 are mandating battery electric vehicle penetration curves that exceed prior industry planning assumptions. Automakers are responding by consolidating cell supply agreements with domestic producers capable of meeting IRA domestic content thresholds, compressing qualification timelines for Korean and Japanese suppliers seeking US manufacturing presence.
Fleet procurement is consolidating around total cost of ownership contracting rather than capital expenditure purchase models. Commercial vehicle operators in California and New York are negotiating battery-as-a-service arrangements where cell degradation risk transfers to manufacturer or third-party asset managers, shifting balance sheet treatment and supplier selection criteria toward warranty depth and residual value guarantees.
United States Electric Vehicle Battery Manufacturing Market Segmentation
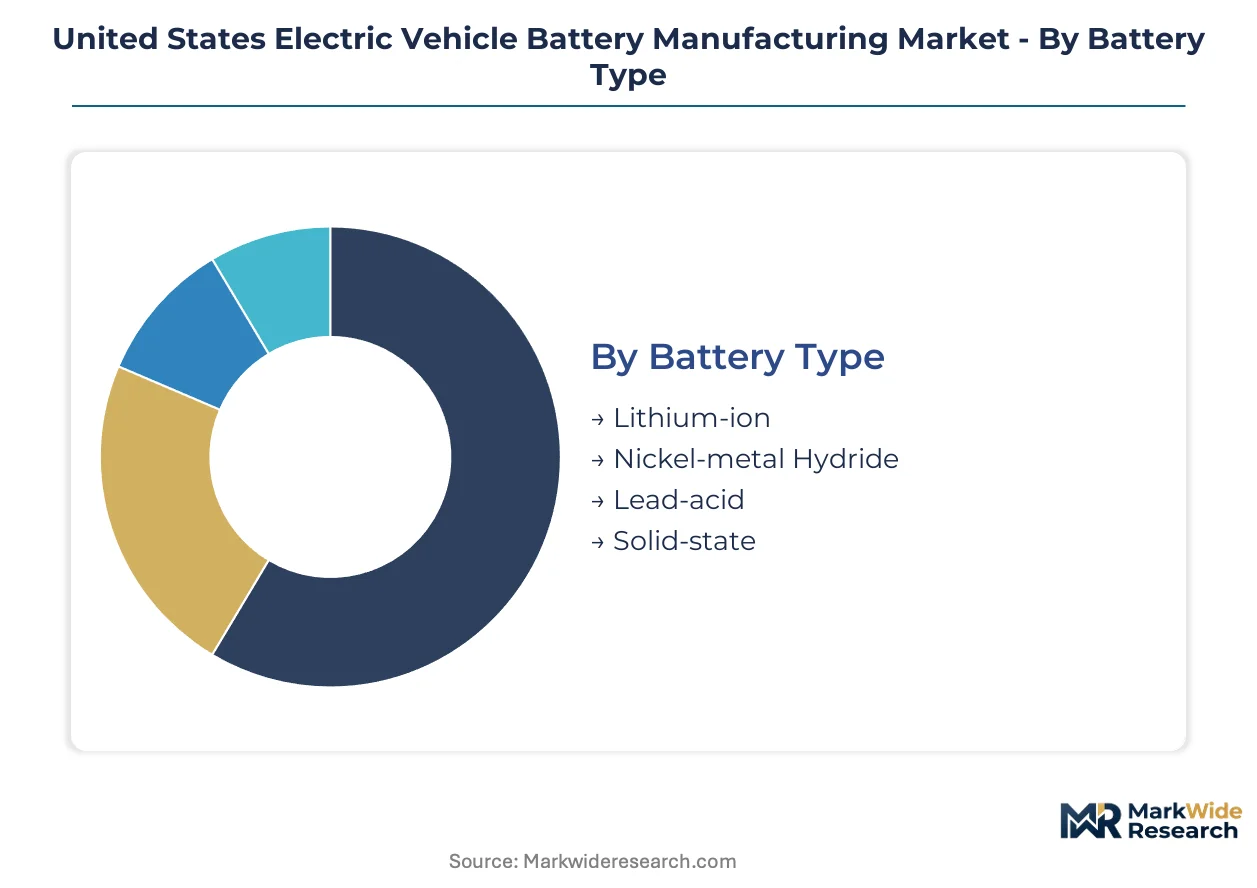
Segmentation reveals how IRA compliance mechanics and chemistry tradeoffs split demand across customer types and applications. Manufacturers configure cell formats and cathode formulations differently depending on whether packs serve passenger range targets or commercial duty cycles.
Battery Type:
Cost tier determines which chemistry dominates which vehicle class and which supply chains qualify for federal incentives.
- Lithium-ion:Nickel-cobalt-manganese and lithium-iron-phosphate formulations constitute the installed manufacturing base across Nevada, Michigan, and Tennessee gigafactories. Cell producers optimize NCM blends for premium passenger range requirements while LFP dominates commercial fleet procurement where cycle life outweighs energy density.
- Solid-state:Sulfide and oxide electrolyte architectures promise 400+ Wh/kg energy density with reduced thermal runaway risk. Venture-backed pilots in California and Massachusetts are attracting automaker pre-commitments for performance-oriented platforms.
- Nickel-metal Hydride:Legacy chemistry retains niche presence in hybrid-electric transition vehicles where established pack designs minimize requalification costs.
- Lead-acid:Starter-lighting-ignition applications and low-speed electric vehicle segments absorb limited domestic production volume.
Lithium-ion commands the established base. The steepest expansion runs through solid-state.
End User:
Customer type dictates contract structure, warranty depth, and whether procurement emphasizes capital expenditure or total cost of ownership.
- Automakers:OEMs negotiate multi-year offtake agreements with domestic content thresholds tied to IRA credit eligibility. Cell qualification timelines stretch 18-24 months as manufacturers validate formation protocols and thermal runaway containment.
- Fleet Operators:Last-mile delivery and regional haul carriers in California and New York are consolidating orders under battery-as-a-service models. SK On and domestic joint venture partners are capturing share through residual value guarantees and degradation risk transfer.
- Public Transport:Transit agencies procure heavy-duty formats for electric bus deployment, with FTA funding requirements driving domestic assembly preferences.
- E-Bike Manufacturers:Low-voltage pack assemblers source cylindrical cells from tier-two producers, operating outside IRA credit structures.
Automakers command the established base. The steepest expansion runs through fleet operators.
Technology:
Maturity gradients separate commercialized capabilities from pre-scale innovations attracting venture allocation.
- Fast Charging:Silicon-composite anode formulations and advanced electrolyte salts enable 350kW+ charge rates without lithium plating. Megawatt-scale corridor deployment along Interstate highways is unlocking long-haul electrification for commercial vehicle segments.
- Battery Management Systems:Cell-level sensing and predictive thermal algorithms protect asset value under warranty coverage. Domestic software engineering centers in Austin and Detroit are developing platform-agnostic BMS architectures.
- Wireless Charging:Inductive pad systems for fleet depot automation remain pre-commercial, with pilot deployments constrained by efficiency losses and infrastructure capital requirements.
- Energy Density:Cathode active material loading and anode silicon percentage are the primary levers, with dry electrode coating reducing binder content and freeing volume for active material.
Battery management systems command the established base. The steepest expansion runs through fast charging.
Application:
Volume concentration and margin structure diverge sharply between mass-market passenger formats and specialized commercial duty cycles.
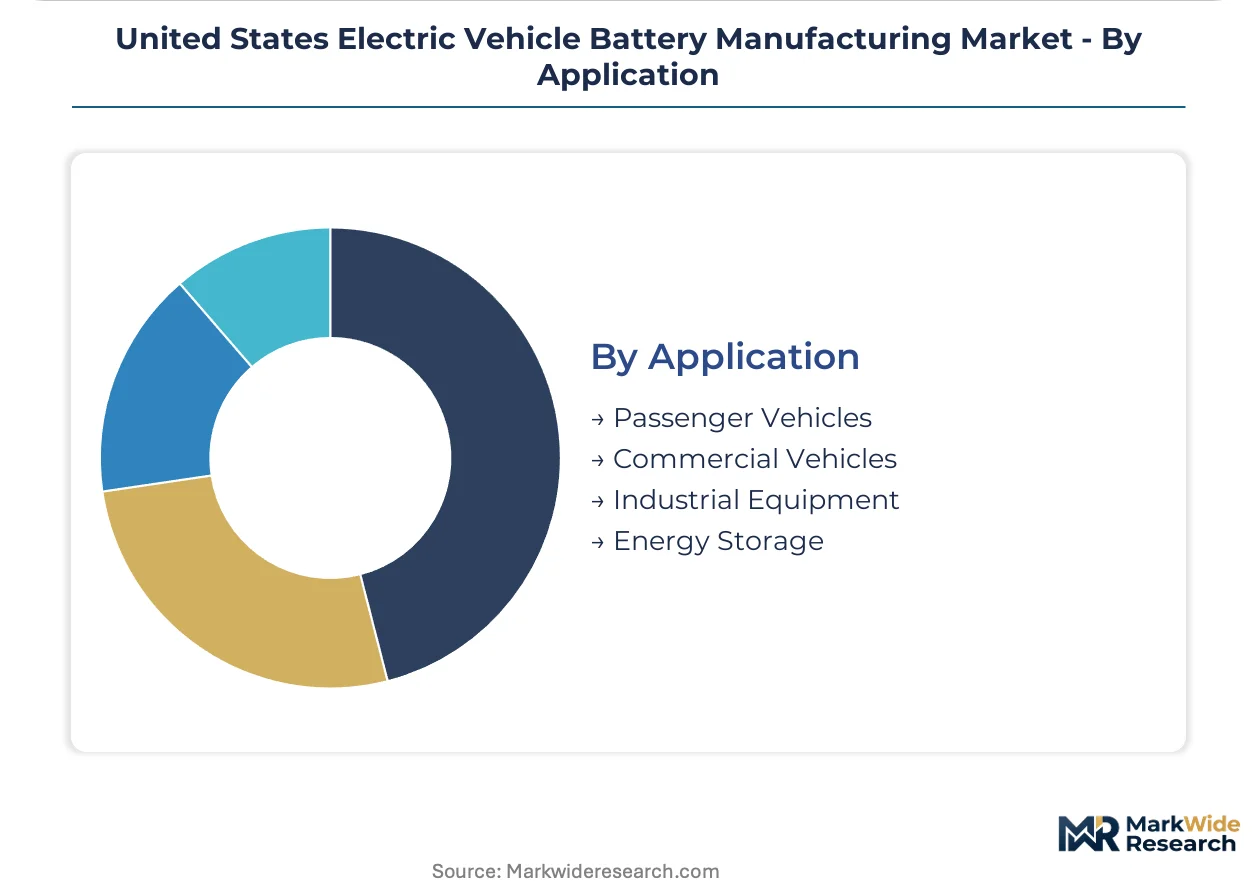
- Passenger Vehicles:Light-duty platforms absorb the majority of cylindrical and prismatic cell output, with EPA tailpipe standards mandating BEV penetration curves that exceed prior planning assumptions. Michigan and Tennessee production corridors serve Detroit Three and transplant OEM assembly plants.
- Commercial Vehicles:Heavy-duty pack formats for delivery vans and regional haul trucks are deepening order backlogs. Fleet electrification mandates in California and New York are compressing supplier qualification timelines for domestic producers.
- Industrial Equipment:Forklift and material handling applications source established LFP chemistries with less stringent energy density requirements.
- Energy Storage:Second-life repurposing of retired EV packs and dedicated grid-scale production are opening revenue streams for lifecycle managers serving Texas and California ISOs.
Passenger vehicles command the established base. The steepest expansion runs through commercial vehicles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic cell production is clustering around three distinct manufacturing corridors where IRA-compliant supply chains are taking shape. Michigan, Tennessee, and Nevada anchor the emerging gigafactory network as cathode active material processing relocates from Asian hubs.
Michigan
Detroit Three automakers are consolidating multi-year offtake agreements with cell producers near their assembly plants. The state's EV tax credits and workforce development programs under the Michigan Strategic Fund are accelerating facility construction. Holland and Grand Rapids host electrode coating and formation cycling operations serving light-duty platforms.
Tennessee
SK On joint ventures with domestic OEMs are expanding prismatic cell capacity for commercial vehicle applications. The FastTrack infrastructure program and Department of Economic and Community Development incentives are compressing construction timelines. Clarksville and Spring Hill form a production corridor where dry electrode coating pilots are eliminating solvent recovery burdens.
Nevada
Tesla's vertical integration from raw material contracts through pack assembly sustains the state's manufacturing base. The Governor's Office of Economic Development lithium tax abatements are attracting cathode precursor investments tied to Thacker Pass spodumene supply. Reno-Sparks and the Tahoe-Reno Industrial Center concentrate formation cycling and thermal management system assembly.
Georgia
Hyundai-Kia affiliate cell plants are ramping to supply the Metaplant America complex. The Georgia Department of Economic Development's electric mobility incentives are redirecting Korean supplier networks toward domestic content compliance. Bryan County and the Savannah port corridor handle inbound mineral concentrate and outbound pack shipments.
Ohio
General Motors-LG Energy Solution joint ventures are commissioning cylindrical cell lines for Ultium platform vehicles. The JobsOhio automotive investment fund is underwriting supplier park development near Lordstown. Warren and Youngstown host anode material processing and battery management system engineering centers.
United States Electric Vehicle Battery Manufacturing Market Competitive Landscape
Vertically integrated OEMs and dedicated cell producers split the market between captive supply security and merchant scale economics. Korean and Japanese specialists dominate cylindrical and prismatic formats through US-based joint ventures, while domestic automakers pursue backward integration into electrode manufacturing. Two archetypes define competitive positioning: integrated OEMs controlling mineral-to-pack value chains, and independent cell producers qualifying multiple automaker platforms. Capacity expansion and strategic partnerships represent the dominant competitive moves as qualification timelines compress.
Among Korean specialists, LG Energy Solution and SK On exemplify the joint-venture model for IRA compliance, anchoring production in Georgia and Tennessee through partnerships with Detroit and transplant OEMs. Tesla represents the integrated archetype, sustaining in-house production from Nevada raw material processing through pack assembly. Panasonic occupies a position as a cylindrical cell specialist serving performance-oriented platforms through its Nevada operations.
| Leading Market Players |
|---|
| LG Energy Solution |
| Tesla |
| Panasonic |
| SK On |
| General Motors |
| Samsung SDI |
| Ford Motor Company |
| Northvolt |
| Microvast |
| Others |
Pricing and Supply Chain Analysis
Reno-Sparks cell production corridors concentrate formation cycling capacity, compressing regional cost structures while IRA domestic content thresholds concentrate buyer leverage among qualifying suppliers. Lithium carbonate volatility and cathode precursor import dependencies feed directly into cell producer margin structures, creating asymmetric pricing power across the value chain.
Pricing Analysis
Aftermarket service revenue for battery diagnostics and second-life repurposing drives lifetime value capture as original equipment manufacturers build captive service networks. Cell producers deploy contract-based long-term offtake agreements with automakers, with price differentiation resting on IRA domestic content compliance and volume scale commitments. Pricing pressure stems from lithium carbonate spot volatility compressing margins during upstream tightness. Fleet operators exhibit highest price sensitivity through total cost of ownership contracting, while premium passenger platforms absorb technology premiums for energy density performance.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk assessment for graphite anode materials and electrolyte salt formulations. Domestic cell production draws from Australian spodumene concentrate, Chilean and Argentine brine-derived lithium carbonate, and Indonesian nickel sulfate processing hubs. Single-source vulnerability concentrates in Chinese synthetic graphite production subject to FERC trade scrutiny. Distribution runs through dedicated automotive logistics corridors serving Michigan, Tennessee, and Nevada gigafactory clusters with just-in-time electrode and electrolyte delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation around battery-as-a-service procurement models has shifted buyer power toward total cost of ownership contracting, fragmenting supplier selection criteria across warranty depth and residual value guarantees.
For Market Incumbents: Entrench position through backward integration into cathode active material processing and dry electrode coating capacity expansion in Tennessee and Georgia corridors. Solid-state venture pilots and silicon-composite anode qualification timelines represent emerging technology threats requiring R&D allocation. IRA foreign entity of concern rule evolution constitutes regulatory uncertainty demanding supply chain optionality. For New Entrants and Emerging Players: Second-life stationary storage applications in Texas and California ISO markets represent the most penetrable entry point for lifecycle managers without cell manufacturing scale. Direct lithium extraction projects in Arkansas Smackover Formation brine offer upstream white space for cathode precursor suppliers. Go-to-market positioning should emphasize degradation risk transfer mechanisms under battery-as-a-service arrangements. For Investors and Strategic Acquirers: Long-term, this sits as a domestic content compliance play because IRA bonus credit mechanics will persistently reward North American mineral processing and cell production capacity. Acquisition targets should screen for electrode coating expertise and formation cycling yield optimization capabilities. The signal to watch is FERC interconnection reform implementation pace determining greenfield facility energization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Cathode Precursor Investment | IRA compliance eligibility hinges on North American processing capacity for nickel sulfate and cobalt hydroxide. |
| Dry Electrode Coating Scale-Up | SK On Georgia pilots eliminating N-methyl-2-pyrrolidone handling reduce capital intensity and environmental compliance burden. |
| Solid-State Joint Venture Formation | Sulfide electrolyte pilots in California and Massachusetts attract automaker pre-commitments for premium platforms. |
| Battery-as-a-Service Platform Launch | Fleet operators in California and New York transfer degradation risk to manufacturers through residual value guarantees. |
| Direct Lithium Extraction Partnership | Arkansas and Salton Sea brine projects promise domestic lithium carbonate supply reducing import dependency. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, EPA regulatory dockets, and FERC interconnection queues with bottom-up and top-down triangulation. Primary interviews engaged cell producer operations executives, OEM platform engineering directors, fleet procurement managers, and cathode active material supplier technical leads. Secondary validation drew from Department of Energy funding announcements, state economic development incentive disclosures, and lithium trade flow customs data.
Forecast inputs span vehicle class, propulsion architecture, cathode chemistry formulation, and regional production cluster segmentation across the analysis window. CAGRs derive from production capacity commissioning schedules, IRA credit uptake modeling, and fleet electrification mandate compliance curves. Specific inputs include EPA tailpipe standard stringency assumptions and NHTSA fuel economy regulatory trajectory.
Macroeconomic conditions sit as an overlay; deviation in lithium carbonate spot prices, Chinese export tariff implementation, or FERC interconnection queue processing speed would shift the trajectory. Forecasts reflect documented assumptions subject to revision as IRA foreign entity of concern rules evolve and solid-state technology maturation accelerates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
United States Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Middle-East and Africa Electric Vehicle Battery Anode Market
EV Batteries
Electric Vehicle Battery Coolant Market
EV Batteries
Curved Lipo Battery Market
EV Batteries
Asia-Pacific LFP Battery Pack Market
EV Batteries
South America Electric Vehicle VRLA Batteries Market
EV Batteries
India Electric Vehicle Battery Manufacturing Market
EV Batteries
North America Electric Vehicle VRLA Batteries Market
EV Batteries
Electric Vehicle Battery Conditioners Market
EV Batteries
China Electric Vehicle Battery Materials Market
EV Batteries
Europe Electric Vehicle Battery Manufacturing Market
EV Batteries
France Electric Vehicle Battery Manufacturing Market
EV Batteries
South America Hybrid Electric Vehicle Battery Market
EV Batteries
United Kingdom Electric Vehicle Battery Manufacturing Market
EV Batteries
Asia-Pacific Electric Vehicle Battery Market
EV Batteries
UK EV Battery Pack Market