
 EV Battery Heating System Market | 2026-2036
EV Battery Heating System Market Size, Share, and Industry Trends Forecast 2026-2036
EV Battery Heating System Market Foresight
The capital-intensity divergence between integrated thermal system suppliers and component-only vendors is collapsing as battery pack architectures consolidate heating, cooling, and power electronics into single modules. Continental AG leverages its powertrain electronics footprint to anchor combined thermal-electric designs. Robert Bosch GmbH sustains R&D intensity across resistance heating and heat pump control firmware. LG Chem competes through captive cell chemistry knowledge that shapes heating duty cycles.
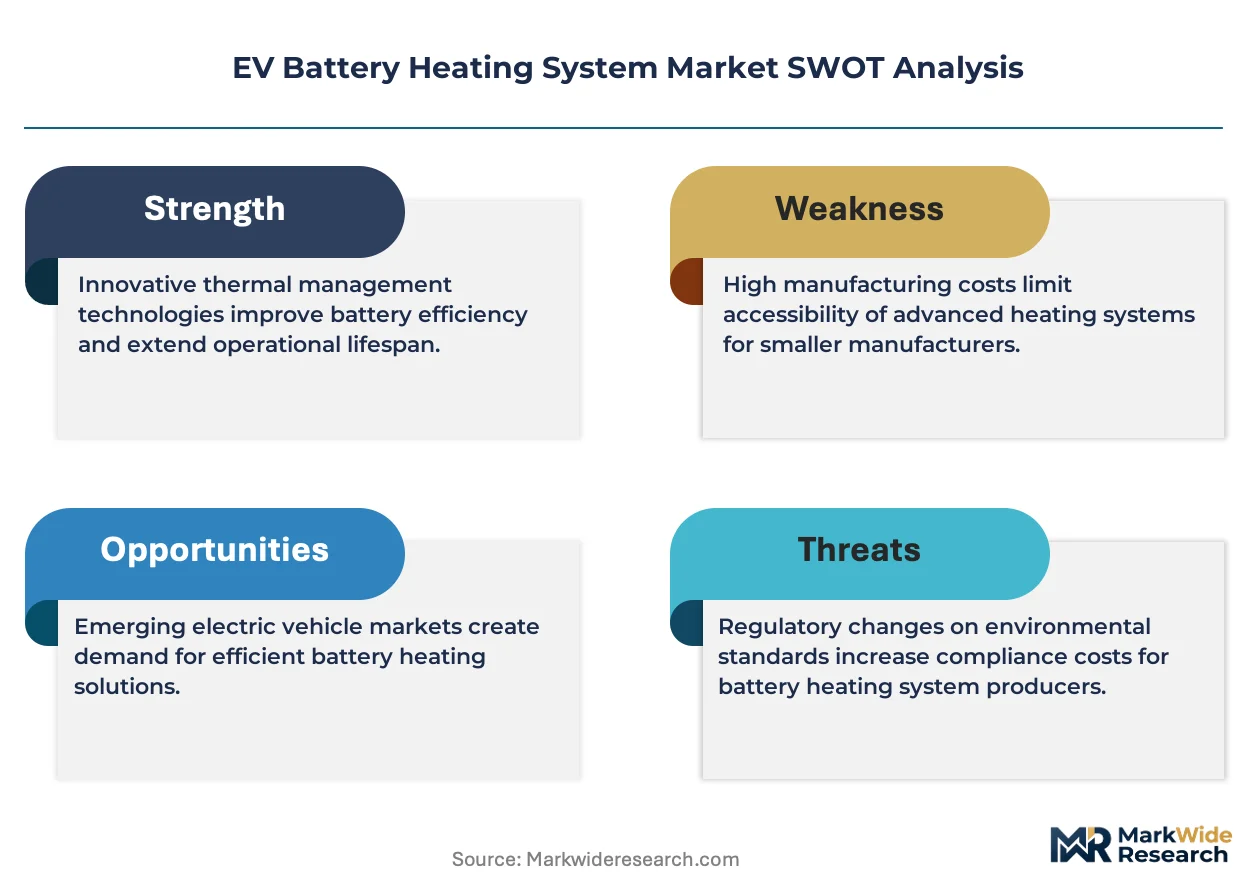
EV battery heating systems are electromechanical assemblies that maintain lithium-ion cells within optimal temperature bands, typically using positive temperature coefficient heaters, refrigerant-based heat pumps, or glycol circulation loops rated from 2 kW to 8 kW thermal output. Their primary purpose is to prevent capacity fade, enable fast charging, and preserve driving range in ambient conditions below 10°C. Liquid heating architectures currently dominate OEM factory installations due to packaging flexibility and existing coolant infrastructure, while heat pump technology is capturing specification share in premium passenger vehicle platforms where efficiency credits offset higher unit cost. Resistance heating retains aftermarket and retrofitting volume for older battery platforms lacking integrated thermal loops.
FDA oversight of automotive-grade materials remains indirect, though EPA tailpipe and fuel economy standards indirectly tighten thermal efficiency requirements for battery conditioning loads. The EU F-Gas Regulation and REACH chemical restrictions constrain refrigerant selection and heater element coatings, while China's GB standards and MIIT new energy vehicle rules mandate low-temperature performance disclosure. Stakeholders must monitor how refrigerant chemistry transitions under the EU Green Deal reshape heat pump cost structures and whether OEMs internalize heating module production or sustain tier-one supplier relationships.
Market Dynamics
The EU F-Gas Regulation is forcing refrigerant chemistry transitions across heat pump architectures, collapsing the cost advantage of conventional fluorinated systems and redirecting engineering investment toward alternative warming technologies.
Growth Catalysts
- Cold-climate range retention mandates:Germany's fleet electrification timeline and winter temperature profiles create specification pressure for thermal management systems that preserve battery capacity below 10°C.
- REACH chemical restrictions:Heater element coating requirements under EU chemical law are accelerating substitution toward ceramic and polymer-based alternatives with lower toxicity profiles.
- Fast-charging infrastructure rollout:High-power charging stations require preconditioned battery packs, pulling demand for 6-8 kW thermal output systems at highway corridor locations.
Market Restraints
- Copper and nickel price volatility:Resistance heating elements and power electronics depend on these commodity inputs, compressing margins when London Metal Exchange prices spike.
- Refrigerant supply concentration:Heat pump manufacturers face input risk from concentrated production of HFO-1234yf and CO2 refrigerants in specific chemical clusters.
- Technical limitation of ambient temperature floors:Air-source heat pumps lose coefficient-of-performance efficiency below -20°C, requiring supplemental resistance heating in Scandinavian and Canadian markets.
Strategic Opportunities
- Commercial vehicle electrification:Bus and truck OEMs in Nordic countries are specifying battery heating for depot-charged fleets operating on fixed routes with predictable thermal loads.
- Battery-as-a-service models:Leasing providers are internalizing thermal system costs and prioritizing longevity-optimized heating duty cycles over first-cost minimization.
- EU Green Deal industrial funding:Clean technology manufacturing subsidies are lowering capital barriers for domestic production of heat pump compressors and PTC heater assemblies.
Industry Challenges
- Systems integration engineering talent:The convergence of thermal, electrical, and control systems requires specialists fluent in both refrigerant thermodynamics and battery electrochemistry.
- Homologation timeline compression:OEM platform cycles are shortening while UN ECE R100 and R136 safety certifications for battery thermal systems require extended validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Battery Heating System Market |
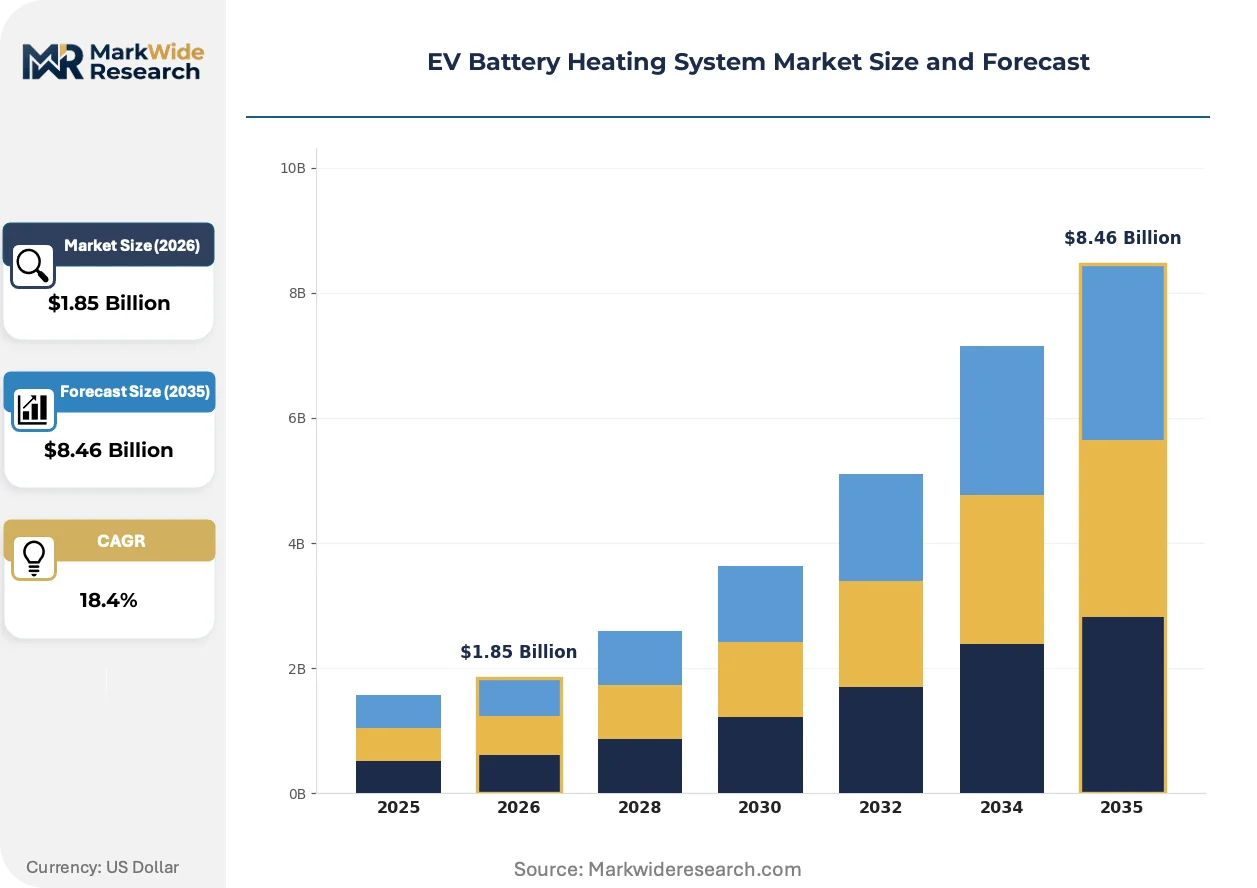
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $8.46 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: Resistance Heating, Heat Pump, Liquid Heating, Thermal Batteries End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Operators Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy-Duty Vehicles Installation Type: OEM Installation, Retrofitting, Factory Installation, Custom Solutions |
| Companies Covered | Continental AG, Robert Bosch GmbH, LG Chem, Gentherm Incorporated, Valeo, MAHLE GmbH, Hanon Systems, BorgWarner Inc., Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Battery Heating System Market Shifts & Advancements
Component integration is compressing the physical envelope of thermal management hardware as battery pack architectures consolidate multiple functions into single modules.
Positive temperature coefficient heater films are miniaturizing from discrete cartridge assemblies to thin-film substrates laminated directly onto cell surfaces. Premium passenger vehicle platforms in Germany and South Korea are adopting these substrates for zonal heating control. This miniaturization is eliminating separate heater housing volumes and reducing coolant mass in the thermal loop.
EPA tailpipe standards are tightening indirect thermal efficiency requirements by including battery conditioning loads within vehicle energy consumption metrics. OEMs must now optimize heating system power draw to maintain fleet-average compliance. California Air Resources Board zero-emission vehicle rules are accelerating this specification pressure for vehicles sold into the US West Coast market.
Fleet operators are unbundling thermal system service contracts from vehicle procurement, creating direct commercial relationships with heating module suppliers. Large logistics buyers in cold-climate states are negotiating performance-guaranteed heating uptime rather than accepting standard OEM warranty terms. This disintermediation is most advanced in Germany's parcel delivery electrification programs and Norway's taxi fleet conversions.
EV Battery Heating System Market Segmentation
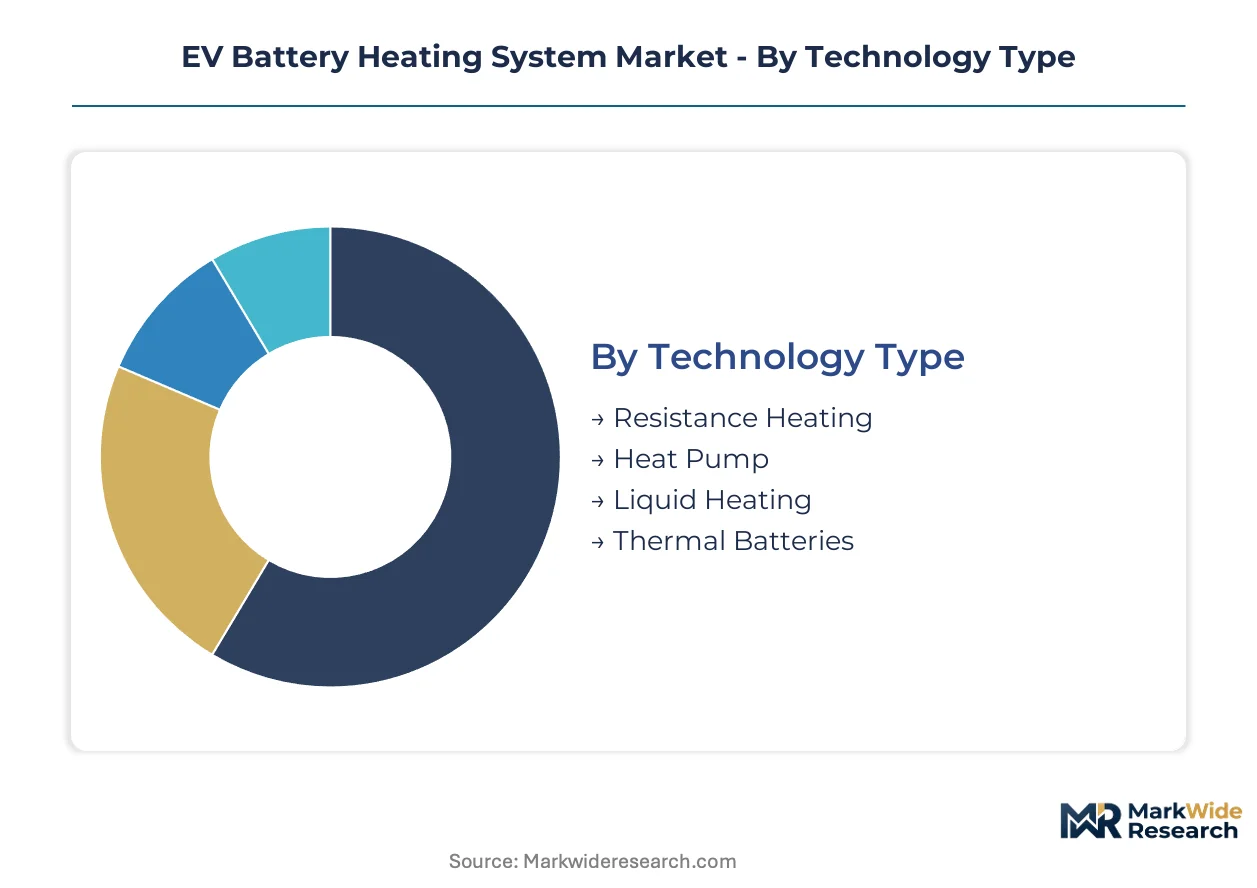
Technology choices in EV battery heating directly determine thermal efficiency, packaging constraints, and regulatory compliance pathways across cold-climate markets. Segment boundaries are blurring as integrated thermal modules consolidate multiple functions, forcing suppliers to reposition across traditional category lines.
Technology Type:
Margin pools concentrate where OEMs pay premiums for coefficient-of-performance efficiency in sub-zero operating conditions.
- Resistance Heating:Positive temperature coefficient heaters and high-voltage cartridge elements deliver 2-8 kW thermal output with minimal system complexity. Fleet operators in Norway and Germany specify these for depot-charged commercial vehicles where first-cost minimization outweighs energy efficiency penalties.
- Heat Pump:Refrigerant-based architectures using CO2 or HFO-1234yf achieve 2-4x efficiency multiples over resistance heating above -10°C ambient. EU F-Gas Regulation compliance costs are compressing margins for fluorinated systems while redirecting engineering toward natural refrigerant alternatives.
- Liquid Heating:Glycol circulation loops leverage existing battery pack coolant infrastructure for packaging flexibility. German passenger vehicle OEMs dominate procurement specifications.
- Thermal Batteries:Phase-change material storage systems decouple heating energy supply from instantaneous electrical draw. Nordic bus operators pilot these for route-optimized thermal management.
Heat pump holds installed capacity. Resistance heating is rotating up the share rankings in commercial vehicle retrofit applications.
End User:
Procurement authority is fragmenting as battery-as-a-service providers internalize thermal system decisions previously owned by vehicle OEMs.
- OEMs:Factory-integrated thermal module specifications favor suppliers with combined powertrain electronics and refrigerant thermodynamics capabilities. German and South Korean passenger vehicle platforms drive premium heat pump adoption.
- Aftermarket Providers:Retrofit specialists target older battery platforms lacking integrated thermal loops, using resistance heating cartridges with simplified control firmware. North American cold-climate states generate concentrated demand.
- Vehicle Assemblers:Contract manufacturers for emerging EV brands specify modular heating subsystems compatible with multiple battery form factors.
- Fleet Operators:Direct procurement of performance-guaranteed heating uptime is disintermediating standard OEM warranty structures in Germany's parcel delivery electrification programs.
OEMs retain specification control for new platforms. Fleet operators are rotating up the share rankings as battery leasing models expand.
Application:
Volume concentration diverges sharply between mass-market passenger specifications and heavy-duty thermal loads with predictable duty cycles.
- Passenger Vehicles:Premium platforms in Germany and South Korea integrate zonal heat pump control for cabin and battery conditioning. EPA tailpipe standards include battery thermal loads within vehicle energy consumption metrics.
- Commercial Vehicles:Bus and truck OEMs in Nordic countries specify preconditioned battery packs for depot-charged fleets on fixed routes. Predictable thermal profiles enable optimized heating duty cycles.
- Two-Wheelers:Compact PTC heater films address space-constrained battery enclosures in electric scooters and motorcycles. Asian urban mobility markets dominate volume.
- Heavy-Duty Vehicles:Mining and construction electrification drives demand for 8 kW+ thermal output systems with extreme ambient temperature tolerance.
Passenger vehicles hold installed capacity. Commercial vehicles are climbing the fastest as Nordic fleet electrification accelerates.
Installation Type:
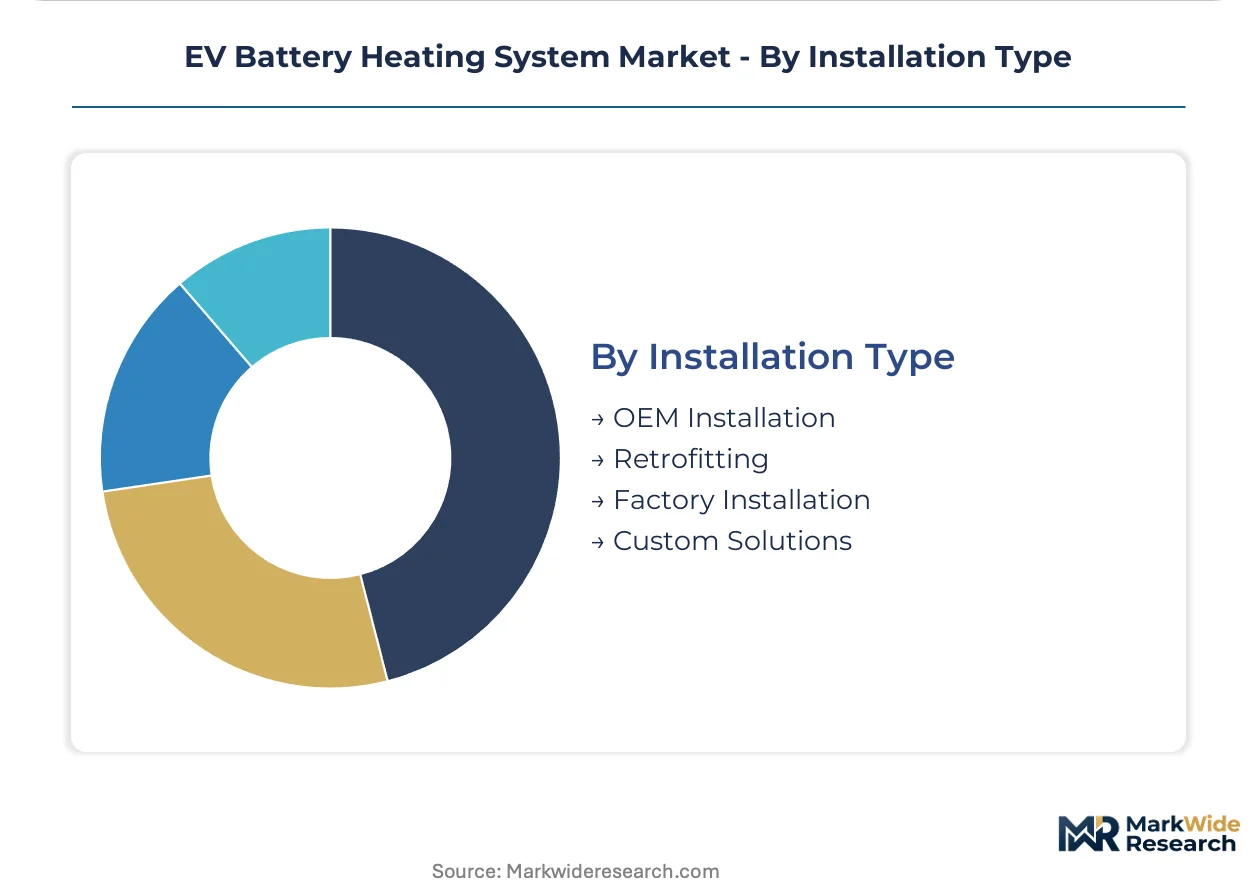
Factory integration captures value through warranty bundling while retrofit channels compete on speed-to-deployment for legacy fleet conversions.
- OEM Installation:Tier-one suppliers embed heating modules within battery pack assemblies during vehicle platform development. German OEMs consolidate procurement with thermal-electronics integrated vendors.
- Retrofitting:Post-manufacture installation targets older battery platforms with degraded cold-weather performance. North American and Scandinavian aftermarket specialists dominate.
- Factory Installation:Contract assemblers integrate standardized heating subsystems across multiple vehicle programs. Volume scale drives cost reduction.
- Custom Solutions:Engineering-to-order for specialized vehicle architectures in heavy-duty and off-road segments. Low volume, high margin.
OEM installation holds installed capacity. Retrofitting is gaining share fastest as legacy fleet electrification extends vehicle service life.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and South Korea absorb premium heat pump costs for coefficient-of-performance efficiency, while fleet operators in Norway and North American cold-climate states prioritize resistance heating for first-cost minimization.
Germany
Passenger vehicle OEMs in Stuttgart and Munich specify integrated thermal-electric modules for zonal battery conditioning. The EU F-Gas Regulation accelerates refrigerant chemistry transitions toward CO2-based heat pump architectures. Thermal management engineering clusters in Baden-Württemberg consolidate procurement with powertrain electronics suppliers.
United States
EPA tailpipe standards include battery conditioning loads within fleet-average energy consumption metrics, tightening thermal efficiency requirements for OEMs selling into California and the West Coast. The Inflation Reduction Act's clean vehicle credits indirectly condition battery thermal performance thresholds. Detroit-area engineering centers and Austin EV manufacturing corridors drive specification pressure for 6-8 kW preconditioning systems.
China
MIIT new energy vehicle rules mandate low-temperature range disclosure, forcing domestic OEMs to specify heating systems for winter performance certification. GB standards constrain refrigerant selection and heater element material composition. Yangtze River Delta battery manufacturing clusters in Ningbo and Suzhou integrate thermal modules at pack assembly stage.
South Korea
Premium passenger platforms from Seoul-based OEMs adopt heat pump control firmware for cabin and battery conditioning efficiency. The country's national industrial regulator supports domestic compressor manufacturing through clean technology subsidies. Gyeonggi-do province hosts concentrated R&D activity for PTC heater film miniaturization.
Norway
Depot-charged commercial fleets in Oslo and Bergen specify preconditioned battery packs for fixed-route operations with predictable thermal profiles. National fleet electrification timelines for bus and truck segments create concentrated demand for resistance heating retrofits. Tromsø-area cold-climate testing facilities validate system performance at -25°C ambient floors.
EV Battery Heating System Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where integrated thermal-electronics vendors command premium positioning and component specialists compete on manufacturing scale. The vendor base separates into three strategic archetypes: diversified automotive suppliers with powertrain electronics footprints, captive battery manufacturers with cell chemistry knowledge, and focused thermal component fabricators. Dominant competitive moves include backward integration into refrigerant compressor manufacturing and strategic partnerships between heating module suppliers and fast-charging infrastructure operators.
Among diversified automotive suppliers, Continental AG and Robert Bosch GmbH exemplify the integrated thermal-electronics archetype, while LG Chem represents captive battery manufacturers leveraging cell-level knowledge to shape heating duty cycles. These three players anchor distinct competitive vectors: Continental AG occupies a position combining powertrain electronics with refrigerant thermodynamics, Robert Bosch GmbH exemplifies sustained R&D intensity across control firmware architectures, and LG Chem represents the chemistry-captive model where thermal system design derives from cell electrochemistry expertise.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| LG Chem |
| Gentherm Incorporated |
| Valeo |
| MAHLE GmbH |
| Hanon Systems |
| BorgWarner Inc. |
| Denso Corporation |
| Others |
Supply & Pricing Matrix
Forty-five to sixty-day compressor lead times from German and South Korean suppliers concentrate pricing power with integrated thermal-electronics vendors, while tier-two resistance heating specialists absorb margin compression from copper and nickel volatility. OEM procurement teams exploit this asymmetry through dual-source contracts that lock heat pump architectures at fixed refrigerant conversion costs.
Pricing Analysis
After-sales service contracts and extended thermal uptime guarantees now drive lifetime value capture beyond initial module sales. Pricing stratifies across premium heat pump systems with CO2 compressors, standard HFO-1234yf architectures, and economy resistance heating cartridges for retrofit applications. Cost compression in economy tiers intensifies because nickel price spikes from London Metal Exchange trading directly transfer to PTC heater element manufacturing. Fleet operators in Norway exhibit highest price sensitivity, accepting efficiency penalties for first-cost minimization, while German passenger vehicle OEMs absorb premiums for coefficient-of-performance ratings.
Supply Chain Analysis
Strategic stockpiling of refrigerant compressors and PTC ceramic substrates dominates over just-in-time preferences, reflecting EU F-Gas Regulation transition uncertainty. Manufacturing concentrates in Germany for integrated thermal-electric modules, South Korea for heat pump control firmware, and China for high-volume PTC heater film production. Raw material dependencies draw from Chilean copper concentrates, Indonesian nickel laterites, and fluorinated chemical feedstocks from Belgian and Japanese chemical clusters. Single-source vulnerability runs through concentrated HFO-1234yf and CO2 refrigerant production. Distribution runs through tier-one automotive supplier networks with direct OEM platform engineering relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against solid-state battery architectures that eliminate external heating through internal ionic conductivity management. Incumbents must navigate this technology transition while preserving revenue from liquid-cooled lithium-ion platforms.
For Market Incumbents: Secure captive refrigerant compressor manufacturing through backward integration into CO2 pump production, insulating margin from EU F-Gas Regulation compliance cost transfers. Anchor platform engineering relationships with Stuttgart and Munich OEMs through combined powertrain electronics and thermal module offerings. Solid-state battery pilot programs in South Korean and Japanese cell manufacturing threaten obsolescence of external heating architectures within the next technology cycle.
For New Entrants and Emerging Players: UN ECE R100 certification fast-tracks enable aftermarket retrofit penetration in North American cold-climate states where legacy fleet electrification extends vehicle service life. Target resistance heating cartridge replacement demand from Scandinavian commercial vehicle operators. Pursue direct fleet operator relationships disintermediating OEM warranty structures through performance-guaranteed heating uptime contracts.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified automotive suppliers divesting non-core thermal component divisions during portfolio restructuring. Long-term viability hinges on heat pump technology lock-in across premium passenger platforms before solid-state batteries achieve commercial scale. Monitor solid-state battery pilot production announcements from South Korean and Japanese cell manufacturers as inflection indicators for external heating system demand erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Chemistry Transition | EU F-Gas Regulation compliance redirects engineering investment toward CO2 heat pump architectures. |
| Integrated Thermal-Electric Module Development | Combined powertrain electronics and heating firmware capture premium positioning with German OEMs. |
| PTC Heater Film Miniaturization | Thin-film substrates laminated directly onto cell surfaces eliminate separate housing volumes. |
| Fleet Operator Direct Contracting | Performance-guaranteed heating uptime disintermediates standard OEM warranty structures in Germany. |
| Solid-State Battery Monitoring | Internal ionic conductivity management threatens obsolescence of external heating architectures. |
Research Methodology
Desk research of regulatory filings including EU F-Gas Regulation implementation documents, EPA tailpipe standard amendments, and MIIT new energy vehicle certification databases preceded structured interviews with OEM platform engineers, tier-one supplier procurement directors, fleet operations managers, and thermal system R&D leads. Secondary validation drew from vehicle production databases, IHS Markit registration data, customs trade records for copper and nickel flows, and refrigerant chemical production disclosures. Bottom-up module shipment estimates triangulated against top-down OEM electrification timeline projections.
Variance decomposition across technology type, end user, application, and installation type dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level shipment trajectories weighted by thermal output capacity and unit cost evolution. Key forecast inputs included OEM platform cycle timelines, EU Green Deal industrial funding disbursement schedules, and cold-climate range retention specification pressure indices.
Decision-makers should treat outputs as directional under assumptions of sustained lithium-ion battery chemistry dominance and gradual solid-state technology transition; material deviation would warrant model refresh. Revision becomes warranted when solid-state battery pilot production volumes cross commercialization thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Market
EV Batteries
Middle-East and Africa Electric Vehicle Battery Anode Market
EV Batteries
China Electric Vehicle Battery Materials Market
EV Batteries
EV Battery Cell and Pack Materials Market
EV Batteries
South America Electric Vehicle VRLA Batteries Market
EV Batteries
EV Battery Cells Market
EV Batteries
South America Hybrid Electric Vehicle Battery Market
EV Batteries
UK EV Battery Pack Market
EV Batteries
United Kingdom Electric Vehicle Battery Manufacturing Market
EV Batteries
Italy Electric Vehicle Battery Manufacturing Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
ASEAN Countries Electric Vehicle Battery Manufacturing Market
EV Batteries
Germany EV Battery Pack Market
EV Batteries
North America Electric Vehicle Battery Anode Market
EV Batteries
Europe LFP Battery Pack Market
EV Batteries
India Electric Vehicle Battery Manufacturing Market