
 United States Electric Vehicle Battery Materials Market | 2026-2036
United States Electric Vehicle Battery Materials Market Size, Share, and Industry Trends Forecast 2026-2036
United States Electric Vehicle Battery Materials Market Insights
The cathode precursor capability gap between integrated miners and chemical converters is unwinding competitive hierarchies in the domestic battery supply base. Albemarle Corporation leverages its Kings Mountain lithium concentration infrastructure to anchor upstream supply security for southeastern cell plants. BASF SE sustains R&D intensity across high-nickel cathode formulations through its Ohio technical center. Redwood Materials specializes in hydrometallurgical recovery, positioning closed-loop feedstock as a parallel sourcing channel against virgin extraction.
United States electric vehicle battery materials comprise refined active substances—lithium compounds, nickel sulfate, cobalt hydroxide, and synthetic or natural graphite—engineered to specific purity thresholds exceeding 99.5 percent for cathode and anode fabrication. These materials determine cell energy density, cycle stability, and thermal safety profiles in lithium-ion architectures. Lithium and nickel segments command the deepest margin pools given cathode cost concentration and chemistry migration toward high-nickel NMC variants. Graphite supply remains structurally import-dependent despite expanding domestic spheronization capacity. The LFP chemistry segment competes aggressively on cost for commercial vehicle and energy storage applications where energy density requirements moderate.
The Department of Energy loan programs office and NHTSA fuel economy standards collectively tighten domestic content thresholds and electrification mandates. The EPA tailpipe emissions framework accelerates OEM procurement commitments, while the SEC climate disclosure rules expose supply chain provenance risks. Stakeholders must monitor how Treasury guidance on IRA critical mineral sourcing reshapes offtake contracting terms and joint venture structures.
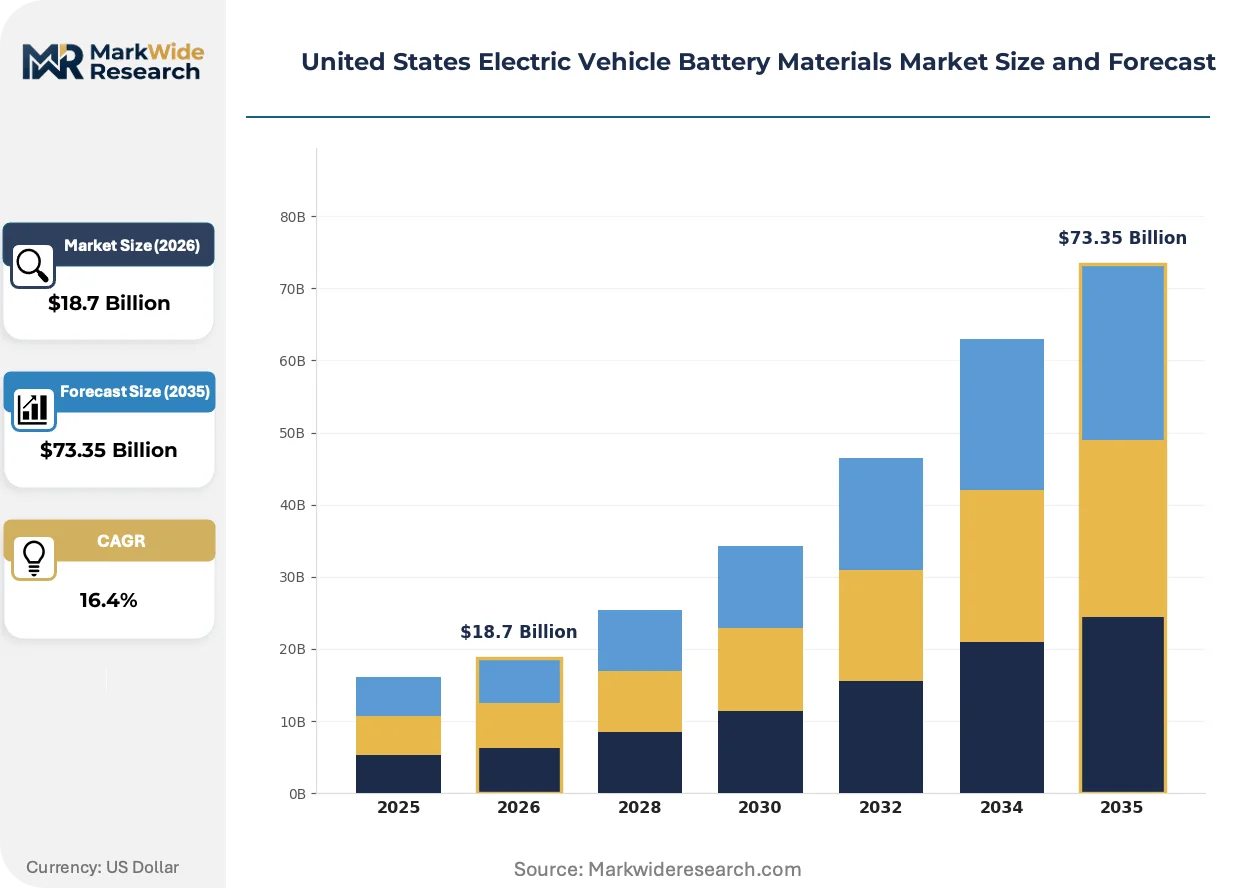
Market Dynamics
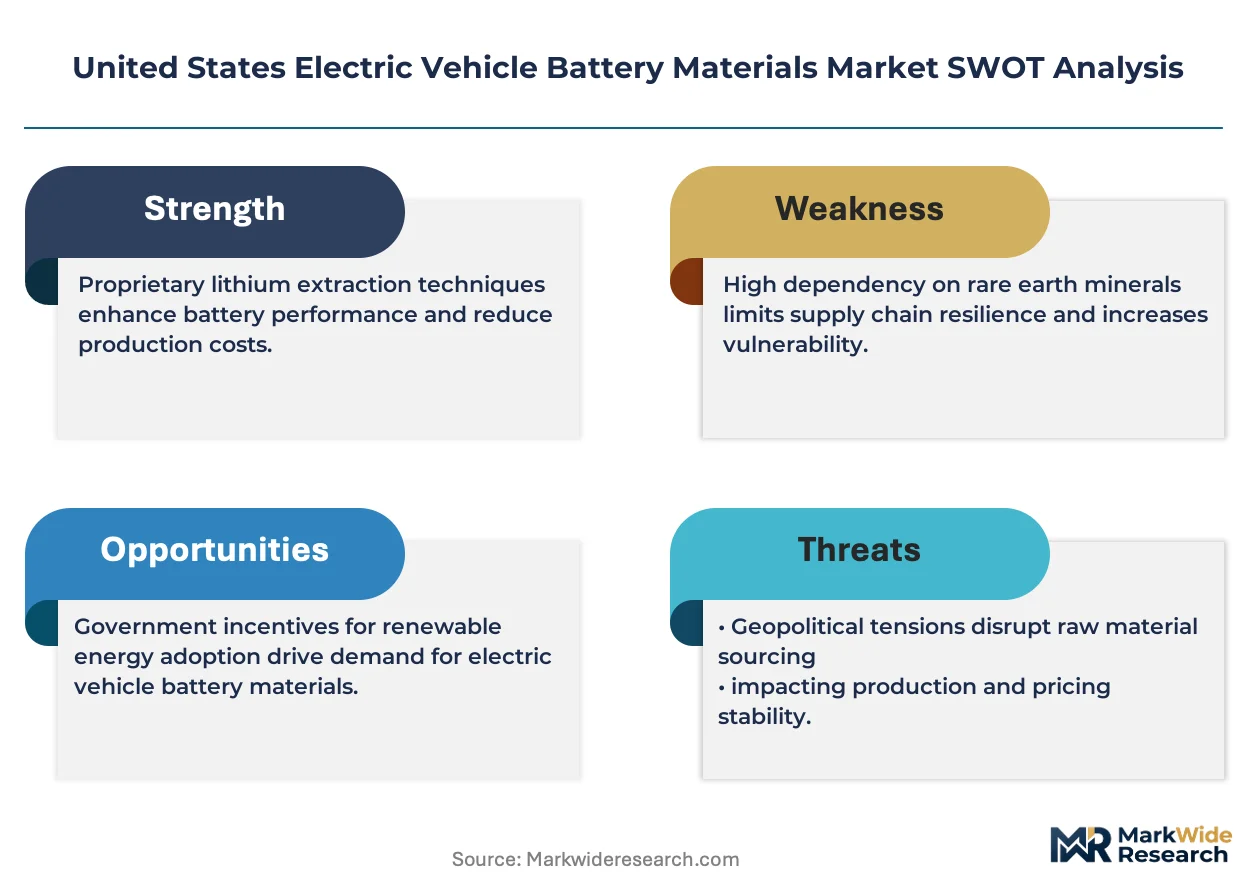
The Inflation Reduction Act's domestic content thresholds are forcing cell manufacturers to reconfigure supply contracts around North American-sourced lithium, nickel, and graphite, compressing procurement timelines and elevating offtake premiums for qualifying feedstock.
Growth Catalysts
- NHTSA Fuel Economy Standards:Stringent fleet efficiency mandates compel OEMs to accelerate electrification roadmaps, tightening cathode active material procurement cycles.
- Lithium Refining:Expansion of domestic spodumene-to-hydroxide conversion capacity in the Great Lakes corridor reduces import dependency for high-purity lithium compounds.
- Fleet Electrification:Commercial vehicle operators in Michigan, Ohio, and Illinois are committing to battery-electric platforms faster than consumer adoption curves projected.
Market Restraints
- Graphite Import Concentration:Spheronized natural graphite remains structurally dependent on Chinese processing, exposing anode supply chains to tariff and logistics volatility.
- Cobalt Sulfate Cost Structure:Price instability in Central African feedstock concentrates margin pressure on NMC cathode formulations requiring cobalt hydroxide.
- Permitting Friction:EPA environmental review timelines for greenfield lithium extraction in Nevada and North Carolina extend project development cycles beyond capital commitment horizons.
Strategic Opportunities
- Closed-Loop Recovery:Hydrometallurgical black mass processing in the southeastern manufacturing belt offers parallel feedstock streams independent of virgin mining.
- LFP Chemistry Migration:Commercial vehicle and grid storage applications in Texas and California are adopting lithium iron phosphate cells for cost-optimized duty cycles.
- IRA Manufacturing Credits:Treasury guidance on advanced manufacturing production incentives is redirecting joint venture structures toward Ohio and Tennessee cathode precursor facilities.
Industry Challenges
- Electrochemical Engineering Talent:Shortages of cell design specialists and solid-state electrolyte researchers constrain R&D velocity across Midwestern technical centers.
- Integration Complexity:Retrofitting legacy automotive stamping plants for dry electrode coating and cell assembly requires simultaneous workforce reskilling and equipment reconfiguration.
- SEC Climate Disclosure:Supply chain provenance documentation demands are extending due diligence timelines for critical mineral sourcing contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Electric Vehicle Battery Materials Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Lithium, Cobalt, Nickel, Graphite Battery Chemistry: LFP, NMC, NCA, LTO End User: Automakers, Startups, Aftermarket Providers, Fleet Operators Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Energy Storage Systems |
| Companies Covered | Targray Technology International Inc., BASF SE, Mitsubishi Chemical Group Corporation, UBE Corporation, Umicore SA, Redwood Materials, Albemarle Corporation, Livent Corporation, QuantumScape Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Electric Vehicle Battery Materials Market Trends and Innovations
Solid-state and silicon-anode architectures are forcing material suppliers to reformulate purity specifications and thermal management properties, splitting competitive advantage between incumbent chemical converters and specialized nanomaterial entrants.
High-nickel NMC cathode chemistry is bifurcating procurement strategies across the United States market. Cell manufacturers serving premium passenger EV segments in California and Washington are specifying nickel-cobalt-manganese ratios above 8:1:1 for energy density maximization. Fleet operators in Texas and Arizona are retreating toward mid-nickel variants to balance cycle life against thermal runaway risk, fragmenting cathode precursor demand into performance-tiered supply contracts.
EPA tailpipe emissions frameworks are tightening OEM compliance timelines, compressing the window between prototype validation and mass production scale-up. The regulatory pressure is concentrating engineering resources on high-volume cell formats. Midwestern manufacturing clusters in Michigan and Ohio are absorbing the bulk of this compliance-driven capacity expansion.
Buyer concentration among vertically integrated automakers is displacing merchant market spot purchasing for cathode active materials. Ford, GM, and Tesla are locking multi-year offtake agreements directly with chemical converters, squeezing independent cell producers into secondary supply tiers. This consolidation is most visible in the Great Lakes corridor, where integrated OEM gigafactories are capturing preferred queue positions at domestic precursor plants.
United States Electric Vehicle Battery Materials Market Segmentation
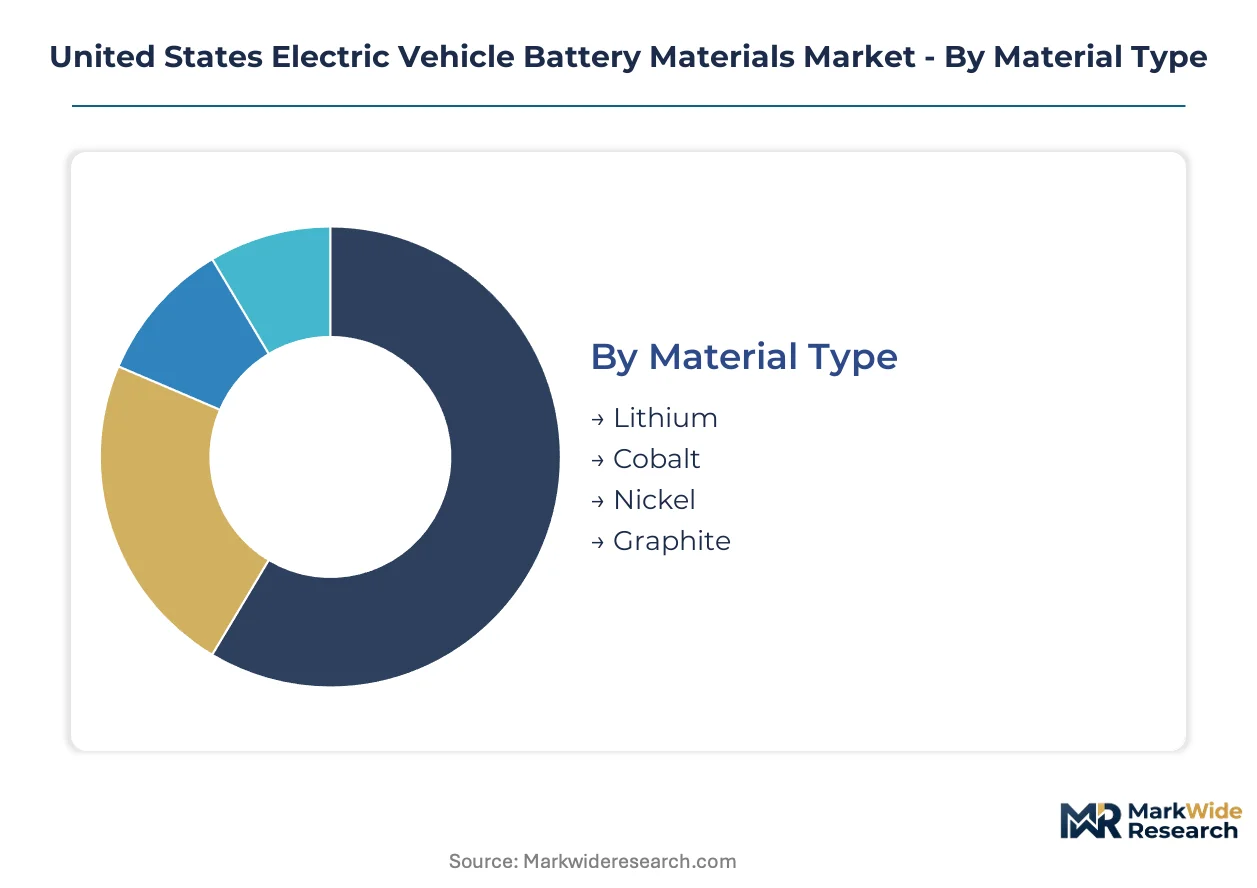
Material specifications and chemistry migration patterns fragment procurement strategies across the United States supply base. Battery makers must align feedstock sourcing with IRA domestic content thresholds and OEM platform roadmaps simultaneously.
Material Type:
Lithium faces the strongest substitution pressure as sodium-ion prototypes advance, while nickel and cobalt contend with chemistry reformulation toward lower-loading variants.
- Lithium:Spodumene-derived lithium hydroxide monohydrate serves high-nickel cathode formulations with purity thresholds exceeding 99.5 percent. Demand concentrates in Michigan and Ohio gigafactories where Ford and GM have locked multi-year offtake agreements with Great Lakes corridor refiners.
- Nickel:Class 1 nickel sulfate hexahydrate enables NMC 811 and 9½½ cathode architectures demanding minimal cobalt loading. Michigan cathode precursor plants are absorbing the bulk of domestic nickel chemical conversion capacity as OEMs prioritize energy density for premium passenger platforms.
- Cobalt:Cobalt hydroxide remains concentrated in NMC formulations despite aggressive thrifting trends; Central African feedstock dependency exposes margin structures to price volatility and SEC provenance documentation requirements.
- Graphite:Spheronized natural graphite and synthetic graphite compete for anode share; domestic spheronization capacity in Louisiana and Tennessee cannot displace Chinese processing dependence for battery-grade specifications.
Lithium anchors the volume base while nickel gains share at the steepest rate as high-loading cathode chemistries proliferate.
Battery Chemistry:
Cost tier differentiation separates premium energy density formulations from mass-market cost-optimized alternatives.
- LFP:Lithium iron phosphate cells eliminate cobalt and minimize nickel loading, delivering cycle stability and thermal safety for commercial vehicle duty cycles. Fleet operators in Texas and California are specifying LFP for battery-electric trucks and grid storage installations where energy density requirements moderate.
- NMC:Nickel-cobalt-manganese layered oxide cathodes span 523, 622, 811, and 9½½ stoichiometries with nickel content climbing toward 90 percent in premium formulations. California and Washington passenger EV markets are driving specification toward highest-nickel variants for range maximization.
- NCA:Nickel-cobalt-aluminum oxide delivers superior energy density for cylindrical cell formats; Tesla's Nevada gigafactory remains the primary domestic demand anchor for NCA precursor materials.
- LTO:Lithium titanate oxide anodes enable extreme fast-charging and cycle longevity for specialty commercial applications; limited adoption constrains demand to niche transit and industrial vehicle segments.
NMC retains the dominant revenue position while LFP expands most quickly across commercial and stationary storage applications.
End User:
Customer type determines contracting structures, with integrated OEMs displacing merchant market purchasing through captive supply arrangements.
- Automakers:Vertically integrated Detroit Three and Tesla are locking direct offtake agreements with chemical converters, squeezing independent cell producers into secondary supply tiers.
- Startups:Emerging cell manufacturers face constrained queue positions at domestic precursor plants, forcing reliance on import feedstock that fails IRA credit thresholds.
- Aftermarket Providers:Replacement battery suppliers source through spot markets and secondary distributors, exposed to price volatility in lithium carbonate and graphite anode materials.
- Fleet Operators:Commercial vehicle electrification commitments in Illinois and Ohio are accelerating faster than consumer adoption curves, concentrating demand for LFP and mid-nickel NMC formulations.
Automakers command procurement volume while fleet operators are climbing the fastest as electrification timelines compress.
Application:
Geography within the United States shapes chemistry selection, with coastal states prioritizing range density and interior corridors optimizing for cost and cycle life.
- Passenger Vehicles:Premium sedans and SUVs in California and Washington specify high-nickel NMC for maximum range; IRA consumer tax credits tighten domestic content requirements for qualifying vehicles.
- Commercial Vehicles:Battery-electric trucks and buses in Texas, Arizona, and Michigan favor LFP and mid-nickel NMC for thermal stability under heavy-duty cycling.
- Two-Wheelers:Electric motorcycles and scooters represent marginal demand within the United States market, concentrated in California urban mobility pilots.
- Energy Storage Systems:Grid-scale installations in Texas and California are adopting LFP cells for cost-optimized stationary storage, decoupled from energy density constraints.
Passenger vehicles anchor installed capacity while energy storage systems are expanding most quickly as utility procurement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across the United States market. Fleet operators in Texas and Arizona prioritize cost-optimized LFP chemistries, while California and Washington passenger buyers absorb premiums for high-nickel energy density. This bifurcation concentrates procurement power in distinct regional corridors.
California
Premium passenger EV buyers in the San Francisco Bay Area and Los Angeles metro command maximum range specifications, driving NMC 811 and 9½½ cathode demand. CARB zero-emission vehicle mandates tighten annually, compelling OEMs to secure IRA-compliant domestic content for tax credit eligibility. The Tesla-Panasonic Nevada gigafactory partnership anchors cathode precursor contracting volumes across the Southwest manufacturing belt.
Texas
Commercial vehicle electrification accelerates fastest here, with fleet operators specifying LFP cells for battery-electric trucks serving Houston and Dallas-Fort Worth logistics corridors. ERCOT grid instability propels utility-scale energy storage procurement, decoupling from passenger EV chemistry preferences. Spheronized graphite anode demand concentrates in Beaumont-Port Arthur processing clusters serving regional cell assembly.
Michigan
The Detroit Three automakers lock multi-year offtake agreements directly with Great Lakes corridor chemical converters, squeezing independent cell producers into secondary supply tiers. NHTSA fuel economy standards compress compliance timelines, forcing cathode active material procurement cycles tighter. Ford's BlueOval SK joint venture in Marshall exemplifies integrated OEM-chemical converter structures dominating regional queue positions.
Ohio
BASF's Elyria technical center sustains R&D intensity across high-nickel cathode formulations, anchoring Midwestern electrochemical engineering talent concentration. Honda's announced EV hub near Marysville triggers precursor plant commitments from Korean chemical converters seeking IRA manufacturing credits. The Appalachian lithium belt spodumene deposits in neighboring states feed regional hydroxide conversion capacity.
Nevada
Thacker Pass lithium extraction projects face EPA environmental review timelines extending development cycles beyond capital commitment horizons. Tesla's Nevada gigafactory remains the primary domestic demand anchor for NCA precursor materials in cylindrical cell formats. Geothermal lithium brine recovery ventures in the Silver Peak district compete against hard rock spodumene economics for regional feedstock share.
United States Electric Vehicle Battery Materials Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the United States electric vehicle battery materials market. Integrated mining-chemical conglomerates control upstream lithium and nickel sulfate supply security, while specialized recyclers and nanomaterial entrants capture downstream value in closed-loop recovery and solid-state electrolyte formulations. The competitive structure fragments across three strategic archetypes: upstream resource owners, cathode precursor specialists, and hydrometallurgical recovery operators. Dominant competitive moves include backward integration into extraction assets and joint venture structuring around IRA manufacturing credit eligibility.
Within the integrated mining tier, Albemarle Corporation anchors upstream lithium concentration infrastructure through its Kings Mountain operations, while BASF SE exemplifies European-headquartered chemical converters sustaining R&D presence through Ohio technical centers. Redwood Materials occupies a distinct position as a specialized hydrometallurgical recovery operator, positioning closed-loop black mass processing as a parallel feedstock channel against virgin extraction dependence. These three represent the archetypal competitive positions—upstream resource security, chemical conversion R&D intensity, and circular material recovery—shaping procurement contracting structures across the domestic supply base.
| Leading Market Players |
|---|
| Targray Technology International Inc. |
| BASF SE |
| Mitsubishi Chemical Group Corporation |
| UBE Corporation |
| Umicore SA |
| Redwood Materials |
| Albemarle Corporation |
| Livent Corporation |
| QuantumScape Corporation |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between Great Lakes corridor chemical converters and Detroit Three automakers lock in cathode precursor supply access while fixing price visibility across multi-year procurement cycles. These structures insulate qualified feedstock from spot market volatility while compressing margins for independent cell producers excluded from preferred queue positions.
Pricing Analysis
After-sales service bundling and technical support contracts drive lifetime value differentiation among cathode active material suppliers. Three-tier pricing structure across premium high-nickel NMC, standard mid-nickel formulations, and economy LFP grades reflects purity thresholds and certification complexity. Cost compression in mid-nickel tiers is intensifying because Korean chemical converters are redirecting excess capacity toward Ohio precursor plants. Fleet operators in Texas commercial vehicle segments exhibit highest price sensitivity, while California passenger EV buyers absorb premiums for maximum energy density specifications.
Supply Chain Analysis
China controls spheronized natural graphite processing, South Korea dominates high-purity nickel sulfate conversion, and Australia anchors spodumene concentrate exports. Domestic anode supply draws from Chinese feedstock dependency, cobalt hydroxide rests on Central African mining concentration, and lithium hydroxide hinges on Great Lakes corridor refinery expansion. Single-source vulnerability in graphite anode inputs exposes cell manufacturers to tariff and logistics disruption. Distribution runs through vertically integrated OEM gigafactories capturing preferred offtake positions ahead of merchant market purchasers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where IRA domestic content thresholds create regulatory entrenchment that locks out import-dependent competitors and secures queue positions for qualifying producers.
For Market Incumbents: Secure upstream spodumene extraction assets in Nevada and North Carolina to anchor lithium hydroxide supply security against permitting friction extending project timelines. Lock multi-year offtake extensions with Ford and GM before Korean chemical converters capture remaining Great Lakes corridor capacity. Sodium-ion prototype advancement poses substitution threat to lithium compound demand in commercial vehicle segments. For New Entrants and Emerging Players: UL 1973 certification fast-track for stationary storage battery systems opens white-space entry into Texas ERCOT grid installations where LFP demand outruns qualified domestic supply. Target aftermarket replacement battery channels serving independent repair networks in California urban mobility pilots. Go-to-market angle: closed-loop black mass recovery partnerships with southeastern hydrometallurgical processors bypassing virgin mining qualification timelines. For Investors and Strategic Acquirers: Specialized hydrometallurgical recovery operators with proven black mass processing yields represent acquisition target archetype capturing circular material premiums. Long-term viability centers on Treasury guidance stability for IRA manufacturing credits across the mid-decade window. Signal to watch: EPA environmental review acceleration for Thacker Pass lithium projects as inflection indicator for domestic spodumene supply scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Extraction Assets | Albemarle's Kings Mountain infrastructure secures upstream lithium concentration for southeastern cell plants. |
| IRA Manufacturing Credit Joint Venture | Honda's Marysville EV hub triggers Korean converter commitments to Ohio cathode precursor facilities. |
| Hydrometallurgical Recovery Scale-Up | Redwood Materials positions closed-loop feedstock as parallel channel against virgin extraction dependence. |
| High-Nickel Cathode R&D Intensity | BASF's Elyria technical center sustains formulation leadership for NMC 811 and 9½½ architectures. |
| Fleet Electrification Partnership | Texas commercial vehicle operators accelerate LFP procurement faster than consumer adoption curves projected. |
Research Methodology
A spread of perspectives from cathode precursor plant managers, OEM procurement executives at Ford and GM, IRA technical guidance specialists, and SEC climate disclosure counsel converged on the working assumptions governing supply chain localization timelines. Primary fieldwork with Great Lakes corridor chemical converters combined with secondary validation from EPA environmental review databases, NHTSA fuel economy standard filings, and Treasury IRA guidance documents. Bottom-up cell capacity buildout estimates triangulated against top-down EV sales penetration models.
Segmentation dimensions modeled span material type, battery chemistry stoichiometry, end-user contracting structure, and application geography across the projection horizon. CAGRs were derived from installed capacity buildout curves and chemistry migration assumptions. Forecast inputs incorporated NHTSA compliance timeline compression and fleet electrification acceleration in Michigan, Ohio, and Illinois.
Decision-makers should treat outputs as directional under IRA credit stability and permitting velocity assumptions; material deviation in Treasury guidance or EPA review timelines would warrant model refresh. Recalibration cycles align with material shifts in domestic content threshold enforcement and cathode precursor plant commissioning schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
North America Electric Vehicle VRLA Batteries Market
EV Batteries
Italy Electric Vehicle Battery Manufacturing Market
EV Batteries
Solar DC Coupled Battery Market
EV Batteries
Canada Electric Vehicle Battery Electrolyte Market
EV Batteries
Europe Electric Vehicle Battery Manufacturing Market
EV Batteries
Europe Electric Bus Battery Pack Market
EV Batteries
UK EV Battery Pack Market
EV Batteries
US EV Battery Pack Market
EV Batteries
North America Electric Vehicle Battery Anode Market
EV Batteries
Automotive Rechargeable Battery Market
EV Batteries
Japan EV Battery Pack Market
EV Batteries
ASEAN Countries Electric Vehicle Battery Manufacturing Market
EV Batteries
Electric Vehicle Battery Conditioners Market
EV Batteries
China Electric Vehicle Battery Materials Market
EV Batteries
North America Electric Vehicle Battery Materials Market