
 India EV Battery Pack Market | 2026-2036
India EV Battery Pack Market Size, Share, and Industry Trends Forecast 2026-2036
India EV Battery Pack Market Insights
The PLI scheme for Advanced Chemistry Cell manufacturing is decoupling domestic battery pack assembly from import-dependent cell supply chains. CATL leverages its global cell engineering depth to anchor technology partnerships with Indian pack integrators. Exide Industries sustains its century-old distribution network to dominate aftermarket service channels. Ola Electric specializes in in-house pack design for its two-wheeler platform, compressing development cycles.
An EV battery pack is an integrated electromechanical assembly comprising cells, modules, thermal management hardware, and a battery management system, engineered to deliver nominal voltages between 48V and 800V depending on vehicle class. Its primary purpose is to store and discharge electrical energy safely across thousands of cycles while maintaining thermal stability under Indian ambient conditions ranging from sub-zero Himalayan altitudes to 50°C desert corridors. Lithium-ion chemistry occupies the dominant share of new pack deployments, though solid-state prototypes are advancing through pilot lines as manufacturers chase higher energy density targets. Two-wheeler and e-rickshaw end-user segments concentrate volume demand, while commercial vehicle applications command premium pricing due to larger pack capacities and stringent duty-cycle requirements.
BIS certification mandates, CEA safety protocols, and the FAME II subsidy framework collectively shape product standards and market access for battery pack suppliers operating in India. The central bank's green financing guidelines and state-level EV policies in Maharashtra, Karnataka, and Telangana further channel capital toward localized manufacturing capacity. Stakeholders must monitor how BIS evolves its testing standards for emerging chemistries and whether the PLI scheme extends beyond initial allocations to sustain domestic cell production scale.
Market Dynamics
The PLI scheme for Advanced Chemistry Cell manufacturing is decoupling domestic battery pack assembly from import-dependent cell supply chains, creating a structural inflection point for localization economics.
Growth Catalysts
- FAME II subsidy framework:Fleet operators in commercial vehicle segments are scaling electrified logistics through demand-side incentives that compress total cost of ownership.
- Tamil Nadu manufacturing cluster:Concentrated cell-to-pack assembly investments attract tier-1 supplier ecosystems and reduce logistics friction for OEMs.
- Lithium-ion chemistry maturation:Established cell formats enable pack integrators to focus capital on thermal management and battery management system differentiation.
Market Restraints
- Cell import concentration:Domestic pack assembly remains tethered to Chinese and Korean cell suppliers, exposing margins to currency volatility and geopolitical friction.
- Raw material cost structure:Lithium carbonate and nickel sulfate prices transmit directly to pack pricing, with limited domestic mining or refining capacity to buffer shocks.
- BIS certification timelines:Extended testing protocols for new chemistries delay product launches and freeze working capital in inventory.
Strategic Opportunities
- Gujarat supplier ecosystem:Emerging port-adjacent manufacturing zones offer duty advantages for export-oriented pack production serving Middle Eastern and African markets.
- Solid-state chemistry convergence:Pilot line investments by domestic integrators position early movers for energy density premiums in premium two-wheeler segments.
- State-level EV policies:Maharashtra, Karnataka, and Telangana channel green financing toward localized capacity, creating first-mover land and power cost advantages.
Industry Challenges
- Thermal engineering talent scarcity:Pack designers with expertise in 50°C ambient operation and sub-zero cold-start performance command premium compensation and extend hiring cycles.
- Capex intensity for testing infrastructure:BIS-mandated abuse testing chambers and thermal runaway propagation facilities require multi-year depreciation schedules that strain balance sheets.
- Legacy fleet integration complexity:Retrofit pack architectures for existing commercial vehicle platforms demand custom mechanical interfaces that fragment production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India EV Battery Pack Market |
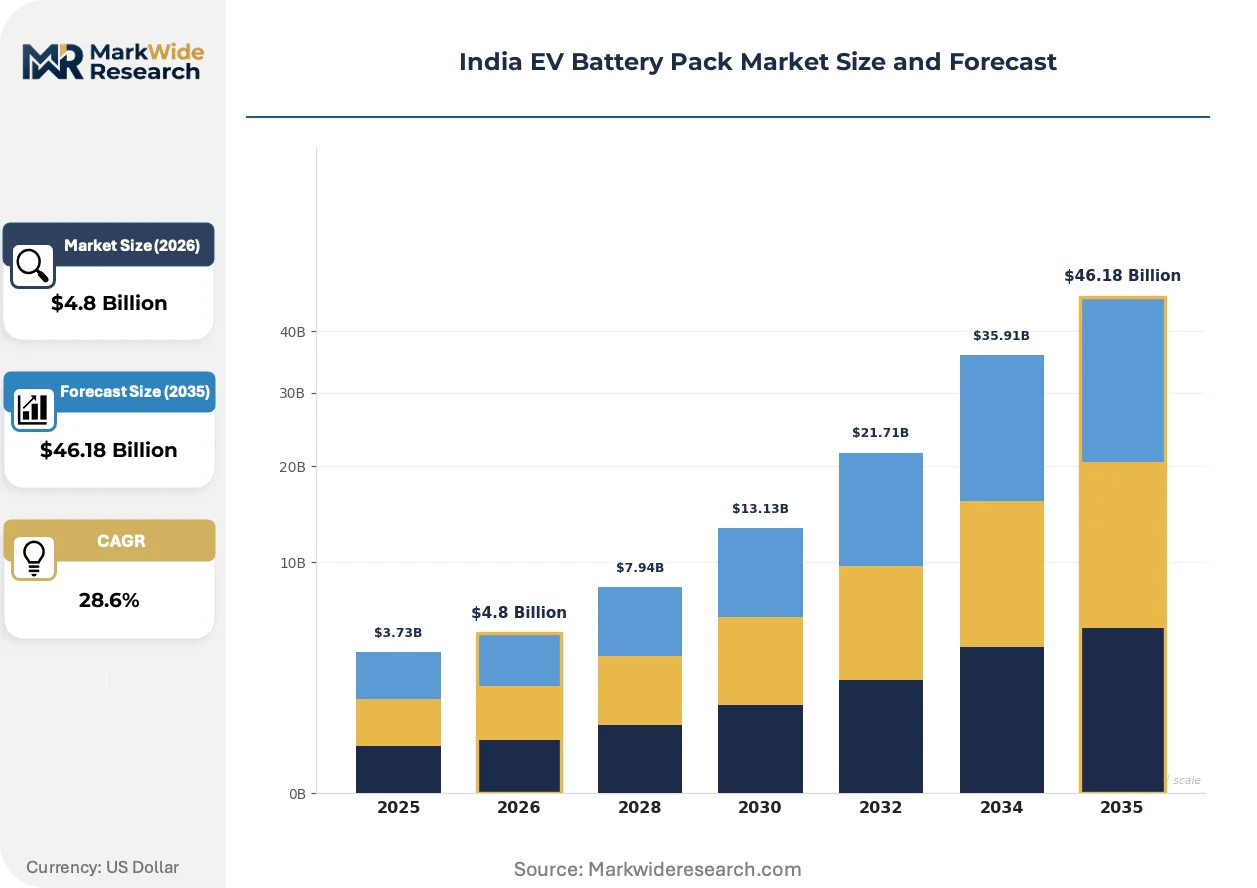
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $46.18 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead-acid, Nickel-metal Hydride, Solid State End User: Passenger Vehicles, Commercial Vehicles, Two-wheelers, E-rickshaws Application: Electric Mobility, Energy Storage, Power Tools, Appliances Technology: Battery Management System, Fast Charging, Wireless Charging, Recycling |
| Companies Covered | Contemporary Amperex Technology Co. Ltd. (CATL), Nexcharge, Amara Raja Batteries, Denso Corporation, Okaya Power Group, Exide Industries, Tata Autocomp Systems Ltd., Ola Electric, LG Energy Solution Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India EV Battery Pack Market Trends and Innovations
Active materials research and regulatory tightening are compressing development cycles while reshaping how pack suppliers compete on safety credentials rather than cost alone.
Silicon-anode formulations are rewriting energy density benchmarks for Indian two-wheeler applications. Tier-1 pack integrators are sampling 400 Wh/kg prototype cells from Korean suppliers for premium scooter platforms. This chemistry transition is compressing the performance gap between domestic packs and imported alternatives.
CEA safety protocols now mandate thermal runaway propagation testing for all commercial vehicle battery packs. Manufacturers must submit abuse test documentation to central electricity authority regional offices before grid interconnection approval. Commercial fleet operators are responding by specifying certified packs exclusively in procurement tenders.
Direct OEM-pack integrator partnerships are displacing traditional component distribution channels. Two-wheeler manufacturers in Pune and Chennai are embedding engineers within supplier facilities to co-develop form factors. This pattern is most visible in the electric scooter segment where platform-specific thermal architectures command design exclusivity agreements.
India EV Battery Pack Market Segmentation
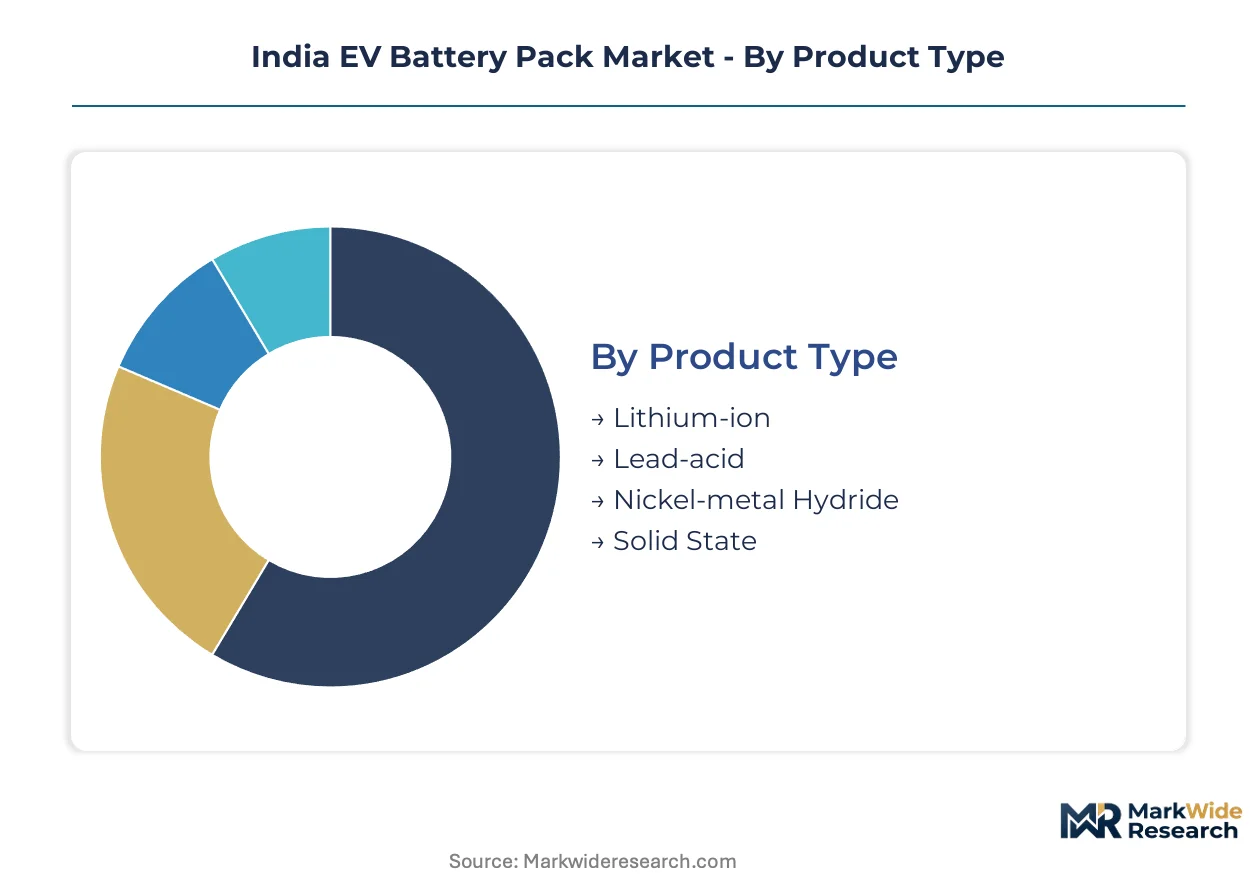
Pack integrators configure cell chemistry, thermal architecture, and management electronics differently across vehicle classes and stationary applications. Segmentation reveals where BIS certification burdens concentrate and which end-use segments justify dedicated production lines.
Product Type:
Supply concentration for cell inputs shapes how pack assemblers allocate engineering resources across chemistry portfolios.
- Lithium-ion:NMC and LFP cell formats dominate current pack deployments, with LFP gaining share in commercial vehicle applications due to thermal stability and cycle life advantages. Tamil Nadu and Gujarat assembly plants process imported cylindrical and prismatic cells into module and pack configurations for two-wheeler OEMs.
- Lead-acid:Flooded and AGM variants persist in price-sensitive e-rickshaw retrofits and low-speed electric vehicle segments where BIS certification costs outweigh chemistry performance gaps. Demand clusters in Uttar Pradesh and Bihar aftermarket channels.
- Nickel-metal Hydride:Limited to hybrid vehicle auxiliary packs and industrial backup applications where established supply relationships with Japanese cell suppliers reduce switching costs.
- Solid State:Pilot line investments by domestic integrators target premium two-wheeler segments with sulfide and oxide electrolyte prototypes undergoing abuse testing at CEA-certified facilities.
Lithium-ion absorbs the bulk of installed capacity; solid state is expanding most quickly.
End User:
Vehicle duty cycles and operating temperature ranges determine pack sizing, cooling architecture, and warranty terms across customer categories.
- Two-wheelers:Compact 48V-72V packs with passive air cooling dominate volume production, with Ola Electric and Ather Energy specifying custom form factors that compress development cycles through co-located engineering teams.
- Commercial Vehicles:400V-800V architectures with active liquid cooling command premium pricing due to larger capacities and FAME II fleet subsidy eligibility. Tata Motors and Mahindra Electric specify thermal runaway propagation testing for all procurement tenders.
- E-rickshaws:Swappable lead-acid and lithium-ion packs serve last-mile logistics operators in Delhi-NCR and Kolkata metropolitan regions under state-level EV policies.
- Passenger Vehicles:SUV and sedan platforms from Hyundai, Tata, and MG Motor integrate imported cell-based packs with localized BMS calibration for Indian ambient temperature profiles.
Two-wheelers absorb the bulk of installed capacity; commercial vehicles are climbing the fastest.
Application:
Margin structure and certification pathways diverge sharply between mobility and stationary energy applications.
- Electric Mobility:Pack designs prioritize gravimetric energy density and crash safety compliance under AIS-156 standards, with OEM-direct procurement displacing traditional distribution channels.
- Energy Storage:Second-life automotive packs and purpose-built stationary systems serve telecom tower backup and grid-scale solar pairing projects under CEA interconnection protocols.
- Power Tools:Cylindrical cell-based packs for construction and agriculture equipment require IP65 enclosure ratings and rapid swap interfaces.
- Appliances:Low-voltage packs for residential inverters and UPS systems compete on cost with established lead-acid alternatives in tier-2 and tier-3 retail channels.
Electric mobility absorbs the bulk of installed capacity; energy storage is gaining share fastest.
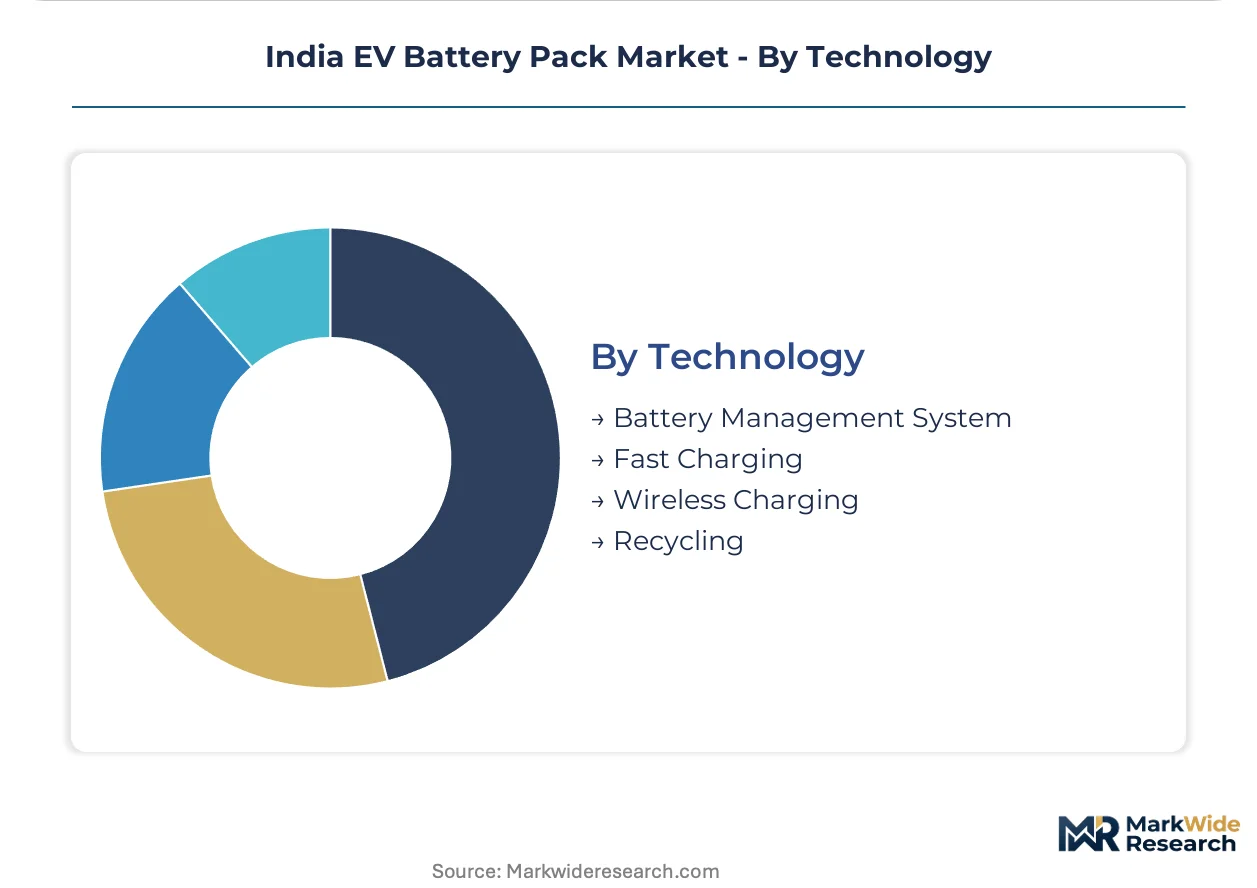
Technology:
Value capture in pack assembly increasingly concentrates on thermal management and electronic control subsystems rather than cell sourcing.
- Battery Management System:ASIL-D compliant BMS hardware with cell balancing, state-of-charge estimation, and thermal monitoring differentiates pack suppliers for premium vehicle segments.
- Fast Charging:350A+ capable pack architectures with enhanced cooling loops enable 15-minute charge targets for commercial fleet operators scaling electrified logistics.
- Wireless Charging:Inductive pad integration for automated guided vehicles and premium two-wheeler parking infrastructure remains pre-commercial with limited BIS standardization.
- Recycling:Hydrometallurgical and pyrometallurgical recovery processes for lithium, cobalt, and nickel from end-of-life packs attract PLI-linked investments in Maharashtra and Karnataka.
Battery Management System absorbs the bulk of installed capacity; recycling is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial fleet operators and two-wheeler OEMs concentrate demand in specific Indian states where manufacturing clusters, port access, and state-level EV policies create differentiated investment environments.
Tamil Nadu
Two-wheeler OEMs and commercial vehicle assemblers drive pack procurement from Chennai and Hosur manufacturing corridors. The state's EV policy offers capital subsidies and land cost concessions for battery pack investments. Sriperumbudur and Oragadam industrial zones host cell-to-pack assembly operations serving domestic OEMs and export markets.
Gujarat
Port-adjacent manufacturing at Mundra and Hazira enables duty-efficient import of cells and export of finished packs to Middle Eastern and African markets. The state's industrial policy prioritizes ACC manufacturing under PLI-linked incentives. Sanand and Halol emerging as dedicated EV component zones with dedicated power infrastructure.
Maharashtra
Pune and Chakan automotive clusters generate concentrated demand from passenger vehicle and commercial fleet electrification programs. The state's EV policy mandates green financing channeling through Maharashtra State Road Development Corporation. Thane-Bhiwandi logistics corridors drive swappable pack demand for last-mile delivery operators.
Karnataka
Bengaluru-based two-wheeler startups and electric bus operators source packs from localized assembly operations. The state's EV policy exempts battery packs from electricity duty and offers reimbursement of SGST for intrastate sales. Electronic City and Peenya industrial areas concentrate BMS and thermal management subsystem suppliers.
Telangana
Hyderabad emerging as a testing and certification hub with CEA-recognized facilities for thermal runaway propagation studies. The state's EV policy reserves manufacturing zones in Zaheerabad and Choutuppal for battery and component investments. T-Hub startup ecosystem incubating pack design ventures focused on two-wheeler applications.
India EV Battery Pack Market Competitive Landscape
Korean and Chinese cell producers anchor the supply tier; Indian pack integrators and automotive component specialists hold the assembly and system integration tier. Market structure tilts toward concentrated upstream cell sourcing and fragmented downstream pack assembly. Three archetypes dominate: global cell engineering licensors, domestic legacy battery manufacturers repurposing distribution networks, and captive OEM pack designers. Capacity expansion and strategic technology licensing represent the dominant competitive vectors.
Among global cell engineering licensors, Contemporary Amperex Technology Co. Ltd. and LG Energy Solution Ltd. occupy positions as technology anchors for Indian pack integrators seeking chemistry and format access. Exide Industries and Amara Raja Batteries exemplify legacy battery manufacturers extending century-old distribution infrastructure into EV aftermarket channels. Ola Electric represents the captive OEM archetype, integrating pack design with vehicle platform development to compress iteration cycles.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co. Ltd. (CATL) |
| Nexcharge |
| Amara Raja Batteries |
| Denso Corporation |
| Okaya Power Group |
| Exide Industries |
| Tata Autocomp Systems Ltd. |
| Ola Electric |
| LG Energy Solution Ltd. |
| Others |
Pricing and Supply Chain Analysis
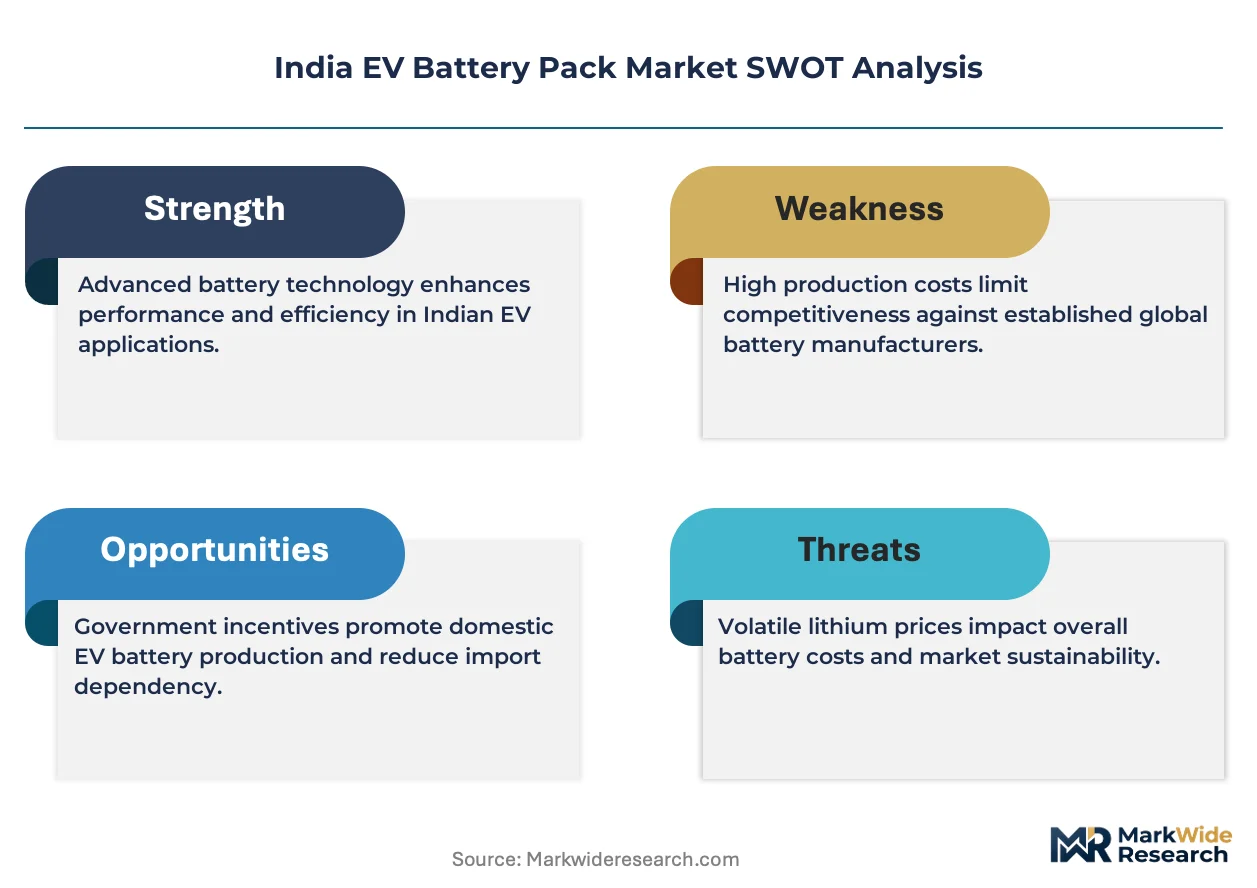
CEA thermal runaway propagation testing mandates gate qualified supply and premium-tier pricing access for battery pack suppliers serving commercial vehicle fleet operators. BIS certification timelines freeze working capital in inventory while compressing margins for non-compliant assemblers unable to access FAME II-linked procurement channels.
Pricing Analysis
Short lead-time premiums for certified pack deliveries command pricing spreads over spot inventory from uncertified suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects BIS certification grade and volume scale. Price differentiation stems from thermal management complexity and after-sales service bundling. Cost compression in economy-tier lead-acid retrofits is intensifying because e-rickshaw operators in Uttar Pradesh and Bihar prioritize acquisition cost over cycle life. Commercial fleet operators demonstrate least price sensitivity due to FAME II total cost of ownership calculations.
Supply Chain Analysis
Reverse-logistics flows for end-of-life pack collection and hydrometallurgical recovery are emerging as cost centers rather than revenue streams for integrators lacking scale. Cell supply concentrates in China, South Korea, and Japan, with domestic assembly drawing from imported cylindrical and prismatic formats. Lithium carbonate, nickel sulfate, and cobalt hydroxide constitute critical raw material dependencies. Single-source vulnerability to Chinese cell suppliers exposes margins to currency volatility and geopolitical friction. Distribution runs through OEM-direct procurement channels displacing traditional aftermarket networks for lithium-ion packs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where BIS certification and CEA safety protocols erect barrier-to-entry moats favoring capitalized incumbents with testing infrastructure already depreciated.
For Market Incumbents: To counter margin erosion from Chinese cell price volatility, deepen backward integration into module assembly automation and expand captive thermal engineering talent pools. Secure multi-year offtake agreements with Korean cell suppliers to buffer currency exposure. Prioritize ASIL-D BMS certification investments to lock in premium passenger vehicle procurement channels. For New Entrants and Emerging Players: Swappable pack architectures for e-rickshaw fleet operators in Delhi-NCR represent the most penetrable white-space target. Second-life stationary energy storage for telecom tower backup offers alternative revenue streams with reduced certification burdens. Lead with pay-per-use financing models to bypass upfront capital constraints among price-sensitive buyer segments. For Investors and Strategic Acquirers: PLI scheme extension announcements beyond initial ACC allocations are the leading indicator that domestic cell production scale will sustain pack assembly localization economics. Target mid-cap pack integrators with established CEA-certified testing infrastructure and existing OEM engineering co-location agreements. Monitor state-level EV policy revisions in Maharashtra and Karnataka for land and power cost advantage shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Assembly Scale-Up | Tamil Nadu and Gujarat manufacturing clusters reduce logistics friction for domestic OEMs. |
| Solid-State Chemistry Pilot Investment | Sulfide and oxide electrolyte prototypes position early movers for premium two-wheeler energy density premiums. |
| Thermal Engineering Talent Acquisition | Pack designers with 50°C ambient expertise command premium compensation and extend hiring cycles. |
| CEA-Certified Testing Infrastructure | Thermal runaway propagation facilities enable grid interconnection approval for commercial vehicle applications. |
| State-Level Policy Arbitrage | Maharashtra, Karnataka, and Telangana green financing channels capital toward localized capacity. |
Research Methodology
Multi-period observation of cell import volumes, BIS certification timelines, and PLI scheme allocation patterns anchored the trend analysis, supplemented by interviews with pack integrator procurement leads, OEM platform engineers, thermal management subsystem suppliers, and CEA regional testing facility directors. Secondary validation drew from DGFT trade data, CEA safety protocol amendments, state EV policy documents, and SEC filings of listed battery manufacturers. Bottom-up capacity build-up estimates triangulated against top-down fleet electrification targets under FAME II.
Segment-weighting across vehicle class, chemistry format, cooling architecture, and regional manufacturing cluster shaped the analytical framework. Modeled dimensions included two-wheeler versus commercial vehicle duty cycles, NMC versus LFP cell preferences, passive air versus active liquid thermal systems, and Tamil Nadu versus Gujarat production location. CAGRs derived from installed capacity trajectories, fleet operator procurement pipelines, and subsidy regime elasticity assumptions. Industry-specific inputs encompassed lithium carbonate price transmission coefficients and BIS testing queue durations.
Revisions become necessary when PLI scheme extensions fail to materialize, Chinese export restrictions on cell formats tighten, or solid-state chemistry pilot lines achieve commercial scale earlier than modeled. Forecasts reflect documented assumptions about subsidy continuity, raw material price corridors, and certification timeline stability. Practitioners should monitor DGFT import policy shifts, CEA testing standard evolutions for emerging chemistries, and state-level EV policy fiscal health for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Europe LFP Battery Pack Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Market
EV Batteries
EV Battery Cells Market
EV Batteries
EV Battery Heating System Market
EV Batteries
Canada Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Materials Market
EV Batteries
Asia Pacific Electric Vehicle Battery Manufacturing Market
EV Batteries
France Electric Vehicle Battery Manufacturing Market
EV Batteries
Electric Vehicle Battery Conditioners Market
EV Batteries
North America Electric Vehicle Battery Manufacturing Market
EV Batteries
Canada EV Battery Pack Market
EV Batteries
China Electric Vehicle Battery Materials Market
EV Batteries
Asia-Pacific Electric Vehicle Solid State Battery Market
EV Batteries
South America Hybrid Electric Vehicle Battery Market
EV Batteries
United States Electric Vehicle Battery Anode Market
EV Batteries
India Electric Vehicle Battery Manufacturing Market