
 Asia-Pacific EV Battery Pack Market | 2026-2036
Asia-Pacific EV Battery Pack Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific EV Battery Pack Market Insights
Direct supply contracts between cell manufacturers and automakers are rewriting procurement architecture across the Asia-Pacific EV battery pack value chain. CATL leverages its vertical reach from cathode materials to finished packs, securing long-term offtake agreements with domestic and foreign OEMs. BYD Company Limited anchors its competitive position through in-house production of both cells and electric vehicles, creating captive demand that insulates pricing cycles. Samsung SDI Co., Ltd. competes on high-nickel chemistry specialization, targeting premium passenger vehicle platforms where energy density thresholds command technical preference.
An EV battery pack integrates multiple electrochemical cells with thermal management, battery management systems, and structural enclosures to deliver stored electrical energy for propulsion, typically operating at nominal voltages between 300 and 800 volts depending on platform architecture. Lithium-ion configurations currently dominate installed capacity, though solid-state chemistries are attracting engineering investment for their potential to eliminate liquid electrolyte fire risk while doubling volumetric energy density. Passenger vehicles represent the primary application segment by value, while commercial vehicle electrification is expanding fastest due to fleet operator pressure on total cost of ownership. Fast charging technology constitutes a critical performance battleground, with 800-volt architectures reducing dwell time at public charging stations.
China's MIIT enforces GB standards for battery safety and recycling traceability, while India's BIS and CEA are formulating technical regulations for domestic cell manufacturing under the PLI scheme. Japan's METI coordinates industry consortia on solid-state commercialization timelines, creating divergent compliance obligations for regional suppliers. Stakeholders must monitor how subsidy phase-out schedules and local content requirements reshape sourcing decisions across Korea, Japan, China, and India.
Market Dynamics
China's MIIT enforcement of GB standards for battery safety and recycling traceability is forcing cell-to-pack integration decisions across the Asia-Pacific EV battery pack value chain. This regulatory pressure concentrates investment in Jiangsu and Guangdong provinces where integrated facilities cluster near OEM assembly plants.
Growth Catalysts
- Dual Carbon Goals:China's national carbon neutrality targets redirect state capital toward localized gigafactory construction, accelerating domestic cell-to-pack capacity expansion.
- Electric Bus Procurement:Municipal transport authorities across South Korea and Japan are accelerating fleet electrification mandates, creating sustained demand for high-cycle-life battery configurations.
- PLI Scheme:India's production-linked incentive framework for advanced chemistry cell manufacturing redirects automotive supply chains toward domestic battery pack assembly.
Market Restraints
- Lithium Price Volatility:Raw material input cost fluctuations constrain margin stability for pack assemblers dependent on spot-market cathode precursor sourcing.
- Supply Concentration Risk:Separator membrane and electrolyte additive production concentrates in specific Japanese and Korean chemical conglomerates, creating single-source vulnerability.
- Solid-State Timeline Uncertainty:Technical limitations in ceramic electrolyte manufacturing scalability delay commercialization roadmaps beyond current lithium-ion replacement cycles.
Strategic Opportunities
- India Underpenetration:Domestic passenger vehicle electrification remains below regional averages, creating white space for localized pack assembly serving Maruti-Suzuki and Tata Motors platforms.
- 800-Volt Architecture Convergence:Silicon carbide power electronics integration with high-voltage pack designs enables ultra-fast charging infrastructure deployment.
- Second-Life Stationary Storage:Retired automotive cells find emerging application in grid-scale energy storage, extending value capture beyond initial vehicle lifecycle.
Industry Challenges
- Thermal Management Engineering Gap:Pack assemblers face acute shortages of computational fluid dynamics specialists capable of optimizing liquid cooling channel geometries for high-nickel chemistries.
- GB Standard Certification Timelines:Extended testing protocols for nail penetration and thermal runaway propagation create product launch delays for new pack architectures targeting Chinese OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific EV Battery Pack Market |
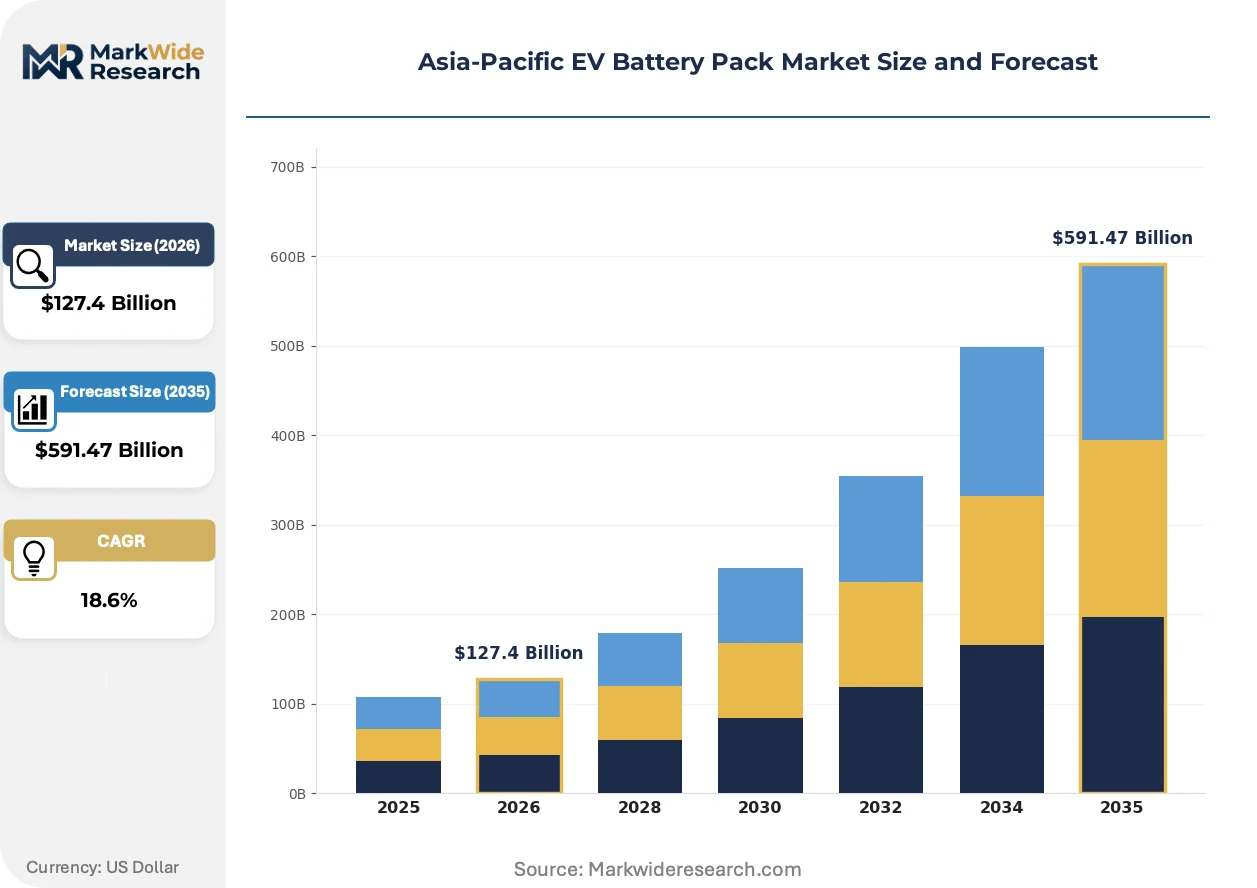
| Market Size in 2026 | $127.4 Billion |
| Market Size in 2035 | $591.47 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead-acid, Nickel Metal Hydride, Solid-state Application: Passenger Vehicles, Commercial Vehicles, E-Scooters, E-Bikes Technology: Fast Charging, Wireless Charging, Regenerative Braking, Battery Management Systems End User: Automakers, Fleet Operators, Retail Consumers, Public Transport |
| Companies Covered | Contemporary Amperex Technology Co. Limited (CATL), BYD Company Limited, LG Energy Solution, Samsung SDI Co., Ltd., Panasonic Corporation, SK Innovation Co., Ltd., Toshiba Corporation, Hitachi Ltd., Mitsubishi Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific EV Battery Pack Market Trends and Innovations
Cell-to-pack architectures are collapsing traditional module assembly steps, compressing manufacturing cost structures while redistributing technical risk toward direct cell-to-structural integration. This structural shift redefines supplier relationships across the Asia-Pacific EV battery pack ecosystem.
Cell-to-pack technology eliminates intermediate module housings by bonding cells directly into the vehicle floor structure. Premium passenger vehicle platforms from Korean and Chinese OEMs are adopting this architecture fastest, lured by weight reduction and space efficiency gains. The technology is collapsing legacy tiered supplier hierarchies, forcing module specialists to pivot toward thermal management or exit the value chain entirely.
China's MIIT has tightened GB 38031 enforcement for battery system safety, mandating five-minute thermal runaway warning intervals and full lifecycle traceability. Pack manufacturers must now integrate blockchain-enabled tracking from cathode material sourcing through end-of-life recycling. Korean exporters face the steepest compliance recalibration, as their legacy certification frameworks predate these specific propagation containment requirements.
Fleet operators are consolidating procurement decisions at the holding-company level, bypassing traditional dealer-network intermediaries for direct manufacturer negotiations. Commercial vehicle electrification across Australian mining operations and Southeast Asian logistics corridors exhibits this pattern most visibly, with operators demanding guaranteed residual value and battery health monitoring as contract inclusions rather than aftermarket add-ons.
Asia-Pacific EV Battery Pack Market Segmentation
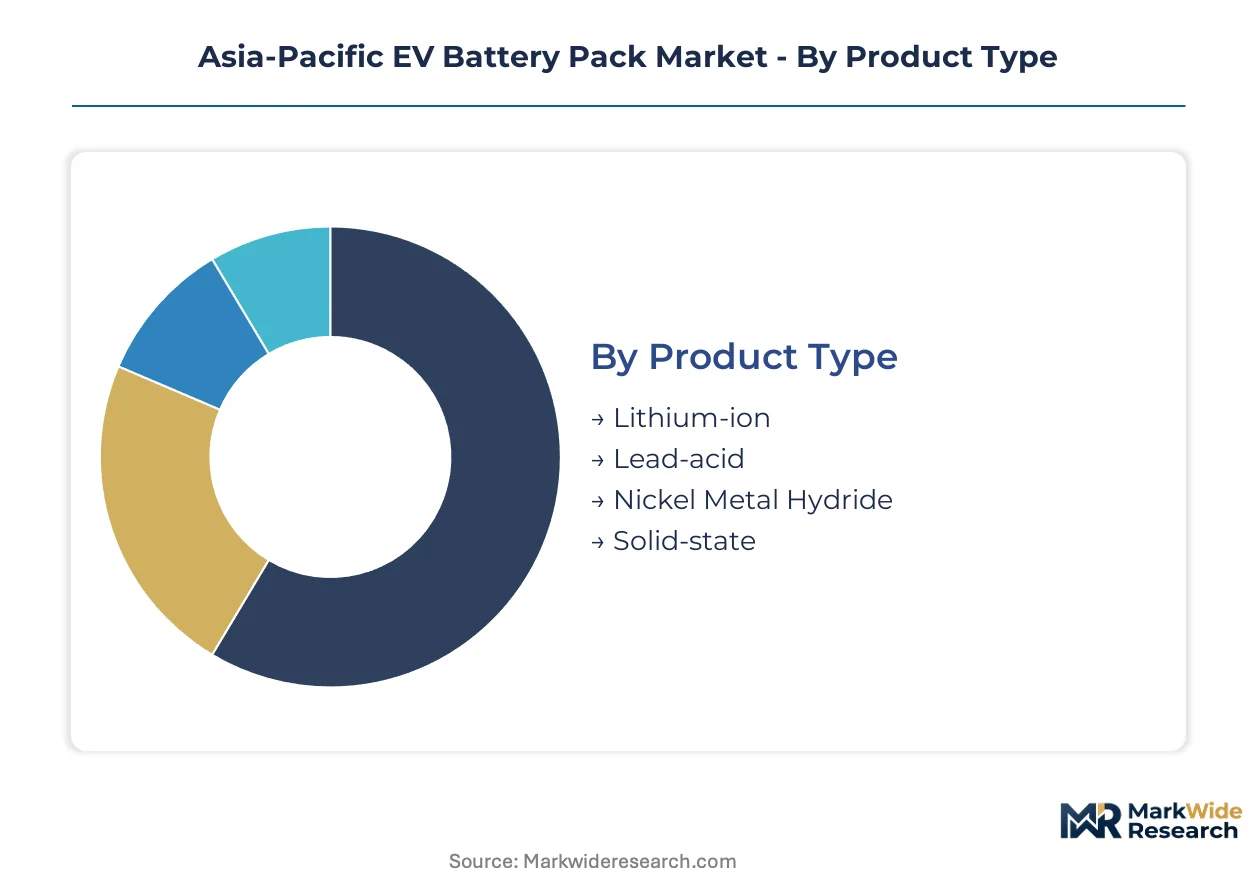
Segmentation reveals how procurement cycles, technical requirements, and margin structures diverge across the Asia-Pacific EV battery pack landscape. Understanding these divisions exposes where capital concentrates and which configurations face obsolescence pressure.
Product Type:
Lithium-ion chemistry dominates current cycle times with the shortest replacement intervals, while solid-state development operates on decade-long commercialization horizons.
- Lithium-ion:NCM and LFP configurations constitute the installed base, with Jiangsu and Guangdong facilities producing cell-to-pack architectures for domestic OEMs. CATL and BYD anchor supply through integrated cathode-to-assembly operations, though nickel and cobalt price volatility compresses assembler margins.
- Solid-state:Ceramic electrolyte designs promise doubled energy density and eliminated thermal runaway risk, but manufacturing scalability bottlenecks delay mass production. Japan's METI coordinates industry consortia targeting commercialization, with Korean and Chinese cell makers monitoring technical milestones.
- Lead-acid:Legacy chemistry persists in low-speed commercial applications and aftermarket replacement markets where cost sensitivity outweighs energy density requirements.
- Nickel Metal Hydride:Toyota's hybrid platforms sustain residual demand, though chemistry share contracts as full-electric architectures displace transitional powertrains.
Lithium-ion anchors the volume base while solid-state gains share at the steepest rate.
Application:
Passenger vehicle procurement cycles align with model-year refreshes, whereas commercial fleet electrification follows holding-company capital allocation timelines.
- Passenger Vehicles:Premium platforms from Korean and Chinese OEMs adopt 800-volt architectures fastest, enabling silicon carbide integration and ultra-fast charging. Energy density thresholds command technical preference, with high-nickel chemistries penetrating luxury segments.
- Commercial Vehicles:Australian mining operators and Southeast Asian logistics corridors consolidate procurement at holding-company level, demanding guaranteed residual value and battery health monitoring as contract inclusions. Fleet pressure on total cost of ownership accelerates electrification mandates.
- E-Scooters:Urban last-mile delivery and personal mobility drive demand across Indian and Southeast Asian cities, with swappable battery configurations addressing dwell-time constraints.
- E-Bikes:Japanese and Korean commuter markets sustain premium demand, while price-competitive Chinese manufacturing serves export markets.
Passenger vehicles command revenue concentration while commercial vehicles expand most quickly.
Technology:
Fast charging infrastructure investment cycles outpace regenerative braking maturation, creating divergent R&D allocation priorities.
- Fast Charging:800-volt pack architectures reduce station dwell time, requiring thermal management engineering for high-C-rate acceptance. China's charging network deployment and Korea's highway corridor electrification create concentrated demand.
- Regenerative Braking:Energy recovery integration with battery management systems optimizes cell cycle life, particularly relevant for urban bus applications with frequent stop-start patterns.
- Wireless Charging:Inductive pad systems attract fleet depot and autonomous vehicle applications where connector wear elimination justifies efficiency trade-offs.
- Battery Management Systems:Cell balancing and state-of-charge algorithms constitute critical software differentiation, with MIIT's GB 38031 traceability requirements mandating blockchain-enabled lifecycle tracking.
Battery management systems underpin all configurations while fast charging captures capital deployment priority.
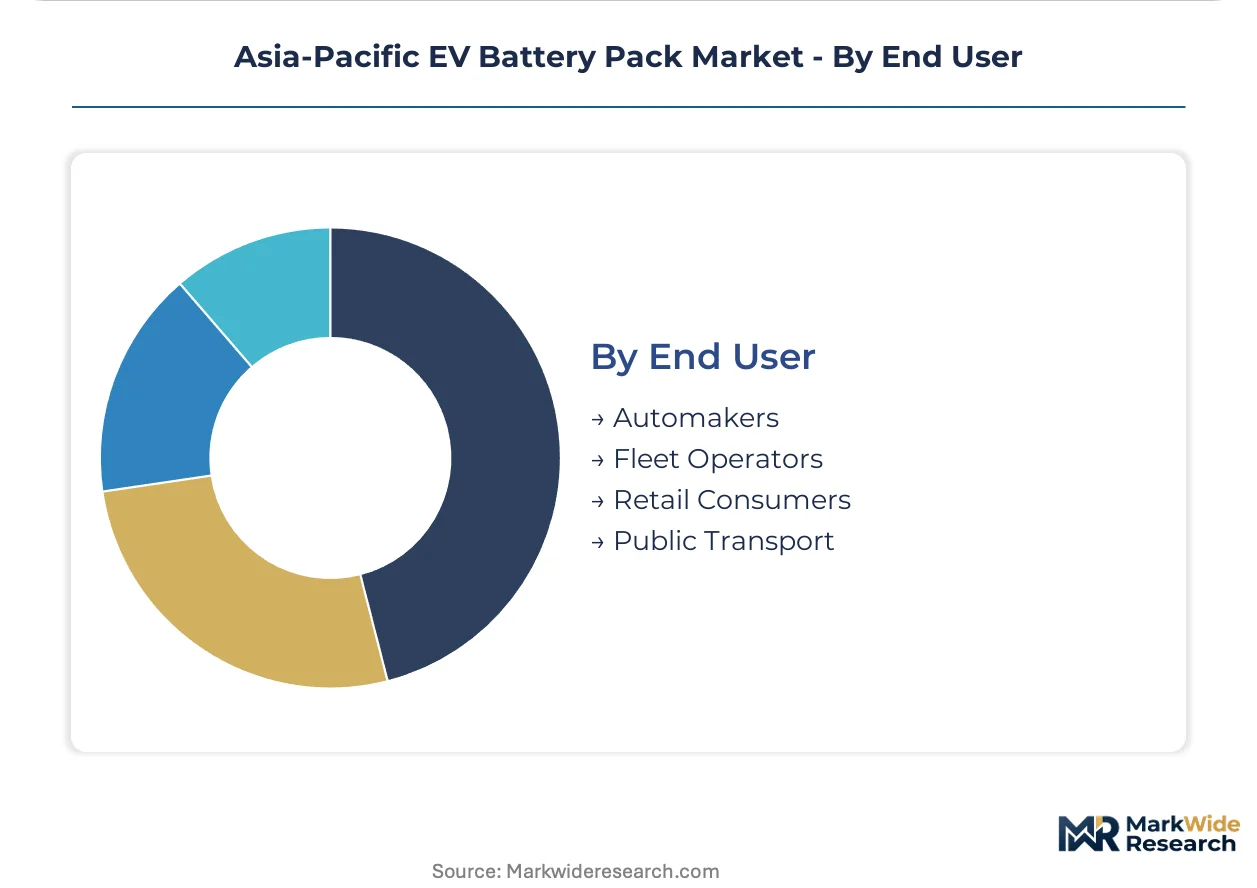
End User:
Automaker direct procurement operates on multi-year platform cycles, contrasting with fleet operator spot-market flexibility and retail consumer price sensitivity.
- Automakers:Long-term offtake agreements with cell manufacturers rewrite procurement architecture, with CATL securing supply contracts across domestic and foreign OEM assembly plants in China.
- Fleet Operators:Municipal transport authorities in South Korea and Japan accelerate electric bus procurement, creating sustained demand for high-cycle-life configurations with guaranteed performance contracts.
- Public Transport:State-owned operators in China and India's metro corporations electrify bus fleets under carbon neutrality mandates, with procurement centralized at municipal authority level.
- Retail Consumers:Replacement pack demand concentrates in aftermarket channels for out-of-warranty vehicles, with price sensitivity favoring LFP chemistries over premium NCM alternatives.
Automakers dominate contract value while fleet operators drive standardization momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Chinese Jiangsu and Guangdong manufacturing clusters while Indian and Southeast Asian markets absorb cost premiums on imported cell technology. This asymmetry shapes capital allocation toward localized assembly capacity.
China
Provincial governments in Jiangsu and Guangdong channel state capital toward integrated cell-to-pack facilities positioned adjacent to OEM assembly plants. MIIT enforcement of GB 38031 safety standards mandates five-minute thermal runaway warning intervals and blockchain-enabled lifecycle traceability from cathode sourcing through recycling. Shenzhen and Changzhou industrial zones host the densest concentrations of backward-integrated cathode-to-assembly operations serving domestic and export demand.
India
Maruti-Suzuki and Tata Motors platforms drive procurement consolidation as passenger vehicle electrification lags regional penetration rates. The PLI scheme for advanced chemistry cell manufacturing redirects automotive supply chains toward domestic battery pack assembly with BIS and CEA formulating technical regulations. Tamil Nadu and Gujarat states attract initial gigafactory investments targeting fleet electrification mandates from state transport corporations.
Japan
Hybrid platform residual demand sustains nickel metal hydride configurations even as METI coordinates industry consortia on solid-state commercialization timelines. Toyota's captive demand patterns influence supplier qualification protocols across the Nagoya and Tokyo industrial corridors. Kyushu-based chemical conglomerates retain concentration in separator membrane and electrolyte additive production.
South Korea
Municipal transport authorities in Seoul and Busan accelerate electric bus procurement with guaranteed performance contracts demanding high-cycle-life configurations. Highway corridor electrification investments create concentrated demand for 800-volt architectures enabling silicon carbide integration. Gyeonggi-do and Ulsan manufacturing belts anchor cell-to-pack capacity serving premium passenger vehicle platforms.
Australia
Mining fleet operators in Western Australia and Queensland consolidate procurement at holding-company level, bypassing dealer networks for direct manufacturer negotiations. Guaranteed residual value and battery health monitoring feature as mandatory contract inclusions rather than aftermarket add-ons. Perth and Brisbane logistics corridors exhibit the most visible commercial vehicle electrification patterns across the region.
Asia-Pacific EV Battery Pack Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream negotiating supply security through long-term offtake agreements. The market structure consolidates around cathode-to-assembly backward integration and captive vehicle production, with tiered supplier hierarchies collapsing under cell-to-pack architecture pressure. Three archetypes dominate: integrated cell-and-pack manufacturers, standalone pack assemblers dependent on external cell supply, and materials-to-systems conglomerates controlling separator and electrolyte inputs. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with silicon carbide power electronics integration emerging as a technical differentiator.
Among China-based integrated manufacturers, Contemporary Amperex Technology Co. Limited and BYD Company Limited exemplify the platform-integrator archetype through captive demand structures and cathode-to-assembly operations. Samsung SDI Co., Ltd. occupies a position representing the high-nickel chemistry specialization tier targeting premium passenger vehicle segments. These three anchors illustrate how geographic clustering and integration depth stratify competitive positioning across the regional value chain.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co. Limited (CATL) |
| BYD Company Limited |
| LG Energy Solution |
| Samsung SDI Co., Ltd. |
| Panasonic Corporation |
| SK Innovation Co., Ltd. |
| Toshiba Corporation |
| Hitachi Ltd. |
| Mitsubishi Corporation |
| Others |
Pricing and Supply Chain Analysis
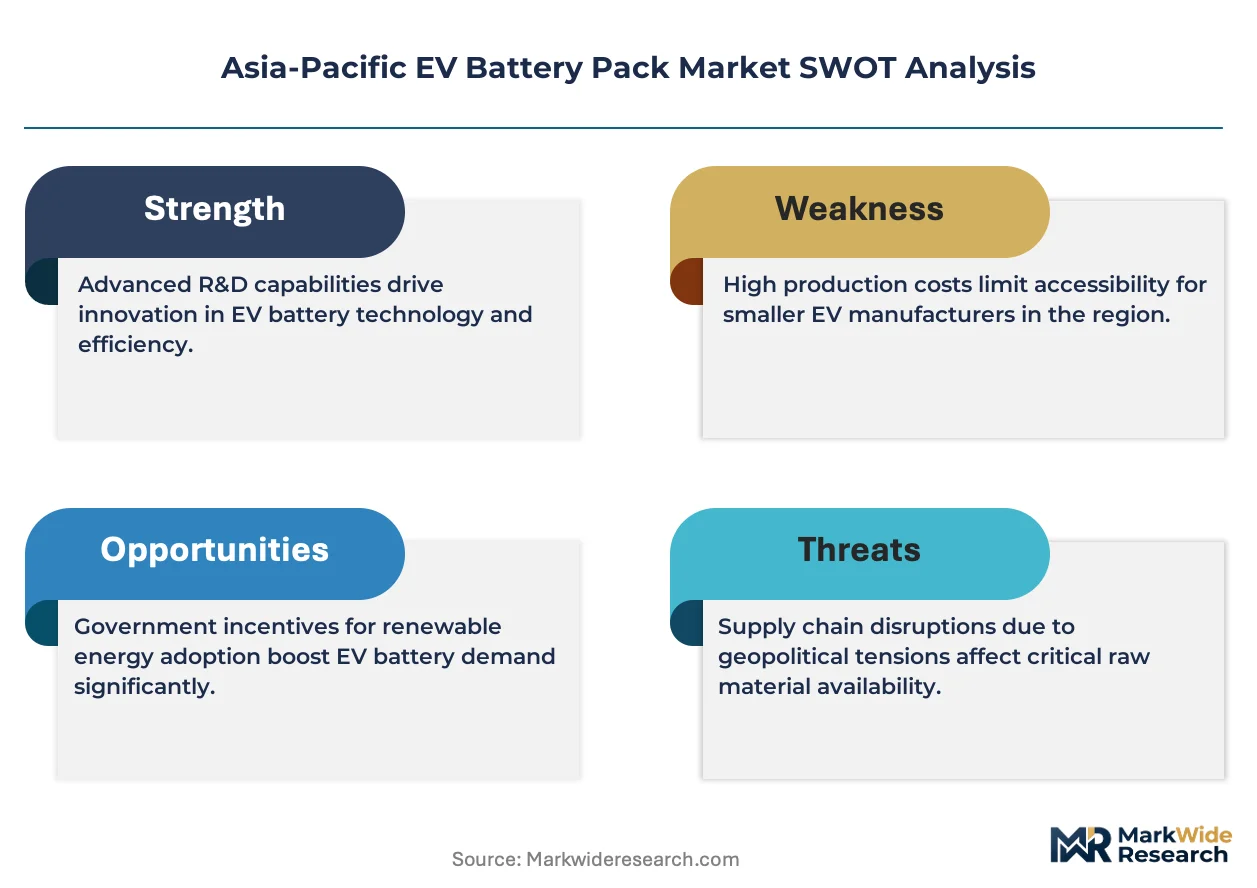
Single-source dependency on Korean and Japanese separator membrane production determines both pricing tier spreads and supply chain shape across the Asia-Pacific EV battery pack market, compressing assembler margins while concentrating procurement leverage with cathode-to-pack integrators.
Pricing Analysis
The customization-premium spread between configured-to-order cell-to-pack architectures and standard module-based configurations spans three distinct pricing levels across premium passenger vehicle, commercial fleet, and economy personal mobility tiers. Price differentiation hinges on nickel chemistry grade and MIIT GB 38031 certification status, with high-nickel NCM cells commanding substantial premiums over LFP alternatives. Cost compression in standard module assemblies is intensifying because spot-market lithium carbonate sourcing exposes assemblers to raw material volatility. Fleet operators exhibit the lowest price sensitivity due to total cost of ownership modeling, while aftermarket retail consumers drive aggressive LFP substitution to minimize replacement expenditure.
Supply Chain Analysis
Tariff exposure between China and downstream Southeast Asian assembly markets dominates supply chain risk calculus for regional pack manufacturers. Geographic concentration centers on China, South Korea, and Japan, with Jiangsu and Guangdong facilities anchoring cathode active material production and cell-to-pack integration. The supply chain draws from Australian spodumene concentrate, Chilean lithium carbonate, and Indonesian nickel matte as critical upstream inputs. Distribution runs through direct OEM offtake agreements and municipal transport authority procurement channels, bypassing traditional dealer intermediaries for commercial vehicle segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific EV battery pack market represents an early-cycle expansion story, with India's PLI scheme for advanced chemistry cell manufacturing accelerating domestic capacity buildout before passenger vehicle electrification reaches regional penetration parity.
For Market Incumbents: Entrench market position through backward integration into cathode precursor production and captive cell-to-pack capacity expansion in Tamil Nadu and Gujarat industrial corridors. Solid-state chemistry commercialization timelines from Japan's METI-coordinated consortia threaten to displace incumbent lithium-ion architectures within the next technology replacement cycle. Certification investment in MIIT GB 38031 blockchain-enabled traceability systems secures Chinese OEM qualification pipelines against Korean exporter compliance recalibration. For New Entrants and Emerging Players: Build out localized pack assembly operations targeting India's underpenetrated passenger vehicle segment, where Maruti-Suzuki and Tata Motors platform electrification lags regional adoption curves. Swappable battery configurations for Southeast Asian e-scooter fleets offer the most penetrable application white space, with urban last-mile delivery operators prioritizing dwell-time elimination over energy density optimization. Direct procurement partnerships with state transport corporations bypass established dealer network barriers. For Investors and Strategic Acquirers: Thermal management engineering specialists with computational fluid dynamics capabilities for high-nickel liquid cooling optimization represent the priority acquisition archetype, as capability scarcity in this domain constrains pack architecture development timelines. Long-term viability assessment across the five-to-ten year horizon hinges on silicon carbide power electronics integration trajectories and solid-state ceramic electrolyte manufacturing scalability milestones. The signal to watch is 800-volt platform adoption velocity among premium Korean and Chinese OEMs, indicating infrastructure readiness for ultra-fast charging deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Capacity Expansion | Backward-integrated facilities in Jiangsu and Guangdong compress manufacturing cost structures while redistributing technical risk. |
| Silicon Carbide Power Electronics Integration | 800-volt architectures with SiC inverters enable ultra-fast charging infrastructure deployment across Korean highway corridors. |
| GB 38031 Certification Investment | MIIT-mandated thermal runaway containment and blockchain traceability secure Chinese OEM procurement qualification. |
| Second-Life Stationary Storage Partnerships | Retired automotive cells extend value capture beyond initial vehicle lifecycle through grid-scale energy storage applications. |
| Direct Fleet Procurement Agreements | Holding-company level negotiations with Australian mining operators bypass dealer networks and guarantee residual value. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with battery pack engineering directors, OEM platform procurement managers, thermal management specialists, and state transport authority fleet planners; alongside secondary validation from MIIT regulatory filings, BIS technical regulation drafts, customs trade databases, and IHS Markit vehicle production records. Bottom-up triangulation across cell-to-pack facility capacity announcements and top-down demand modeling from OEM electrification roadmaps anchored volume estimates.
Forecast inputs spanning vehicle class, propulsion architecture, chemistry configuration, and regional production cluster were modeled across the projection horizon. CAGRs were derived from segmented growth trajectory analysis incorporating PLI scheme incentive phase-out schedules and local content requirement implementation timelines. Silicon carbide adoption curves and solid-state commercialization milestones from METI-coordinated industry consortia informed technology transition assumptions.
Stress conditions across lithium price volatility bands, separator membrane supply disruption scenarios, and GB standard certification timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding subsidy phase-out schedules and regional trade policy configurations. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
EV Battery Water Cold Plates Market
EV Batteries
Cold-Climate Optimized EV Battery Systems Market
EV Batteries
Germany Electric Vehicle Battery Manufacturing Market
EV Batteries
Asia-Pacific Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Cobalt Powder for EV Battery Market
EV Batteries
China Electric Vehicle Battery Materials Market
EV Batteries
EV Battery Cell and Pack Materials Market
EV Batteries
Middle-East Electric Vehicle Battery Market
EV Batteries
Middle-East and Africa Electric Vehicle Battery Anode Market
EV Batteries
France EV Battery Pack Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Materials Market
EV Batteries
India EV Battery Pack Market
EV Batteries
Europe Electric Vehicle Battery Electrolyte Market
EV Batteries
Electric Vehicle Battery Market
EV Batteries
Canada Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Europe Electric Vehicle VRLA Batteries Market