
 South Africa Container Glass Market | 2026-2036
South Africa Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Container Glass Market Insights
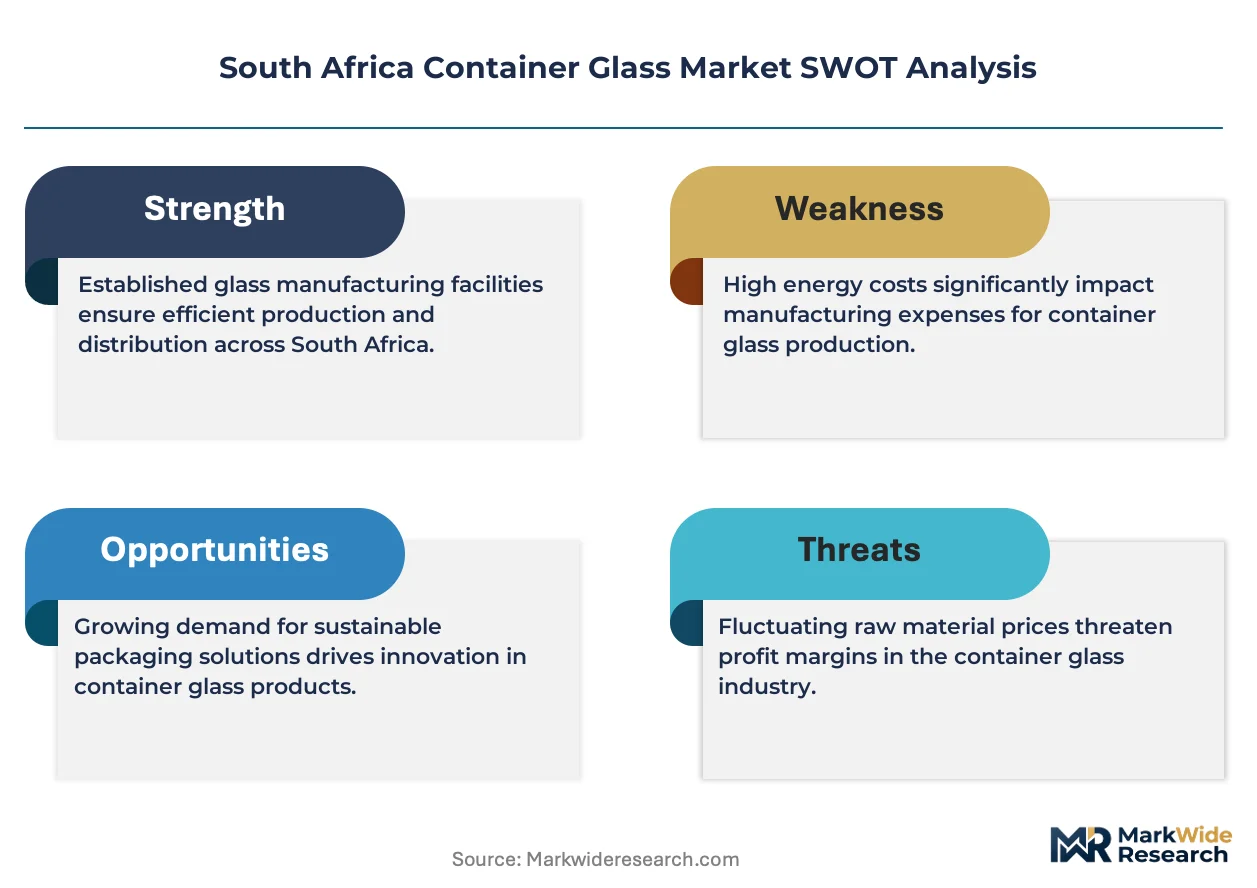
Extended Producer Responsibility regulations is hardening the cost-of-entry calculus for new container glass suppliers in South Africa. Consol Glass leverages backward integration into raw material sourcing to sustain margin resilience against compliance burdens. Ardagh Glass Packaging Holdings Africa anchors its position through manufacturing scale across multiple production facilities. Isanti Glass differentiates via specialized pharmaceutical-grade container output that commands premium positioning.
Container glass comprises silica sand, soda ash, limestone, and cullet melted at temperatures exceeding 1,500°C to form rigid, chemically inert vessels for liquid and solid storage. The material offers impermeability, UV protection, and infinite recyclability without quality degradation, making it indispensable for sensitive product categories. Bottles dominate volume throughput in the Food & Beverages end-use channel, where returnable systems still capture significant share against single-use alternatives. Amber-colored glass commands specialized margin pools in the Pharmaceuticals segment due to its light-blocking properties that protect photosensitive formulations.
South Africa's National Regulator for Compulsory Specifications enforces dimensional and thermal-shock standards, while Department of Forestry, Fisheries and the Environment oversees EPR implementation timelines. BIS-aligned import testing protocols further condition market access for foreign suppliers. Stakeholders must monitor regulatory enforcement intensity and cullet recovery rates as decisive variables for capacity planning and investment timing.
Market Dynamics
Extended Producer Responsibility compliance is compressing margin structures for South African container glass producers while simultaneously erecting barriers against import competition. The Department of Forestry, Fisheries and the Environment mandates escalating cullet recovery targets that reshape capital allocation priorities across the value chain.
Growth Catalysts
- Alcoholic Beverages Premiumization:Spirits and craft beer producers are upgrading packaging specifications to differentiate shelf presence, driving demand for heavier base weights and specialized surface finishes.
- EPR-Driven Localization:South Africa's Extended Producer Responsibility regulations incentivize domestic manufacturing over imports by assigning compliance liability to local entities with established collection infrastructure.
- Pharmaceutical Light-Protection Mandates:Photosensitive drug formulations are expanding amber glass requirements as CDSCO-aligned standards penetrate the domestic generics sector.
Market Restraints
- Soda Ash Import Dependency:South Africa lacks domestic natural soda ash deposits, exposing converters to freight cost volatility and currency fluctuation risks on bulk chemical imports.
- Gauteng Production Concentration:Over 70% of national melting capacity sits within a 150-kilometer radius of Johannesburg, creating systemic vulnerability to regional power grid instability.
- Aluminum Can Substitution:Beverage brands are piloting lightweight metal alternatives for single-serve formats where returnable glass economics prove uncompetitive in informal retail channels.
Strategic Opportunities
- Western Cape Wine Export Packaging:Stellenbosch and Paarl producers are expanding cold-chain-compatible bottle formats for premium export markets requiring enhanced thermal shock resistance.
- Lightweighting Technology Convergence:Thin-wall forming combined with surface coating chemistries enables material reduction without sacrificing mechanical performance.
- Direct-to-Contractor Distribution:Bypassing traditional merchant intermediaries to supply craft distilleries and microbreweries through dedicated logistics partnerships.
Industry Challenges
- Furnace Rebuild Capital Intensity:Refractory replacement cycles demand 18-24 month planning horizons and foreign currency exposure for specialized European equipment procurement.
- Cullet Quality Standardization:Inconsistent post-consumer glass sorting yields contamination rates that disrupt furnace chemistry and increase defect rates in pharmaceutical-grade output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Container Glass Market |
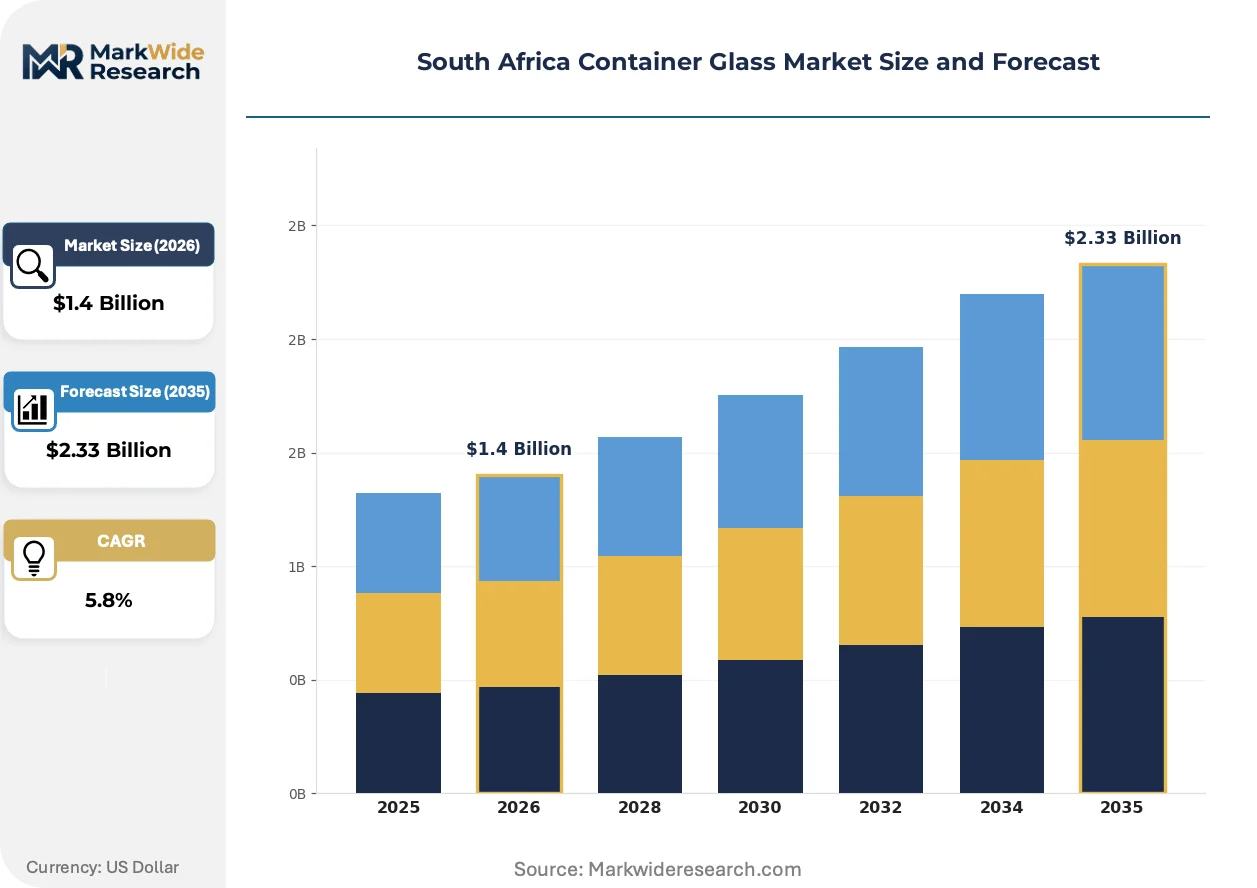
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Vials, Jugs End Use Industry: Food & Beverages, Pharmaceuticals, Cosmetics, Personal Care Shape: Round, Square, Rectangular, Custom Color: Clear, Green, Amber, Frosted |
| Companies Covered | Ardagh Glass Packaging Holdings Africa, Isanti Glass, Consol Glass, Nampak Glass, O-I Glass, Schott AG, Glassto, Glasspak, SGD S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Container Glass Market Trends and Innovations
Electrification of melting processes and digital quality control systems are reshaping competitive differentiation in South African container glass manufacturing. These shifts intersect with regulatory pressure and buyer specification evolution to redefine operational excellence benchmarks.
Hybrid oxy-fuel furnace technology is modularizing production line configurations across Consol Glass and Ardagh facilities. Mid-scale producers are adopting skid-mounted oxygen generation units to reduce NOx emissions without full regenerative rebuild investments. This modularizing approach allows phased capex deployment aligned with EPR compliance timelines rather than single-point furnace commitments.
South Africa's National Regulator for Compulsory Specifications is tightening thermal-shock testing protocols for food-contact glassware. The revised standards mandate expanded temperature differential testing that eliminates marginal suppliers lacking laboratory certification capabilities. Pharmaceutical and infant nutrition segments are absorbing compliance costs fastest, passing specifications upstream to converters with captive testing infrastructure.
Returnable bottle pooling systems are regaining share against single-use alternatives in informal retail channels. Township taverns and spaza shops are reactivating deposit-refund mechanics abandoned during pandemic disruptions, supported by brewer-sponsored logistics networks. This reversal concentrates procurement influence with beverage manufacturers operating captive washing and inspection facilities rather than independent packaging distributors.
South Africa Container Glass Market Segmentation
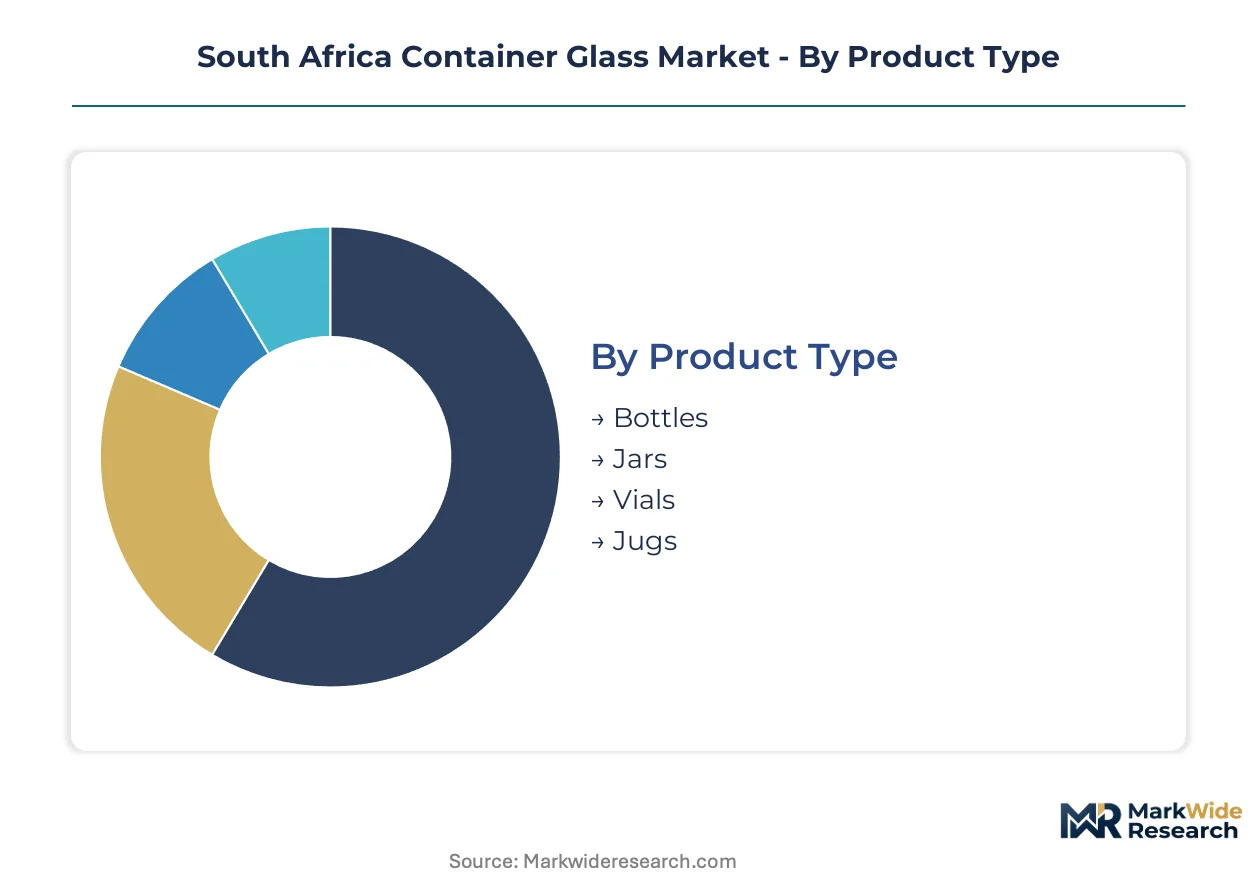
Container glass segmentation in South Africa reflects divergent technical requirements across beverage, pharmaceutical, and cosmetic channels. Procurement specifications vary sharply between returnable beer bottles and single-use pharmaceutical vials, driving specialized furnace configurations and color chemistry investments.
Product Type:
Standalone packaging formats dominate volume throughput, while embedded systems such as dropper assemblies and pump mechanisms command specialized tooling investments.
- Bottles:Formed through blow-and-blow or press-and-blow processes with neck finish precision critical for crown cork and screw cap compatibility. Demand concentrates in Gauteng's beverage manufacturing corridor, where returnable beer bottle pooling systems require heavier base weights and reinforced heel designs to withstand 30+ wash cycles.
- Jars:Wide-mouth containers with continuous thread or lug finishes, typically produced via press-and-blow forming for dimensional stability. Food processors in the Western Cape are expanding procurement of thermal-shock-resistant jars for pasteurized preserve applications, driven by export market compliance with EU food contact regulations.
- Vials:Small-volume pharmaceutical containers with tight dimensional tolerances for rubber stopper and aluminum seal integration.
- Jugs:Large-format vessels with handle attachments, primarily serving bulk food service and industrial chemical applications.
Volume placements concentrate in Bottles; the faster expansion belongs to Vials.
End Use Industry:
Cost tier stratification separates commodity beverage contracts from premium pharmaceutical and cosmetic specifications that absorb compliance overhead.
- Food & Beverages:Encompasses carbonated soft drinks, beer, wine, spirits, and processed foods requiring oxygen barrier properties and UV protection. Alcoholic beverage premiumization in Stellenbosch and Paarl is driving specification upgrades toward heavier base weights and specialized surface treatments that differentiate shelf presence in export markets.
- Pharmaceuticals:Demands Type I borosilicate or Type III soda-lime glass with chemical durability certification for parenteral and oral dosage forms. CDSCO-aligned standards penetrating South Africa's generics sector are expanding amber glass requirements for photosensitive drug formulations, concentrating procurement with converters holding captive laboratory testing infrastructure.
- Cosmetics:Fragrance and skincare packaging emphasizing aesthetic differentiation through color chemistry and surface decoration.
- Personal Care:Hair care and hygiene products requiring chemical compatibility with surfactant formulations.
Food & Beverages captures the dominant volume position; Pharmaceuticals is climbing the fastest on regulatory tailwinds.
Shape:
Application-specific geometry requirements determine forming complexity and mold capital allocation across production facilities.
- Round:Axially symmetric forms optimized for uniform wall thickness distribution and minimal stress concentration. Wine exporters in the Western Cape are expanding procurement of round bottles with enhanced shoulder profiles for cold-chain compatibility in premium export markets.
- Square:Rectilinear forms maximizing palletization efficiency and shelf space utilization. Spirits producers favor square profiles for premium positioning, accepting higher forming defect rates and reinforced corner designs that increase material consumption.
- Rectangular:Elongated flat profiles common in food jar applications.
- Custom:Proprietary geometries requiring dedicated mold investments and extended qualification timelines.
Round shapes hold the volume anchor; Custom geometries are gaining share fastest among craft distilleries seeking differentiation.
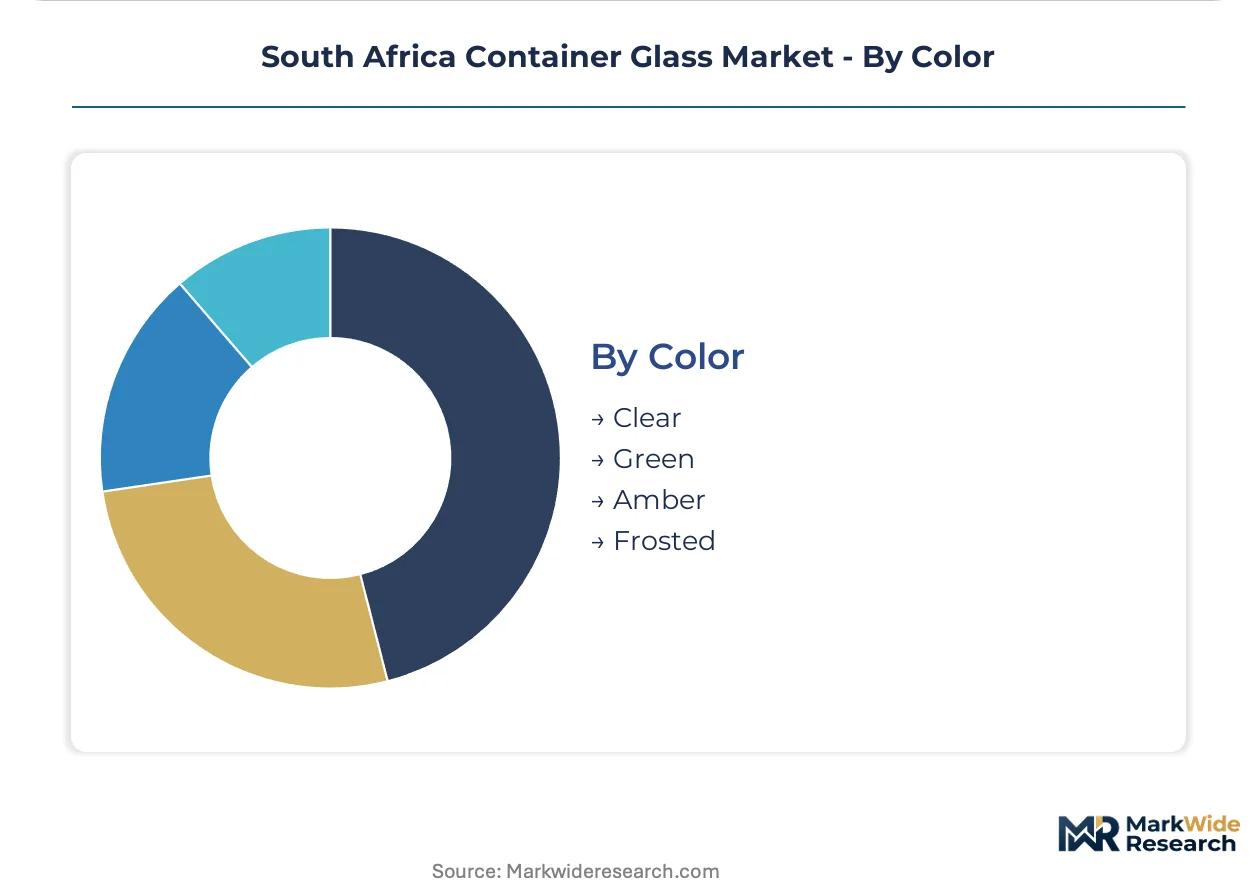
Color:
Margin tiering separates commodity clear glass from specialized color chemistry commanding premium positioning.
- Clear:Unpigmented soda-lime glass offering maximum product visibility and UV transmission. Beverage manufacturers in Gauteng specify clear glass for premium spirits and mixers where color clarity drives consumer preference, though this exposes contents to photochemical degradation risks.
- Amber:Iron-sulfur color chemistry absorbing wavelengths below 450nm to protect photosensitive formulations. Pharmaceutical light-protection mandates from South Africa's national pharmaceutical regulator are expanding amber glass procurement faster than other color segments, with converters investing in dedicated furnace campaigns to manage color transition costs.
- Green:Chromium or iron-based coloration common in wine and beer applications.
- Frosted:Acid-etched or molded surface treatments for cosmetic premium positioning.
Clear glass dominates volume placements; Amber is expanding most quickly on pharmaceutical compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for container glass in South Africa concentrates heavily in Gauteng province, where beverage manufacturing clusters anchor procurement volumes, while Western Cape wine exporters and KwaZulu-Natal pharmaceutical processors drive specialized specification requirements.
Gauteng
Johannesburg and Pretoria host over 70% of national melting capacity within a 150-kilometer radius, creating systemic exposure to regional power grid instability. The Department of Forestry, Fisheries and the Environment enforces escalating cullet recovery targets that reshape capital allocation for converters operating in this corridor. Consol Glass maintains multiple production facilities across the province, leveraging backward integration into raw material sourcing to sustain margin resilience against compliance burdens.
Western Cape
Stellenbosch and Paarl wine producers are expanding cold-chain-compatible bottle formats for premium export markets requiring enhanced thermal shock resistance. South Africa's National Regulator for Compulsory Specifications tightened thermal-shock testing protocols that eliminate marginal suppliers lacking laboratory certification capabilities. Cape Town-based converters are investing in dedicated furnace campaigns to manage color transition costs for amber and green glass specifications demanded by export-oriented wineries.
KwaZulu-Natal
Durban pharmaceutical manufacturers are absorbing compliance costs fastest as CDSCO-aligned standards penetrate the domestic generics sector, expanding amber glass requirements for photosensitive drug formulations. The country's national pharmaceutical regulator mandates expanded temperature differential testing that concentrates procurement with converters holding captive testing infrastructure. Isanti Glass anchors specialized pharmaceutical-grade container output from this region, commanding premium positioning through dedicated quality infrastructure.
Eastern Cape
Port Elizabeth industrial zones support secondary processing and distribution logistics for container glass moving into African export markets. BIS-aligned import testing protocols condition market access for foreign suppliers, favoring domestic entities with established collection infrastructure under Extended Producer Responsibility frameworks. Local distributors are reactivating deposit-refund mechanics for returnable bottle pooling systems in township retail channels abandoned during pandemic disruptions.
South Africa Container Glass Market Competitive Landscape
Gauteng-based producers anchor one tier; Western Cape specialists hold differentiated positions in export-oriented wine packaging. The market structure reflects moderate consolidation around three dominant melting operations, with mid-scale converters occupying niche pharmaceutical and cosmetic segments. Strategic archetypes separate backward-integrated raw material controllers, multi-facility scale operators, and specialized pharmaceutical-grade specialists. Competitive moves center on furnace rebuild timing aligned with EPR compliance deadlines and lightweighting technology licensing partnerships.
Among scale-driven operators, Consol Glass and Ardagh Glass Packaging Holdings Africa exemplify the multi-facility manufacturing archetype, while Isanti Glass occupies a specialized position within pharmaceutical-grade output tiers. These three entities represent the dominant competitive anchors, with Consol leveraging captive supply of silica sand and soda ash procurement channels, Ardagh deploying modular oxy-fuel furnace technology across distributed production sites, and Isanti commanding premium positioning through laboratory certification capabilities that satisfy tightening national regulatory standards for light-protective container specifications.
| Leading Market Players |
|---|
| Ardagh Glass Packaging Holdings Africa |
| Isanti Glass |
| Consol Glass |
| Nampak Glass |
| O-I Glass |
| Schott AG |
| Glassto |
| Glasspak |
| SGD S.A. |
| Others |
Pricing and Supply Chain Analysis
Soda ash import price indices cascading from United States Natural Soda Ash Corporation benchmarks transmit directly into South African container glass pricing tiers. The absence of domestic alkali deposits forces converters to absorb freight cost volatility and currency fluctuation exposure, compressing margin structures for standard-grade clear glass while pharmaceutical-grade amber commands defensive premium positioning.
Pricing Analysis
Volume placements concentrate in returnable beer bottles at compressed margins, while pharmaceutical vials and export wine formats capture premium tiers. Three-tier pricing structure across premium, standard, and economy levels separates certified laboratory-tested output from commodity beverage contracts and informal channel generics. Pricing pressure stems from Extended Producer Responsibility compliance cost absorption without full pass-through to beverage manufacturers. Informal retail channels exhibit highest price sensitivity, whereas pharmaceutical processors absorb specification premiums fastest.
Supply Chain Analysis
Skilled furnace operations personnel availability constrains expansion in Gauteng's 150-kilometer production radius around Johannesburg. Raw material sourcing draws from Namibian silica sand deposits, United States soda ash bulk shipments, and domestic limestone quarries. Single-source vulnerability concentrates in soda ash import channels exposed to Red Sea logistics disruptions. Distribution runs through beverage manufacturer captive logistics networks for returnable systems, with independent merchant channels serving fragmented cosmetic and pharmaceutical processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's container glass market represents a consolidation play as Extended Producer Responsibility compliance burdens force sub-scale converters toward exit. Furnace rebuild capital intensity and cullet recovery infrastructure requirements favor incumbent scale operators over marginal entrants.
For Market Incumbents: Deepen backward integration into silica sand quarrying and soda ash procurement channels to defend margin resilience against import cost volatility. Prioritize captive laboratory certification investments ahead of National Regulator for Compulsory Specifications thermal-shock testing protocol tightening. Aluminum can substitution in single-serve beverage formats demands accelerated lightweighting technology licensing to preserve share. For New Entrants and Emerging Players: Begin with specialized pharmaceutical-grade vial production targeting KwaZulu-Natal generics manufacturers absorbing CDSCO-aligned light-protection mandates. Western Cape wine export packaging offers penetrable white space for cold-chain-compatible thermal shock resistant formats. Direct-to-contractor distribution partnerships with Stellenbosch and Paarl craft distilleries bypass entrenched Gauteng merchant intermediaries. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale converters with captive cullet recovery infrastructure in Gauteng province. Long-term viability hinges on furnace rebuild timing alignment with Department of Forestry, Fisheries and the Environment compliance deadlines rather than commodity glass volume exposure. Monitor National Regulator for Compulsory Specifications enforcement intensity as inflection indicator for laboratory-capable asset premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Electrification Investment | Hybrid oxy-fuel technology reduces NOx emissions ahead of Department of Forestry, Fisheries and the Environment deadlines. |
| Backward Integration into Silica Sand | Namibian quarry control insulates Consol Glass against raw material cost volatility from freight rate spikes. |
| Pharmaceutical Laboratory Certification | Captive testing infrastructure satisfies National Regulator for Compulsory Specifications thermal-shock protocol tightening. |
| Returnable Bottle Pooling Expansion | Brewer-sponsored logistics networks in township channels displace single-use alternatives abandoned during pandemic. |
| Lightweighting Technology Licensing | Thin-wall forming with surface coating chemistries defends against aluminum can substitution in premium spirits. |
Research Methodology
Multi-period observation of cullet recovery rates, furnace utilization metrics, and import soda ash price spreads anchored the trend analysis, supplemented by interviews with plant operations managers at Gauteng melting facilities, procurement leads at Stellenbosch wine estates, pharmaceutical quality directors in Durban, and distribution channel partners in Eastern Cape township retail networks. Secondary validation drew from South African Revenue Service customs records, Department of Forestry, Fisheries and the Environment regulatory filings, National Regulator for Compulsory Specifications testing protocols, and industry association production statistics. Bottom-up volume modeling triangulated against top-down value estimates across product type, end-use industry, and color chemistry segments.
Segment-weighting approaches assigned differential growth coefficients to pharmaceutical-grade amber glass versus commodity beverage clear glass based on regulatory compliance intensity. The analytical framework modeled product type, end-use channel, color specification, and regional production hub dimensions across the analysis window. CAGRs were derived from exponential curve fitting to historical shipment data adjusted for furnace rebuild cycle interruptions. Forecast inputs incorporated Extended Producer Responsibility cullet recovery target trajectories and National Regulator for Compulsory Specifications protocol adoption timelines.
Regulatory enforcement intensity shifts, furnace rebuild capital commitment delays, and soda ash import logistics disruptions are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding Department of Forestry, Fisheries and the Environment timeline adherence and power grid stability in Gauteng production corridors. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Glass Jugs Market
Glass Packaging
Bulgaria Container Glass Market
Glass Packaging
Slovakia Container Glass Market
Glass Packaging
Glass Liquor Bottles Market
Glass Packaging
France Glass Packaging Market
Glass Packaging
Uruguay Container Glass Market
Glass Packaging
Saudi Arabia Glass Packaging Market
Glass Packaging
Europe Cosmetic and Perfumery Glass Bottle Packaging Market
Glass Packaging
United Kingdom (UK) Glass Bottles and Containers Market
Glass Packaging
Poland Container Glass Market
Glass Packaging
Nigeria Container Glass Market
Glass Packaging
United Kingdom Glass Packaging Market
Glass Packaging
South Korea Container Glass Market
Glass Packaging
Ethiopia Container Glass Market
Glass Packaging
Middle East and Africa Pharmaceutical Glass Packaging Market
Glass Packaging
Amber Glass Packaging Market