
 Glass Frosting for Packaging Market | 2026-2036
Glass Frosting for Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Frosting for Packaging Market Insights
Subscription-based surface-treatment services for cosmetic packaging is consolidating procurement decisions at major beauty houses. Verescence leverages its French manufacturing heritage to anchor premium fragrance contracts across Europe. Heinz-Glas sustains specialized UV-coated frosting capacity for pharmaceutical vial applications. SGD Pharma competes through dedicated acid-etching lines serving personal care multinationals.
Glass frosting for packaging denotes controlled surface roughening of soda-lime or borosilicate containers through acid etching, mechanical abrasion, or polymer coating, producing light-diffusing finishes with Ra values typically between 0.5 and 5.0 micrometers. The process serves primarily to elevate perceived product value, improve grip ergonomics, and enable label adhesion without visual competition from reflective substrates. Acid-etched finishes dominate luxury fragrance applications where depth and uniformity command price premiums, while spray-coated variants grow fastest in food containers due to lower capital requirements and faster batch turnaround. Electrochemical frosting occupies a narrow but high-margin niche in pharmaceutical vials, where process repeatability satisfies FDA validation protocols.
REACH registration requirements in Europe constrain hydrofluoric acid formulations, while EPA OSHA permissible exposure limits shape etchant handling protocols in United States facilities. FDA cGMP standards for pharmaceutical packaging impose surface-integrity testing that favors validated electrochemical over manual sandblasting methods. Stakeholders must monitor evolving chemical substitution mandates and validate alternative etchant chemistries before regulatory deadlines compress formulation windows.
Market Dynamics
REACH registration requirements for hydrofluoric acid formulations are compressing etchant supply windows across European glassworks, forcing rapid validation of alternative chemistries before 2027 substitution deadlines.
Growth Catalysts
- Matte-finish premiumization:Cosmetic houses in France and Germany are expanding acid-etched glass programs for luxury fragrance lines, where tactile depth commands price premiums over spray-coated alternatives.
- REACH substitution mandates:The European Chemicals Agency's tightening hydrofluoric acid restrictions are accelerating investment in validated alternative etchants, creating first-mover advantages for compliant suppliers.
- Pharmaceutical validation protocols:FDA cGMP surface-integrity requirements for borosilicate vials are pulling demand toward electrochemical frosting methods with documented batch repeatability.
Market Restraints
- Etchant input cost volatility:Fluorochemical supply concentration in Chinese manufacturing clusters exposes European processors to tariff and shipping cost swings.
- Capital intensity barrier:Electrochemical frosting lines require validated cleanroom infrastructure that excludes mid-cap cosmetic packagers from pharmaceutical-grade contracts.
- Substitution threat from polymer coatings:UV-cured matte coatings on PET and rPET containers are capturing mid-market skincare share where glass weight poses logistics penalties.
Strategic Opportunities
- Underpenetrated Indian cosmetic packaging:Domestic fragrance houses in Mumbai and Delhi are importing finished frosted glass at premium markups, creating localization incentives under PLI scheme offsets.
- Regulatory tailwind from EU Green Deal:Packaging and Packaging Waste Regulation recycled-content mandates favor infinitely recyclable glass over coated plastics in premium personal care.
- Technology convergence:Integration of laser surface texturing with traditional acid etching is enabling programmable pattern variation for limited-edition cosmetic releases.
Industry Challenges
- Etchant chemistry skill gap:Formulation chemists with hydrofluoric acid handling expertise are retiring faster than REACH-compliant replacement training programs can replenish.
- Validation timeline compression:FDA process validation for pharmaceutical frosting lines now extends 18-24 months, locking working capital during qualification periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Frosting for Packaging Market |
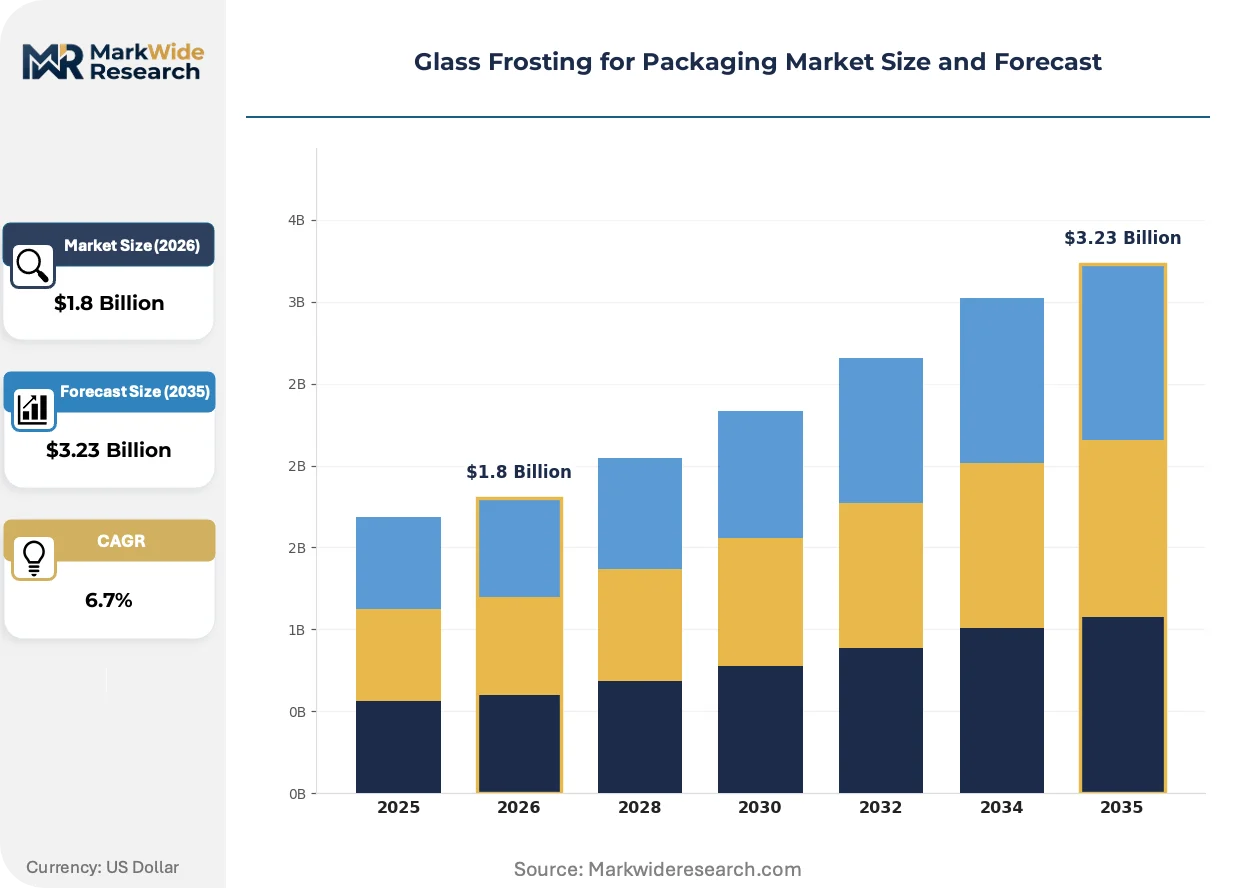
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acid Etched, Sandblasted, Spray Coated, UV Coated, Electrochemical Application: Food Containers, Cosmetic Bottles, Beverage Packaging, Pharmaceutical Vials, Luxury Packaging Packaging Type: Glass Jars, Glass Bottles, Tubes, Vials, Ampoules End User Industry: Personal Care, Food & Beverage Manufacturers, Pharma Labs, Specialty Chemicals, Fragrance Producers |
| Companies Covered | Verescence, Heinz-Glas, Pochet du Courval, SGD Pharma, Berlin Packaging, Piramal Glass, Bormioli Luigi, Stoelzle Glass Group, Saverglass, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Frosting for Packaging Market Trends and Innovations
Laser-assisted surface texturing is displacing manual sandblasting in high-mix cosmetic production, compressing changeover times from hours to minutes while preserving acid-etched optical depth.
Closed-loop acid-recovery systems are automating etchant neutralization and metal salt extraction in European glassworks, reducing hazardous waste volumes by half. SGD Pharma and Verescence have deployed these systems at French and German facilities respectively. The technology is automating compliance cost structures that previously required manual monitoring and third-party disposal contracts.
REACH Annex XIV authorization requirements for hydrofluoric acid are forcing reformulation toward ammonium bifluoride and fluoride salt alternatives with comparable etch rates. German processors face the steepest compliance cliff with 2026 sunset dates. Pharmaceutical vial manufacturers are responding by accelerating electrochemical process validation to bypass etchant chemistry exposure entirely.
Beauty houses are consolidating surface-treatment procurement under subscription-based service contracts that bundle frosting, coating, and logistics. L'Oréal and Estée Lauder have shifted fragrance glass sourcing to multi-year agreements with guaranteed capacity blocks. This restructuring is most advanced in France, where heritage glassworks clusters offer integrated design-to-delivery capabilities that standalone coaters cannot replicate.
Glass Frosting for Packaging Market Segmentation
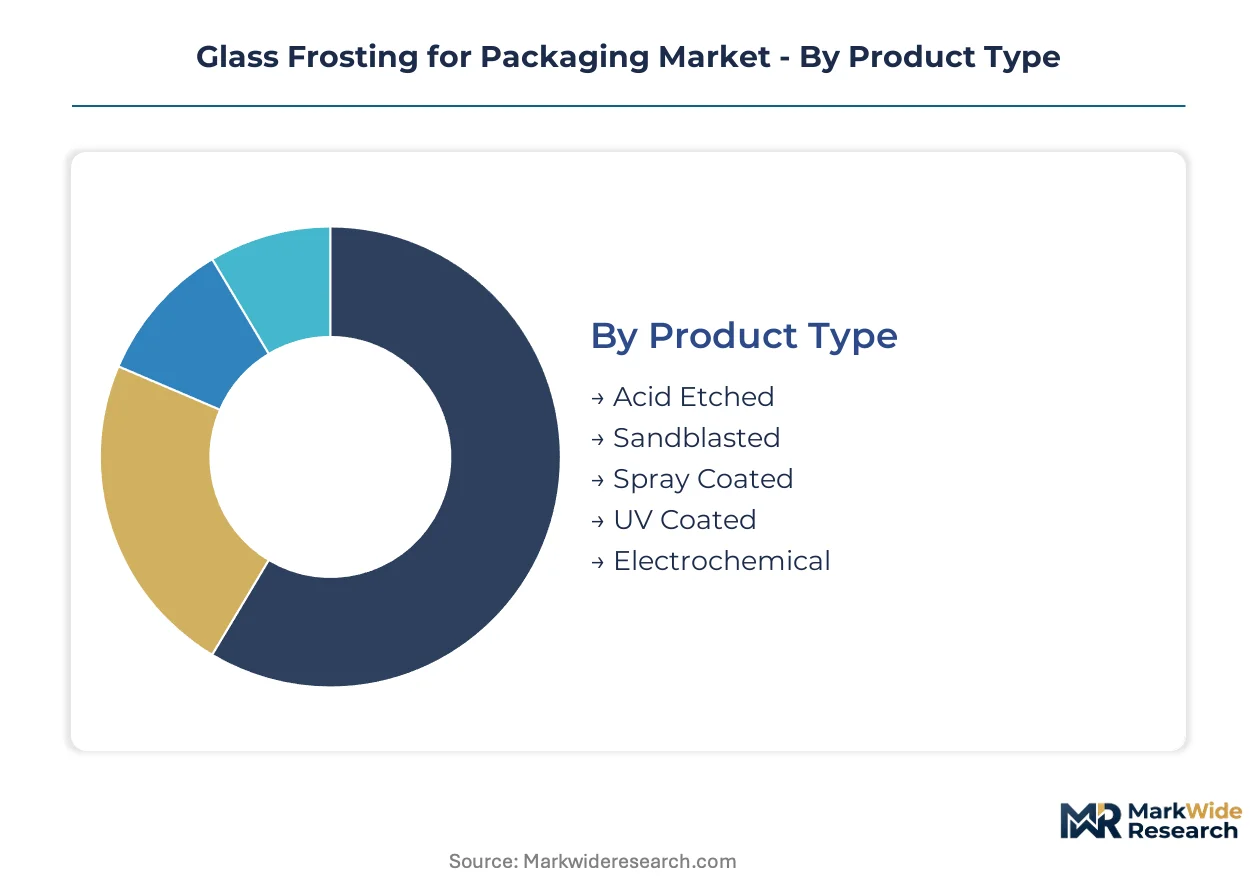
Glass frosting technologies serve distinct performance tiers across packaging applications, with upgrade cycles driven by regulatory compliance mandates and cosmetic brand premiumization programs. Material substitution pressures and validation protocol evolution reshape procurement patterns within each segment cluster.
Product Type:
Upgrade cycles in glass frosting equipment accelerate where REACH deadlines force chemistry transitions and where FDA validation requirements favor documented process repeatability.
- Acid Etched:Hydrofluoric acid formulations create uniform surface roughness with Ra values between 0.5 and 5.0 micrometers. Demand concentrates in French and German heritage glassworks supplying luxury fragrance houses, where tactile depth commands price premiums over spray alternatives. REACH Annex XIV authorization deadlines are forcing rapid validation of ammonium bifluoride substitutes.
- Electrochemical:Ion-exchange surface modification delivers batch-to-batch consistency without hazardous etchant handling. Pharmaceutical vial manufacturers in the United States are accelerating adoption to satisfy FDA cGMP surface-integrity testing requirements, bypassing etchant chemistry exposure entirely.
- Sandblasted:Mechanical abrasion with aluminum oxide or silicon carbide media suits low-volume cosmetic prototyping.
- Spray Coated:UV-cured polymer matte finishes offer lower capital requirements for food container applications.
- UV Coated:Cured resin systems provide scratch-resistant frosting for beverage packaging with faster batch turnaround.
Volume placements concentrate in Acid Etched; the faster expansion belongs to Electrochemical.
Application:
Application demand splits across cost tiers, with premium cosmetic and pharmaceutical segments absorbing higher unit costs for validated processes while food and beverage buyers prioritize throughput economics.
- Cosmetic Bottles:Acid-etched soda-lime glass dominates premium skincare and fragrance, where matte finishes differentiate shelf presence. L'Oréal and Estée Lauder have consolidated procurement under multi-year service contracts with guaranteed capacity blocks from French glassworks clusters.
- Pharmaceutical Vials:Borosilicate containers require electrochemical frosting to meet FDA validation protocols for surface integrity and batch repeatability. Process qualification timelines now extend 18-24 months, locking working capital during validation periods.
- Food Containers:Spray-coated variants capture share where glass weight poses logistics penalties against polymer alternatives.
- Beverage Packaging:UV-cured coatings serve mid-market spirits brands seeking premium aesthetics without acid-etching infrastructure.
- Luxury Packaging:Limited-edition releases integrate laser surface texturing with traditional etching for programmable pattern variation.
Cosmetic Bottles anchor current revenue; Pharmaceutical Vials are climbing the fastest on regulatory tailwinds.
Packaging Type:
Packaging geometry determines frosting method compatibility, with cylindrical forms favoring continuous electrochemical processing and irregular shapes requiring manual or robotic spray application.
- Glass Bottles:Standard cylindrical profiles accommodate continuous acid-etching lines and automated electrochemical baths. French and German manufacturers dominate supply for fragrance and premium spirits, with heritage clusters offering integrated design-to-delivery capabilities.
- Vials:Small-diameter borosilicate containers for injectable pharmaceuticals require validated electrochemical frosting with documented surface-roughness consistency. FDA cGMP standards favor automated over manual methods.
- Glass Jars:Wide-mouth cosmetic and food containers suit spray-coated finishes with lower capital barriers.
- Tubes:Narrow cylindrical forms for specialty cosmetics accommodate selective frosting of label panels.
- Ampoules:Single-use pharmaceutical containers demand electrochemical processing to eliminate particulate contamination risks from mechanical methods.
Glass Bottles maintain the largest installed base; Vials show the steepest expansion trajectory on pharmaceutical validation requirements.
End User Industry:
End user procurement patterns diverge between consolidated beauty houses with subscription-based service contracts and fragmented food manufacturers with spot-market purchasing.
- Fragrance Producers:Heritage houses in France demand acid-etched glass with documented provenance from specific glassworks clusters. Verescence anchors premium contracts through integrated design, frosting, and logistics capabilities that standalone coaters cannot replicate.
- Pharma Labs:Injectable drug manufacturers require electrochemical frosting with FDA-validated batch records. SGD Pharma competes through dedicated acid-etching lines, though electrochemical adoption accelerates to bypass REACH compliance exposure.
- Personal Care:Skincare brands expand matte-finish programs across North American and European markets.
- Food & Beverage Manufacturers:Mid-market buyers favor spray-coated alternatives where logistics costs penalize glass weight.
- Specialty Chemicals:Niche producers source frosted glass for reagent packaging with chemical resistance requirements.
Fragrance Producers command the highest value per unit; Pharma Labs are gaining share fastest on regulatory compliance investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paris anchors the world's most concentrated glass frosting capacity, with heritage glassworks clusters in northern France supplying premium fragrance houses across Europe and North America.
France
Luxury fragrance producers in Paris and Normandy drive acid-etched glass demand for limited-edition releases. ECHA's REACH Annex XIV authorization requirements for hydrofluoric acid are forcing rapid reformulation toward ammonium bifluoride substitutes. The Arques glassworks cluster in Pas-de-Calais maintains integrated frosting, coating, and logistics capabilities that standalone processors cannot replicate.
Germany
Pharmaceutical vial manufacturers in Bavaria and Baden-Württemberg are accelerating electrochemical frosting adoption to bypass etchant chemistry exposure entirely. The 2026 sunset dates for hydrofluoric acid under REACH are compressing validation timelines for alternative chemistries. The Tettau glassmaking district in northern Bavaria specializes in borosilicate pharmaceutical containers with FDA-validated surface-integrity protocols.
United States
Cosmetic brands in New Jersey and California are expanding matte-finish glass programs for premium skincare lines. EPA OSHA permissible exposure limits shape etchant handling protocols at processing facilities in Pennsylvania and Ohio. The Ohio River Valley hosts specialized UV-coated frosting capacity serving pharmaceutical vial applications with documented batch repeatability.
India
Domestic fragrance houses in Mumbai and Delhi are importing finished frosted glass at premium markups, creating localization incentives under PLI scheme offsets. BIS standards for cosmetic packaging materials are tightening quality benchmarks for imported glass substitutes. The Bhiwandi industrial corridor outside Mumbai is emerging as a contract manufacturing hub for mid-market personal care brands seeking domestic frosting capacity.
China
Fluorochemical supply concentration in Jiangsu and Zhejiang provinces exposes European processors to tariff and shipping cost swings. MEE environmental compliance inspections are shuttering unlicensed etchant formulation facilities in the Yangtze River Delta. The Yantai glass manufacturing base in Shandong Province supplies acid-etched containers to Asian cosmetic brands with shorter lead times than European imports.
Glass Frosting for Packaging Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the glass frosting value chain, with integrated glassworks holding cost advantages in premium fragrance contracts while specialized coaters capture mid-market food container share. The vendor base splits between heritage European manufacturers with in-house acid-etching lines and Asian contract processors serving volume cosmetic brands. Three archetypes dominate: integrated design-to-delivery glassworks, standalone surface-treatment specialists, and pharmaceutical-grade validation leaders. Competitive moves concentrate on multi-year service contracts with guaranteed capacity blocks and closed-loop acid-recovery systems that automate compliance cost structures.
Within the integrated glassworks tier, Verescence and Heinz-Glas exemplify European heritage manufacturers with captive frosting capabilities, while SGD Pharma occupies a position among pharmaceutical-grade specialists with dedicated acid-etching lines. These three entities represent distinct competitive positions: Verescence anchors premium fragrance contracts through French manufacturing heritage, Heinz-Glas exemplifies specialized capacity for pharmaceutical vial applications, and SGD Pharma competes through validated process lines serving personal care multinationals. Each represents a strategic archetype rather than a fungible competitor, with customer relationships structured around multi-year agreements that bundle frosting, coating, and logistics.
| Leading Market Players |
|---|
| Verescence |
| Heinz-Glas |
| Pochet du Courval |
| SGD Pharma |
| Berlin Packaging |
| Piramal Glass |
| Bormioli Luigi |
| Stoelzle Glass Group |
| Saverglass |
| Others |
Pricing and Supply Chain Analysis
Captive acid-etching lines at French and German heritage glassworks anchor premium pricing power through integrated design-to-delivery capabilities that standalone coaters cannot replicate. REACH compliance costs and fluorochemical supply concentration in Chinese manufacturing clusters feed directly into margin structures across European processors.
Pricing Analysis
Margin tightening in pharmaceutical-grade electrochemical frosting reflects FDA validation timelines extending 18-24 months and locking working capital during qualification periods. Three-tier pricing structure across premium acid-etched fragrance glass, validated pharmaceutical vial finishes, and economy spray-coated food containers separates tiers by certification grade and process repeatability documentation. Cost-down pressure on mid-market cosmetic packaging accelerates as UV-cured polymer coatings on PET capture share where glass weight imposes logistics penalties. Fragrance producers demonstrate lowest price sensitivity due to heritage provenance requirements, while food container buyers prioritize throughput economics over tactile finish depth.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from consolidated beauty houses, while spot-market purchasing persists among fragmented food manufacturers. Fluorochemical supply concentrates in Jiangsu and Zhejiang provinces of China, with heritage glassworks clusters in northern France and Bavaria, Germany anchoring European finishing capacity. Raw material dependencies center on hydrofluoric acid formulations facing REACH substitution mandates, ammonium bifluoride alternatives, and borosilicate glass feedstock from specialized melt furnaces. Tariff exposure on Chinese fluorochemical imports presents structural risk to European etchant supply windows. Distribution runs through multi-year service contracts bundling frosting, coating, and logistics for premium cosmetic accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrochemical surface modification is displacing legacy acid-etching methods in pharmaceutical applications, creating a technology-transition window where validation capabilities determine competitive survival.
For Market Incumbents: To counter substitution threats from UV-cured polymer coatings on PET and rPET containers, accelerate closed-loop acid-recovery system deployment to automate compliance cost structures, and deepen captive electrochemical validation capacity for FDA cGMP pharmaceutical contracts before REACH hydrofluoric acid sunset deadlines compress formulation windows further.
For New Entrants and Emerging Players: Contract manufacturing partnerships with domestic fragrance houses in Mumbai and Delhi offer the most penetrable entry vector, leveraging PLI scheme offsets to localize currently imported frosted glass capacity and capture premium markups on finished goods.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated packaging conglomerates seeking European heritage glassworks capabilities. Long-term viability hinges on electrochemical process validation assets that bypass etchant chemistry exposure entirely. Watch for ECHA authorization timeline acceleration as the inflection signal for alternative chemistry investment urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Acid Recovery Deployment | Automates REACH compliance costs at French and German facilities, reducing hazardous waste volumes by half. |
| Electrochemical Process Validation | Enables FDA cGMP pharmaceutical contracts without hydrofluoric acid handling exposure or ECHA authorization risk. |
| Multi-Year Service Contract Structuring | Locks guaranteed capacity blocks with L'Oréal and Estée Lauder, replicating Verescence's integrated design-to-delivery model. |
| Laser Surface Texturing Integration | Compresses cosmetic production changeover times from hours to minutes while preserving acid-etched optical depth. |
| Indian Localization Partnership | Captures PLI scheme offsets for domestic frosting capacity serving Mumbai and Delhi fragrance houses. |
Research Methodology
Document review covered regulatory filings with ECHA and FDA, trade customs data, and glass industry association reports, complemented by interviews with plant managers at European heritage glassworks, procurement leads at cosmetic packaging multinationals, technical R&D directors for etchant formulation, and pharmaceutical quality assurance officers. Secondary validation drew from SEC filings of listed packaging companies, REACH Annex XIV authorization databases, and pharmaceutical validation protocol repositories. Bottom-up capacity modeling triangulated against top-down demand segmentation across cosmetic, pharmaceutical, and food container end uses.
Historical volume trajectories cross-referenced against expert panel input on REACH substitution timelines and FDA validation backlog estimates. Segmentation dimensions modeled include frosting technology type, application category, packaging geometry, and end-user industry procurement pattern. CAGRs were derived from regression analysis of installed capacity expansion plans and brand premiumization program announcements. Industry-specific forecast inputs incorporated ECHA authorization sunset schedules and PLI scheme offset qualification criteria for Indian manufacturing.
Several conditions sit outside the modeled scope, including unannounced MEE enforcement actions shuttering Chinese fluorochemical facilities, abrupt EPA OSHA permissible exposure limit revisions, and breakthrough polymer coating technologies achieving glass-equivalent tactile depth. Forecasts reflect base-case assumptions on regulatory timeline adherence and technology adoption curves. Periodic stress-testing of base assumptions is recommended against ECHA authorization acceleration signals and pharmaceutical validation backlog clearance rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Cosmetic and Perfume Glass Bottle Market
Glass Packaging
Retail Glass Packaging Market
Glass Packaging
Brazil Container Glass Market
Glass Packaging
Mexico Glass Packaging Market
Glass Packaging
Glass Decanters Market
Glass Packaging
United Arab Emirates Glass Packaging Market
Glass Packaging
Portugal Container Glass Market
Glass Packaging
North America Amber Glass Packaging Market
Glass Packaging
Sri Lanka Container Glass Market
Glass Packaging
Glass Bottles and Jars Decoration Market
Glass Packaging
Glass Bottles Market
Glass Packaging
Global Glass Bottles and Containers Market
Glass Packaging
Morocco Container Glass Market
Glass Packaging
Germany Glass Packaging Market
Glass Packaging
France Glass Packaging Market
Glass Packaging
Canada Glass Bottles and Containers Market