
 Ukraine Container Glass Market | 2026-2036
Ukraine Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Ukraine Container Glass Market Insights
Premium container glass is decoupling from commodity borosilicate and standard flint grades on both specification and pricing. Vetropak Hostomelʹsʹkyy Sklozavod anchors production through its integrated melting furnace complex north of Kyiv. Verallia Ukraine differentiates via pharmaceutical-grade vial certification that commands tighter dimensional tolerances. Malinovsky Glassworks dominates amber bottle supply for domestic spirits exporters.
Ukraine container glass denotes soda-lime silica vessels formed by blow-and-blow or press-and-blow processes, with wall thickness typically ranging from 2.5 to 6.0 mm depending on internal pressure requirements, serving as chemically inert primary packaging for liquids and solids. Bottles capture the dominant share of volume given entrenched beverage industry demand, while pharmaceutical vials generate disproportionate margin pools due to GMP compliance costs and customer stickiness. Jars within food packaging applications sustain steady offtake from preserved vegetable and honey processors seeking oxygen-barrier closures.
Ukraine's national technical regulator enforces DSTU standards harmonized with EU packaging directives, while the State Service of Ukraine on Food Safety and Consumer Protection inspects pharmaceutical glass contact compliance. These frameworks elevate entry barriers for uncertified imports and incentivize domestic furnace upgrades. Stakeholders must monitor furnace rebuild timelines and recycled cullet supply chains as determinants of cost competitiveness.
Market Dynamics
Ukraine's container glass sector is contending with furnace fuel-switching pressures as natural gas supply volatility forces producers toward hybrid electric-gas melting technologies, reshaping capital allocation and operational flexibility across western and central oblasts.
Growth Catalysts
- EU Packaging Waste Directive alignment:Ukraine's Association Agreement obligations mandate rising recycled-content thresholds, compelling domestic producers to upgrade cullet processing and secure premium pricing for certified sustainable output.
- Cross-border beverage logistics:Western oblasts bordering Poland and Slovakia are attracting export-oriented flint and amber bottle production to serve EU craft spirits and premium beer bottlers.
- Pharmaceutical packaging certification:GMP-compliant vial demand from domestic and regional drug manufacturers is pulling technical investment toward tighter dimensional tolerance capabilities.
Market Restraints
- Natural gas price volatility:Melting furnace operations remain exposed to Ukrainian energy market fluctuations, compressing margin predictability for soda-lime silica batch processing.
- Recycled cullet supply fragmentation:Collection infrastructure gaps across eastern oblasts limit feedstock availability for furnace operations seeking EU-mandated recycled content ratios.
- Flat glass substitution in food packaging:Polymer barrier films and metal cans are displacing traditional glass jars in preserved vegetable segments where oxygen sensitivity is secondary to cost.
Strategic Opportunities
- Lviv Oblast export corridor expansion:Proximity to Polish rail and road networks enables Ukrainian producers to capture EU beverage bottler procurement previously sourced from German and Czech suppliers.
- Lightweighting technology adoption:Thin-wall blow-and-blow process refinements are opening premium spirits segments where gram-weight reductions offset transport cost premiums.
- Pharmaceutical serialization integration:Track-and-trace compliance requirements for EU-bound drug exports create demand for laser-etched vial marking capabilities that command technical specification premiums.
Industry Challenges
- Refractory materials sourcing:Furnace rebuild cycles depend on Ukrainian importers securing zirconia-alumina-silica brick from limited European suppliers amid extended lead times.
- Color-switching furnace downtime:Amber-to-flint campaign changes require 10-14 day production halts, complicating just-in-time responsiveness for multi-SKU beverage customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ukraine Container Glass Market |
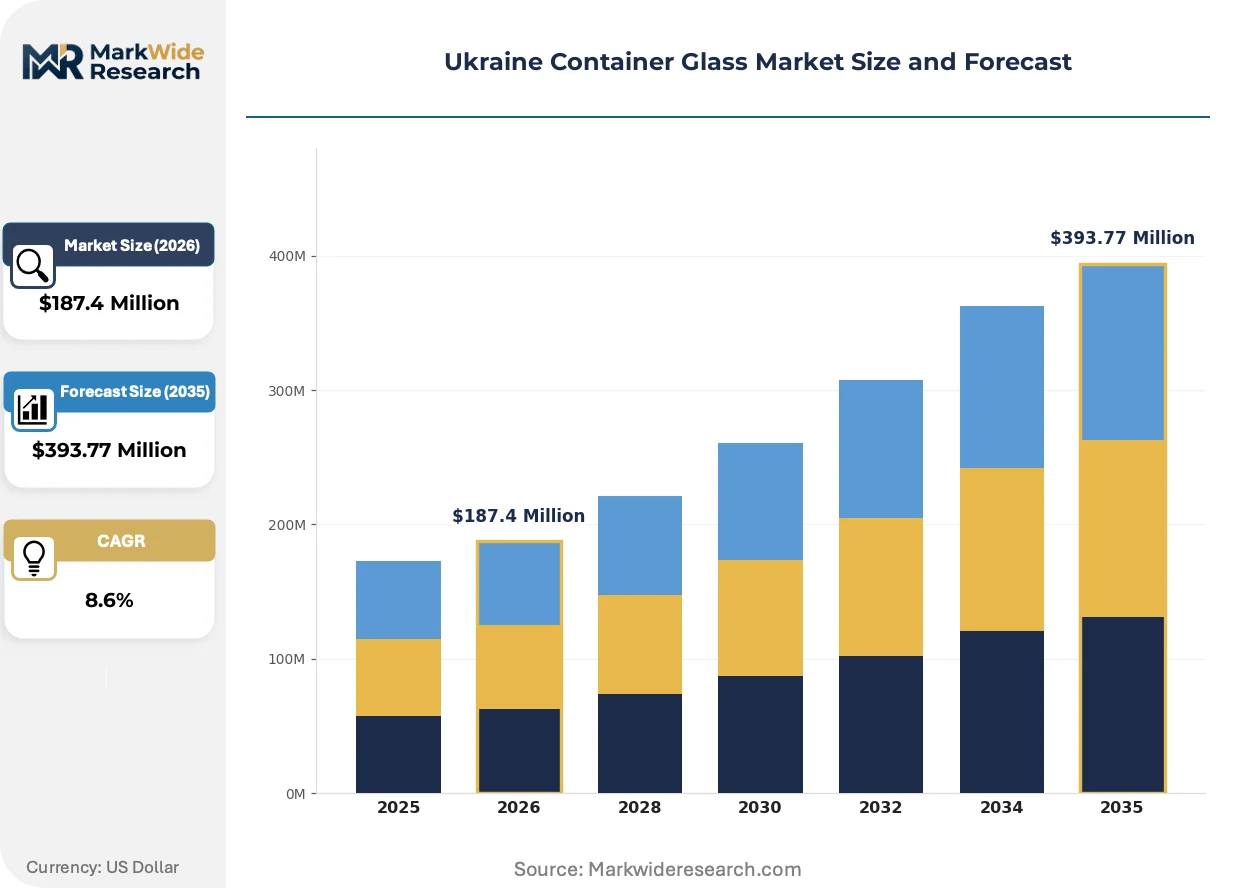
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Jugs, Vials Application: Food Packaging, Beverage Packaging, Pharmaceutical Packaging, Personal Care End User: Food Industry, Beverage Manufacturers, Healthcare Providers, Cosmetic Companies Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Vetropak Hostomelʹsʹkyy Sklozavod, Ilona PKP, Verallia Ukraine, Malinovsky Glassworks, Rokitnovskiy Glass Work, Orion Glass LLC, BIOMEDSKLO PJSC, Druzhkovka Glass Plant, Sklo Alliance LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ukraine Container Glass Market Trends and Innovations
Electrification of melting operations, regulatory harmonization with EU technical standards, and procurement consolidation among multinational beverage bottlers are reconfiguring competitive requirements across Ukrainian glass production clusters.
Oxy-fuel combustion retrofitting is consolidating as the dominant furnace upgrade pathway for Ukrainian producers seeking to reduce natural gas dependency while maintaining melting temperatures above 1500°C for soda-lime silica batches. Large-format beverage bottlers in the spirits sector are mandating these upgrades as qualification criteria for supplier accreditation. The technology is consolidating supplier tiers by excluding smaller furnaces lacking capital for electrode and burner system overhauls.
EU Packaging and Packaging Waste Regulation (PPWR) implementation through Ukraine's Association Agreement enforcement is mandating extended producer responsibility frameworks and recycled-content verification systems. Domestic regulators are aligning DSTU standards with EN 15343 traceability protocols, elevating compliance costs for uncertified imports. Pharmaceutical vial segments are responding fastest, with exporters pre-emptively adopting EU-wide serialization standards to maintain market access.
Consolidated procurement by multinational beverage groups is compressing supplier bases and extending contract durations in exchange for volume commitments and technical co-development. Ukrainian producers serving Polish and Slovak distribution hubs are encountering bundled sourcing requirements that favor integrated mold-design-to-delivery capabilities. This pattern is most pronounced in Lviv and Zakarpattia oblasts where cross-border logistics integration is deepest.
Ukraine Container Glass Market Segmentation
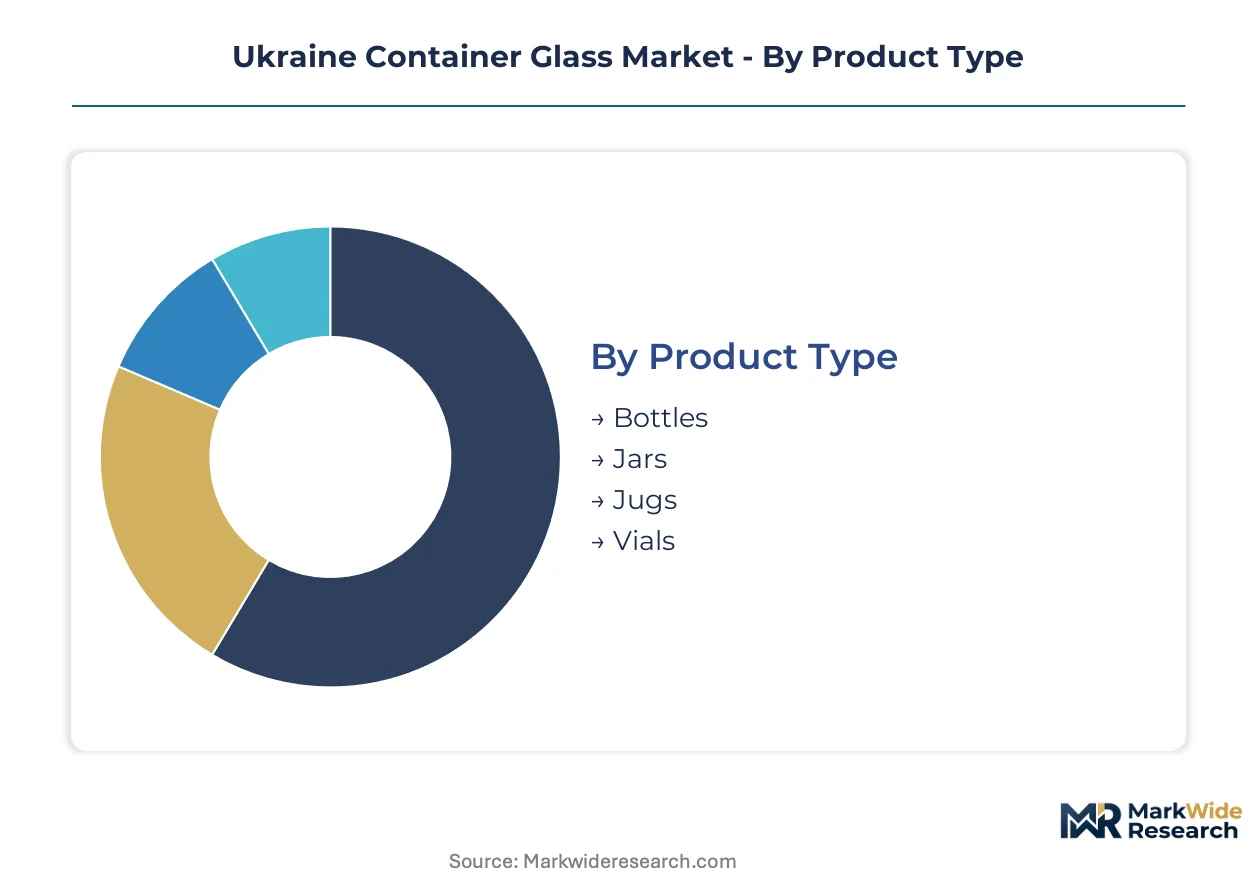
Ukraine's container glass market segments reflect divergent technical requirements and margin structures. Furnace operators configure batch chemistry and forming speeds differently across product categories to match end-use specifications.
Product Type:
Standalone vessels dominate procurement volumes, while embedded pharmaceutical formats command specification premiums due to certification overhead.
- Bottles:Soda-lime silica vessels formed by blow-and-blow processes with wall thickness calibrated for internal pressure resistance. Beverage manufacturers in Lviv and Zakarpattia oblasts drive procurement of flint and amber variants for cross-border spirits exports.
- Jars:Wide-mouth press-and-blow containers with oxygen-barrier closure compatibility for preserved vegetables and honey. Food processors in western oblasts sustain steady offtake despite polymer film substitution in cost-sensitive segments.
- Jugs:Large-format containers serving bulk liquid storage with reinforced heel designs for mechanical handling.
- Vials:Pharmaceutical-grade borosilicate or soda-lime formats with dimensional tolerances meeting GMP compliance for serialization and track-and-trace integration.
Bottles lead volumes today; vials are gaining share fastest through export certification requirements.
Application:
Cost tiers separate commodity food formats from premium beverage and regulated pharmaceutical packaging.
- Food Packaging:Standard flint and amber jars for preserved vegetables and condiments. Processors prioritize closure compatibility over premium glass grades, constraining margin expansion in this segment.
- Beverage Packaging:Premium spirits and craft beer bottles with gram-weight optimization and decorative surface treatments. Cross-border logistics into Poland and Slovakia pull flint and amber production toward western furnace clusters.
- Pharmaceutical Packaging:GMP-compliant vials requiring laser-etched serialization for EU market access. Domestic drug manufacturers and regional exporters anchor demand for tight-tolerance dimensional specifications.
- Personal Care:Cosmetic bottles and jars with decorative finishing for premium positioning. Smaller volume segment with fragmented customer base across Kyiv and Odesa distribution hubs.
Beverage packaging leads volumes today; pharmaceutical packaging is expanding most quickly.
End User:
Customer type determines contract structure, with multinational beverage groups consolidating procurement against fragmented food processor demand.
- Food Industry:Preserved vegetable and honey processors procuring standard jars through seasonal contracts. Price sensitivity limits technical co-development opportunities.
- Beverage Manufacturers:Spirits exporters and craft brewers mandating furnace upgrade qualifications and lightweighting capabilities. Extended contract durations accompany volume commitments.
- Healthcare Providers:Domestic drug manufacturers requiring vial serialization integration for EU distribution compliance.
- Cosmetic Companies:Premium positioning drives demand for decorative surface treatments in smaller batch quantities.
Beverage manufacturers lead volumes today; healthcare providers are climbing the fastest on regulatory compliance pull.
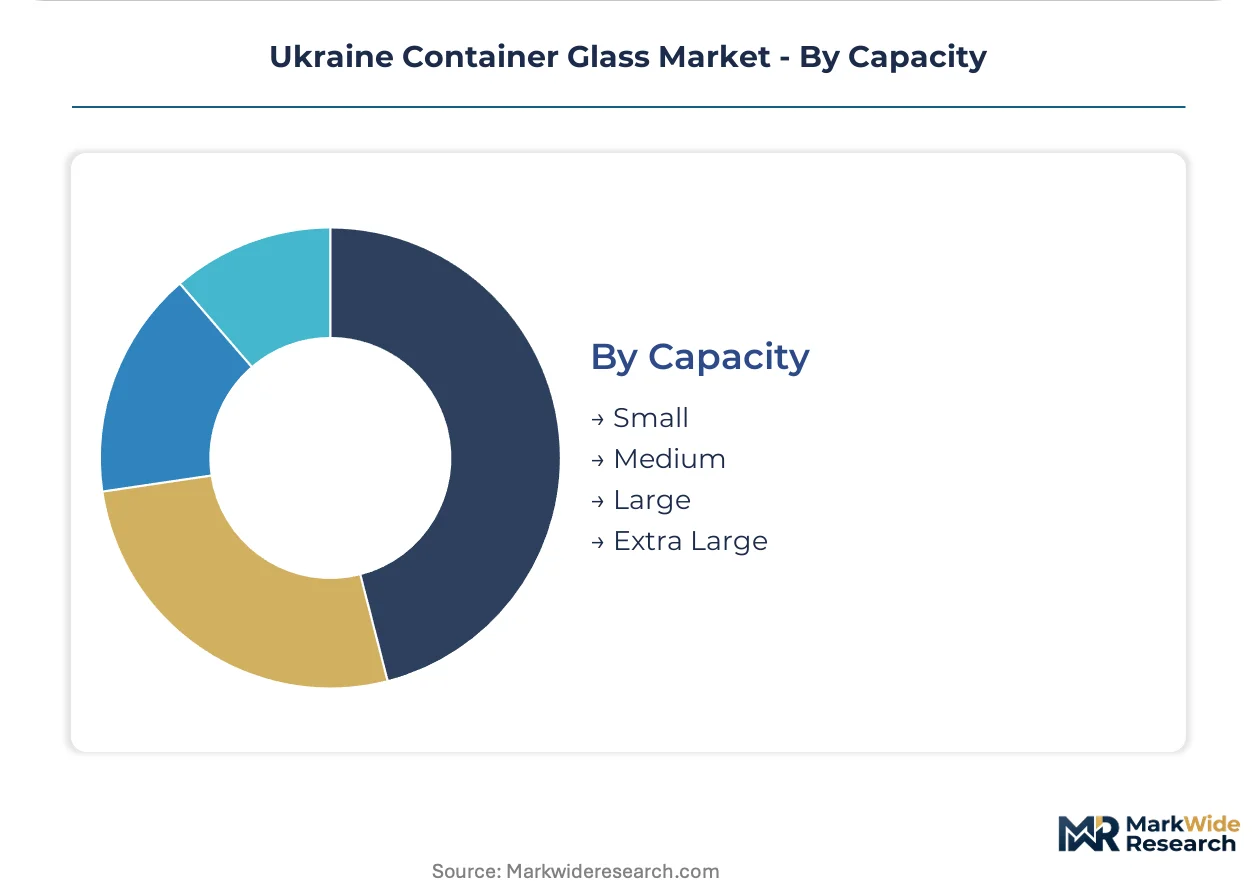
Capacity:
Volume scale segments align with logistics economics and end-use handling requirements.
- Small:Pharmaceutical vials and sample-size cosmetic containers. High unit value offsets lower absolute tonnage per shipment.
- Medium:Standard beverage bottles and food jars. Balances forming efficiency with palletization economics for cross-border truck loads.
- Large:Bulk spirits bottles and institutional food containers. Favored by export-oriented producers seeking transport cost optimization.
- Extra Large:Industrial jugs and specialty formats. Niche segment with limited furnace compatibility due to mold size constraints.
Medium capacity leads volumes today; small capacity shows steepest expansion trajectory on pharmaceutical demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled furnace operators and glass technologists concentrate in western Ukrainian oblasts where cross-border logistics infrastructure enables export-oriented production clusters.
Lviv Oblast
Polish and Slovak distribution hubs pull flint and amber bottle production toward Lviv's furnace clusters. Ukraine's Association Agreement enforcement mandates rising recycled-content thresholds through DSTU harmonization with EU standards. Rail and road corridors through Mostyska and Krakivets border crossings anchor beverage glass export volumes.
Kyiv Oblast
Integrated melting furnace complexes north of the capital serve domestic pharmaceutical and beverage packaging demand. The State Service of Ukraine on Food Safety and Consumer Protection inspects GMP compliance for vial serialization requirements. Hostomel and surrounding industrial zones concentrate technical glass production capacity.
Zakarpattia Oblast
Carpathian logistics corridors enable just-in-time delivery to Hungarian and Romanian bottling facilities. EU Packaging and Packaging Waste Regulation alignment pressures producers toward extended producer responsibility frameworks. Uzhhorod and Mukachevo sub-regions host mold-design-to-delivery operations for craft spirits exporters.
Dnipropetrovsk Oblast
Eastern industrial heritage sustains heavy-format container production for bulk liquid storage. Natural gas supply volatility forces hybrid electric-gas melting technology adoption across central furnace operations. Kryvyi Rih and Dnipro industrial zones maintain jar and jug manufacturing for preserved food processors.
Odesa Oblast
Black Sea port access supports import-dependent cullet supply chains for recycled-content mandates. The national technical regulator enforces batch chemistry standards harmonized with EN 15343 traceability protocols. Odesa and surrounding distribution hubs serve personal care and cosmetic packaging demand with decorative finishing capabilities.
Ukraine Container Glass Market Competitive Landscape
Top-tier vendors anchor integrated furnace operations with GMP certification and export logistics integration, while mid-tier specialists occupy regional beverage and food packaging niches. The vendor base stratifies across three archetypes: multinational-certified pharmaceutical suppliers, western oblast export-oriented flint/amber producers, and eastern commodity jar manufacturers. Capacity expansion and furnace electrification retrofits constitute the dominant competitive moves as natural gas price volatility reshapes operational economics.
Among Ukraine-based producers, Vetropak Hostomelʹsʹkyy Sklozavod, Verallia Ukraine, and Malinovsky Glassworks occupy positions across distinct market tiers. Vetropak Hostomelʹsʹkyy Sklozavod exemplifies the integrated furnace archetype with melting complex scale. Verallia Ukraine represents the pharmaceutical-certified tier through GMP-compliant vial capabilities. Malinovsky Glassworks anchors the amber bottle specialization segment serving domestic spirits exporters. These three producers collectively illustrate the market's structural segmentation across certification levels and end-use applications.
| Leading Market Players |
|---|
| Vetropak Hostomelʹsʹkyy Sklozavod |
| Ilona PKP |
| Verallia Ukraine |
| Malinovsky Glassworks |
| Rokitnovskiy Glass Work |
| Orion Glass LLC |
| BIOMEDSKLO PJSC |
| Druzhkovka Glass Plant |
| Sklo Alliance LLC |
| Others |
Pricing and Supply Chain Analysis
Skilled furnace operators concentrated in western Ukrainian oblasts command wage premiums that compress margin spreads between premium pharmaceutical-grade output and standard beverage formats. Labor-cost differentials between Lviv's export-oriented clusters and eastern commodity producers translate into pricing-tier spreads that favor certified sustainable output over uncertified commodity glass.
Pricing Analysis
Bundled mold-design-to-delivery services command premiums against unbundled container-only procurement across Ukrainian glass supply. Three-tier pricing structure across GMP-certified pharmaceutical, export-grade beverage, and domestic commodity food segments reflects certification overhead and cross-border logistics integration. Pricing pressure stems from natural gas cost volatility forcing hybrid furnace retrofits that erode margin predictability in standard flint grades. Food processors exhibit highest price sensitivity, while pharmaceutical exporters accept premium positioning for serialization-ready vial supply.
Supply Chain Analysis
Workforce availability constraints in Dnipropetrovsk and eastern oblasts limit furnace rebuild capacity against western Ukraine's deeper glass-technician pools. Raw material sourcing draws from Ukrainian silica sand deposits, imported soda ash from Bulgaria and Romania, and zirconia-alumina-silica refractory brick from limited European suppliers. Single-source vulnerability in refractory materials sourcing extends furnace maintenance lead times. Distribution runs through Polish and Slovak rail corridors for export-oriented beverage bottlers, while domestic pharmaceutical supply feeds from Hostomel and Kyiv industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
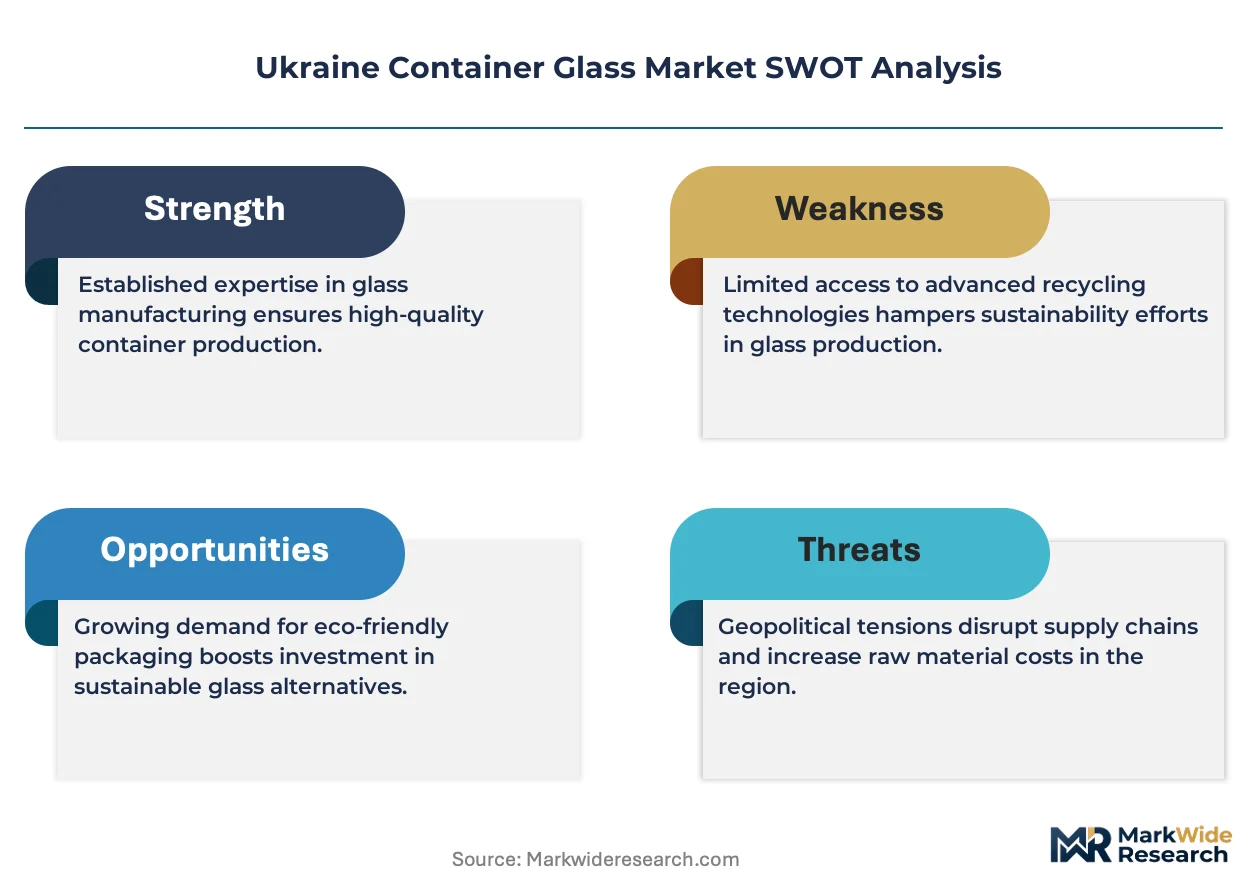
This market represents a late-cycle quality story as spirits exporters and pharmaceutical manufacturers shift procurement toward GMP-certified, lightweighted formats with verified recycled content. Premium specification demand is decoupling pricing power from commodity soda-lime grades.
For Market Incumbents: Hedge margin exposure in natural gas-dependent furnace operations by accelerating oxy-fuel combustion retrofits and securing long-term cullet supply agreements with Polish and Slovak collection networks. Defensive consolidation around pharmaceutical serialization capabilities protects against emerging mold-design specialists from Zakarpattia oblasts. For New Entrants and Emerging Players: Begin with pharmaceutical vial serialization integration as the most penetrable white-space target, where GMP certification barriers exclude uncertified imports and domestic capacity constraints persist. Carpathian logistics corridors through Uzhhorod offer geographic positioning for craft spirits lightweighting services. For Investors and Strategic Acquirers: Beverage bottlers with cross-border EU distribution networks are the most active acquirer in this space, seeking backward integration into captive glass supply. Long-term viability centers on furnace electrification readiness and Association Agreement compliance infrastructure. Watch DSTU-EN 15343 traceability protocol enforcement as the inflection signal for recycled-content premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Oxy-Fuel Furnace Retrofit | Reduces natural gas dependency while maintaining melting temperatures above 1500°C for soda-lime batches. |
| GMP Certification Investment | Unlocks pharmaceutical vial premiums through State Service of Ukraine on Food Safety compliance. |
| Cullet Supply Integration | Secures feedstock for EU-mandated recycled content ratios under Association Agreement obligations. |
| Lightweighting Technology Adoption | Captures premium spirits segments where gram-weight reductions offset Polish and Slovak transport costs. |
| Cross-Border Logistics Partnership | Enables just-in-time delivery to Hungarian and Romanian bottling facilities through Carpathian corridors. |
Research Methodology
Bottom-up beverage and pharmaceutical end-use modeling reconciled against top-down furnace capacity and cullet supply tracking forms the analytical core of this study. Primary interviews with plant managers at integrated melting complexes, procurement leads at spirits exporters, regulatory affairs specialists at pharmaceutical manufacturers, and distribution channel partners across Polish and Slovak border zones combined with secondary validation from customs records, DSTU standard filings, and Association Agreement implementation reports.
Input-output matrices map batch chemistry configurations, forming speeds, and fuel-switching timelines across product segments without year-specific anchoring. Segmentation dimensions span product type, application tier, end-user contract structure, and capacity scale across the projection horizon. CAGRs derive from furnace rebuild cycles, recycled-content mandate phase-ins, and cross-border logistics capacity expansion. Forecast inputs incorporate natural gas price volatility scenarios and EN 15343 traceability protocol adoption curves.
Several conditions sit outside the modeled scope, including military conflict disruption to eastern furnace operations and abrupt EU Packaging Waste Directive enforcement acceleration. Forecasts reflect assumptions about cullet collection infrastructure buildout and refractory materials import continuity. Material deviation in natural gas supply stability or Association Agreement suspension warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
India Glass Packaging Market
Glass Packaging
Glass Bottles Market
Glass Packaging
Mason Jars Market
Glass Packaging
Asia Pacific Pharmaceutical Glass Packaging Market
Glass Packaging
Uruguay Container Glass Market
Glass Packaging
Packaging Jars Market
Glass Packaging
Argentina Container Glass Market
Glass Packaging
Pharmaceutical Glass Packaging Market
Glass Packaging
Glass Jugs Market
Glass Packaging
Morocco Container Glass Market
Glass Packaging
Malaysia Container Glass Market
Glass Packaging
Peru Container Glass Market
Glass Packaging
Glass Decanters Market
Glass Packaging
Australia Container Glass Market
Glass Packaging
Africa Glass Bottles and Containers Market
Glass Packaging
Czech Republic Container Glass Market