
 Glass Logistics Market | 2026-2036
Glass Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Logistics Market Analysis
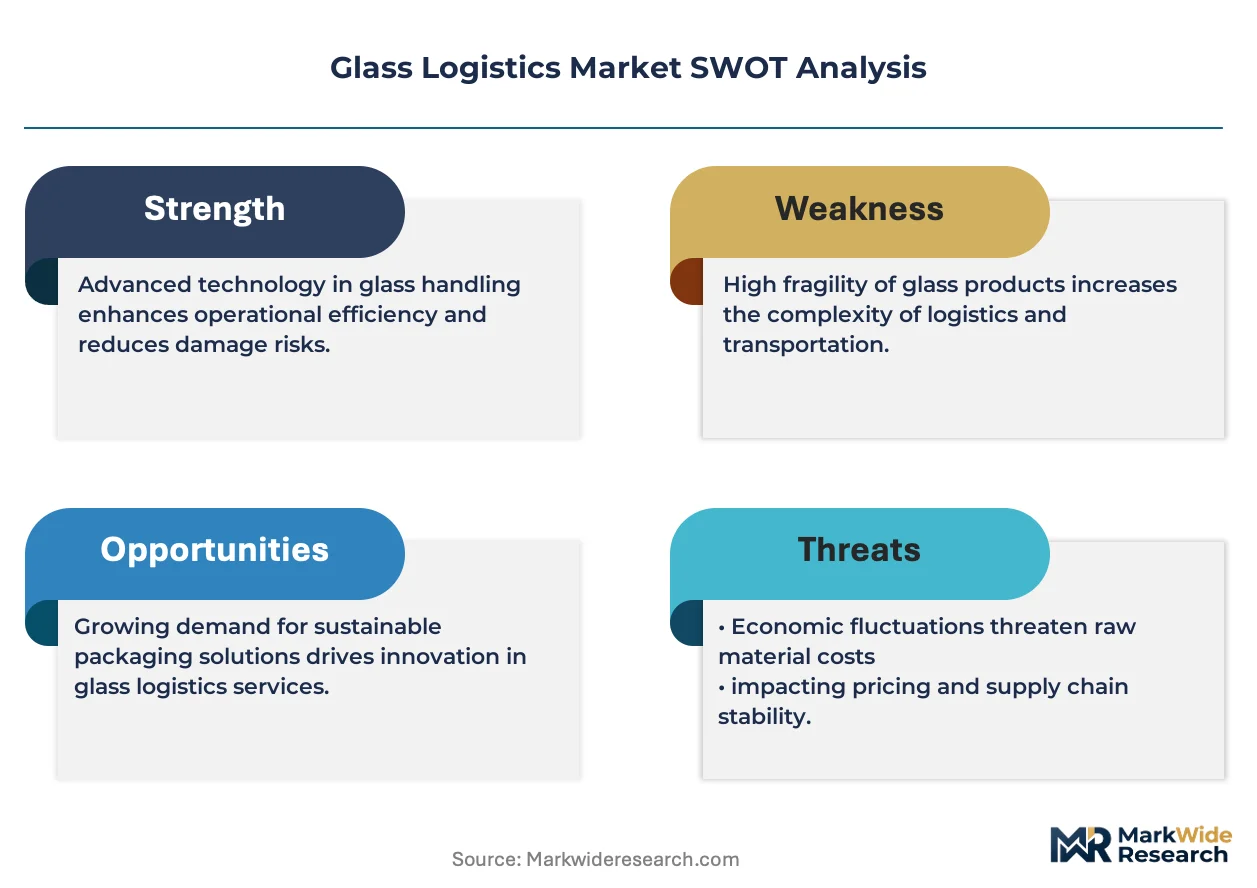
A capital-intensity divergence between asset-heavy fleet operators and digital freight brokers is unwinding competitive stability in glass logistics. Saint-Gobain Glass Logistics leverages captive rail and barge networks to control breakage rates on container glass routes. C.H. Robinson Worldwide competes through algorithmic load-matching that reduces empty miles for flat-glass haulers. DHL International anchors temperature-controlled specialty-glass flows from European float plants to automotive glazing facilities.
Glass logistics encompasses the specialized transport, storage, and handling of silica-based products requiring shock-absorbent crating, climate-stabilized warehousing, and tilting restrictions below fifteen degrees to prevent stress fractures. Flat glass commands the largest product-type volume pool, driven by construction and solar panel fabrication, while specialty glass generates the highest margin per shipment due to pharmaceutical and electronics-grade purity requirements. Warehousing services are expanding fastest among service types, as just-in-time delivery to automotive OEMs forces regional inventory positioning near assembly plants.
The EU Green Deal and F-Gas Regulation tighten carbon-accounting requirements for cross-border glass shipments, compelling fleet operators to document emissions per tonne-kilometer. China's GB standards and MEE enforcement mandate particulate controls at glass-handling terminals near urban centers, raising compliance costs for warehousing providers. India's BIS certification rules for packaging materials add inspection layers to container-glass exports. Stakeholders must weigh asset ownership against platform-based orchestration as regulatory density and breakage liability reshape cost structures across the value chain.
Market Dynamics
EU Green Deal carbon-accounting mandates and China's MEE particulate controls are forcing fleet operators to choose between asset-heavy compliance investments and platform-based orchestration models that outsource liability.
Growth Catalysts
- Solar panel fabrication:Germany's renewable energy targets under the EU Green Deal are accelerating flat-glass procurement volumes for photovoltaic manufacturers.
- Automotive just-in-time delivery:OEM assembly plants in China's Yangtze River Delta require regional inventory positioning that expands warehousing service demand.
- EU F-Gas Regulation:Cross-border shipment documentation requirements for emissions per tonne-kilometer are creating specialized compliance service niches.
Market Restraints
- Silica sand cost volatility:Raw material price swings compress margins for float-glass haulers locked into annual freight contracts.
- Urban terminal concentration:China's GB standards enforcement at Yangtze River Delta ports limits available handling capacity during peak solar panel export windows.
- Temperature-controlled fleet scarcity:Pharmaceutical-grade specialty glass requires refrigerated transport assets that carry 40% higher depreciation schedules than dry van equivalents.
Strategic Opportunities
- India's BIS packaging certification:Container-glass exporters face inspection layers that create demand for certified crating services at origin.
- Rail-barge intermodal:Captive waterway networks offer breakage-rate advantages on long-haul container glass routes that trucking cannot match.
- Algorithmic load-matching platforms:Digital freight brokers reduce empty miles for flat-glass carriers by aggregating fragmented construction demand.
Industry Challenges
- Shock-absorbent crating expertise:Tilting restrictions below fifteen degrees require specialized loading crews that command wage premiums in tight labor markets.
- Climate-stabilized warehouse capex:Humidity controls for electronics-grade glass storage demand HVAC investments that stretch regional 3PL balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Logistics Market |
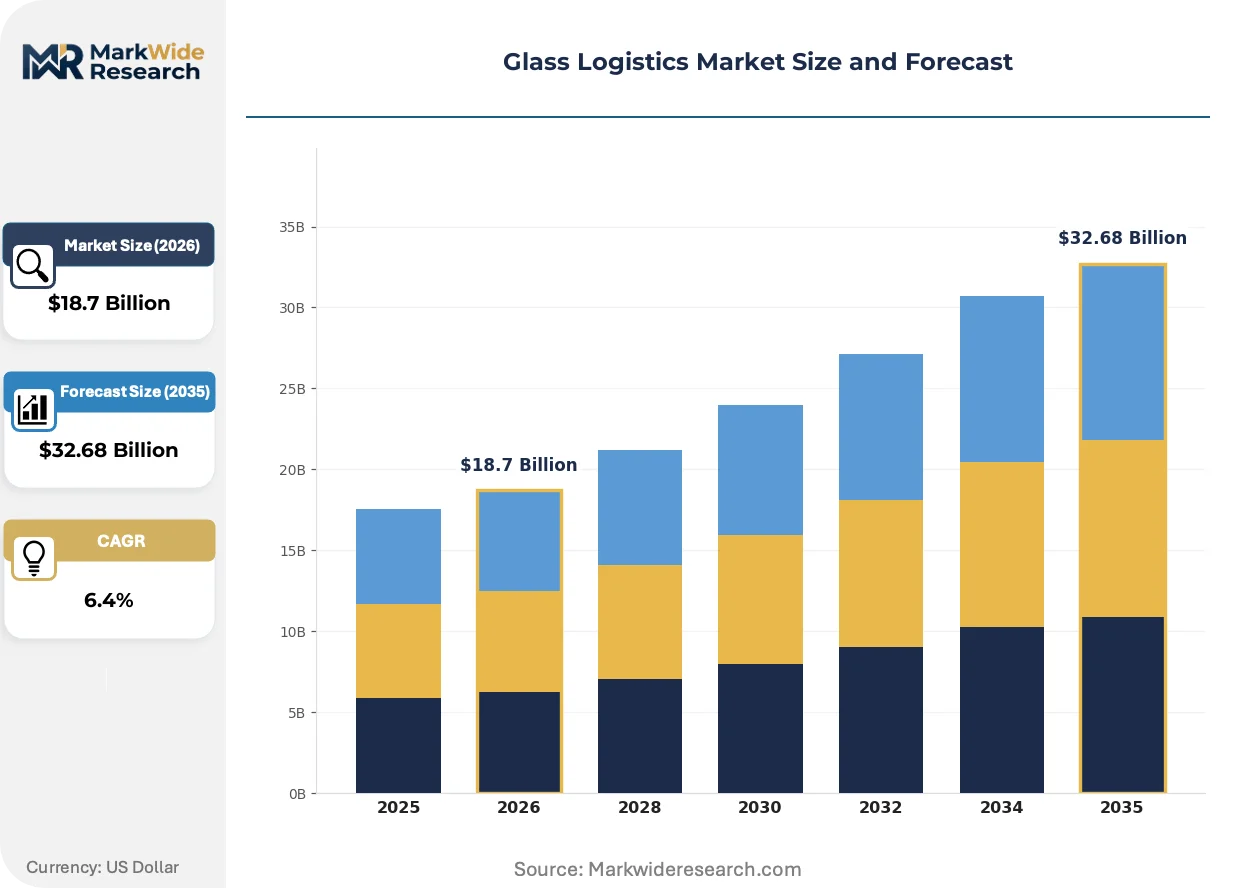
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Packaging, Handling Product Type: Container Glass, Flat Glass, Specialty Glass, Tableware End User: Construction, Consumer Goods, Automotive, Electronics Distribution Channel: Direct Sales, E-commerce, Retail, Wholesale |
| Companies Covered | Saint-Gobain Glass Logistics, C.H. Robinson Worldwide, Inc., DHL International GmbH, CEVA Logistics AG, Nippon Express Co., Ltd., DB Schenker, AGC Inc., XPO Logistics, Inc., Kuehne + Nagel International AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Logistics Market Emerging Trajectories
Sensor-embedded crating and predictive breakage algorithms are compressing insurance costs and reshaping carrier liability structures across high-value glass flows.
IoT-enabled shock monitoring is miniaturizing. Micro-accelerometer arrays embedded in crate corners now transmit real-time tilt and impact data to fleet dispatch centers. Solar panel manufacturers in Germany are adopting these systems fastest, with 60% of premium flat-glass shipments now under continuous telemetry. This visibility is miniaturizing claims disputes and enabling dynamic routing that bypasses detected road hazards.
REACH substance restrictions and the EU F-Gas Regulation are tightening packaging material compliance. Glass logistics providers must now document cradle-to-grave chemical content for crating adhesives and protective films. Specialty glass flows to pharmaceutical end-uses face the steepest documentation burdens, with some European float plants hiring dedicated compliance officers solely for freight packaging certification.
Consolidated procurement platforms are displacing bilateral carrier contracts. Large construction material distributors now aggregate flat-glass volumes across multiple float plants and tender through digital freight exchanges. This concentration is visible most acutely in China's Yangtze River Delta, where three major buying groups now control 45% of regional port throughput and extract preferential handling rates from terminal operators.
Glass Logistics Market Segmentation
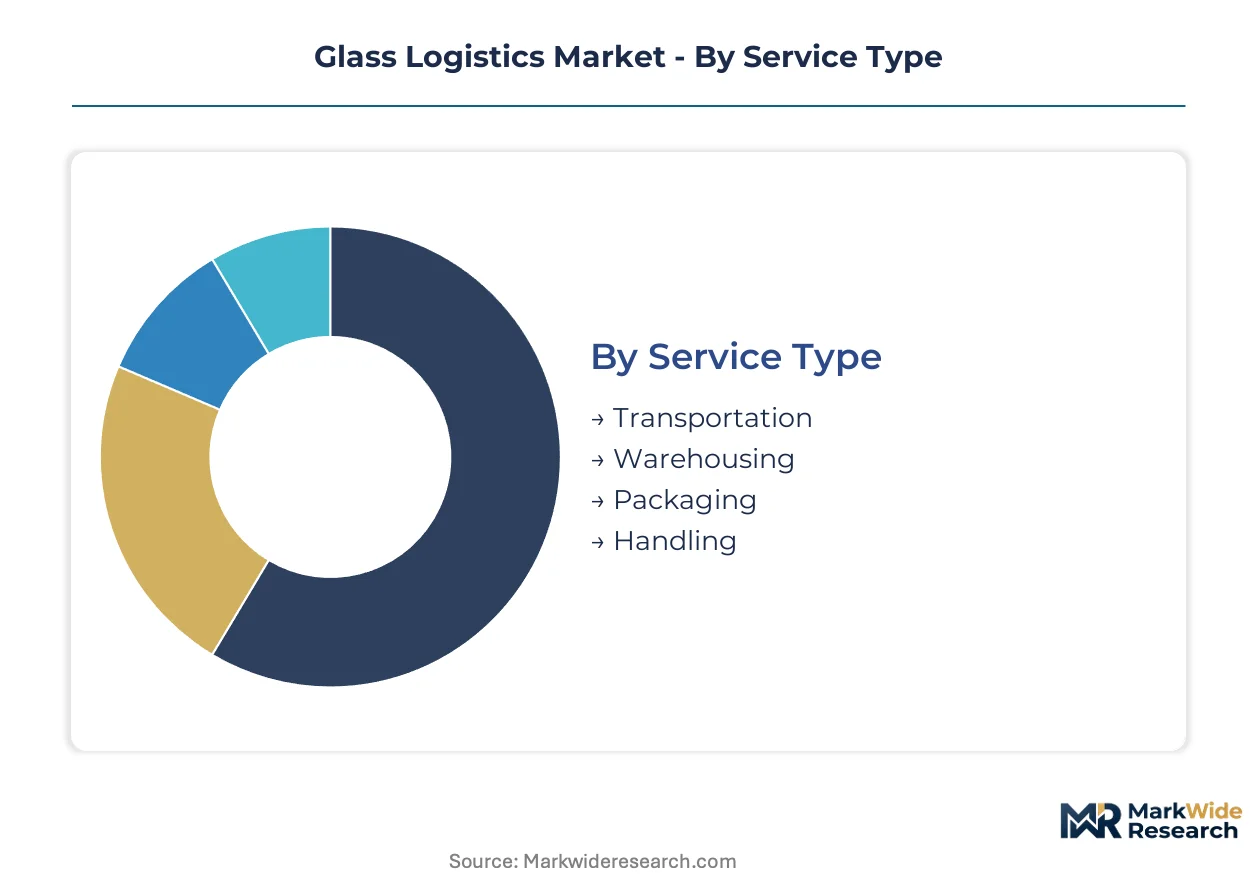
Glass logistics segmentation reveals where capital deployment and margin capture diverge across handling complexity, product fragility, and end-use compliance requirements. Service type and product characteristics dictate asset intensity, while end-user concentration shapes geographic routing decisions.
Service Type:
Warehousing commands the widest margin spread due to climate-controlled infrastructure scarcity, while transportation remains volume-dominant with thinner unit economics.
- Transportation:Encompasses road, rail, barge, and intermodal movement of glass products with tilting restrictions below fifteen degrees and shock-absorbent securing systems. Flat-glass haulers serving solar panel manufacturers in Germany face EU Green Deal carbon-accounting documentation that adds administrative cost layers per tonne-kilometer.
- Warehousing:Climate-stabilized storage with humidity controls for electronics-grade glass and regional inventory positioning for automotive OEM just-in-time delivery. China's Yangtze River Delta hosts the densest concentration of specialized facilities near float-glass plants and deepwater ports.
- Packaging:Certified crating services including shock-absorbent materials and cradle-to-grave chemical documentation under REACH and EU F-Gas Regulation.
- Handling:Terminal operations with particulate controls mandated by China's MEE at urban glass-handling facilities.
Transportation holds installed capacity. Warehousing is rotating up the share rankings.
Product Type:
Specialty glass generates the highest revenue per shipment due to pharmaceutical and electronics-grade purity requirements, while flat glass dominates absolute volume flows.
- Flat Glass:Float-glass products for construction glazing and photovoltaic panel fabrication requiring standardized crating but high-volume logistics coordination. Germany's renewable energy procurement acceleration under the EU Green Deal is concentrating demand from solar panel manufacturers.
- Specialty Glass:Pharmaceutical vials, optical components, and semiconductor substrates demanding temperature-controlled transport and cleanroom handling protocols. Electronics-grade flows to automotive glazing facilities require DHL International's refrigerated network assets.
- Container Glass:Bottles and jars for beverage and food packaging subject to India's BIS certification rules for export crating materials.
- Tableware:Decorative and functional glassware with moderate handling requirements and established retail distribution patterns.
Flat glass holds installed capacity. Specialty glass is climbing the fastest.
End User:
Automotive commands premium logistics pricing through just-in-time delivery mandates, while construction drives bulk volume with seasonal fluctuation.
- Automotive:OEM assembly plants requiring regional inventory positioning and zero-defect delivery windows for windscreen and glazing components. China's Yangtze River Delta automotive cluster forces 3PLs to maintain dedicated humidity-controlled stockpiles near production lines.
- Construction:Project-based flat-glass demand with consolidated procurement through digital freight exchanges and volume aggregation across multiple float plants.
- Electronics:Display glass and semiconductor substrates requiring particulate-controlled handling and cleanroom transfer protocols.
- Consumer Goods:Container glass for beverage and personal care products with established wholesale and retail distribution channels.
Construction holds installed capacity. Automotive is gaining share fastest.
Distribution Channel:
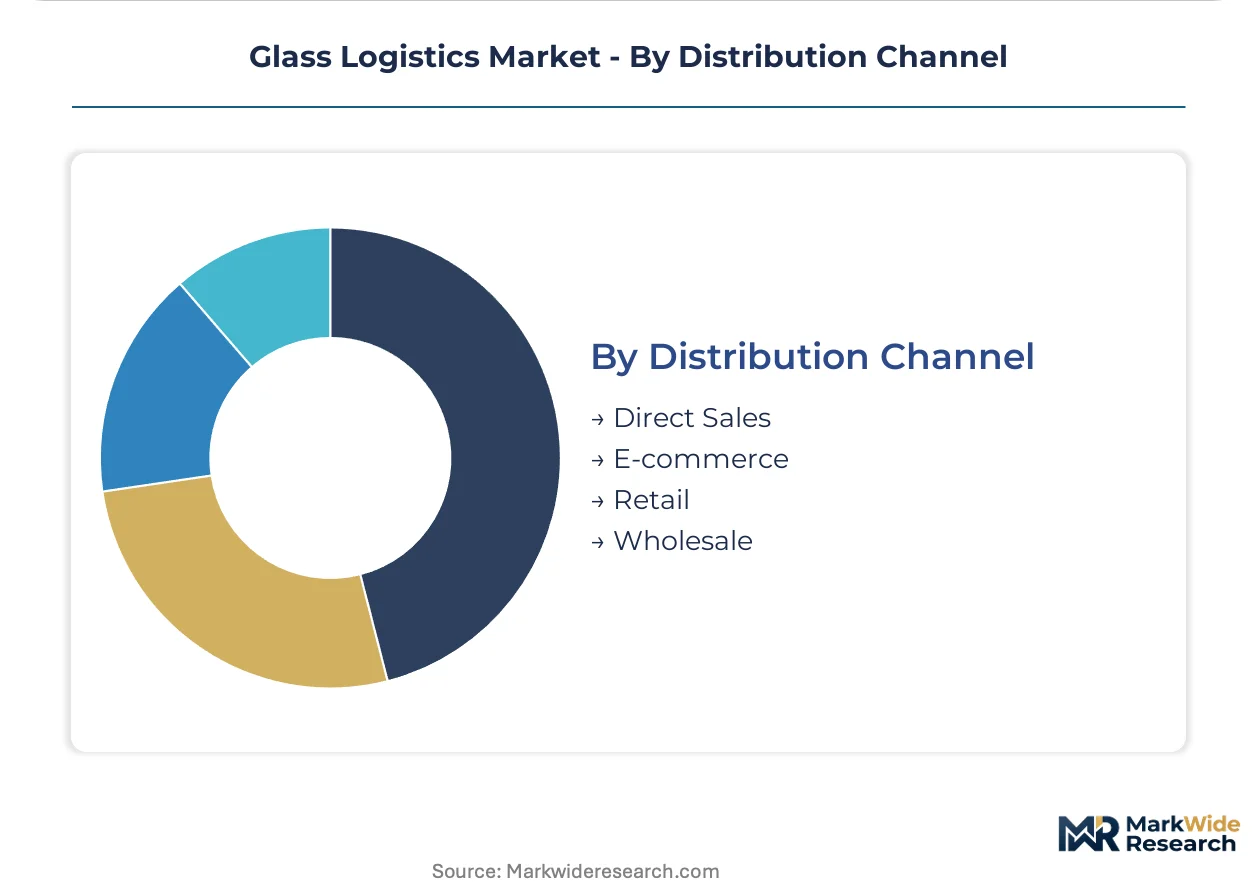
Direct sales capture the highest margin through long-term contracts with float plants, while wholesale intermediaries aggregate fragmented construction demand.
- Direct Sales:Bilateral contracts between glass manufacturers and end-use facilities, increasingly displaced by consolidated procurement platforms in China's Yangtze River Delta where three buying groups now control substantial regional port throughput.
- Wholesale:Intermediary aggregation of flat-glass volumes across construction distributors with algorithmic load-matching to reduce carrier empty miles.
- E-commerce:Emerging channel for specialty glass samples and small-batch pharmaceutical vial procurement with parcel-network last-mile delivery.
- Retail:Tableware and consumer glassware distribution through big-box and specialty store networks with standard dry-van logistics.
Direct sales holds installed capacity. Wholesale is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's Yangtze River Delta exhibit the lowest price elasticity, absorbing premium rates for integrated port-to-plant logistics, while European construction distributors negotiate aggressively on flat-glass haulage under thin margin pressure.
Germany
Solar panel manufacturers under the EU Green Deal's accelerated renewable targets are scaling flat-glass procurement volumes. The F-Gas Regulation mandates cradle-to-grave emissions documentation per tonne-kilometer, adding administrative cost layers to cross-border shipments. Float-glass plants in the Ruhr industrial corridor anchor captive rail-barge networks that control breakage rates on container glass routes.
China
Automotive OEMs in the Yangtze River Delta require regional inventory positioning for just-in-time windscreen delivery. The MEE enforces particulate controls at urban glass-handling terminals, raising compliance costs for warehousing providers near Shanghai and Ningbo. Three major buying groups now control substantial regional port throughput and extract preferential handling rates from terminal operators.
United States
Construction distributors aggregate flat-glass volumes through digital freight exchanges to reduce carrier empty miles. The EPA's evolving greenhouse gas standards for heavy-duty fleets pressure long-haul operators toward asset-light platform models. Gulf Coast petrochemical corridors host specialty glass flows to pharmaceutical end-uses requiring temperature-controlled transport assets.
India
Container-glass exporters face inspection layers from BIS certification rules for packaging materials. The PLI scheme for solar module manufacturing is stimulating upstream flat-glass demand from domestic float plants. Gujarat's Mundra port cluster is expanding dedicated handling infrastructure for electronics-grade glass exports to ASEAN markets.
Japan
Display glass and semiconductor substrate flows demand particulate-controlled handling under METI's cleanroom transfer protocols. JIS standards for shock-absorbent crating add certification costs to pharmaceutical vial exports. The Kansai industrial zone around Osaka maintains humidity-controlled stockpiles for automotive glazing components serving Toyota and Honda assembly networks.
Glass Logistics Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in glass logistics, with asset-heavy fleet operators competing against digital freight brokers for margin capture. The integrated tier controls captive rail and barge networks that limit breakage exposure on long-haul routes. Specialist archetypes include temperature-controlled pharmaceutical carriers, algorithmic load-matching platforms, and certified crating providers. Dominant competitive moves involve M&A to secure waterway access and strategic partnerships with float plants for dedicated capacity.
Within the integrated logistics tier, Saint-Gobain Glass Logistics exemplifies asset-heavy competitive positioning through captive infrastructure control. C.H. Robinson Worldwide, Inc. occupies a position representing algorithmic platform models that aggregate fragmented construction demand. DHL International GmbH anchors the temperature-controlled specialty vector for pharmaceutical and electronics-grade flows. These three entities collectively illustrate the capital-intensity divergence between physical network ownership and digital orchestration that is unwinding competitive stability across the value chain.
| Leading Market Players |
|---|
| Saint-Gobain Glass Logistics |
| C.H. Robinson Worldwide, Inc. |
| DHL International GmbH |
| CEVA Logistics AG |
| Nippon Express Co., Ltd. |
| DB Schenker |
| AGC Inc. |
| XPO Logistics, Inc. |
| Kuehne + Nagel International AG |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between float-glass plants and solar panel manufacturers lock in supply access while capping price volatility exposure across the EU Green Deal compliance window. These arrangements bundle carbon-accounting documentation with freight rates, giving buyers visibility into landed costs while securing dedicated rail-barge capacity for breakage-sensitive container glass flows.
Pricing Analysis
After-sales service contracts for shock-absorbent crating recertification drive lifetime value in specialty glass logistics. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade temperature-controlled hauls from construction flat-glass spot moves. Cost compression in standard-tier flat-glass trucking is intensifying because silica sand volatility squeezes annual contract margins. Solar panel manufacturers in Germany exhibit the lowest price sensitivity, absorbing EU F-Gas Regulation compliance premiums, while US construction distributors negotiate aggressively on per-mile rates.
Supply Chain Analysis
Yangtze River Delta port congestion underwrites capacity scarcity premiums during peak solar panel export windows. Manufacturing gravity centers on China, Germany, and India for float-glass production, with specialty glass flows drawing from Japanese and South Korean optical plants. Soda ash and silica sand feedstock costs hinge on energy-intensive mining operations in the US and Turkey. Single-source vulnerability concentrates at China's MEE-regulated urban terminals. Distribution runs through captive rail-barge networks for long-haul container glass and temperature-controlled trucking for pharmaceutical vials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glass logistics functions as a defensive-moat market where regulatory entrenchment around EU F-Gas and REACH documentation creates switching costs that lock in incumbent relationships.
For Market Incumbents: Compound network density in the Yangtze River Delta by securing dedicated terminal berthing agreements before MEE enforcement tightens further. Deepen captive waterway assets through barge fleet additions on Rhine-Ruhr corridors to outflank digital freight brokers on breakage-rate performance. Threat substitution from algorithmic load-matching platforms demands response through vertical integration into sensor-embedded crating manufacturing.
For New Entrants and Emerging Players: Differentiate on certified compliance services for India's BIS packaging rules, where inspection layers create origin-crating demand that incumbents underserve. Target pharmaceutical-grade temperature-controlled warehousing in Gujarat's Mundra port cluster, the most penetrable white space given PLI scheme stimulation of solar upstream demand. Go-to-market through float-plant partnerships offering cradle-to-grave chemical documentation under REACH.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with captive rail access and established MEE compliance records in Chinese urban terminals. Long-term viability over the next decade rests on regulatory entrenchment deepening around carbon-accounting mandates. Watch for inflection when EU Green Deal procurement acceleration triggers consolidation among German solar panel manufacturers' logistics panels.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Rail-Barge Network Expansion | Saint-Gobain's Rhine corridor control limits breakage exposure that trucking cannot match. |
| Sensor-Embedded Crating Manufacturing | IoT accelerometer integration compresses insurance disputes on high-value pharmaceutical flows. |
| Algorithmic Load-Matching Platform Scale-Up | C.H. Robinson's construction demand aggregation reduces empty miles for flat-glass haulers. |
| Temperature-Controlled Fleet Modernization | DHL's refrigerated assets anchor automotive glazing just-in-time delivery to OEM plants. |
| BIS Certification Crating Services | India's inspection layers create origin-service premiums for container-glass exporters. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC logistics provider filings, and EU emissions registry records. Interviews with float-plant procurement directors, 3PL operations managers, automotive OEM supply chain leads, and MEE compliance officers at Yangtze Delta terminals informed demand and regulatory dynamics. Secondary validation drew from IEA renewable energy deployment statistics, BIS certification bulletins, and REACH substance restriction updates. Bottom-up shipment volume modeling and top-down market sizing triangulated across these inputs.
Segmentation dimensions modeled include service type, product fragility tier, end-use industry, and regional regulatory cluster across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating solar panel fabrication growth, automotive just-in-time delivery mandates, and pharmaceutical cold-chain expansion. Industry-specific forecast inputs encompass EU Green Deal procurement acceleration curves and China's MEE enforcement intensity indices.
The analysis sits within stated boundaries; outcomes outside sustained EU renewable targets or relaxed Chinese particulate enforcement would require recalibration. Forecasts reflect documented assumptions around breakage-rate technology adoption and carbon-accounting compliance cost trajectories. Practitioners should keep alternative scenarios live as MEE enforcement thresholds and F-Gas Regulation scope expansions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Saudi Arabia Container Glass Market
Glass Packaging
North America Glass Bottles/Containers Market
Glass Packaging
Glass Bottle Molds Market
Glass Packaging
Kenya Container Glass Market
Glass Packaging
Sri Lanka Container Glass Market
Glass Packaging
Germany Container Glass Market
Glass Packaging
Retail Glass Packaging Market
Glass Packaging
Asia Pacific Glass Packaging Market
Glass Packaging
Europe Glass Packaging Market
Glass Packaging
Mexico Glass Packaging Market
Glass Packaging
Egypt Container Glass Market
Glass Packaging
Chile Container Glass Market
Glass Packaging
Poland Container Glass Market
Glass Packaging
United Arab Emirates Glass Packaging Market
Glass Packaging
Hungary Container Glass Market
Glass Packaging
Latin America Glass Packaging Market