
 Angola Container Glass Market | 2026-2036
Angola Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Angola Container Glass Market Insights
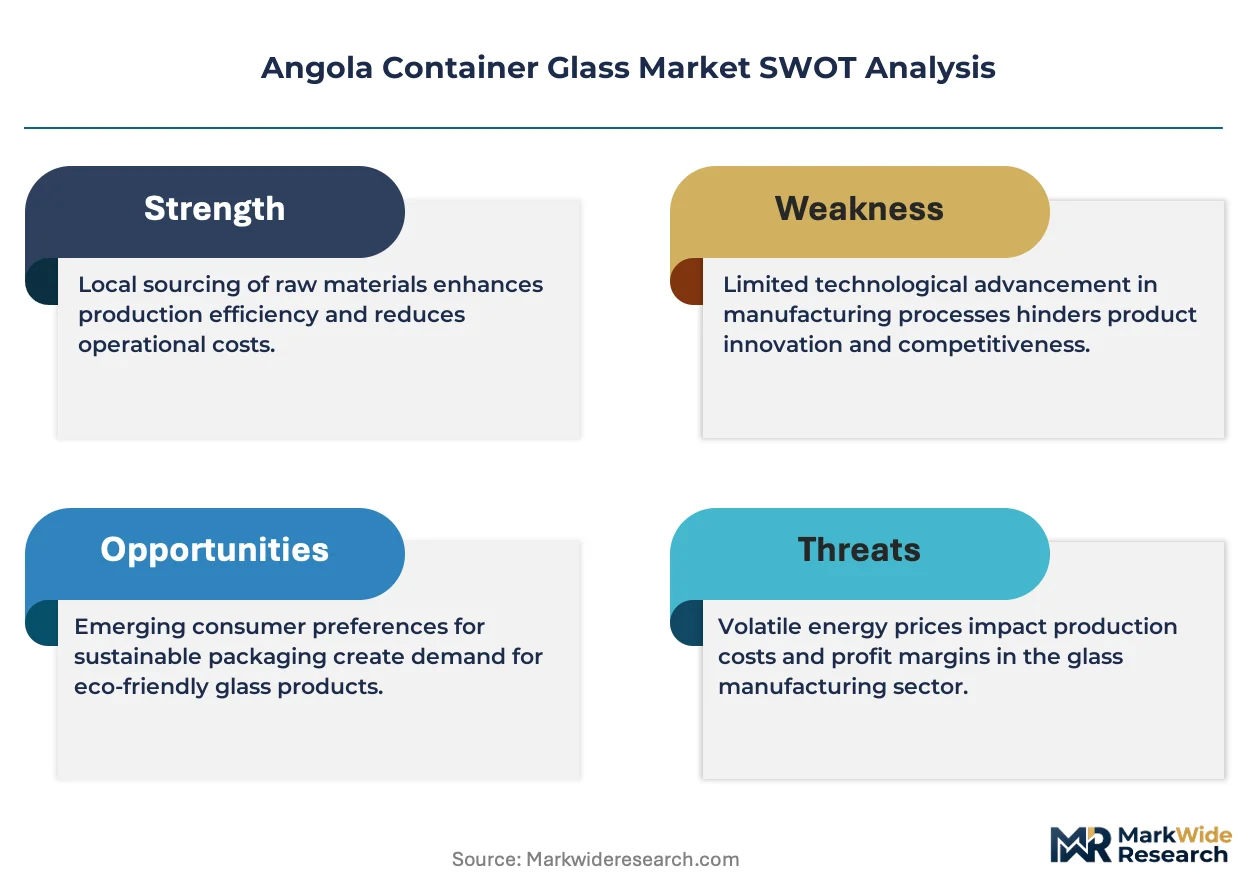
Pharmaceutical-grade borosilicate specification upgrades is unwinding across Angola's container glass sector as domestic drug packaging standards tighten. Beta Glass Plc leverages its Nigerian manufacturing base to supply premium amber bottles into Angolan pharmaceutical channels. Vidrul - Angolan Glass Factory anchors local production with furnace operations near Luanda, while EMBALVIDRO-INDÚSTRIA (SU), LDA specializes in custom jar formats for regional food processors.
Container glass denotes soda-lime silica vessels formed through blow-and-blow or press-and-blow processes, typically achieving wall thickness of 2-5 mm and thermal shock resistance to 42°C differential, designed primarily for hermetic product containment and UV-protective storage. Amber bottles command the strongest position in pharmaceutical and premium beverage applications where light-blocking properties justify higher unit economics. Clear glass dominates volume in standard beverage packaging, while frosted color treatments are gaining traction in cosmetics as brands seek tactile differentiation on retail shelves.
Angola's national standards body enforces container integrity specifications for food-contact glassware, while the country's pharmaceutical regulator mandates USP-compliant packaging for drug distribution, collectively elevating quality thresholds for imports and local production alike. Environmental compliance frameworks are beginning to target furnace emissions and cullet recycling rates, pressuring older production lines toward efficiency retrofits. Stakeholders must weigh the capital requirements of furnace modernization against the margin compression from rising energy costs and evolving compliance obligations.
Market Dynamics
Angola's import substitution mandate is compressing the container glass supply chain toward domestic furnace capacity, forcing beverage bottlers and pharmaceutical packagers to requalify local sources against previously dominant Nigerian and European imports.
Growth Catalysts
- Pharmaceutical packaging standards:Angola's national pharmaceutical regulator mandates USP-compliant packaging for drug distribution, creating certified demand pull for borosilicate-grade amber bottles.
- Beverage sector expansion:Luanda-based bottlers are scaling premium beer and soft drink lines, requiring hermetic glass containment with UV-blocking properties.
- Cullet recycling mandates:Environmental compliance frameworks now target furnace emissions and post-consumer glass recovery rates, incentivizing efficiency retrofits on older production lines.
Market Restraints
- Natural gas price volatility:Furnace operations depend on imported LNG feedstock, exposing margin structures to global energy market swings.
- Equipment import dependency:Critical furnace refractories and forming machinery originate from European and Asian suppliers, creating lead-time vulnerability.
- Aluminum can substitution:Beverage packagers in cost-sensitive segments are trialing metal alternatives for single-serve formats.
Strategic Opportunities
- Benguela province food processing:Emerging agro-industrial clusters in southwestern Angola lack localized jar and bottle supply, creating greenfield demand for custom formats.
- Lightweighting technology convergence:Thin-wall forming techniques combined with surface coating innovations enable material reduction without strength compromise.
- Regional export positioning:SADC trade protocols allow duty-preferred access to neighboring markets currently served by distant Asian suppliers.
Industry Challenges
- Skilled furnace operations talent:Local technical institutes lack specialized glass technology curricula, forcing reliance on expatriate melt specialists.
- Pharmaceutical certification timelines:USP and FDA-equivalent validation processes for new packaging lines extend 18-24 months, delaying revenue recognition on capital deployed.
- Legacy logistics integration:Existing distribution networks optimized for imported palletized goods require reconfiguration for domestically produced bulk formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Angola Container Glass Market |
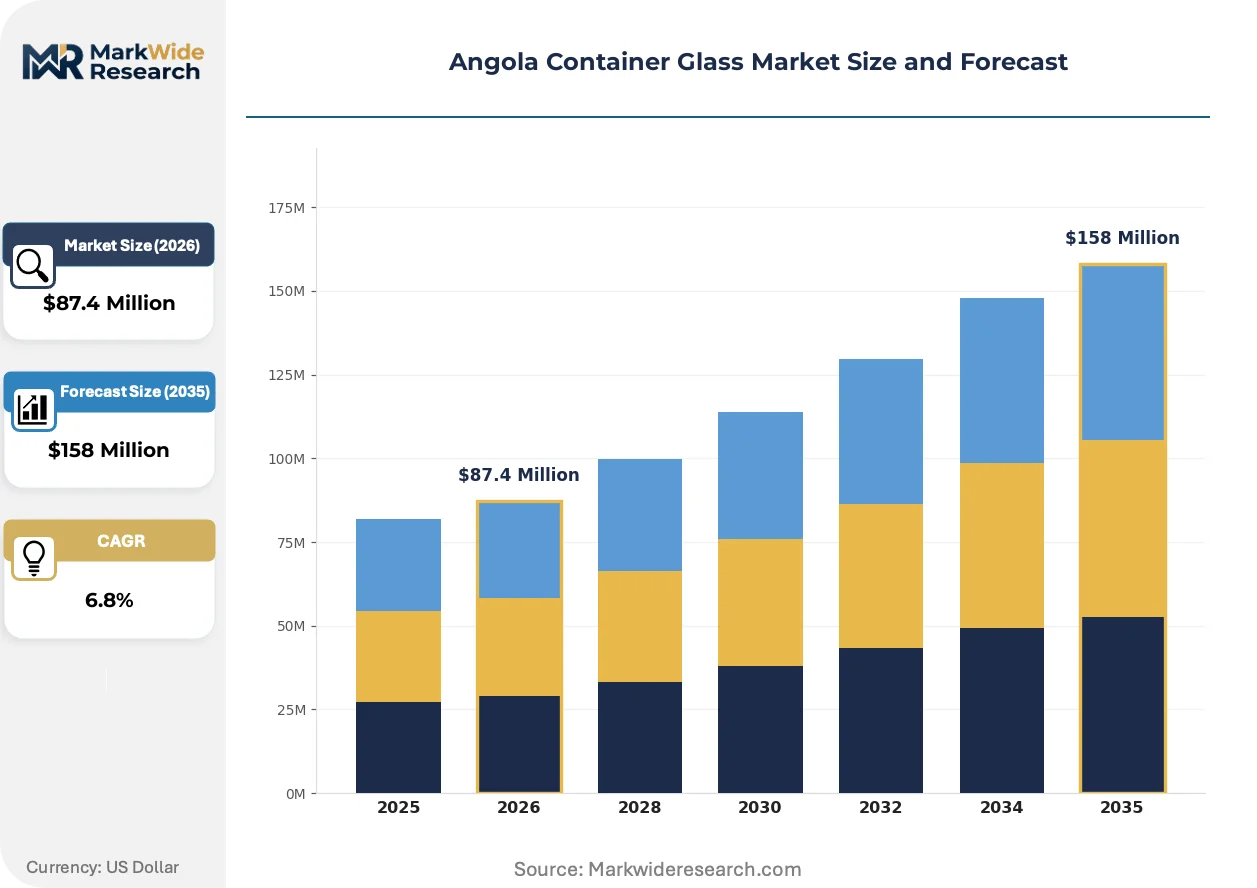
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Tumblers, Jugs End User: Beverage Industry, Food Sector, Pharmaceuticals, Cosmetics Application: Packaging, Storage, Transportation, Distribution Color: Clear, Amber, Green, Frosted |
| Companies Covered | Beta Glass Plc, Ardagh Group S.A., EMBALVIDRO-INDÚSTRIA (SU), LDA, Sotancro - Embalagem de Vidro SA, Newrest Angola, Vidrul - Angolan Glass Factory, Didactic Africa, United Glass Containers Company, Krones Angola Lda., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Angola Container Glass Market Trends and Innovations
Container glass manufacturing in Angola is pivoting toward precision forming and regulatory-grade certification as domestic production displaces import dependency. Three converging developments are restructuring competitive capability requirements.
Electromagnetic boosting systems are miniaturizing energy profiles in glass melting operations. Vidrul and emerging furnace operators are retrofitting oxy-fuel combustion with electric auxiliary heating to reduce natural gas intensity. This hybrid architecture is compressing per-ton energy costs while enabling finer temperature control for pharmaceutical-grade borosilicate production.
Angola's national standards body is tightening food-contact glassware specifications alongside parallel pharmaceutical packaging mandates. These overlapping compliance frameworks are elevating quality thresholds for both imports and local production. Amber bottle segments serving drug distribution channels face the steepest requalification requirements, driving capital allocation toward inspection and traceability systems.
Beverage bottlers are consolidating supplier relationships around single-source domestic partnerships with technical service attachments. Long-term offtake agreements now bundle furnace capacity reservation with format development support, displacing spot procurement from fragmented import channels. This contractual evolution is most visible among premium beer and spirits packagers in the greater Luanda industrial corridor.
Angola Container Glass Market Segmentation
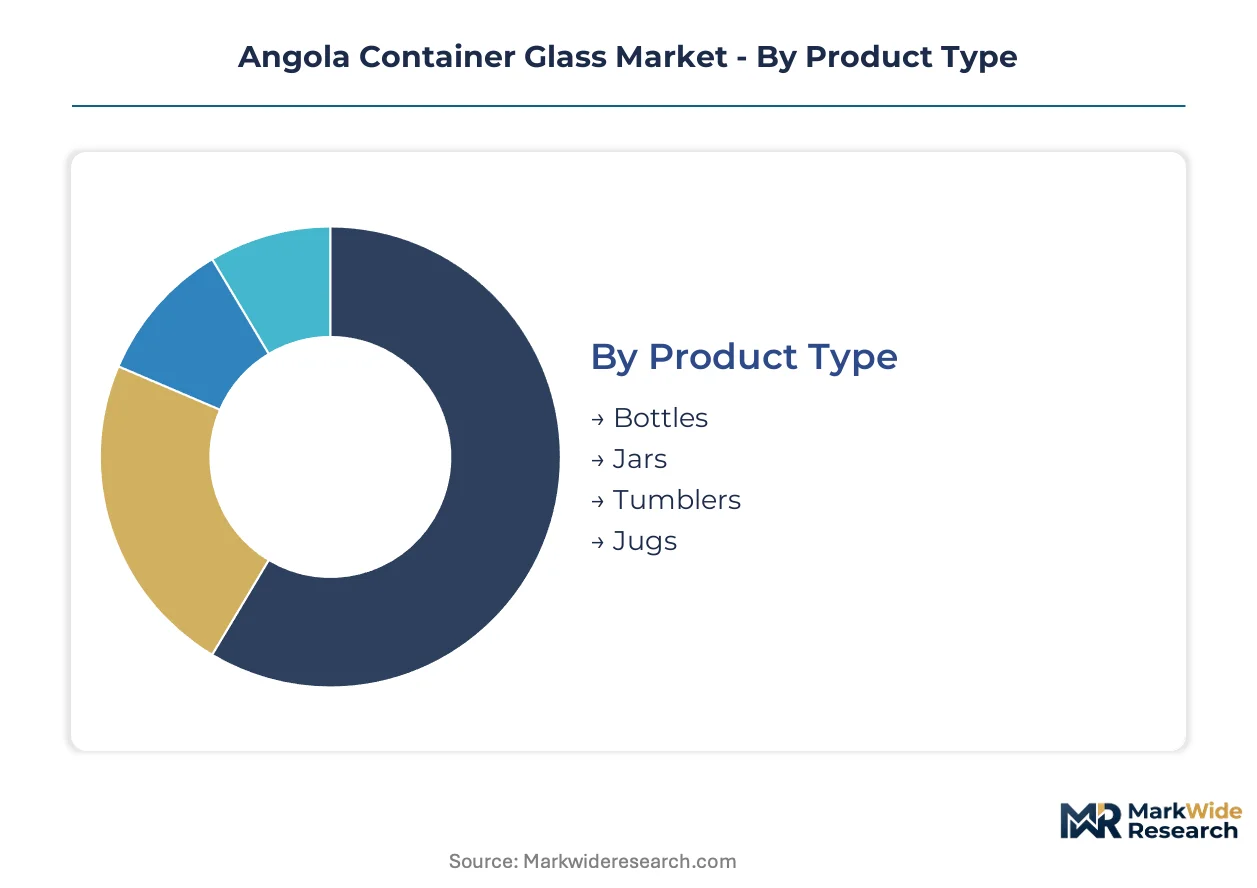
Container glass demand in Angola fragments across product geometry, end-use certification requirements, and color-dependent UV protection specifications. Each segmentation axis carries distinct margin profiles and regulatory compliance burdens that shape supplier capability investments.
Product Type:
Angola's national pharmaceutical regulator and food-contact standards body enforce divergent dimensional tolerances across vessel categories, creating specification-driven sourcing patterns.
- Bottles:Narrow-neck cylindrical vessels with 18-28 mm finish diameters dominate pharmaceutical and premium beverage applications. Luanda-based bottlers are consolidating long-term offtake agreements for amber and clear formats as import substitution mandates compress supply chains toward Vidrul's domestic furnace output.
- Jars:Wide-mouth containers with 43-110 mm openings serve regional food processors in Benguela province's emerging agro-industrial clusters. EMBALVIDRO-INDÚSTRIA specializes in custom jar formats, though capacity constraints force many processors to maintain parallel import channels for standard sizes.
- Tumblers:Straight-walled drinking vessels without applied finishes occupy limited commercial volume, primarily serving hospitality procurement in Luanda's urban corridor.
- Jugs:Large-format handled containers for bulk liquid distribution face competition from plastic alternatives in cost-sensitive segments.
Established volume favors bottles; emerging adoption favors jars as food processing localizes.
End User:
Customer procurement patterns diverge sharply between regulated pharmaceutical channels and price-sensitive beverage segments.
- Beverage Industry:Beer and soft drink bottlers in the greater Luanda industrial corridor generate the largest unit demand, with premium lines requiring UV-blocking amber or cobalt-tinted glass. Long-term furnace capacity reservations are displacing spot procurement from Nigerian suppliers.
- Food Sector:Processors of palm oil, preserves, and condiments in Benguela and Huíla provinces drive jar demand, though many lack localized supply and rely on imported palletized goods.
- Pharmaceuticals:USP-compliant amber bottles for drug distribution face 18-24 month certification timelines, concentrating demand among Beta Glass Plc's Nigerian-sourced premium offerings and Vidrul's upgrading domestic lines.
- Cosmetics:Frosted and decorative treatments are gaining traction as brands seek tactile shelf differentiation in Luanda's retail environment.
Beverage procurement concentrates volume; pharmaceutical certification elevates margin capture.
Application:
Functional use cases determine performance specifications for thermal shock resistance and hermetic integrity.
- Packaging:Primary containment applications demand 2-5 mm wall thickness and 42°C thermal shock tolerance. Pharmaceutical and premium beverage packagers prioritize hermetic seal reliability over unit cost.
- Storage:Secondary warehousing applications emphasize stack strength and pallet efficiency, with food processors optimizing for bulk handling in Benguela's emerging distribution hubs.
- Transportation:Export-oriented glassware requires enhanced impact resistance for multi-modal logistics through Luanda port infrastructure.
- Distribution:Last-mile delivery formats prioritize lightweighting to reduce fuel costs across Angola's road network.
Packaging commands specification investment; distribution drives lightweighting adoption.
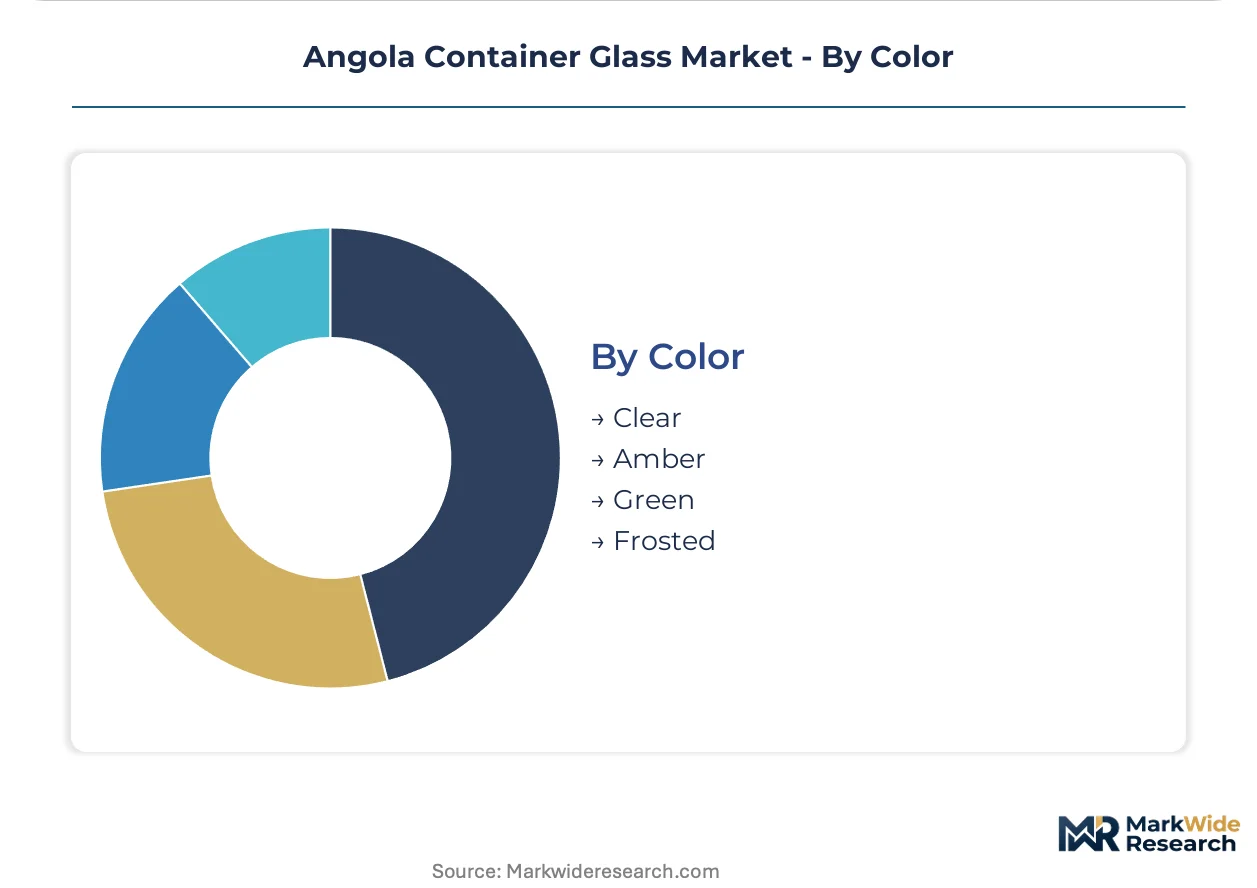
Color:
Light-blocking properties determine price positioning across pharmaceutical and beverage segments.
- Clear:Standard soda-lime silica without colorants dominates beverage volume in cost-sensitive soft drink and water segments, though offers minimal UV protection.
- Amber:Iron-sulfur amber chemistry blocks 90% of UV light below 450 nm, justifying premium positioning in pharmaceutical and beer applications where the national regulator mandates light protection for drug stability.
- Green:Chromium-tinted formats occupy niche positioning in wine and specialty beverage segments with moderate UV filtering requirements.
- Frosted:Acid-etched or molded matte surfaces serve cosmetics and premium spirits where tactile differentiation supports brand positioning.
Amber captures pharmaceutical premium; clear dominates beverage scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Angola's container glass trade balance tilts toward import dependency, with Nigerian and European suppliers capturing premium pharmaceutical and beverage segments while domestic furnace capacity struggles to match volume and certification standards. Import substitution mandates are compressing this gap, redirecting procurement toward Luanda-based production.
Luanda Province
Beverage bottlers and pharmaceutical packagers concentrate demand in Angola's capital corridor, where Vidrul operates the country's primary glass furnace. The national standards body enforces food-contact specifications that elevate local production thresholds. Industrial clusters in Viana and Cacuaco municipalities are absorbing capacity expansion from import displacement programs.
Benguela Province
Emerging agro-industrial food processors drive jar demand for palm oil and condiment packaging, though localized supply remains inadequate. Import substitution policies prioritize glass container manufacturing investments in southwestern Angola. The Lobito corridor industrial zone is attracting logistics infrastructure to support regional distribution networks.
Huíla Province
Agricultural processing hubs generate secondary container demand for food preservation and bulk liquid storage. The provincial government coordinates with national industrial development funds to attract packaging suppliers. Lubango's emerging distribution infrastructure connects southern agricultural zones to coastal export channels.
Huambo Province
Central highland food processors rely on imported glassware due to absent local furnace capacity, creating logistics cost penalties. National development programs target intermediate cities for industrial decentralization. The Caála industrial zone is designated for future packaging manufacturing investments under central planning frameworks.
Cabinda Province
Isolated enclave geography forces reliance on maritime imports through Congolese port infrastructure, inflating landed costs for container glass. Customs coordination protocols with neighboring states affect supply security. Offshore oil service operations generate niche demand for specialized chemical-resistant glassware.
Angola Container Glass Market Competitive Landscape
Listed multinationals compete with private domestic specialists across furnace scale and certification capability tiers. Market structure fragments between Nigerian supply anchors serving pharmaceutical channels, European technology providers, and emerging Angolan fabricators. Two archetypes dominate: import-dependent distributors with established regulatory relationships, and capital-intensive furnace operators pursuing vertical integration into raw material sourcing. Competitive dynamics center on long-term offtake contracting and pharmaceutical-grade certification attainment.
Within the import-dependent tier, Beta Glass Plc and Ardagh Group S.A. exemplify cross-border supply archetypes leveraging Nigerian and European manufacturing bases to serve Angolan pharmaceutical and premium beverage channels. Vidrul - Angolan Glass Factory occupies the domestic furnace operator position, representing capital-intensive localization strategy against import substitution policy tailwinds. These three entities anchor distinct competitive vectors: offshore premium supply, multinational technology access, and domestic capacity scaling.
| Leading Market Players |
|---|
| Beta Glass Plc |
| Ardagh Group S.A. |
| EMBALVIDRO-INDÚSTRIA (SU), LDA |
| Sotancro - Embalagem de Vidro SA |
| Newrest Angola |
| Vidrul - Angolan Glass Factory |
| Didactic Africa |
| United Glass Containers Company |
| Krones Angola Lda. |
| Others |
Pricing and Supply Chain Analysis
Vidrul's furnace utilization rates near Luanda anchor price floors across Angola's container glass sector, compressing margin structures for Nigerian imports while elevating domestic amber bottle premiums. Scale advantages in natural gas procurement and cullet recovery create defensive moats that reshape competitive positioning between local furnace operators and cross-border suppliers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that dominate Angola's container glass procurement. Three-tier pricing stratifies across USP-certified pharmaceutical amber, premium beverage clear and tinted formats, and economy-grade food jars. Cost compression in economy tiers intensifies because aluminum can substitution trials in single-serve beverage segments force glass packagers to absorb freight differentials. Food processors in Benguela province exhibit highest price sensitivity due to parallel plastic packaging alternatives, while pharmaceutical distributors accept premium positioning for certified borosilicate supply.
Supply Chain Analysis
Port congestion at Luanda's container terminal and irregular feeder vessel schedules from European refractory suppliers extend lead times for critical furnace components. Manufacturing concentration rests on Nigeria, Europe, and emerging Angolan domestic capacity for finished glassware, while raw material dependencies draw from silica sand deposits in Namibe province, imported soda ash from Kenya and Tanzania, and Nigerian cullet supplies. Single-source vulnerability concentrates in European-sourced forming machinery and oxy-fuel combustion systems. Distribution runs through palletized bulk delivery to Luanda industrial clusters, with emerging hub-and-spoke configurations reaching Benguela and Huíla provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Angola's container glass sector is navigating a cyclical recovery driven by import substitution mandates compressing procurement toward domestic furnace capacity. This policy tailwind creates differentiated opportunity sets across incumbent defenders, niche attackers, and capital deployers.
For Market Incumbents: Consolidate furnace capacity reservations through bundled technical service attachments that displace spot procurement channels. Deepen backward integration into Namibe silica sand quarries to secure raw material cost control against imported soda ash volatility. Aluminum can substitution in beverage single-serve formats and Nigerian cross-border supply persistence represent the primary margin threats requiring defensive contracting structures.
For New Entrants and Emerging Players: Differentiate on pharmaceutical-grade certification velocity, targeting the 18-24 month USP validation bottleneck that concentrates premium amber bottle supply among limited qualified sources. Benguela province's agro-industrial jar demand offers the most penetrable white-space, with food processors currently maintaining parallel import channels due to inadequate local supply. A technical partnership model bundling format development with furnace capacity reservation provides the strongest go-to-market angle against established Nigerian suppliers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors domestic furnace operators with electromagnetic boosting retrofits and oxy-fuel hybrid architectures that compress per-ton energy costs. Long-term viability across a 5-10 year window hinges on regulatory enforcement durability for import substitution and environmental compliance escalation. The signal to watch is pharmaceutical certification queue depth at Angola's national standards body, as validation backlog inflections indicate demand pull ahead of capacity response.
| Strategic Initiative | Industry Significance |
|---|---|
| Electromagnetic Boosting Retrofit | Hybrid oxy-fuel electric heating reduces natural gas intensity for borosilicate production at Vidrul's Luanda furnace. |
| Pharmaceutical Certification Investment | USP-compliant amber bottle qualification opens premium drug packaging channels closed to uncertified imports. |
| Silica Sand Backward Integration | Captive Namibe quarry supply insulates margin structures from imported raw material cost volatility. |
| Benguela Logistics Hub Development | Lobito corridor infrastructure expansion enables jar supply localization for southwestern food processors. |
| Cullet Recovery Network Buildout | Post-consumer glass collection systems satisfy environmental compliance mandates while reducing virgin material costs. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with furnace operations managers at Vidrul, procurement leads at Luanda-based beverage bottlers, pharmaceutical packaging specialists at Beta Glass Plc's Nigerian operations, and food processing executives in Benguela province. Secondary validation drew from Angola's national standards body regulatory filings, SADC trade protocol documentation, customs import records for container glass categories, and industrial development fund disbursement reports. Bottom-up volume modeling from end-use segment demand and top-down capacity assessments from furnace operators were triangulated to converge on market sizing.
Across the analysis window, projections rest on analytical frameworks segmenting by product geometry, end-use certification tier, color-dependent UV protection specification, and regional industrial corridor concentration. CAGRs were derived from elasticity modeling against beverage production growth, pharmaceutical distribution expansion, and food processing localization trends. Key forecast inputs include natural gas price scenarios affecting furnace economics and import substitution policy enforcement intensity.
The analysis sits within stated boundaries; outcomes outside sustained regulatory commitment to domestic production preference or severe LNG price dislocation would require recalibration. Forecasts reflect documented assumptions around certification timeline stability, equipment import lead time normalization, and SADC trade access continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
South Africa Container Glass Market
Glass Packaging
Global Glass Packaging Rectifier Diode Market
Glass Packaging
Amber Glass Packaging Market
Glass Packaging
Thin Wall Glass Container Market
Glass Packaging
Sweden Container Glass Market
Glass Packaging
Glass Frosting for Packaging Market
Glass Packaging
Thailand Container Glass Market
Glass Packaging
Europe Glass Packaging Market
Glass Packaging
Paragon Glass Jar Market
Glass Packaging
Hermetic Jars Market
Glass Packaging
Chile Container Glass Market
Glass Packaging
India Glass Packaging Market
Glass Packaging
UAE Container Glass Market
Glass Packaging
China Glass Container Packaging Market
Glass Packaging
Slovakia Container Glass Market
Glass Packaging
Czech Republic Container Glass Market