
 Africa Glass Bottles and Containers Market | 2026-2036
Africa Glass Bottles and Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Glass Bottles and Containers Market Outlook
The African Union's green recovery frameworks and national plastic restriction policies is rebalancing procurement priorities across beverage and pharmaceutical supply chains. Beta Glass PLC leverages its Nigerian manufacturing base to serve West African brewers and soft-drink bottlers with returnable bottle systems. Consol Glass anchors Southern African demand through integrated container production and cullet recycling infrastructure. Société d'Exploitation de Verreries au Maroc competes in North African pharmaceutical and cosmetics packaging with specialized amber and flint glass capabilities.
Africa glass bottles and containers comprise silica-soda-lime formulations manufactured through blow-and-blow or press-and-blow forming, with thermal shock resistance and chemical inertness making them essential for carbonated beverages, sterile pharmaceuticals, and reactive chemicals. Clear bottles dominate beverage packaging volumes due to brand visibility requirements, while amber bottles command premium positioning in pharmaceutical and personal care segments where UV protection preserves product integrity. The food and beverage end-user category sustains the largest demand share, though cosmetics applications are expanding fastest among medium-capacity jars and custom-sized specialty containers.
Nigeria's National Environmental Standards and Regulations Enforcement Agency, South Africa's Department of Forestry, Fisheries and the Environment, and Egypt's Environmental Affairs Agency each enforce packaging waste directives that elevate glass recycling targets and restrict competing plastic formats. Kenya's National Environment Management Authority implements strict single-use plastic prohibitions that directly expand glass container demand in food service and household product distribution. Stakeholders must monitor evolving extended producer responsibility schemes and harmonization of regional standards to anticipate compliance costs and localized supply advantages.
Market Dynamics
Returnable glass bottle systems are rebalancing procurement across African beverage supply chains as Nigerian brewers and North African pharmaceutical manufacturers expand domestic melting capacity to reduce import dependency.
Growth Catalysts
- Kenya's single-use plastic prohibitions:The National Environment Management Authority enforces strict bans that directly expand glass container demand in food service and household product distribution channels.
- South Africa's extended producer responsibility regulations:The Department of Forestry, Fisheries and the Environment mandates packaging waste directives that elevate glass recycling targets and restrict competing plastic formats.
- Pharmaceutical UV protection requirements:Amber glass capabilities are commanding premium positioning as sterile pharmaceutical and personal care segments prioritize chemical inertness and UV barrier properties.
Market Restraints
- Silica and soda ash input cost volatility:Raw material price fluctuations constrain margin stability for domestic manufacturers dependent on imported batch materials.
- Egyptian manufacturing concentration risk:North African supply clusters face single-point vulnerability from energy subsidy disruptions and natural gas supply interruptions.
- Lightweight PET substitution in beverage packaging:Plastic formats continue pressuring glass volume in cost-sensitive soft-drink segments despite regulatory headwinds.
Strategic Opportunities
- West African pharmaceutical packaging expansion:Nigeria's domestic manufacturing base offers regional distribution advantages for sterile injectable and oral solid dose containers.
- Cosmetics specialty jar demand:Medium-capacity custom-sized containers represent the fastest-growing application category among personal care brands.
- Integrated cullet recycling infrastructure:Closed-loop glass recovery systems create localized supply advantages under evolving extended producer responsibility schemes.
Industry Challenges
- Furnace rebuild capex intensity:Regenerative melting technology upgrades require substantial capital deployment with extended payback periods.
- Harmonization delays across regional standards:Divergent national packaging waste directives complicate compliance cost forecasting for multi-country operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Glass Bottles and Containers Market |
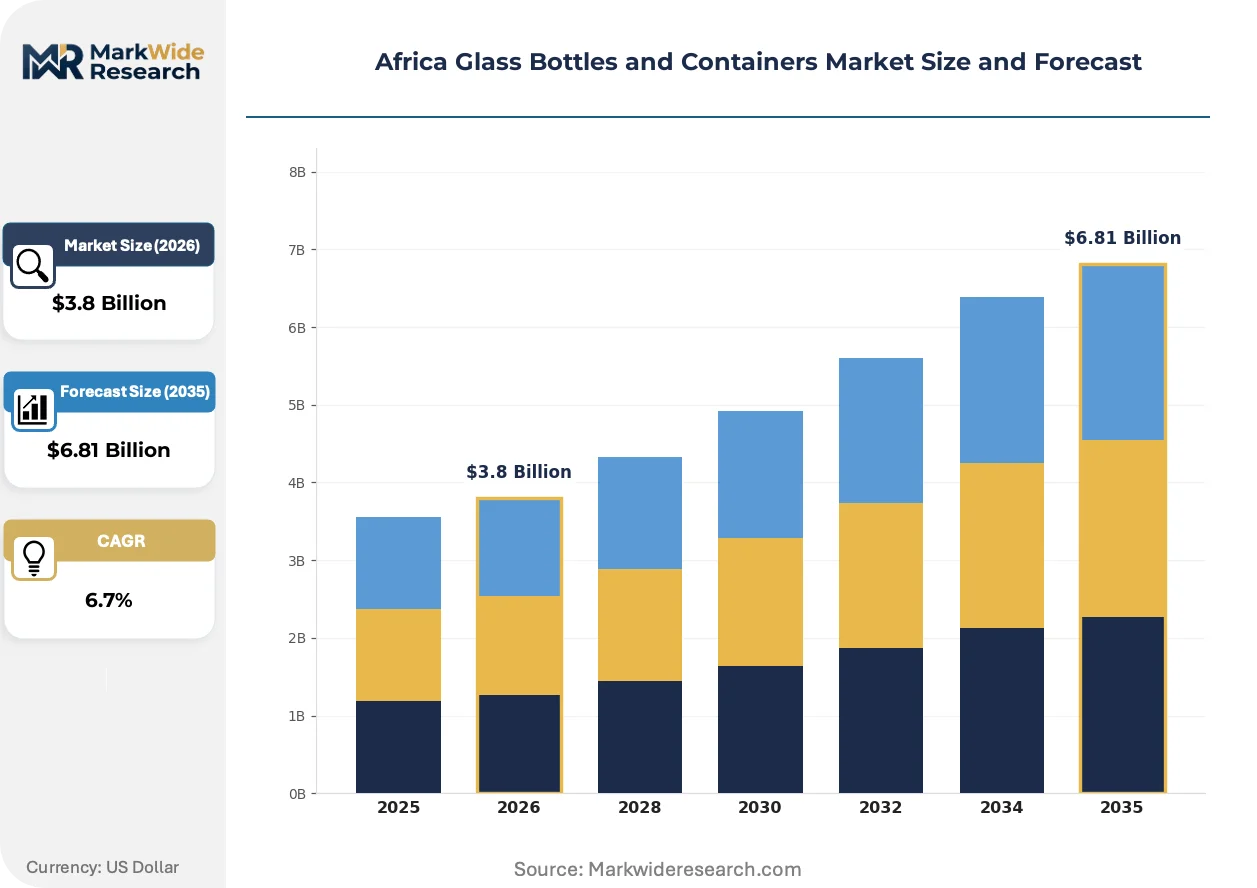
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amber Bottles, Clear Bottles, Green Bottles, Jars End User: Food and Beverage, Pharmaceuticals, Cosmetics, Chemicals Application: Beverage Packaging, Food Packaging, Personal Care, Household Products Size: Small Capacity, Medium Capacity, Large Capacity, Custom Sizes |
| Companies Covered | Beta Glass PLC, Société d'Exploitation de Verreries au Maroc, Consol Glass, Glass Force Ltd., Middle East Glass Manufacturing Company, Nampak Glass, United Glass Containers Company, Tunisia Glass Company, Ardagh Group, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Glass Bottles and Containers Market Strategic Shifts
Electrification of melting operations and lightweighting formulations are compressing energy intensity benchmarks while regulatory pressure accelerates format substitution away from competing materials.
Advanced oxy-fuel combustion technology is consolidating furnace efficiency standards across African container glass manufacturing. Nigerian and Egyptian producers are retrofitting regenerative systems to reduce natural gas consumption per ton of melted glass. This thermal efficiency gain is consolidating competitive positioning toward operators with capital access for furnace modernization.
South Africa's extended producer responsibility regulations are mandating minimum recycled content thresholds and producer-funded collection infrastructure. The Department of Forestry, Fisheries and the Environment enforces these directives through licensing conditions on packaging manufacturers. Food and beverage segments are responding by integrating returnable bottle systems with deposit-return schemes to meet compliance targets.
Brand visibility requirements are intensifying demand for high-clarity flint glass in premium beverage positioning. Major brewers and soft-drink bottlers are specifying custom bottle designs with embossed branding elements to differentiate shelf presence. This specification escalation is most visible in Nigerian and Egyptian metropolitan distribution networks serving formal retail channels.
Africa Glass Bottles and Containers Market Segmentation
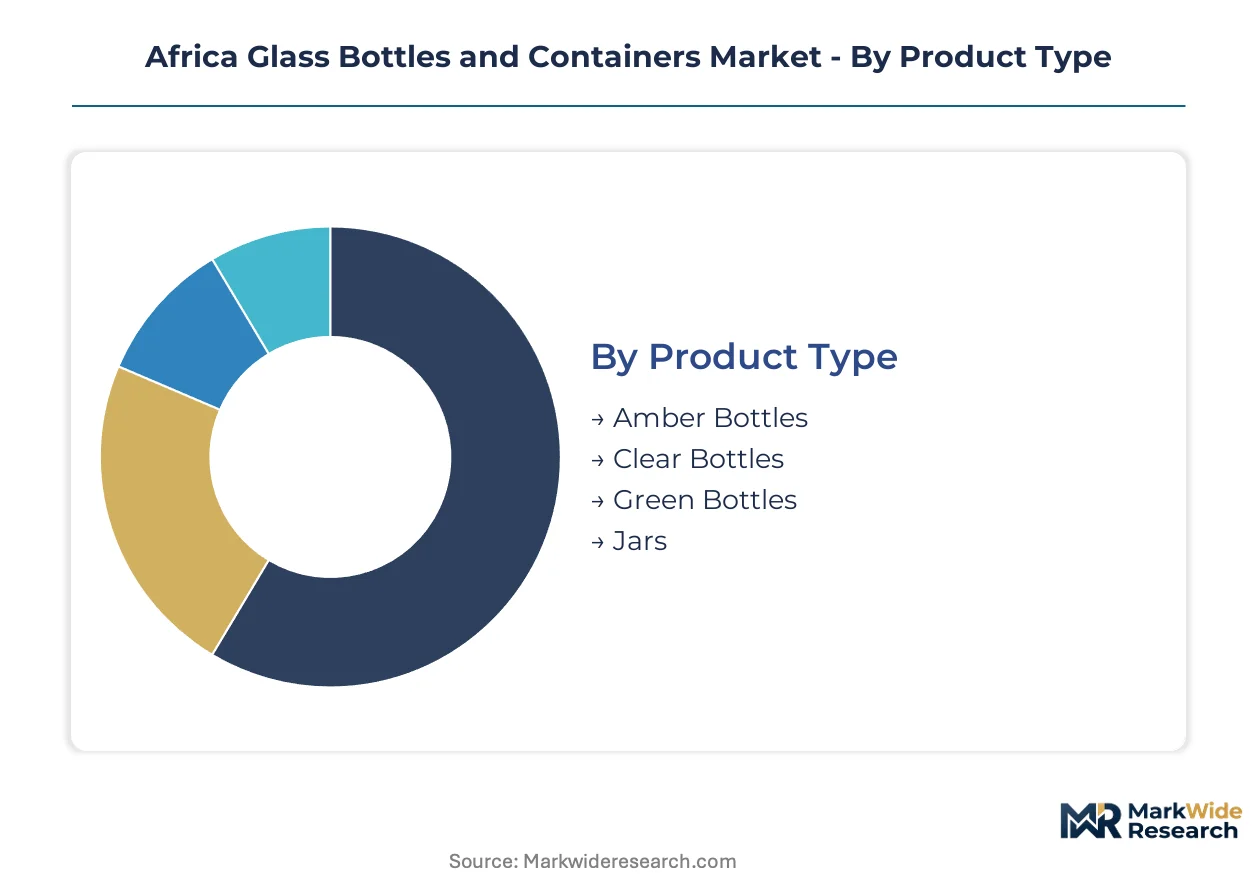
Glass container procurement across Africa fragments across color chemistry, end-use specifications, and capacity requirements. Each dimension carries distinct furnace configuration and mold investment implications for domestic manufacturers balancing import substitution against export competitiveness.
Product Type:
Capital intensity peaks with specialized color chemistry requiring dedicated furnace campaigns and controlled oxidation protocols.
- Amber Bottles:Iron-sulfur-carbon formulations absorb UV wavelengths below 450nm, protecting photosensitive pharmaceutical actives and personal care formulations. Nigerian and Egyptian pharmaceutical clusters specify amber glass for sterile injectables and oral solid doses where chemical inertness prevents drug-container interaction. Most installed capacity flows through Clear Bottles. Expansion is steepest in Amber Bottles.
- Clear Bottles:Low-iron flint glass maximizes brand visibility for premium beverage positioning. South African brewers and North African soft-drink bottlers specify high-clarity specifications with embossed branding elements for formal retail channel differentiation.
- Green Bottles:Chromium-iron coloration provides moderate UV protection with distinctive shelf presence. Limited African production concentrates in wine and specialty beer exports to European markets.
- Jars:Wide-mouth press-and-blow configurations serve food preservation and cosmetics applications. Medium-capacity cosmetic jars are climbing the fastest among personal care brand specifications.
Color campaign flexibility determines furnace utilization rates across multi-product African facilities.
End User:
Volume concentration and margin structure diverge sharply between commodity beverage flows and specialized pharmaceutical compliance requirements.
- Food and Beverage:Carbonated soft drinks, beer, and food preservation dominate tonnage throughput. Returnable bottle systems in Nigeria and Kenya create closed-loop demand with deposit-return infrastructure investments.
- Pharmaceuticals:Sterile injectables, oral solid doses, and liquid formulations require Type I borosilicate or treated soda-lime compliance. Egypt's domestic manufacturing expansion targets regional export to Sub-Saharan markets.
- Cosmetics:Premium skincare and fragrance brands specify custom jar geometries with thick-base stability. South African formulators drive specialty container specifications.
- Chemicals:Reactive and corrosive substance containment leverages chemical inertness against plastic permeation. Industrial solvent and agrochemical distribution in North Africa sustains demand.
Beverage procurement absorbs the largest furnace capacity share. Pharmaceutical compliance requirements command the highest per-unit margins.
Application:
Distribution channel specifications determine neck finish tolerances, label adhesion properties, and palletization strength requirements.
- Beverage Packaging:Carbonated pressure retention and crown cork compatibility define technical specifications. Nigerian and Egyptian metropolitan distribution networks prioritize lightweighting with maintained vertical load strength.
- Food Packaging:Hermetic seal integrity for pasteurization and vacuum processes drives jar and bottle selection. Kenya's single-use plastic prohibitions are expanding glass substitution in food service channels.
- Personal Care:Pump dispenser compatibility and finger-grip ergonomics influence mold design. Premium positioning in South African formal retail demands distinctive silhouette differentiation.
- Household Products:Chemical resistance and child-resistant closure integration serve cleaning and maintenance formulations. Medium-capacity specifications balance handling convenience with consumption economics.
Beverage applications concentrate melting capacity deployment. Personal care specifications are diversifying fastest across custom geometries.
Size:
Mold inventory depth and changeover flexibility determine cost competitiveness across volume tiers.
- Small Capacity:Single-serve pharmaceutical vials and cosmetic sampler formats require precision neck finish tolerances. High-speed forming lines in Egyptian facilities target export markets.
- Medium Capacity:Standard beverage and food service formats balance material efficiency with handling ergonomics. Returnable bottle systems concentrate in this range for Nigerian brewers.
- Large Capacity:Bulk chemical and institutional food service containers prioritize vertical load strength for palletized distribution. Limited African production relies on imported formats.
- Custom Sizes:Proprietary brand differentiation through unique silhouettes and embossed elements. South African extended producer responsibility regulations incentivize standardization to streamline recycling sortation.
Medium capacity formats absorb the majority of furnace output. Custom size specifications are expanding most quickly among premium beverage and cosmetics positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Glass container manufacturing in Africa traces its commercial roots to colonial-era breweries and pharmaceutical packaging facilities established in the early twentieth century. Egyptian and South African melting operations scaled first, creating furnace technology bases that Nigerian and Kenyan producers later adapted for regional beverage and food service markets.
Nigeria
Lagos-based Beta Glass PLC anchors West African supply through integrated returnable bottle systems serving Nigerian Breweries and Coca-Cola HBC. The National Environmental Standards and Regulations Enforcement Agency enforces packaging waste directives that elevate glass recycling targets above competing plastic formats. Domestic melting capacity in Agbara Industrial Estate now supplies Ghanaian and Ivorian distributors with medium-capacity beverage containers.
South Africa
Consol Glass operates Southern Africa's largest container glass furnace complex from Wadeville, Gauteng, serving SABMiller and Distell with flint and amber specifications. The Department of Forestry, Fisheries and the Environment mandates extended producer responsibility through licensing conditions requiring minimum recycled content thresholds. Cape Town's cullet collection infrastructure feeds closed-loop recovery systems meeting compliance targets for formal retail channel distribution.
Egypt
Pharmaceutical packaging demand concentrates in Cairo and Alexandria, where Société d'Exploitation de Verreries au Maroc competes with domestic producers for sterile injectable container contracts. The Environmental Affairs Agency enforces industrial emissions standards that accelerate furnace modernization toward oxy-fuel combustion technology. Sharm El-Sheikh's cosmetics manufacturing cluster drives specialty amber bottle specifications for UV-sensitive skincare formulations.
Kenya
Nairobi's food service distributors are expanding glass substitution following National Environment Management Authority prohibitions on single-use plastics in hospitality channels. Domestic jar production from Thika-based facilities supplies East African Community markets with food preservation formats. Mombasa port logistics enable Ethiopian and Ugandan re-export of medium-capacity containers for brewing and soft-drink bottling operations.
Morocco
Casablanca's pharmaceutical and cosmetics packaging sector leverages specialized amber and flint capabilities for European export markets. Domestic regulators align industrial licensing with EU REACH compliance frameworks to maintain pharmaceutical container certification. Tangier Med port infrastructure supports Moroccan glass container transshipment to West African Francophone markets seeking compliant pharmaceutical packaging.
Africa Glass Bottles and Containers Market Competitive Environment
Capital-heavy furnace operators compete with asset-light trading houses and import-dependent distributors across African container glass markets. The vendor base stratifies between integrated manufacturers with captive melting capacity and regional distributors sourcing from Egyptian or European production bases. Three archetypes dominate: furnace-owning multinationals with African subsidiaries, domestic integrated producers serving national markets, and specialized pharmaceutical packaging specialists with amber glass campaigns. Competitive moves concentrate on furnace rebuild cycles for thermal efficiency gains and strategic partnerships with beverage bottlers for returnable system deployment.
Among Nigerian and Southern African integrated producers, Beta Glass PLC, Consol Glass, and Société d'Exploitation de Verreries au Maroc occupy positions representing distinct geographic anchoring strategies. Beta Glass exemplifies West African manufacturing concentration with regional distribution reach. Consol Glass represents Southern African scale advantages through Wadeville furnace infrastructure. Société d'Exploitation de Verreries au Maroc sits within North African specialist positioning for pharmaceutical and cosmetics color chemistry requirements.
| Leading Market Players |
|---|
| Beta Glass PLC |
| Société d'Exploitation de Verreries au Maroc |
| Consol Glass |
| Glass Force Ltd. |
| Middle East Glass Manufacturing Company |
| Nampak Glass |
| United Glass Containers Company |
| Tunisia Glass Company |
| Ardagh Group |
| Others |
Value Chain & Pricing Dynamics
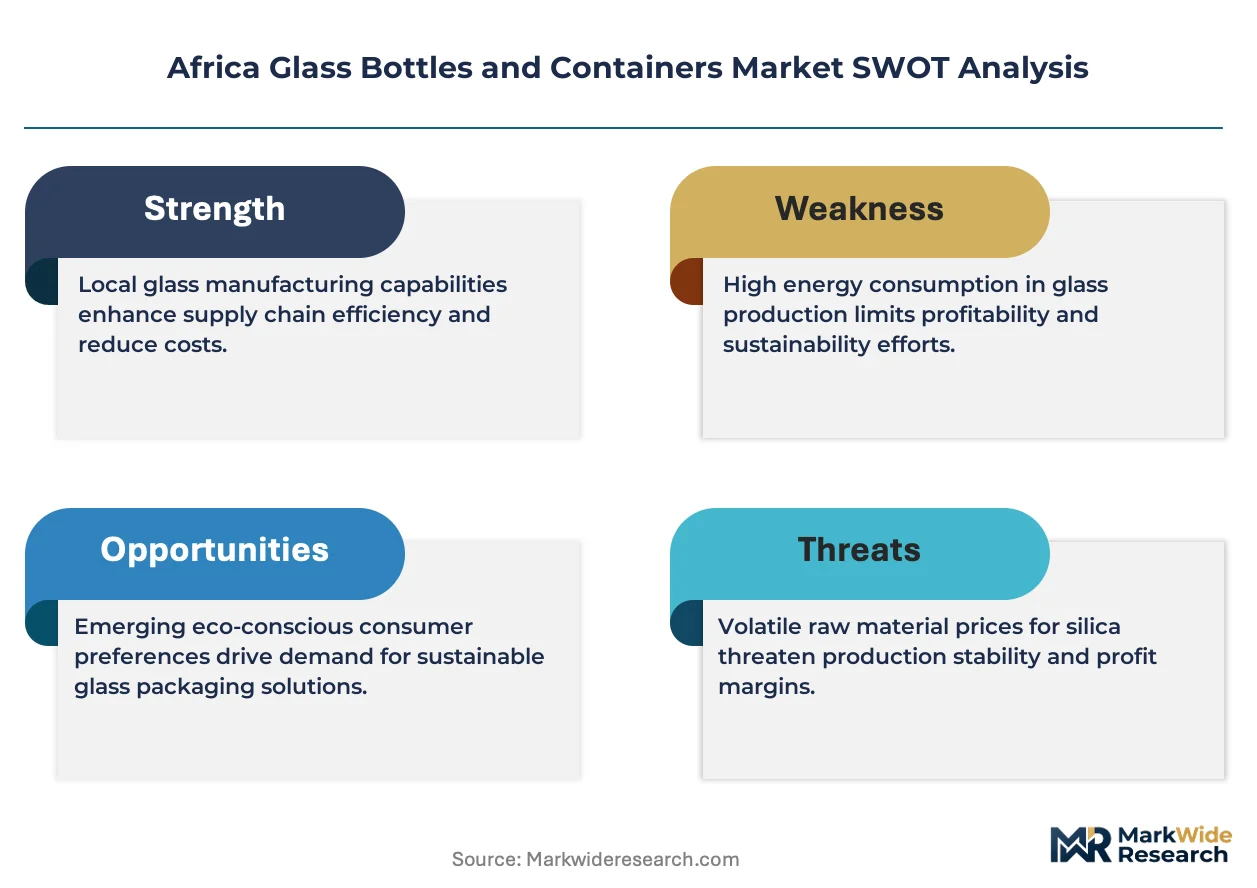
Captive furnace ownership across Nigerian and Egyptian manufacturing clusters anchors both supply security and pricing power for domestic container glass producers. Beta Glass PLC and Société d'Exploitation de Verreries au Maroc leverage in-house melting capacity to offset imported batch material volatility while commanding premium positioning in pharmaceutical amber specifications.
Pricing Analysis
Contract-based long-term offtake agreements with Nigerian Breweries and Coca-Cola HBC dominate volume procurement, locking in furnace utilization across multi-year horizons. Price differentiation separates UV-protective amber pharmaceutical grades from commodity flint beverage formats, with certification to Egypt's Environmental Affairs Agency standards commanding additional positioning. Pricing pressure stems from soda ash and silica import cost volatility pressuring margin stability at non-integrated operators. Cost-sensitive soft-drink bottlers exhibit highest price sensitivity, while sterile pharmaceutical manufacturers prioritize compliance over unit economics.
Supply Chain Analysis
Skilled furnace operations talent concentrates in Wadeville, Lagos, and Cairo, where generational technical expertise sustains regenerative melting campaigns. Raw material sourcing draws from imported Egyptian silica sand, Kenyan soda ash transshipments, and South African cullet recovery networks. Single-source vulnerability runs through natural gas supply interruptions to Egyptian production clusters. Distribution runs through regional beverage bottler partnerships with deposit-return infrastructure investments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Pharmaceutical and cosmetics brands are shifting procurement toward UV-protective amber specifications that command structural premium positioning over commodity beverage formats.
For Market Incumbents: Extend furnace modernization programs to oxy-fuel combustion technology, reducing natural gas intensity per ton while meeting South Africa's extended producer responsibility recycled content thresholds. Deepen backward integration into cullet collection infrastructure to defend margin position against imported batch material volatility. Prioritize amber glass campaign flexibility to capture pharmaceutical demand expansion in Cairo and Lagos clusters. For New Entrants and Emerging Players: Begin with specialty cosmetic jar specifications in medium-capacity formats, where South African personal care brands seek distinctive silhouette differentiation with limited incumbent mold inventory. Target East African Community markets through Mombasa port logistics for Ethiopian and Ugandan re-export opportunities. Lead with custom embossing capabilities and rapid mold turnaround to penetrate premium beverage positioning in Nigerian metropolitan retail channels. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale furnace operators with captive cullet recycling infrastructure because extended producer responsibility schemes are consolidating compliance advantages toward integrated producers. Five-to-ten year viability favors operators with thermal efficiency upgrade capital access and regional distribution partnerships. Watch Egyptian natural gas subsidy policy direction as inflection indicator for North African manufacturing cost competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Modernization to Oxy-Fuel Combustion | Beta Glass PLC and Egyptian producers reduce natural gas consumption per melted ton while meeting Environmental Affairs Agency emissions standards. |
| Integrated Cullet Recycling Infrastructure | Consol Glass's Wadeville closed-loop recovery systems satisfy South Africa's Department of Forestry, Fisheries and the Environment licensing conditions. |
| Amber Glass Campaign Expansion | Société d'Exploitation de Verreries au Maroc captures pharmaceutical UV-protection demand from Cairo sterile injectable manufacturers. |
| Returnable Bottle System Deployment | Nigerian Breweries and Coca-Cola HBC partnerships lock in medium-capacity furnace utilization through deposit-return infrastructure. |
| Cosmetic Specialty Jar Capacity Addition | Thika-based facilities supply East African Community markets with fastest-growing personal care container specifications. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with furnace operations managers, beverage procurement directors, pharmaceutical packaging engineers, and regulatory compliance officers at Nigeria's National Environmental Standards and Regulations Enforcement Agency with secondary validation from customs trade records, industrial emissions filings, and extended producer responsibility licensing databases. Bottom-up capacity assessments at Agbara Industrial Estate and Wadeville furnace complexes triangulated against top-down demand modeling from beverage bottler volume disclosures.
Segment-weighting applied product type, end user category, and application dimensions across the projection horizon, with color chemistry campaigns and returnable system penetration modeled as industry-specific demand drivers. CAGRs derived from furnace capacity expansion pipelines, regulatory enforcement timelines, and substitution elasticity estimates for plastic format displacement under Kenya's National Environment Management Authority prohibitions.
Several conditions sit outside the modeled scope, including Egyptian energy subsidy policy reversals, harmonization delays across African Union packaging waste directives, and unforeseen lightweight PET technology breakthroughs. Forecasts reflect documented assumptions regarding furnace rebuild completion schedules and regional trade flow stability. Material deviation in natural gas pricing or extended producer responsibility enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Glass Growlers Market
Glass Packaging
United Kingdom (UK) Glass Bottles and Containers Market
Glass Packaging
APAC Glass Bottles/Containers Market
Glass Packaging
Dosing Bottles Market
Glass Packaging
Glass Decanters Market
Glass Packaging
Russia Container Glass Market
Glass Packaging
Thailand Container Glass Market
Glass Packaging
Russia Glass Packaging Market
Glass Packaging
Italy Container Glass Market
Glass Packaging
Congo Container Glass Market
Glass Packaging
Glass Bottles and Jars Decoration Market
Glass Packaging
Europe Glass Packaging Market
Glass Packaging
United Kingdom Glass Packaging Market
Glass Packaging
Spain Packaging Market
Glass Packaging
Oman Container Glass Market
Glass Packaging
Glass Frosting for Packaging Market