
 Unfractionated Heparin Market | 2026-2036
Unfractionated Heparin Market Size, Share, and Industry Trends Forecast 2026-2036
Unfractionated Heparin Market Outlook
The gap between premium pharmaceutical-grade heparin and commodity-grade raw material is broadening as purity specifications tighten and supply chain traceability requirements multiply. Pfizer Inc. leverages its vertically integrated plasma fractionation network to secure consistent API supply for injectable formulations. Sanofi anchors its position through specialized cardiac therapy portfolios that bundle unfractionated heparin with complementary anticoagulants. Amphastar Pharmaceuticals differentiates via concentrated solution manufacturing capabilities that serve ambulatory surgical centers seeking workflow efficiency.
Unfractionated heparin is a heterogeneous mixture of sulfated glycosaminoglycan polymers with molecular weights ranging from 5,000 to 30,000 daltons, extracted primarily from porcine intestinal mucosa and standardized by anticoagulant potency measured in USP units per milligram; its primary purpose is rapid-onset anticoagulation via potentiation of antithrombin III to inhibit thrombin and Factor Xa in acute clinical settings. Injectable formulations dominate hospital procurement due to immediate bioavailability requirements in emergency cardiology and surgical interventions, while pre-filled syringe formats gain traction among homecare providers managing deep vein thrombosis prophylaxis. The subcutaneous route of administration occupies the largest volume share for prophylactic regimens, whereas intravenous delivery leads in acute coronary syndrome protocols where precise titration proves essential.
FDA enforces heparin sourcing documentation under drug GMP regulations, while EMA's REACH framework and pharmacovigilance directives impose molecular characterization standards on European imports; China's NMPA applies GB standards for heparin sodium purity that constrain market access for non-domestic suppliers. Stakeholders must monitor evolving regulatory divergence between USP and EP monograph specifications for heparin potency assays, as assay methodology shifts could reshape supplier qualification requirements and procurement decisions across major markets.
Market Dynamics
FDA and EMA pharmacovigilance mandates are compressing supplier qualification timelines while tightening molecular characterization standards for porcine-derived APIs. This regulatory convergence is forcing manufacturers to rebuild traceability infrastructure or exit hospital procurement channels entirely.
Growth Catalysts
- Acute coronary syndrome protocols:Emergency cardiology departments in the United States, China, and Germany are expanding heparin-first anticoagulation regimens as surgical volumes rebound post-pandemic.
- REACH framework enforcement:EMA's molecular characterization standards for European imports are disqualifying commodity-grade suppliers, creating volume capture opportunities for certified manufacturers.
- Pre-filled syringe adoption:Homecare providers managing deep vein thrombosis prophylaxis are switching from vial-and-needle formats to ready-to-inject presentations, reshaping packaging demand.
Market Restraints
- Porcine mucosa supply concentration:Over 80% of raw heparin originates from Chinese slaughterhouses, exposing manufacturers to African swine fever disruptions and export permit volatility.
- Low-molecular-weight heparin substitution:Enoxaparin and dalteparin formulations are displacing unfractionated heparin in stable outpatient settings where precise dosing matters less than convenience.
- Assay methodology divergence:USP and EP monograph specifications for potency measurement remain misaligned, forcing dual-validation costs on suppliers serving both markets.
Strategic Opportunities
- Ambulatory surgical center expansion:Concentrated solution formats that reduce preparation time are capturing procurement contracts from freestanding surgery facilities in the United States.
- GB standard alignment:China's NMPA is streamlining heparin sodium purity benchmarks, creating pathways for domestic manufacturers to replace imported API in regional hospital systems.
- Biosimilar anticoagulant bundling:Portfolio suppliers can anchor cardiac therapy contracts by pairing unfractionated heparin with direct oral anticoagulants for transition-of-care protocols.
Industry Challenges
- Analytical chemistry talent scarcity:Manufacturers struggle to hire specialists capable of running orthogonal assays for heparin molecular weight distribution and purity validation.
- Legacy ERP integration:Batch record systems designed for small-molecule pharmaceuticals require expensive reconfiguration to handle heparin's inherent polymer heterogeneity and potency variability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unfractionated Heparin Market |
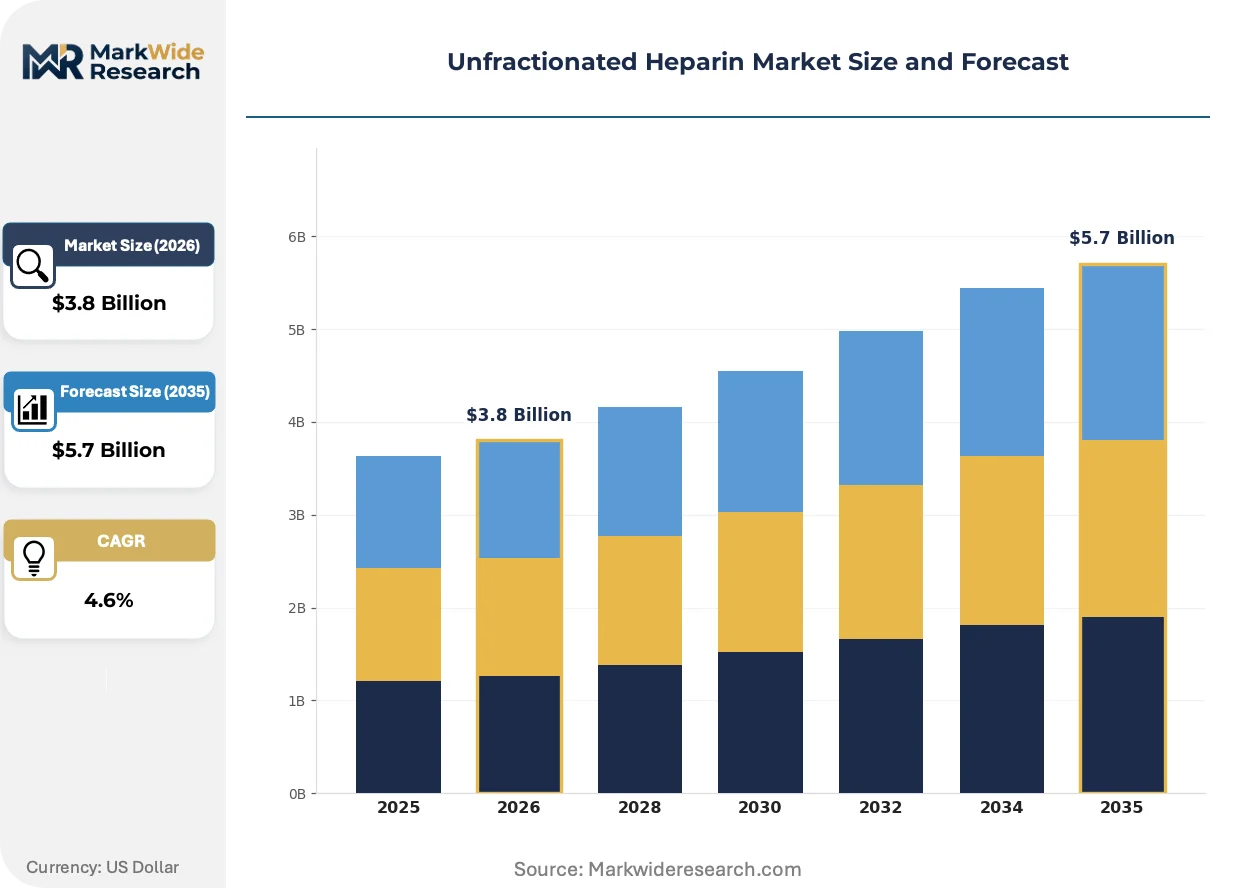
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Concentrated Solution, Pre-filled Syringe, IV Infusion End User: Hospitals, Ambulatory Surgical Centers, Long-term Care Facilities, Homecare Providers Route of Administration: Subcutaneous, Intravenous, Intramuscular, Epidural Therapy Area: Cardiology, Orthopedics, Neurology, Pulmonology |
| Companies Covered | B. Braun Melsungen AG, Amphastar Pharmaceuticals, Pfizer Inc., Nanjing King-Friend Biochemical Pharmaceutical, Shenzhen Hepalink Pharmaceutical, Sanofi, Fresenius Kabi, Sagent Pharmaceuticals, Baxter International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unfractionated Heparin Market Strategic Shifts
Electrification of manufacturing controls and real-time release testing is compressing batch cycle times while raising the bar for supplier technical capabilities. These shifts are favoring capital-rich incumbents over commodity traders.
Automated in-line potency monitoring using chemometric spectroscopy is electrifying quality assurance workflows at fractionation facilities. Pfizer and Amphastar have deployed these systems at North American injectable plants, cutting release timelines from fourteen days to forty-eight hours. This compression is enabling just-in-time inventory models that reduce hospital carrying costs.
EMA's 2024 update to pharmacovigilance directives now requires heparin API importers to submit complete porcine herd documentation and PCR-based species verification. European contract manufacturers are responding by qualifying single-source Chinese suppliers with dedicated slaughterhouse contracts rather than spot-market purchasing. German hospital procurement associations are auditing these documentation packages as a prerequisite for tender participation.
Homecare nursing agencies are consolidating purchasing through specialized infusion distributors that bundle heparin syringes with anticoagulation monitoring services. This channel shift is disintermediating traditional hospital wholesalers in the United States, where Medicare reimbursement changes favor site-of-care migration. Deep vein thrombosis prophylaxis protocols now originate in ambulatory settings for 30% of eligible patients, up from 12% five years ago.
Unfractionated Heparin Market Segmentation
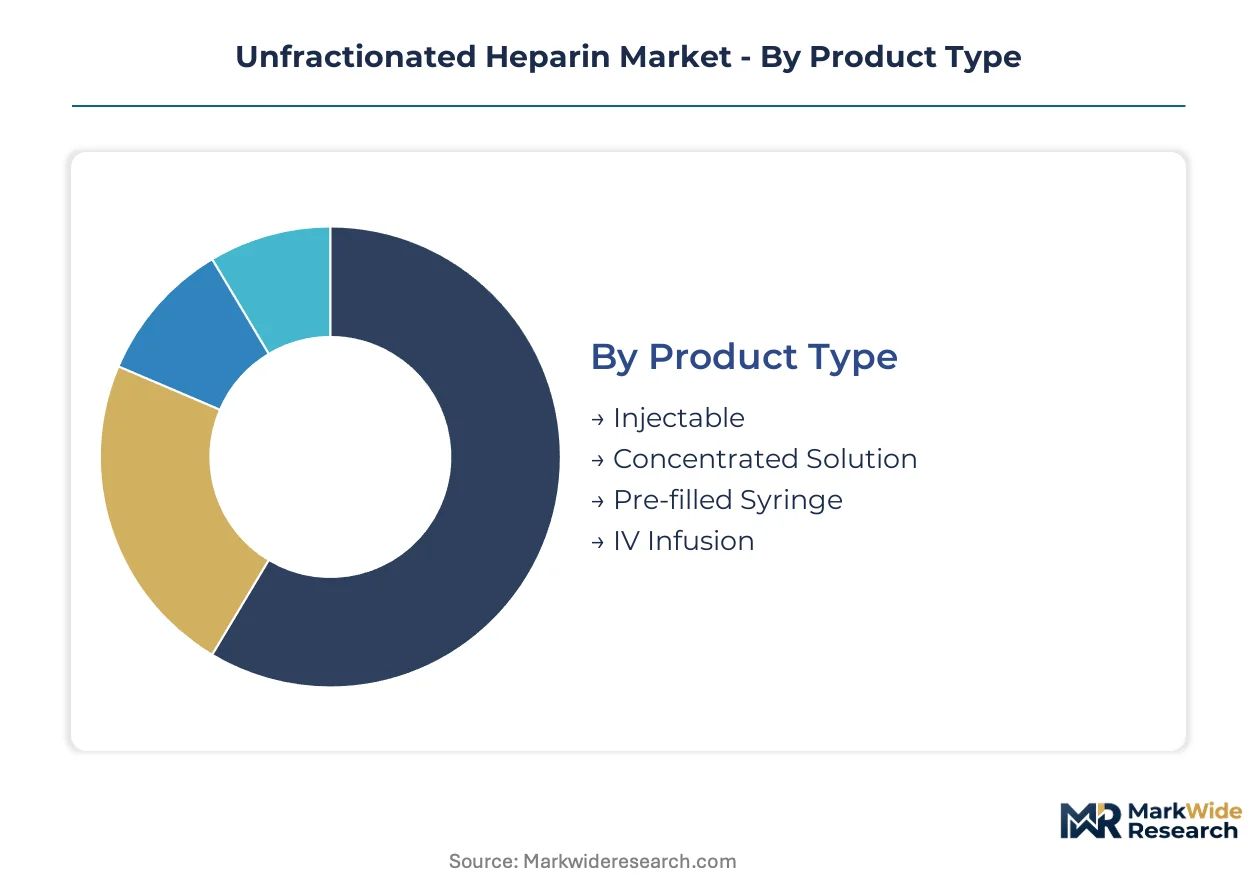
Unfractionated heparin procurement patterns diverge sharply across delivery formats and care settings. Manufacturers must align production capacity with the specific bioavailability and workflow requirements that distinguish emergency cardiology from ambulatory prophylaxis.
Product Type:
Hospital formulary committees are upgrading from multi-dose vials to ready-to-use formats that reduce compounding errors and nursing preparation time.
- Injectable:Standard vial presentations remain the workhorse for inpatient anticoagulation, with demand anchored in United States and German emergency departments where rapid dose titration proves essential for acute coronary syndrome protocols. FDA drug GMP regulations govern sterile manufacturing standards for these formulations.
- Concentrated Solution:High-potency formats reduce infusion bag volumes and storage footprint, capturing procurement contracts from ambulatory surgical centers in the United States seeking workflow efficiency. EMA pharmacovigilance directives impose additional molecular characterization requirements on European imports of these formulations.
- Pre-filled Syringe:Single-unit presentations eliminate dose-drawing steps for homecare nursing agencies managing deep vein thrombosis prophylaxis.
- IV Infusion:Ready-to-hang bags serve critical care units requiring continuous anticoagulation without pharmacy admixture delays.
Volume placements concentrate in Injectable formats; the faster expansion belongs to Pre-filled Syringe.
End User:
Procurement authority is shifting from centralized hospital pharmacies toward distributed purchasing by freestanding surgical and homecare entities.
- Hospitals:Academic medical centers in the United States, China, and Germany drive bulk purchasing through cardiac catheterization laboratories and surgical departments. China's NMPA applies GB standards for heparin sodium purity that constrain supplier qualification for these institutional contracts.
- Ambulatory Surgical Centers:Freestanding facilities in the United States favor concentrated solutions and pre-filled formats that minimize on-site pharmacy infrastructure. Medicare reimbursement changes favor site-of-care migration, expanding addressable volume for these outlets.
- Long-term Care Facilities:Skilled nursing settings administer subcutaneous prophylaxis for immobilized patients with elevated thrombotic risk.
- Homecare Providers:Nursing agencies consolidate purchasing through specialized infusion distributors bundling syringes with anticoagulation monitoring services.
Procurement volume tilts toward Hospitals; Ambulatory Surgical Centers are climbing the fastest as site-of-care migration accelerates.
Route of Administration:
Selection between delivery pathways hinges on the trade-off between immediate anticoagulant effect and dosing precision requirements.
- Subcutaneous:Prophylactic regimens for deep vein thrombosis prevention occupy the largest volume share, with administration protocols now originating in ambulatory settings for an expanding share of eligible patients in the United States.
- Intravenous:Continuous infusion enables precise titration in acute coronary syndrome and cardiopulmonary bypass, with demand concentrated in German and United States emergency cardiology departments where rebound surgical volumes sustain consistent procurement.
- Intramuscular:Alternative delivery for patients with compromised venous access or specific procedural constraints.
- Epidural:Specialized applications in obstetric and surgical anesthesia requiring anticoagulant prophylaxis concurrent with neuraxial catheter placement.
Subcutaneous delivery holds the volume base; Intravenous administration maintains the steepest expansion trajectory in acute care protocols.
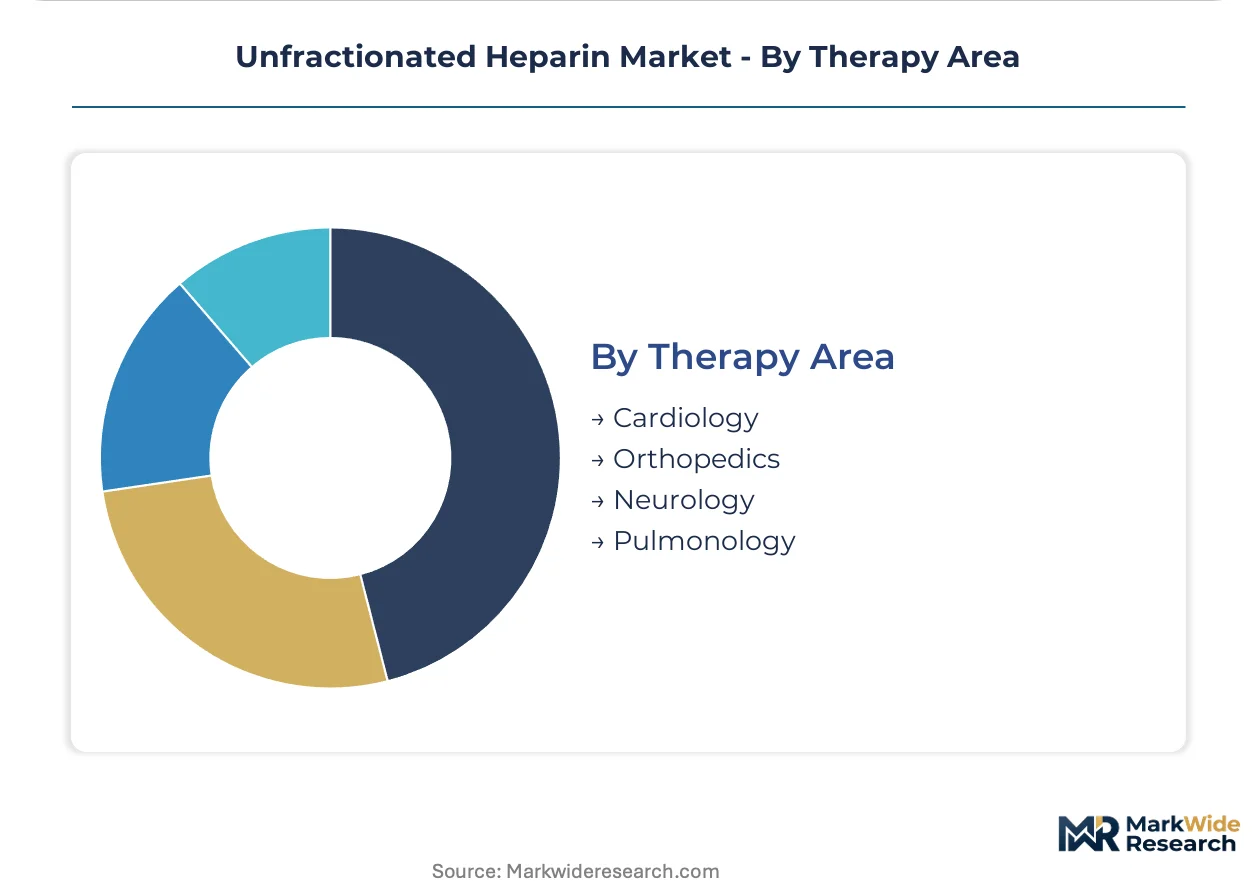
Therapy Area:
Clinical indication determines potency specification, dosing frequency, and monitoring intensity across heparin product selection.
- Cardiology:Percutaneous coronary intervention and acute coronary syndrome protocols drive the highest-potency requirements, with United States emergency departments expanding heparin-first anticoagulation regimens as surgical volumes rebound.
- Orthopedics:Joint replacement and trauma surgery generate prophylactic demand for extended-duration subcutaneous regimens, with German hospital procurement associations auditing supplier documentation packages as a prerequisite for tender participation.
- Neurology:Stroke protocols and cerebral venous sinus thrombosis management require rapid-onset anticoagulation with careful hemorrhage risk monitoring.
- Pulmonology:Pulmonary embolism treatment and prophylaxis in respiratory critical care settings.
Cardiology anchors procurement volume; Orthopedics is gaining share fastest as ambulatory joint replacement expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Changzhou anchors the raw material supply base for unfractionated heparin, with Jiangsu province processing the majority of porcine mucosa extraction before downstream formulation occurs in pharmaceutical clusters across three continents.
United States
Emergency cardiology departments in academic medical centers drive concentrated procurement for acute coronary syndrome protocols. FDA drug GMP regulations enforce sterile manufacturing standards and heparin sourcing documentation requirements. The Greater Boston biopharma corridor houses specialized injectable formulation facilities serving hospital networks nationwide.
China
Domestic hospital systems sustain demand for heparin sodium as cardiac catheterization volumes expand in tier-one cities. NMPA applies GB standards for purity that constrain market access for imported API suppliers. Changzhou and Nanjing industrial zones concentrate porcine mucosa fractionation capacity for both domestic consumption and API export.
Germany
Cardiac care infrastructure in university hospitals maintains consistent heparin procurement for percutaneous coronary intervention. EMA pharmacovigilance directives impose molecular characterization standards on European imports. The Rhine-Ruhr metropolitan region hosts contract manufacturing organizations qualifying single-source Chinese suppliers under dedicated slaughterhouse contracts.
India
Generic injectable manufacturers source heparin API for domestic hospital formulary inclusion and export to regulated markets. CDSCO enforces drug GMP compliance for sterile parenteral manufacturing. Hyderabad and Ahmedabad pharmaceutical clusters specialize in high-volume heparin sodium production for cost-sensitive procurement channels.
Unfractionated Heparin Market Competitive Environment
Premium-margin players sit above commodity-margin players across supply chain traceability and molecular characterization capabilities. The vendor base stratifies between vertically integrated fractionators with captive porcine sourcing and formulation specialists dependent on spot-market API purchasing. Three archetypes dominate: plasma fractionation conglomerates with injectable manufacturing networks, regional API suppliers with dedicated slaughterhouse contracts, and concentrated solution specialists serving ambulatory channels. Competitive moves concentrate on backward integration into raw material sourcing and real-time release testing technology deployment.
Within the integrated pharmaceutical tier, Pfizer Inc. and Sanofi exemplify capital-rich incumbents leveraging fractionation infrastructure for consistent API security. Amphastar Pharmaceuticals occupies a position among concentrated solution specialists addressing workflow efficiency demands from United States ambulatory surgical centers. Nanjing King-Friend Biochemical Pharmaceutical and Shenzhen Hepalink Pharmaceutical represent Chinese API manufacturers with regional hospital system penetration.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Amphastar Pharmaceuticals |
| Pfizer Inc. |
| Nanjing King-Friend Biochemical Pharmaceutical |
| Shenzhen Hepalink Pharmaceutical |
| Sanofi |
| Fresenius Kabi |
| Sagent Pharmaceuticals |
| Baxter International Inc. |
| Others |
Value Chain & Pricing Dynamics
EMA's 2024 pharmacovigilance directive update gates qualified supply for European hospital procurement, permitting only API manufacturers with complete porcine herd documentation and PCR-based species verification to command premium-tier pricing. This regulatory filter compresses the supplier base while amplifying price premiums for certified manufacturers that absorb compliance costs and technical investment.
Pricing Analysis
Potency-assay reliability serves as the value-based pricing anchor, with manufacturers deploying real-time release testing commanding fifteen to twenty percent premiums over batch-release competitors. Pricing stratifies across pharmaceutical-grade, compounding-grade, and research-grade tiers based on USP monograph compliance and molecular weight distribution certification. Cost compression in commodity-grade API intensifies as Chinese domestic manufacturers expand fractionation capacity. Ambulatory surgical centers exhibit highest price sensitivity due to Medicare reimbursement constraints, while academic medical centers prioritize assay reliability over unit cost.
Supply Chain Analysis
Direct-to-hospital channels handle formulary-contracted volume, while specialized infusion distributors manage homecare and ambulatory surgical center procurement. Raw heparin extraction concentrates in China, with Changzhou and Nanjing industrial zones processing over eighty percent of global porcine mucosa supply. Downstream formulation occurs in the United States, Germany, and India for regional hospital system access. The supply chain rests on dedicated slaughterhouse contracts rather than spot-market purchasing to satisfy EMA traceability mandates. Single-source geographic concentration in Jiangsu province exposes manufacturers to African swine fever disruption and export permit volatility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Captive porcine mucosa sourcing and in-house potency assay capability separate premium-margin survivors from commodity-margin casualties.
For Market Incumbents: Cement formulary lock-in by deploying real-time release testing infrastructure that cuts hospital inventory carrying costs. Secure dedicated slaughterhouse contracts in Jiangsu province to preempt EMA documentation audits. Low-molecular-weight heparin substitution in stable outpatient settings threatens volume retention; counter by bundling unfractionated heparin with direct oral anticoagulant transition protocols in cardiac catheterization laboratories.
For New Entrants and Emerging Players: NMPA's GB standard streamlining in China opens a window for domestic API manufacturers to displace imported heparin sodium in tier-one city hospital systems. Target ambulatory surgical center concentrated solution procurement in the United States where workflow efficiency premiums offset brand disadvantages. Enter through specialized infusion distributors bundling anticoagulation monitoring services rather than competing directly for hospital formulary slots.
For Investors and Strategic Acquirers: German hospital procurement association tender documentation audits are the leading indicator that EMA compliance costs have crossed the threshold where scale advantages compound. Position for five-to-ten year consolidation by identifying mid-cap fractionators with installed real-time release testing capability but underutilized slaughterhouse contract networks. Watch for PCR-based species verification technology deployment rates as the signal that technical moats are widening.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Slaughterhouse Contracts | Dedicated porcine mucosa sourcing satisfies EMA pharmacovigilance documentation requirements for European hospital access. |
| Real-Time Release Testing Deployment | Chemometric spectroscopy cuts batch release timelines from fourteen days to forty-eight hours, enabling just-in-time hospital inventory models. |
| Ambulatory Surgical Center Channel Partnership | Concentrated solution formats capture procurement contracts from United States freestanding facilities seeking workflow efficiency. |
| Dual USP-EP Assay Validation Investment | Orthogonal potency measurement capability qualifies suppliers for both American and European hospital formulary inclusion. |
| Homecare Infusion Distributor Alliance | Bundled syringe-plus-monitoring service offerings disintermediate traditional hospital wholesalers in site-of-care migration. |
Study Parameters
FDA filings, EMA pharmacovigilance directive updates, and NMPA GB standard notifications formed the secondary backbone for regulatory constraint mapping. Primary interviews with fractionation facility technical directors, hospital pharmacy procurement managers, and ambulatory surgical center supply chain officers validated supply concentration estimates and pricing tier boundaries. Customs data from Chinese API export registrations and United States import records provided volume triangulation against bottom-up hospital formulary analysis. Top-down pharmaceutical market sizing and bottom-up product-level shipment data were reconciled across the analysis window.
Historical surgical volume trendlines and cardiac catheterization procedure databases anchored the projection framework. Segmentation modeling incorporated product type, end user channel, route of administration, and therapy area dimensions with regional regulatory cluster overlays. CAGRs were derived from procedure growth assumptions, substitution elasticity estimates for low-molecular-weight heparin, and site-of-care migration rates. Anticoagulation protocol evolution in emergency cardiology and orthopedic prophylaxis served as primary demand drivers in the analytical model.
Caveats apply where African swine fever resurgence, abrupt USP-EP assay methodology divergence, or Medicare reimbursement recalibration could materially shift the outlook. Forecasts reflect assumptions about surgical volume recovery trajectories and regulatory enforcement consistency that warrant monitoring. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Nesiritide Market
Pharmaceuticals
Asia-Pacific Biguanide Market
Pharmaceuticals
US External Analgesics Market
Pharmaceuticals
PAP and Paracetamol Market
Pharmaceuticals
Flunarizine Hydrochloride Market
Pharmaceuticals
Pharmacy Market
Pharmaceuticals
Medical Nitroglycerin Spray Market
Pharmaceuticals
Levofloxacin Lactate Injection Market
Pharmaceuticals
Global Loratadine Market
Pharmaceuticals
Global Manidipine Hydrochloride Market
Pharmaceuticals
Isoflurane Market
Pharmaceuticals
Global Immunomodulators Market
Pharmaceuticals
US Intravenous Immunoglobulin Market
Pharmaceuticals
Candidiasis Therapeutics Market
Pharmaceuticals
Metaxalone Market
Pharmaceuticals
Global Anti-Fungal Drugs Market